
 Medium Voltage Drives Market | 2026-2036
Medium Voltage Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Medium Voltage Drives Market Analysis
Modular drive packaging is consolidating buyer choice around integrated power-cell architectures with embedded diagnostics. ABB Ltd leverages its installed base in process industries to sustain aftermarket revenue streams. Siemens AG anchors European utility retrofits with engineered-to-order medium voltage systems. Danfoss A/S competes through specialized marine and offshore drive configurations.
Medium voltage drives are power conversion systems operating between 2.3 kV and 13.8 kV that regulate motor speed and torque through insulated-gate bipolar transistor or integrated gate-commutated thyristor switching topologies, primarily serving heavy-industrial motor loads where direct-on-line starting would damage mechanical equipment or waste energy. AC Drives dominate installed capacity across water pumping and fan applications where variable flow requirements match centrifugal load curves. Converter Drives represent the fastest-expanding product configuration as mining operators seek regenerative braking and active front-end harmonic mitigation for deep-shaft hoists.
IEC 61800-4 sets type-testing protocols for medium voltage drive thermal and electrical performance, while NEMA ICS 7.0 governs North American construction and safety requirements; China's GB/T 12668 series mandates electromagnetic compatibility thresholds that shape import qualification timelines. The EU F-Gas Regulation and REACH chemical restrictions increasingly influence capacitor and insulation material selections in European-bound equipment. Stakeholders must monitor evolving grid-code harmonization between IEEE 1547 and IEC standards as distributed generation integration reshapes drive harmonic compliance obligations.
Market Dynamics
Industrial electrification mandates across China, Germany, and the United States are forcing water utilities and mining operators to replace fixed-speed motors with regenerative medium voltage drive systems, compressing payback periods below three years in high-duty-cycle applications.
Growth Catalysts
- NEMA MG1 Revisions:North American motor efficiency standards are compelling petrochemical facilities to upgrade aging drive infrastructure, triggering replacement cycles across Texas and Louisiana refining corridors.
- Deep-Shaft Mining:South African and Chilean underground operations require regenerative braking and active front-end harmonic mitigation for hoisting systems, accelerating Converter Drive specification.
- Water Utility Electrification:Municipal pumping stations in California and the Yangtze River basin face carbon reduction targets that favor variable-speed drive retrofits over pipeline expansion.
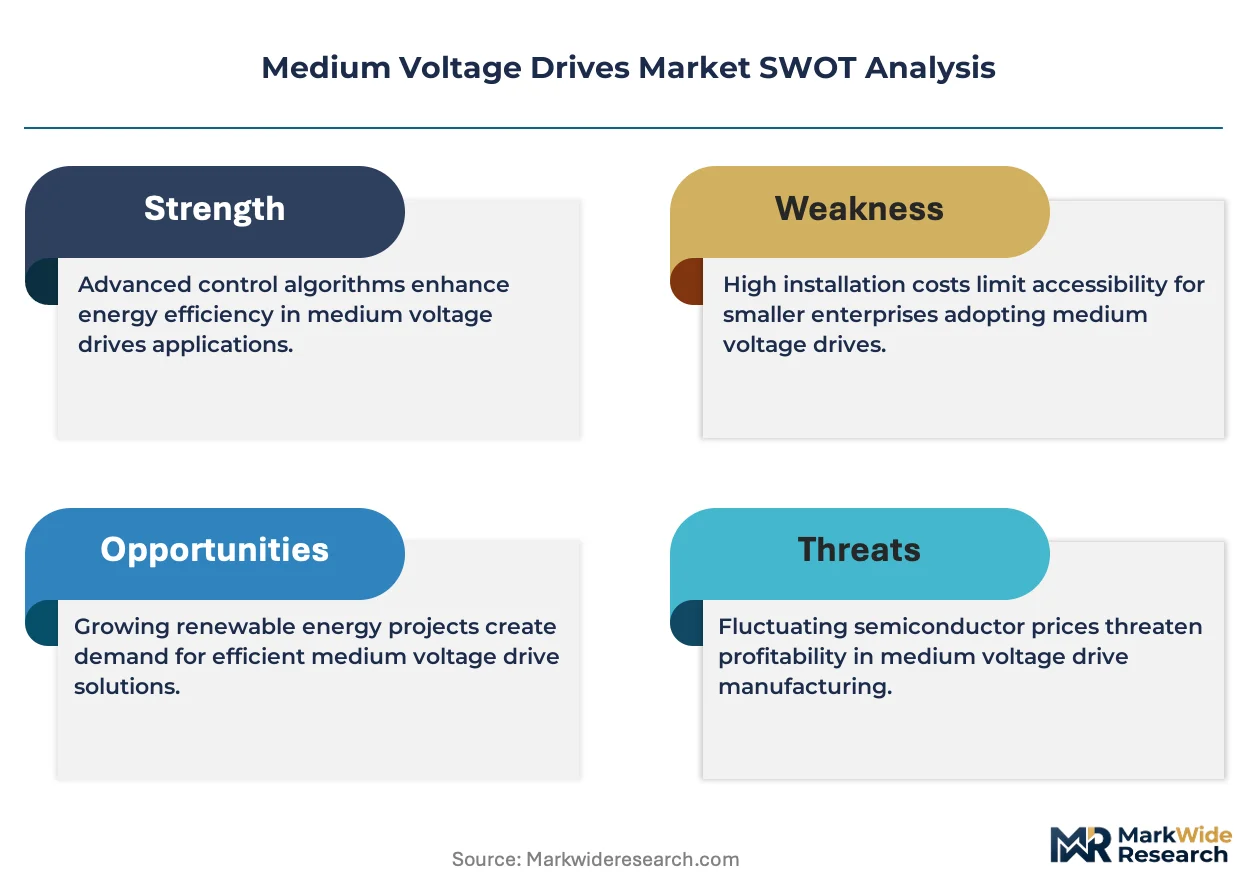
Market Restraints
- IGBT Supply Concentration:Japanese and German semiconductor foundries control insulated-gate bipolar transistor wafer supply, exposing drive manufacturers to 18-month lead time volatility.
- EU F-Gas Regulation:Capacitor dielectric material restrictions under REACH and F-Gas protocols are forcing redesign cycles that delay European product certification by 9-14 months.
- Direct-On-Line Substitution:Low-cost soft starters retain cost advantage in applications with infrequent speed changes, limiting addressable market in batch-process industries.
Strategic Opportunities
- India Industrial Corridors:PLI scheme incentives for domestic manufacturing are attracting drive assembly investments in Gujarat and Tamil Nadu, creating localized supply advantages.
- Offshore Wind Integration:Converter Drive demand from turbine manufacturers is expanding into grid-forming applications requiring active front-end rectification.
- Digital Twin Convergence:Embedded diagnostics from power-cell architectures are merging with cloud-based predictive maintenance platforms, enabling subscription revenue models.
Industry Challenges
- Power Electronics Talent Gap:Shortage of engineers skilled in medium voltage insulation coordination and thermal management is extending commissioning timelines for complex multi-level topologies.
- IEC 61800-4 Certification Burden:Type-testing protocols for thermal and electrical performance require 14-18 month validation cycles, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium Voltage Drives Market |
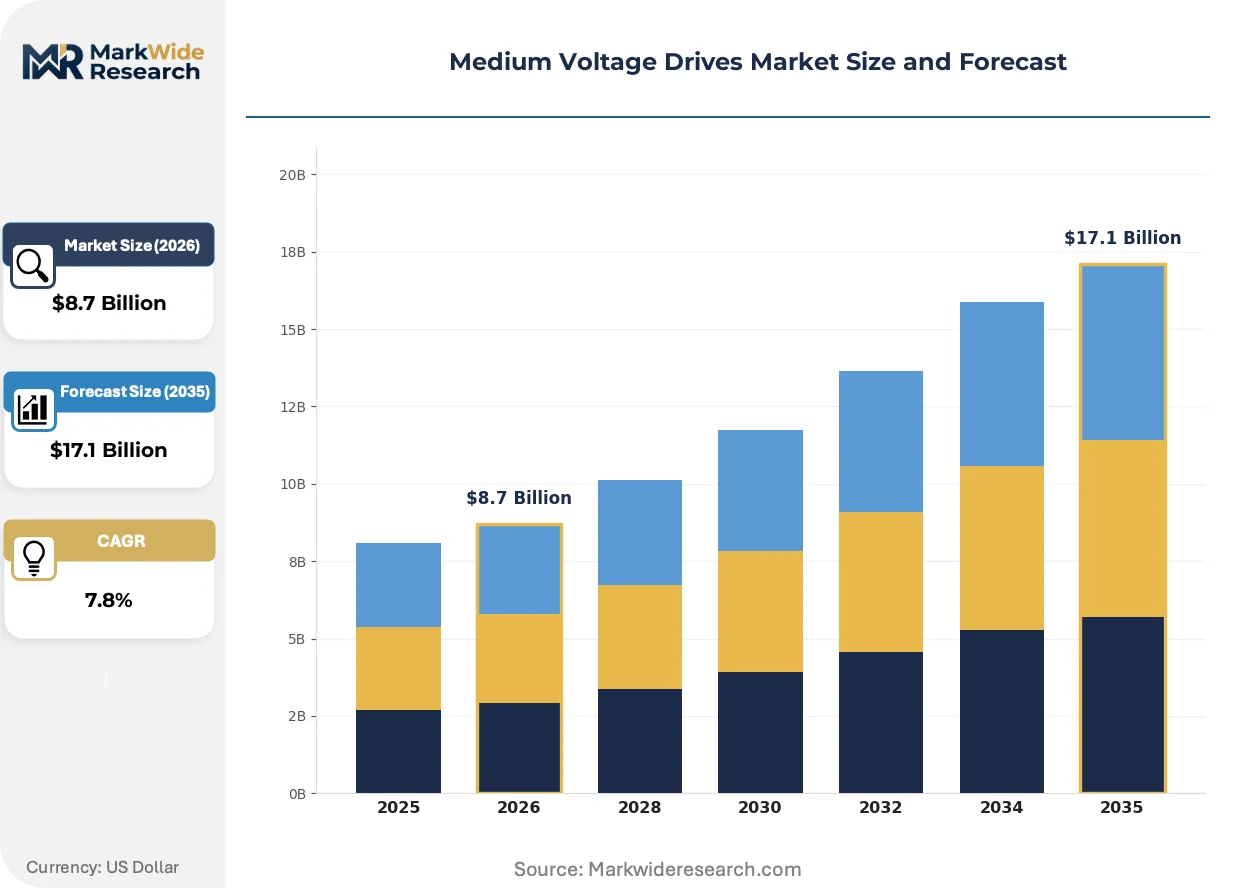
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Drives, DC Drives, Converter Drives, Multi-Level Drives Application: Water/Wastewater Management, Mining, Oil & Gas, Power Generation End User: Manufacturing, Utilities, Construction, Transportation Technology: VFD, Servo, Direct Torque Control, Vector Control |
| Companies Covered | Eaton Corporation plc, Fuji Electric Co., Ltd., Siemens AG, Nidec Corporation, Danfoss A/S, ABB Ltd, Rockwell Automation, Inc., Yaskawa Electric Corporation, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium Voltage Drives Market Emerging Trajectories
Power semiconductor evolution and embedded intelligence are redefining medium voltage drive architecture, shifting competitive advantage from hardware scale to software-defined performance optimization and predictive system integration.
Silicon carbide switching devices are expanding into medium voltage drive designs previously dominated by silicon IGBTs, enabling higher switching frequencies that reduce filter component size by 40%. Mining operators in Australia and Canada are specifying SiC-based systems for deep-shaft hoists where regenerative energy recovery justifies premium procurement. This transition is expanding into marine propulsion and offshore platform applications where footprint constraints dominate specification criteria.
EU F-Gas Regulation and REACH chemical restrictions are reshaping capacitor and insulation material selections for European-bound equipment, eliminating hydrofluorocarbon-based dielectric fluids from new designs. Drive manufacturers are reformulating thermal management systems around synthetic esters and dry film technologies. Water utilities in Germany and the Netherlands face the tightest compliance timelines, accelerating supplier qualification processes for alternative material stacks.
Service unbundling is fragmenting traditional procurement relationships as end-users separate hardware acquisition from commissioning and long-term maintenance contracts. Mining houses in Chile and steel producers in South Korea are negotiating multi-year performance guarantees independent of initial capital expenditure. This pattern is most pronounced in process industries where operational technology teams retain lifecycle cost accountability separate from procurement functions.
Medium Voltage Drives Market Segmentation
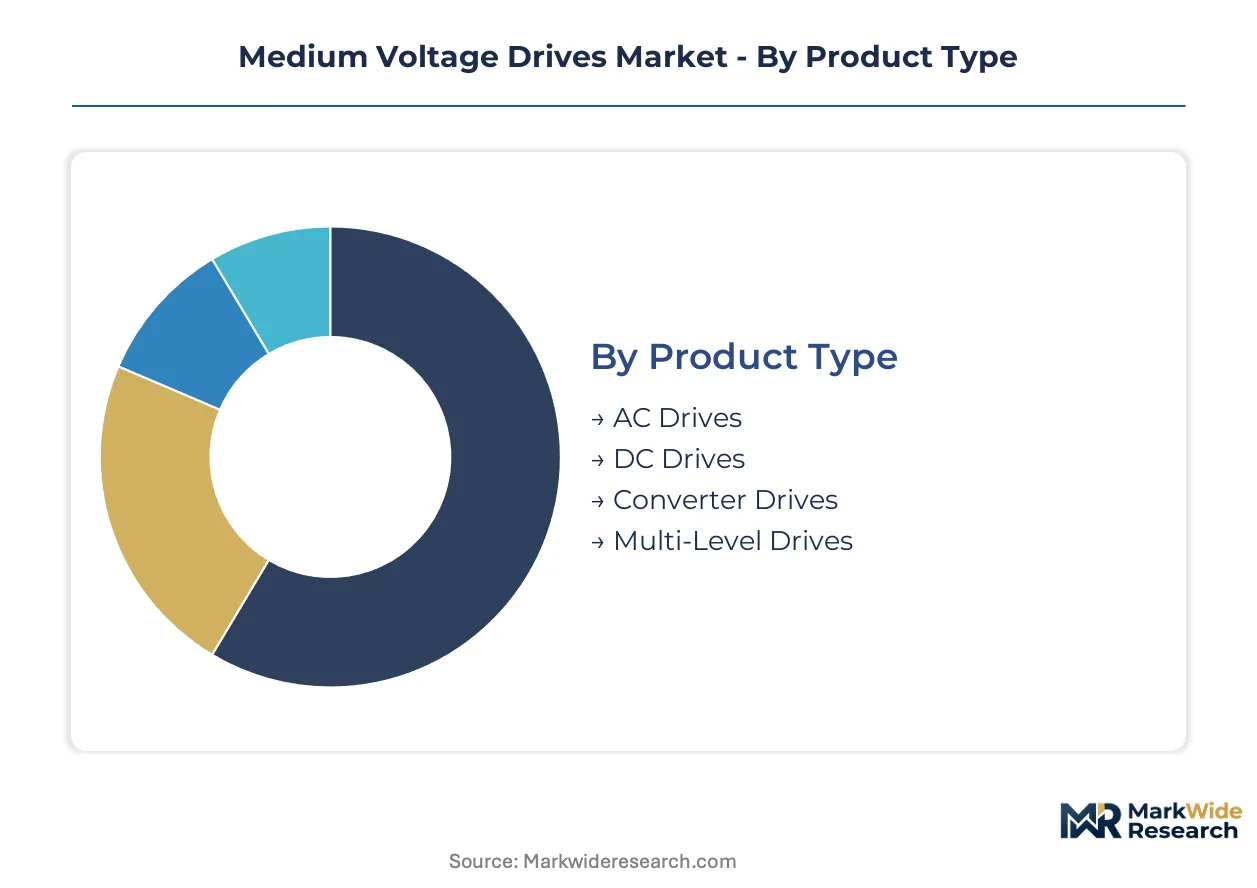
Medium voltage drive procurement patterns diverge sharply between efficiency-driven retrofits and greenfield electrification projects. Product architecture, application duty cycles, and control technology requirements create distinct commercial clusters that shape supplier engagement models and lifecycle revenue structures.
Product Type:
AC Drives dominate installed base volume while Converter Drives command premium positioning through regenerative capabilities.
- AC Drives:These systems regulate motor speed through voltage-frequency modulation using IGBT-based inverters, serving centrifugal pumps and fans where variable flow control matches load curves. Water utilities in California and Germany specify AC Drives for municipal pumping stations facing carbon reduction mandates, with payback periods compressing below three years in high-duty-cycle installations.
- Converter Drives:Active front-end rectification enables four-quadrant operation with regenerative braking and harmonic mitigation, essential for deep-shaft mining hoists. Mining operators in South Africa and Chile absorb premium procurement costs to recover descent energy and meet IEEE 519 compliance in weak grid conditions.
- DC Drives:Legacy Ward Leonard and thyristor-based systems persist in specific heavy-industrial retrofits where existing DC motor assets require preservation.
- Multi-Level Drives:Neutral-point-clamped and cascaded H-bridge topologies reduce dv/dt stress on motor windings, finding specification in long-cable offshore platform applications.
Mature deployment sits with AC Drives across established water infrastructure. Newer deployment is concentrated in Converter Drives as mining electrification accelerates regenerative system specification.
Application:
Water management applications anchor replacement demand while mining electrification drives specification of advanced topologies.
- Water/Wastewater Management:Variable-speed control of centrifugal pumps eliminates throttling losses in distribution networks. Municipal operators in the Yangtze River basin and Netherlands face pipeline capacity constraints that favor drive retrofits over physical infrastructure expansion, with efficiency gains of 20-30% against fixed-speed baselines.
- Mining:Hoist and conveyor applications demand regenerative braking and precise torque control for deep-shaft operations. Australian and Canadian underground mines specify silicon carbide-based systems where energy recovery justifies premium capital expenditure against diesel-electric alternatives.
- Oil & Gas:Compressor and pump control in upstream and midstream operations, with NEMA MG1 revisions triggering replacement cycles across Texas refining corridors.
- Power Generation:Boiler feed pumps and induced draft fans in thermal plants, plus emerging grid-forming applications in offshore wind integration.
Established application concentration rests with Water/Wastewater Management across aging infrastructure bases. Steepest expansion trajectory is emerging in Mining as electrification mandates displace mechanical and diesel drive systems.
End User:
Utility procurement patterns favor lifecycle cost optimization while manufacturing demand concentrates on integration with process automation architectures.
- Utilities:Water and electric utilities prioritize 20-year total cost of ownership in specification, separating hardware acquisition from long-term service contracts. German and Dutch water utilities lead European qualification of F-Gas-compliant capacitor materials under REACH restrictions.
- Manufacturing:Steel and cement producers integrate medium voltage drives with distributed control systems, requiring embedded diagnostics and digital twin compatibility for predictive maintenance platforms.
- Construction:Tunnel boring machines and material handling systems specify ruggedized drive packages for temporary power infrastructure conditions.
- Transportation:Marine propulsion and port crane applications demand compact footprint solutions with classification society certification.
Volume concentration aligns with Utilities given infrastructure replacement cycles. Margin expansion is concentrating in Manufacturing as digital service unbundling creates subscription revenue opportunities.
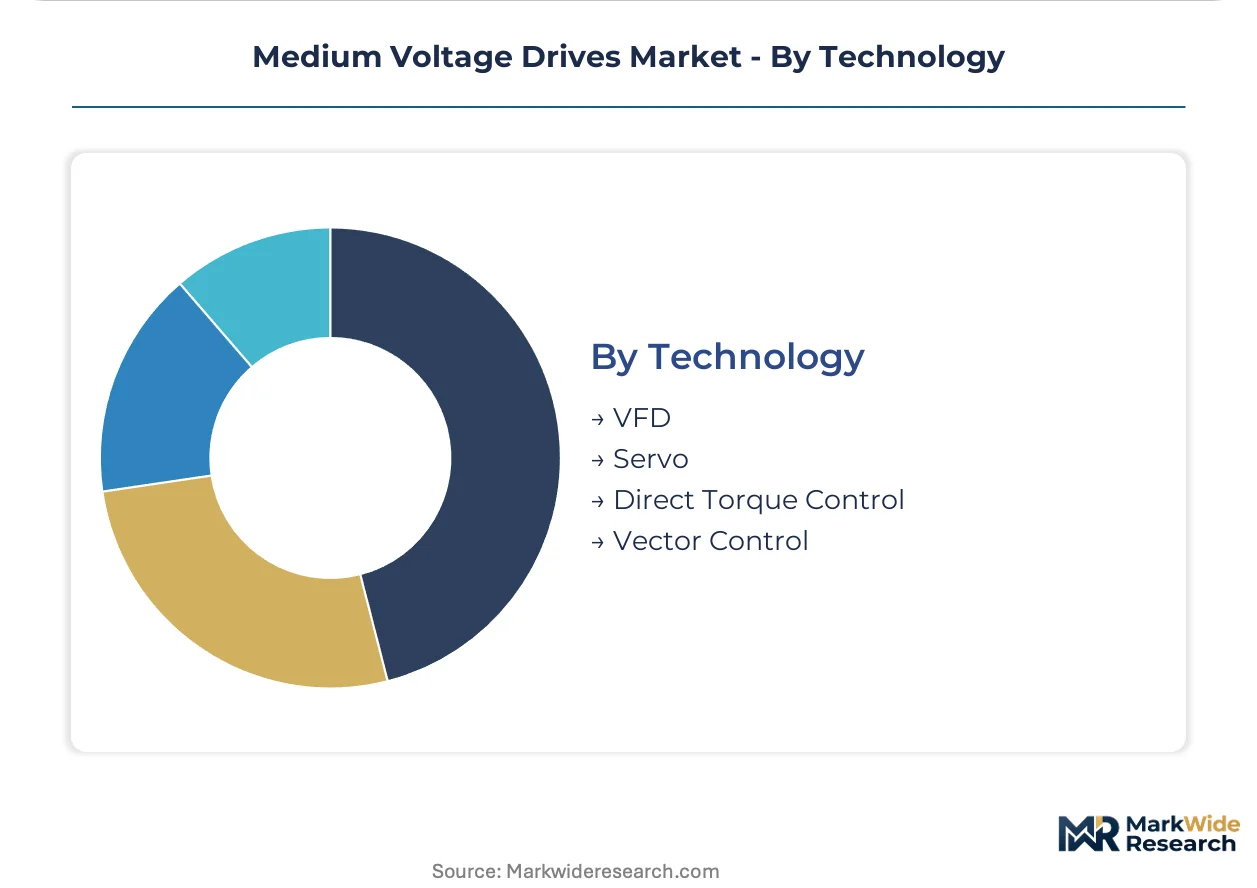
Technology:
VFD platforms dominate commercial availability while advanced control algorithms differentiate premium system performance.
- VFD:Variable frequency drive platforms using pulse-width modulation provide the fundamental speed control architecture across 2.3 kV to 13.8 kV ratings. IEC 61800-4 type-testing protocols standardize thermal and electrical performance validation for these systems.
- Direct Torque Control:Direct stator flux and torque regulation without modulator stage enables sub-millisecond response for mining hoist applications requiring precise load handling.
- Servo:Closed-loop position and velocity control for coordinated multi-axis applications in material handling and specialized manufacturing processes.
- Vector Control:Field-oriented algorithms decouple torque and flux components for high-dynamic-performance motor control in test stands and specialized machinery.
Established technology deployment centers on VFD across standard industrial applications. Emerging specification is concentrating in Direct Torque Control as mining and marine sectors demand superior dynamic response characteristics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and China while consumption concentrates across industrial electrification corridors in the United States and mining belts in South Africa and Chile. This geographic split shapes supplier qualification timelines and service network investments.
United States
Petrochemical refineries along the Texas and Louisiana Gulf Coast are replacing fixed-speed motor systems under NEMA MG1 efficiency mandates. The EPA enforces emissions thresholds that accelerate drive retrofits in heavy process industries. Municipal water utilities in California face carbon reduction targets that favor variable-speed pumping over pipeline expansion.
Germany
Industrial machinery manufacturers in Bavaria and North Rhine-Westphalia specify medium voltage drives for integrated automation architectures. The EU F-Gas Regulation and REACH chemical restrictions force capacitor material redesigns that extend product certification cycles. Water utilities in the Netherlands and German Rhine basin lead European qualification of alternative dielectric fluids.
China
Dual carbon goals and industrial electrification mandates compress payback periods for regenerative drive systems in Yangtze River basin pumping stations. MIIT oversees GB/T electromagnetic compatibility standards that shape import qualification timelines. Manufacturing clusters in Jiangsu and Zhejiang provinces anchor domestic supply chain expansion.
South Africa
Deep-shaft platinum and gold mining operations require regenerative braking systems for hoisting applications with weak grid conditions. The country's national mining regulator enforces safety standards that favor active front-end harmonic mitigation. Underground operations in the Bushveld Complex specify converter drives for energy recovery during descent cycles.
India
PLI scheme incentives attract drive assembly investments in Gujarat and Tamil Nadu industrial corridors. The CEA mandates efficiency standards for utility-scale pumping infrastructure that accelerate municipal retrofits. Steel producers in Odisha and cement manufacturers in Rajasthan integrate medium voltage systems with process control architectures.
Medium Voltage Drives Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive semiconductor relationships and process industry installed bases. Market concentration remains moderate with tiered positioning across premium engineered-to-order systems and standardized modular platforms. Two strategic archetypes dominate: integrated power electronics manufacturers with backward component control, and automation specialists bundling drives with digital service layers. Capacity expansion and technology licensing represent the dominant competitive moves as lead time volatility in IGBT supply chains forces supply security investments.
Within the diversified industrial tier, Siemens AG and ABB Ltd occupy positions anchored by process industry relationships and aftermarket service networks. Eaton Corporation plc exemplifies the power infrastructure specialist archetype with electrical distribution heritage. Danfoss A/S represents the application-focused configuration, occupying a position in specialized marine and offshore drive segments. These three companies collectively illustrate how competitive positioning fragments across integrated automation, power distribution, and vertical specialization vectors.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| Fuji Electric Co., Ltd. |
| Siemens AG |
| Nidec Corporation |
| Danfoss A/S |
| ABB Ltd |
| Rockwell Automation, Inc. |
| Yaskawa Electric Corporation |
| Schneider Electric SE |
| Others |
Supply Flow & Price Mechanics
Power electronics engineering talent concentration in Germany and Japan feeds labor-cost differentials that widen pricing-tier spreads between engineered-to-order systems and modular platforms. The premium commanded by specialists in medium voltage insulation coordination and thermal management separates tier-one suppliers from assembly-focused competitors in emerging manufacturing corridors.
Pricing Analysis
Margin tightening in standard AC Drive configurations reflects IGBT supply concentration and soft starter substitution pressure in batch-process industries. Three-tier pricing structure across premium converter systems, standard variable frequency platforms, and economy AC drives differentiates on certification grade and after-sales bundling. Cost-down pressure on economy tiers accelerates because municipal utilities in high-debt regions prioritize capital expenditure minimization over lifecycle optimization. Water utilities exhibit highest price sensitivity; mining operators absorbing premium converter systems for regenerative applications show lowest.
Supply Chain Analysis
EU F-Gas Regulation and REACH chemical restrictions are extending capacitor material qualification timelines for European-bound equipment, forcing redesign cycles that gate supplier access. Manufacturing concentrates in Germany, China, and the United States; IGBT wafer supply draws from Japanese and German semiconductor foundries. Raw material dependencies span silicon carbide substrates, synthetic ester dielectric fluids, and copper busbar assemblies. Single-source vulnerability in power semiconductor supply exposes drive manufacturers to allocation volatility. Distribution runs through electrical distribution channels and direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Medium Voltage Drives Market represents a consolidation play as IGBT supply concentration and certification burden squeeze sub-scale competitors lacking captive semiconductor relationships or process industry installed bases.
For Market Incumbents: Deepen backward integration into power semiconductor supply through foundry partnerships or captive wafer allocation agreements to defend against lead time volatility. Expand service unbundling capabilities to capture subscription revenue from predictive maintenance platforms, reinforcing lifecycle cost accountability separation that procurement functions increasingly demand. For New Entrants and Emerging Players: Capture white-space in India PLI scheme corridors where domestic assembly incentives attract investment without requiring full semiconductor fabrication capability. Target marine and offshore drive configurations where classification society certification barriers limit incumbent specialization depth, entering through application-engineering partnerships with shipyards. For Investors and Strategic Acquirers: The window for entry favors automation specialists with digital service layer capabilities over pure-play hardware manufacturers. Long-term viability centers on software-defined performance optimization convergence. Target acquisition archetype: mid-tier drive manufacturers with established IEC 61800-4 certification and regional utility relationships but limited predictive maintenance platform integration. Watch silicon carbide adoption curves in mining electrification as inflection indicator for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Supply | Captive IGBT allocation secures production continuity against Japanese and German foundry volatility. |
| Digital Twin Platform Development | Embedded diagnostics merger with cloud predictive maintenance enables subscription revenue models. |
| India Manufacturing Footprint Expansion | PLI scheme incentives in Gujarat and Tamil Nadu create localized cost advantages for domestic supply. |
| Synthetic Ester Material Qualification | F-Gas-compliant thermal management systems unlock German and Dutch water utility procurement access. |
| SiC Switching Topology Migration | Higher frequency operation reduces filter footprint for Australian and Canadian deep-shaft mining specifications. |
Methodological Framework
Multi-period observation of IGBT lead time volatility, certification timeline extensions, and municipal utility procurement patterns anchored the trend analysis, supplemented by interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads. Secondary validation drew from IEC 61800-4 type-testing documentation, SEC filings of diversified industrial conglomerates, MIIT GB/T standard publications, and customs trade data for power electronics components. Bottom-up segment sizing triangulated against top-down industrial electrification mandate tracking.
Segment-weighting across product type, application duty cycle, end-user procurement pattern, and control technology architecture shaped the analytical framework throughout the projection horizon. CAGRs derived from installation base replacement velocity and greenfield electrification project pipelines. Industry-specific forecast inputs incorporated NEMA MG1 revision compliance deadlines and EU F-Gas Regulation phase-out timelines for capacitor dielectric materials.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to power semiconductor technology transitions and grid-code harmonization between IEEE 1547 and IEC standards. Forecasts reflect documented assumptions about industrial electrification mandate continuity and mining sector capital allocation priorities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Marine Variable Frequency Drives Market
Power Systems
Global Flexible Batteries Market
Power Systems
DC Power Supplies Market
Power Systems
Harmonic Generators Market
Power Systems
Europe Shunt Reactors Market
Power Systems
Digital Inverter Market
Power Systems
South America Battery Management System Market
Power Systems
Southeast Asia Uninterruptible Power Supply (UPS) Market
Power Systems
Automotive Power Electronics Market
Power Systems
Germany Rechargeable Battery Market
Power Systems
BCD Power IC Market
Power Systems
Thyristor Market
Power Systems
Buck-Boost Controller Market
Power Systems
Series Reactor Market
Power Systems
Hybrid Inverters Market
Power Systems
Power Supply Isolation Equipment Market