
 Integrated Gate Commutated Thyristors (IGCT) Market | 2026-2036
Integrated Gate Commutated Thyristors (IGCT) Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Gate Commutated Thyristors (IGCT) Market Foresight
Software-defined gate control is broadening what IGCT suppliers monetize beyond discrete components. Hitachi Energy leverages its power systems integration expertise to bundle predictive maintenance contracts with hardware shipments. ABB anchors European demand through its traction and industrial drive portfolios. Mitsubishi Electric specializes in high-voltage rail applications where IGCT reliability requirements exclude most competitors.
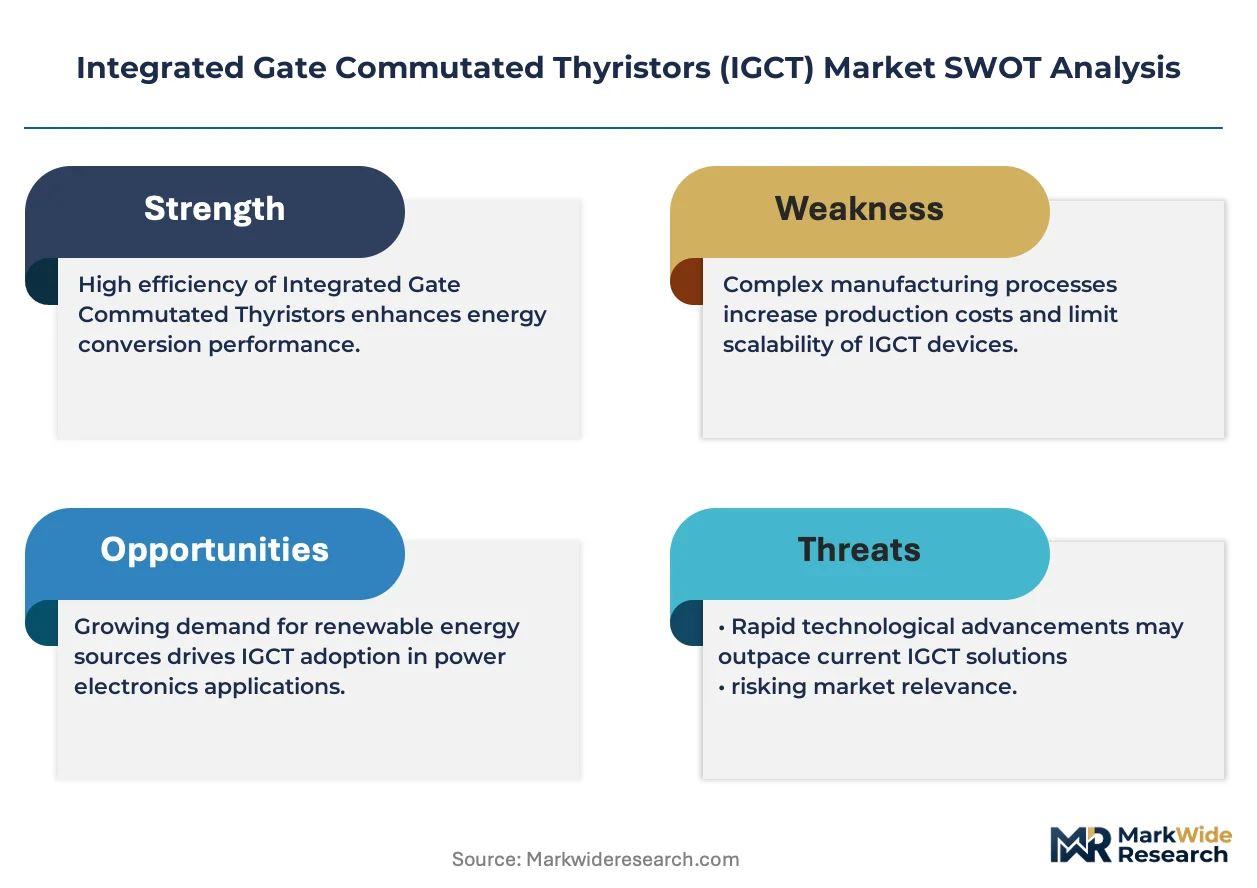
An Integrated Gate Commutated Thyristor is a high-power semiconductor switch combining thyristor current-handling capability with gate turn-off functionality, typically rated above 4.5 kV and 4 kA for medium-voltage drives and grid converters. The device integrates a gate commutated thyristor chip with a monolithically integrated gate unit to achieve microsecond switching speeds in megawatt-scale power electronics. Voltage-controlled IGCT variants command premium positioning in renewable energy inverters where switching losses directly impact system efficiency. Phase-controlled devices occupy mature, cost-sensitive niches in industrial motor control. Silicon-based technology dominates manufacturing scale, though SiC hybrid architectures are penetrating applications demanding higher frequency operation.
IEC 60747 semiconductor standards, China's GB/T energy efficiency codes, and the EU F-Gas Regulation collectively shape IGCT product specifications and market access requirements across major demand centers. EPA efficiency mandates for industrial motor systems in the United States further tighten permissible loss profiles for drive-integrated power electronics. Stakeholders must monitor gate driver integration roadmaps and substrate material transitions to preserve technology positioning as efficiency thresholds tighten.
Market Dynamics
China's dual carbon goals and grid modernization mandates are tightening efficiency standards for high-power semiconductors, forcing IGCT suppliers to accelerate gate driver integration and substrate material transitions to preserve technology positioning.
Growth Catalysts
- Renewable energy capacity expansion:Utility-scale solar and wind installations require megawatt-scale power converters where IGCT switching performance minimizes conversion losses.
- EU F-Gas Regulation:The phase-down of fluorinated greenhouse gases in electrical equipment pushes manufacturers toward solid-state switching solutions with lower thermal footprints.
- Rail electrification programs:High-speed rail networks in Germany and Japan specify IGCT-based traction drives for reliability in 25 kV AC systems.
Market Restraints
- Silicon carbide MOSFET substitution:SiC devices above 3.3 kV are penetrating medium-voltage drives where switching frequency requirements exceed IGCT capabilities.
- Gate driver cost concentration:Specialized gate units represent 15-20% of system BOM, with supply constrained by precision magnetic component availability.
- IEC 60747 certification timelines:Type testing for new IGCT variants requires 18-24 months, delaying product launches in safety-critical applications.
Strategic Opportunities
- Offshore wind converter demand:Floating wind platforms in the North Sea require compact, high-reliability power electronics where IGCT robustness outperforms IGBT modules.
- India's PLI scheme for power electronics:Domestic manufacturing incentives create localized assembly opportunities for IGCT-based drives serving steel and cement sectors.
- SiC hybrid architectures:Combining silicon IGCT main switches with SiC diodes enables higher frequency operation in renewable inverters without full device replacement.
Industry Challenges
- Power semiconductor packaging expertise:The specialized skill set for hermetic ceramic housing design and thermal management engineering faces generational shortage across manufacturing bases.
- Legacy drive retrofit compatibility:IGCT replacements in 1990s-era industrial installations require mechanical and electrical interface adaptation, complicating aftermarket service models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Gate Commutated Thyristors (IGCT) Market |
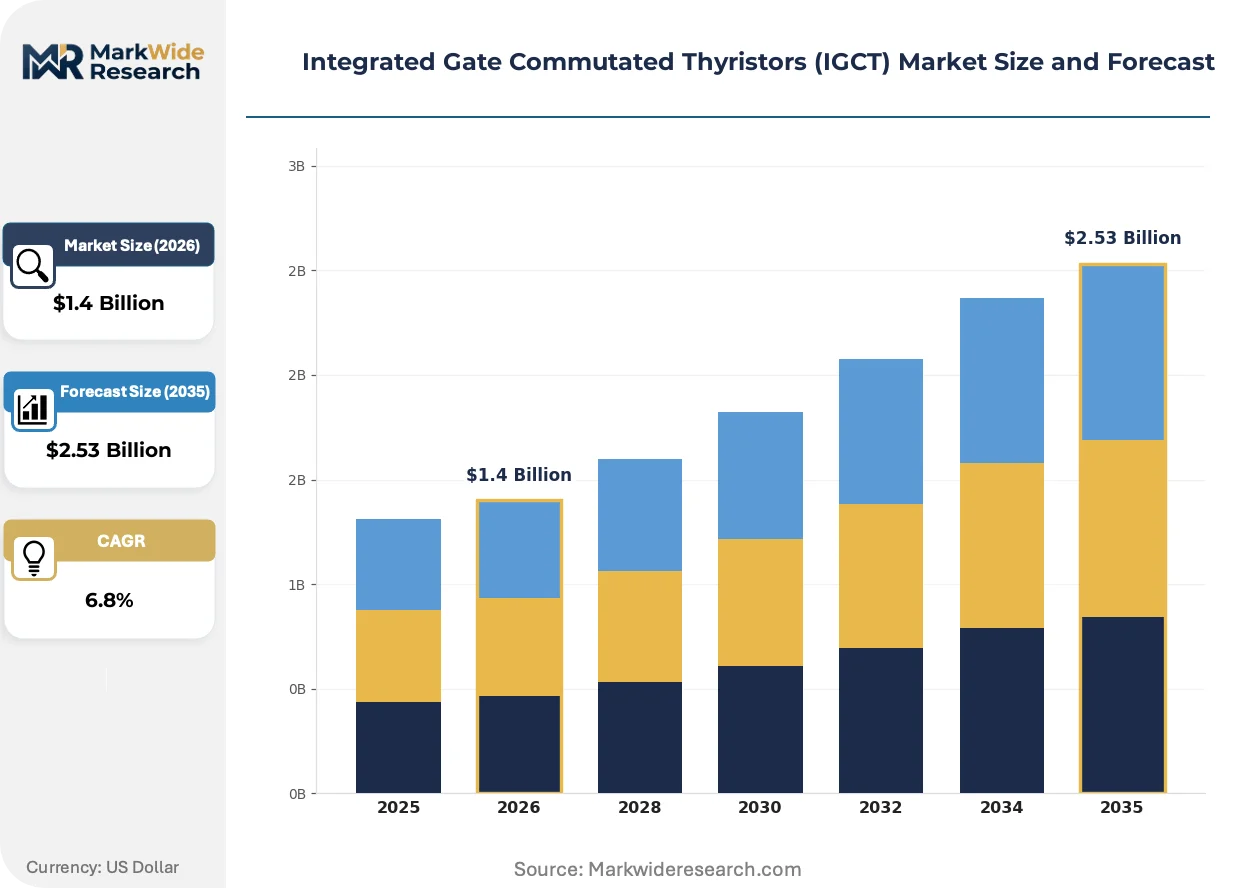
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phase-Controlled, Voltage-Controlled, Current-Controlled, Merged Devices Application: Power Electronics, Renewable Energy, Industrial Drives, Motor Control End User: Energy Sector, Manufacturing, Transportation, Construction Technology: Silicon, SiC, GaN, Hybrid |
| Companies Covered | Hitachi Energy, CRRC Corporation Limited, ABB, Semikron International, Fuji Electric, Infineon Technologies, General Electric, Toshiba Corporation, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Gate Commutated Thyristors (IGCT) Market Shifts & Advancements
Software-defined gate control architectures are broadening what IGCT suppliers monetize beyond discrete components, bundling predictive analytics and remote diagnostics into hardware relationships.
SiC hybrid IGCT modules are rewriting performance expectations in renewable energy inverters. These devices combine silicon thyristor structures with silicon carbide freewheeling diodes to achieve switching frequencies above 1 kHz without sacrificing current-handling capacity. Wind turbine OEMs in Denmark and Spain are qualifying these hybrids for next-generation converters. The technology is compressing the traditional frequency-versus-power tradeoff that segmented IGBT and thyristor markets.
China's GB/T energy efficiency codes are tightening loss thresholds for medium-voltage motor drives. The 2024 revisions mandate maximum switching losses for semiconductors above 2.5 kV, directly affecting IGCT product specifications. Industrial drive manufacturers in Shanghai and Shenzhen are redesigning thermal management systems to meet the new standards. The regulation is accelerating adoption of voltage-controlled IGCT variants over phase-controlled alternatives.
Service contract unbundling is fragmenting traditional hardware-plus-maintenance relationships. Power systems integrators now procure IGCTs separately from predictive maintenance software, reversing decades of bundled pricing. This pattern is most visible in Germany's industrial drive sector, where Siemens and ABB face pressure from independent service providers offering third-party diagnostics. Buyers are optimizing total cost of ownership through competitive software sourcing rather than single-vendor dependency.
Integrated Gate Commutated Thyristors (IGCT) Market Segmentation
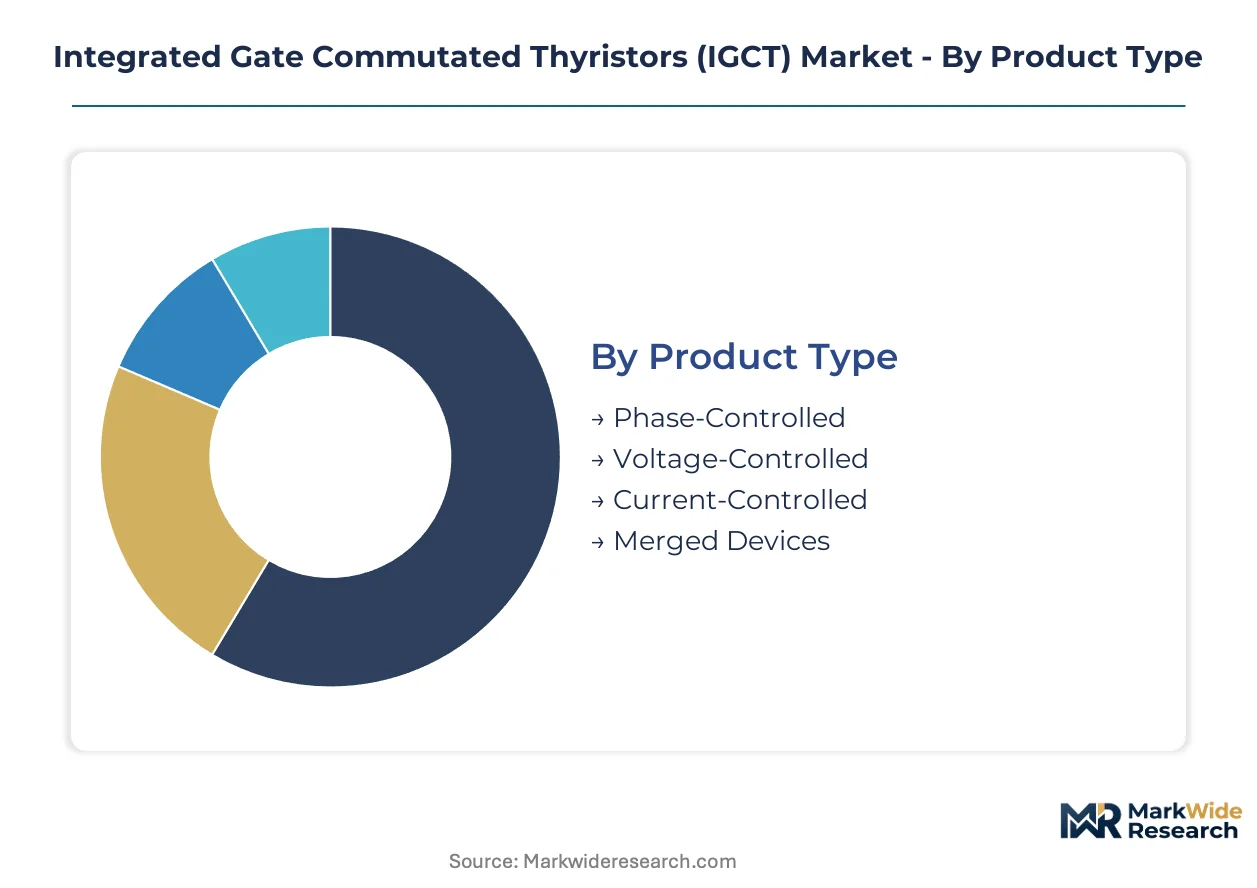
IGCT procurement patterns diverge sharply between standardized commodity devices and engineered-to-order solutions for megawatt-scale installations. Understanding these segmentation boundaries clarifies where suppliers capture premium positioning versus where price competition dominates.
Product Type:
Standardized gate driver architectures serve high-volume industrial drives, while customized switching profiles command premiums in grid-scale renewable converters.
- Voltage-Controlled:Gate units modulate turn-off via applied voltage rather than current injection, enabling sub-microsecond switching in 4.5 kV+ applications. Wind turbine OEMs in Denmark and Spain specify these variants for converter efficiency optimization under IEC 60747-9 thermal cycling requirements. China's GB/T 12668 loss thresholds are accelerating displacement of phase-controlled alternatives in new installations.
- Phase-Controlled:Legacy thyristor commutation relies on line-frequency zero-crossing, constraining these devices to 400 Hz operation in mature motor control installations. Cement and steel mills in Germany's Ruhr region maintain substantial installed bases, though replacement demand is flattening as voltage-controlled retrofits penetrate.
- Current-Controlled:Direct gate current injection suits high-reliability rail traction where electromagnetic immunity overrides switching speed priorities.
- Merged Devices:Monolithic integration of thyristor and freewheeling diode functions reduces module count in compact offshore wind converters.
Most installed capacity flows through Phase-Controlled devices. Expansion is steepest in Voltage-Controlled variants.
Application:
Application selection correlates directly with switching frequency requirements and thermal management constraints.
- Renewable Energy:Utility-scale solar and wind converters above 2 MW demand IGCT robustness where IGBT series connection complexity becomes prohibitive. Floating offshore platforms in the North Sea specify these devices for salt-mist resistance and maintenance access limitations. The EU F-Gas Regulation is accelerating solid-state switching adoption versus gas-insulated alternatives.
- Industrial Drives:Medium-voltage motor control above 1 kV represents the historical volume anchor, with Siemens and ABB supply chains dominating German procurement. India's PLI scheme for power electronics is localizing assembly for steel and cement sector demand.
- Power Electronics:Grid interconnection and HVDC link applications specify ultra-high voltage ratings above 6.5 kV.
- Motor Control:Phase-controlled variants persist in 1990s-era installations where retrofit economics favor like-for-like replacement.
Industrial Drives absorb the highest unit volumes. Renewable Energy is gaining share fastest.
End User:
Customer sophistication and procurement scale create distinct service requirements across end-user categories.
- Energy Sector:Grid operators and IPPs demand predictive maintenance integration and 25-year service life guarantees. China's State Grid procurement mandates dual carbon compliance documentation.
- Transportation:Rail OEMs specify IGCT-based traction for 25 kV AC electrification networks in Germany and Japan.
- Manufacturing:Discrete factory automation favors standardized drives with minimized customization.
- Construction:Mobile equipment applications represent emerging demand for compact, high-torque motor control.
Energy Sector procurement dominates absolute value. Transportation specifications are tightening fastest.
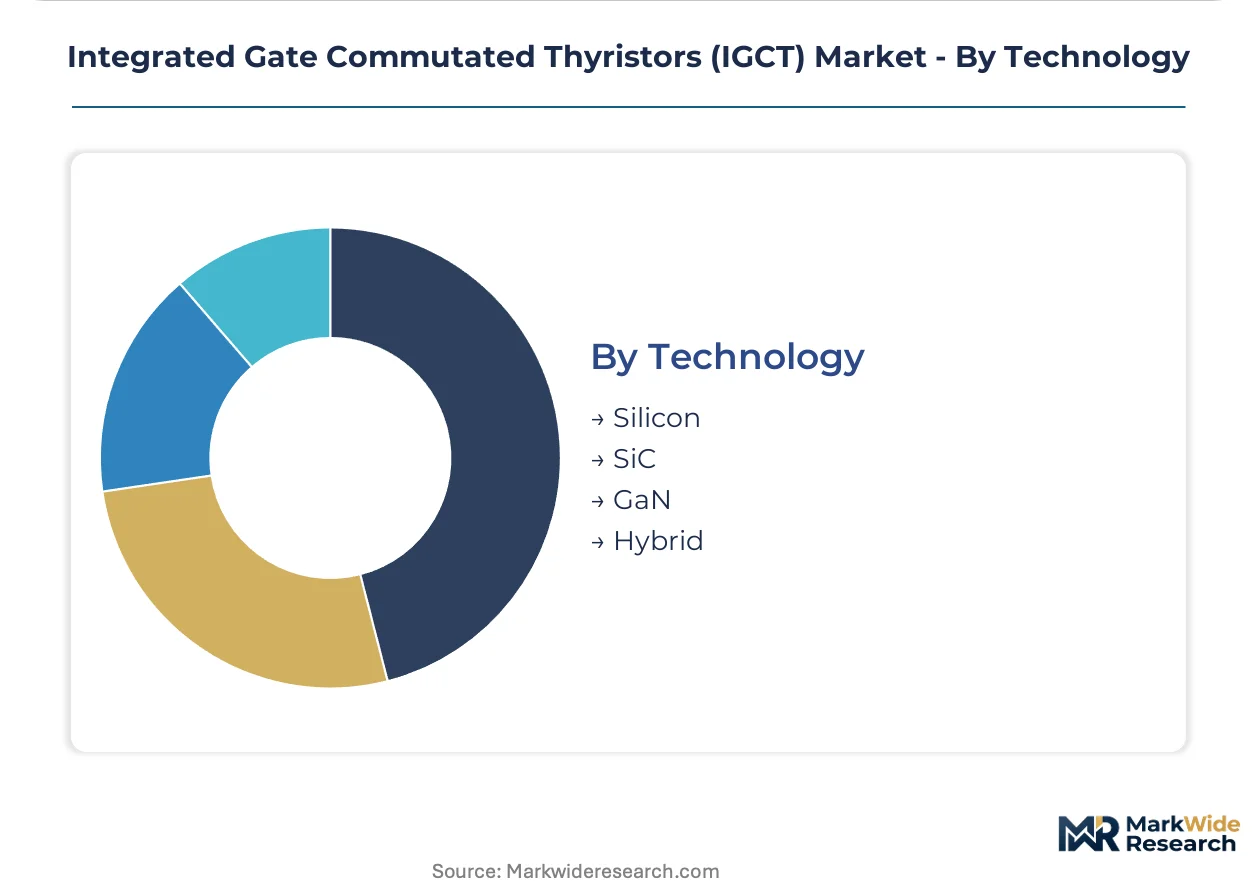
Technology:
Substrate material selection determines frequency-power tradeoffs and thermal performance ceilings.
- Hybrid:Silicon IGCT main switches paired with SiC freewheeling diodes achieve 1 kHz+ switching without sacrificing current-handling. Wind converter OEMs are qualifying these architectures for next-generation turbine designs.
- Silicon:Mature manufacturing scale and established reliability data sustain dominance in cost-sensitive industrial drives.
- SiC:Full silicon carbide implementations above 3.3 kV are penetrating frequency-critical niches where complete IGCT replacement becomes economical.
- GaN:Gallium nitride remains below IGCT voltage thresholds, with no commercial penetration in 4.5 kV+ applications.
Silicon technology carries the majority of installed base. Hybrid architectures are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Divergent efficiency mandates across major economies are redirecting IGCT procurement toward jurisdictions with favorable cost-of-compliance profiles. China's dual carbon goals and the EU F-Gas Regulation impose stricter loss thresholds than EPA industrial motor standards, compressing margins for suppliers serving multiple regulatory regimes. Production planning increasingly weights certification timelines against market access premiums.
China
State Grid's procurement mandates for 25-year service life guarantees are reshaping supplier qualification requirements. GB/T energy efficiency codes now cap switching losses for semiconductors above 2.5 kV, forcing redesigns of thermal management systems in Shanghai and Shenzhen manufacturing clusters. The dual carbon policy framework accelerates displacement of phase-controlled devices in new installations.
Germany
Siemens and ABB supply chains anchor European IGCT consumption through traction and industrial drive portfolios. The EU F-Gas Regulation phases down fluorinated greenhouse gases in electrical equipment, pushing manufacturers toward solid-state switching with lower thermal footprints. The Ruhr region's cement and steel mills maintain substantial installed bases of legacy phase-controlled devices.
United States
EPA efficiency mandates for industrial motor systems tighten permissible loss profiles for drive-integrated power electronics. Utility-scale solar and wind installations in Texas and California require megawatt-scale converters where IGCT robustness outperforms IGBT series connection complexity. FERC grid interconnection standards influence procurement specifications for HVDC link applications.
Japan
METI-backed rail electrification programs specify IGCT-based traction drives for reliability in 25 kV AC systems. Mitsubishi Electric specializes in high-voltage rail applications where reliability requirements exclude most competitors. The Kansai and Chubu industrial corridors concentrate demand for voltage-controlled variants in factory automation retrofits.
India
The PLI scheme for power electronics creates localized assembly opportunities for IGCT-based drives serving steel and cement sectors. CEA grid modernization mandates tighten efficiency standards for high-power semiconductors in utility-scale renewable projects. Maharashtra and Gujarat industrial clusters are qualifying domestic suppliers for medium-voltage motor control applications.
Integrated Gate Commutated Thyristors (IGCT) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated power systems providers capturing premium positioning in renewable energy while component suppliers serve cost-sensitive industrial retrofits. Market concentration reflects the scarcity of hermetic ceramic housing design expertise and thermal management engineering capabilities. Three archetypes dominate: diversified electrical equipment conglomerates with captive semiconductor fabrication, specialized power semiconductor houses with deep application engineering, and rail-focused traction drive specialists. Competitive moves center on gate driver integration roadmaps and SiC hybrid architecture partnerships.
Among diversified electrical equipment conglomerates, Hitachi Energy and ABB occupy positions bundling predictive maintenance contracts with hardware shipments. Mitsubishi Electric exemplifies the traction drive specialist archetype, anchoring high-reliability rail applications. These three companies represent distinct strategic postures: systems integration expertise, European industrial drive dominance, and Japanese rail electrification specialization respectively.
| Leading Market Players |
|---|
| Hitachi Energy |
| CRRC Corporation Limited |
| ABB |
| Semikron International |
| Fuji Electric |
| Infineon Technologies |
| General Electric |
| Toshiba Corporation |
| Mitsubishi Electric |
| Others |
Supply & Pricing Matrix
Rail OEM procurement concentration in Germany and Japan anchors contract-based long-term offtake pricing for high-reliability IGCT variants, while utility-scale renewable developers in China and India negotiate project-based bundles where gate driver integration premiums dominate total cost.
Pricing Analysis
Capacity additions in China's power electronics manufacturing clusters are reshaping price floors for standardized industrial drive variants. Three-tier pricing structure across premium, standard, and economy levels separates voltage-controlled renewable energy specifications from phase-controlled retrofit devices. Cost compression in the economy tier intensifies because domestic Chinese suppliers are qualifying for State Grid procurement under GB/T loss thresholds. Cement and steel mills in Germany's Ruhr region exhibit highest price sensitivity due to legacy installation retrofit economics, while North Sea offshore wind developers show lowest sensitivity where 25-year service life guarantees override upfront component costs.
Supply Chain Analysis
Dual-sourcing mandates from European rail OEMs and Chinese grid operators require IGCT buyers to qualify suppliers across Germany, Japan, and China simultaneously. Hermetic ceramic housing production draws from specialized manufacturing bases in Switzerland and Japan, while precision magnetic components for gate drivers rest on Taiwanese and South Korean substrate suppliers. Single-source vulnerability concentrates in high-purity silicon wafer supply where geopolitical export controls threaten substrate availability. Distribution runs through authorized systems integrators who bundle predictive maintenance software with hardware shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IGCT procurement has shifted toward late-cycle quality specifications as China's dual carbon goals and EU F-Gas Regulation tighten loss thresholds beyond legacy device capabilities.
For Market Incumbents: Hedge silicon carbide substitution risk by accelerating SiC hybrid architecture partnerships before full SiC devices penetrate above 3.3 kV. Secure backward integration into gate driver magnetic component supply to defend against 15-20% BOM cost concentration. Lock in 25-year service contracts with State Grid and Deutsche Bahn before independent software providers fragment bundled pricing relationships. For New Entrants and Emerging Players: India's PLI scheme for power electronics opens a window for domestic IGCT assembly targeting Maharashtra and Gujarat steel and cement sectors. Target voltage-controlled retrofit demand in China's coastal manufacturing clusters where GB/T 2024 revisions disqualify phase-controlled alternatives. Pursue qualification partnerships with European wind turbine OEMs seeking second-source offshore wind converter supply. For Investors and Strategic Acquirers: Diversified electrical equipment conglomerates are the most active acquirer in this space, seeking captive semiconductor fabrication to secure gate driver integration roadmaps. Focus on specialized power semiconductor houses with hermetic ceramic housing expertise facing generational skill shortages. Watch SiC device qualification timelines above 4.5 kV as the inflection signal for IGCT displacement economics.| Strategic Initiative | Industry Significance |
|---|---|
| Gate Driver Integration Roadmap | Hitachi Energy bundles predictive maintenance contracts with hardware shipments to lock in recurring revenue. |
| SiC Hybrid Architecture Partnership | Combining silicon IGCT main switches with SiC diodes enables 1 kHz+ switching for Danish wind converter OEMs. |
| Domestic Manufacturing Localization | India's PLI scheme creates assembly opportunities for IGCT-based drives serving steel and cement sectors. |
| 25-Year Service Life Guarantee | State Grid procurement mandates force thermal management redesigns in Shanghai manufacturing clusters. |
| Phase-Controlled Device Displacement | China's GB/T energy efficiency codes accelerate voltage-controlled variant adoption in new installations. |
Research Methodology
Coverage spans China, Germany, Japan, India, and the United States, with primary inputs from each market through interviews with power systems integration engineers, rail traction procurement managers, renewable energy EPC contractors, and industrial drive maintenance directors. Secondary validation drew from IEC 60747 certification databases, GB/T standards filings, EU F-Gas Regulation implementation reports, and SEC filings from listed electrical equipment manufacturers. Bottom-up unit demand estimates triangulated against top-down power electronics market sizing.
Rate-of-change decomposition anchored the analytical framework across the projection horizon, modeling volume and value trajectories by product type, application, end user, and technology substrate. Segmentation dimensions included voltage control methodology, renewable energy versus industrial drive end-use, and silicon versus hybrid SiC architecture. CAGRs derived from regression analysis against installed capacity growth in utility-scale solar and wind, rail electrification program commitments, and industrial motor efficiency mandate tightening.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt SiC device cost reductions or geopolitical disruption to precision magnetic component supply. Deviation in China's dual carbon policy enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Thyristor Surge Protectors Market
Power Systems
Japan Surge Protector Market
Power Systems
Germany Rechargeable Battery Market
Power Systems
Embedded Power Generation Market
Power Systems
Charge Pumps Market
Power Systems
AC DC Power Adapter Market
Power Systems
BCD Power IC Market
Power Systems
MCR Based Static VAR Compensator Market
Power Systems
Low Voltage AC Drive Market
Power Systems
E-Axle Inverter and Control Unit Systems Market
Power Systems
USB Power Adapters Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Switch Mode Power Supply (SMPS) Market
Power Systems
South Korea Battery Management Systems Market
Power Systems
Power Semiconductor Market
Power Systems
Thermoelectric Generator (TEG) Market