
 Latin America Lidar Market | 2026-2036
Latin America Lidar Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Lidar Market Foresight
Subscription-based software-defined feature licensing is hardening as the dominant commercial model for lidar data processing across Latin America. Velodyne Lidar Inc. leverages its sensor-software bundling strategy to anchor recurring revenue streams with large infrastructure contractors. Trimble Inc. sustains channel control through its established dealer network serving agricultural and construction clients from São Paulo to Mexico City. FARO Technologies Inc. specializes in high-precision terrestrial scanning for forensic and industrial metrology niches.
Light detection and ranging (lidar) systems emit pulsed laser light and measure return time to generate dense three-dimensional point clouds, typically achieving centimeter-level accuracy at ranges from tens to hundreds of meters; these point clouds serve as foundational datasets for topographic mapping, asset inspection, and volumetric analysis. Aerial lidar dominates procurement budgets across Latin American transportation ministries due to its efficiency in corridor mapping for road and rail expansion. Mobile lidar is displacing static terrestrial setups in urban planning applications across rapidly densifying Mexican and Colombian cities. Time-of-Flight technology leads unit shipments while Frequency Modulated Continuous Wave architectures attract R&D investment for their superior performance in adverse weather conditions.
Brazil's national spatial data infrastructure mandates and Mexico's federal surveying standards shape public-sector procurement specifications, filtering market access to vendors with certified calibration protocols. Chile's mining safety regulator and Peru's environmental compliance frameworks require periodic geotechnical monitoring, directly stimulating bathymetric and terrestrial lidar deployments at open-pit and tailings facilities. Stakeholders must monitor evolving data localization requirements and cross-border cloud processing restrictions that could reshape how point cloud analytics are delivered to government and enterprise clients.
Market Dynamics
Subscription-based software licensing is hardening as the dominant commercial model across Latin America, compressing upfront hardware margins while anchoring recurring revenue streams for vendors with large infrastructure contractors.
Growth Catalysts
- Brazil's spatial data mandates:The country's updated national spatial data infrastructure requirements accelerate government procurement of survey-grade systems for cadastral mapping and environmental monitoring.
- Chilean mining safety protocols:The national mining regulator mandates periodic geotechnical monitoring at open-pit and tailings facilities, directly stimulating bathymetric and terrestrial lidar deployments.
- Frequency Modulated Continuous Wave R&D:This architecture attracts investment for superior performance in adverse weather conditions, expanding operational windows in tropical and high-altitude environments.
Market Restraints
- Import dependency for precision optics:Laser emitters and photodetector arrays concentrate in East Asian supply chains, exposing Latin American integrators to currency volatility and extended lead times.
- Calibration certification bottlenecks:Brazil's INCRA and Mexico's federal surveying standards require vendor-specific certification protocols that filter market access to established players with accredited laboratories.
- Photogrammetry substitution in low-accuracy applications:Drone-based photogrammetry captures topographic mapping contracts where centimeter precision is not contractually specified.
Strategic Opportunities
- Colombian urban densification corridors:Mobile lidar penetration remains below aerial and terrestrial alternatives in Bogotá and Medellín planning departments, creating first-mover advantages for mobile mapping specialists.
- Peruvian environmental compliance frameworks:Tailings facility monitoring requirements expand beyond mining operators to encompass hydroelectric and agricultural reservoir operators.
- Edge computing convergence:Onboard point cloud preprocessing reduces bandwidth requirements for cloud-restricted government clients navigating evolving data localization mandates.
Industry Challenges
- Geodetic surveyor scarcity:Certified professionals capable of executing control network design for high-precision aerial campaigns concentrate in São Paulo and Mexico City, constraining project scaling in secondary markets.
- Legacy CAD integration friction:Point cloud-to-BIM workflows require custom middleware development for infrastructure contractors operating decade-old Autodesk and Bentley installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Lidar Market |
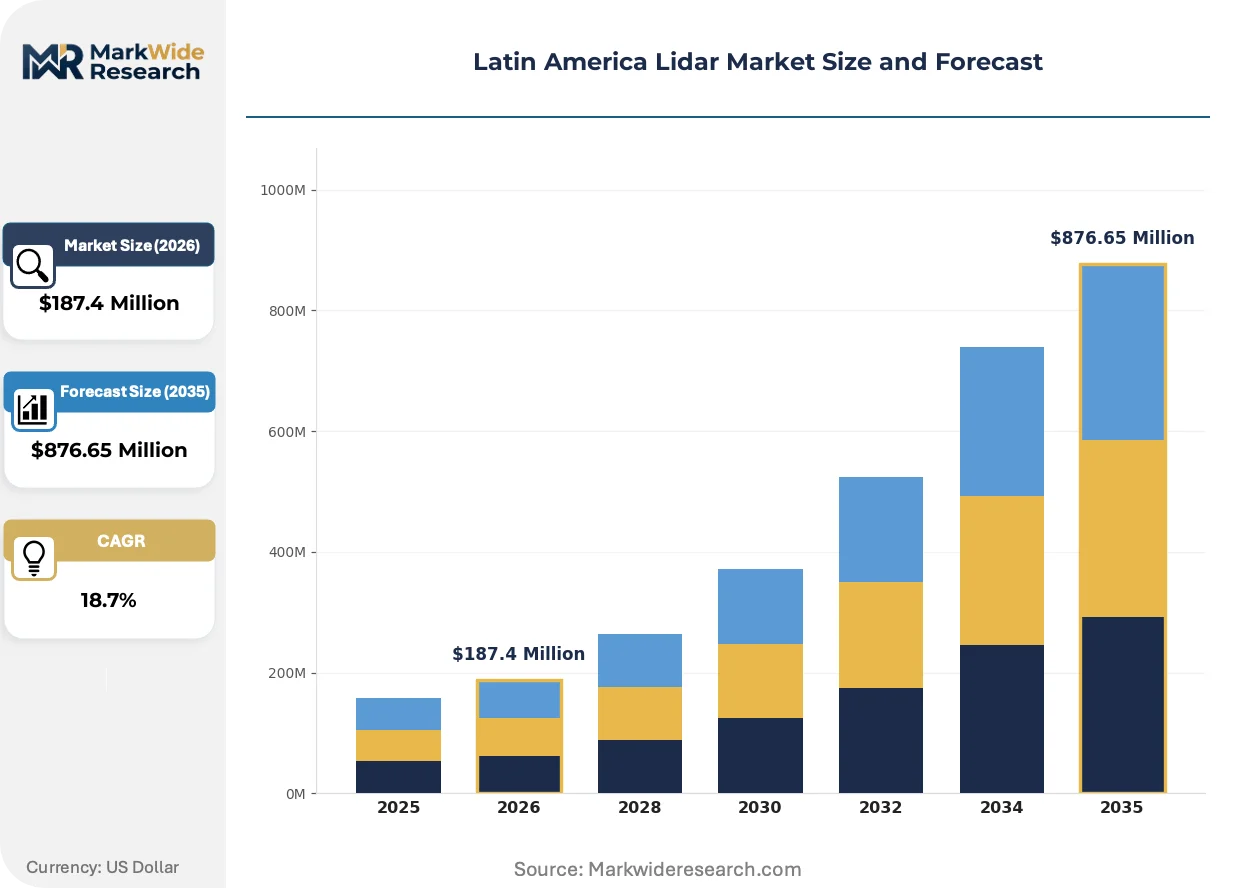
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terrestrial Lidar, Aerial Lidar, Mobile Lidar, Bathymetric Lidar End User: Transportation, Agriculture, Construction, Mining Technology: Time-of-Flight, Frequency Modulated Continuous Wave, Coherent, Non-Coherent Application: Mapping, Surveying, Environmental Monitoring, Urban Planning |
| Companies Covered | Leica Geosystems AG, Velodyne Lidar Inc., Sick AG, Jenoptik AG, Trimble Inc., FARO Technologies Inc., Teledyne Technologies Inc., RIEGL USA, Neptec Technologies Corp, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Lidar Market Shifts & Advancements
Hardware commoditization is compressing sensor margins while software-defined feature licensing and edge analytics reshape how value is captured across the value chain.
Frequency Modulated Continuous Wave lidar is overtaking Time-of-Flight architectures in R&D investment portfolios across Brazilian and Chilean system integrators. Mining operators in the Andean corridor pilot FMCW units for dust-penetration applications where pulsed systems generate sparse returns. This technology is overtaking conventional approaches in environmental monitoring contracts where adverse weather clauses penalize data collection delays.
Data localization requirements are tightening across Latin American public-sector procurement specifications. Brazil's updated national spatial data infrastructure mandates and emerging cross-border cloud processing restrictions in Mexico reshape how point cloud analytics are delivered to government clients. Vendors with in-country edge processing capabilities capture transportation ministry contracts that exclude foreign-hosted processing environments.
Subscription licensing is displacing perpetual software purchases among large infrastructure contractors from São Paulo to Mexico City. Feature-unlocking models tie processing capabilities to recurring payments rather than upfront capital expenditure. This shift concentrates most visibly in corridor mapping applications where project-based contracting previously dominated vendor-client relationships.
Latin America Lidar Market Segmentation
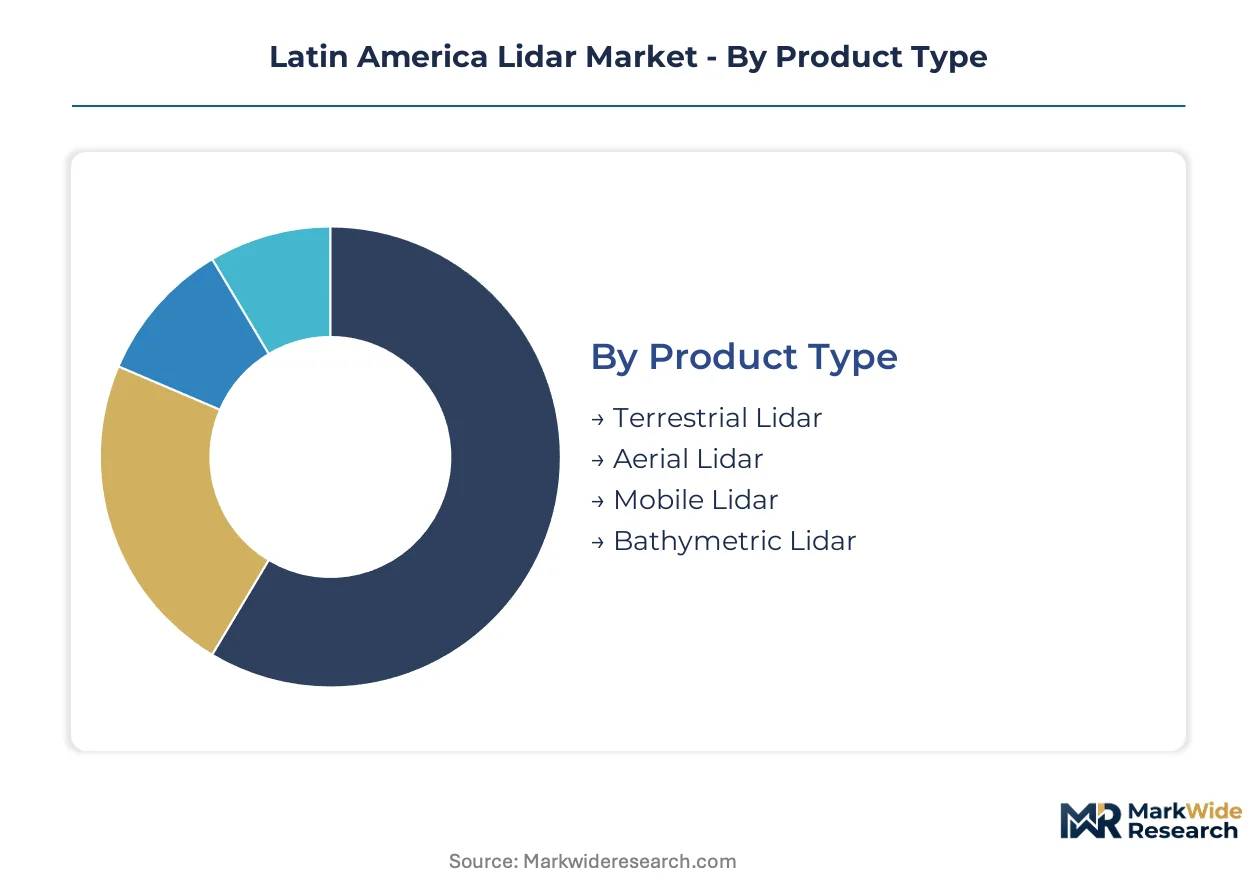
Segmentation reveals how certification burdens and procurement specifications fragment vendor access across Latin America's lidar landscape. Each dimension—product, end user, technology, and application—carries distinct regulatory filters that determine competitive positioning.
Product Type:
Certification requirements diverge sharply across product categories, with aerial systems facing Brazil's INCRA calibration mandates and terrestrial scanners subject to Mexico's federal surveying standards.
- Aerial Lidar:Airborne laser scanning systems mounted on fixed-wing aircraft and helicopters achieve corridor-scale coverage with pulse repetition rates exceeding 400 kHz. Transportation ministries in Brazil and Mexico concentrate procurement budgets here for road and rail expansion projects, though ANAC and DGAC operational certifications create vendor entry barriers.
- Terrestrial Lidar:Tripod-mounted static scanners deliver sub-millimeter precision for forensic documentation and industrial metrology. Mining operators in Chile's Atacama Desert and Peru's Andean corridor deploy these for geotechnical monitoring, where the national mining regulator mandates periodic structural assessment.
- Mobile Lidar:Vehicle-mounted systems integrate IMU and GNSS for continuous street-level capture at highway speeds.
- Bathymetric Lidar:Green-wavelength systems penetrate water columns for riverbed and coastal mapping, required under Peruvian environmental compliance frameworks.
Leading the category by volume: Aerial Lidar. Growing fastest: Mobile Lidar.
End User:
Cost tiers separate end-user segments, with mining and transportation commanding premium survey-grade budgets while agriculture operates at standard-tier price points.
- Mining:Open-pit operators and tailings facility managers in Chile and Peru anchor demand for geotechnical stability monitoring. The sector absorbs the highest per-unit prices due to safety-critical applications where data gaps trigger regulatory penalties.
- Construction:Large infrastructure contractors from São Paulo to Mexico City drive subscription software licensing adoption for earthwork volumetrics and progress monitoring.
- Transportation:Federal and state ministries fund corridor mapping for highway expansion and rail rehabilitation across Brazil and Mexico.
- Agriculture:Precision farming operations in Mato Grosso and Buenos Aires provinces adopt lower-cost drone-integrated systems for terrain modeling and drainage planning.
Capturing the largest procurement budgets: Mining. Expanding most quickly: Construction.
Technology:
Maturity curves separate established Time-of-Flight architectures from emerging Frequency Modulated Continuous Wave R&D investments across Brazilian and Chilean system integrators.
- Time-of-Flight:Pulsed laser systems dominate current unit shipments with proven performance in standard atmospheric conditions. The technology anchors most operational deployments across Latin American transportation and construction sectors due to lower unit costs and established maintenance networks.
- Frequency Modulated Continuous Wave:Continuous-wave systems with coherent detection enable dust penetration and adverse-weather operation. Andean mining operators pilot these units where pulsed systems generate sparse returns in high-particulate environments.
- Coherent:Phase-sensitive detection architectures enable Doppler velocity measurement for specialized meteorological and atmospheric research applications.
- Non-Coherent:Direct-detection systems serve cost-sensitive applications where velocity data is unnecessary.
Holding dominant share: Time-of-Flight. Gaining share fastest: Frequency Modulated Continuous Wave.
Application:
Customer type stratification distinguishes government-mandated surveying contracts from private-sector environmental monitoring engagements.
- Mapping:Large-scale topographic base mapping underpins cadastral systems and national spatial data infrastructure initiatives. Brazil's updated mandates accelerate procurement here, with INCRA specifying certified calibration protocols that filter vendor participation.
- Surveying:Engineering-grade measurement for construction staking and boundary determination concentrates revenue in certified professional surveyor networks.
- Environmental Monitoring:Tailings dam stability and deforestation tracking applications expand under Chilean and Peruvian regulatory frameworks.
- Urban Planning:Mobile and terrestrial deployments support densification modeling in Bogotá and Medellín planning departments.
Generating the highest contract values: Mapping. Climbing the fastest: Environmental Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil consumes the largest share of lidar hardware across Latin America, yet precision optics and laser emitter supply chains remain concentrated in East Asian manufacturing hubs. Mexico and the Andean mining corridor generate specialized demand for geotechnical monitoring systems.
Brazil
Transportation ministries in Brasília and São Paulo drive aerial lidar procurement for highway corridor mapping under updated national spatial data infrastructure mandates. INCRA certification requirements filter vendor access to established players with accredited calibration laboratories. São Paulo anchors the region's largest concentration of certified geodetic surveyors capable of executing control network design for high-precision campaigns.
Mexico
Federal surveying standards shape public-sector procurement specifications for cadastral mapping and urban densification projects. DGAC operational certifications for airborne systems create entry barriers for unproven vendors. Mexico City planning departments accelerate mobile lidar adoption for street-level capture in rapidly densifying metropolitan zones.
Chile
Open-pit mining operators in the Atacama Desert deploy terrestrial and bathymetric systems for tailings facility monitoring. The national mining regulator mandates periodic geotechnical assessments that trigger direct equipment procurement. Santiago hosts the regional headquarters for several survey-grade system integrators serving Andean corridor clients.
Peru
Environmental compliance frameworks expand lidar deployment beyond mining to hydroelectric and agricultural reservoir operators. Tailings dam stability monitoring requirements stimulate green-wavelength bathymetric system adoption. Lima concentrates demand for integrated sensor-software bundles among large infrastructure contractors.
Colombia
Urban planning applications in Bogotá and Medellín create first-mover opportunities for mobile mapping specialists as densification accelerates. Municipal procurement budgets favor subscription-based software licensing over perpetual purchases. The Andean highland corridor pilots Frequency Modulated Continuous Wave units for dust-penetration applications where pulsed systems underperform.
Latin America Lidar Market Competitive Landscape
Top-tier vendors anchor premium survey-grade positioning, while mid-tier specialists compete on software-defined feature licensing and regional service density. The vendor base stratifies across three archetypes: sensor-software bundlers, precision hardware fabricators, and niche terrestrial scanning specialists. Consolidation pressure concentrates among infrastructure contractors demanding integrated point cloud-to-BIM workflows. Strategic moves center on edge computing capability builds and in-country calibration laboratory accreditation.
Within the sensor-software bundler archetype, Velodyne Lidar Inc. and Trimble Inc. occupy positions that exemplify recurring revenue anchoring with large infrastructure contractors from São Paulo to Mexico City. FARO Technologies Inc. sits within the precision terrestrial scanning specialization. Sick AG and Jenoptik AG represent German-based fabricators with established industrial automation positioning. Leica Geosystems AG, Teledyne Technologies Inc., and RIEGL USA anchor the premium-tier hardware vector with survey-grade system legacies.
| Leading Market Players |
|---|
| Leica Geosystems AG |
| Velodyne Lidar Inc. |
| Sick AG |
| Jenoptik AG |
| Trimble Inc. |
| FARO Technologies Inc. |
| Teledyne Technologies Inc. |
| RIEGL USA |
| Neptec Technologies Corp |
| Others |
Supply & Pricing Matrix
Laser emitter and photodetector array costs cascade through three distinct pricing tiers, with East Asian sourcing concentration amplifying currency-driven volatility for Brazilian and Mexican system integrators facing INCRA and federal surveying certification mandates.
Pricing Analysis
Margin tightening in survey-grade systems reflects hardware commoditization compressing sensor margins while software-defined feature licensing anchors recurring revenue. Three-tier pricing structure across premium, standard, and economy levels separates certified calibration-grade systems from uncertified alternatives, with transportation ministries in Brazil and Mexico absorbing premium tiers and agricultural drone operators in Mato Grosso clustering at economy levels. Cost-down pressure on terrestrial scanners accelerates because photogrammetry substitution captures low-accuracy contracts. Mining operators in Chile and Peru exhibit least price sensitivity due to safety-critical regulatory mandates, while municipal planning departments in Colombia demonstrate highest elasticity.
Supply Chain Analysis
Precision optics supply rests on Chinese, Japanese, and South Korean specialty component manufacturers, with laser diode arrays and avalanche photodiodes constituting critical path items. Inertial measurement units and GNSS receivers draw from Taiwanese and German industrial sensor networks. Single-source vulnerability concentrates in high-pulse-rate laser emitters where qualified alternative suppliers require 18-24 month requalification cycles. Distribution runs through São Paulo and Mexico City-based system integrators with accredited calibration laboratories, filtering foreign direct sales to end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over edge computing capabilities and in-country calibration infrastructure determines contract access under tightening data localization mandates.
For Market Incumbents: To counter hardware commoditization eroding sensor margins, deepen software-software bundling to lock recurring revenue with infrastructure contractors from São Paulo to Mexico City. Secure INCRA and federal surveying certification accreditations to filter competitor access to Brazilian and Mexican public-sector procurement. Expand edge processing capability builds to capture transportation ministry contracts excluding foreign-hosted cloud environments. For New Entrants and Emerging Players: Enter via mobile lidar penetration gaps in Colombian urban planning departments where densification accelerates but aerial systems still dominate procurement. Target Peruvian environmental compliance frameworks extending tailings monitoring requirements to hydroelectric and agricultural reservoir operators. Pursue subscription-based software licensing models that municipal budgets favor over perpetual purchases. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier mobile mapping specialists with established Colombian or Peruvian channel relationships over hardware-commoditized sensor fabricators. Long-term viability hinges on software attach rates and recurring revenue mix rather than unit shipment volume. Watch FMCW technology maturation as inflection indicator for technology substitution risk in Andean mining applications.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Capability Build | Captures Brazilian transportation ministry contracts excluding foreign cloud processing under data localization mandates. |
| Calibration Laboratory Accreditation | Filters market access to INCRA-certified vendors for Brazil's national spatial data infrastructure procurement. |
| Sensor-Software Bundling | Anchors recurring revenue streams with large infrastructure contractors replacing perpetual purchase models. |
| Mobile Lidar Geographic Expansion | Penetrates under-served Colombian urban planning departments accelerating densification modeling adoption. |
| FMCW Technology Licensing | Addresses dust-penetration requirements in Chilean and Peruvian mining safety protocols where pulsed systems underperform. |
Research Methodology
Document review covered customs trade records, INCRA certification registries, and mining regulator compliance filings, complemented by interviews with geodetic surveyors, transportation ministry procurement officers, mining safety engineers, and system integrator technical directors. Secondary validation drew from ANAC and DGAC operational certification databases, Chilean mining regulator geotechnical monitoring mandates, and Peruvian environmental compliance framework documentation. Bottom-up unit shipment estimates triangulated against top-down procurement budget allocations across Brazilian, Mexican, and Andean corridor public-sector contracts.
Historical deployment patterns cross-referenced against panel input from equipment distributors and rental fleet operators shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user sector, technology architecture, and application category, with regulatory certification tier and data localization requirement status as lidar-specific overlay variables. CAGRs derived from unit shipment trajectory analysis weighted by average selling price evolution, incorporating edge computing adoption curves and subscription licensing penetration as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under currency volatility spikes affecting East Asian component sourcing and accelerated data localization mandate enforcement. Forecasts reflect assumptions regarding certification timeline stability and mining regulatory continuity. Supply chain disruption, abrupt trade restriction imposition, or photogrammetry technology leapfrogging could revise trajectory. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
Connected Sensors Market
Sensors and Controls
Europe Smart Air Purifier Market
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Smart Temporal Thermometer Market
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
Touch Sensor Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
Temperature Monitoring Devices Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
DCT Mechatronic Control Unit Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Laser Sensor Market