
 Train Auxiliary Rectifier Market | 2026-2036
Train Auxiliary Rectifier Market Size, Share, and Industry Trends Forecast 2026-2036
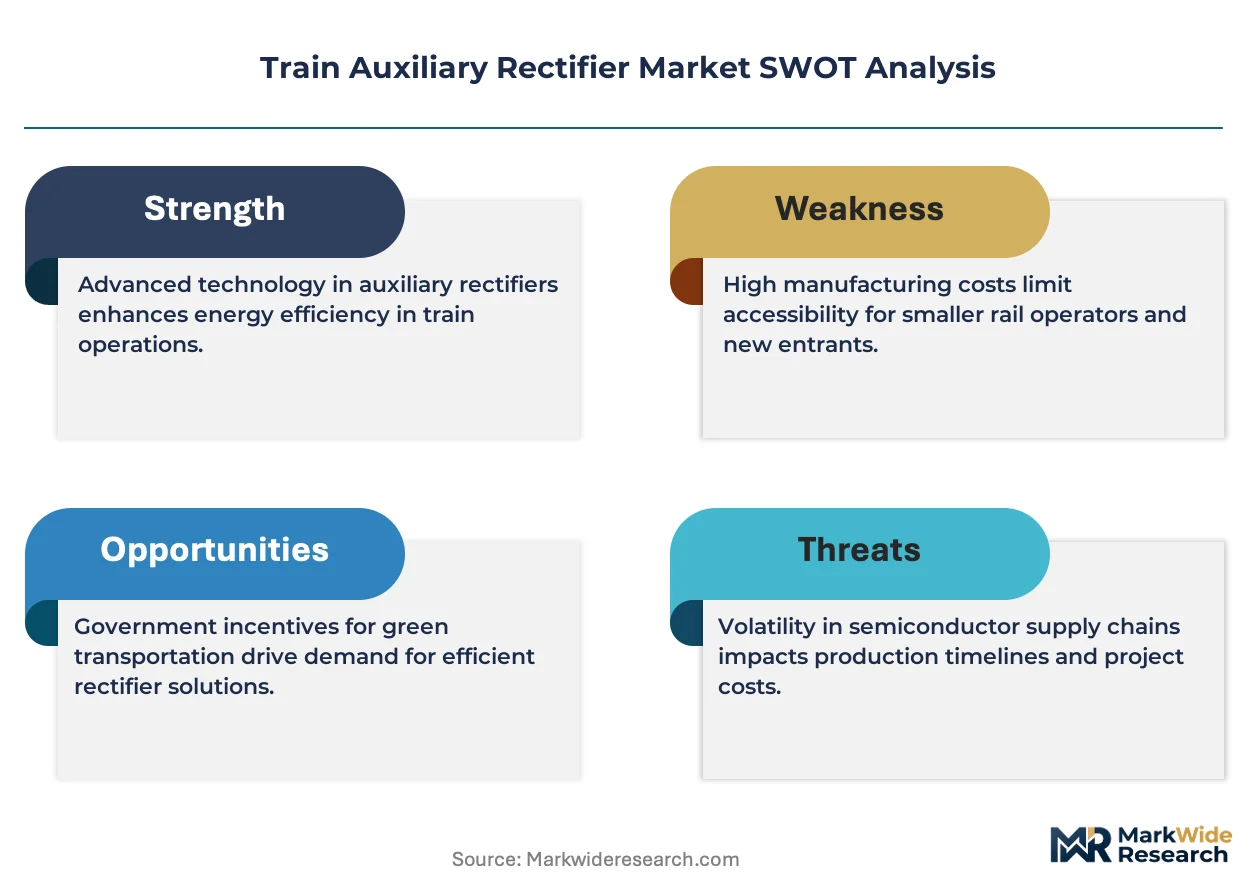
Train Auxiliary Rectifier Market Analysis
Urban transit authorities are bifurcating from freight operators as the dominant procurement archetype for auxiliary rectifiers. ABB leverages its integrated power electronics portfolio to anchor European light rail electrification projects. Siemens sustains technology leadership through proprietary thyristor rectifier platforms deployed across German and Austrian intercity networks. CRRC dominates captive supply chains for China's expanding high-speed rail fleet, while Alstom competes aggressively in North African and Southeast Asian tender markets.
Train auxiliary rectifiers convert alternating current from overhead catenary or third-rail systems into direct current for onboard auxiliary loads including lighting, HVAC, and control electronics, typically operating at output voltages between 24V and 110V DC with efficiency thresholds exceeding 95 percent in modern silicon-carbide designs. Thyristor rectifiers retain structural dominance in heavy freight applications where ruggedness outweighs efficiency premiums, while PWM rectifiers capture the fastest expansion in high-speed rail segments demanding regenerative braking compatibility and harmonic distortion below 5 percent. Three-phase architectures concentrate margin pools in premium passenger applications, whereas single-phase variants occupy cost-sensitive retrofit markets across aging commuter fleets.
EU F-Gas Regulation and REACH constrain coolant and insulation material choices for rectifier thermal management systems, compelling redesign cycles among European OEMs. China's NMPA and GB standards enforce electromagnetic compatibility testing protocols that shape market access for imported power electronics. India's CEA railway electrification mandates and BIS certification requirements are accelerating domestic procurement localization. Stakeholders must monitor how cascading efficiency standards across multiple regulatory jurisdictions reshape component sourcing strategies and manufacturing location decisions.
Market Dynamics
Silicon-carbide power semiconductors are restructuring procurement priorities across rail electrification programs, as efficiency thresholds above 95 percent become baseline specifications rather than premium differentiators in auxiliary rectifier tenders.
Growth Catalysts
- China's high-speed rail expansion:Fleet electrification programs along Beijing-Shanghai and Chengdu-Chongqing corridors are generating concentrated demand for regenerative braking-compatible rectifier systems.
- EU F-Gas Regulation:Thermal management redesign mandates are accelerating replacement cycles for legacy coolant-dependent rectifier installations across German and French intercity networks.
- Silicon-carbide MOSFET adoption:Wide-bandgap semiconductor platforms are enabling compact auxiliary power units with harmonic distortion below 5 percent in premium passenger applications.
Market Restraints
- Raw material concentration:Rare earth element processing for high-performance magnetic components concentrates in Chinese supply chains, exposing European OEMs to input volatility.
- Technical limitation of legacy thyristors:Phase-controlled rectifier architectures cannot achieve regenerative braking compatibility without complete platform replacement, freezing upgrade paths for aging freight fleets.
- REACH compliance friction:Insulation material restrictions are extending prototype validation timelines by 8-14 months for rectifier thermal management systems targeting EU markets.
Strategic Opportunities
- India's railway electrification mandate:CEA directives and BIS certification requirements are creating localized procurement windows for domestic manufacturing investments in auxiliary power electronics.
- North African tender markets:Morocco and Egypt are expanding light rail networks with EU-compliant specifications, opening channels for rectifier suppliers with established REACH documentation.
- Digital twin integration:Predictive maintenance platforms converging with power electronics are enabling performance-based service contracts for auxiliary rectifier lifecycle management.
Industry Challenges
- Electromagnetic compatibility certification:China's GB standards and NMPA testing protocols require dedicated validation facilities, raising market entry costs for non-domestic suppliers.
- Legacy system integration:Three-phase rectifier architectures demand complete rewiring of aging commuter fleets with single-phase infrastructure, complicating retrofit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Train Auxiliary Rectifier Market |
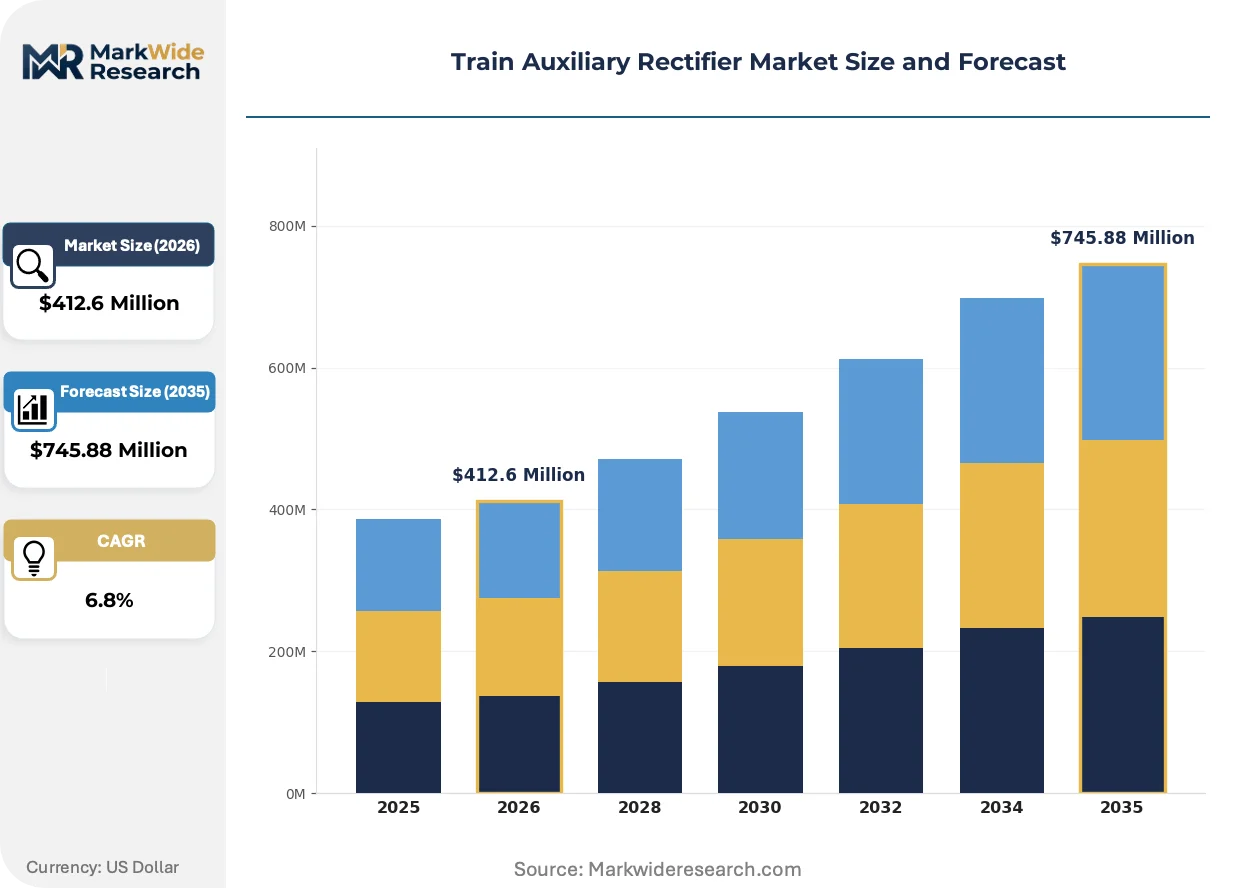
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
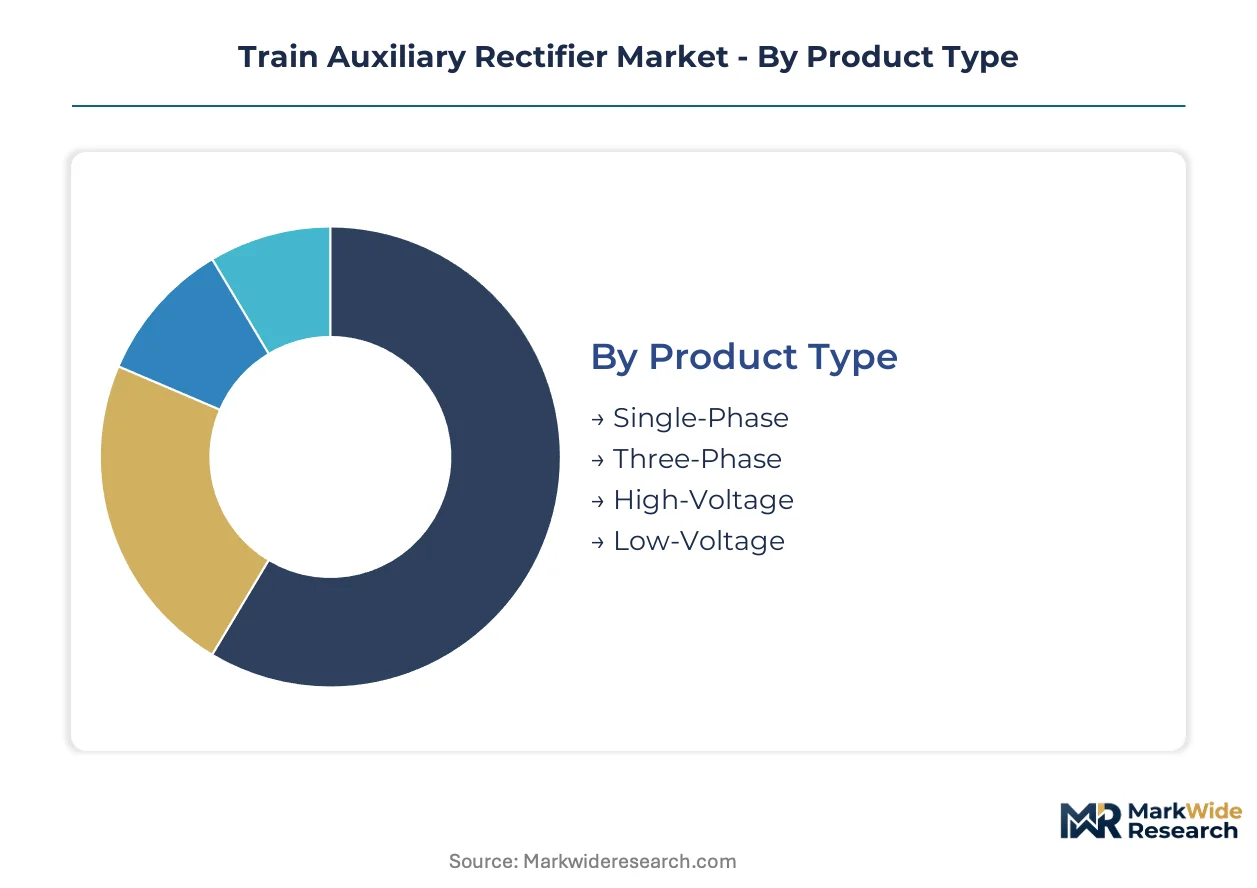
| Segmentation | Product Type: Single-Phase, Three-Phase, High-Voltage, Low-Voltage Technology: Diode Rectifiers, Thyristor Rectifiers, ACDC Converters, PWM Rectifiers Application: Passenger Trains, Freight Trains, Light Rail, High-Speed Rail End User: Rail Operators, OEMs, Maintenance Providers, Infrastructure Companies |
| Companies Covered | ABB, Siemens, MEIDENSHA CORPORATION, Fuji Electric, Medcom, Alstom, Hitachi Rail, CRRC, Hind Rectifiers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Train Auxiliary Rectifier Market Emerging Trajectories
Power semiconductor material transitions and thermal management redesigns are compressing product development cycles, while procurement centralization among national rail operators is consolidating specification authority.
Silicon-carbide rectifier modules convert overhead catenary AC to onboard DC with switching frequencies exceeding 50 kHz, enabling dramatic passive component downsizing. High-speed rail operators in China and Japan are specifying SiC-based auxiliary power units as standard equipment in new fleet tenders. Thyristor-based platforms are supplanting diode rectifiers in heavy freight retrofit markets where ruggedness premiums outweigh efficiency gains.
EU F-Gas Regulation bans hydrofluorocarbon coolants in rectifier thermal management systems above specific global warming potential thresholds. European OEMs are redesigning heat sink architectures and adopting phase-change materials to maintain thermal performance. Premium passenger applications in Germany and Austria face the steepest compliance costs due to higher power density requirements.
Rail operators are consolidating auxiliary rectifier procurement through framework agreements covering decade-long fleet renewal cycles. Traditional distributor channels serving maintenance depots are losing volume to direct OEM contracting with national infrastructure authorities. China's CRRC and India's Integral Coach Factory demonstrate this pattern most visibly, with captive technical specifications displacing open competitive tendering for auxiliary power electronics.
Train Auxiliary Rectifier Market Segmentation
Auxiliary rectifier procurement splits sharply across voltage classes and semiconductor architectures. Regulatory frameworks in China, the European Union, and India enforce distinct electromagnetic compatibility and material compliance standards that reshape segment viability.
Product Type:
EU F-Gas Regulation and REACH compliance create divergent thermal management requirements across voltage tiers, with high-density designs facing steeper redesign cycles.
- Three-Phase:These architectures deliver balanced load distribution across auxiliary systems in premium passenger applications. German and Austrian intercity networks concentrate procurement here, driven by regenerative braking compatibility mandates that single-phase designs cannot satisfy.
- High-Voltage:Operating above 750V DC output, these systems integrate silicon-carbide MOSFET platforms for switching frequencies exceeding 50 kHz. China's Beijing-Shanghai and Chengdu-Chongqing corridors specify these units as standard equipment in new high-speed fleet tenders.
- Single-Phase:Dominant in aging commuter fleet retrofits across France and Italy where infrastructure rewiring costs prohibit three-phase migration.
- Low-Voltage:Standard for light rail HVAC and lighting loads in Moroccan and Egyptian networks with EU-compliant specifications.
Established volume favors Three-Phase; emerging adoption favors High-Voltage.
Technology:
Cost tiers separate legacy thyristor platforms from premium silicon-carbide designs, with freight operators anchoring the former and high-speed rail the latter.
- Thyristor Rectifiers:Phase-controlled architectures withstand electrical stress in heavy freight duty cycles. German freight operators retain these systems where ruggedness premiums outweigh efficiency gains, though regenerative braking incompatibility locks out upgrade paths.
- PWM Rectifiers:Pulse-width modulation enables harmonic distortion below 5 percent and full regenerative capability. Japanese Shinkansen and Chinese Fuxing fleets mandate these for auxiliary power units in new-build tenders.
- Diode Rectifiers:Uncontrolled rectification occupies cost-sensitive retrofit markets across India's aging commuter fleets under CEA electrification mandates.
- ACDC Converters:Integrated conversion stages serve maintenance providers performing depot-level auxiliary power unit replacements in North African light rail networks.
Margin concentration sits with PWM Rectifiers; volume retention sits with Thyristor Rectifiers.
Application:
Customer procurement authority clusters differently across passenger and freight modes, with national infrastructure authorities dominating the former and private operators the latter.
- High-Speed Rail:Fleet electrification programs demand regenerative braking compatibility and electromagnetic compliance with China's GB standards and NMPA testing protocols. These specifications displace open competitive tendering in favor of captive technical requirements.
- Light Rail:Urban transit authorities in Morocco and Egypt are expanding networks with EU F-Gas and REACH-compliant auxiliary power electronics, opening channels for suppliers with established documentation.
- Passenger Trains:Regional operators across France and Spain prioritize thermal management redesigns to eliminate hydrofluorocarbon coolants above global warming potential thresholds.
- Freight Trains:Heavy-haul operators in Germany and Austria accept efficiency trade-offs for thyristor ruggedness in unidirectional power flow applications.
Specification authority concentrates in High-Speed Rail; retrofit opportunity concentrates in Light Rail.
End User:
Supply chain configuration shifts as framework agreements displace traditional distributor channels across decade-long fleet renewal cycles.
- Rail Operators:National infrastructure authorities in China and India consolidate procurement through captive specifications at CRRC and Integral Coach Factory, eliminating open tendering for auxiliary power electronics.
- OEMs:Rolling stock manufacturers in Germany and France face REACH compliance friction extending prototype validation timelines by 8-14 months for thermal management systems.
- Maintenance Providers:Depot-level service operations lose volume to direct OEM contracting as predictive maintenance platforms enable performance-based lifecycle contracts.
- Infrastructure Companies:Third-rail and catenary system operators in Egypt and Morocco specify auxiliary rectifier compatibility in network expansion tenders.
Procurement centralization favors Rail Operators; service margin migration favors OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports auxiliary rectifier systems to Southeast Asian and North African rail electrification projects, while European OEMs supply Middle Eastern and Latin American fleet modernization programs through technology licensing arrangements.
China
Beijing-Shanghai and Chengdu-Chongqing high-speed corridors drive concentrated procurement for regenerative braking-compatible rectifier systems. NMPA and GB standards enforce electromagnetic compatibility testing protocols that shape market access for imported power electronics. CRRC's captive supply chains dominate technical specifications across the Yangtze River Delta manufacturing cluster.
Germany
German intercity networks anchor European demand for three-phase thyristor rectifiers in heavy freight duty cycles. EU F-Gas Regulation and REACH compliance extend prototype validation timelines by 8-14 months for thermal management redesigns. Siemens maintains technology leadership through proprietary platforms deployed across Bavaria and North Rhine-Westphalia rail infrastructure.
India
CEA railway electrification mandates and BIS certification requirements accelerate domestic procurement localization for auxiliary power electronics. The country's national railway regulator enforces electromagnetic compatibility protocols for imported components. Integral Coach Factory in Chennai consolidates framework agreements covering decade-long fleet renewal cycles.
Morocco
Light rail network expansion in Casablanca and Rabat generates demand for EU F-Gas and REACH-compliant auxiliary power units. The country's national infrastructure authority specifies thermal management standards aligned with European environmental regulations. Alstom competes aggressively in tender markets with established documentation for coolant-free rectifier designs.
Japan
Shinkansen fleet operators mandate PWM rectifier architectures with harmonic distortion below 5 percent for new-build auxiliary power units. METI efficiency standards drive silicon-carbide MOSFET adoption in premium passenger applications. Hitachi Rail anchors technology deployment across the Kanto and Kansai industrial corridors.
Train Auxiliary Rectifier Market Vendor Landscape
Listed leaders compete with private specialists across technology licensing and captive supply arrangements. The vendor base clusters around three strategic tiers: integrated power electronics conglomerates with full rolling stock portfolios, pure-play rectifier specialists serving retrofit markets, and state-backed rail equipment manufacturers with domestic procurement mandates. Primary competitive moves center on backward integration into semiconductor supply chains and geographic expansion through framework agreements with national infrastructure authorities.
Among European-based integrated suppliers, ABB and Siemens exemplify the conglomerate archetype with diversified power electronics portfolios spanning multiple voltage classes and semiconductor architectures. Alstom occupies a position within the international project specialist tier, competing in tender markets where EU regulatory documentation provides competitive differentiation. CRRC represents the state-backed captive supply archetype, with technical specifications displacing open competitive tendering in domestic procurement windows.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| MEIDENSHA CORPORATION |
| Fuji Electric |
| Medcom |
| Alstom |
| Hitachi Rail |
| CRRC |
| Hind Rectifiers |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation and REACH compliance simultaneously gate supplier qualification and stratify price tiers across auxiliary rectifier procurement, forcing OEMs to absorb thermal management redesign costs while buyers pay premiums for documented environmental compliance.
Pricing Analysis
Silicon-carbide MOSFET platforms command 15-25 percent premiums over legacy thyristor architectures, while diode-based systems occupy the economy tier in Indian retrofit markets. Three-tier pricing structure across premium, standard, and economy levels reflects semiconductor generation, with PWM rectifiers capturing mid-tier positioning through regenerative braking compatibility. Pricing pressure stems from rare earth magnet cost volatility in Chinese supply chains, compressing margins for European OEMs. Freight operators exhibit highest price sensitivity, accepting efficiency trade-offs for ruggedness, while high-speed rail authorities prioritize performance over unit cost.
Supply Chain Analysis
Extended prototype validation timelines of 8-14 months for REACH-compliant thermal management systems have stretched strategic inventory positions across German and French manufacturing clusters. Rare earth element processing concentrates in China, silicon-carbide wafer fabrication anchors in Japan and the United States, and final assembly clusters in Germany and India. Single-source vulnerability pervades magnetic component supply, with neodymium-dysprosium processing tethered to Chinese refiners. Distribution runs through direct OEM contracting with national rail operators, displacing traditional maintenance depot channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon-carbide semiconductor transitions and EU thermal management mandates are disrupting established procurement patterns, creating asymmetric opportunity windows across technology tiers and geographic markets.
For Market Incumbents: Secure backward integration into wide-bandgap semiconductor supply chains before Chinese and Japanese substrate manufacturers consolidate captive positions. Lock in decade-long framework agreements with China's CRRC and India's Integral Coach Factory to defend against emerging domestic suppliers leveraging BIS certification requirements as market entry barriers. For New Entrants and Emerging Players: Predictive maintenance platform integration represents the most penetrable service-layer gap, as incumbent OEMs under-invest in lifecycle performance contracting. Target North African light rail expansion corridors in Morocco and Egypt, where EU F-Gas documentation requirements filter out unprepared competitors. Lead with coolant-free thermal management designs to bypass REACH compliance friction extending incumbent validation cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized rail power electronics divisions lacking silicon-carbide roadmap investments. Five-to-ten year viability hinges on semiconductor material transition timing, with pure-play thyristor specialists facing stranded asset risk. Watch for NMPA testing protocol harmonization announcements as the signal indicating accelerated market access for non-Chinese suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Carbide Platform Migration | Enables switching frequencies above 50 kHz for compact auxiliary power units in Chinese high-speed corridors. |
| REACH-Compliant Thermal Redesign | Eliminates hydrofluorocarbon coolants to satisfy EU F-Gas Regulation across German intercity networks. |
| Framework Agreement Consolidation | Captures decade-long fleet renewal cycles at India's Integral Coach Factory and China's CRRC. |
| Predictive Maintenance Integration | Converges digital twin platforms with power electronics for performance-based lifecycle contracts. |
| North African Market Entry | Leverages established environmental documentation to supply Moroccan and Egyptian light rail expansion. |
Methodological Framework
A standing panel of rolling stock procurement directors, thermal management engineers, and rail operator maintenance chiefs provided ongoing calibration against secondary validation from customs trade databases, OEM SEC filings, and national electrification mandate documents. Triangulation between bottom-up segment builds and top-down macro constraints anchored volume and value estimates.
Consistency checks against external benchmarks validated analytical outputs across the projection horizon, with segmentation modeling spanning semiconductor architecture, voltage class, application mode, and end-user procurement authority. CAGRs derived from fitted growth curves incorporating fleet electrification program timelines, regulatory compliance cycle acceleration, and technology substitution elasticities for thyristor-to-silicon-carbide transitions.
Underlying assumptions cover sustained Chinese high-speed rail expansion, stable rare earth supply chain configurations, and REACH enforcement continuity, with deviation risk concentrated in electromagnetic compatibility certification reciprocity between China and Western markets. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Low Voltage DC Circuit Breaker Market
Power Systems
Space DC-DC Converters Market
Power Systems
Battery Voltage Supervisor Market
Power Systems
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Global Power Semiconductor Switches Market
Power Systems
Battery Electronic Control Unit Market
Power Systems
Synchrophasors Market
Power Systems
Global Uninterruptible Power Supply (UPS) Market
Power Systems
Global Battery Thermal Management System Market
Power Systems
Superconducting Magnet Systems Market
Power Systems
Thyristor Surge Protectors Market
Power Systems
Charge Controller System Market
Power Systems
Data Center Power Quality and Harmonics Monitoring Test Systems Market
Power Systems
Thermoelectric Coolers Market
Power Systems
EV Power Module Market
Power Systems
Converter Modules Market