
 Thermoelectric Assemblies Market | 2026-2036
Thermoelectric Assemblies Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoelectric Assemblies Market Analysis
The EU F-Gas Regulation is broadening the cost-of-entry calculus for conventional compressor-based cooling, forcing OEMs to evaluate solid-state alternatives. Ferrotec Corporation leverages its integrated materials-to-systems capability to anchor supply security for semiconductor fabrication tools. Laird Thermal Systems sustains technology leadership in miniature thermoelectric modules for medical diagnostics. Phononic differentiates through its proprietary semiconductor process for high-density cooling arrays.
Thermoelectric assemblies are solid-state heat pump devices that exploit the Peltier effect to transfer thermal energy across semiconductor junctions, typically achieving temperature differentials of 40–70°C depending on module architecture and heat sink coupling. These systems serve industrial and commercial markets requiring precise, vibration-free temperature control without refrigerant circulation. Module and cooler categories dominate current volume, while generator applications are gaining structural traction in waste heat recovery installations across automotive and industrial settings. Bismuth telluride remains the primary material platform for near-room-temperature applications, though half-heusler compounds are emerging for higher-temperature power generation segments.
The US Environmental Protection Agency enforces refrigerant phase-down schedules that directly expand addressable market for thermoelectric alternatives in HVAC and transportation cooling. Japan's METI promotes solid-state energy conversion through efficiency standards that favor distributed thermal management architectures. China's Ministry of Ecology and Environment implements dual carbon goals that incentivize waste heat recovery deployments in steel and cement plants. Stakeholders must monitor evolving material efficiency thresholds and certification harmonization between North American and Asian testing protocols.
Market Dynamics
The EU F-Gas Regulation is systematically eroding the cost advantage of vapor-compression cooling, redirecting capital toward solid-state thermal management architectures across industrial and commercial segments.
Growth Catalysts
- EPA Refrigerant Phase-Down:The US Environmental Protection Agency's scheduled hydrofluorocarbon reductions are eliminating incumbent cooling options in HVAC and transportation applications, expanding thermoelectric addressable market.
- Semiconductor Fabrication Precision:Lithography and etching equipment manufacturers require vibration-free temperature control that compressor-based systems cannot deliver, pulling thermoelectric assemblies into critical process tools.
- Japan's METI Efficiency Standards:Distributed thermal management architectures now receive preferential treatment under revised industrial energy codes, accelerating adoption in precision manufacturing clusters.
Market Restraints
- Bismuth Telluride Supply Concentration:Refined tellurium sourcing depends on copper anode slime processing concentrated in Chinese smelters, exposing module manufacturers to geopolitical supply disruption.
- Coefficient of Performance Gap:Thermoelectric cooling achieves one-third the efficiency of vapor-compression systems at equivalent temperature lift, constraining penetration in cost-sensitive commercial refrigeration.
- Half-Heusler Manufacturing Scale:High-temperature power generation materials require vacuum induction melting capabilities held by limited specialty metallurgical suppliers, throttling generator segment expansion.
Strategic Opportunities
- US Inflation Reduction Act Credits:Domestic clean energy manufacturing incentives now cover thermoelectric waste heat recovery equipment, creating subsidy-backed entry paths for generator system suppliers.
- Medical Diagnostics Miniaturization:Point-of-care PCR and immunoassay platforms require sub-0.1°C stability in handheld formats, opening volume opportunities for micro-module architectures.
- China Dual Carbon Deployment:Steel and cement plant retrofits under Ministry of Ecology and Environment mandates are creating project finance availability for industrial waste heat recovery installations.
Industry Challenges
- Thermoelectric Material Science Talent:PhD-level expertise in semiconductor thermoelectrics concentrates in national laboratory and university research groups, constraining private-sector R&D scaling.
- Multi-Protocol Certification Burden:Medical device thermal modules require simultaneous FDA 510(k), CE MDR, and ISO 13485 compliance, extending commercialization timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoelectric Assemblies Market |
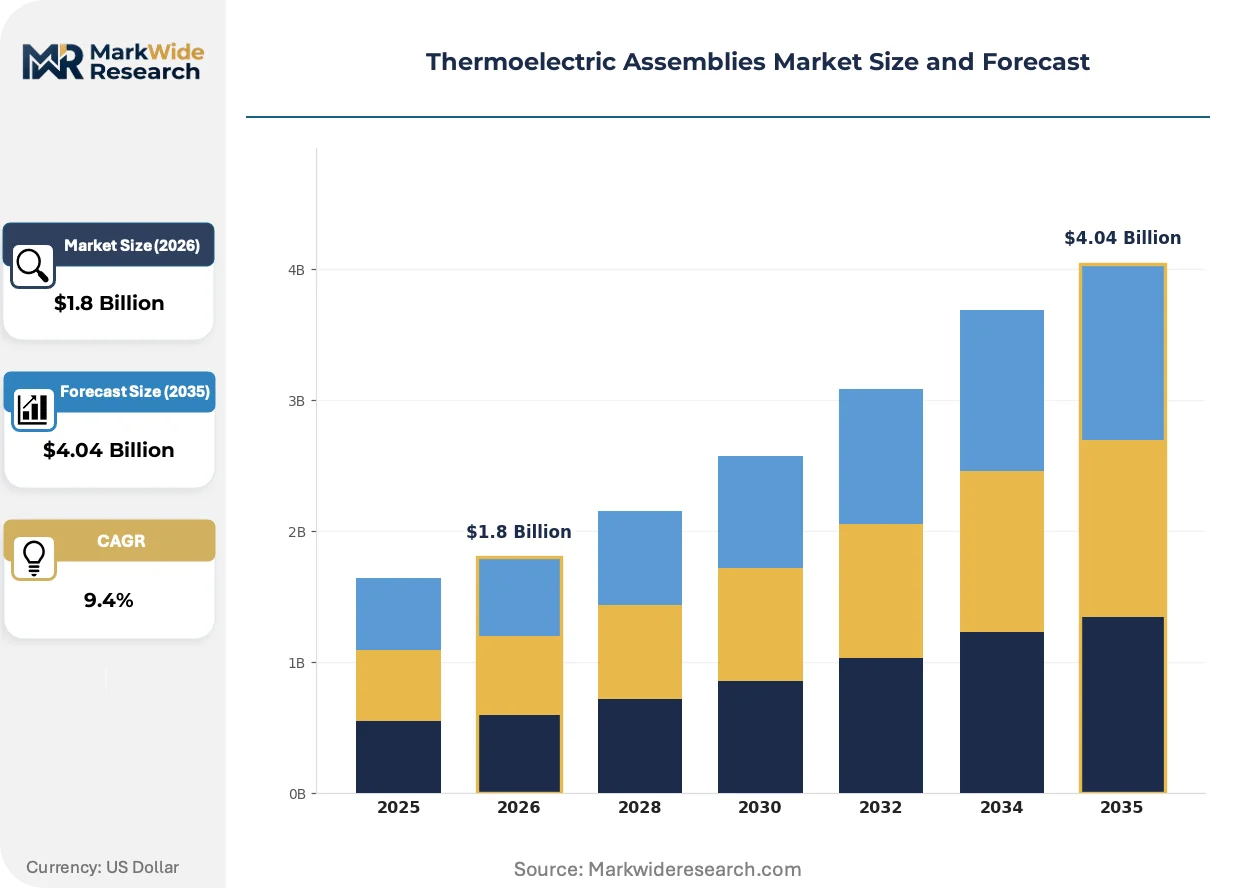
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Module, Generator, Cooler, Heater Application: Automotive, Aerospace, Industrial, Consumer Electronics Material: Bismuth Telluride, Lead Telluride, Half-Heusler, Skutterudite End User: Manufacturing, Research Institutions, Transportation, HVAC |
| Companies Covered | Ferrotec Corporation, Laird Thermal Systems, Coherent Corp., TE Technology, KELK Ltd., Kryotherm, Crystal Ltd., Phononic, RMT Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoelectric Assemblies Market Emerging Trajectories
Active materials research and regulatory chemistry restrictions are converging to restructure competitive advantage around thermal management system architectures rather than discrete component supply.
Thermoelectric module architectures are modularizing around standardized interface geometries that decouple heat sink selection from semiconductor junction design. Medical device OEMs in Germany and Japan are adopting these platforms to compress qualification cycles for diagnostic equipment. The structural consequence is collapsing the traditional custom-engineering revenue model in favor of configurable product families.
The EU F-Gas Regulation's 2024 service ban on high-global-warming-potential refrigerants is forcing cold-chain equipment manufacturers to evaluate solid-state alternatives for last-mile pharmaceutical distribution. Transport refrigeration OEMs are responding with hybrid architectures that reserve thermoelectric units for precision payload zones while retaining compressor-based systems for bulk cooling.
Medical device procurement teams are consolidating thermal subsystem sourcing around suppliers offering integrated temperature control electronics rather than discrete modules. Diagnostic platform manufacturers in the US and Switzerland are displacing in-house thermal design with vendor-supplied complete assemblies. This pattern concentrates purchasing power among three to five system-level suppliers per major OEM.
Thermoelectric Assemblies Market Segmentation
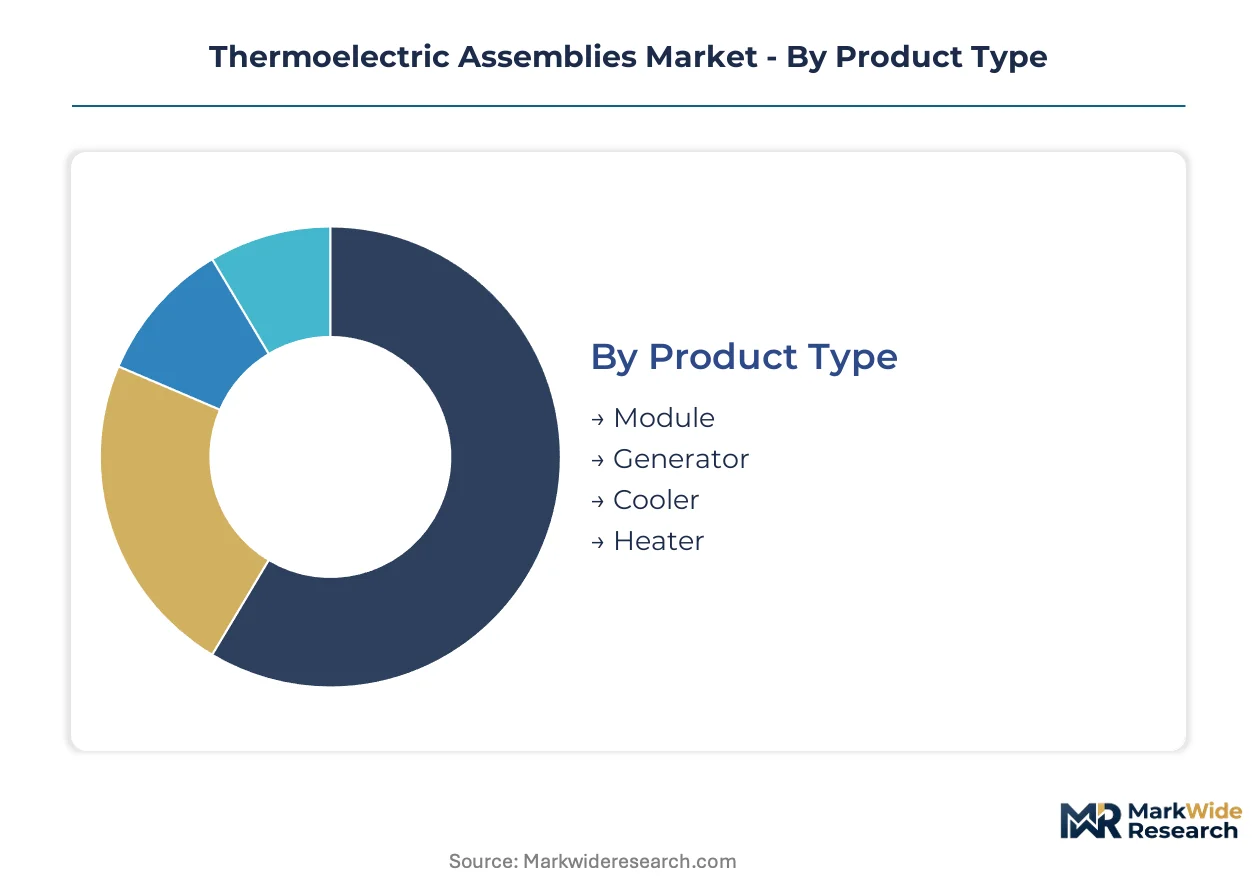
Thermoelectric assemblies fragment across four intersecting dimensions that determine performance specifications, cost structures, and procurement channels. Product architecture and material chemistry dominate technical differentiation, while application verticals and end-user categories dictate commercial access patterns.
Product Type:
Module and cooler categories anchor current volume shipments, while generator architectures command premium positioning in waste heat recovery installations.
- Module:Semiconductor junction arrays packaged with ceramic substrates and electrode interconnects, achieving 40–70°C temperature differentials. Demand concentrates in semiconductor fabrication tools across Germany and Japan, where lithography equipment manufacturers require vibration-free thermal stability that compressor systems cannot deliver. Bismuth telluride junctions remain standard for near-room-temperature operation.
- Generator:Thermoelectric converters harvesting waste heat gradients above 200°C for power output. Steel and cement plants in China under MEE dual carbon mandates are retrofitting exhaust streams with half-heusler-based units, creating project finance availability for industrial deployments.
- Cooler:Integrated assemblies coupling Peltier modules to heat sinks and fans for precision temperature control. Point-of-care diagnostic OEMs in Switzerland and the US are consolidating procurement around vendor-supplied complete thermal subsystems rather than discrete components.
- Heater:Reverse-biased thermoelectric units providing localized heating in battery thermal management and medical device incubation. Automotive cabin comfort applications in electric vehicles are emerging as a volume outlet.
Today's leader: Module. Tomorrow's challenger: Generator.
Application:
Industrial and automotive verticals split the market between precision control requirements and waste heat recovery economics.
- Industrial:Process automation, laser cooling, and analytical instrumentation requiring sub-0.1°C stability. Germany's industrial automation corridor concentrates demand for standardized interface geometries that compress equipment qualification cycles.
- Automotive:Battery thermal management, seat climate control, and exhaust gas heat recovery. US EPA refrigerant phase-down schedules are eliminating incumbent cooling options in HVAC and transportation segments, expanding thermoelectric addressable market.
- Aerospace:Satellite thermal control and avionics cooling in vibration-sensitive environments. Radiation-hardened module specifications limit supplier qualification to a handful of defense-aerospace contractors.
- Consumer Electronics:Miniature coolers for PCR devices, wine cabinets, and portable medical storage. Last-mile pharmaceutical distribution in the EU is forcing cold-chain equipment manufacturers to evaluate solid-state alternatives under F-Gas Regulation service bans.
Industrial commands the installed base. Automotive offers the steepest expansion trajectory.
Material:
Cost-performance tradeoffs in thermoelectric materials segment the market between mature bismuth telluride production and emerging high-temperature compounds.
- Bismuth Telluride:Polycrystalline p-type and n-type alloys optimized for 200–400 K temperature ranges. Near-room-temperature modules for medical diagnostics and semiconductor fabrication depend on refined tellurium sourcing concentrated in Chinese copper smelters.
- Half-Heusler:Intermetallic compounds (TiNiSn, ZrNiSn base) delivering figure-of-merit above 1.0 at 600–900 K. Vacuum induction melting capabilities held by limited specialty metallurgical suppliers are throttling manufacturing scale for generator applications.
- Lead Telluride:Mid-temperature material platform for 400–800 K operation in automotive exhaust recovery. Toxicity concerns and RoHS compliance constraints restrict deployment in consumer-facing products.
- Skutterudite:Cobalt antimonide structures with filled-cage phonon scattering for high-efficiency power generation. Active research programs at national laboratories are advancing toward commercial manufacturing readiness.
Bismuth telluride dominates economics. Half-Heusler is gaining share fastest in high-temperature segments.
End User:
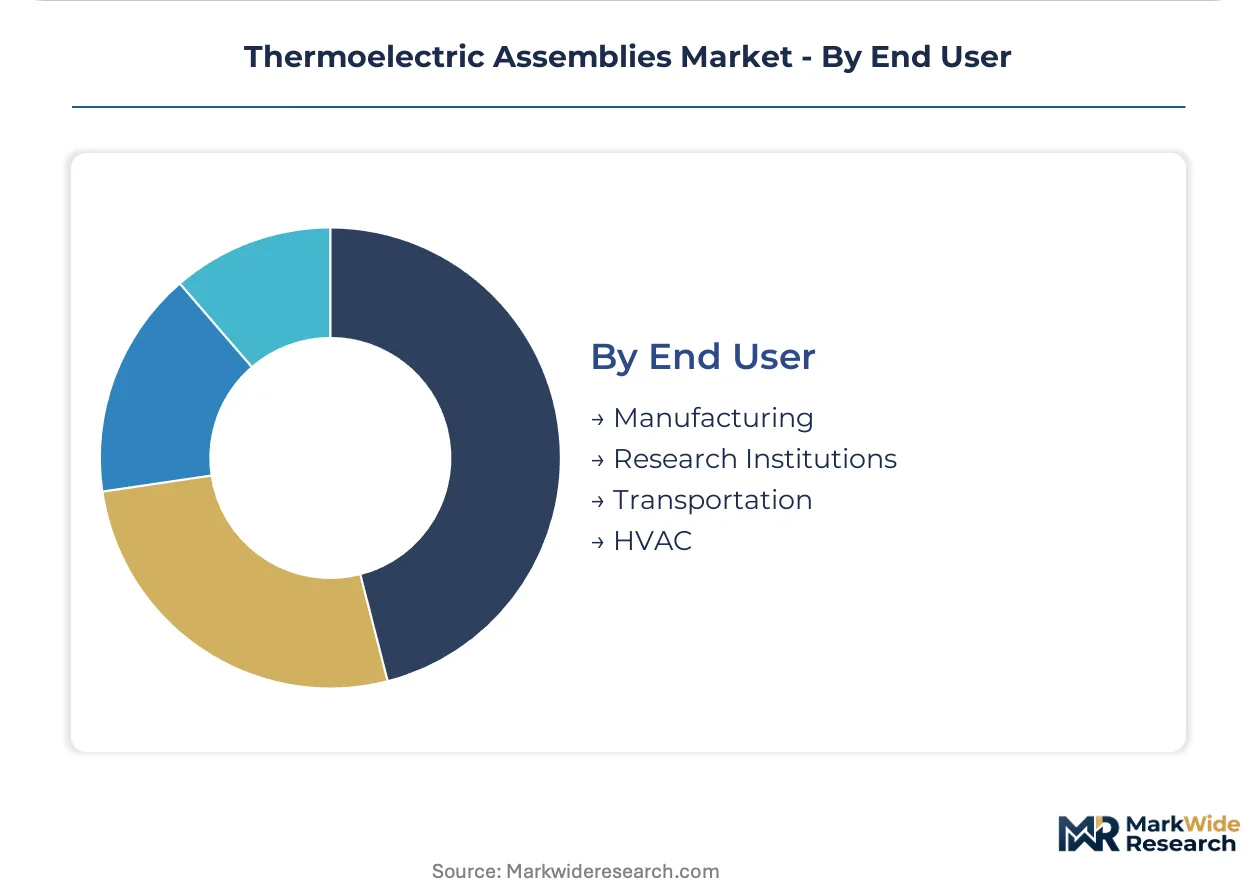
Procurement authority concentrates in manufacturing operations and research institutions, with transportation and HVAC channels requiring distinct commercial approaches.
- Manufacturing:Semiconductor fabs, automotive tier-1s, and industrial automation OEMs purchasing integrated thermal subsystems. Diagnostic platform manufacturers are displacing in-house thermal design with vendor-supplied complete assemblies.
- Research Institutions:National laboratories and university groups advancing material science and device physics. PhD-level expertise in semiconductor thermoelectrics concentrates in these organizations, constraining private-sector R&D scaling.
- Transportation:Fleet operators and rail systems evaluating waste heat recovery for fuel efficiency compliance. Japan's METI efficiency standards favor distributed thermal management architectures in precision manufacturing clusters.
- HVAC:Commercial building operators and cold-chain logistics providers responding to refrigerant phase-down mandates. Hybrid architectures combining thermoelectric precision zones with compressor bulk cooling are emerging as a transitional configuration.
Manufacturing sets specifications. Research institutions determine next-generation material platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PhD-level expertise in semiconductor thermoelectrics concentrates in national laboratory and university research groups across the United States, Germany, Japan, and China, constraining private-sector R&D scaling and anchoring regional innovation capacity.
United States
Semiconductor fabrication tool manufacturers and medical diagnostic OEMs drive precision thermal control procurement. The EPA refrigerant phase-down schedules eliminate incumbent cooling options in HVAC and transportation segments. Austin and Boston corridor fabs require vibration-free temperature stability for lithography equipment.
Germany
Industrial automation OEMs and laser cooling system builders standardize interface geometries to compress equipment qualification cycles. The EU F-Gas Regulation service ban redirects capital toward solid-state alternatives. Stuttgart and Munich industrial clusters adopt configurable thermoelectric product families over custom engineering.
China
Steel and cement plant retrofits under MEE dual carbon mandates create project finance availability for waste heat recovery installations. Refined tellurium sourcing concentrates in copper smelters, exposing module manufacturers to supply concentration. Yangtze River Delta fabrication corridors scale domestic module production.
Japan
Precision manufacturing clusters adopt distributed thermal management architectures under METI efficiency standards. Point-of-care diagnostic platforms require sub-0.1°C stability in handheld formats. Nagoya and Osaka medical device OEMs consolidate procurement around integrated temperature control electronics.
Switzerland
Diagnostic platform manufacturers displace in-house thermal design with vendor-supplied complete assemblies. CE MDR compliance requirements extend commercialization timelines for medical device thermal modules. Basel and Zurich pharmaceutical corridors drive last-mile cold-chain solid-state cooling evaluation.
Thermoelectric Assemblies Market Vendor Landscape
The competitive structure tilts toward integrated materials-to-systems specialists with captive semiconductor processing capabilities. Tiered positioning separates premium-tier suppliers serving semiconductor fabrication and medical diagnostics from scale-focused module fabricators addressing industrial automation. Three archetypes dominate: vertically integrated materials specialists, miniature module architects, and high-temperature generator developers. Capacity expansion in bismuth telluride refining and strategic partnerships for half-heusler vacuum induction melting represent the dominant competitive moves.
Among integrated specialists, Ferrotec Corporation anchors supply security positioning through materials-to-systems capability spanning semiconductor fabrication tools. Laird Thermal Systems exemplifies miniature module architecture leadership for medical diagnostics and precision instrumentation. Phononic occupies a position within high-density cooling arrays through proprietary semiconductor process differentiation. These three represent distinct capability vectors rather than direct segment overlap.
| Leading Market Players |
|---|
| Ferrotec Corporation |
| Laird Thermal Systems |
| Coherent Corp. |
| TE Technology |
| KELK Ltd. |
| Kryotherm |
| Crystal Ltd. |
| Phononic |
| RMT Ltd. |
| Others |
Supply Flow & Price Mechanics
Tellurium price volatility cascading from copper smelter output fluctuations directly compresses module manufacturer margins and stratifies end-market pricing tiers across medical, industrial, and automotive buyer segments.
Pricing Analysis
Bundled subsystem procurement displaces discrete module transactions as diagnostic OEMs consolidate vendor relationships. Pricing stratifies across FDA 510(k)-certified medical tiers, industrial automation standard grades, and automotive economy volumes. Cost compression in the automotive battery thermal management tier intensifies because nickel-alternative material research is accelerating. Medical device manufacturers exhibit the lowest price sensitivity due to regulatory qualification lock-in, while HVAC retrofit contractors face acute margin pressure.
Supply Chain Analysis
CE MDR and FDA 510(k) certification gating restricts qualified supplier pools to a handful of integrated specialists. Refined tellurium concentrates in Chinese copper smelters, bismuth mining anchors in Peru and China, and ceramic substrate fabrication centers in Japan. Single-source vulnerability pervades the half-heusler vacuum induction melting stage held by limited German and Japanese metallurgical houses. Distribution runs through direct OEM supply agreements rather than distributor networks for qualified medical and semiconductor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermoelectric assemblies market functions as a regulatory compounder where the EU F-Gas Regulation's refrigerant service ban is systematically expanding solid-state cooling demand across cold-chain and precision control applications.
For Market Incumbents: Deploy captive tellurium refining partnerships to neutralize Chinese smelter concentration risk. Backward integration into bismuth telluride crystal growth secures margin against commodity volatility. Incumbents must also deepen ISO 13485 certification moats as medical device OEMs consolidate procurement around qualified system suppliers. For New Entrants and Emerging Players: Launch via modular platform architectures targeting Germany's industrial automation corridor where standardized interface geometries are displacing custom engineering relationships. White-space concentration sits in point-of-care diagnostic micro-modules and automotive seat climate control subsystems. A direct technical sales model bypassing distributor markups offers the most penetrable path against entrenched medical incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with half-heusler generator specialists holding vacuum induction melting capabilities as China's MEE dual carbon mandates accelerate industrial waste heat recovery deployment. Long-term viability hinges on material science talent pipelines and regulatory qualification velocity rather than manufacturing scale alone. The signal to watch is project finance closure rates for steel and cement plant retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Bismuth Telluride Refining | Captive tellurium supply secures margin stability against Chinese smelter concentration. |
| Half-Heusler Vacuum Induction Melting Partnership | Access to limited German and Japanese metallurgical capacity unlocks generator segment growth. |
| FDA 510(k) and CE MDR Dual Certification Investment | Simultaneous qualification compresses commercialization timelines for medical diagnostic OEMs. |
| Modular Platform Standardization | Configurable product families displace custom engineering revenue models in German industrial clusters. |
| Project Finance Structuring for Waste Heat Recovery | MEE-mandated steel and cement retrofits in China create bankable industrial deployment pipelines. |
Methodological Framework
Direct dialogue with thermoelectric module design engineers, semiconductor fabrication tool procurement managers, medical device thermal subsystem directors, and industrial automation OEM technical buyers grounded qualitative findings. Secondary validation drew from EPA refrigerant phase-down schedules, EU F-Gas Regulation implementation guidance, METI efficiency standard revisions, and MEE dual carbon policy documents. Bottom-up shipment modeling and top-down macroeconomic triangulation converged on segment-level estimates.
Installed base projections and replacement cycle analysis across the modeling period reflect semiconductor fabrication capacity expansion, automotive electric vehicle thermal management content growth, and medical diagnostic platform miniaturization trends. Segmentation modeling incorporated product architecture, material chemistry, application vertical, and end-user procurement authority. CAGRs were derived from regression against historical adoption curves in comparable solid-state energy conversion technologies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tellurium supply disruption scenarios or accelerated half-heusler manufacturing scale breakthroughs. A model refresh is warranted upon material change in EPA refrigerant phase-down enforcement velocity or MEE project finance availability for industrial waste heat recovery.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Space DC-DC Converters Market
Power Systems
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Global Next Generation Power Semiconductors Market
Power Systems
Global Synchronous Motor Market
Power Systems
Traction Inverter Market
Power Systems
Battery Balancer Market
Power Systems
Silicon Carbide Power Devices Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
Power Semiconductor Market
Power Systems
Surface Mounted Medium Voltage Distribution Panel Market
Power Systems
Japan Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Charge Pumps Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Organic Fixed Power Capacitors Sales Market
Power Systems
Automotive Power Electronics Market
Power Systems
MOSFET and IGBT Gate Driver Market