
 North America Spirits Market | 2026-2036
North America Spirits Market Size, Share, and Industry Trends Forecast 2026-2036
North America Spirits Market Intelligence
The expansion of craft distillery capacity across the United States and Canada is reshaping competitive positioning. Diageo Plc leverages its vast portfolio and global distribution network to maintain market leadership across multiple categories. Constellation Brands, Inc. focuses on premium wine and spirits segments, particularly tequila, to capture high-margin growth. Sazerac Company, Inc. competes through a diverse brand lineup that includes historic American whiskeys and popular vodka expressions.
Spirits are alcoholic beverages produced by the distillation of a fermented agricultural mash, such as grains, fruits, or vegetables. This process concentrates the alcohol content, typically above 20% ABV, and is often followed by aging in wooden casks to develop flavor. While Whiskey and Vodka remain foundational product types, the fastest-growing segment in terms of consumer interest is often Gin, fueled by cocktail culture. The market's value growth is increasingly driven by the Super Premium and Premium price tiers as consumers trade up for higher-quality offerings in both retail and on-premise channels.
In the United States, the Alcohol and Tobacco Tax and Trade Bureau (TTB) sets federal standards for labeling, advertising, and production. Canadian provinces, through powerful liquor control boards like Ontario's LCBO or Quebec's SAQ, exert tight control over retail, pricing, and distribution. Success for distillers depends on navigating this fragmented regulatory environment while adapting to consumer demand for both convenience and product authenticity.
Market Dynamics
The North American spirits market is being fundamentally reshaped by the dual forces of premiumization and channel fragmentation. Consumer demand is shifting towards higher-quality, authentic products, while the proliferation of e-commerce and direct-to-consumer sales models disrupts traditional three-tier distribution systems, particularly in the United States.
Growth Catalysts
- Premiumization and Cocktail Culture:Rising consumer interest in craft cocktails and high-end spirits, especially in major United States metropolitan hubs, drives value growth as shoppers trade up to super-premium brands.
- E-commerce Liberalization:The gradual easing of regulations governing direct-to-consumer alcohol shipping in various US states creates new, high-margin revenue streams for distilleries, bypassing traditional distribution bottlenecks.
- Ready-to-Drink (RTD) Innovation:The expansion of spirit-based RTD cocktails meets consumer demand for convenience and high-quality ingredients, opening a significant new product category that bridges beer and traditional spirits.
Market Restraints
- Provincial Control Boards:In Canada, powerful liquor control boards like Ontario's LCBO and Quebec's SAQ exert monopolistic control over retail and distribution, creating significant barriers to entry and limiting brand access.
- Agricultural Input Volatility:The supply and price of essential raw materials, such as blue Weber agave for tequila or specific heirloom grains for whiskey, are subject to climate and agricultural pressures, impacting production costs.
- Fragmented Regulatory Landscape:The patchwork of federal, state, and local laws governing production, labeling, and sales in the United States creates a complex and costly compliance environment for distillers of all sizes.
Strategic Opportunities
- Low- and No-Alcohol Spirits:Developing and marketing sophisticated non-alcoholic or low-ABV spirit alternatives caters to wellness-conscious consumers, representing a largely untapped segment within the broader market.
- Digital Engagement and Subscriptions:Building direct-to-consumer relationships through distillery-exclusive releases, online tasting events, and subscription clubs fosters brand loyalty and provides valuable consumer data.
- Terroir-Driven Product Lines:Highlighting the local origin of grains, water, and botanicals allows craft distillers to create unique, terroir-driven spirits that appeal to consumer demand for authenticity and local sourcing.
Industry Challenges
- Distribution Access:Securing and maintaining relationships with distributors remains a primary operational hurdle for new and craft distilleries competing for limited shelf space against large, established portfolios.
- Compliance and Labeling Burden:Adhering to the Alcohol and Tobacco Tax and Trade Bureau (TTB) regulations for formula approval, labeling, and advertising requires specialized expertise and significant administrative overhead.
- Skilled Labor Scarcity:The rapid growth in craft distilleries across North America has created intense competition for experienced master distillers, blenders, and specialized production staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Spirits Market |
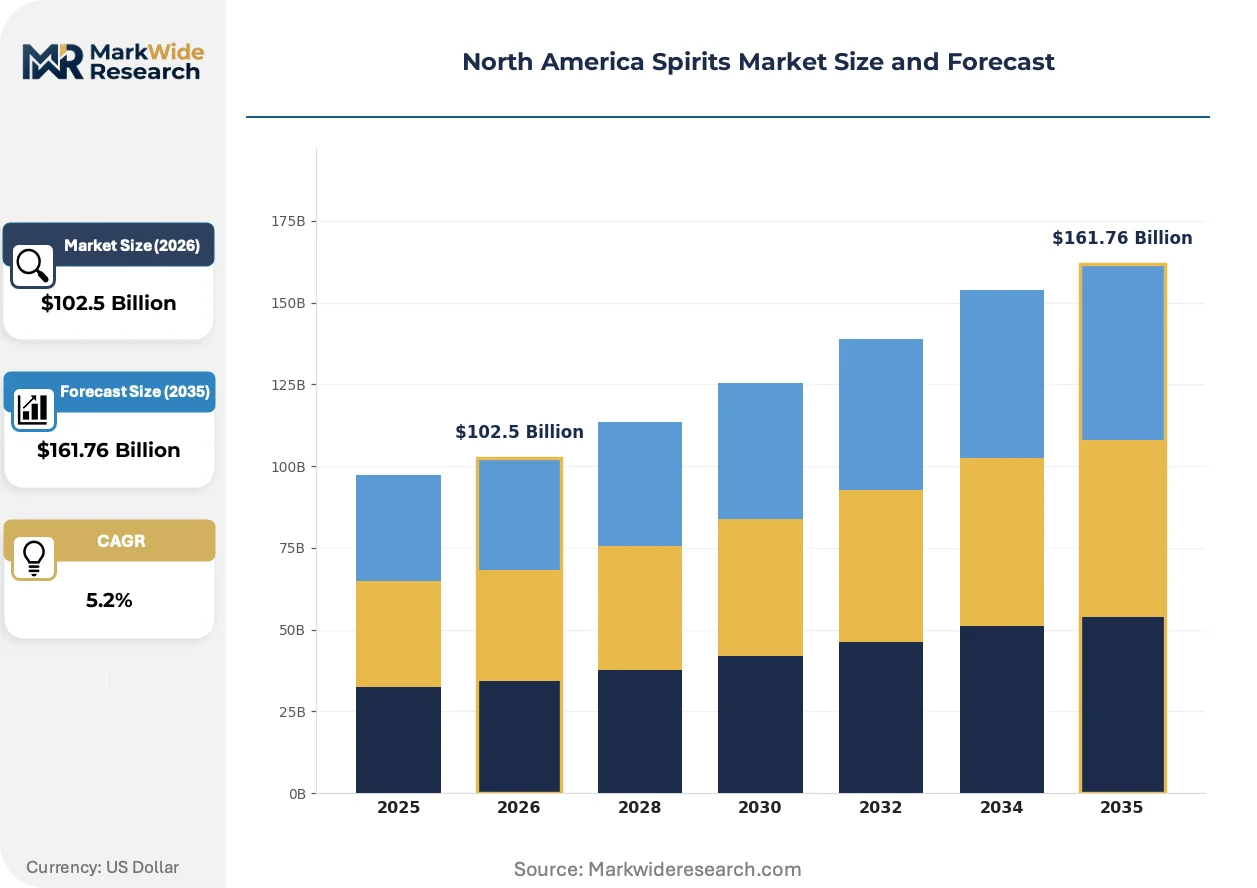
| Market Size in 2026 | $102.5 Billion |
| Market Size in 2035 | $161.76 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whiskey, Vodka, Rum, Gin End User: Bars, Restaurants, Retailers, Online Consumers Packaging Type: Bottles, Cans, Kegs, Pouches Price Tier: Premium, Mid-range, Budget, Super Premium |
| Companies Covered | Diageo Plc, Pernod Ricard, Constellation Brands, Inc., Brown-Forman, Bacardi Limited, Suntory Holdings Limited, Rémy Cointreau, Sazerac Company, Inc., Davide Campari-Milano N.V., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Spirits Market Strategic Shifts & Innovations
Product formulation and go-to-market strategies are evolving in response to consumer demand for authenticity, novelty, and convenience. This shift forces producers to reconsider traditional aging processes, navigate new regulatory definitions, and adapt to a radically different retail environment.
Barrel aging technology provides a clear example of product evolution. Distillers use accelerated aging techniques, such as smaller casks or ultrasonic treatment, to influence flavor development. Both craft and large-scale producers are adopting these methods to create novel expressions and respond faster to market tastes. The production process itself is migrating from standardized, long-term maturation in traditional barrels to more flexible finishing techniques that enable rapid product innovation.
Regulatory frameworks are adapting to product innovation within the industry. The US Alcohol and Tobacco Tax and Trade Bureau (TTB) recently established a formal standard of identity for American Single Malt Whiskey. This action provides a clear, legally protected definition for a growing category, which encourages producer investment and reduces consumer confusion. The American whiskey segment is most affected, as distillers can now confidently market products under a federally recognized and protected classification.
Consumer purchasing behavior is undergoing a significant transformation away from legacy channels. A growing number of shoppers buy spirits via e-commerce marketplaces, brand websites, and third-party delivery applications. This disintermediates the traditional on-premise and off-premise retail models that have long governed the industry's structure. This channel shift is most pronounced in US states with more permissive laws regarding direct-to-consumer alcohol shipments.
North America Spirits Market Segmentation
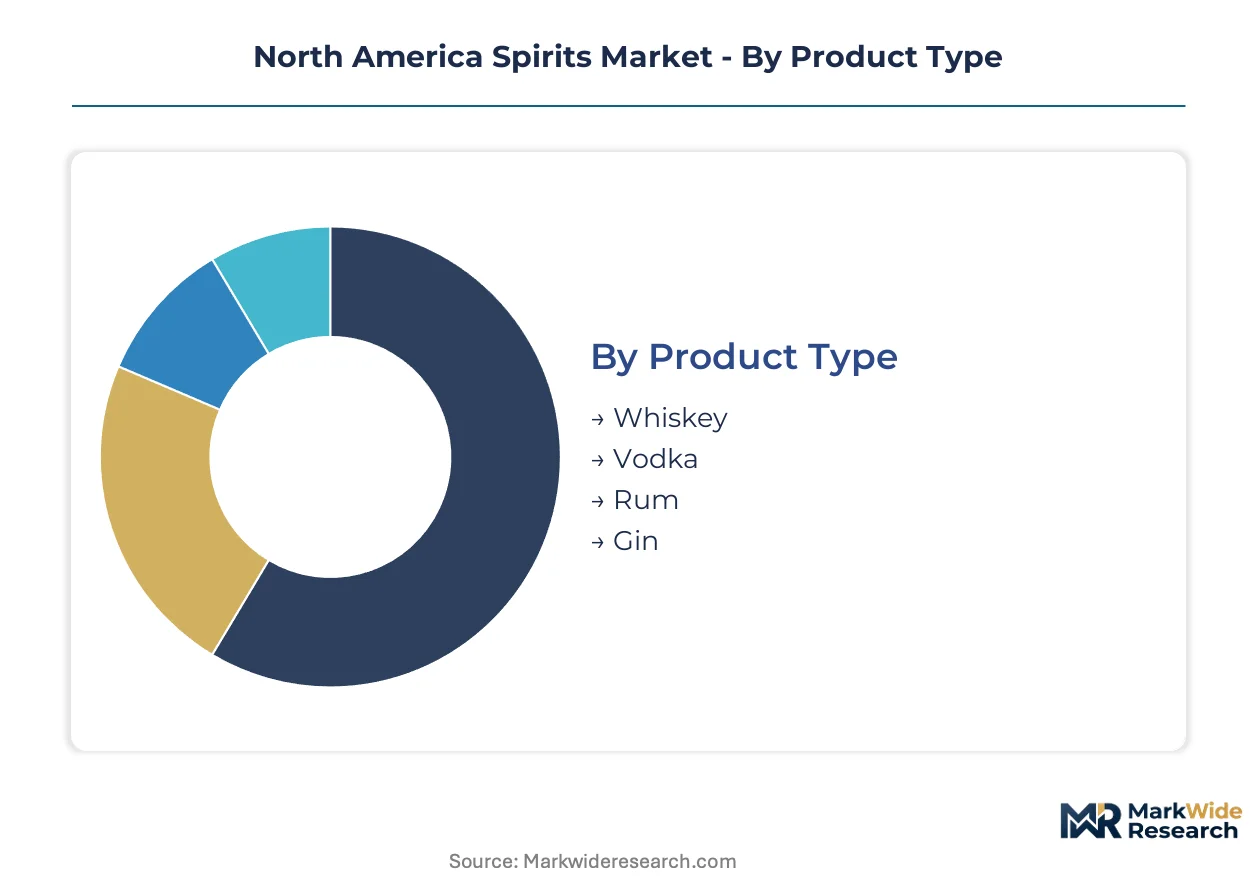
The North America spirits market divides into distinct categories reflecting diverse consumer preferences and distribution channels. Understanding these segments enables distillers and retailers to tailor product development, marketing efforts, and supply chain strategies. This granular view highlights areas of concentrated demand and emerging growth opportunities across the region.
Product Type:
The product type segment spans mature, foundational spirit categories and rapidly expanding niche offerings.
- Whiskey:This distilled alcoholic beverage, often aged in wooden barrels, derives from fermented grain mash such as barley, corn, rye, or wheat. Demand concentrates in major United States metropolitan centers where premiumization trends drive interest in craft and aged expressions.
- Vodka:A clear distilled alcoholic beverage composed primarily of water and ethanol, typically produced by the distillation of fermented grains or potatoes. Its versatility as a cocktail base ensures consistent demand across both on-premise and retail channels throughout North America.
- Rum:This distilled alcoholic beverage originates from sugarcane byproducts like molasses or sugarcane juice, often aged in oak barrels.
- Gin:A distilled alcoholic beverage that derives its predominant flavor from juniper berries and other botanicals.
Whiskey handles the majority of throughput; Gin is the fastest mover on share.
End User:
End-user segmentation reveals where spirits are consumed, from traditional hospitality venues to modern digital storefronts.
- Retailers:These include liquor stores, supermarkets, and convenience stores, representing the primary off-premise sales channel for bottled spirits. Retailers in Canadian provinces operate under strict control by provincial liquor boards, impacting product availability and pricing.
- Online Consumers:Individuals purchasing spirits through e-commerce platforms, brand websites, or third-party delivery services. This segment is experiencing significant growth in US states with liberalized direct-to-consumer shipping laws, offering convenience and broader selection.
- Bars:Establishments primarily focused on serving alcoholic beverages for immediate consumption, often featuring extensive cocktail menus.
- Restaurants:Venues where spirits are typically consumed alongside meals, contributing to on-premise sales and cocktail culture.
Retailers account for substantial volume; online consumers demonstrate the steepest expansion trajectory.
Packaging Type:
Packaging innovation and consumer convenience preferences shape the types of containers used for spirits across North America.
- Bottles:Traditional glass containers, available in various sizes, remain the dominant packaging format for nearly all spirit categories due to their aesthetic appeal and preservation qualities. Bottles are the standard for premium and super-premium offerings, particularly in the United States and Canada.
- Cans:Aluminum containers, increasingly popular for ready-to-drink (RTD) cocktails and single-serve spirit formats, offer portability and convenience. This format addresses demand for on-the-go consumption and is expanding quickly across North American markets.
- Kegs:Large bulk containers primarily used in on-premise establishments like bars and restaurants for draft cocktails or high-volume spirit service.
- Pouches:Flexible, lightweight packaging solutions, often used for travel-sized spirits or cost-effective bulk options in certain regional markets.
Bottles command the largest share of volume; cans are gaining share fastest due to RTD innovation.
Price Tier:
The price tier segmentation reflects consumer willingness to trade up for quality, authenticity, and brand prestige.
- Super Premium:Spirits positioned at the highest price points, characterized by exceptional quality, limited production, and often unique aging processes or raw materials. This tier drives significant value growth, especially in affluent United States metropolitan areas.
- Premium:High-quality spirits offering a superior drinking experience compared to standard options, often with distinct brand stories and refined production methods. Premium products appeal to consumers trading up for better ingredients and craftsmanship.
- Mid-range:Spirits that balance quality and affordability, representing a broad segment accessible to a wide consumer base.
- Budget:Entry-level spirits focused on cost-effectiveness, typically offering standard quality for everyday consumption.
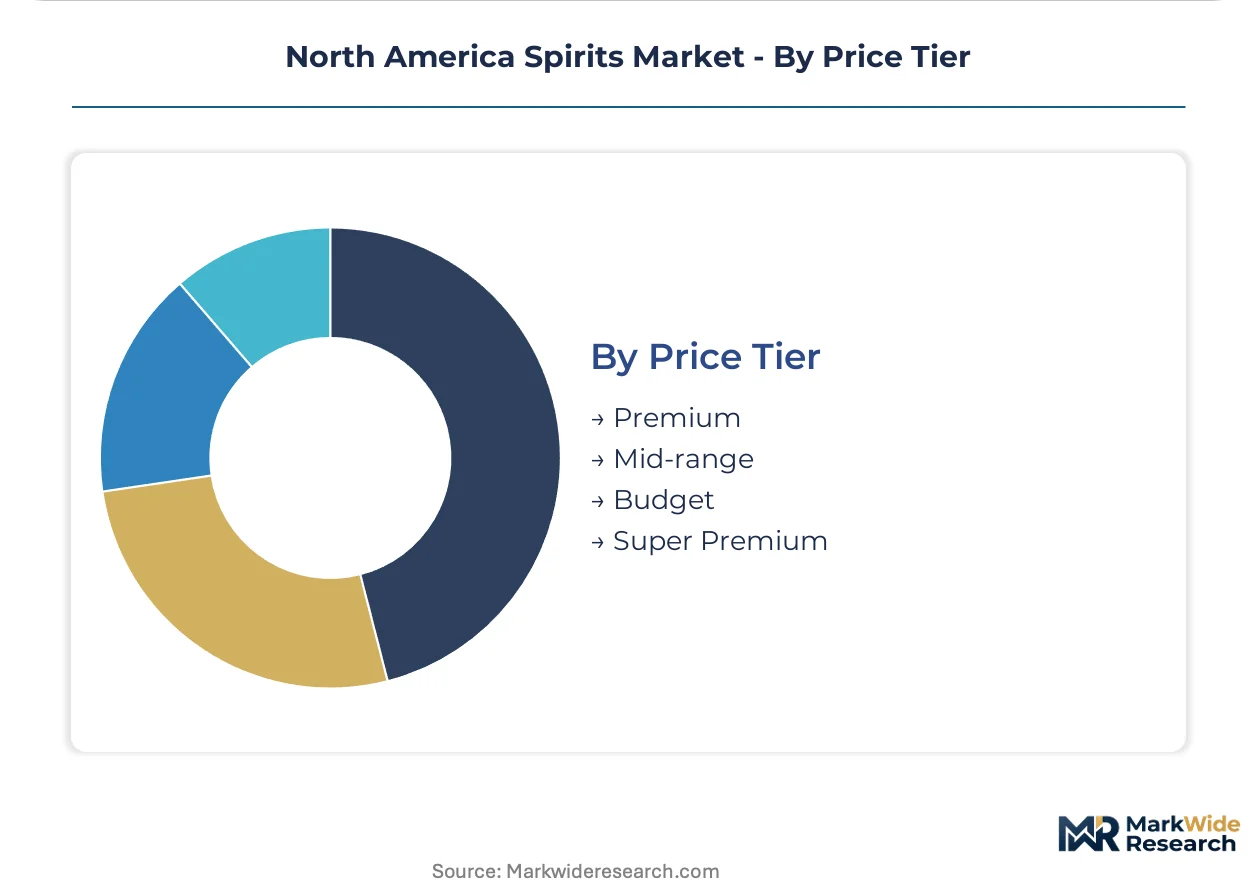
Premium and Super Premium tiers capture the majority of value; Super Premium is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American spirits market exhibits a concentrated supply profile across its diverse segments. Production capabilities for premium and super-premium spirits are often clustered in specific geographic pockets. This regional specialization influences distribution networks and consumer access across the continent.
United States
Consumer demand for super-premium spirits and craft cocktails drives significant value growth in the United States. The Alcohol and Tobacco Tax and Trade Bureau (TTB) establishes federal standards for production and labeling. Major metropolitan centers such as New York City and Chicago concentrate interest in high-end offerings and innovative product types.
Canada
Canadian consumers show strong interest in convenient ready-to-drink formats and a broad selection of spirits. Provincial liquor control boards, such as Ontario's LCBO, maintain tight control over retail pricing and distribution. Major urban centers like Toronto and Vancouver are pivotal for new product introductions and market penetration strategies.
Mexico
Mexico's spirits market sees robust demand for indigenous spirits like tequila and mezcal, alongside a growing premium imported segment. Local regulatory bodies enforce strict quality and appellation standards for traditional spirits. The Jalisco region remains the epicenter for tequila production, underpinning significant domestic consumption and export volumes.
United States (West Coast)
The West Coast of the United States exhibits strong demand for low- and no-alcohol spirits and innovative craft expressions. California's Department of Alcoholic Beverage Control (ABC) regulates state-level direct-to-consumer shipping. Urban centers like San Francisco and Portland foster a vibrant craft distillery scene, driving product innovation.
North America Spirits Market Key Industry Players
Global portfolio giants and niche premium specialists split the North America spirits market. The competitive landscape features a few dominant players with extensive distribution alongside numerous craft distilleries. Companies pursue strategic acquisitions and continuous portfolio diversification to maintain market share. Geographic expansion into new states or provinces also represents a critical competitive move for growth. Smaller regional players often differentiate through unique product offerings and local sourcing strategies.
Within the global portfolio giant archetype, Diageo Plc, a London-based public limited company, anchors a significant portion of the market. Constellation Brands, Inc., a New York-based corporation, exemplifies a focus on premium wine and spirits segments, particularly tequila. Sazerac Company, Inc., a privately held American corporation, occupies a position through its diverse brand lineup, including historic American whiskeys. These entities leverage their established market presence and distribution networks to influence pricing and product availability across North America.
| Leading Market Players |
|---|
| Diageo Plc |
| Pernod Ricard |
| Constellation Brands, Inc. |
| Brown-Forman |
| Bacardi Limited |
| Suntory Holdings Limited |
| Rémy Cointreau |
| Sazerac Company, Inc. |
| Davide Campari-Milano N.V. |
| Others |
Cost & Logistics Intelligence
The Jalisco region's concentrated tequila production capacity directly influences global agave spirit pricing power. North American spirits pricing and supply chains are deeply interconnected, with raw material availability and regulatory frameworks shaping market dynamics.
Pricing Analysis
The Alcohol and Tobacco Tax and Trade Bureau (TTB) dictates the pricing tier structure for spirits in the United States, alongside state-level regulations. Pricing stratifies across Super Premium, Premium, Mid-range, and Budget tiers. Quality grade, including aging duration and raw material provenance, drives significant price differentiation. Pricing pressure stems from agricultural input volatility, particularly for specialty grains or agave. Budget-tier consumers exhibit the highest price sensitivity, while Super Premium buyers prioritize brand prestige and unique product attributes.
Supply Chain Analysis
Agricultural input volatility, particularly for blue Weber agave or specific heirloom grains, creates a significant supply chain risk. Supply concentration draws from the United States, Canada, and Mexico for various spirit types. Raw material dependencies include grains for whiskey and vodka, sugarcane for rum, and juniper berries for gin. The distribution model primarily runs through a three-tier system in the United States, while Canadian provinces operate under monopolistic control boards like Ontario's LCBO.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
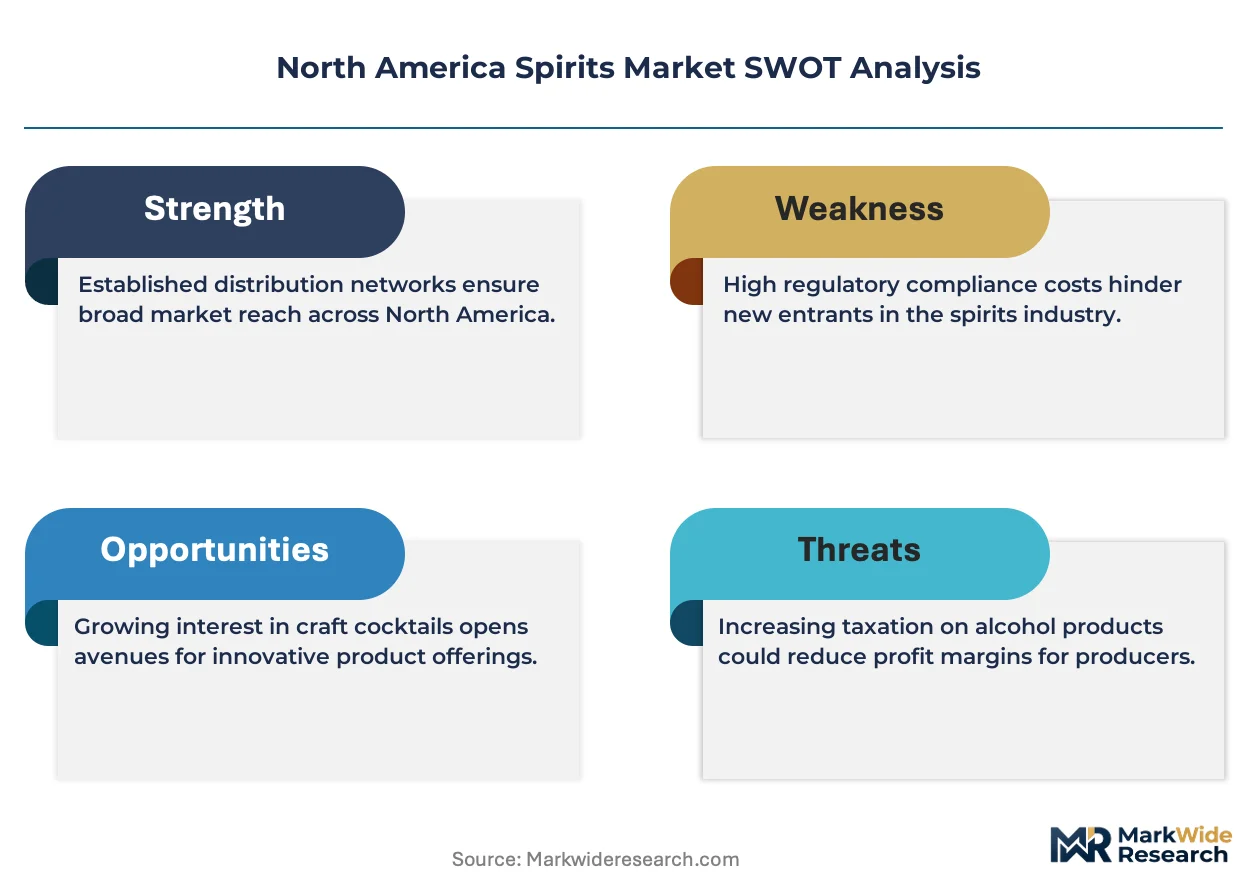
This North America spirits market sits as a defensive-moat story because regulatory entrenchment and established brand loyalties create substantial barriers to entry.
For Market Incumbents: Build regulatory expertise to navigate the complex federal and state-level compliance landscape across North America. Diversify existing portfolios to include fast-growing ready-to-drink (RTD) formats to counter emerging competitive threats from new product categories. Deepen distribution network relationships to maintain shelf space against an increasing number of craft distilleries. Invest in digital engagement platforms to capture direct-to-consumer revenue streams and valuable shopper data.
For New Entrants and Emerging Players: Build out niche product lines focusing on authenticity and unique provenance, such as terroir-driven spirits. Target online consumers in US states with liberalized direct-to-consumer shipping laws, representing a highly penetrable segment. Develop sophisticated low- and no-alcohol spirit alternatives to meet evolving wellness consumer demands. Employ digital marketing and subscription models to foster brand loyalty and bypass traditional distribution bottlenecks.
For Investors and Strategic Acquirers: Long-term, this sits as a brand consolidation play because established brands command significant market share and consumer trust. Identify craft distilleries with strong regional followings or innovative product lines for strategic acquisition. Focus on companies demonstrating robust e-commerce capabilities or unique raw material sourcing advantages. The signal to watch is further loosening of direct-to-consumer shipping regulations, which would unlock substantial new revenue potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into RTDs | Captures new consumer demand for convenience and expands market reach beyond traditional spirits. |
| Investment in E-commerce Infrastructure | Enables direct-to-consumer sales, bypassing traditional distribution and building brand loyalty. |
| Acquisition of Craft Brands | Integrates unique product offerings and regional market penetration into larger portfolios. |
| Sustainable Sourcing Initiatives | Appeals to wellness-conscious consumers and mitigates agricultural input volatility risks. |
| Development of Low/No-ABV Offerings | Addresses the growing health and wellness trend, opening new segments for market expansion. |
Research Approach
Cross-validation between primary interviews and secondary data anchors the qualitative findings within this study. The research involved extensive conversations with distillery owners, brand managers, retail buyers, and regulatory officials from the TTB and Canadian liquor boards. Secondary validation drew from industry reports, trade association publications, and public data from federal and provincial regulatory bodies. This approach facilitated both bottom-up market sizing and top-down trend validation.
The forecast framework was calibrated against historical market trends and future demand projections across the analysis window. Segmentation dimensions modeled include product type, end user, packaging type, price tier, and regional consumption patterns. Compound Annual Growth Rates (CAGRs) were derived by analyzing historical growth trajectories and incorporating expert insights on future market drivers. Key forecast inputs included raw material prices and evolving consumer spending patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large portfolio holders or disruptive e-commerce platforms would shift outcomes. Forecasts reflect underlying assumptions regarding regulatory stability and consumer preference evolution. Unexpected shifts in agricultural supply or further regulatory fragmentation represent specific risk factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Winetainer Market
Alcoholic Beverages
Whiskey Market
Alcoholic Beverages
South America Alcoholic Beverages Market
Alcoholic Beverages
Global Soju Market
Alcoholic Beverages
Grain Neutral Spirits Market
Alcoholic Beverages
Barware Market
Alcoholic Beverages
France Alcohol E-Commerce Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
South Africa Tequila Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Bright Beer Tank Market
Alcoholic Beverages
Wine Bottle Sterilizer Market
Alcoholic Beverages
Mexico Alcohol E-Commerce Market
Alcoholic Beverages
Canada Wine Coolers Market