
 Grain Neutral Spirits Market | 2026-2036
Grain Neutral Spirits Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Neutral Spirits Market Outlook
Buyer concentration in the beverage industry is broadening as craft distilleries and private-label spirit brands multiply alongside consolidated multinational bottlers. Archer Daniels Midland Company sustains extensive grain origination networks that secure feedstock for large-scale neutral spirit production. MGP Ingredients Inc. specializes in custom distillation services that serve both established liquor houses and emerging craft labels. Cargill Incorporated leverages its integrated agricultural supply chain to control input costs across multiple production facilities.
Grain neutral spirits are ethanol derived from cereal grains, typically distilled to proof exceeding 190 degrees and filtered to remove congeners, color, and flavor compounds for use as a base in beverage, pharmaceutical, and industrial applications. The neutral grain spirits category dominates volume throughput due to its role as the foundational input for vodka, gin, and liqueur manufacturing. Gin production represents the fastest-expanding segment as botanical-infusion trends drive demand for ultra-clean ethanol bases that carry no residual flavor interference.
The US Alcohol and Tobacco Tax and Trade Bureau governs proof standards, labeling, and tax classification for neutral spirits entering commercial distribution. The US EPA regulates wastewater discharge and air emissions from distillery operations, raising capital requirements for new production capacity. The FDA oversees ethanol purity when grain neutral spirits cross into pharmaceutical or sanitizer applications, creating dual-compliance obligations for suppliers. Stakeholders must monitor evolving TTB guidance on craft distillery classification and EPA effluent limits when evaluating facility expansion or geographic diversification.
Market Dynamics
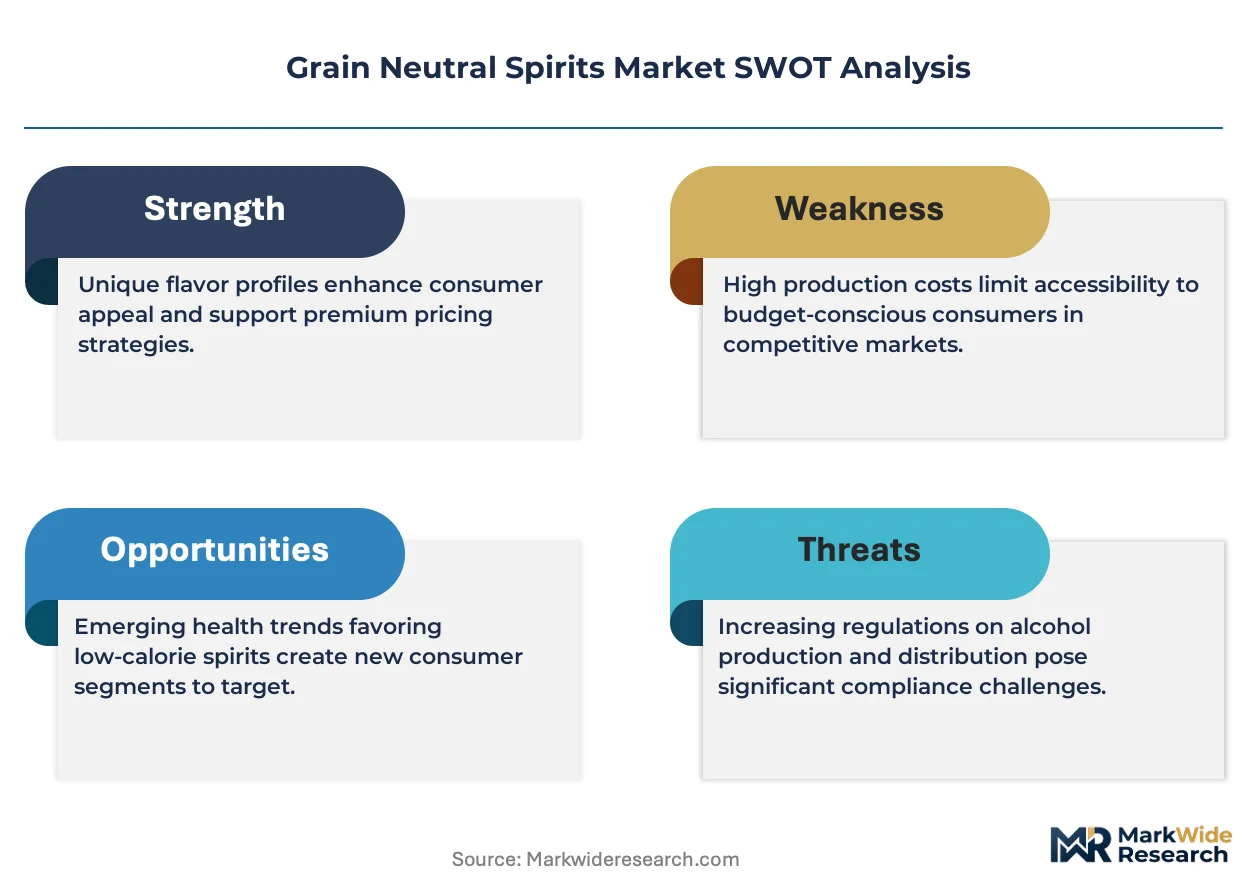
Clean-label specifications from beverage bottlers are compressing permissible congener thresholds and forcing distilleries to upgrade filtration infrastructure or lose contract volumes.
Growth Catalysts
- TTB Proof Standards:Federal classification clarity for neutral spirits above 190 proof enables premium vodka producers to market ultra-purity credentials directly to consumers.
- Botanical-Infusion Demand:Craft gin distilleries require ethanol bases with zero residual flavor interference, pulling volume toward specialized GNS suppliers with activated carbon and reverse osmosis capabilities.
- Corn Belt Feedstock Access:Concentrated grain origination networks across Iowa, Illinois, and Nebraska secure input cost stability for large-scale continuous column still operations.
Market Restraints
- EPA Effluent Limits:Wastewater discharge regulations for high-BOD stillage raise capital requirements for distillery expansion, particularly constraining small-batch producers in water-stressed regions.
- Natural Gas Price Volatility:Distillation energy costs fluctuate with Henry Hub pricing, compressing margins for facilities without anaerobic digesters or biogas capture systems.
- Input Concentration Risk:Yellow corn supply chains concentrate among three major origination houses, creating vulnerability to weather-driven yield shocks in the US Midwest.
Strategic Opportunities
- Pharmaceutical-Grade Certification:FDA ethanol purity requirements for sanitizer and excipient applications open dual-revenue streams for distilleries willing to implement USP-grade quality systems.
- Ready-to-Drink Cocktail Bases:Canned spritz and hard seltzer brands seek contract-distilled neutral spirits with consistent spec sheets for flavor-house blending operations.
- Carbon Capture Integration:Fermentation CO2 recovery systems qualify for IRA tax credits while generating merchant gas revenue streams for ethanol producers with proximity to food-grade CO2 buyers.
Industry Challenges
- Master Distiller Talent Scarcity:Deep expertise in continuous column still optimization and congener profiling remains concentrated among retiring practitioners, constraining quality consistency at scaling craft operations.
- Dual-Compliance Burden:Facilities serving both beverage and pharmaceutical end-uses must maintain parallel TTB and FDA quality systems, extending batch release timelines and audit frequency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Neutral Spirits Market |
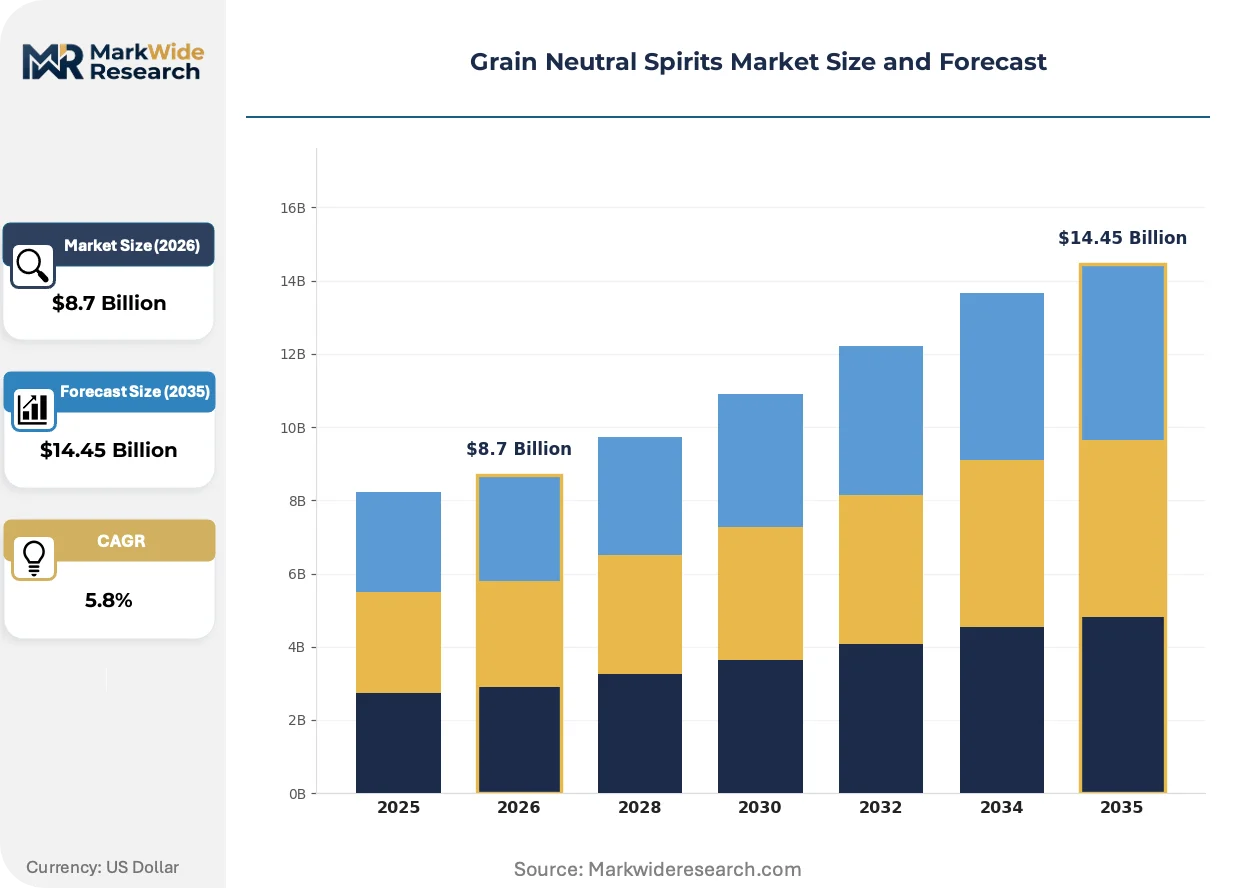
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vodka, Gin, Neutral Grain Spirits, Liqueurs End User: Beverage Industry, Food Industry, Distilleries, Retailers Application: Cocktails, Cooking, Infused Spirits, Bartending Distribution Channel: Online, Supermarkets, Specialty Stores, Bars |
| Companies Covered | Pernod Ricard SA, Wilmar International Limited, Archer Daniels Midland Company, Roquette Frères SA, Suntory Holdings Limited, Cargill Incorporated, MGP Ingredients Inc., Greenfield Global Inc., Diageo plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Neutral Spirits Market Strategic Shifts
Membrane filtration and carbon treatment technologies are displacing traditional copper pot finishing as the primary mechanism for achieving neutral spirit purity, while regulatory scrutiny of environmental discharge intensifies capital deployment patterns.
Continuous membrane filtration is integrating into distillery process flows as the dominant method for removing fusel oils and aldehydes without heat degradation. Large-scale vodka producers in the United States and France are retrofitting existing column still outputs with cross-flow nanofiltration skids. This technology is integrating quality consistency and throughput speed, compressing the competitive advantage of legacy charcoal filtration houses.
The EPA's updated effluent limitation guidelines for distillery operations are mandating anaerobic pretreatment of high-strength wastewater before municipal discharge. Facilities in California and Texas face construction deadlines for covered lagoon or upflow anaerobic sludge blanket systems. Small and mid-size producers are responding with mobile treatment unit leases rather than permanent capital installation, shifting cost structures toward operating expenditure models.
Contract distillation agreements are displacing in-house neutral spirit production among emerging craft spirit brands. New entrants in the gin and flavored vodka segments are outsourcing base ethanol procurement to specialized GNS houses with TTB-certified facilities. This pattern concentrates most visibly in Colorado and Oregon, where local craft labels prioritize botanical sourcing and brand marketing over capital-intensive distillation infrastructure ownership.
Grain Neutral Spirits Market Segmentation
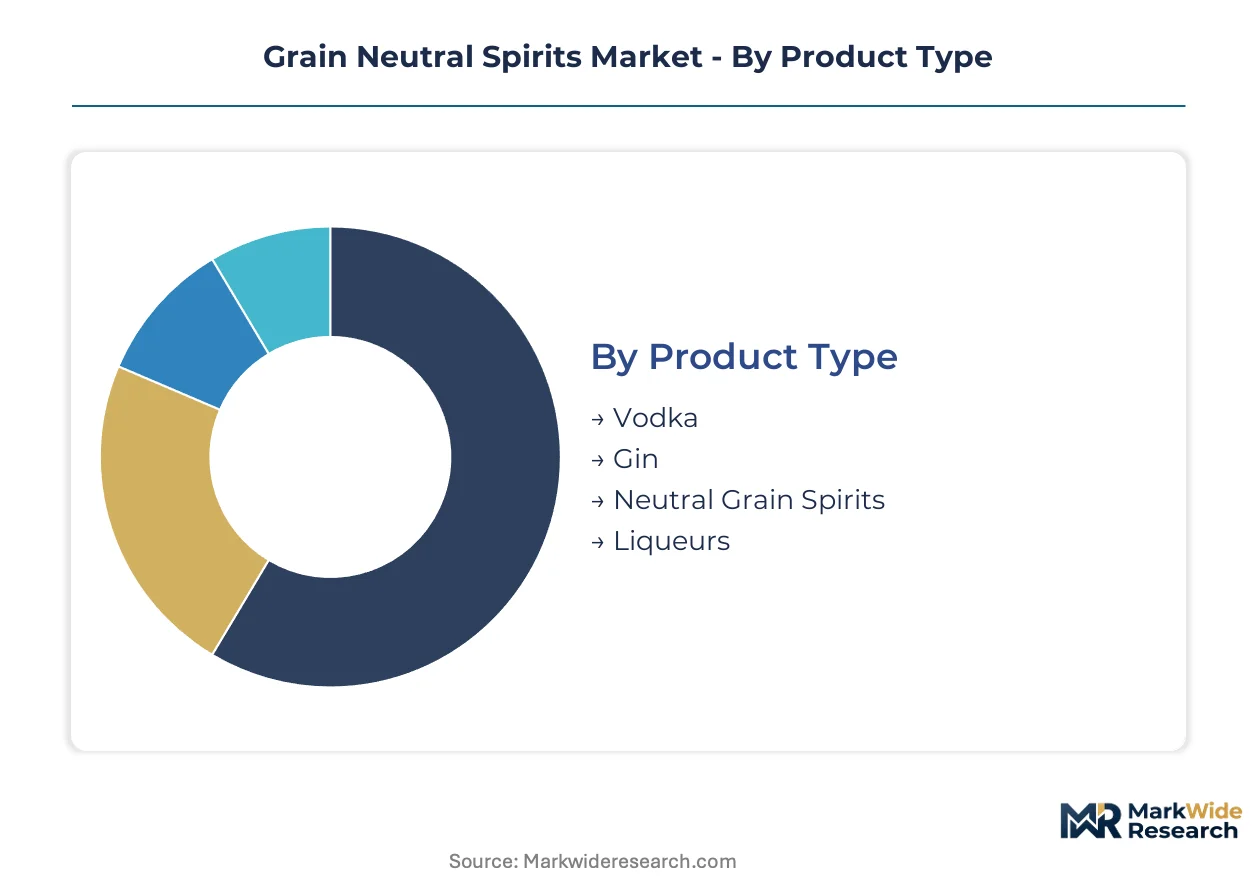
Grain neutral spirits serve divergent purity requirements across beverage manufacturing, pharmaceutical compounding, and industrial solvent applications. Segment boundaries reflect specification tiers rather than commodity equivalence, with filtration grade and congener thresholds determining contract eligibility and pricing bands.
Product Type:
Standardization dominates vodka and bulk neutral grain spirits, while gin and liqueur segments demand customizable base specifications that accommodate botanical integration and sugar addition protocols.
- Vodka:Distilled to 190+ proof and filtered through activated carbon or membrane systems to achieve TTB-defined neutrality. US and French producers drive procurement volumes as clean-label positioning tightens permissible congener limits below 2 ppm total fusel oils.
- Gin:Requires ethanol bases with zero residual flavor interference to prevent botanical masking. Craft distilleries in Colorado and Oregon concentrate demand for custom-specified neutral spirits with documented aldehyde profiles and guaranteed absence of sulfur compounds.
- Neutral Grain Spirits:Bulk commodity grade serving as feedstock for rectification and redistillation. Large continuous column still operations in Iowa and Illinois supply multinational bottlers with tanker-volume contracts tied to corn futures pricing.
- Liqueurs:Sugar-compatible bases with controlled ester content to prevent precipitation during maceration. European compounders prioritize consistent spec sheets for cream and fruit liqueur manufacturing.
Most installed capacity flows through Neutral Grain Spirits. Expansion is steepest in Gin.
End User:
Volume concentration sits with integrated beverage manufacturers, while margin capture favors specialized distilleries serving dual pharmaceutical and sanitizer markets.
- Beverage Industry:Multinational vodka and gin houses procure tanker quantities under annual contracts with congener guarantees. TTB-certified facilities in Nebraska and Kansas supply proof-gallon volumes to bottling plants in Kentucky and Tennessee.
- Distilleries:Contract distillation clients include emerging craft brands outsourcing base ethanol production to focus on botanical sourcing and brand marketing. Colorado and Oregon host the densest clustering of these arrangements.
- Food Industry:Flavor extraction and vanilla bean maceration applications require food-grade ethanol with documented heavy metal limits below FDA thresholds.
- Retailers:Private-label spirit brands source neutral grain spirits through co-packing agreements with established distilleries, concentrating procurement among three major origination houses.
Contract volumes concentrate with Beverage Industry. Fastest margin expansion occurs in Distilleries serving dual-use certification.
Application:
Functional requirements split between mixology-forward cocktail applications demanding batch consistency and culinary uses tolerating wider specification variance.
- Cocktails:Premium bars and ready-to-drink manufacturers specify ultra-clean bases that carry no interference with bitters, vermouth, or fresh citrus. Cross-flow nanofiltration capabilities differentiate suppliers in this segment.
- Infused Spirits:Botanical-infusion trends drive demand for ethanol with documented absence of sulfur compounds that react with terpenes. Small-batch producers in Texas and California lead procurement innovation.
- Bartending:High-volume nightclub and hotel operations prioritize cost-stable supply over premium filtration, accepting broader congener ranges for well-pour applications.
- Cooking:Culinary ethanol for flambé and extraction tolerates higher water content and less stringent congener control, opening supply to lower-proof distillation outputs.
Specification stringency peaks in Cocktails. Volume throughput remains largest in Bartending.
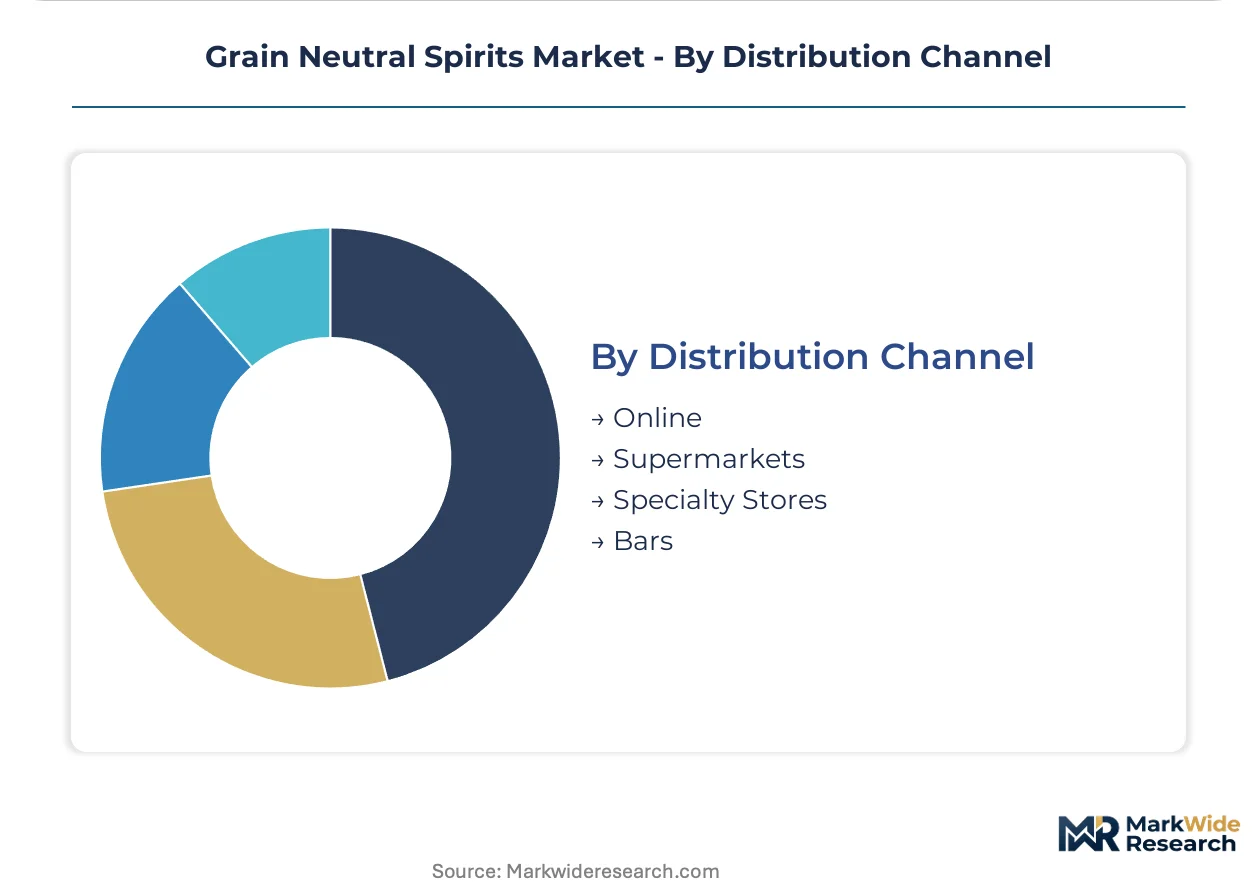
Distribution Channel:
Channel selection reflects buyer scale and specification complexity, with direct tanker delivery dominating bulk procurement and fragmented retail handling premium small-lot sales.
- Supermarkets:Mass-market vodka and gin brands distribute through controlled-state systems and private retail networks, with shelf placement tied to TTB label approval and state-by-state registration compliance.
- Specialty Stores:Independent retailers curate craft spirit portfolios including contract-distilled neutral bases with provenance marketing. Oregon and Colorado host the densest specialty channel penetration.
- Online:Direct-to-consumer shipping faces TTB and state liquor authority restrictions, limiting growth to states with explicit permissive legislation for distilled spirits delivery.
- Bars:On-premise accounts procure through authorized distributors with tied-house law compliance requirements varying by state jurisdiction.
Volume concentration remains with Supermarkets. Fastest channel development occurs in Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates more neutral grain spirit production capacity than France, yet both countries serve fundamentally different end-use segments. American facilities prioritize bulk commodity throughput for multinational vodka houses, while French distilleries emphasize pharmaceutical-grade certification and luxury gin bases.
United States
Corn Belt feedstock availability and TTB regulatory clarity sustain the world's largest neutral spirit production base. The EPA's updated effluent limitation guidelines mandate anaerobic pretreatment systems for distillery wastewater, raising capital barriers for new entrants. Iowa and Illinois host dense clusters of continuous column still operations supplying tanker volumes to Kentucky and Tennessee bottling plants.
France
Botanical-infusion trends from Parisian craft gin houses pull demand for ultra-clean ethanol with documented aldehyde profiles. ANSM pharmaceutical-grade standards enable dual-use certification for distilleries serving both beverage and sanitizer markets. The Cognac and Alsace regions concentrate specialized GNS facilities with activated carbon and reverse osmosis capabilities.
India
Domestic vodka and whisky brands expand procurement of imported neutral grain spirits as FSSAI labeling requirements tighten. BIS certification standards for food-grade ethanol create compliance differentiation among suppliers. Maharashtra and Karnataka host emerging contract distillation arrangements for craft spirit labels prioritizing botanical sourcing over capital-intensive still ownership.
Germany
Industrial ethanol applications and premium liqueur manufacturing split demand between commodity and specification-grade suppliers. REACH compliance for chemical-grade ethanol exports shapes filtration investment decisions. North Rhine-Westphalia and Bavaria concentrate integrated agricultural processors with captive distillation capacity.
United Kingdom
London's gin revival drives procurement of neutral spirits with guaranteed sulfur compound absence to prevent terpene reactions. HMRC excise classification clarity supports contract distillation growth for emerging craft brands. Scotland and England host specialized suppliers serving both heritage whisky blenders and independent botanical houses.
Grain Neutral Spirits Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered supply segments. The market structure concentrates volume among agricultural processors with captive grain origination, while margin capture favors specialized distilleries with dual-use pharmaceutical certification. Three archetypes dominate: integrated agribusinesses controlling upstream feedstock, contract distillation houses serving craft brand outsourcing, and diversified beverage multinationals with captive neutral spirit production. Capacity expansion and strategic partnerships represent the dominant competitive moves, particularly for facilities seeking carbon capture integration and anaerobic digestion systems.
Among integrated agricultural processors, Archer Daniels Midland Company and Cargill Incorporated exemplify the feedstock-control archetype with extensive origination networks. MGP Ingredients Inc. occupies the contract distillation specialist tier, serving both established liquor houses and emerging craft labels with custom specification capabilities. These three entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Pernod Ricard SA |
| Wilmar International Limited |
| Archer Daniels Midland Company |
| Roquette Frères SA |
| Suntory Holdings Limited |
| Cargill Incorporated |
| MGP Ingredients Inc. |
| Greenfield Global Inc. |
| Diageo plc |
| Others |
Value Chain & Pricing Dynamics
Family-owned Midwest grain processors anchor supply-side discipline through captive origination networks that buffer spot-market volatility while enforcing long-term contract pricing fidelity across beverage and pharmaceutical offtake agreements.
Pricing Analysis
Capacity additions in Iowa and Illinois are reshaping price floors for bulk neutral grain spirits as continuous column still expansions compress per-proof-gallon production costs. Pricing stratifies across pharmaceutical-grade, premium beverage, and commodity rectification tiers, with TTB certification and FDA dual-compliance commanding the widest spreads. Cost compression in standard-grade volumes is intensifying because corn futures hedging costs have risen alongside natural gas price volatility. Contract bottlers in Kentucky and Tennessee exhibit the highest price sensitivity, while Parisian craft gin houses prioritize specification guarantees over unit economics.
Supply Chain Analysis
Rail freight and tanker logistics costs from Corn Belt production clusters to coastal bottling plants represent the dominant supply chain cost layer after feedstock procurement. Geographic concentration centers on the United States, France, and India, with Iowa and Illinois hosting the densest production infrastructure. The supply chain draws from yellow corn origination networks, activated carbon filtration media, and natural gas feedstock for distillation energy. Single-source vulnerability concentrates in Midwest grain origination houses controlling over half of feedstock supply. Distribution runs through direct tanker delivery for bulk beverage manufacturers and drum shipments for pharmaceutical compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA effluent guidelines and TTB proof standards simultaneously raise capital barriers and create certification-based pricing power for compliant producers.
For Market Incumbents: Hedge feedstock exposure through backward integration into grain origination or long-dated corn futures positions to offset weather-driven yield volatility. Prioritize anaerobic digestion and carbon capture infrastructure to qualify for IRA tax credits while insulating margins from natural gas price swings. Defensive consolidation of craft contract distillation capacity in Colorado and Oregon will preempt emerging entrants from securing botanical-forward client relationships.
For New Entrants and Emerging Players: Private-label spirit brands and ready-to-drink cocktail manufacturers represent the most penetrable buyer archetype, as these segments prioritize specification consistency over legacy supplier relationships. Target pharmaceutical-grade certification as the fastest margin expansion pathway, given FDA dual-compliance requirements create scarcity rents. Establish co-packing partnerships with established distilleries rather than greenfield capacity to compress time-to-revenue and avoid EPA capital requirements.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale contract distillation specialists lacking pharmaceutical certification but possessing TTB-certified infrastructure and regional market access. Long-term viability favors facilities with proximity to Corn Belt feedstock and demonstrated capability to serve both beverage and sanitizer end-uses. Monitor TTB guidance on craft distillery classification and state-level direct-to-consumer shipping legislation as inflection indicators for contract distillation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | FDA dual-compliance unlocks sanitizer and excipient revenue streams beyond beverage applications. |
| Anaerobic Digestion System Installation | EPA effluent compliance qualifies facilities for IRA tax credits while reducing natural gas dependency. |
| Contract Distillation Capacity Expansion | Outsourcing trends from Colorado and Oregon craft brands concentrate volume toward specialized GNS houses. |
| Carbon Capture Integration | Fermentation CO2 recovery generates merchant gas revenue and carbon credit monetization opportunities. |
| Cross-Flow Nanofiltration Retrofit | Membrane filtration displaces legacy charcoal systems for ultra-clean ethanol bases serving botanical-infusion demand. |
Study Parameters
Coverage spans the United States, France, India, Germany, and the United Kingdom, with primary inputs from each market gathered through structured interviews with master distillers, TTB compliance officers, grain procurement managers at agricultural processors, and pharmaceutical ethanol buyers. Secondary validation draws from EPA effluent limitation guidelines, TTB labeling standards, FDA ethanol purity requirements, customs trade data for neutral spirit imports, and SEC filings from publicly traded agricultural processors. Bottom-up volume estimates from individual production facilities triangulate against top-down demand projections from beverage and pharmaceutical end-use segments.
Segmentation modeling operates at product-type granularity across vodka, gin, neutral grain spirits, and liqueurs, with additional dimensioning by end-user category and application intensity. Value projections across the analysis window incorporate proof-gallon pricing differentials by certification tier, corn futures basis adjustments, and energy cost pass-through assumptions. CAGRs derive from trend extrapolation of procurement volumes by multinational bottlers and contract distillation growth patterns in craft-heavy states.
Underlying measurement precision varies by segment; pharmaceutical-grade certification volumes carry tighter precision than commodity rectification grades due to documented FDA registration requirements. Forecasts embed assumptions regarding EPA enforcement consistency, natural gas price trajectory, and craft distillery outsourcing propensity that could shift materially with regulatory or macroeconomic developments. Stakeholders should weight assumptions against their own operating context and feedstock hedging capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
US Alcohol E-Commerce Market
Alcoholic Beverages
Black Beer Market
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Craft Beer Market
Alcoholic Beverages
France Alcohol E-Commerce Market
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Asia Pacific Wine Coolers Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
Home Brewing Systems Market
Alcoholic Beverages
Premixed Cocktail Shots Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Hopped Malt Extract Market
Alcoholic Beverages
Luxury Wines and Spirits Market
Alcoholic Beverages
Beer Processing Market