
 Canada Wine Coolers Market | 2026-2036
Canada Wine Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Wine Coolers Market Insights
Market Context
The hospitality sector is decoupling from residential demand as Canada's restaurant and hotel recovery accelerates post-pandemic. LG Corporation leverages its compressor technology leadership to anchor the premium built-in segment in Toronto and Montreal. Danby competes aggressively on price in the compact residential channel through mass retail partnerships. Electrolux AB differentiates via under-counter integration expertise targeting Vancouver's high-density condominium market.
Technical Definition and Segment Structure
Canada wine coolers are thermoelectric or compressor-based refrigeration appliances engineered to maintain precise temperature zones between 5°C and 18°C with humidity control between 50% and 70% RH for optimal wine preservation. These units serve commercial cellaring, hospitality display, and residential collection management across Canada's climate-variable geography. The built-in product type commands the strongest margin pool as kitchen-integrated design gains traction in new condominium construction, while the hospitality end user segment outpaces residential growth fueled by Ontario's restaurant licensing expansion and British Columbia's wine tourism infrastructure. Electric cooling technology dominates the compact and medium size tiers, though compressor systems retain preference in large and extra large formats where temperature stability across dual zones proves critical.
Regulatory Frame and Outlook
Health Canada's Energy Efficiency Regulations under the Natural Resources Canada EnerGuide program mandate minimum performance standards for wine cooler energy consumption, while provincial electrical safety authorities in Ontario and British Columbia enforce CSA C22.2 certification for commercial installation. The Canadian Food Inspection Agency's guidelines on beverage storage temperature indirectly influence commercial buyer specifications, particularly in licensed establishments. Stakeholders must monitor evolving federal refrigerant phase-down schedules under Canada's Montreal Protocol commitments and their impact on compressor technology selection across the forecast horizon.
Market Dynamics
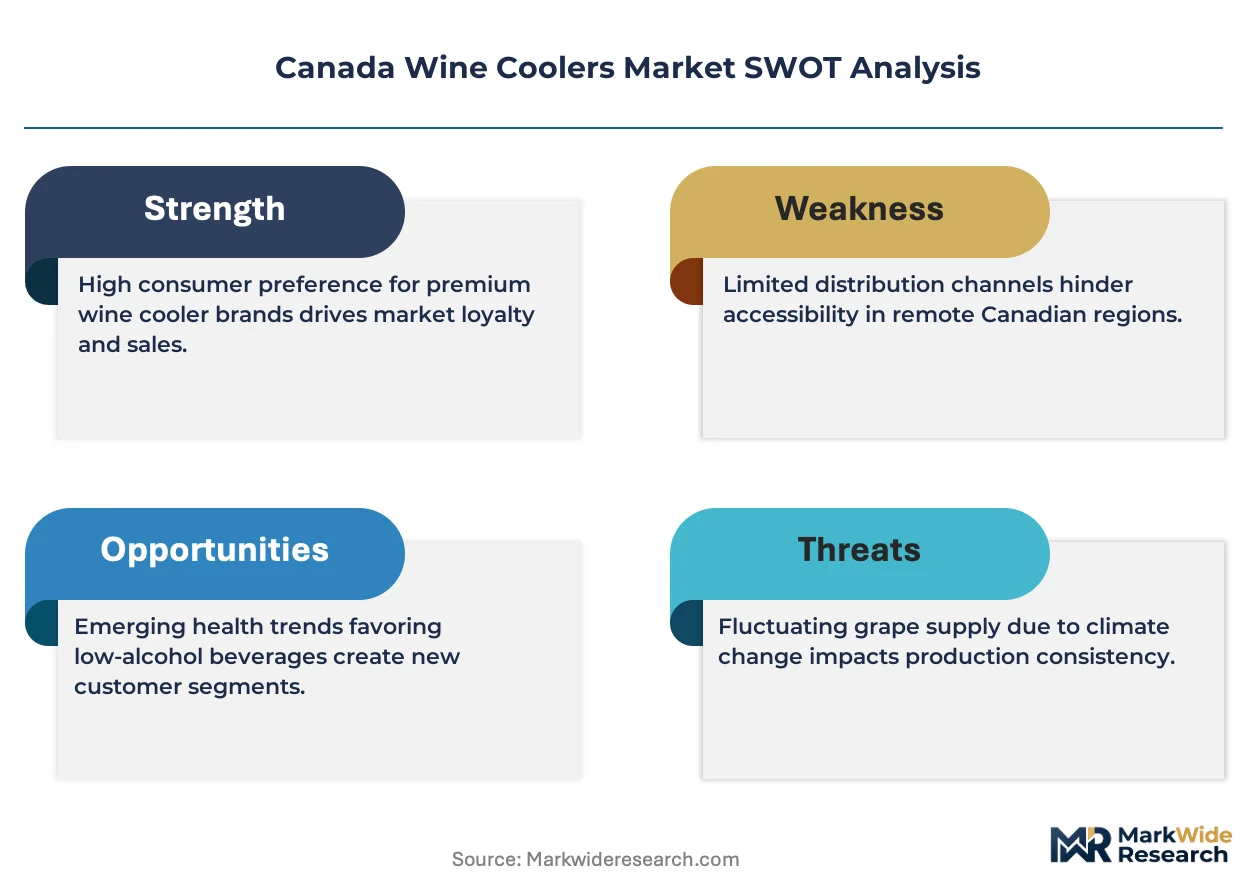
Canada's wine cooler market pivots on provincial liquor board procurement centralization, which compresses distributor margins while elevating specification standards for hospitality-grade units.
Growth Catalysts
- Ontario's Restaurant Licensing Expansion:The Alcohol and Gaming Commission of Ontario accelerated patio and lounge permits post-pandemic, triggering replacement cycles for under-counter display refrigeration in Toronto's entertainment district.
- CSA C22.2 Commercial Certification:Electrical safety authorities in British Columbia and Ontario mandated upgraded certification tiers for permanent hospitality installations, forcing specification upgrades that favor premium compressor systems.
- Dual-Zone Compressor Engineering:Advances in variable-speed compressor technology now deliver temperature stability within 0.5°C variance across separate compartments, enabling simultaneous red and white service from single units.
Market Restraints
- Copper and Aluminum Input Volatility:Heat exchanger and coil fabrication depends on base metal prices that fluctuate with commodity cycles, compressing manufacturer margins during inflationary periods.
- Quebec Distributor Concentration:The Société des alcools du Québec controls inbound logistics for commercial beverage equipment, creating single-channel dependency for brands seeking provincial hospitality penetration.
- Thermoelectric Performance Ceiling:Peltier-based cooling systems face fundamental thermodynamic limits below 12°C ambient differential, disqualifying them from unheated Canadian garage installations and northern climate deployment.
Strategic Opportunities
- Atlantic Canada Wine Tourism Infrastructure:Nova Scotia's emerging vineyard corridor lacks adequate hospitality refrigeration density, presenting first-mover positioning for built-in specialists targeting boutique inn and restaurant construction.
- Natural Resources Canada EnerGuide Tier Advancement:Anticipated 2026 efficiency standard revisions will create regulatory pull for inverter-driven compressor retrofits in existing commercial installations.
- Smart Home Integration Convergence:Wi-Fi-enabled temperature logging and humidity alerting is expanding into residential collector segments previously served by passive cellaring, opening subscription service revenue streams.
Industry Challenges
- Commercial Refrigeration Technician Shortage:HVAC-R certification programs in Ontario and British Columbia graduate insufficient technicians qualified for built-in installation and sealed-system repair, extending service response times.
- Legacy 120V Infrastructure Compatibility:Older Toronto condominium stock lacks dedicated 240V circuits for high-capacity units, forcing costly electrical upgrades or limiting product selection for renovation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Wine Coolers Market |
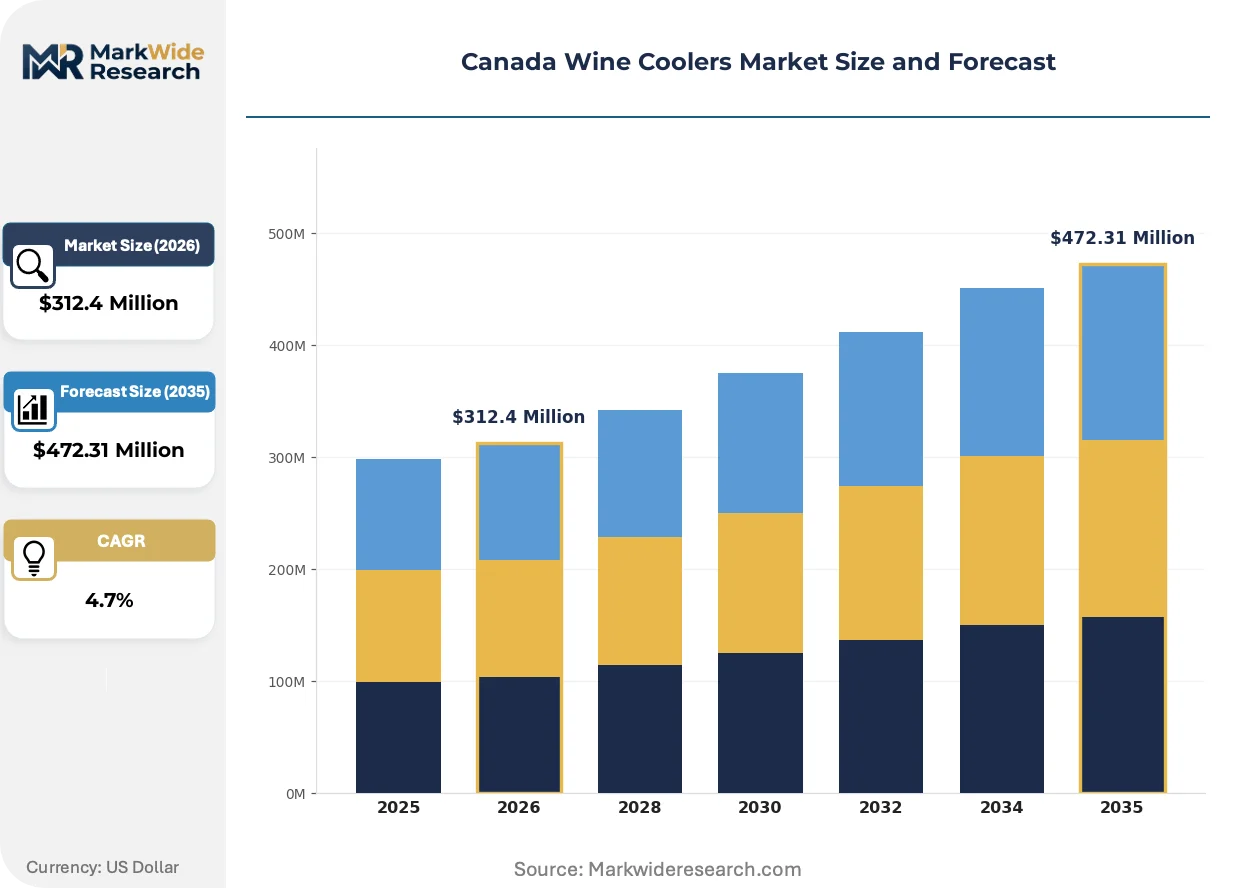
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Electric, Portable, Built-in End User: Residential, Commercial, Hospitality, Retail Size: Compact, Medium, Large, Extra Large Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Haier Group Corporation, LG Corporation, Equator Advanced Appliances, The Legacy Companies (Avanti Products Inc), Electrolux AB, Eurocave SAS, Dunavox Kft, La Sommeliere Int SAS, Danby, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Wine Coolers Market Trends and Innovations
Active transformation in Canada's wine cooler landscape centers on precision climate engineering, federal efficiency mandates, and procurement professionalization reshaping buyer-vendor relationships.
Inverter-driven variable-speed compressors are expanding into mid-tier residential and commercial segments previously served by fixed-speed systems. Vancouver's high-density condominium developers specify these units for under-counter kitchen integration, where noise reduction and temperature precision command premium positioning. The technology is expanding into price-accessible formats through economies of scale in Asian component sourcing.
Health Canada's Montreal Protocol refrigerant phase-down schedule accelerates hydrofluorocarbon transition timelines for appliance manufacturers. The regulatory pressure forces compressor redesigns using R600a isobutane and R290 propane alternatives with lower global warming potential. Commercial buyers in Ontario's licensed establishments face accelerated replacement cycles as service parts for legacy refrigerant systems diminish.
Consolidated procurement through provincial liquor boards and hospitality purchasing cooperatives concentrates buying power among fewer decision-makers. Independent restaurants in British Columbia's Okanagan Valley increasingly source through group purchasing organizations rather than traditional equipment distributors, compressing margin structures and elevating service-bundle requirements. This concentration is most visible in Vancouver's hotel corridor, where property management companies negotiate enterprise-wide supply agreements spanning multiple brands.
Canada Wine Coolers Market Segmentation
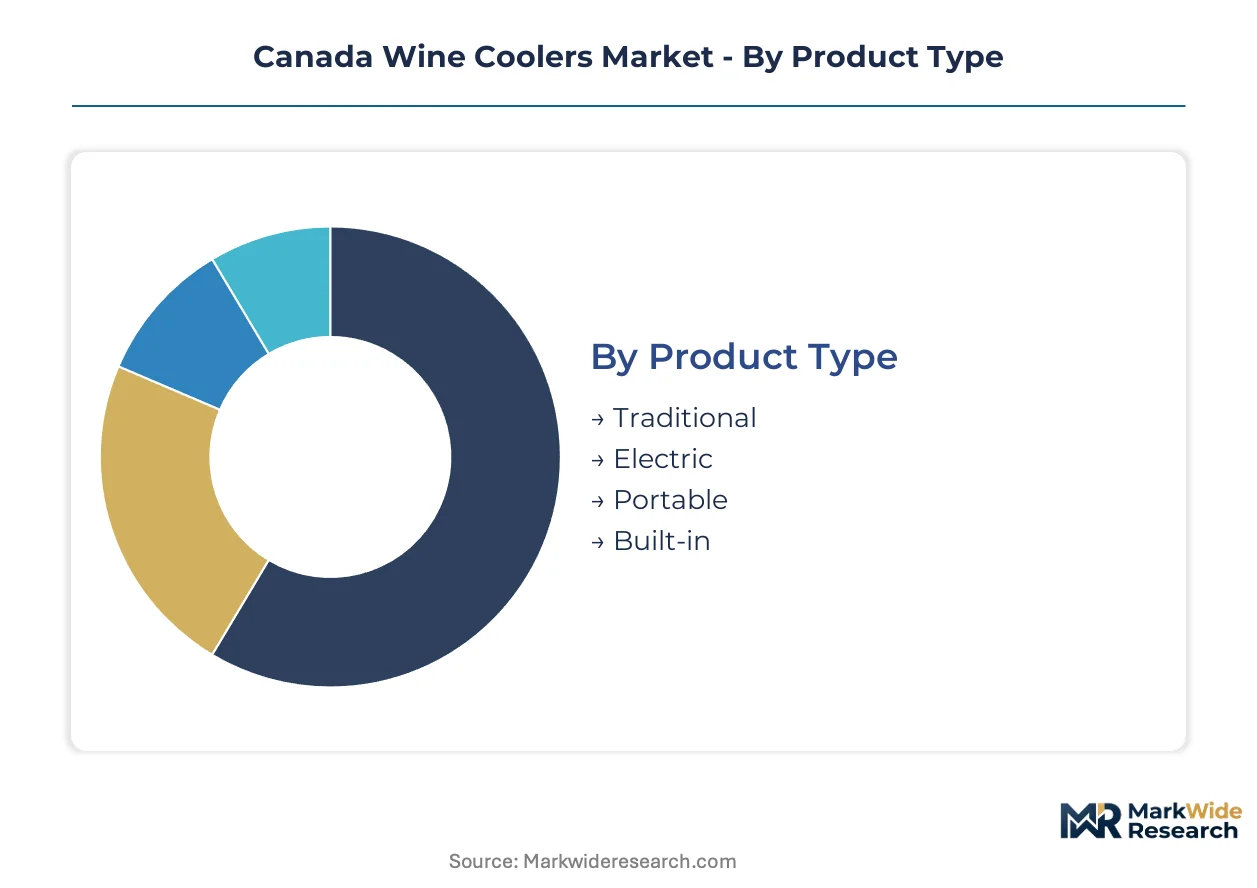
Wine cooler segmentation in Canada reflects divergent certification burdens across installation contexts. Health Canada's EnerGuide efficiency tiers and provincial electrical safety mandates fragment compliance requirements, with built-in hospitality units facing the densest regulatory stack.
Product Type:
CSA C22.2 commercial certification applies differentially across product types, with permanent installation categories carrying heavier approval burdens than portable alternatives.
- Traditional:Conventional freestanding units with single-zone compressor architecture dominate residential replacement cycles in Ontario's suburban markets. These systems require only baseline EnerGuide labeling for retail distribution, though Ontario Electrical Safety Code compliance adds installation-layer costs in older Toronto housing stock.
- Electric:Thermoelectric Peltier systems operate silently below 75dB, suiting open-concept condominiums in Vancouver where noise restrictions constrain mechanical alternatives. Health Canada's energy efficiency thresholds disadvantage thermoelectric technology above 50L capacity, capping addressable market share.
- Portable:Countertop and rolling units bypass fixed electrical permitting entirely, accelerating purchase velocity through mass retail channels in Quebec.
- Built-in:Kitchen-integrated designs demand dual certification under CSA C22.2 and provincial building codes, elevating specification scrutiny for Vancouver condominium developers and Toronto hospitality construction.
Built-in sits at the top of the volume ranking, with Portable climbing the fastest.
End User:
Procurement professionalization varies sharply across end user categories, with institutional buyers consolidating purchasing power while residential demand fragments across channels.
- Residential:Individual collectors drive compact and medium format demand through big-box retail and direct-to-consumer channels. Toronto's high-rise density constrains floor-standing unit adoption, tilting preferences toward under-counter integration.
- Commercial:Independent restaurants and wine bars in British Columbia's Okanagan Valley source through group purchasing organizations, compressing distributor margins while elevating service-bundle requirements for multi-unit warranty coverage.
- Hospitality:Hotel and resort procurement in Vancouver's tourism corridor operates through enterprise-wide supply agreements negotiated by property management companies spanning multiple brands. These contracts mandate inverter-driven compressor systems for energy reporting compliance.
- Retail:Liquor board-operated stores and private wine merchants require display refrigeration with glass-door visibility and LED lighting for merchandising optimization, with the Société des alcools du Québec controlling inbound logistics for Quebec-based retail chains.
Hospitality commands the steepest expansion trajectory, with Residential maintaining absolute volume leadership.
Size:
Physical capacity segmentation maps directly to cooling technology feasibility, with thermoelectric economics deteriorating above threshold volumes where compressor efficiency dominates.
- Compact:Under-50L units serve countertop and dormitory applications where space constraints override capacity needs. Peltier technology retains cost competitiveness in this tier, though Health Canada efficiency regulations narrow the gap.
- Medium:50-150L formats balance residential collection scale with kitchen footprint limitations, dominating Vancouver condominium specifications where developer-installed appliances must satisfy strata council aesthetic standards.
- Large:150-300L units transition exclusively to compressor-based systems with dual-zone capability, enabling simultaneous red and white service in Toronto restaurant applications.
- Extra Large:Above-300L capacity addresses estate cellaring and commercial inventory management, with variable-speed inverter compressors becoming standard for temperature stability across fluctuating ambient conditions in unheated Canadian garage installations.
Medium formats lead current installation volumes, with Extra Large gaining share fastest in hospitality new construction.
Price Tier:
Margin structures stratify across certification intensity and component sourcing geography, with premium tiers capturing value from efficiency performance and smart connectivity integration.
- Budget:Entry-level thermoelectric units sourced through Asian component supply chains dominate mass retail price points below 300 CAD, sacrificing temperature precision for acquisition cost minimization.
- Mid-range:Fixed-speed compressor systems with single-zone operation serve replacement demand in established residential markets, with EnerGuide tier positioning determining shelf placement in Canadian Tire and Home Depot channels.
- Premium:Dual-zone compressor engineering with inverter drives and Wi-Fi connectivity commands positioning in Vancouver developer specifications and Toronto hospitality renovations, where energy reporting and remote monitoring justify price escalation.
- Luxury:Custom panel-ready integrated systems with humidity-independent climate control target high-net-worth collectors in Montreal's Westmount and Vancouver's Shaughnessy districts, with installation requiring specialized HVAC-R technicians holding CSA certification.
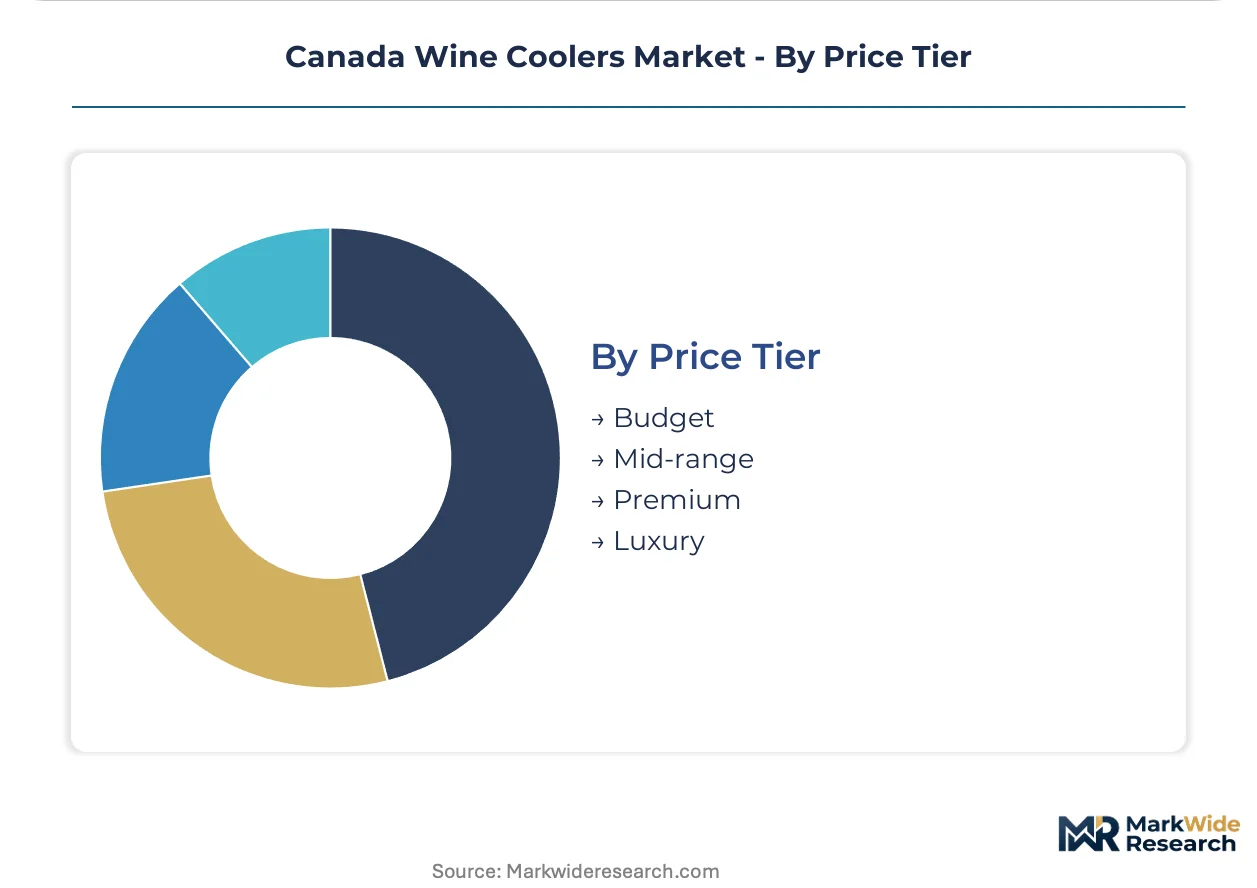
Mid-range maintains volume dominance, with Premium expanding most quickly as efficiency regulations force specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics favor provinces with streamlined electrical permitting and lower commercial certification costs, driving production migration toward Ontario and British Columbia while Quebec's centralized distribution creates compliance friction.
Ontario
Toronto's restaurant licensing expansion and condominium construction pipeline anchor provincial demand. The Alcohol and Gaming Commission of Ontario accelerated patio permits post-pandemic, triggering hospitality refrigeration replacement cycles. Kitchen-integrated built-in units dominate new high-rise developments across the Greater Toronto Area.
British Columbia
Vancouver's wine tourism cluster and high-density condominium market sustain premium-tier adoption. The British Columbia Safety Authority enforces CSA C22.2 certification for permanent hospitality installations, elevating specification standards. Okanagan Valley vineyard hospitality projects concentrate demand in Kelowna and Penticton corridors.
Quebec
Montreal's Westmount district and Quebec City hospitality corridors drive luxury-tier residential demand. The Société des alcools du Québec controls inbound logistics for commercial beverage equipment, creating single-channel procurement dependency. Independent restaurants face margin compression through this centralized distribution structure.
Alberta
Calgary's corporate hospitality sector and Edmonton retail chains sustain mid-range volume demand. The provincial government maintains lighter regulatory touch on commercial refrigeration certification compared to coastal provinces. Distribution runs through independent equipment dealers rather than liquor board intermediaries.
Atlantic Canada
Nova Scotia's emerging vineyard corridor lacks adequate hospitality refrigeration density, presenting positioning opportunities. Provincial electrical codes adopt CSA standards with reduced enforcement bandwidth compared to Ontario. Boutique inn construction in Wolfville and Annapolis Valley drives compact-format demand.
Canada Wine Coolers Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers extend from adjacent refrigeration categories into wine-specific climate control. The vendor base clusters around three strategic archetypes: Asian conglomerates with compressor technology leadership, European specialists in built-in integration, and North American mass-market distributors competing on price-accessible formats. Technology licensing and backward integration into compressor supply represent the dominant competitive vectors, with efficiency certification tiers serving as the primary differentiation mechanism.
Among Asian conglomerates, Haier Group Corporation and LG Corporation exemplify scale-driven positioning anchored by captive compressor manufacturing. Electrolux AB occupies a position within the European specialist tier, representing integration expertise for under-counter hospitality applications. Danby sits within the North American mass-market archetype, competing through retail channel density and price-accessible thermoelectric formats. These three anchors illustrate how geographic origin and corporate structure map to divergent strategic postures across certification-intensive and price-sensitive segments.
| Leading Market Players |
|---|
| Haier Group Corporation |
| LG Corporation |
| Equator Advanced Appliances |
| The Legacy Companies (Avanti Products Inc) |
| Electrolux AB |
| Eurocave SAS |
| Dunavox Kft |
| La Sommeliere Int SAS |
| Danby |
| Others |
Pricing and Supply Chain Analysis
Built-in versus freestanding certification divergence splits Canada's wine cooler market into parallel cost structures, with CSA C22.2 commercial compliance adding 15-25% to landed costs while thermoelectric commodity units flow through mass retail without electrical permitting overhead. This bifurcation concentrates margin capture among compressor-integrated manufacturers serving Toronto hospitality and Vancouver condominium developers, while Asian-sourced Peltier systems compete on acquisition price through Quebec's SAQ-controlled retail channels.
Pricing Analysis
Distributor margin compression runs through provincial liquor board procurement centralization, particularly the Société des alcools du Québec's single-channel control over commercial beverage equipment. Three-tier pricing structure across premium, standard, and economy levels maps to certification intensity and cooling technology, with inverter-driven dual-zone units commanding positioning in Vancouver developer specifications while fixed-speed single-zone systems serve Alberta's independent equipment dealer network. Price differentiation hinges on EnerGuide tier positioning and CSA C22.2 commercial certification, with hospitality buyers in Ontario's AGCO-licensed establishments least sensitive to acquisition cost and residential collectors through Canadian Tire most responsive to promotional pricing.
Supply Chain Analysis
Single-source vulnerability sits with Chinese compressor component supply, where variable-speed inverter manufacturing concentrates among three dominant OEMs serving Haier and LG captive production. Heat exchanger fabrication draws from South Korean aluminum coil supply and Thai copper tubing, with refrigerant charging and final assembly anchored in Guangdong province. Tariff exposure on finished appliances entering through Vancouver port creates margin risk for European specialists like Electrolux, while distribution runs through provincial electrical safety authority certification layers that add 6-8 week lead times for built-in hospitality installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's wine cooler market compounds steadily as provincial hospitality licensing expansion and condominium construction sustain replacement and new-installation demand across Ontario and British Columbia.
For Market Incumbents: Deepen captive compressor technology control to defend margin position against Asian cost leaders, prioritizing R&D in R600a isobutane refrigerant systems ahead of Health Canada's Montreal Protocol phase-down deadlines. Secure CSA C22.2 pre-certification for entire product portfolios to accelerate Ontario and British Columbia hospitality procurement cycles, locking out smaller competitors lacking compliance bandwidth.
For New Entrants and Emerging Players: The mid-range price-point gap between Danby's thermoelectric economy positioning and LG's premium built-in tier offers white-space for inverter-driven single-zone specialists targeting Alberta's lighter regulatory environment. Atlantic Canada's underpenetrated vineyard corridor, particularly Nova Scotia's Wolfville inn construction pipeline, presents first-mover positioning without entrenched distributor relationships. Pursue direct-to-developer specification in Vancouver's high-rise market through strata council aesthetic compliance rather than retail channel buildout.
For Investors and Strategic Acquirers: Consolidation pressure builds where CSA C22.2 certification costs and Health Canada EnerGuide tier advancement force sub-scale manufacturers toward exit or acquisition. Target mid-tier compressor-integrated specialists with established provincial electrical safety authority relationships and existing hospitality dealer networks. Monitor refrigerant transition timelines and technician certification graduation rates from Ontario HVAC-R programs as inflection indicators for service-network valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| CSA C22.2 Pre-Certification Investment | Accelerates procurement approval in Ontario and British Columbia hospitality corridors. |
| Inverter Compressor R&D Expansion | Positions manufacturers ahead of Natural Resources Canada EnerGuide tier advancement deadlines. |
| Atlantic Canada Distribution Partnership | Captures Nova Scotia vineyard tourism infrastructure buildout before competitor saturation. |
| Refrigerant Transition Compliance Program | Ensures service parts availability as Health Canada Montreal Protocol phase-down accelerates. |
| HVAC-R Technician Training Alliance | Addresses Ontario and British Columbia commercial refrigeration certification shortage extending response times. |
Research Methodology
Multiple input streams — regulatory filings with Health Canada and Natural Resources Canada, provincial electrical safety authority certification databases, and hospitality procurement contract disclosures — were reconciled against primary interviews with commercial refrigeration distributors, condominium developer specification managers, and restaurant equipment procurement officers. Secondary validation drew from CSA Group standards documentation, Société des alcools du Québec inbound logistics records, and Alcohol and Gaming Commission of Ontario licensing expansion data. Bottom-up unit shipment estimates by product type and price tier were triangulated against top-down market value reconstruction.
Data-stream reconciliation across the analysis window applied segmentation dimensions of cooling technology, installation context, and end-user procurement professionalization. CAGRs were derived from trend extrapolation of provincial liquor board equipment procurement, condominium construction permitting, and hospitality licensing expansion. Industry-specific forecast inputs included Montreal Protocol refrigerant phase-down schedules and evolving CSA C22.2 certification tier requirements.
Caveats apply where copper and aluminum commodity volatility, provincial distributor consolidation, or refrigerant technology transition delays could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Canned Wine Market
Alcoholic Beverages
Fortified Wine Market
Alcoholic Beverages
Tequila Market
Alcoholic Beverages
Grain Neutral Spirits Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Spirits Miniatures Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Wine Destemmer Market
Alcoholic Beverages
France Alcohol E-Commerce Market
Alcoholic Beverages
Wine Bags Market
Alcoholic Beverages
Barware Market
Alcoholic Beverages
Beer Kegs Market
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
West Africa Alcoholic Beverages Market