
 Whiskey Market | 2026-2036
Whiskey Market Size, Share, and Industry Trends Forecast 2026-2036
Whiskey Market Analysis
Single-serve miniature bottles and curated tasting sets are realigning how consumers sample premium expressions before committing to full-size purchases. Diageo leverages its global distribution network to place these formats in airport retail and hotel minibars across multiple continents. Brown-Forman anchors its portfolio strength in American whiskey through sustained investment in barrel programs and heritage visitor experiences. William Grant & Sons differentiates via family-owned positioning and limited-edition releases that command collector premiums.
Whiskey denotes a distilled spirit produced from fermented grain mash, typically aged in wooden casks for a minimum period defined by regional standards, with alcohol content generally ranging from 40% to 60% ABV depending on category and origin regulations. The spirit serves commercial purposes across retail, on-premise hospitality, and gifting segments where provenance and maturation duration function as quality signals. Blended whiskey occupies the largest volume position due to accessible price points and consistent supply, while single malt commands disproportionate margin pools from connoisseur segments. Japanese origin expressions represent the fastest-growing category as distribution expands beyond domestic boundaries into North American and European specialty retailers.
The U.S. Alcohol and Tobacco Tax and Trade Bureau enforces strict identity standards for bourbon and straight rye, shaping product formulation and label claims for American producers. EMA and national food safety regulators across Europe govern additive restrictions and geographic indication protections that affect import access and competitive positioning for Scotch and Irish categories. The EU Green Deal's packaging waste directives are pressing distillers toward lighter glass weights and recycled content minimums. Stakeholders must monitor how regulatory divergence between American and European labeling regimes affects cross-border portfolio strategy and production investment timing.
Market Dynamics
Premiumization pressures and maturation capacity constraints are compressing inventory cycles across distilleries, forcing capital allocation trade-offs between aged stock accumulation and near-term revenue capture.
Growth Catalysts
- EU Green Deal packaging mandates:Recycled glass minimums and weight reduction targets are accelerating lightweight bottle adoption, reducing per-unit shipping costs for exporters.
- Direct-to-consumer channels:E-commerce platforms and distillery subscription services are bypassing traditional wholesale markups, capturing margin previously lost to distributor tiers.
- Single malt maturation premiums:Collector demand for 18+ year expressions is widening price spreads between age-statement and NAS categories, incentivizing extended barrel programs.
Market Restraints
- Oak barrel supply concentration:American white oak cooperage capacity centers on Missouri and Kentucky, creating bottlenecks for bourbon producers seeking new charred barrels.
- Climate volatility in barley belts:Scottish and Irish distillers face harvest variability in Aberdeenshire and Cork, squeezing malt supply consistency.
- Spirit substitution in emerging markets:Local baijiu in China and soju in South Korea retain price advantages at entry tiers, limiting whiskey penetration.
Strategic Opportunities
- India's import tariff liberalization:Proposed reductions on Scotch and Irish whiskey duties would unlock volume expansion in a 1.4 billion population market.
- Non-age-statement innovation:Cask-finished and wine-barrel expressions offer margin protection while bypassing the capital intensity of extended aging.
- Climate-controlled warehousing technology:Precision humidity and temperature systems enable maturation acceleration without quality degradation, shortening inventory cycles.
Industry Challenges
- Master distiller talent scarcity:Retirement waves across Scotland and Kentucky are outpacing apprenticeship pipeline output, threatening consistency in blending programs.
- TTB label approval timelines:The U.S. Alcohol and Tobacco Tax and Trade Bureau's backlog for expression approvals delays market entry by 6-12 months for new releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whiskey Market |
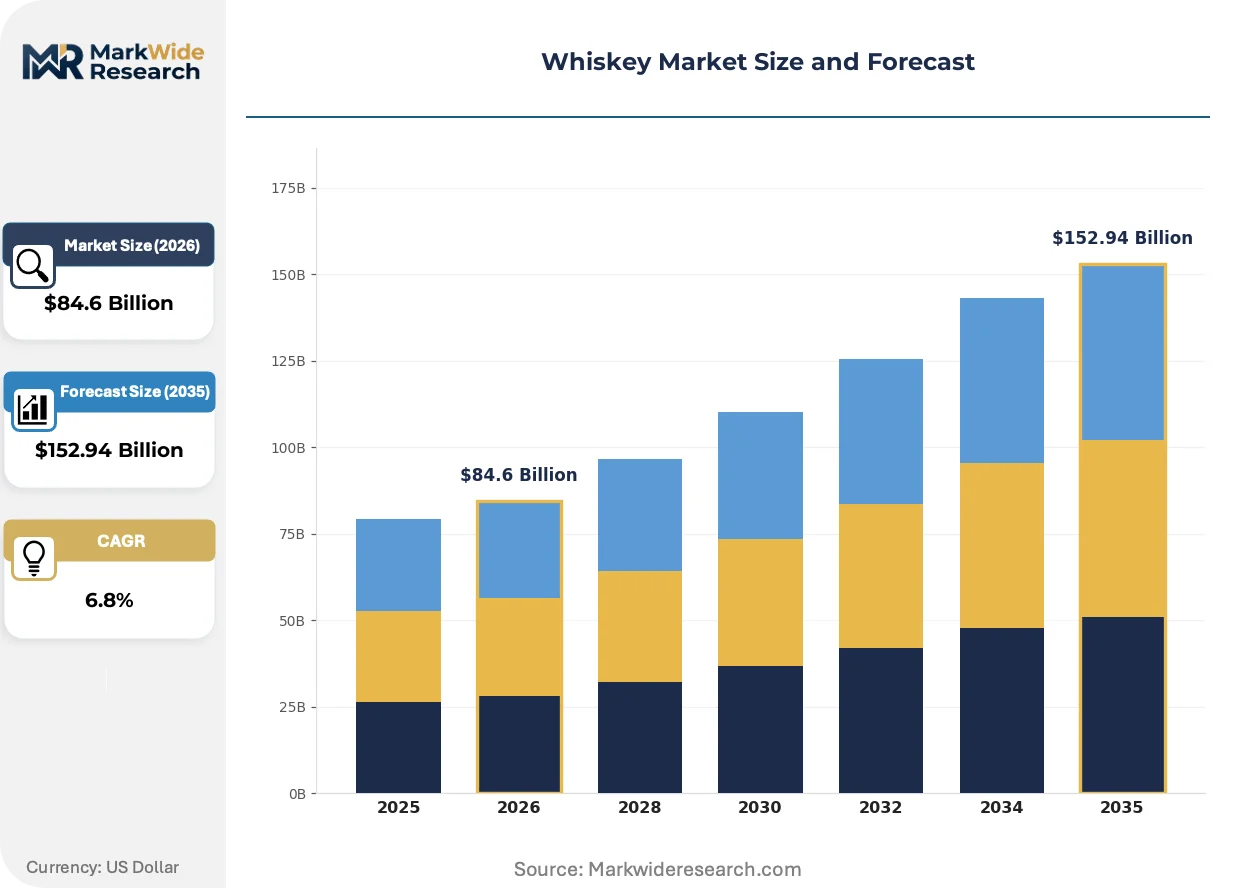
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Malt, Blended, Bourbon, Rye Age Statement: 6 Years, 12 Years, 18 Years, 21 Years Origin: Scotch, Irish, American, Japanese Packaging Type: Glass Bottle, Ceramic Bottle, Tetra Pack, Miniature Bottle |
| Companies Covered | Diageo, Pernod Ricard, Bacardi Limited, Brown-Forman, Suntory Global Spirits, William Grant & Sons, Constellation Brands, Sazerac Company, Heaven Hill Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whiskey Market Emerging Trajectories
Maturation science and packaging engineering are converging to reshape how whiskey moves from distillery to glass, compressing traditional timelines while elevating provenance signaling.
Precision cask management software is overtaking manual inventory tracking in large-scale operations. Scottish and Japanese distilleries deploy sensor-equipped warehouses to monitor angel's share loss and flavor compound extraction in real time. This granularity enables dynamic barrel relocation and earlier harvesting decisions, reducing capital tied up in underperforming stock.
The EU Green Deal's packaging waste directives are forcing glass weight reductions and recycled content minimums across export portfolios. Distillers reformulate bottle designs to maintain shelf presence with thinner walls, while compliance teams map supply chains to certify post-consumer recycled glass percentages. Premium segments face the steepest redesign costs given heritage bottle shapes and embossing requirements.
Collector behavior is fragmenting across digital auction platforms and private buying clubs, displacing traditional retail allocation models. Connoisseurs in Singapore, London, and New York now source rare expressions through blockchain-verified provenance systems rather than licensed merchants. This channel shift is concentrating price discovery power in platform operators and eroding distributor influence over scarcity marketing.
Whiskey Market Segmentation
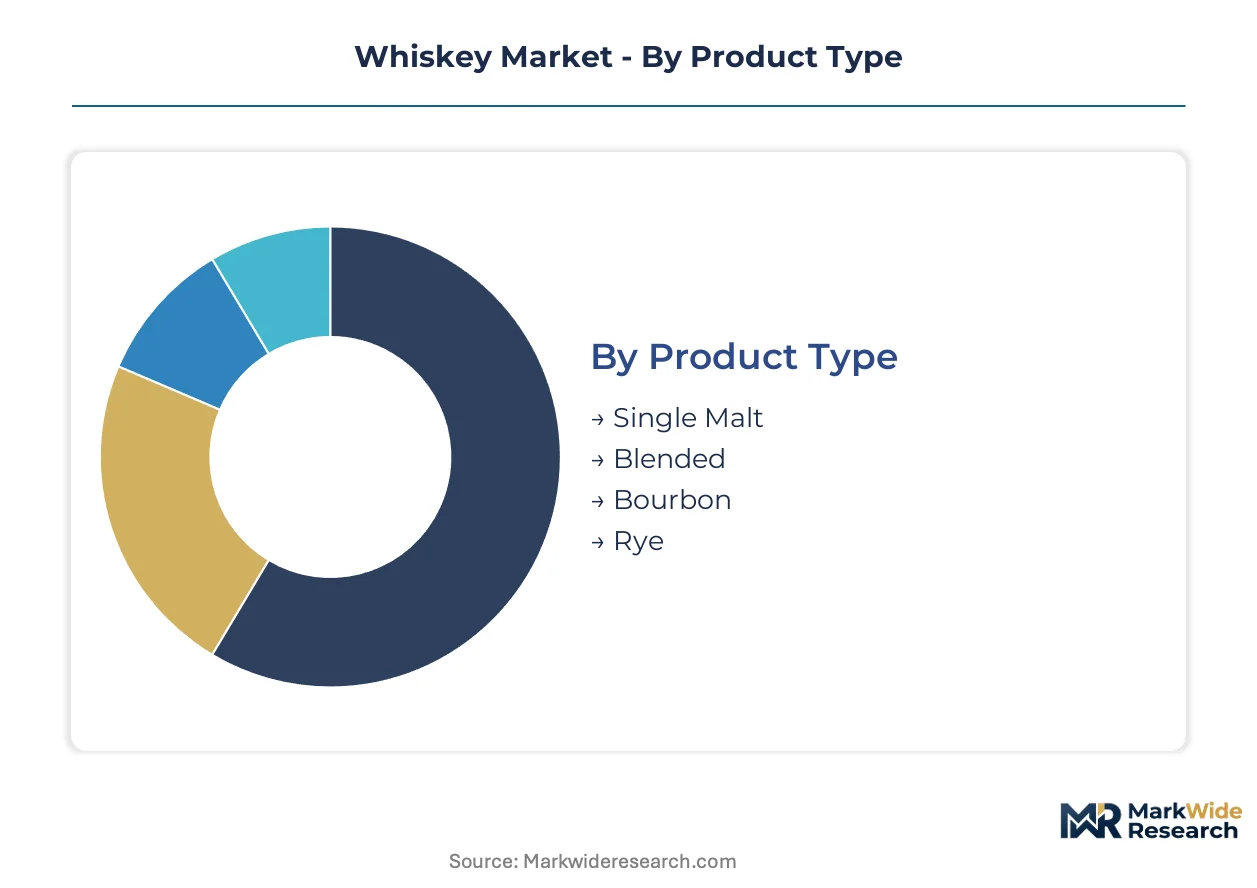
Whiskey segmentation reveals how maturation economics, geographic provenance laws, and packaging formats split consumer wallets across distinct occasion-based purchasing patterns. Producers configure portfolio depth against these axes to capture trade-up momentum while defending volume positions in accessible tiers.
Product Type:
Standardization dominates at volume tiers while customization intensifies toward collector segments, with grain bills and blending protocols varying sharply across price bands.
- Single Malt:Distilled from 100% malted barley at a single distillery, this category commands the widest price spreads between entry and ultra-premium tiers. Collector demand concentrates in Speyside and Islay expressions where distillery character functions as a scarcity signal.
- Blended:Combines malt and grain whiskies from multiple distilleries to achieve consistency at scale. Volume leadership rests with accessible price points in travel retail and standard hospitality channels across India and Brazil.
- Bourbon:American corn-dominant spirit aged in new charred oak barrels per TTB standards. Kentucky and Tennessee distilleries anchor supply, with export demand climbing in German and Japanese specialty retailers.
- Rye:Spicy grain-forward profile from minimum 51% rye mash bills. Pennsylvania and Maryland heritage recipes are experiencing revival as bartenders specify it for classic cocktail formulations.
Most installed capacity flows through Blended. Expansion is steepest in Single Malt.
Age Statement:
Maturation duration functions as the primary quality signal, with capital intensity escalating non-linearly beyond the 12-year threshold.
- 6 Years:Entry-tier positioning balancing flavor development against inventory carrying costs. Demand concentrates in price-sensitive markets where younger legal drinking age cohorts dominate consumption.
- 12 Years:Industry benchmark where oak influence peaks without excessive extraction. Scottish distilleries allocate the largest share of cask inventory to this band, serving both duty-free and domestic retail channels.
- 18 Years:Premium tier where angel's share losses exceed 40% in traditional dunnage warehouses. Japanese distilleries command outsized premiums here as supply constraints meet connoisseur recognition.
- 21 Years:Ultra-premium segment requiring multi-decade capital commitment. Collector markets in Singapore and London absorb limited releases through auction channels rather than licensed retail.
Twelve-year expressions carry the heaviest cask inventory allocation. Twenty-one-year releases are climbing the fastest as allocation models shift toward direct-to-collector channels.
Origin:
Geographic indication protections create regulatory moats that shape competitive access and pricing power across export markets.
- Scotch:Protected by UK and EU geographic indication laws requiring Scottish distillation and minimum three-year aging. EMA-aligned food safety standards govern additive restrictions affecting flavoring and coloring protocols.
- Irish:Triple-distilled tradition producing lighter mouthfeel, with production clustering in Cork and Dublin. American market share is expanding through bartender education programs emphasizing cocktail versatility.
- American:Bourbon and rye categories governed by TTB identity standards for grain composition and barrel treatment. Missouri cooperage supply bottlenecks are compressing new entrant expansion timelines.
- Japanese:Domestic distillery capacity constraints have created severe allocation scarcity for aged expressions. North American and European specialty retailers now receive sub-10% of requested stock for 18+ year releases.
Scottish distilleries hold the deepest aged stock reserves. Japanese origin expressions are gaining share fastest as distribution expands beyond domestic boundaries.
Packaging Type:
Format selection reflects channel economics and occasion-based consumption patterns, with sustainability mandates now penetrating premium tiers.
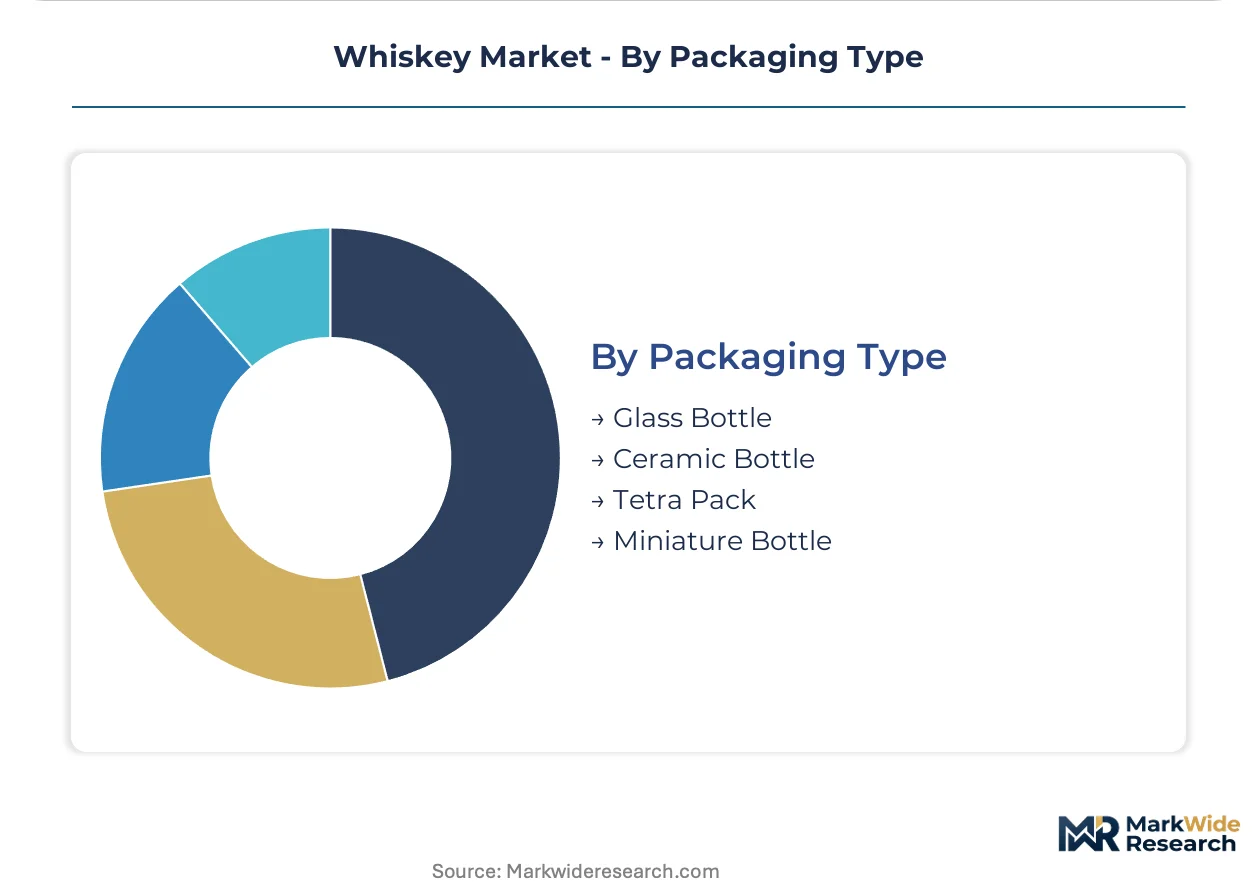
- Glass Bottle:Dominant format across all price tiers, with EU Green Deal directives pressing toward lighter weights and recycled content minimums. Heritage embossing requirements complicate compliance for established brands.
- Ceramic Bottle:Limited to gift and collector segments where perceived value justifies higher unit costs. Chinese and South Korean gifting occasions absorb the majority of ceramic-decanted ultra-premium releases.
- Tetra Pack:Entry-tier format for mixer-oriented consumption in price-sensitive emerging markets. Indian railways and budget hospitality channels represent primary demand concentration.
- Miniature Bottle:Single-serve format enabling trial before full-bottle commitment. Airport retail and hotel minibars across Dubai, London Heathrow, and Singapore Changi drive placement decisions.
Standard glass bottles carry the vast majority of volume throughput. Miniature formats are expanding most quickly as sampling economics reshape discovery patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scottish distilleries pioneered commercial whiskey production in the 18th century, establishing aging protocols and geographic indication frameworks that now govern trade across six continents. The industry's regional footprint reflects historical concentration in temperate barley belts and oak-rich cooperage zones, with regulatory divergence creating distinct competitive access patterns.
United States
Bourbon demand from German and Japanese specialty retailers is climbing steadily, while domestic cocktail culture drives rye whiskey revival. The TTB enforces strict identity standards for grain composition and new charred oak barrel requirements. Kentucky's Bluegrass region and Tennessee's Lincoln County anchor production, with Missouri cooperage bottlenecks compressing expansion timelines for new entrants.
Scotland
Collector demand concentrates in Speyside and Islay expressions where distillery character signals scarcity. UK and EU geographic indication laws mandate Scottish distillation and minimum three-year aging with additive restrictions. Aberdeenshire's malt supply faces harvest variability, squeezing consistency for Highland and Lowland distillers dependent on local barley belts.
Japan
Domestic distillery capacity constraints have created severe allocation scarcity for 18+ year expressions. METI oversees food safety standards affecting export certification and labeling protocols. Yamazaki and Hakushu facilities in Osaka and Yamanashi prefectures now direct sub-10% of requested aged stock to North American and European specialty retailers.
India
Proposed import tariff reductions on Scotch and Irish whiskey would unlock volume expansion in a 1.4 billion population market. The DGFT manages customs duties affecting competitive positioning against domestic malt spirits. Mumbai and Delhi retail channels absorb premium imported expressions while domestic distillers in Punjab and Karnataka defend volume tiers.
Ireland
American market share is expanding through bartender education programs emphasizing cocktail versatility. National food safety regulators govern additive restrictions affecting flavoring protocols for export. Cork and Dublin production clusters anchor triple-distilled tradition, with Midleton's cooperage supplying maturation capacity for multiple distillery operations.
Whiskey Market Vendor Landscape
The competitive structure tilts toward diversified spirits conglomerates with whiskey as a portfolio pillar rather than pure-play specialists. Consolidation among the top five producers controls the majority of aged stock reserves and distribution infrastructure across duty-free and domestic retail channels. Two strategic archetypes dominate: heritage-anchored American distillers leveraging barrel programs and visitor experiences, and family-owned Scottish operators commanding collector premiums through limited releases. Capacity expansion and direct-to-consumer channel development represent the dominant competitive moves, with distilleries bypassing traditional wholesale markups through subscription services and e-commerce platforms.
Within the conglomerate tier, Diageo and Pernod Ricard represent global distribution scale, while Brown-Forman exemplifies heritage-anchored American whiskey specialization. Suntory Global Spirits occupies a position bridging Japanese craft credibility with international expansion, and William Grant & Sons sits within the family-owned archetype emphasizing collector-oriented limited editions. These four names illustrate how geographic origin and ownership structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Diageo |
| Pernod Ricard |
| Bacardi Limited |
| Brown-Forman |
| Suntory Global Spirits |
| William Grant & Sons |
| Constellation Brands |
| Sazerac Company |
| Heaven Hill Brands |
| Others |
Supply Flow & Price Mechanics
EU Green Deal packaging mandates gate both qualified glass supply and premium-tier pricing access, as distillers reformulate bottle designs to maintain shelf presence with lighter weights while compliance teams certify post-consumer recycled content percentages. Buyers seeking heritage embossing and ultra-premium positioning face steeper redesign costs and extended supplier qualification timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by maturation duration and provenance signaling. Price differentiation rests on age-statement credibility and geographic indication protections, with 18+ year expressions commanding collector premiums. Cost compression in entry tiers is intensifying because climate volatility in Scottish barley belts squeezes malt supply consistency. Emerging market consumers exhibit highest price sensitivity, while Singapore and London collectors demonstrate lowest.
Supply Chain Analysis
Empty barrel returns and cask refurbishment flows sustain cooperage economics, with American white oak staves cycling through multiple char cycles before retirement. Supply concentrates in Missouri and Kentucky for new charred barrels, while Scottish dunnage warehouses draw from Spanish and Portuguese sherry cask networks. Single-source vulnerability in Missouri cooperage creates bottlenecks for bourbon producers. Distribution runs through duty-free channels, licensed retail, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Whiskey markets function as geographic-arbitrage plays where India's proposed import tariff reductions on Scotch and Irish whiskey would unlock volume expansion against domestic malt spirits pricing advantages.
For Market Incumbents: Extend aged stock accumulation programs to defend margin position against Japanese single malt allocation scarcity. Brown-Forman and Diageo should deepen barrel program investments in Kentucky and Tennessee. Vertical integration into Missouri cooperage insulates against new entrant expansion bottlenecks. Channel control through distillery subscription services captures margin previously lost to distributor tiers. For New Entrants and Emerging Players: Capture India's import tariff liberalization window before incumbent portfolio reallocation completes. The most penetrable segment lies in 12-year blended expressions for Mumbai and Delhi retail channels. A go-to-market angle emphasizing cocktail versatility for American rye revival targets bartender education programs. Cask-finished innovation bypasses capital intensity of extended aging while protecting margins. For Investors and Strategic Acquirers: Roll-up economics work for family-owned Scottish distilleries because METI export certification bottlenecks and TTB label approval backlogs create acquisition scarcity premiums for established aged-stock reserves. Long-term viability frames around climate-controlled warehousing technology shortening inventory cycles. The signal to watch is master distiller retirement waves outpacing apprenticeship pipelines across Scotland and Kentucky.| Strategic Initiative | Industry Significance |
|---|---|
| Barrel Program Expansion | Kentucky and Tennessee cooperage investments secure new charred oak supply against Missouri bottlenecks. |
| Direct-to-Consumer Launch | Distillery subscription services bypass traditional wholesale markups across North American and European markets. |
| Cask-Finished Innovation | Wine-barrel and alternative wood expressions offer margin protection without multi-decade aging commitments. |
| Climate-Controlled Warehousing | Precision humidity systems enable maturation acceleration, compressing inventory cycles for working capital efficiency. |
| Geographic Indication Defense | EU and UK geographic indication protections maintain pricing power against non-Scotch competitors in export markets. |
Methodological Framework
Bottom-up hospitality and retail channel modeling reconciled against top-down distillery capacity and aged-stock tracking forms the analytical core. Primary interviews with master distillers, cooperage procurement managers, duty-free retail buyers, and TTB regulatory affairs specialists combined with secondary validation from EMA additive restriction filings, EU Green Deal packaging directives, customs import records, and SEC spirits segment disclosures. Triangulation across these sources ensures coverage of both production constraints and demand-side trade-up patterns.
Input-output matrices map grain-to-glass flows across product type, age statement, origin geography, and packaging format dimensions. CAGRs derive from modeling price-volume elasticities by tier and channel mix shifts over the projection horizon. Industry-specific forecast inputs include angel's share loss curves by warehouse climate zone and collector auction price discovery trajectories through blockchain-verified provenance platforms.
Climate volatility in barley belts, TTB label approval timeline extensions, and Indian tariff policy reversals are the dominant revision risks. Practitioners should monitor harvest variability in Aberdeenshire and Cork, backlog fluctuations at the U.S. Alcohol and Tobacco Tax and Trade Bureau, and DGFT customs duty announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Alcoholic Flavors Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
Global Premium Alcoholic Beverage Market
Alcoholic Beverages
Spirits Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
Alcohol Enzymes Market
Alcoholic Beverages
Cordial Drink Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Cannabis Beverages Market
Alcoholic Beverages
Pisco Market
Alcoholic Beverages
Asia-Pacific Spirits Market