
 Bright Beer Tank Market | 2026-2036
Bright Beer Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Bright Beer Tank Market Analytics
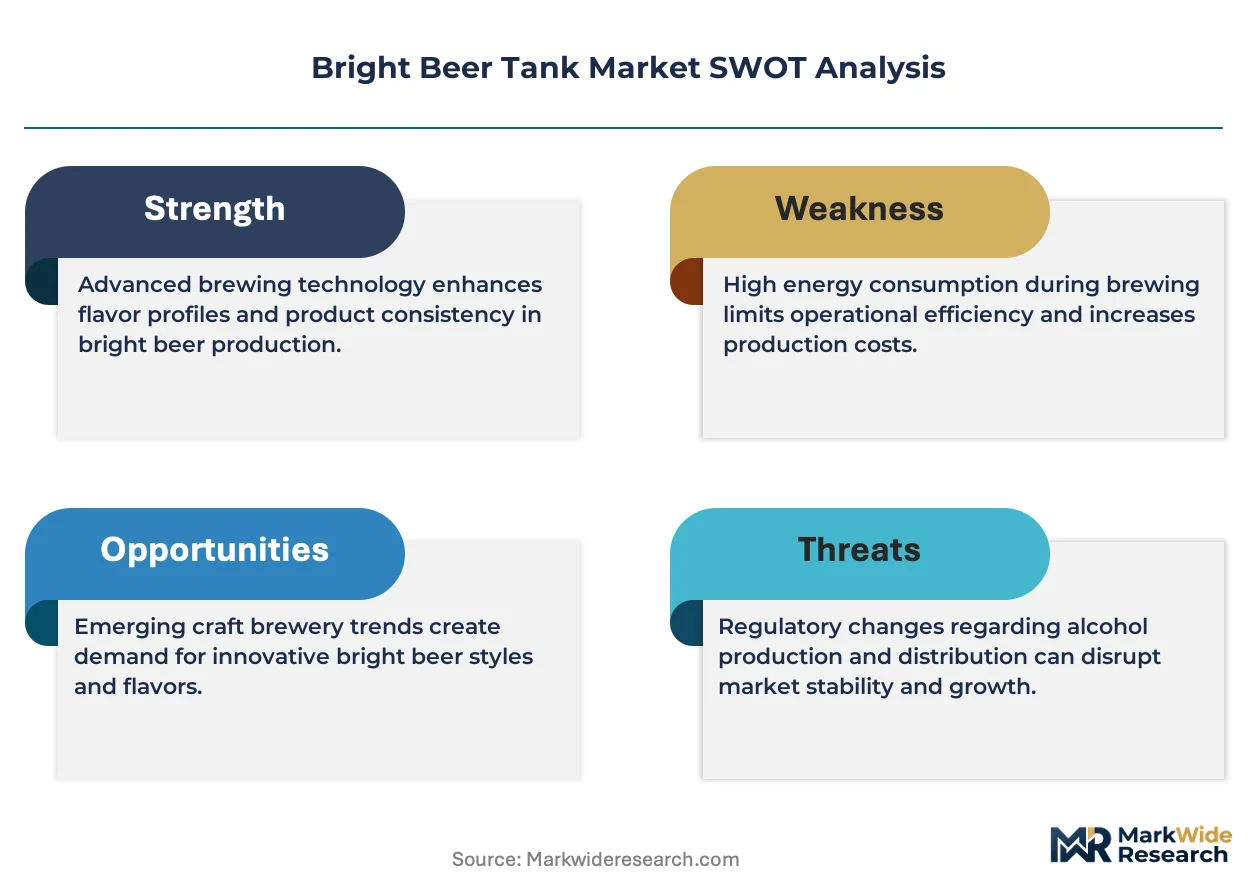
Preventive maintenance contracts and remote monitoring subscriptions is recalibrating how brewers procure bright beer tanks, shifting capital expenditure into operationalized service relationships. GEA leverages its digital brewing platform to extend lifecycle revenue beyond hardware sales. Krones anchors its position through integrated cellar logistics that bundle bright tanks with automated transfer systems. Ziemann competes on modular tank architectures that reduce installation downtime for expanding breweries.
A bright beer tank is a pressure-rated vessel, typically constructed from 304 or 316L stainless steel with polished internal surfaces below 0.8 micrometers Ra, designed to hold filtered beer at near-freezing temperatures while carbonation stabilizes prior to packaging. Horizontal tanks dominate microbrewery footprints where ceiling height constraints limit vertical installations, while insulated vertical configurations capture margin pools in commercial breweries running continuous conditioning cycles. Stainless steel material grades command preference over carbon steel due to corrosion resistance mandates in food-contact applications, though fiberglass options penetrate budget-sensitive brewpub segments.
Regulators including the FDA, EU food contact material frameworks under EFSA, and China's SAMR enforce surface finish, pressure vessel certification, and material migration limits that determine tank marketability across jurisdictions. Brewers in the United States face FDA Title 21 compliance for food-contact surfaces alongside ASME pressure vessel codes, while European suppliers navigate CE marking and updated F-Gas Regulation implications for jacketed cooling systems. Stakeholders must weigh regional certification burdens against modular platform strategies that simplify cross-border deployment.
Market Dynamics
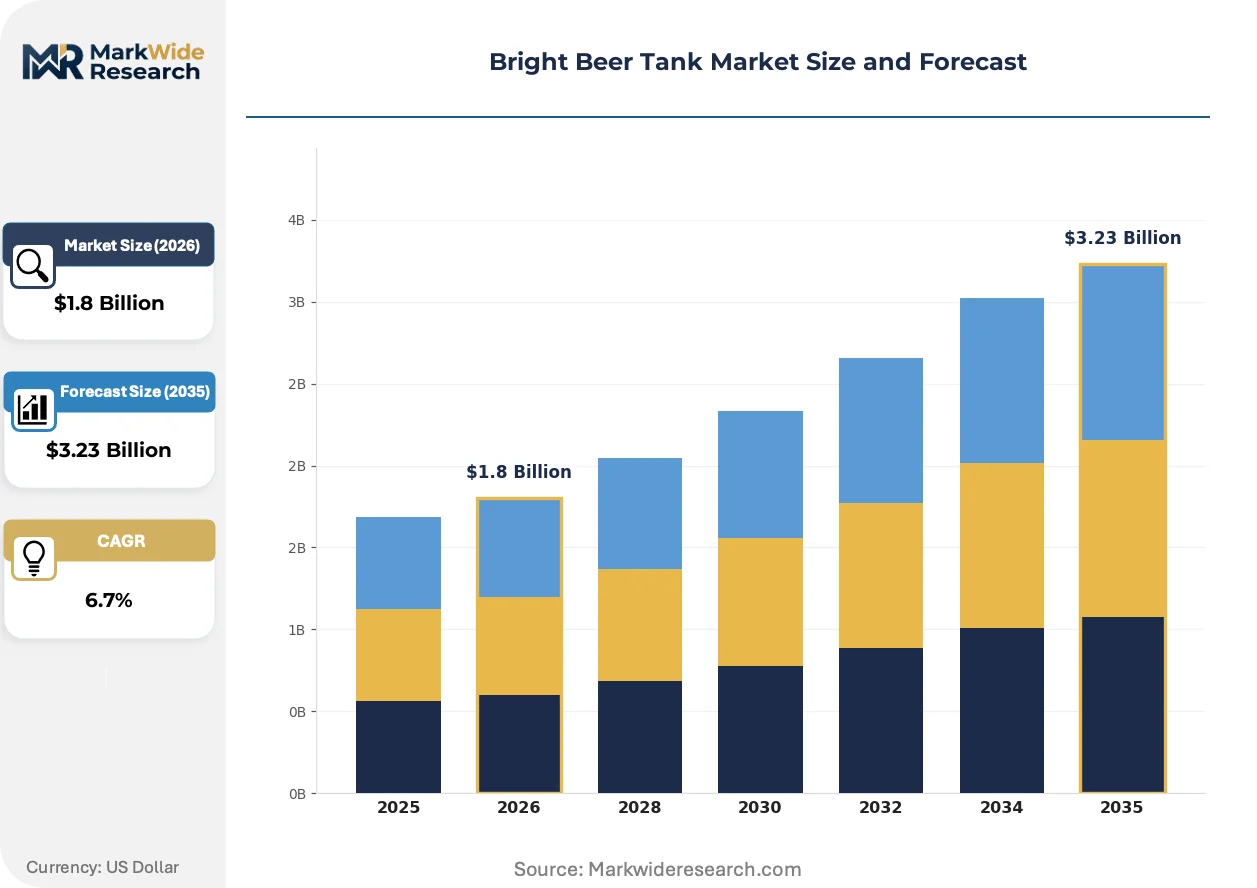
Preventive maintenance contracts and remote monitoring subscriptions are recalibrating how brewers procure bright beer tanks, shifting capital expenditure into operationalized service relationships that extend vendor lifecycle revenue beyond hardware sales.
Growth Catalysts
- EU Food Contact Material Regulations:Craft breweries across Germany and the Czech Republic are expanding bright tank fleets to meet lager conditioning standards under EFSA frameworks, creating replacement demand for certified stainless steel vessels.
- Remote Monitoring Platforms:IoT-enabled pressure and temperature sensors allow brewers to optimize carbonation cycles and reduce product loss, accelerating adoption among mid-scale commercial operations.
- Brazil and Mexico Demand Concentration:Stainless steel vertical tank configurations are capturing volume in Latin American markets where commercial brewery capacity expansions outpace microbrewery growth.
Market Restraints
- Nickel Price Volatility:304 and 316L stainless steel grades depend on nickel alloy inputs, exposing tank manufacturers to commodity cost swings that compress margin on fixed-price contracts.
- Pressure Vessel Certification Burden:ASME code compliance in the United States and CE marking requirements in Europe impose multi-month approval timelines that delay revenue recognition for custom tank orders.
- Fiberglass Substitution Threat:Budget-sensitive brewpub segments in emerging markets increasingly specify fiberglass tanks for non-critical conditioning stages, eroding addressable volume for stainless steel suppliers.
Strategic Opportunities
- Modular Tank Architectures:Field-expandable vessel designs reduce installation downtime for expanding breweries, creating differentiation against fixed-capacity competitors.
- F-Gas Regulation Tailwinds:Updated EU F-Gas Regulation implications for jacketed cooling systems are accelerating replacement cycles in European cellars, opening retrofit service revenue streams.
- Automated Transfer System Convergence:Integration of bright tanks with robotic cellar logistics creates bundled solution opportunities for vendors with in-house automation capabilities.
Industry Challenges
- Surface Finish Certification Talent Gap:Brewers and inspectors face shortages of technicians qualified to validate sub-0.8 micrometer Ra internal surface specifications required by FDA Title 21 and EFSA frameworks.
- Legacy Cooling System Integration:Jacketed bright tanks must interface with existing glycol infrastructure, creating engineering complexity that extends commissioning timelines and strains project management resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bright Beer Tank Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Tanks, Vertical Tanks, Insulated Tanks, Non-Insulated Tanks Material: Stainless Steel, Carbon Steel, Plastic, Fiberglass Capacity: 100-500 Liters, 500-1000 Liters, 1000-5000 Liters, Above 5000 Liters End User: Microbreweries, Craft Breweries, Commercial Breweries, Brewpubs |
| Companies Covered | Mueller, GEA, Krones, Paul Mueller Company, Ziemann, GW Kent, Briggs, Criveller, Wenzhou Deli Machinery Equipment Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bright Beer Tank Market Evolving Landscape
Digital brewing platforms are converging with hardware sales to create continuous revenue streams, while regulatory pressure on cooling systems and evolving procurement models reshape competitive positioning across vessel categories.
IoT-enabled fermentation monitoring is converging with predictive analytics to transform how breweries manage conditioning cycles. Mid-scale commercial operations in Germany and the Czech Republic are deploying these systems at accelerating pace. This technology convergence is compressing the acceptable response window for carbonation deviations, forcing tank suppliers to bundle sensor packages or lose specification battles.
The EU F-Gas Regulation is tightening compliance requirements for jacketed cooling systems in bright beer tanks, mandating lower-global-warming-potential refrigerants and leak detection protocols. European suppliers face accelerated redesign cycles to maintain CE marking eligibility. Commercial breweries running continuous conditioning cycles are absorbing premium pricing for compliant systems rather than risking operational shutdowns.
Service unbundling is fragmenting traditional tank procurement patterns. Brazilian and Mexican mid-scale breweries are separating hardware purchases from installation and maintenance contracts, creating openings for specialized service providers. This behavioral shift is most visible in Latin American markets where capital constraints favor operational expenditure structures over upfront vessel ownership.
Bright Beer Tank Market Segmentation
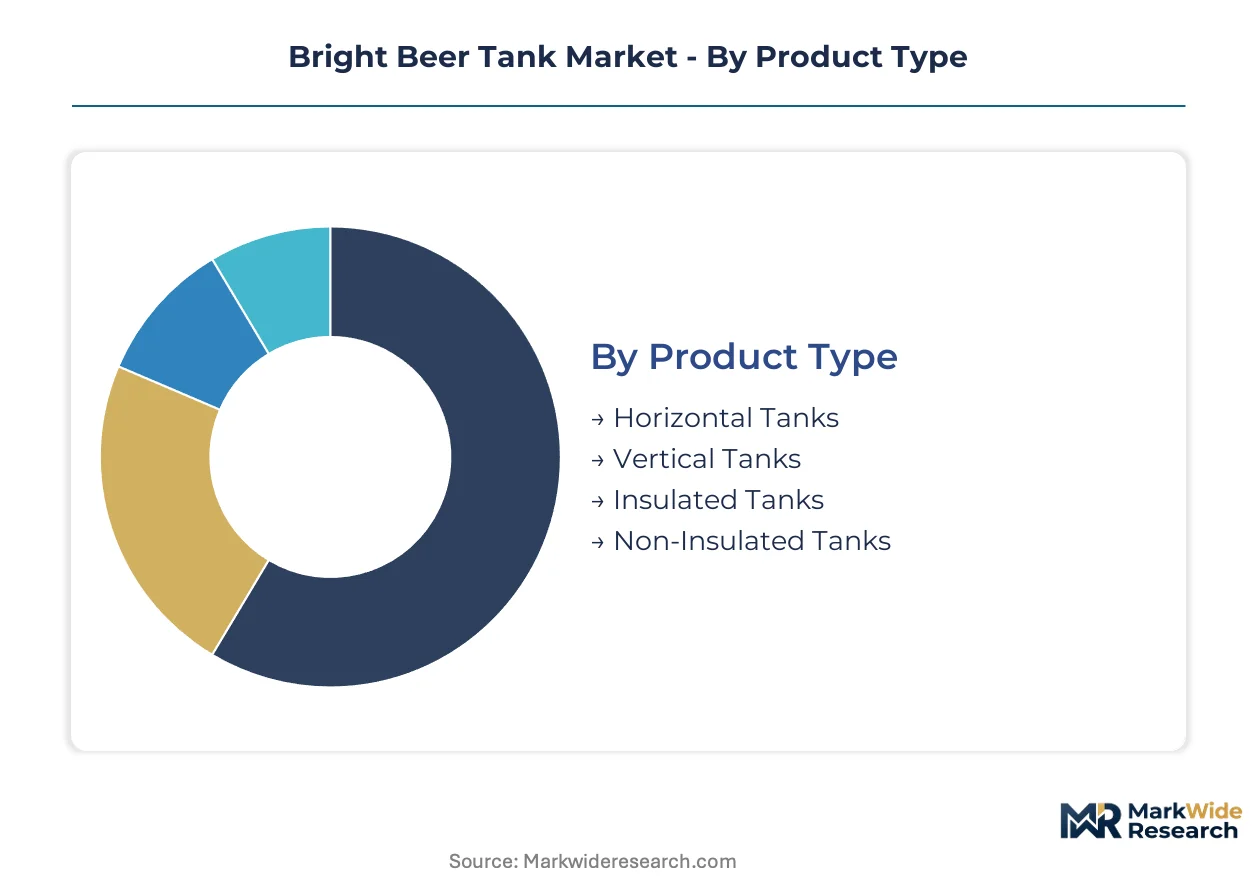
Bright beer tank procurement patterns diverge sharply across vessel geometry, material grade, and operational scale. Upgrade cycles for pressure-rated conditioning equipment now favor modular configurations that minimize installation downtime during cellar expansions.
Product Type:
Replacement demand concentrates in configurations that reduce footprint constraints while maintaining carbonation stability during extended conditioning cycles.
- Horizontal Tanks:Low-profile cylindrical vessels optimize floor space utilization in facilities with ceiling height restrictions below four meters. Microbreweries across Germany and the Czech Republic specify horizontal geometries to maximize tank count within existing cellar footprints while meeting EFSA food contact surface requirements.
- Vertical Tanks:Upright cylindrical configurations with conical or dished bottoms enable gravity-assisted transfer operations and superior thermal stratification control. Commercial breweries in Brazil and Mexico prioritize vertical tanks for continuous conditioning cycles where jacketed cooling efficiency determines throughput economics.
- Insulated Tanks:Polyurethane-foam-jacketed vessels maintain temperature stability within 0.5°C variance for extended lagering periods.
- Non-Insulated Tanks:Bare-metal configurations serve ambient-temperature holding applications or climate-controlled cellars where external insulation adds unnecessary capital burden.
Vertical tanks sit at the top of the volume ranking, with horizontal tanks climbing the fastest among retrofit-oriented microbrewery operators.
Material:
Surface finish certification requirements under FDA Title 21 and EFSA frameworks are concentrating procurement toward corrosion-resistant grades that validate sub-0.8 micrometer Ra specifications.
- Stainless Steel:304 and 316L austenitic grades dominate pressure-rated applications with polished internal surfaces below 0.8 micrometers Ra. Craft breweries across Germany and the Czech Republic mandate 316L for chloride-bearing cleaning chemistries, absorbing nickel alloy premiums to secure regulatory compliance.
- Carbon Steel:Epoxy-lined carbon vessels serve non-critical holding stages where food-contact exposure is limited and capital constraints predominate.
- Plastic:High-density polyethylene tanks penetrate budget-sensitive brewpub segments for low-pressure conditioning or temporary holding.
- Fiberglass:Composite vessels with food-grade resin barriers capture emerging market volume where stainless steel costs exclude mid-scale commercial entrants.
Stainless steel commands the dominant revenue share, with fiberglass expanding most quickly in price-sensitive Latin American brewpub installations.
Capacity:
Batch size standardization across commercial brewing operations is driving convergence toward vessel sizes that match filtration train outputs and packaging line speeds.
- 100-500 Liters:Pilot-scale vessels support recipe development and seasonal specialty production with minimal capital commitment.
- 500-1000 Liters:Mid-scale configurations bridge microbrewery and commercial production thresholds.
- 1000-5000 Liters:Standard commercial conditioning volumes align with 50-200 hectoliter brewhouse outputs. Brazilian and Mexican commercial breweries concentrate procurement in this bracket to match automated transfer system capacities while maintaining buffer stock for packaging flexibility.
- Above 5000 Liters:Industrial-scale horizontal and vertical tanks serve high-volume lager producers with continuous conditioning requirements. German commercial breweries deploy these vessels for extended cold maturation cycles under strict EFSA temperature logging protocols.
1000-5000 liter vessels anchor volume rankings, with above-5000 liter tanks gaining share fastest among capacity-expanding Latin American operators.
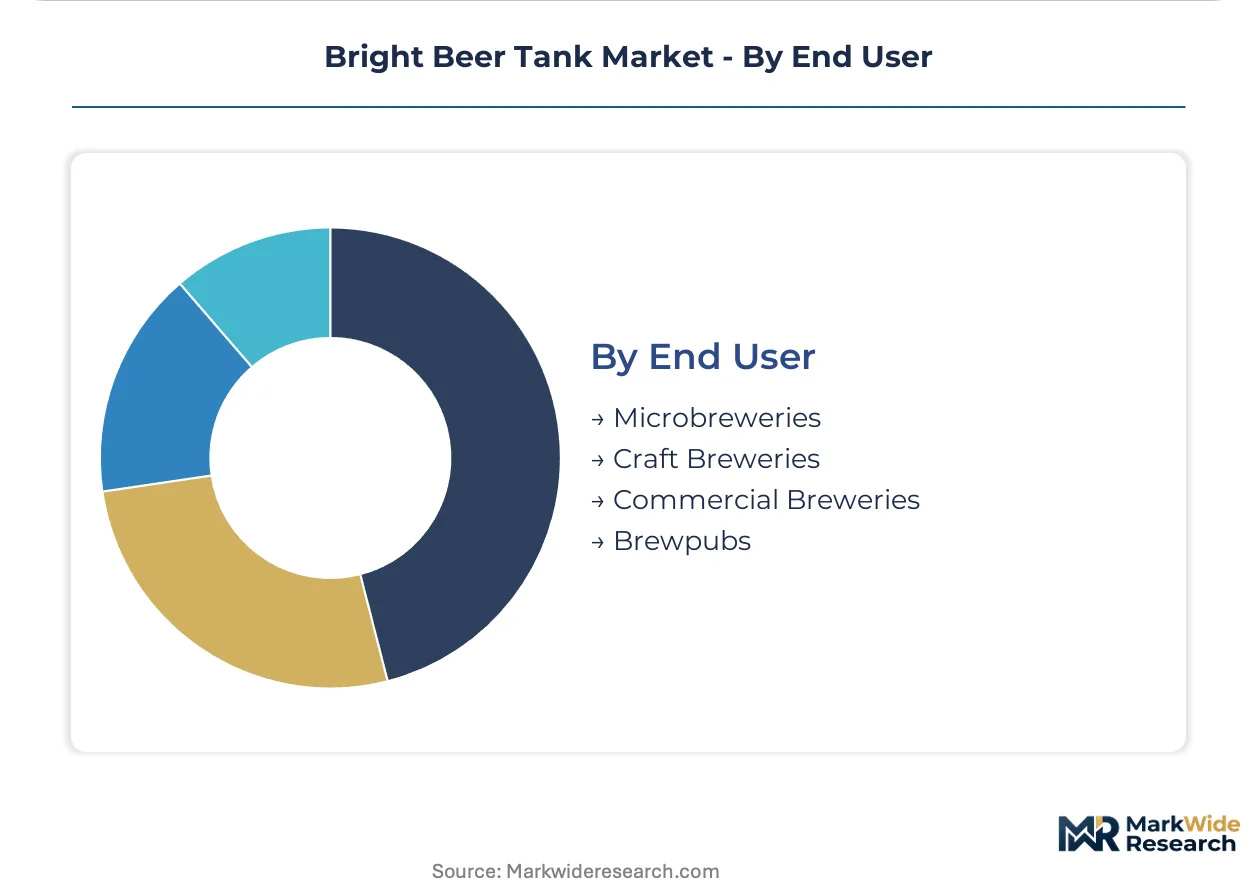
End User:
Procurement sophistication varies dramatically across brewery scale, from specification-heavy commercial operations to price-driven brewpub entrants.
- Microbreweries:Small-scale producers below 5,000 hectoliters annual output prioritize horizontal tanks and modular vertical configurations that accommodate irregular production schedules. German microbreweries are retrofitting IoT-enabled pressure sensors to optimize carbonation cycles and reduce product loss during conditioning.
- Craft Breweries:Mid-scale regional producers balance quality certification with capacity flexibility. Czech craft breweries are expanding bright tank fleets specifically to achieve lager conditioning standards under updated EU food contact material regulations.
- Commercial Breweries:High-volume producers above 50,000 hectoliters demand integrated cellar logistics with automated transfer systems.
- Brewpubs:On-premise production facilities with direct retail service specify compact horizontal tanks or budget fiberglass alternatives where visual tank presentation matters less than capital efficiency.
Commercial breweries generate the highest absolute volume, with craft breweries showing the steepest expansion trajectory as EFSA compliance deadlines accelerate fleet replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany conditions more lager volume than the United States, yet Brazil and Mexico are expanding commercial tank fleets faster as craft brewing formalizes across Latin America.
Germany
Bavarian commercial breweries drive replacement demand for jacketed vertical tanks under updated EU F-Gas Regulation mandates. EFSA food contact material frameworks require sub-0.8 micrometer Ra surface certification, accelerating stainless steel 316L procurement. Munich and Stuttgart industrial clusters host retrofit programs linking IoT sensors to existing cellar infrastructure.
United States
Microbreweries in Pacific Northwest and Colorado prioritize horizontal tank geometries for ceiling-constrained urban facilities. FDA Title 21 compliance for food-contact surfaces operates alongside ASME pressure vessel codes, extending custom order timelines. Portland and Denver brewing districts concentrate specification-heavy procurement for extended cold maturation cycles.
Brazil
Commercial breweries in São Paulo and Minas Gerais states scale 1000-5000 liter vertical tank installations to match automated transfer system capacities. ANVISA pharmaceutical-grade fabrication standards are migrating into food equipment certification, favoring documented surface finish protocols. Campinas industrial corridor anchors stainless steel vessel assembly for mid-scale operators separating hardware from service contracts.
Mexico
Bajío Region and Mexico City Metro brewing operations concentrate demand for insulated vertical configurations serving continuous conditioning cycles. Pressure vessel import regulations align with ASME code recognition, streamlining cross-border procurement from US fabricators. Querétaro and Guadalajara production zones exhibit fastest capacity expansion for lager conditioning infrastructure.
Czech Republic
Plzeň and Prague brewing clusters expand bright tank fleets specifically to achieve traditional lager conditioning standards under EFSA migration limit enforcement. Craft breweries below 5000 hectoliters annual output retrofit horizontal modular systems for irregular production schedules. Brno equipment fabricators supply field-expandable architectures reducing installation downtime.
Bright Beer Tank Market Competitive Landscape
Top-tier vendors anchor integrated cellar logistics, while mid-scale specialists compete on modular architectures and regional fabrication proximity. The vendor base stratifies across three tiers: multinational brewing technology platforms bundling automation, regional stainless steel fabricators with pressure vessel certification depth, and emerging-market specialists serving price-sensitive brewpub segments. Competitive moves concentrate on M&A to acquire digital brewing capabilities and geographic expansion into Latin American growth corridors.
Among German-based brewing technology platforms, GEA, Krones, and Ziemann occupy positions spanning integrated automation to modular vessel design. GEA exemplifies the digital convergence archetype through lifecycle service platforms. Krones anchors bundled cellar logistics positioning. Ziemann represents modular architecture specialization for field-expandable installations. Chinese fabricators including Wenzhou Deli Machinery Equipment Co., Ltd. compete on proximity to Asia-Pacific cost-sensitive demand. US-based Mueller and Paul Mueller Company anchor North American pressure vessel certification depth for FDA-compliant surface finish specifications.
| Leading Market Players |
|---|
| Mueller |
| GEA |
| Krones |
| Paul Mueller Company |
| Ziemann |
| GW Kent |
| Briggs |
| Criveller |
| Wenzhou Deli Machinery Equipment Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Skilled pressure vessel welders concentrated in Bavaria and the Czech industrial corridor create labor-cost differentials that widen pricing-tier spreads between European-fabricated 316L stainless steel tanks and Asian-sourced alternatives. Certification-validated surface finishing expertise anchors premium pricing for EFSA-compliant vessels while budget-sensitive Latin American buyers absorb longer lead times for lower-cost options.
Pricing Analysis
Capacity additions in Chinese stainless steel fabrication zones are reshaping price floors for standard-grade bright beer tanks. Three-tier pricing structure across premium, standard, and economy levels separates 316L EFSA-certified European vessels from 304-grade mid-tier options and fiberglass economy alternatives. Price differentiation hinges on surface finish certification depth and after-sales service bundling. Cost compression in the economy tier is intensifying because Brazilian brewpubs unbundle installation contracts to favor operational expenditure structures. Microbreweries in Germany exhibit lowest price sensitivity due to regulatory compliance mandates, while emerging-market brewpubs drive hardest bargain negotiations.
Supply Chain Analysis
Refurbishment flows for jacketed cooling systems create secondary supply channels that extend vessel lifecycle economics and dampen replacement demand spikes. Manufacturing concentrates in Germany, China, and the United States, with Czech fabricators serving regional European demand. Raw material inputs draw from nickel alloy suppliers in Indonesia and Russia, polished steel sheet producers in Japan and South Korea, and polyurethane insulation foam from German chemical specialists. Single-source vulnerability in nickel supply chains exposes fabricators to commodity cost swings that compress margins on fixed-price contracts. Distribution runs through direct OEM sales for large commercial breweries and specialized brewing equipment distributors serving microbrewery segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EFSA compliance costs in Germany and the Czech Republic diverge from ANVISA-aligned certification pathways in Brazil, creating margin expansion opportunities for vendors with dual-qualification capabilities.
For Market Incumbents: Deepen vertical integration into nickel alloy sourcing to defend margin position against commodity volatility. Secure exclusive distribution agreements with Campinas and Querétaro industrial corridors to lock out Chinese competitors from Latin American growth corridors. Invest in IoT-enabled predictive maintenance platforms to convert hardware sales into recurring service revenue streams that fiberglass substitutes cannot replicate. For New Entrants and Emerging Players: The 40-60% price-point gap between premium 316L European vessels and economy fiberglass alternatives opens white-space targeting for mid-tier 304-grade modular systems. Brazilian mid-scale commercial breweries separating hardware from service contracts represent the most penetrable buyer segment. Enter through field-expandable tank architectures that reduce installation downtime during cellar expansions, winning specification battles against fixed-capacity incumbents. For Investors and Strategic Acquirers: Brewing technology platforms with integrated automation capabilities are the most active acquirer in this space, seeking digital brewing competencies to extend lifecycle revenue beyond vessel sales. Long-term viability favors vendors bundling bright tanks with robotic cellar logistics and predictive analytics platforms. Acquisition target archetype: regional stainless steel fabricators with pressure vessel certification depth but lacking digital service infrastructure. Monitor F-Gas Regulation compliance deadlines across European cellars as inflection indicator for accelerated replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Tank Architecture Development | Field-expandable designs reduce installation downtime for expanding German and Czech breweries. |
| IoT Sensor Platform Integration | Predictive analytics capabilities transform carbonation cycle management for mid-scale commercial operators. |
| Backward Integration into Nickel Sourcing | Captive alloy supply hedges margin compression from commodity price volatility in 304 and 316L grades. |
| F-Gas Compliance System Redesign | Lower-global-warming-potential refrigerant migration secures CE marking eligibility for European jacketed cooling systems. |
| Automated Transfer System Bundling | Robotic cellar logistics integration creates differentiated solution offerings for high-volume commercial breweries. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with brewery operations directors, pressure vessel fabrication engineers, cellar logistics specialists, and aftermarket service heads with secondary validation. Primary fieldwork engaged procurement managers at commercial breweries in São Paulo and Minas Gerais, technical directors at Munich and Stuttgart industrial clusters, and regulatory compliance officers navigating EFSA and FDA frameworks. Secondary sources included ASME boiler and pressure vessel code filings, EU F-Gas Regulation implementation guidance, ANVISA pharmaceutical-grade equipment standards migrating into food applications, and trade flow data for stainless steel vessel exports. Bottom-up tank installation tracking and top-down brewery capacity expansion analysis were triangulated against vendor shipment disclosures.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning vessel geometry, material grade, capacity tier, and end-user scale. The analytical framework modeled replacement cycles for jacketed cooling systems under evolving regulatory compliance deadlines, procurement pattern shifts from capital expenditure to operationalized service relationships, and geographic expansion corridors in Latin American commercial brewing. CAGRs were derived from installed base growth rates, fleet replacement timing, and penetration assumptions for IoT-enabled monitoring platforms. Industry-specific forecast inputs included nickel alloy price trajectory scenarios and EFSA surface finish certification enforcement timelines.
Caveats apply where nickel price volatility, regulatory approval delays for custom pressure vessels, or accelerated fiberglass substitution in emerging markets could materially shift the outlook. Forecasts reflect documented assumptions about brewery capacity expansion rates, compliance deadline adherence, and service unbundling behavioral persistence. Practitioners should monitor F-Gas Regulation implementation progress, ANVISA certification standard migrations, and Brazilian brewpub procurement pattern evolution for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Canada Wine Coolers Market
Alcoholic Beverages
Wine Filtering Machine Market
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
Bahrain Alcoholic Beverages Market
Alcoholic Beverages
US Wine Cooler Market
Alcoholic Beverages
Cider Market
Alcoholic Beverages
United States Beer Market
Alcoholic Beverages
Global Shortenings Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Instant Wine Chillers and Refreshers Market
Alcoholic Beverages
Canned Cocktails Market
Alcoholic Beverages
Rice Wine Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
Distillers Malt Market