
 GCC Fruits and Vegetables Market | 2026-2036
GCC Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Fruits and Vegetables Market Foresight
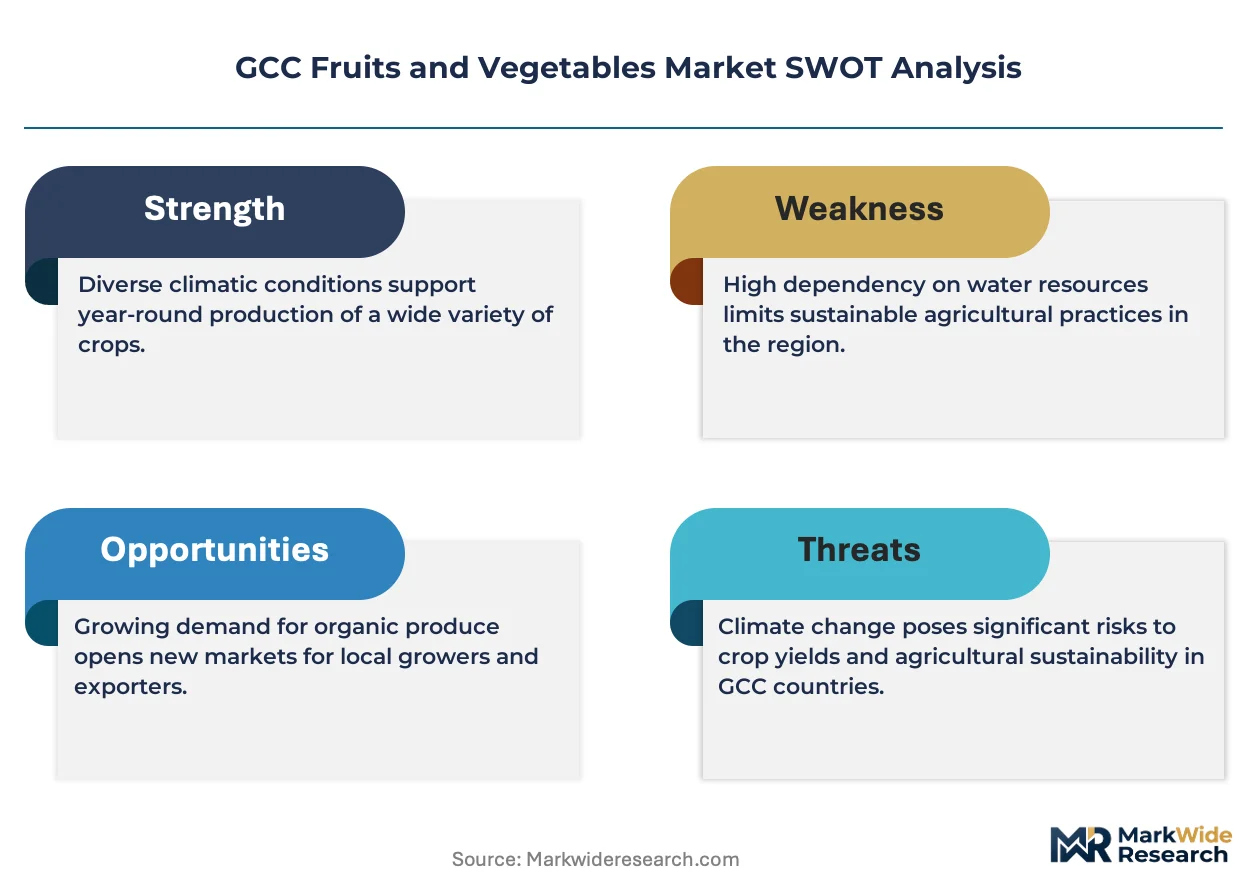
Premium-grade produce certification is reorganizing procurement standards across GCC retail channels. Pure Harvest Smart Farms leverages advanced hydroponic and vertical farming systems to supply pesticide-free tomatoes and leafy greens year-round in the UAE climate. Al Dahra Agriculture anchors large-scale import and domestic cultivation networks across multiple Gulf states. Lulu Group competes through integrated sourcing from its own farms and exclusive supplier agreements across the region.
GCC fruits and vegetables encompass fresh and minimally processed plant products sold for direct consumption, food manufacturing, and hospitality use, with critical quality parameters including Brix levels, shelf-life extension through modified atmosphere packaging, and compliance with halal-handling protocols throughout the supply chain. The product category serves food security objectives, tourism-driven foodservice expansion, and export reprocessing hubs. Citrus fruits and leafy vegetables command disproportionate investment in controlled-environment agriculture due to their perishability and import dependency. The foodservice application segment draws expanding share as Saudi Vision 2030 and Qatar's tourism infrastructure drive restaurant and hotel construction. Wholesale suppliers retain dominant volume flow, though online retailers capture accelerating share among urban households seeking subscription-based delivery.
Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology enforce pesticide maximum residue limits and labeling requirements that determine market access for imported and domestic produce. The UAE's technical regulations for organic certification and Saudi Arabia's Sustainable Agriculture Rural Development Program shape investment incentives toward soilless farming and water-efficient cultivation. Stakeholders must monitor evolving import-substitution targets and water tariff reforms that will determine the economic viability of domestic production versus seaborne supply from India, Egypt, and East Africa.
Market Dynamics
Controlled-environment agriculture is decomposing the GCC's historical dependence on seaborne imports from India and Egypt, as water-scarcity economics and residue-limit enforcement by MOHAP and SFDA tilt procurement toward domestic soilless cultivation.
Growth Catalysts
- Saudi Vision 2030 food security targets:The kingdom's localization mandates require hospitality and retail sectors to source increasing volumes from domestic farms, redirecting procurement budgets toward Riyadh-based controlled-environment producers.
- MOHAP pesticide residue limits:Tightened maximum residue limits on imported leafy greens are disqualifying traditional Egyptian and Indian suppliers, creating market access for UAE-based hydroponic operators with certified residue-free output.
- Qatar's tourism infrastructure buildout:Hotel and restaurant construction ahead of recurring mega-events is expanding foodservice procurement volumes, with operators demanding year-round supply consistency that favors local greenhouse production over seasonal imports.
Market Restraints
- Desalinated water cost volatility:Soilless cultivation in the UAE and Saudi Arabia depends on energy-intensive desalination, making domestic production margins vulnerable to electricity tariff fluctuations and carbon pricing mechanisms.
- Single-source import concentration:Egypt's Nile Delta and India's Maharashtra corridor still supply over half of GCC citrus and onion volumes, exposing buyers to Suez Canal disruption risks and Indian monsoon variability.
- Halal-handling certification friction:Cross-border shipments from non-Muslim majority origins face extended inspection timelines at Jebel Ali and King Abdulaziz Port, compressing shelf-life for perishable consignments.
Strategic Opportunities
- Oman and Bahrain penetration:These markets lack domestic controlled-environment capacity, creating first-mover advantage for UAE-based operators with cross-border logistics networks and MOHAP-equivalent certification.
- Subscription-based home delivery channels:Urban households in Dubai and Riyadh are adopting weekly produce box services, bypassing wholesale markets and capturing margin that traditionally flowed to retail intermediaries.
- Saudi Sustainable Agriculture Rural Development Program:Subsidies for greenhouse construction and drip irrigation in Qassim and Asir provinces are lowering capital barriers for domestic entrants targeting import substitution.
Industry Challenges
- Agritech engineering talent scarcity:Climate control systems and nutrient solution management require specialized expertise that GCC universities have not scaled to match greenhouse construction timelines.
- Organic certification timeline compression:SFDA and Emirates Authority for Standardization and Metrology require multi-year field history documentation that delays revenue generation for new soilless entrants claiming organic status.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Fruits and Vegetables Market |
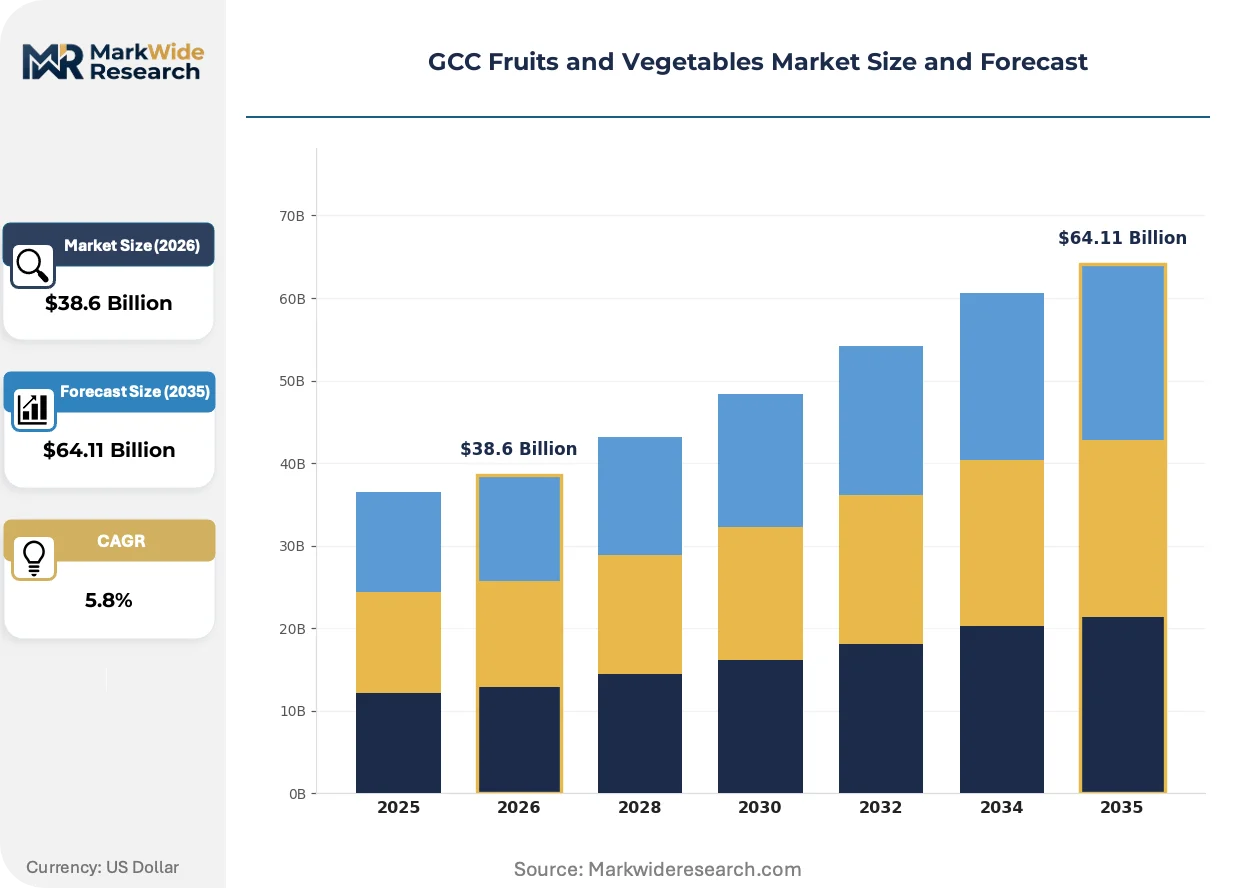
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus Fruits, Leafy Vegetables, Root Crops, Stone Fruits, Tropical Fruits Application: Fresh Consumption, Processing, Export, Foodservice Industry, Retail Packaging Distribution Channel: Supermarkets, Local Markets, Online Retailers, Wholesale Suppliers, Hypermarkets Customer Type: Households, Food Processors, Hospitality Chains, Institutional Buyers, Exporters |
| Companies Covered | Al Ghurair Foods, Al Foah (Agthia Group), Pure Harvest Smart Farms, Carrefour GCC, Lulu Group, Elite Agro, Fresh Fruits Company, Spinneys Dubai LLC, Al Dahra Agriculture, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Fruits and Vegetables Market Shifts & Advancements
Technology convergence and regulatory stringency are compressing traditional supply chain layers, with automation and certification requirements favoring capital-intensive operators over fragmented import traders.
Vertical farming infrastructure is decomposing the seasonal import calendar that historically structured GCC produce procurement. Hydroponic towers and containerized growing systems in Dubai Industrial City and Riyadh's Sudair Industrial City enable year-round harvests of leafy greens and herbs regardless of external climate conditions. Hotel chains and airline caterers are contracting directly with these facilities, eliminating the 7-10 day ocean freight window that degraded product quality.
SFDA's alignment with Codex Alimentarius maximum residue limits is forcing reformulation of pest management protocols across supplier bases. Egyptian and Indian export farms face escalating rejection rates at Saudi ports for exceeding chlorpyrifos and dimethoate thresholds, redirecting volume toward Jordanian and Omani origins with established compliance documentation. Domestic UAE producers with integrated biological pest control are capturing price premiums in this tightened regulatory environment.
Foodservice buyers are consolidating procurement through centralized purchasing cooperatives rather than fragmented spot-market sourcing. Hospital and university cafeteria networks in Abu Dhabi and Jeddah are pooling demand to secure volume commitments from greenhouse operators, replacing the traditional souk-based purchasing that dominated institutional catering. This concentration is visible most acutely in the healthcare and education verticals, where food safety audit requirements favor suppliers with traceability systems.
GCC Fruits and Vegetables Market Segmentation
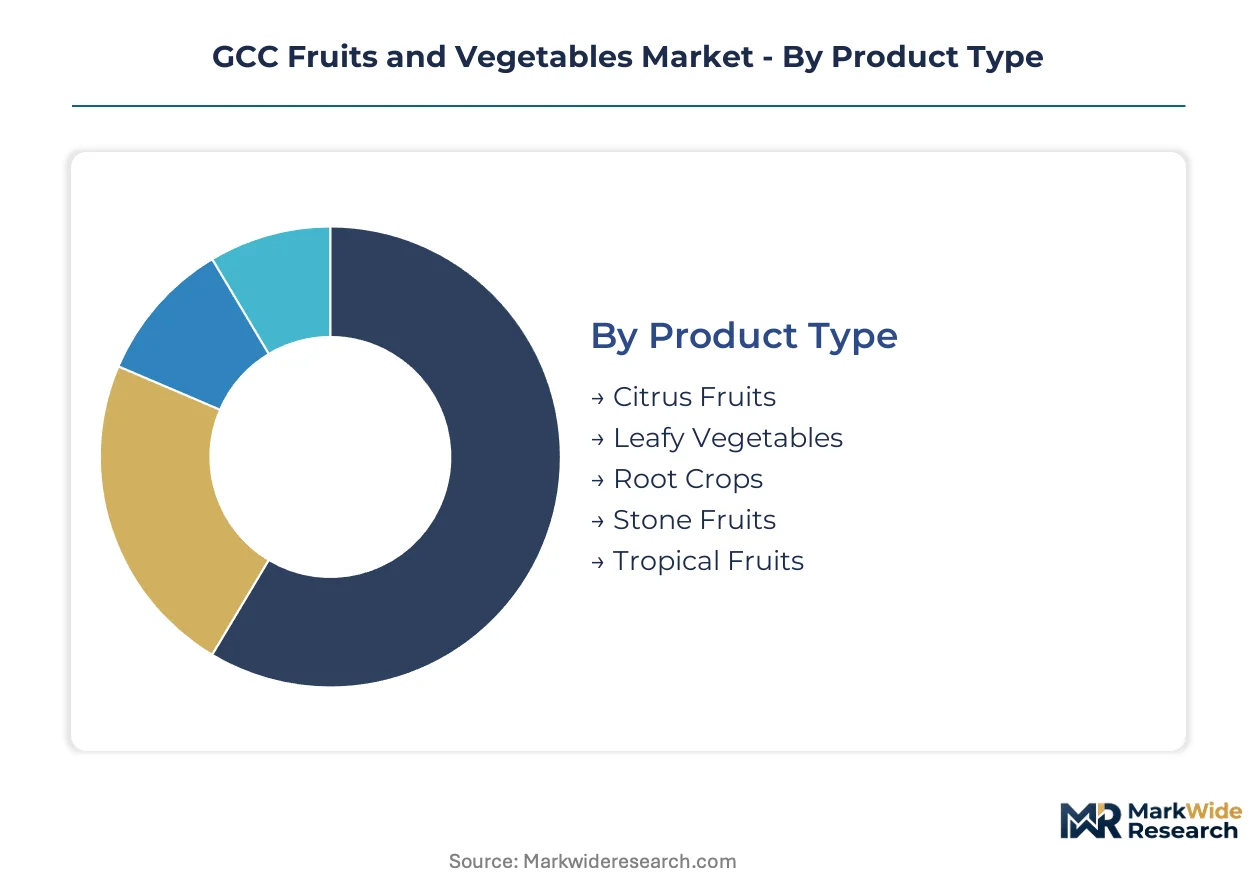
Segmentation in the GCC fruits and vegetables market reveals how water scarcity, import dependency, and regulatory stringency concentrate investment across specific product categories and channel configurations. Procurement patterns diverge sharply between domestic controlled-environment supply and traditional seaborne imports.
Product Type:
Domestic cultivation capacity concentrates in perishable, high-value categories where residue limits and shelf-life constraints disadvantage long-haul imports. Export-led segments remain dominated by Nile Delta and Indian subcontinent supply corridors.
- Citrus Fruits:Oranges, lemons, and grapefruits with strict Brix-level specifications for juice extraction and fresh consumption. Riyadh-based greenhouse operators and Egyptian exporters split procurement in Saudi retail channels, with domestic supply capturing premium shelf space during summer months when shipping heat damage risks peak.
- Leafy Vegetables:Lettuce, spinach, and herbs requiring rapid cold-chain transit from harvest to point-of-sale. UAE hydroponic farms in Al Ain and Dubai Industrial City supply year-round to hotel chains and airline caterers, displacing Jordanian and Lebanese imports that face extended port inspection delays.
- Root Crops:Carrots, potatoes, and onions with extended storage viability enabling seaborne supply from Egypt and India.
- Stone Fruits:Peaches, plums, and apricots with narrow harvest windows and high perishability.
- Tropical Fruits:Bananas, mangoes, and pineapples entirely import-dependent on Southeast Asian and Latin American origins.
Citrus fruits command the established base. The steepest expansion runs through leafy vegetables.
Application:
Cost-tier stratification separates commodity-volume channels from premium-grade certification requirements that dominate foodservice and retail packaging segments.
- Fresh Consumption:Unprocessed produce sold through retail and wholesale channels for direct household preparation. Dubai and Riyadh urban households drive demand for pesticide-free certification and modified atmosphere packaging that extends refrigerator shelf-life.
- Foodservice Industry:Contract supply to hotels, restaurants, and catering operations with strict traceability and halal-handling documentation. Qatar's tourism infrastructure buildout and Saudi Vision 2030 hospitality expansion are redirecting procurement toward domestic greenhouse operators capable of year-round volume commitments.
- Processing:Industrial input for juice extraction, canning, and frozen product manufacturing.
- Export:Reprocessing and transshipment through Jebel Ali and King Abdulaziz Port for redistribution to neighboring markets.
- Retail Packaging:Pre-cut, washed, and portioned products for convenience-oriented consumers.
Fresh consumption anchors volume throughput. Foodservice industry applications are gaining share fastest.
Distribution Channel:
Customer-type concentration shapes channel investment, with institutional buyers consolidating procurement through wholesale networks while urban households fragment toward digital platforms.
- Wholesale Suppliers:Centralized procurement hubs serving hospitality chains, institutional buyers, and retail intermediaries with volume-based pricing and consolidated logistics. Dubai's Al Aweer Fruit and Vegetable Market and Riyadh's Al-Bir Central Market remain dominant flow nodes for Egyptian and Indian import volumes.
- Online Retailers:Subscription-based and on-demand delivery platforms capturing urban household demand in Dubai Marina, Jeddah's Al-Hamra district, and Riyadh's Diplomatic Quarter. Weekly produce box services bypass traditional retail markups and demand traceability systems that favor domestic hydroponic suppliers.
- Supermarkets:Modern retail chains with private-label fresh produce programs and residue-limit compliance requirements.
- Hypermarkets:Large-format stores combining grocery and general merchandise with centralized produce procurement.
- Local Markets:Traditional souk-based retail with fragmented supplier bases and limited cold-chain infrastructure.
Wholesale suppliers retain volume dominance. Online retailers are climbing the fastest.
Customer Type:
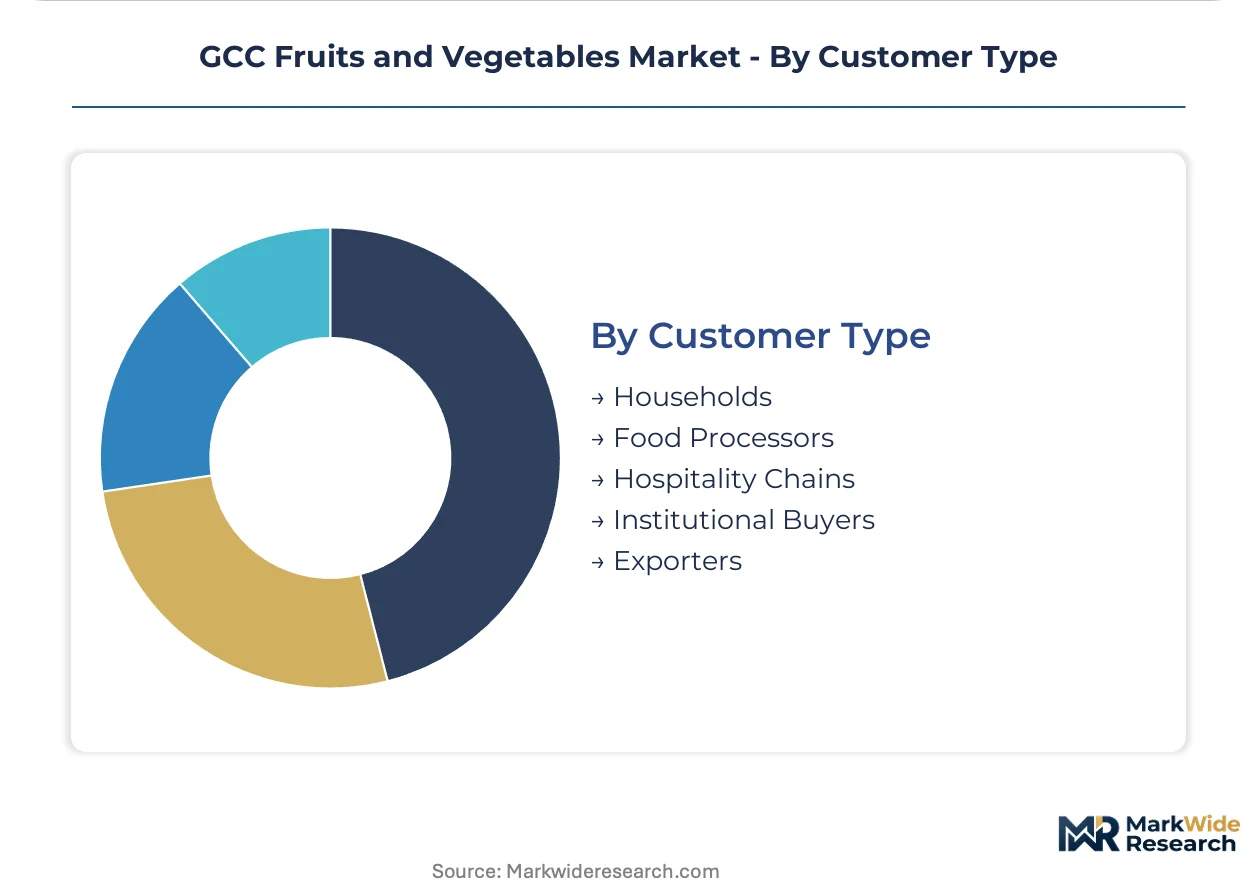
Margin structure varies sharply across buyer categories, with hospitality chains and exporters demanding certification documentation that raises supplier compliance costs while household price sensitivity constrains premium positioning.
- Hospitality Chains:Hotel groups, restaurant franchises, and airline caterers with centralized procurement, audit requirements, and year-round supply consistency mandates. Accor, Marriott, and Emirates Flight Catering contract directly with UAE greenhouse operators, eliminating intermediary margins and specifying integrated pest management protocols.
- Households:Individual consumers purchasing through retail channels with accelerating preference for subscription delivery and organic certification. Saudi Arabia's retail modernization and female workforce participation are shifting time-constrained households toward pre-portioned and ready-to-cook produce formats.
- Food Processors:Industrial manufacturers requiring standardized specifications for juice, canning, and frozen product lines.
- Institutional Buyers:Hospital, university, and government cafeteria networks with pooled procurement and food safety audit requirements.
- Exporters:Trading firms reprocessing and transshipping GCC-origin produce to neighboring markets with documentation for halal-handling and phytosanitary compliance.
Households represent the established demand base. Hospitality chains are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic greenhouse capacity concentrates in Saudi Arabia and the UAE, where desalinated water infrastructure and regulatory enforcement of residue limits are displacing traditional Egyptian and Indian supply corridors.
Saudi Arabia
Riyadh and Jeddah anchor demand as Vision 2030 hospitality investments expand procurement volumes. The Saudi Food and Drug Authority enforces Codex-aligned maximum residue limits that disqualify non-compliant imports. Qassim and Asir provinces host expanding greenhouse clusters funded through the Sustainable Agriculture Rural Development Program.
United Arab Emirates
Dubai's tourism infrastructure and airline catering networks drive year-round demand for traceable produce. The Ministry of Climate Change and Environment tightened pesticide residue limits and import certification requirements. Al Ain and Dubai Industrial City concentrate vertical farming operations supplying hotel chains directly.
Qatar
Hotel and restaurant construction ahead of recurring mega-events expands foodservice procurement volumes. The Qatar General Organization for Standardization enforces halal-handling documentation and phytosanitary compliance. Doha-based procurement cooperatives are consolidating institutional catering demand.
Oman
Domestic controlled-environment agriculture remains underdeveloped, creating import dependency for perishable categories. The Ministry of Agriculture and Fisheries supports greenhouse construction incentives in Al Batinah and Dhofar governorates. Muscat's retail modernization is accelerating subscription-based delivery adoption among urban households.
Bahrain
The kingdom lacks domestic cultivation scale, relying on UAE and Saudi cross-border supply networks. The Bahrain Food Control Directorate enforces residue limits aligned with GCC standardization protocols. Manama's hospitality sector sources through consolidated wholesale channels with limited direct farm contracting.
GCC Fruits and Vegetables Market Competitive Landscape
Concentration sits with integrated retail-hospitality suppliers and domestic greenhouse operators. The market structures around three tiers: large-scale import traders with regional logistics networks, controlled-environment agriculture specialists with residue-free certification, and modern retail chains with private-label programs. Competitive moves center on backward integration into captive cultivation and exclusive procurement partnerships with hospitality chains.
Within the domestic cultivation archetype, Pure Harvest Smart Farms and Elite Agro exemplify capital-intensive greenhouse operators leveraging hydroponic systems for year-round supply. Al Dahra Agriculture anchors the import-trader tier with cross-border sourcing networks spanning multiple Gulf states. Lulu Group occupies a position bridging retail distribution with integrated farm ownership, representing the vertical consolidation pattern reshaping procurement relationships.
| Leading Market Players |
|---|
| Al Ghurair Foods |
| Al Foah (Agthia Group) |
| Pure Harvest Smart Farms |
| Carrefour GCC |
| Lulu Group |
| Elite Agro |
| Fresh Fruits Company |
| Spinneys Dubai LLC |
| Al Dahra Agriculture |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between UAE greenhouse operators and hospitality chains lock in both residue-free supply access and price visibility, insulating domestic producers from Egyptian spot-market volatility while anchoring procurement budgets against desalinated water cost swings.
Pricing Analysis
SFDA and MOHAP maximum residue limits dictate the pricing tier structure across GCC produce procurement. Three-tier pricing structure across premium, standard, and economy levels separates certified organic hydroponic output from conventional greenhouse supply and bulk import commodities. Price differentiation hinges on halal-handling documentation and integrated pest management certification. Cost compression in the standard tier is intensifying because Egyptian exporters face escalating rejection rates at Saudi ports. Hospitality chains exhibit least price sensitivity due to audit requirements, while institutional buyers in education and healthcare verticals drive hardest bargain on volume commitments.
Supply Chain Analysis
Seven-to-ten-day ocean freight windows from Egypt's Nile Delta and India's Maharashtra corridor create inventory vulnerability for perishable categories, compressing effective shelf-life before port inspection delays. Geographic supply concentrates in Egypt, India, and domestic UAE greenhouse clusters. Raw material dependencies rest on desalinated water, specialized nutrient solutions, and biological pest control agents. Single-source vulnerability runs through Suez Canal disruption exposure for Egyptian citrus and onion volumes. Distribution runs through wholesale hubs at Dubai's Al Aweer and Riyadh's Al-Bir Central Market, with online subscription channels capturing accelerating urban household share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospitality procurement cooperatives and pooled institutional catering contracts, fragmenting traditional spot-market intermediaries and shifting margin capture toward direct farm-to-fork relationships.
For Market Incumbents: Fortify residue-free certification moats through backward integration into biological pest control supply and captive desalinated water capacity in Riyadh's Sudair Industrial City. Emerging hydroponic entrants in Qassim province threaten premium positioning. Channel control through exclusive airline catering contracts with Emirates Flight Catering anchors volume visibility.
For New Entrants and Emerging Players: Differentiate on Oman and Bahrain market penetration where domestic controlled-environment capacity is absent and MOHAP-equivalent certification creates first-mover advantage. Subscription-based home delivery in Muscat and Manama represents the most penetrable segment. Direct contracting with hospital and university cafeteria networks bypasses wholesale markups.
For Investors and Strategic Acquirers: Mid-scale greenhouse operators with established SFDA organic certification timelines and cross-border logistics networks into Bahrain and Oman present attractive acquisition profiles. Long-term viability over the projection horizon rests on water tariff reform resilience and import-substitution policy continuity. The signal to watch is Saudi Sustainable Agriculture Rural Development Program subsidy allocation shifts toward Asir province greenhouse clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biological Pest Control | SFDA residue limit alignment secures premium pricing tier access for domestic operators. |
| Cross-Border Logistics Network Expansion | Oman and Bahrain penetration captures underserved markets lacking controlled-environment capacity. |
| Direct Hospitality Chain Contracting | Accor and Marriott procurement cooperatives eliminate wholesale intermediary margins. |
| Subscription-Based Home Delivery Launch | Urban households in Dubai Marina and Riyadh Diplomatic Quarter bypass traditional retail channels. |
| Organic Certification Timeline Acceleration | Multi-year field history documentation with Emirates Authority for Standardization and Metrology unlocks price premiums. |
Research Methodology
Cross-validation between regulatory filing analysis and trade flow data anchors the qualitative findings in this study. Primary interviews with greenhouse operations managers, hospitality procurement directors, SFDA compliance officers, and airline catering supply chain leads combined with secondary validation from customs records, MOHAP technical regulation releases, and Sustainable Agriculture Rural Development Program disclosures. Bottom-up cultivation capacity estimates and top-down hospitality procurement budget analysis triangulate volume assumptions.
Sensitivity analysis across desalinated water tariff scenarios and Egyptian import rejection rate variations stress-tests projection robustness. The analytical framework segments by product perishability tier, cultivation method, certification grade, buyer channel, and regional regulatory cluster throughout the forecast period. CAGRs derive from trend extrapolation of greenhouse construction permits and hospitality sector capital expenditure pipelines. Industry-specific forecast inputs include SFDA residue limit enforcement trajectory and Vision 2030 localization mandate implementation pace.
Material uncertainties — water tariff reform timing, Suez Canal disruption frequency, and organic certification timeline compression — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding policy continuity and infrastructure buildout schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Farro Market
Fruits and Vegetables
Pea Flakes Market
Fruits and Vegetables
South America Olive Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
Fruit Puree Market
Fruits and Vegetables
Peaches and Nectarines Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
North America Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Vaccinium Myrtillus Market
Fruits and Vegetables
Canada Fruits and Vegetables Market
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Jicama Market
Fruits and Vegetables
Venezuela Fruits and Vegetable Market
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Fruit Packaging Market