
 South America Alcoholic Beverages Market | 2026-2036
South America Alcoholic Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
South America Alcoholic Beverages Market Analytics
Skilled brewing technicians and enology specialists are redrawing competitive boundaries across South America's fermented and distilled beverage landscape. Anheuser-Busch InBev anchors massive lager production infrastructure throughout Brazil's industrial corridor. Heineken N.V. leverages its Dutch technical heritage to sustain premium positioning in urban on-trade channels. Grupo Peñaflor dominates Argentina's wine export pipeline with vertically integrated vineyard-to-bottle operations.
South America alcoholic beverages encompass fermented and distilled products containing ethanol, typically ranging from four percent to forty percent alcohol by volume, produced through controlled yeast fermentation, distillation, or both, serving recreational, social, and ceremonial consumption functions. Beer retains the largest volume share across the region's retail and hospitality channels, though spirits command disproportionate margin concentration in metropolitan markets. Wine consumption clusters in Argentina and Chile's domestic bases while export-oriented premium labels capture higher per-unit value. Cider remains a niche category with accelerating trial rates among Gen Z consumers in Brazilian coastal cities.
ANVISA governs product registration, labeling, and health warnings for alcoholic beverages sold in Brazil, while Argentina's national food safety authority enforces additive limits and origin denomination rules that constrain cross-border formulation standardization. Chile's Ministry of Health mandates explicit alcohol content disclosure and restricts marketing imagery targeting younger demographics, compressing advertising budgets for multinational entrants. Stakeholders must weigh regulatory compliance costs against the margin premiums available in premium spirits and craft beer segments before committing capital to new production capacity.
Market Dynamics
ANVISA's evolving labeling mandates and ethanol taxation frameworks are compressing formulation flexibility for importers while privileging domestic Brazilian producers with compliant supply chains. This regulatory asymmetry is redrawing competitive boundaries across fermented and distilled beverage categories.
Growth Catalysts
- Experiential on-trade consumption:Urban hospitality venues in São Paulo and Buenos Aires are capturing premium spending as consumers prioritize social drinking occasions over retail purchases.
- ANVISA compliance infrastructure:Domestic Brazilian producers with established regulatory relationships are accelerating product registration timelines relative to importers navigating unfamiliar protocols.
- Minas Gerais production clustering:Concentrated premium spirits distillation in Brazil's southeastern state belt is generating agglomeration economies and specialized logistics networks.
Market Restraints
- Input cost volatility:Barley and grape concentrate prices fluctuate with Argentine peso instability and Chilean drought cycles, squeezing margin predictability for regional brewers and winemakers.
- Cross-border formulation friction:Argentina's national food safety authority enforces additive limits that conflict with Brazilian ANVISA standards, preventing unified product specifications.
- Technical limitation in cold chain:Inadequate refrigerated transport infrastructure across the Amazon basin restricts perishable craft beer distribution to northern Brazilian markets.
Strategic Opportunities
- Underpenetrated northern Brazil:Amazonian urban centers like Manaus and Belém lack premium spirits distribution density, creating first-mover whitespace for compliant entrants.
- Gen Z cider trial acceleration:Coastal Brazilian cities are showing accelerating adoption rates for low-alcohol fermented alternatives among younger demographic cohorts.
- Chilean marketing restriction arbitrage:The Ministry of Health's constraints on imagery targeting younger demographics create competitive advantage for brands with established adult-market positioning.
Industry Challenges
- Enology specialist scarcity:Argentina's wine sector faces acute shortages of vineyard management talent as aging specialists retire without sufficient replacement training pipelines.
- Capex intensity in compliance:ANVISA-mandated laboratory testing equipment and traceability systems require substantial upfront investment for new market entrants.
- Certification timeline compression:Product registration backlogs at Brazilian health surveillance agencies are extending time-to-market for innovative formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Alcoholic Beverages Market |
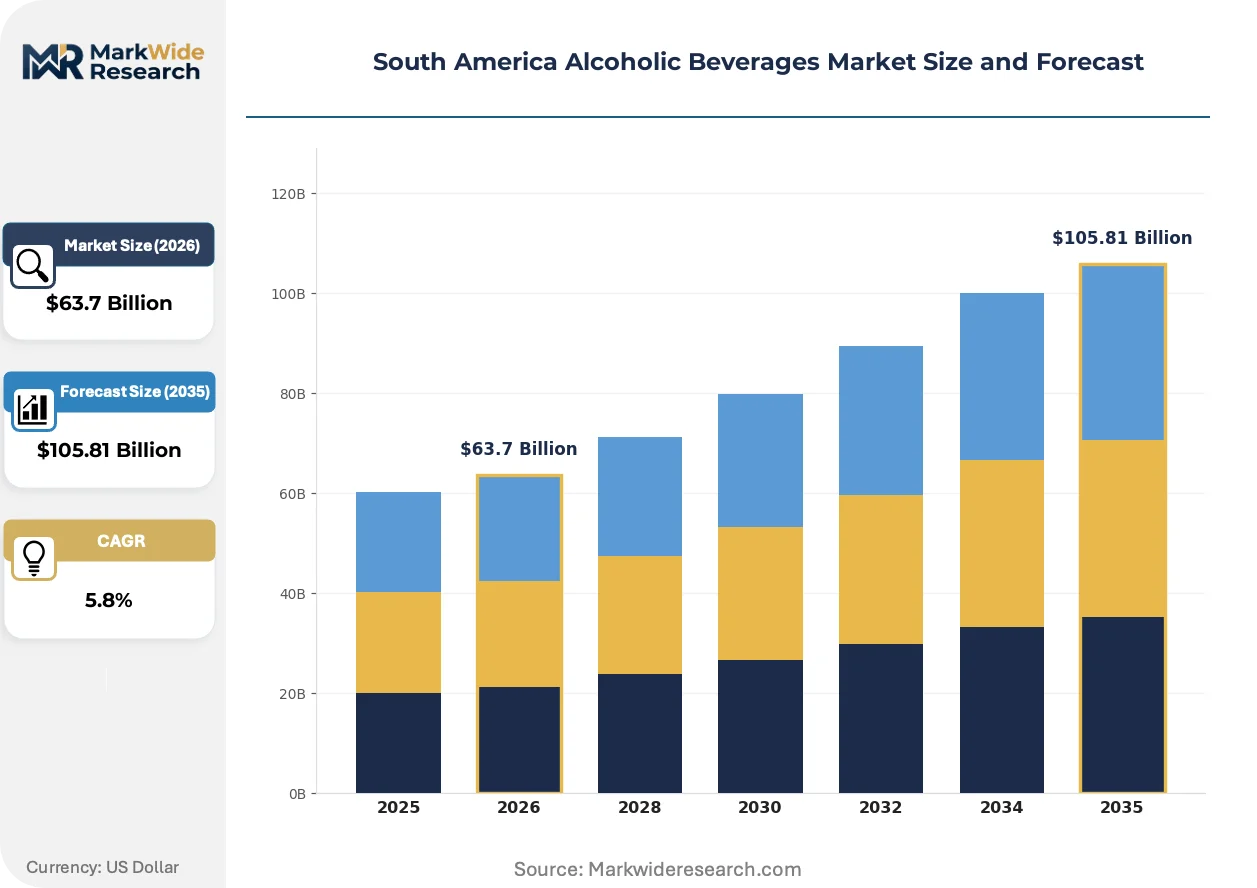
| Market Size in 2026 | $63.7 Billion |
| Market Size in 2035 | $105.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Spirits, Wine, Cider Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops Customer Type: Millennials, Gen Z, Adults, Tourists Packaging Type: Bottles, Cans, Kegs, Boxes |
| Companies Covered | Anheuser-Busch InBev, Heineken N.V., Grupo Peñaflor, Diageo Plc, CCU S.A., Cervejaria Petropolis S/A, Ambev, Pernod Ricard, Bavaria SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Alcoholic Beverages Market Evolving Landscape
Controlled fermentation technologies and precision distillation systems are fragmenting traditional production hierarchies across South America's beverage landscape. These innovations are enabling smaller-scale producers to achieve quality parity with established industrial operations.
Precision temperature-controlled fermentation is fragmenting the competitive landscape in craft beer production. Microbreweries in São Paulo and Porto Alegre are adopting sensor-equipped tanks that maintain exact yeast activity parameters. This technology is fragmenting market share away from mass-market lager producers by enabling consistent small-batch quality at viable unit economics.
Chile's Ministry of Health restrictions on marketing imagery targeting younger demographics are forcing brand architecture redesigns across spirits portfolios. Advertisers must now deploy explicit alcohol content disclosures and age-gated digital channels. Premium labels with established adult-market positioning are responding by shifting budget toward experiential on-trade activations and restricted-access tasting events.
Direct-to-consumer subscription models are disrupting traditional three-tier distribution in Argentina's wine sector. Boutique vineyards in Mendoza are bypassing wholesale intermediaries to capture margin through recurring shipment programs. This channel innovation is most visible in metropolitan Buenos Aires, where affluent consumers demonstrate willingness to prepay for curated quarterly selections.
South America Alcoholic Beverages Market Segmentation
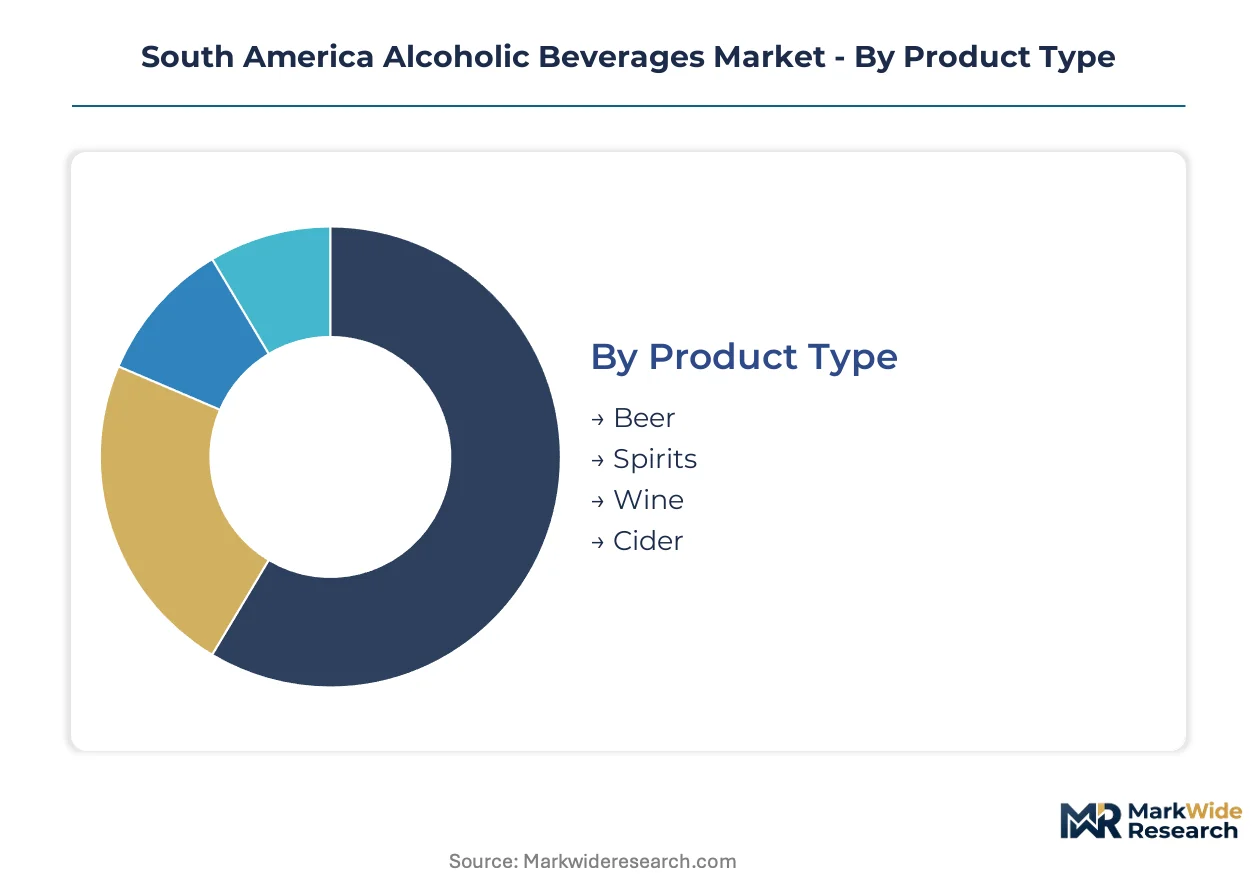
ANVISA labeling mandates and ethanol taxation frameworks in Brazil create divergent compliance burdens across product categories and distribution channels. Segmentation reveals where regulatory asymmetries privilege domestic producers with established certification infrastructure over import-dependent competitors.
Product Type:
ANVISA governs formulation registration and health warning placement differently across ethanol concentration thresholds, fragmenting competitive positioning between fermented and distilled categories.
- Beer:Mass-market lager dominates volume throughput across Brazil's southeastern industrial corridor, with São Paulo and Minas Gerais breweries capturing agglomeration economies in malt supply and specialized logistics. ANVISA's streamlined registration for sub-6% ABV products accelerates domestic product launches relative to higher-alcohol imports.
- Spirits:Premium distilled beverages command disproportionate margin concentration in metropolitan hospitality channels, though ANVISA's extended certification timelines for 20-40% ABV formulations compress formulation flexibility for importers. Cachaça producers leverage compliant supply chains to defend shelf position against delayed foreign entries.
- Wine:Argentina's domestic consumption clusters around Mendoza and San Juan vineyard zones, with export-oriented premium labels capturing higher per-unit value through vertically integrated operations.
- Cider:Low-alcohol fermented alternatives show accelerating trial rates among coastal Brazilian Gen Z cohorts, though category scale remains constrained by limited cold chain infrastructure in northern distribution zones.
Beer handles the majority of throughput; Cider is the fastest mover on share.
Distribution Channel:
Channel cost structures diverge sharply based on ANVISA-mandated traceability requirements and refrigerated handling specifications for perishable craft segments.
- Supermarkets:Large-format retail anchors volume distribution for standardized lager SKUs across Brazil's urban centers, with private label penetration constrained by ANVISA registration costs that favor scaled domestic producers.
- Convenience Stores:Small-format proximity retail captures impulse purchasing in São Paulo's dense commercial districts, though limited cold storage capacity restricts craft beer assortment depth.
- Online Retail:Direct-to-consumer platforms are disrupting traditional three-tier distribution in Argentina's wine sector, with Mendoza boutiques bypassing wholesale intermediaries through subscription shipment programs.
- Specialty Shops:Curated retail formats concentrate premium spirits and craft beer in affluent Buenos Aires and São Paulo neighborhoods, leveraging staff expertise to justify price premiums.
Supermarkets dominate absolute volume; Online Retail is expanding most quickly as wineries capture margin through disintermediation.
Customer Type:
Demographic consumption patterns map directly to Chile's Ministry of Health marketing restrictions and Brazil's on-trade experiential spending shifts.
- Millennials:Urban professionals aged 28-43 drive premiumization in São Paulo hospitality venues, prioritizing social drinking occasions over retail purchases.
- Gen Z:Younger cohorts in Brazilian coastal cities demonstrate accelerating adoption of low-alcohol alternatives, with cider trial rates rising fastest among 18-27 year-olds.
- Adults:Established consumers over 44 sustain volume in traditional wine and spirits categories, particularly in Argentina's domestic base.
- Tourists:International visitors concentrate demand in Buenos Aires and Rio de Janeiro on-trade channels, with experiential consumption reshaping hospitality venue economics.
Millennials anchor current revenue; Gen Z is climbing the fastest as category preferences fragment.
Packaging Type:
Packaging selection reflects the tension between ANVISA labeling mandates and cold chain limitations across Brazil's northern distribution zones.
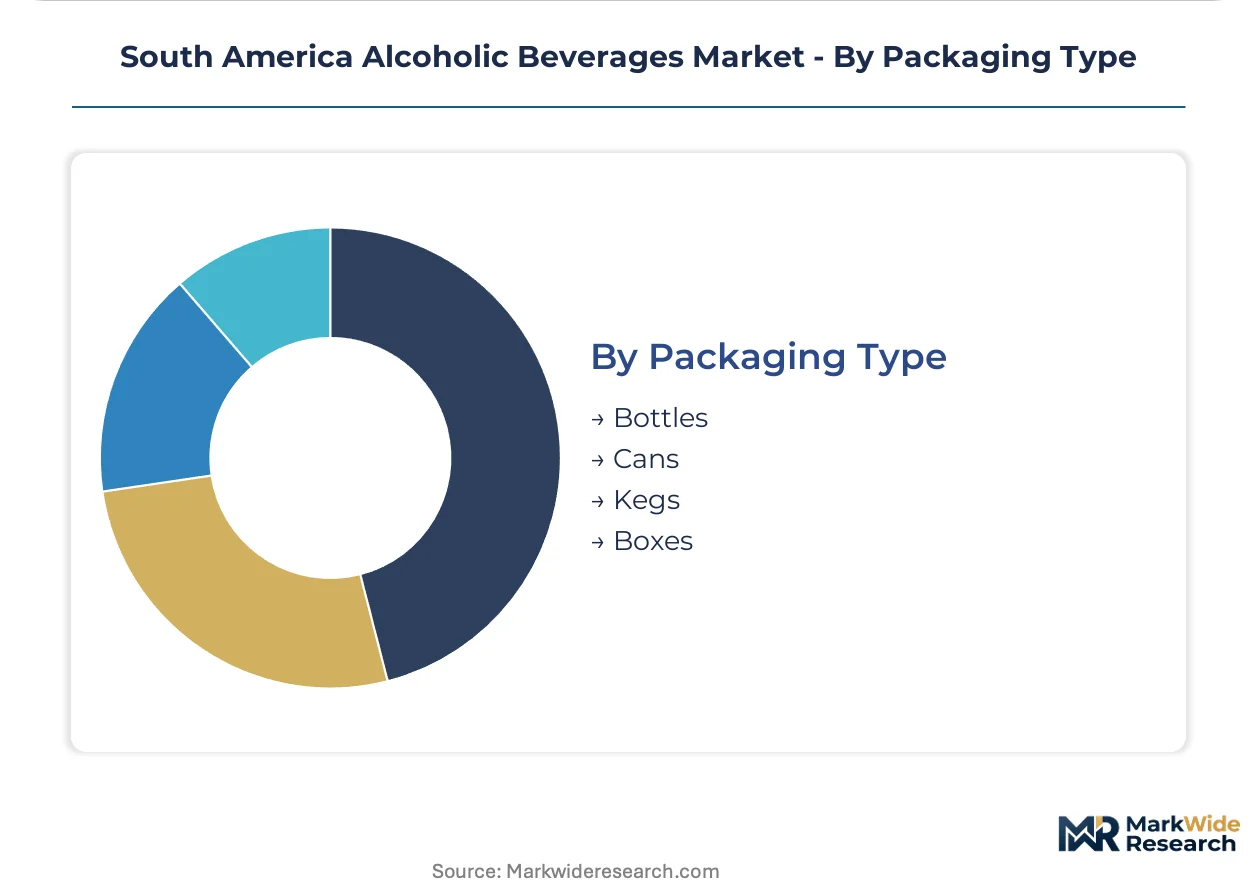
- Bottles:Glass packaging dominates wine and premium spirits, with Argentine export labels leveraging bottle differentiation to signal quality in international markets.
- Cans:Aluminum formats are displacing glass in Brazilian craft beer distribution, enabling lighter logistics and extended shelf stability without refrigeration.
- Kegs:On-trade draft systems concentrate in São Paulo and Buenos Aires hospitality venues, capturing experiential spending through freshness positioning.
- Boxes:Bag-in-box formats serve volume wine consumption in Argentine domestic markets, though premium positioning remains constrained by perceived quality associations.
Bottles retain the largest installed base; Cans are gaining share fastest as craft producers solve logistics constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA anchors regulatory complexity across Brazil's dominant geography, where southeastern industrial corridors concentrate production capacity while fragmented compliance timelines disadvantage import-dependent competitors.
Brazil
São Paulo and Minas Gerais drive premium spirits volume expansion through agglomerated distillation infrastructure and specialized logistics networks. ANVISA's ethanol taxation frameworks and extended certification timelines for higher-ABV formulations compress formulation flexibility for importers while privileging domestic producers with compliant supply chains. The southeastern state belt generates economies of scale in malt supply and cold chain distribution that northern urban centers lack.
Argentina
Mendoza and San Juan vineyard zones anchor domestic wine consumption while export-oriented labels capture premium value through vertically integrated operations. The national food safety authority enforces additive limits and origin denomination rules that conflict with Brazilian standards, preventing unified product specifications across the Mercosur trade zone. Buenos Aires concentrates on-trade experiential spending as urban hospitality venues capture premium social drinking occasions.
Chile
Metropolitan Santiago and Valparaíso harbor domestic wine consumption clusters alongside growing craft beer trial rates among younger demographics. The Ministry of Health mandates explicit alcohol content disclosure and restricts marketing imagery targeting younger cohorts, compressing advertising budgets for multinational entrants. Central Valley vineyard operations sustain export pipeline quality through precision enology techniques.
Colombia
Bogotá and Medellín urban centers concentrate premium spirits demand as on-trade channels expand experiential drinking formats. The national food and drug surveillance institute enforces labeling mandates that diverge from Brazilian ANVISA standards, creating cross-border formulation friction for regional portfolio standardization. Caribbean coastal cities show accelerating adoption of low-alcohol fermented alternatives.
Peru
Lima anchors pisco production heritage with concentrated distillation infrastructure in Ica and Arequipa regions. The national health authority's evolving additive regulations and health warning placement rules create compliance asymmetries favoring established domestic producers over import entrants. Southern vineyard zones sustain grape concentrate supply for regional winemaking operations.
South America Alcoholic Beverages Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across South America's alcoholic beverages landscape. Mass-market lager production concentrates around scaled brewing infrastructure with automated fermentation systems, while premium spirits and craft segments fragment across specialized distillers and microbreweries with precision temperature control capabilities. Three archetypes dominate: multinational brewers with captive distribution networks, vertically integrated wine estates with vineyard-to-bottle operations, and regional spirits specialists with compliant ANVISA certification infrastructure. Competitive moves center on portfolio diversification into adjacent ethanol categories and strategic partnerships to secure barley and grape concentrate supply amid currency volatility.
Among Belgian-origin multinational brewers, Anheuser-Busch InBev and Ambev exemplify scale-driven production archetypes with southeastern Brazilian industrial corridor concentration. Dutch-based Heineken N.V. occupies a premium positioning tier leveraging technical heritage for urban on-trade channel penetration. Argentina's Grupo Peñaflor represents vertically integrated wine estate specialization with Mendoza vineyard control and export pipeline dominance.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Heineken N.V. |
| Grupo Peñaflor |
| Diageo Plc |
| CCU S.A. |
| Cervejaria Petropolis S/A |
| Ambev |
| Pernod Ricard |
| Bavaria SA |
| Others |
Value Network & Pricing Analysis
Ninety-day ANVISA certification timelines for imported spirits compress inventory turns and inflate working capital requirements, concentrating pricing power among Brazilian domestic producers with pre-approved formulations while forcing importers into premium positioning to recover carrying costs. This lead-time asymmetry reshapes competitive economics across fermented and distilled categories.
Pricing Analysis
São Paulo-to-Manaus price spreads for premium cachaça exceed those for mass-market lager by multiples, reflecting cold chain fragmentation and regulatory compliance cost layering. Three-tier pricing structure across premium, standard, and economy levels separates aged-reserve spirits from unaged cachaça from bulk ethanol blends. Pricing pressure stems from Argentine peso volatility inflating grape concentrate costs for regional winemakers. Price-sensitive buyers cluster in northern Brazil's emerging urban centers, while least-sensitive demand concentrates in Buenos Aires and São Paulo experiential hospitality channels.
Supply Chain Analysis
Brazil and Argentina anchor South American alcoholic beverage production, with São Paulo and Minas Gerais breweries capturing agglomeration economies and Mendoza vineyards sustaining export pipeline quality. Malt barley draws from Argentine Pampas cultivation zones, while glass packaging feeds from southeastern Brazilian industrial corridors. Single-source vulnerability concentrates in ANVISA-certified laboratory testing capacity for product registration. Distribution runs through three-tier wholesale networks in Brazil, with direct-to-consumer subscription models disrupting traditional intermediation in Argentina's wine sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enology specialist scarcity across Argentina's aging vineyard management workforce constrains quality expansion for premium wine labels, privileging producers with captive talent pipelines or training infrastructure.
For Market Incumbents: Compound regulatory compliance advantages by deepening ANVISA certification infrastructure and accelerating product registration timelines relative to import-dependent competitors. Defend margin position through backward integration into grape concentrate and malt supply amid Argentine currency volatility. Prioritize capacity positioning in Minas Gerais distillation clusters to capture agglomeration economies. For New Entrants and Emerging Players: Differentiate on precision fermentation technology and sensor-equipped production systems that achieve quality parity with established industrial operations at smaller scale. Target underpenetrated northern Brazilian urban centers like Manaus and Belém where premium spirits distribution density remains lowest. Deploy direct-to-consumer subscription models to bypass wholesale intermediation and capture margin. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational brewers seeking portfolio streamlining, particularly mass-market lager assets facing share erosion from craft alternatives. Long-term viability hinges on regulatory compliance infrastructure and cold chain logistics capabilities rather than brand equity alone. Monitor ANVISA registration backlog clearance rates as inflection indicator for import competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Compliance Infrastructure Investment | Accelerated product registration timelines compress time-to-market versus import-dependent competitors. |
| Precision Fermentation Technology Adoption | Sensor-equipped tanks enable consistent small-batch quality at viable unit economics for craft producers. |
| Direct-to-Consumer Subscription Launch | Mendoza boutiques bypass wholesale intermediaries to capture margin through recurring shipment programs. |
| Backward Integration into Malt Supply | Captive barley sourcing insulates margin from Argentine peso volatility and input cost fluctuations. |
| Cold Chain Logistics Partnership | Refrigerated transport infrastructure expansion unlocks craft beer distribution to northern Brazilian markets. |
Research Methodology
Desk research of customs trade records, ANVISA regulatory filings, and vineyard production databases preceded structured interviews with brewery operations directors, enology specialists, retail category buyers, and hospitality procurement managers. Primary fieldwork combined with secondary validation from industry association reports and company disclosure documents. Bottom-up volume modeling triangulated against top-down macroeconomic consumption trends.
Variance decomposition across product type, distribution channel, customer demographic, and packaging format segmentation dimensions drove analytical framework construction throughout the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporated ANVISA certification timeline data and cold chain infrastructure expansion schedules.
Material uncertainties — regulatory revision at Brazil's health surveillance agency, Argentine currency instability, Chilean drought cycles — sit outside the modeled envelope. Forecasts reflect assumptions about compliance cost trajectories and consumer preference stability. Recalibration cycles align with material shifts in ANVISA mandate implementation and experiential consumption pattern evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Shortenings Market
Alcoholic Beverages
Cognac Market
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
Kegs Market
Alcoholic Beverages
West Africa Alcoholic Beverages Market
Alcoholic Beverages
Rotels Market
Alcoholic Beverages
Wine Bags Market
Alcoholic Beverages
Yorker Spouts Market
Alcoholic Beverages
North America Soju Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Draught Beer Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Japan Beer Market
Alcoholic Beverages
Non-Fuel Grade Alcohol Market
Alcoholic Beverages
Global Bars and Nightclubs Market
Alcoholic Beverages
Brewing Enzymes Market