
 Wine Bottle Sterilizer Market | 2026-2036
Wine Bottle Sterilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Bottle Sterilizer Market Analytics
The EU Green Deal is pivoting winery procurement toward non-chemical sterilization systems across European bottling facilities. Papablic leverages compact UV-C engineering to serve small-batch vineyards with limited floor space. Philips Avent anchors hospital-grade sterilization expertise into commercial wine applications through its existing UV platform architecture. Grownsy competes aggressively on ozone treatment pricing for mid-tier cooperatives in Southern Europe.
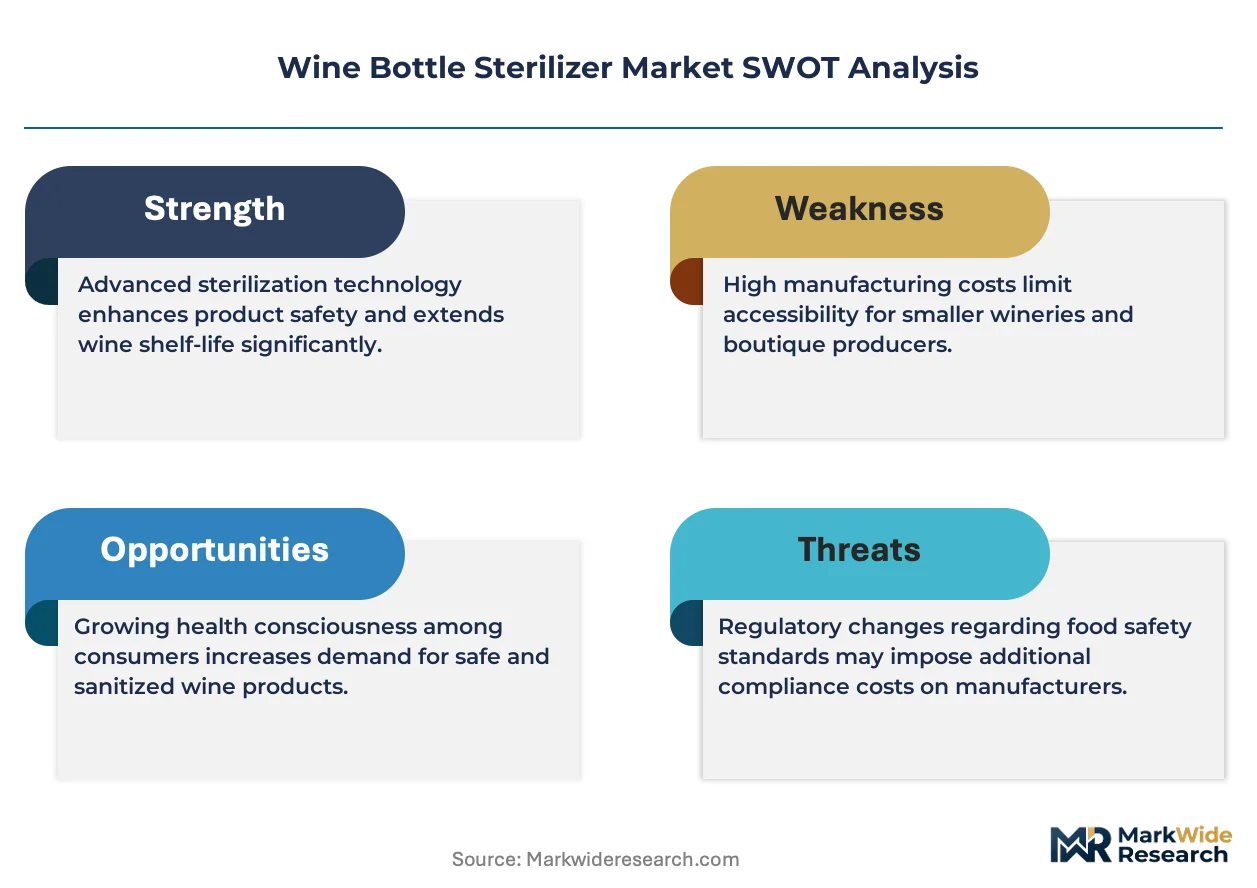
A wine bottle sterilizer is a specialized sanitation device engineered to eliminate microbial contaminants from glass and PET wine containers through controlled UV-C irradiation, heated steam, or ozone infusion, typically achieving 99.9% pathogen reduction at wavelengths between 200 and 280 nanometers. These systems serve critical quality assurance functions in bottling lines, preventing Brettanomyces, lactobacillus, and acetic acid bacteria from compromising vintage integrity. UV-C Light technology dominates installed capacity due to lower operating costs and minimal water consumption compared to heat sterilization, though Ozone Treatment captures the fastest expansion as wineries pursue chemical-free certifications. Heat Sterilization retains entrenched positions in traditional European cooperatives where legacy infrastructure amortization discourages platform switching. Winery end users command the largest value share given their direct exposure to spoilage liability and export compliance requirements.
FDA food contact surface regulations and EU REACH chemical restrictions jointly constrain permissible sterilization chemistries in export-bound wine production. CE marking requirements under the EU Machinery Directive mandate specific UV shielding and interlock protocols for automated bottling integrations. ISO 22000 food safety management certification increasingly functions as a de facto market access threshold for equipment vendors serving multinational beverage conglomerates. Stakeholders must monitor evolving national interpretations of chemical residue limits as these directly determine technology migration timelines and replacement cycle acceleration.
Market Dynamics
EU Green Deal chemical reduction mandates are compressing replacement cycles for legacy heat-sterilization infrastructure across European bottling facilities. This regulatory pivot is accelerating capital redeployment toward UV-C and ozone platforms that eliminate residual chemical liability in export-bound production.
Growth Catalysts
- EU REACH chemical restrictions:Export-bound wineries face compliance deadlines that force equipment replacement, creating immediate demand pull for non-chemical sterilization systems in France, Italy, and Spain.
- Small-batch vineyard expansion:Boutique producers in emerging wine regions require compact, modular sterilization units that integrate with flexible bottling lines rather than fixed industrial infrastructure.
- UV-C wavelength optimization:Advances in 254-nanometer lamp efficiency are reducing energy consumption per bottle, improving operating economics for high-throughput cooperatives.
Market Restraints
- Quartz sleeve degradation:UV-C systems require quarterly replacement of protective sleeves, creating recurring input cost volatility and maintenance labor demands.
- German component concentration:Precision ozone generator electrodes and high-grade UV lamp ballasts concentrate production in Bavarian and Baden-Württemberg manufacturing clusters.
- Heat sterilization legacy lock-in:Traditional cooperatives in Bordeaux and Rioja face sunk-cost barriers from fully amortized steam infrastructure that still meets baseline regulatory thresholds.
Strategic Opportunities
- Portuguese Alentejo expansion:Underpenetrated vineyard consolidation in this southern region creates first-mover positioning for mobile sterilization service providers.
- ISO 22000 certification bundling:Equipment vendors can capture premium positioning by pre-integrating documentation packages that accelerate multinational beverage conglomerate approval timelines.
- IoT sensor convergence:Real-time UV intensity monitoring combined with predictive maintenance algorithms enables outcome-based service contracts for remote vineyard operations.
Industry Challenges
- Electromechanical technician scarcity:Bottling line maintenance crews lack training in ozone generator electrode calibration and UV lamp spectral degradation assessment.
- CE marking timeline compression:EU Machinery Directive interlock protocol validation now requires 14-18 months, delaying revenue recognition for automated integration projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Bottle Sterilizer Market |
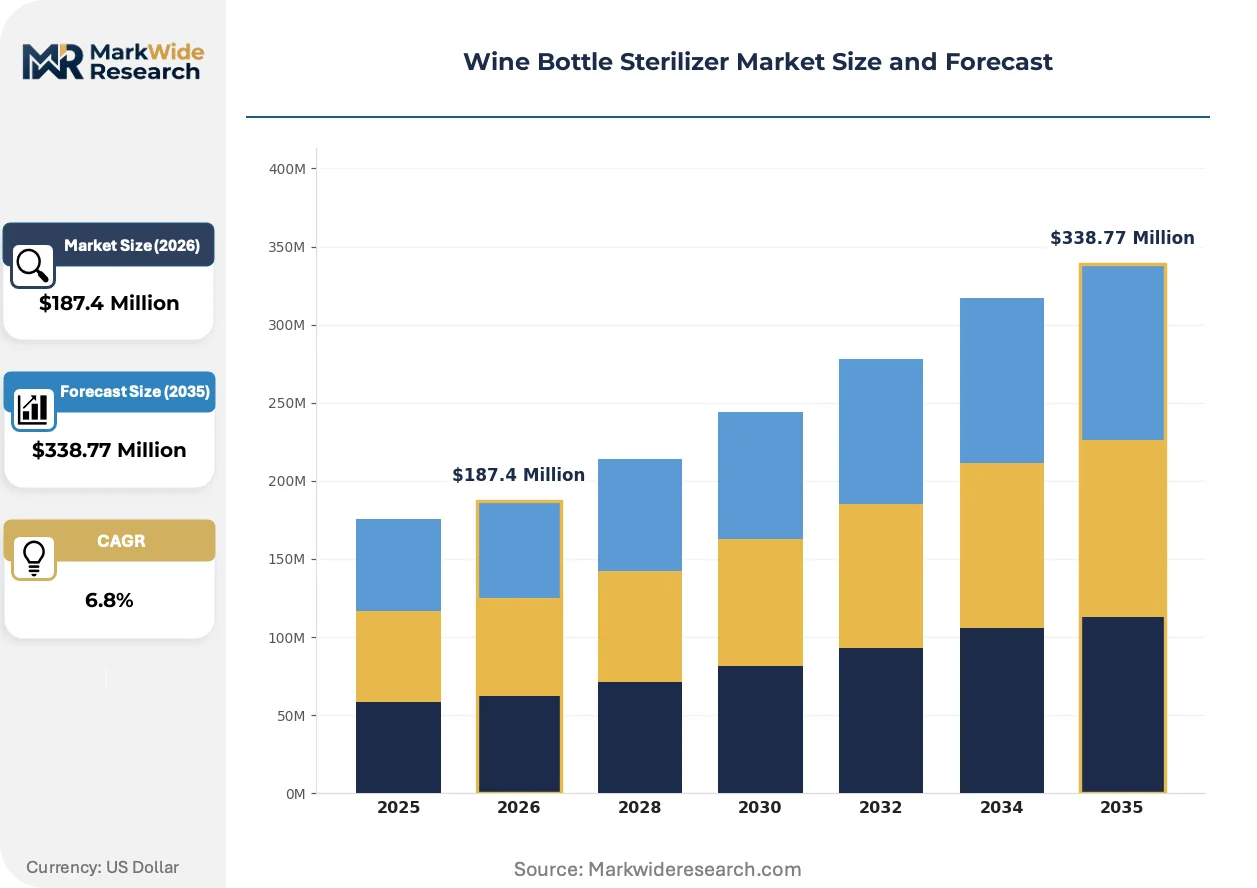
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sterilization Unit, UV Sanitizer, Ozone Sterilizer, Chemical Dilution System Technology: UV-C Light, Ozone Treatment, Heat Sterilization, Ultrasonic Cleaning End User: Winery, Retailer, Restaurant, Home User Application: Bottle Cleaning, Surface Disinfection, Preservation, Quality Control |
| Companies Covered | Papablic, Tommee Tippee, Baby Brezza, Momcozy, Grownsy, Philips Avent, Babymoov, Hauture, Dr. Brown's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Bottle Sterilizer Market Evolving Landscape
Active sterilization modalities are fragmenting as wineries pursue differentiated certification profiles. Technology vendors are responding with hybrid platforms that layer multiple kill mechanisms rather than optimizing single-method performance.
Pulsed UV-C systems is converging with advanced oxidation process controls to deliver variable-dose sterilization that adapts to bottle contamination load in real time. Champagne houses in Reims and Épernay are piloting these hybrid units for prestige cuvée production where Brettanomyces sensitivity peaks. The technology is converging with quality assurance workflows by embedding spectroscopic verification that eliminates manual sampling bottlenecks.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon refrigerants used in heat-sterilization cooling systems. This constraint forces cooperative wineries to evaluate thermal platform replacement earlier than depreciation schedules would dictate. Southern European mid-tier producers face the steepest compliance cost compression given their reliance on legacy steam infrastructure.
Equipment-as-a-service contracting is displacing capital purchase models among small-batch producers with volatile harvest volumes. French négociants and Italian cantina sociale cooperatives now prefer per-bottle pricing that transfers sterilization liability to vendors. This shift concentrates most visibly in Languedoc-Roussillon where vineyard fragmentation exceeds 4,000 individual growers.
Wine Bottle Sterilizer Market Segmentation
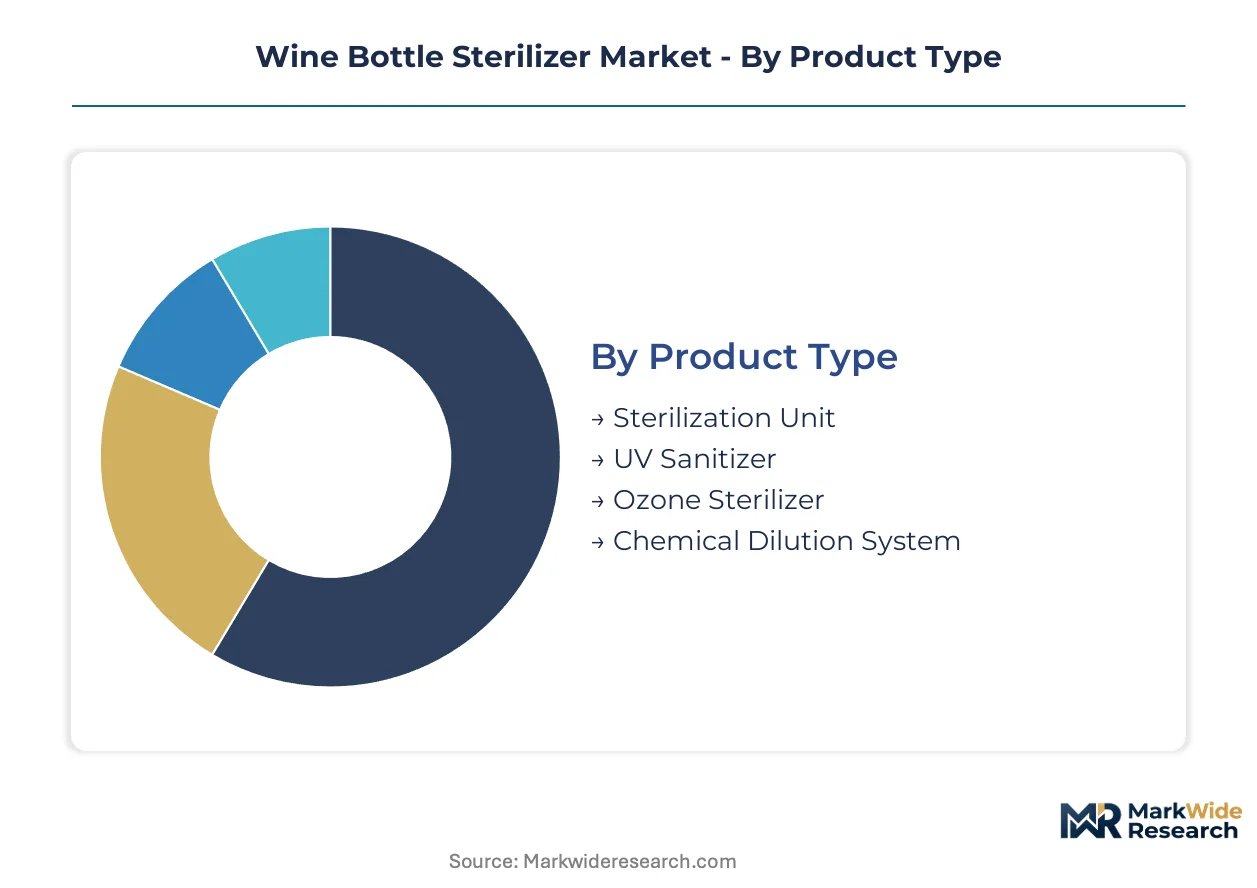
Wine bottle sterilizer procurement varies sharply by operational scale and regulatory exposure. Technology selection tracks directly against spoilage liability thresholds and export certification requirements rather than capital cost alone.
Technology:
Technology choice determines chemical residue profiles and energy intensity across bottling operations.
- UV-C Light:Systems deploy 254-nanometer mercury-vapor or LED arrays to disrupt microbial DNA without thermal loading or water consumption. Demand concentrates in Champagne houses and Bordeaux négociants where Brettanomyces sensitivity and water scarcity drive specification.
- Ozone Treatment:Corona-discharge or electrolytic generators produce triatomic oxygen for cold-sterilization of organic-sensitive packaging. Southern European cooperatives in Alentejo and Languedoc-Roussillon are deploying these units fastest to meet EU organic wine certification deadlines.
- Heat Sterilization:Steam or dry-heat tunnels maintain entrenched positions in Rioja and Piedmont cooperatives with fully amortized legacy infrastructure.
- Ultrasonic Cleaning:High-frequency cavitation systems target precision glassware in laboratory and small-batch artisanal settings.
Mature deployment sits with Heat Sterilization. Newer deployment is concentrated in Ozone Treatment.
End User:
Procurement authority and spoilage liability exposure shape equipment specification tiers.
- Winery:Estate and cooperative producers face direct vintage contamination liability and export compliance burdens. French Champagne houses and Italian cantina sociale cooperatives command the highest equipment specification tiers given batch value concentration.
- Restaurant:Sommelier-driven wine programs in Michelin-tier establishments deploy compact UV-C units for by-the-glass program integrity. Paris and Lyon restaurant clusters specify countertop systems with visible certification displays.
- Retailer:Wine merchants and tasting room operators require batch-scale units for private label bottling and sample preparation.
- Home User:Enthusiast collectors in urban markets purchase portable UV-C wands and cabinet systems for cellar management.
Equipment-as-a-service contracting is displacing capital purchases fastest among Winery end users with harvest volume volatility.
Product Type:
Form factor and integration depth track against facility footprint and line automation level.
- Sterilization Unit:Integrated conveyor systems dominate high-throughput cooperative bottling halls in France and Spain.
- UV Sanitizer:Modular cabinet and tunnel configurations serve mid-tier producers with seasonal volume fluctuation.
- Ozone Sterilizer:Mobile and fixed generator systems are expanding fastest in Portuguese and Greek vineyard consolidation zones.
- Chemical Dilution System:Peracetic acid and chlorine dioxide dosing equipment retains residual share in conventional agriculture zones.
Fixed infrastructure investment concentrates in Sterilization Unit deployments. Flexible capacity expansion favors UV Sanitizer procurement.
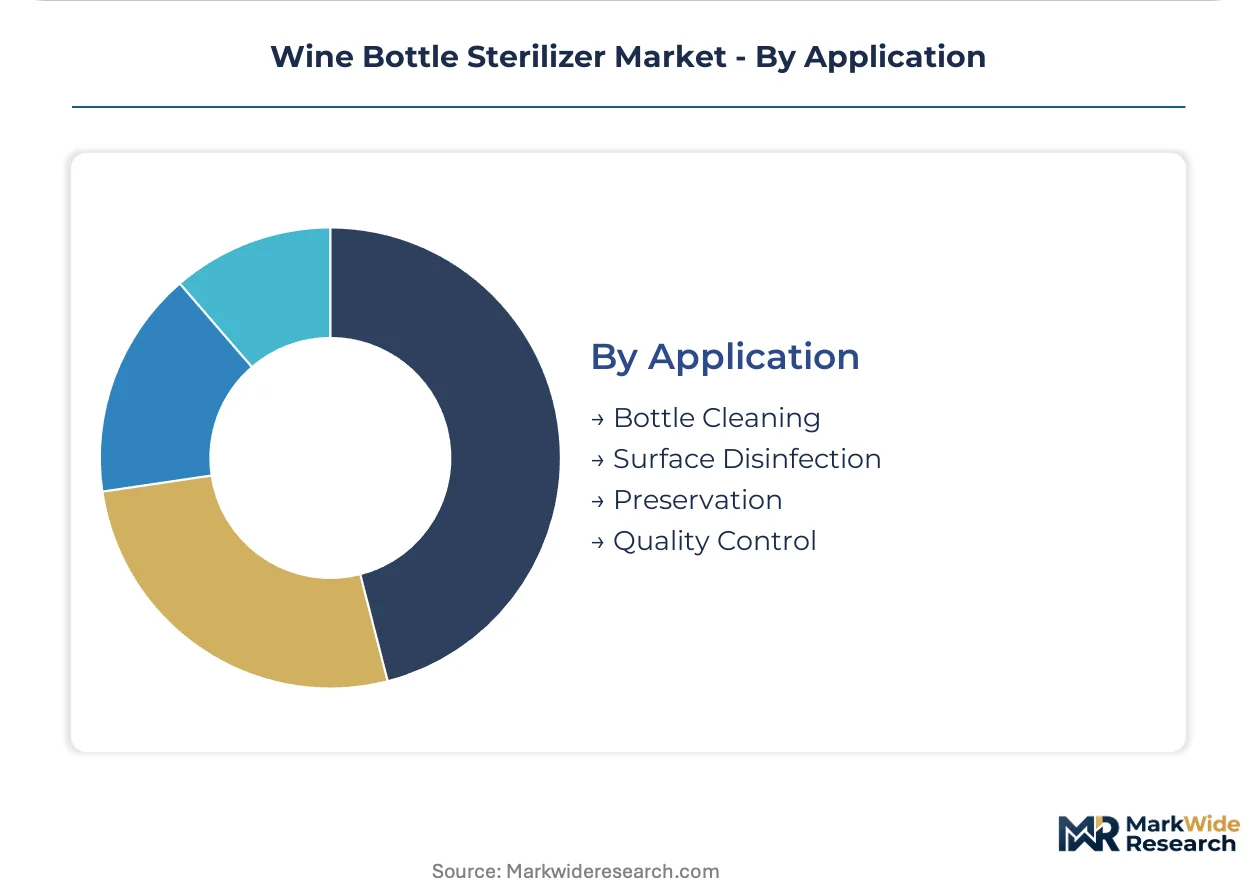
Application:
Functional specification varies by contamination risk point in the production workflow.
- Bottle Cleaning:Pre-fill sanitation of glass and PET containers represents the dominant application by installed base across all European wine regions.
- Quality Control:In-line verification and sampling protocols are gaining specification in AOC and DOCG production zones with traceability mandates.
- Surface Disinfection:Cork, capsule, and equipment sterilization supports packaging integrity in export-oriented facilities.
- Preservation:Post-bottling stabilization applications target low-sulfite and natural wine production segments.
Capital allocation concentrates in Bottle Cleaning. Fastest specification growth is occurring in Quality Control integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Champagne houses in Reims and Épernay drive premium equipment procurement across the European wine belt. Regulatory pressure from Brussels compounds with vineyard consolidation in Southern Europe to reshape sterilization infrastructure deployment.
France
Champagne producers and Bordeaux négociants command the highest specification tiers for Brettanomyces-sensitive production. EU REACH chemical restrictions force estate wineries to replace peracetic acid systems with UV-C platforms before export compliance deadlines. The Languedoc-Roussillon corridor sees fastest equipment-as-a-service adoption among fragmented vineyard cooperatives.
Italy
Cantina sociale cooperatives in Piedmont and Veneto face direct vintage contamination liability from export markets. CE marking requirements under the EU Machinery Directive now demand 14-18 month validation cycles for automated bottling integrations. Tuscan estates pilot hybrid pulsed UV-C systems for organic wine certification pathways.
Spain
Rioja cooperatives confront sunk-cost barriers from fully amortized steam infrastructure that still meets baseline regulatory thresholds. The EU F-Gas Regulation phase-down forces premature evaluation of thermal platform replacement. Catalonian facilities lead ozone treatment deployment for chemical-free cava production.
Portugal
Alentejo vineyard consolidation creates first-mover positioning for mobile sterilization service providers. The country's national food safety regulator enforces residue limits that favor non-chemical modalities. Lisbon-based equipment distributors report fastest quotation growth for modular ozone generators among mid-tier producers.
Germany
Precision ozone generator electrodes and high-grade UV lamp ballasts concentrate production in Bavarian and Baden-Württemberg manufacturing clusters. German component suppliers face capacity constraints as Southern European demand accelerates. Pfalz estate wineries anchor domestic demand for laboratory-grade verification systems.
Wine Bottle Sterilizer Market Competitive Landscape
The competitive structure tilts toward diversified appliance manufacturers with UV platform architectures. Market participation fragments across infant care brands repurposing existing sterilization expertise, industrial equipment specialists, and vineyard-focused service providers. Two archetypes dominate: consumer-appliance diversifiers leveraging R&D amortization across product lines, and industrial specialists capturing premium positioning through certification bundling. Competitive moves concentrate on geographic licensing partnerships and IoT-enabled outcome-based contracting.
Among consumer-appliance diversifiers, Papablic and Philips Avent occupy positions that exemplify compact UV-C engineering for space-constrained operations. Grownsy anchors the aggressive pricing tier for ozone treatment platforms. These three names represent the span from premium-brand cachet to volume-driven cooperative supply, with each archetype targeting distinct spoilage liability thresholds across the winery size spectrum.
| Leading Market Players |
|---|
| Papablic |
| Tommee Tippee |
| Baby Brezza |
| Momcozy |
| Grownsy |
| Philips Avent |
| Babymoov |
| Hauture |
| Dr. Brown's |
| Others |
Value Network & Pricing Analysis
UV-C LED wavelength optimization is compressing unit economics for high-throughput cooperatives while simultaneously concentrating ballast and electrode production in Southern German manufacturing clusters. This dual shift rewards vendors with captive component access and squeezes mid-tier assemblers facing quartz sleeve cost volatility.
Pricing Analysis
Throughput-linked outcome pricing anchors equipment procurement decisions across Champagne houses and Bordeaux négociants, where spoilage liability thresholds dwarf capital outlay considerations. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked automated integrations from semi-manual cabinet systems and entry-level portable units. Cost compression in mid-tier ozone platforms is intensifying because Portuguese and Greek distributors are consolidating procurement volumes. Small-batch vineyard cooperatives in Languedoc-Roussillon exhibit highest price sensitivity, while AOC-designated estates prioritize certification-grade specifications regardless of premium.
Supply Chain Analysis
Regional distribution centers in Lyon, Stuttgart, and Milan orchestrate hub-and-spoke fulfillment to fragmented vineyard clusters across the European wine belt. Precision ozone generator electrodes and high-grade UV lamp ballasts concentrate production in Bavarian and Baden-Württemberg manufacturing clusters, drawing from specialized quartz glass foundries and rare-earth phosphor suppliers. Single-source vulnerability in German component capacity creates bottleneck risk as Southern European demand accelerates. Distribution runs through vineyard equipment distributors with embedded technical service capabilities rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bavarian component capacity constraints are propping equipment pricing across all specification tiers, creating favorable margin dynamics for suppliers with secured electrode and ballast supply.
For Market Incumbents: Deploy certification bundling as the primary lever to deepen relationships with multinational beverage conglomerates facing ISO 22000 compliance deadlines. Backward integration into quartz sleeve production mitigates quarterly replacement cost volatility that threatens mid-tier positioning. Counter mobile sterilization service entrants by anchoring long-term service contracts with predictive maintenance algorithms. For New Entrants and Emerging Players: Capture underpenetrated vineyard consolidation in Portuguese Alentejo through modular ozone generator platforms with per-bottle pricing terms. Target equipment-as-a-service contracting gaps among Italian cantina sociale cooperatives with volatile harvest volumes. Accelerate market entry via Lisbon-based distributor partnerships that bypass CE marking timeline compression. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified appliance manufacturers seeking UV platform architecture expansion. Long-term viability hinges on vendors capturing IoT-enabled outcome-based contract share among remote vineyard operations. Monitor EU F-Gas Regulation enforcement intensity as the signal indicating accelerated thermal platform replacement cycles and corresponding demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | Shortened validation cycles capture automated bottling integration revenue before competitor approval. |
| IoT Sensor Convergence | Real-time UV intensity monitoring enables predictive maintenance contracts for remote Alentejo vineyards. |
| Component Backward Integration | In-house quartz sleeve production insulates margins from Bavarian supply constraints. |
| Mobile Service Deployment | First-mover positioning in Portuguese vineyard consolidation zones bypasses fixed infrastructure competition. |
| ISO 22000 Bundling | Pre-integrated documentation packages accelerate multinational beverage conglomerate approval timelines. |
Research Methodology
Multi-period observation of equipment replacement cycles, regulatory compliance deadlines, and vineyard consolidation patterns anchored the trend analysis, supplemented by interviews with bottling line engineers, cooperative procurement managers, CE marking consultants, and German component suppliers. Secondary validation drew from EU Machinery Directive filings, ECHA REACH restriction updates, customs trade data for ozone generator imports, and SEC disclosures from diversified appliance manufacturers. Bottom-up equipment deployment counts triangulated against top-down winery capital expenditure surveys.
Segment-weighting applied technology modality shares, end-user operational scale distributions, and regional regulatory exposure clusters across the projection horizon. Modeled dimensions spanned sterilization technology type, winery size tier, export certification requirements, and regional vineyard consolidation intensity. CAGRs derived from equipment replacement cycle compression rates overlaid with regulatory mandate timing. Forecast inputs incorporated quartz sleeve degradation curves and EU F-Gas Regulation phase-down schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electromechanical technician training pipeline expansion and evolving national interpretations of chemical residue limits. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Gin and Tonic Tea Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market
Alcoholic Beverages
Barware Market
Alcoholic Beverages
Middle East and Africa Fermented Drinks Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
Global Brewery Filtration Market
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Bayberry Wine Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
Germany Wine Coolers Market
Alcoholic Beverages
Dark Beer Market
Alcoholic Beverages
Alcoholic Beverages Market
Alcoholic Beverages
North America Alcoholic Beverages Market