
 Europe Tequila Market | 2026-2036
Europe Tequila Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tequila Market Insights
Agave sourcing expertise is bifurcating the competitive landscape as established importers struggle to secure certified supply against rising European demand. Jose Cuervo leverages its captive Jalisco estate network to guarantee volume consistency across German and British retail chains. Patrón sustains premium positioning through small-batch tahona production narratives that resonate with affluent urban consumers. Espolon competes on accessible price points and bold visual branding that dominates shelf space in Southern European markets.
Tequila denotes a distilled spirit manufactured exclusively from Weber blue agave in five designated Mexican states, with fermentation yielding alcohol content typically between 35% and 55% ABV and aging duration determining classification from unaged Blanco through oak-rested Reposado to barrel-matured Añejo and Extra Añejo expressions. Blanco captures the highest volume share among entry-level buyers seeking mixology versatility, while Reposado and Añejo concentrate margin pools as on-trade venues in London, Berlin, and Barcelona elevate tequila toward whiskey-style sipping rituals. Distribution through bars and restaurants outpaces retail growth as bartender education programs expand agave literacy and premium pour rates.
The EU Spirits Regulation defines minimum alcohol content and labeling requirements for tequila sold within member states, while EFSA guidelines on health claims constrain marketing language around production methods. REACH compliance affects imported glass and packaging materials, adding certification layers for non-European bottlers. Stakeholders must monitor pending revisions to EU-Mexico trade facilitation measures and evolving sustainability disclosure rules that could reshape supplier qualification criteria.
Market Dynamics
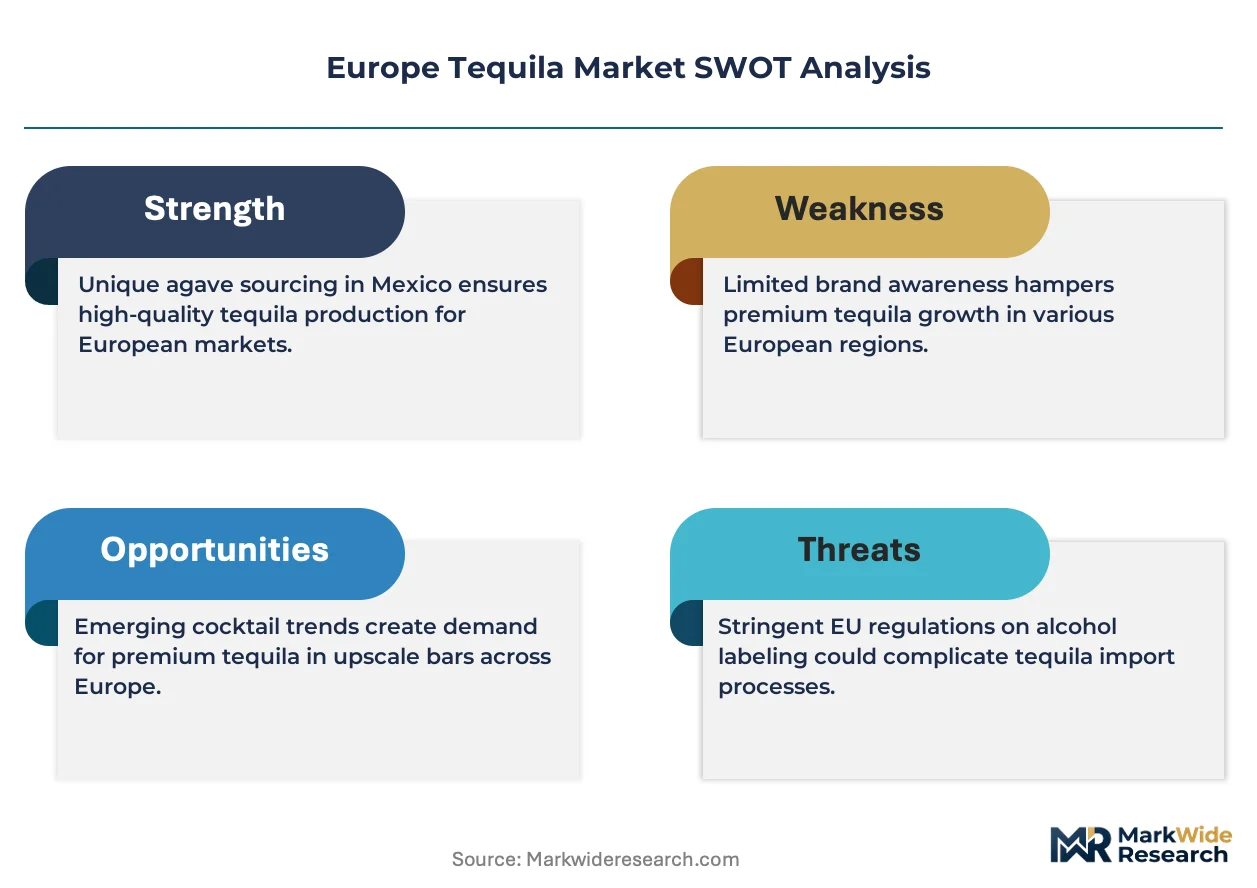
Agave supply certification under EU Spirits Regulation and emerging sustainability disclosure rules are restructuring importer qualification criteria across European distribution networks.
Growth Catalysts
- EU-Mexico Trade Facilitation:Pending revisions to bilateral agreements streamline customs processing for Jalisco-origin shipments entering German and Spanish ports.
- Cocktail Culture Professionalization:Bartender education programs in London, Berlin, and Barcelona expand agave literacy and elevate premium pour rates in on-trade venues.
- Agave Sustainability Certification:ESG-aligned procurement policies at British and German retail chains prioritize suppliers with verified estate-level water stewardship.
Market Restraints
- Agave Price Volatility:Weber blue agave harvest cycles concentrate input cost risk for non-vertically integrated bottlers sourcing from Jalisco highlands.
- REACH Compliance Burden:Certification layers for imported glass and packaging materials delay time-to-market for new market entrants.
- Whiskey Substitution Threat:Mature sipping rituals in Scottish and Irish whiskey categories compete for share of wallet among affluent European consumers.
Strategic Opportunities
- Polish and Romanian Distribution:Underpenetrated Eastern European markets present first-mover positioning for brands establishing retail presence ahead of category maturation.
- Direct-to-Consumer Channels:E-commerce platforms bypass traditional three-tier distribution, enabling margin capture and customer data ownership.
- EU Green Deal Alignment:Carbon footprint labeling requirements favor producers with renewable energy distillation and regenerative agriculture narratives.
Industry Challenges
- Agave Agronomy Expertise Gap:European importers lack in-house botanists to verify estate-level cultivation claims, creating reliance on third-party auditors.
- Extended Certification Timelines:EFSA health claim reviews and EU Spirits Regulation label approvals stretch product launch schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tequila Market |
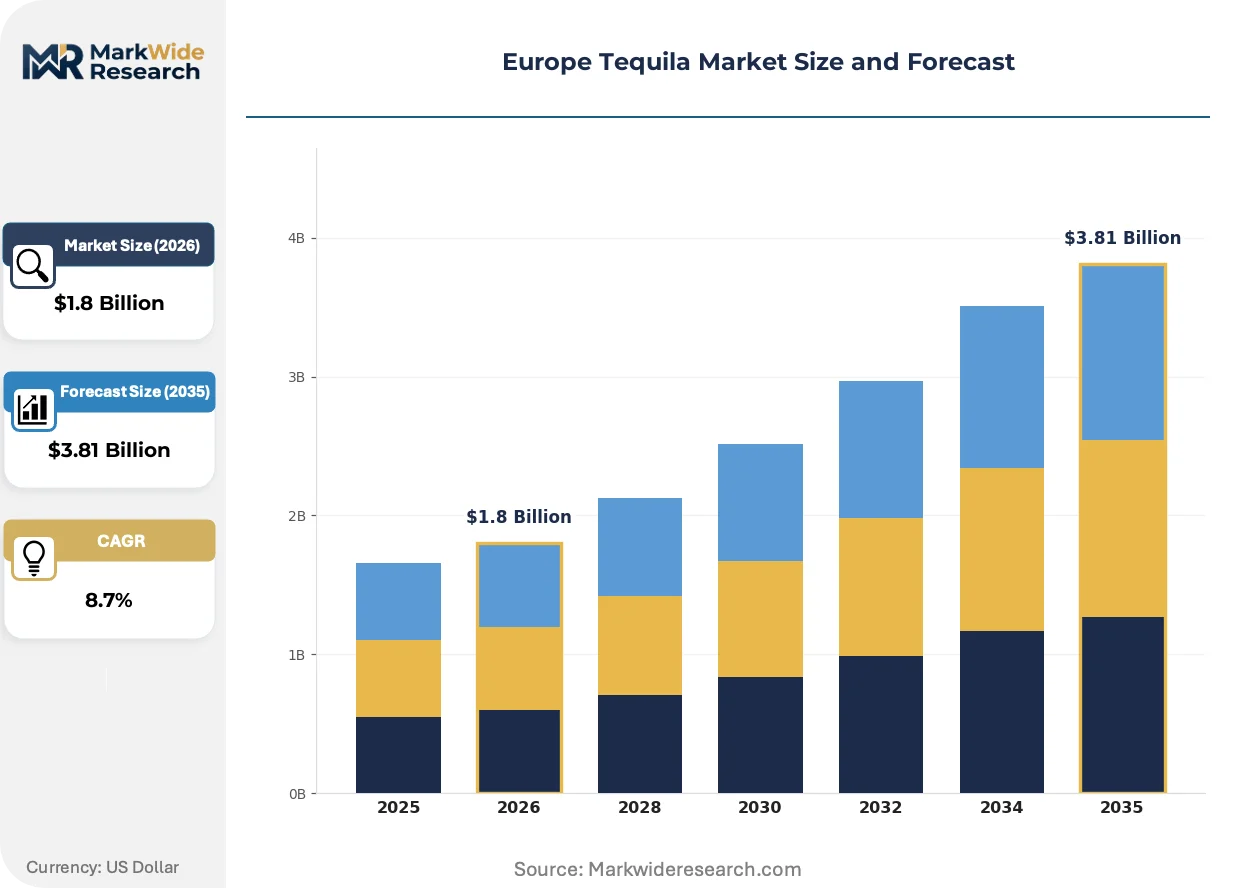
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blanco, Reposado, Añejo, Extra Añejo Distribution Channel: Retail Stores, Online, Bars, Restaurants Consumer Demographics: Millennials, Gen X, Baby Boomers, Affluent Consumers Flavor Profile: Herbal, Citrus, Spicy, Sweet |
| Companies Covered | Jose Cuervo, Patrón, Don Julio, Espolon, 1800 Tequila, El Jimador, Cazadores, Sierra Tequila, Olmeca, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tequila Market Trends and Innovations
Tahona stone milling and diffuser extraction methods are diverging as production philosophies, with premium positioning increasingly tied to artisanal process transparency rather than scale efficiency.
Diffuser technology is supplanting traditional roller mill crushing in volume-oriented production facilities seeking higher sugar extraction rates from agave piñas. Mass-market bottlers serving Southern European retail chains adopt diffusers to maintain price competitiveness against vodka and rum alternatives. This mechanization is compressing the cost structure for entry-level Blanco expressions while creating perceptual distance from premium tahona-produced competitors.
REACH compliance enforcement through ECHA is tightening documentation requirements for imported glass bottles and closure materials used in tequila packaging. Non-European bottlers must now submit full substance safety data sheets prior to customs clearance. German and Dutch importers bear the highest compliance burden as they handle the largest share of bulk shipments entering the EU.
On-trade venues in Madrid, Manchester, and Munich are unbundling tequila from traditional shot service toward whiskey-style sipping presentations with dedicated glassware and food pairing menus. Bartender-led education sessions replace speed-pour conventions with aroma wheel terminology and terroir storytelling. Southern European markets lag Northern counterparts in this behavioral shift, maintaining stronger shot-culture volume concentration.
Europe Tequila Market Segmentation
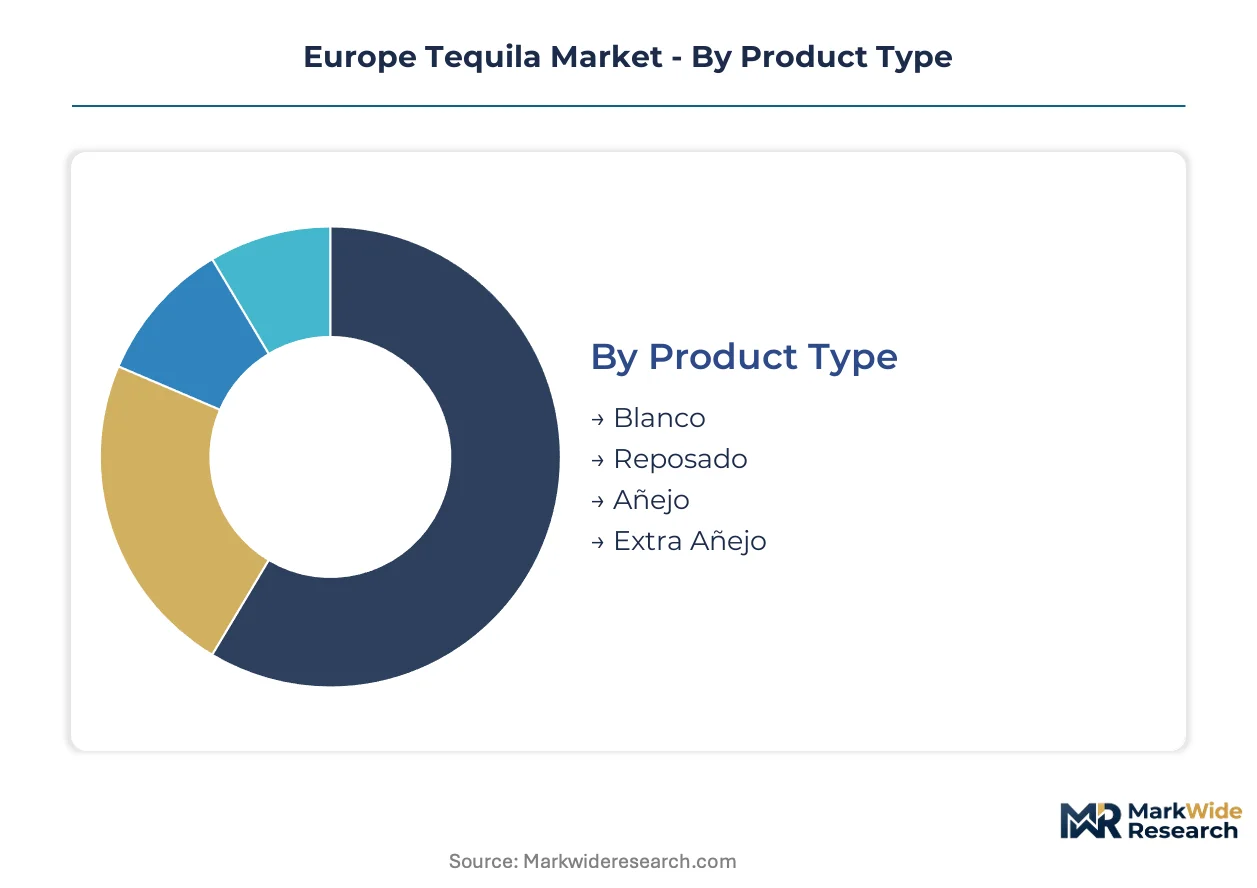
Tequila segmentation in Europe reflects divergent regulatory pathways and consumption rituals. EU Spirits Regulation classification rules, REACH packaging mandates, and ESG procurement policies reshape how categories perform across German retail shelves and Spanish on-trade venues.
Product Type:
EFSA labeling requirements and EU Spirits Regulation aging definitions create distinct compliance burdens across each classification tier.
- Blanco:Unaged expressions bottled directly after distillation preserve raw agave character with 35-55% ABV. German and British retail chains stock Blanco as the entry point for home mixology, constrained by volume-oriented pricing pressure from vodka alternatives.
- Reposado:Oak-rested for two months to one year, Reposado captures the margin migration as London and Berlin bars elevate tequila toward whiskey-style sipping rituals. EFSA health claim restrictions limit producers from marketing oak-derived compounds, forcing reliance on terroir narratives.
- Añejo:Barrel-matured for one to three years, commanding premium positioning in Manchester and Munich venues with dedicated glassware programs.
- Extra Añejo:Extended aging beyond three years, concentrated in ultra-premium allocations for affluent urban consumers in Barcelona and Paris.
Blanco handles the majority of throughput; Reposado is the fastest mover on share.
Distribution Channel:
Cost tier differentiation separates mass-market accessibility from premium margin capture across European touchpoints.
- Retail Stores:Supermarkets and specialist spirits merchants in Germany and the United Kingdom dominate volume throughput. REACH compliance documentation for imported glass bottles adds 8-14 month lead times for new SKU introductions.
- Bars:On-trade venues in Madrid and Barcelona drive premium pour rates through bartender education programs expanding agave literacy. EU Green Deal procurement policies favor suppliers with carbon footprint labeling.
- Restaurants:Food pairing menus in London and Berlin elevate tequila toward digestif positioning alongside whiskey and cognac.
- Online:E-commerce platforms bypass traditional three-tier distribution, enabling direct margin capture and customer data ownership for brands with established fulfillment infrastructure.
Retail Stores handle the majority of throughput; Online is expanding most quickly as regulatory clarity on cross-border alcohol shipping solidifies.
Consumer Demographics:
Application-based segmentation maps consumption occasions to generational purchasing power and ritual adoption speed.
- Millennials:Cocktail culture participants in London and Berlin drive demand for craft presentation and transparent sourcing narratives. This cohort shows highest receptivity to sustainability certification claims under EU Green Deal alignment.
- Affluent Consumers:High-net-worth individuals in Paris and Munich concentrate spending on Extra Añejo and limited estate bottlings. Price insensitivity enables margin extraction for tahona-produced expressions with verified Jalisco highland provenance.
- Gen X:Established whiskey drinkers in Edinburgh and Dublin represent conversion targets for sipping-format migration.
- Baby Boomers:Traditional spirits consumers in Southern European markets maintaining stronger shot-culture volume concentration.
Millennials handle the majority of throughput; Affluent Consumers are climbing the fastest on premium share.
Flavor Profile:
Volume concentration in Southern European markets favors approachable sweetness, while Northern markets reward complexity.
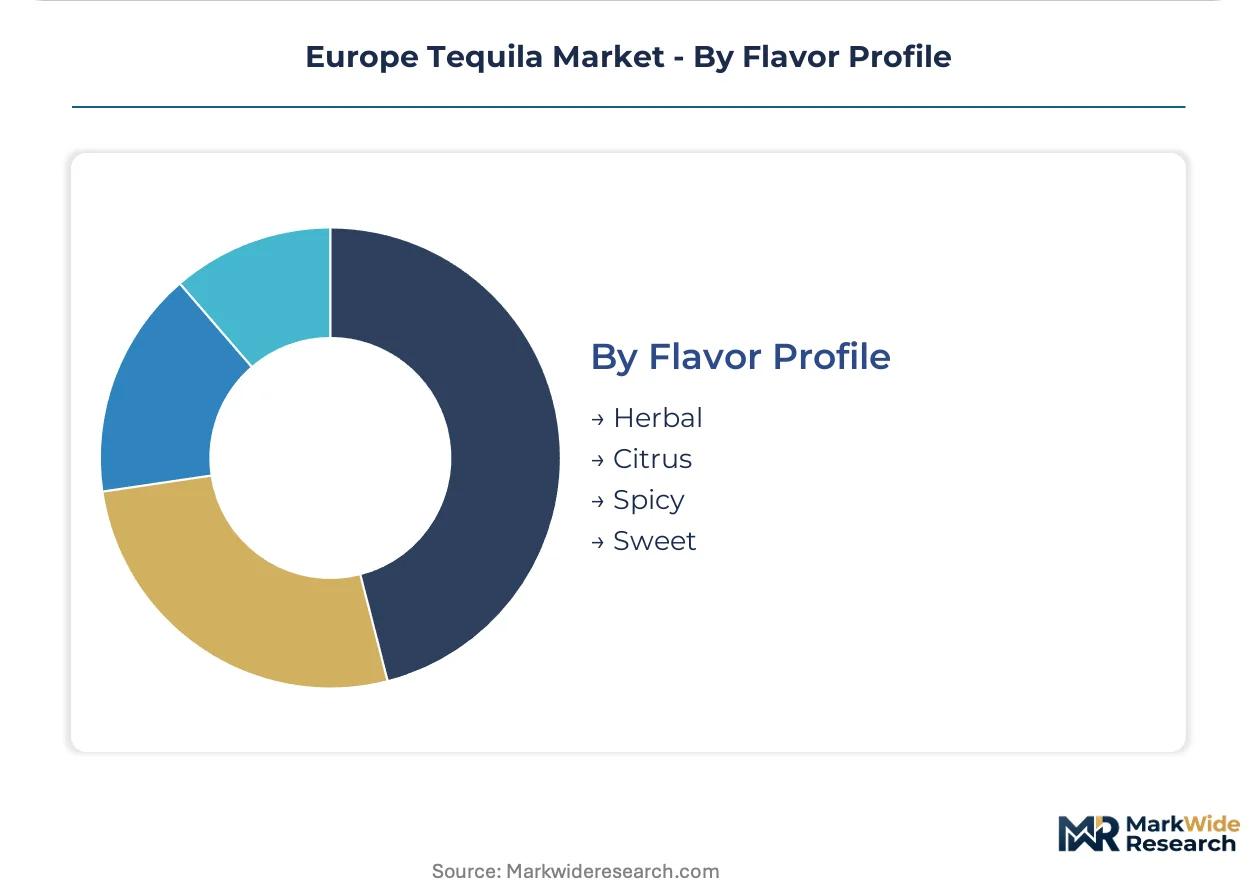
- Citrus:Bright, acidic expressions dominate Mediterranean markets and summer cocktail applications. Spanish importers prioritize citrus-forward Blancos for retail chains serving tourism-dependent coastal regions.
- Herbal:Vegetal, grassy notes align with bartender education programs in Berlin and Amsterdam emphasizing terroir differentiation. This profile commands premium positioning through small-batch production narratives.
- Spicy:Pepper-forward expressions appeal to whiskey crossover drinkers in Glasgow and Belfast seeking comparable heat profiles.
- Sweet:Caramel and vanilla notes from extended oak contact concentrate in Añejo and Extra Añejo allocations for dessert pairing menus.
Citrus handles the majority of throughput; Herbal is gaining share fastest as mixology professionalization spreads northward.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German on-trade venues treat tequila as a sipping spirit alongside whiskey, while Spanish establishments retain stronger shot-culture volume concentration. British consumers drive premiumization through cocktail professionalization. This consumption-mix differential shapes importer strategies across the region.
Germany
Berlin and Munich bars elevate Reposado and Añejo expressions through dedicated glassware programs and food pairing menus. REACH enforcement through ECHA tightens documentation requirements for imported glass bottles entering Hamburg and Bremen ports. Bavaria's hospitality sector concentrates ultra-premium allocations for affluent urban consumers seeking verified Jalisco highland provenance.
United Kingdom
London bartender education programs expand agave literacy and drive premium pour rates in Mayfair and Shoreditch venues. EFSA guidelines on health claims constrain marketing language around production methods and oak-derived compounds. Manchester and Edinburgh represent conversion targets for whiskey drinkers migrating toward sipping-format tequila rituals.
Spain
Madrid and Barcelona on-trade venues unbundle tequila from traditional shot service toward whiskey-style presentations. EU Spirits Regulation defines minimum alcohol content and labeling requirements for all agave spirits sold within member states. Andalusian retail chains maintain higher Blanco throughput for tourism-dependent coastal regions seeking approachable price points.
France
Parisian affluent consumers concentrate spending on Extra Añejo and limited estate bottlings with price-insensitive demand patterns. EU Green Deal procurement policies favor suppliers with carbon footprint labeling and renewable energy distillation narratives. Île-de-France hospitality clusters import directly from verified estates to bypass traditional distribution markups.
Poland
Warsaw and Krakow present underpenetrated first-mover positioning for brands establishing retail presence ahead of category maturation. Pending revisions to EU-Mexico trade facilitation agreements streamline customs processing for Jalisco-origin shipments entering Baltic ports. Polish distributors lack in-house agave agronomy expertise, creating reliance on third-party auditors for estate-level verification.
Europe Tequila Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Europe Tequila Market. Captive estate networks guarantee volume consistency for vertically integrated bottlers serving German and British retail chains. Three archetypes dominate: heritage houses with Jalisco land holdings, premium positioning specialists emphasizing artisanal production narratives, and accessible-price challengers competing for Southern European shelf space. Competitive moves concentrate on securing certified agave supply and expanding bartender education partnerships.
Within the heritage house tier, Jose Cuervo anchors volume throughput through its captive estate network. Patrón occupies a position exemplifying premium tahona production narratives that resonate with affluent urban consumers. Espolon represents the accessible-price challenger archetype, competing through bold visual branding for shelf space dominance in Southern European markets.
| Leading Market Players |
|---|
| Jose Cuervo |
| Patrón |
| Don Julio |
| Espolon |
| 1800 Tequila |
| El Jimador |
| Cazadores |
| Sierra Tequila |
| Olmeca |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Jalisco estate holders and German importers lock in volume commitments and price visibility across harvest cycles. These contracts insulate vertically integrated bottlers from spot-market agave volatility while exposing non-integrated competitors to input cost surges.
Pricing Analysis
Long-term offtake structures dominate premium tier procurement, with price differentiation driven by certification grade under EU Spirits Regulation and volume scale commitments. Cost compression in entry-level Blanco expressions intensifies as diffuser-equipped producers compete against vodka alternatives. British retail chains exhibit highest price sensitivity, while Parisian affluent consumers demonstrate least elasticity for verified estate bottlings.
Supply Chain Analysis
Container availability fluctuations on the Veracruz-Hamburg trade lane elevate inbound logistics costs for bulk shipments entering German ports. Geographic supply concentrates in Jalisco, Guanajuato, and Michoacán, with raw material dependencies on mature Weber blue agave piñas, oak barrel staves, and closure cork. Single-source vulnerability from Jalisco highland estate concentration creates exposure to climate-induced harvest shortfalls. Distribution runs through three-tier wholesale networks anchored in Hamburg, Rotterdam, and Barcelona.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's tequila market represents early-cycle expansion as cocktail culture professionalization drives adoption beyond shot rituals toward sipping formats. Bartender education programs in London and Berlin accelerate penetration among whiskey-converting demographics.
For Market Incumbents: Consolidate agave supply access through captive estate acquisitions or exclusive offtake amendments before EU sustainability disclosure rules tighten qualification criteria. Deepen backward integration into Jalisco highland cultivation to defend margin position against rising spot-market input costs. Prioritize bartender education partnerships in Manchester and Edinburgh to accelerate sipping-format conversion.
For New Entrants and Emerging Players: EU organic certification fast-tracks offer positioning leverage in ESG-aligned British and German retail chains seeking verified estate-level water stewardship. Polish and Romanian distribution networks present underpenetrated white-space with limited incumbent shelf-lock. Direct-to-consumer e-commerce platforms enable margin capture and customer data ownership without three-tier distribution markups.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with captive Jalisco estate networks and established EU import infrastructure. Long-term viability across a 5-10 year horizon hinges on sustainability certification compliance ahead of evolving EU-Mexico trade facilitation measures. Monitor bartender education program expansion rates as inflection indicator for premium pour velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Estate-Level Sustainability Certification | EU Green Deal alignment secures retail chain procurement preference in Germany and Britain. |
| Bartender Education Partnership | Agave literacy programs in London and Berlin drive premium pour rate elevation. |
| Direct-to-Consumer Channel Launch | E-commerce platforms bypass three-tier distribution for margin capture and data ownership. |
| Backward Integration into Cultivation | Captive Jalisco estate networks guarantee volume consistency against harvest volatility. |
| Eastern European Distribution Expansion | First-mover positioning in Poland and Romania ahead of category maturation. |
Research Methodology
The analysis maps Blanco, Reposado, Añejo, and Extra Añejo segments, each validated through primary interviews with Mexican estate operators, German import executives, British retail category buyers, and Spanish on-trade beverage directors. Secondary sources include EU Spirits Regulation filings, ECHA REACH documentation, EFSA health claim registers, and bilateral trade facilitation records. Bottom-up volume builds triangulate against top-down category spend estimates.
Consistency checks validate outputs against external benchmarks including customs shipment manifests and hospitality procurement databases. The analytical framework models product type, distribution channel, consumer demographic, and flavor profile dimensions across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by price realization trends and regulatory pathway impacts.
Underlying assumptions cover sustained EU-Mexico trade facilitation, stable agave harvest yields, and incremental bartender education program expansion, with deviation risk concentrated in climate-induced input shortages and REACH compliance timeline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Brazil Alcohol E-Commerce Market
Alcoholic Beverages
Cider and Perry Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Fruit Wine Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Flavored Whiskey Market
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
United States Beer Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Middle East and Africa Kegs Market