
 US Non-Alcoholic Beverages Market | 2026-2036
US Non-Alcoholic Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
US Non-Alcoholic Beverages Market Insights
FDA Nutrition Facts labeling reform is hardening the cost-of-entry calculus for new entrants. The Coca-Cola Company leverages its bottling infrastructure to absorb compliance costs across multiple product lines. PepsiCo sustains reformulation investments in low-sugar variants to maintain shelf placement in regulated retail environments. Monster Beverage Corporation differentiates through energy-drink-specific caffeine disclosure protocols that exceed baseline federal requirements.
Non-alcoholic beverages comprise formulated and unformulated drinkable liquids excluding ethanol-based products, typically manufactured through blending, carbonation, pasteurization, or reverse osmosis filtration to achieve specified pH, brix, and shelf-stability parameters. These products serve hydration, refreshment, nutritional supplementation, and functional performance purposes across consumer and foodservice channels. Bottled water and sports drinks represent the fastest-expanding product type segments as fitness culture permeates mainstream consumption patterns. Supermarkets and online retail channels capture disproportionate margin pools through direct-to-consumer subscription models and private-label placement strategies.
USDA organic certification standards and EPA water quality regulations intersect with FDA food additive approvals to create a multi-layered compliance architecture for ingredient sourcing and label claims. State-level sugar taxes in select jurisdictions compound federal disclosure mandates, forcing national portfolios to accommodate regional formulation variations. Stakeholders must monitor pending front-of-package labeling proposals and their potential to reorder competitive positioning across convenience store and vending channels.
Market Dynamics
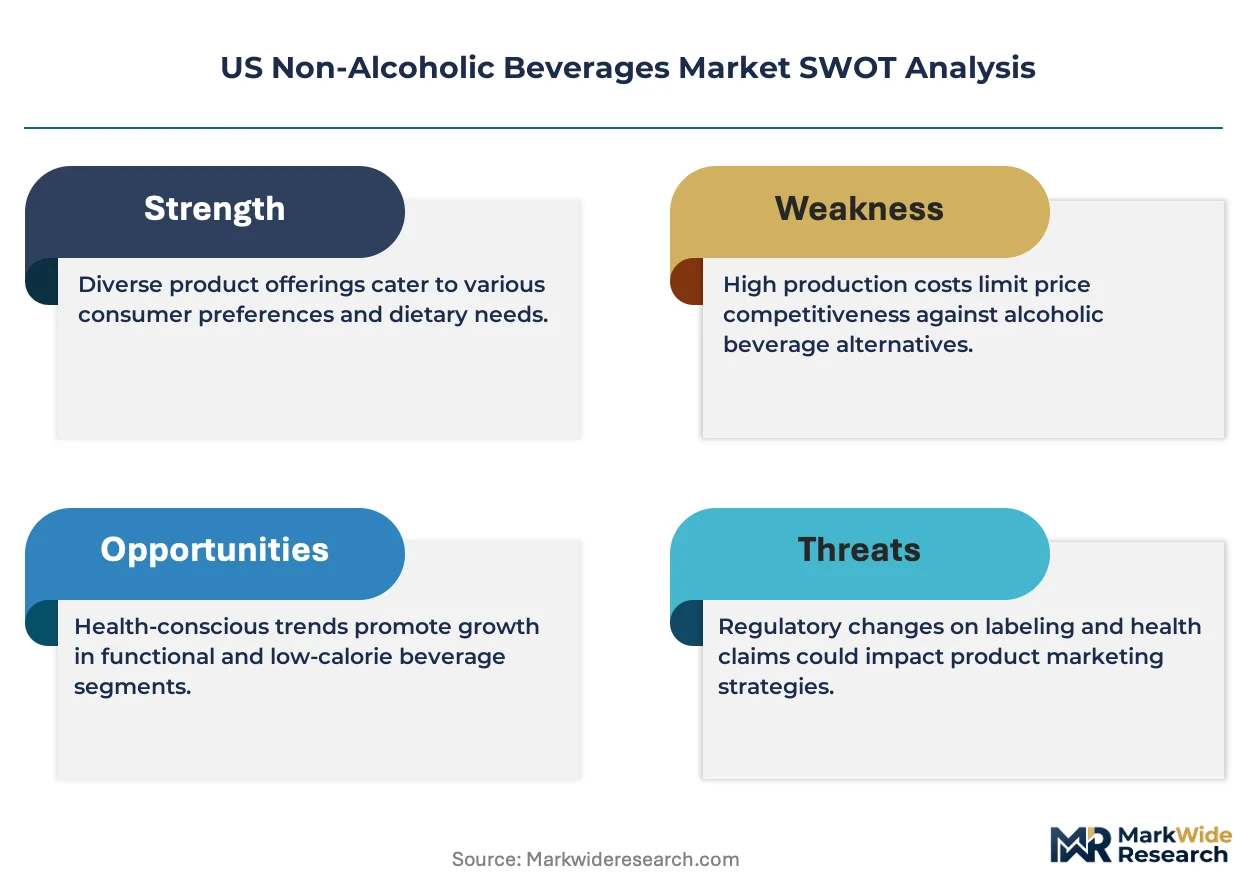
FDA's updated Nutrition Facts labeling requirements are compressing formulation cycles and forcing portfolio-wide reformulation investments that favor scaled manufacturers with centralized R&D infrastructure.
Growth Catalysts
- California metropolitan demand clusters:Fitness and wellness program participation in Los Angeles and San Francisco corridors drives premium functional beverage consumption. Health-conscious consumers prioritize electrolyte-enhanced and adaptogenic formulations.
- USDA organic certification standards:Clean-label procurement mandates from institutional foodservice buyers create certified supply chain premiums. Organic ingredient sourcing contracts now span multi-year horizons.
- Reverse osmosis filtration technology:Bottled water producers deploy advanced purification systems to achieve specified mineral content and pH stability. Equipment upgrades enable shelf-life extension without chemical preservatives.
Market Restraints
- High-fructose corn syrup price volatility:Commodity input fluctuations compress margin predictability for sweetened carbonated portfolios. Hedging costs accumulate across quarterly procurement cycles.
- Multi-layered compliance architecture:Intersection of FDA food additive approvals, EPA water quality regulations, and state-level sugar taxes forces regional formulation variations. National distribution requires SKU proliferation.
- Tap water infrastructure quality improvements:Municipal filtration investments in Northeast corridor states reduce bottled water necessity perception. Consumer substitution toward filtered tap accelerates in urban cores.
Strategic Opportunities
- Direct-to-consumer subscription models:Online retail channels capture recurring revenue through personalized hydration and functional beverage deliveries. Data-driven flavor profiling enables micro-batch customization.
- Front-of-package labeling proposals:Pending FDA initiatives to mandate simplified nutritional scoring create first-mover advantages for reformulated portfolios. Early compliance investments preempt competitive displacement.
- Foodservice fountain system modernization:Post-mix equipment upgrades in convenience store and vending channels enable real-time flavor customization. IoT-enabled dispensers track consumption patterns for inventory optimization.
Industry Challenges
- Flavor chemist talent scarcity:Specialized formulation expertise for sugar reduction without taste compromise commands premium compensation. Recruitment pipelines struggle to match R&D expansion timelines.
- Legacy ERP integration with traceability systems:Batch-level ingredient tracking requirements strain existing enterprise software architectures. Custom middleware development extends compliance implementation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Non-Alcoholic Beverages Market |
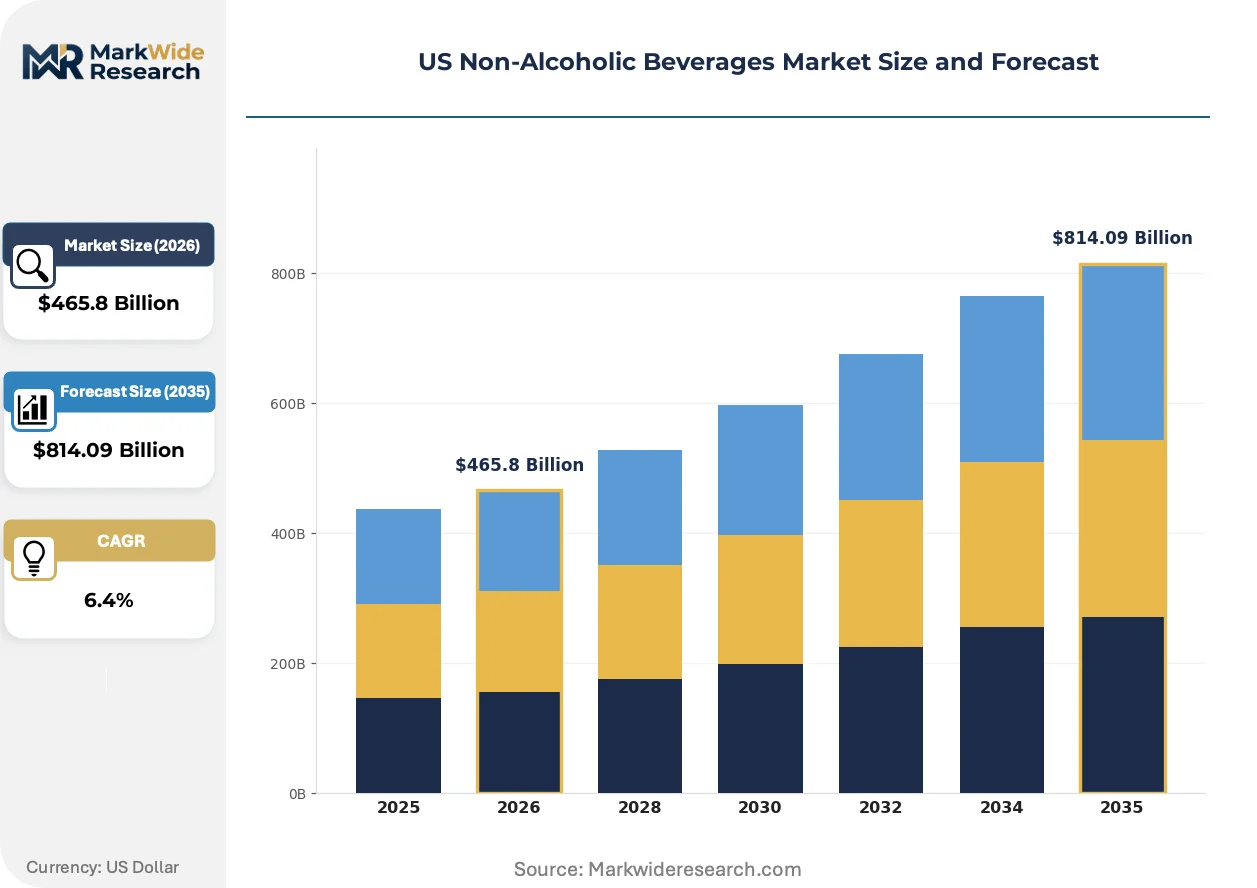
| Market Size in 2026 | $465.8 Billion |
| Market Size in 2035 | $814.09 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodas, Juices, Bottled Water, Sports Drinks Customer Type: Health Conscious, Millennials, Families, Teens Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Restaurants Packaging Type: Cans, Glass Bottles, Plastic Bottles, Tetra Packs |
| Companies Covered | Nestlé, Monster Beverage Corporation, The Coca-Cola Company, Unilever, Danone, PepsiCo, Red Bull GmbH, Cott Corporation, Keurig Dr Pepper, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Non-Alcoholic Beverages Market Trends and Innovations
Reformulation pressure, filtration technology advancement, and channel digitization are converging to reshape competitive positioning across hydration and functional beverage categories.
Reverse osmosis membrane technology paired with remineralization dosing systems is decentralizing purified water production from centralized bottling plants to point-of-use installations. Convenience store operators and corporate campus foodservice providers are adopting compact filtration units that bypass traditional distribution economics. This distributed production model compresses transportation cost structures while enabling hyper-local branding narratives.
The FDA's updated Nutrition Facts labeling requirements mandate added sugars disclosure and revise serving size definitions to reflect actual consumption patterns. Beverage manufacturers must reformulate or face shelf placement penalties in regulated retail environments. Low-sugar and zero-sugar variants receive disproportionate promotional support from supermarket buyers seeking to preempt regulatory scrutiny.
Subscription-based replenishment models are displacing intermittent retail purchasing for routine hydration products. Fitness enthusiasts and remote workers in California and Northeast corridor states prioritize automated delivery schedules over convenience store trips. Direct-to-consumer platforms capture lifetime value through flavor rotation algorithms and loyalty-linked nutritional coaching services.
US Non-Alcoholic Beverages Market Segmentation
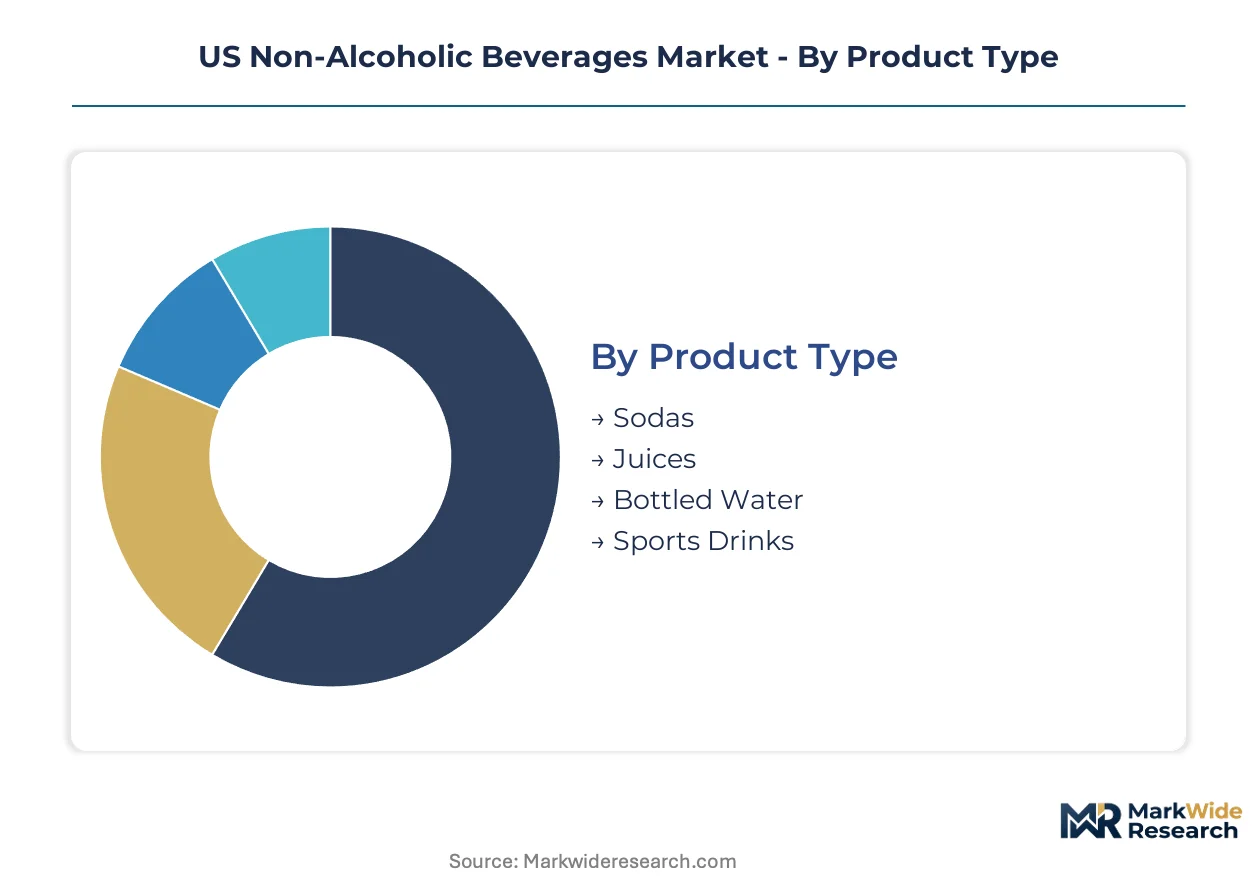
Segmentation in the US non-alcoholic beverages market reveals how formulation priorities, channel economics, and demographic targeting intersect. Manufacturers configure production lines and procurement contracts around these axes to optimize margin capture across distinct consumption occasions.
Product Type:
Formulation complexity and ingredient sourcing requirements differentiate production economics across beverage categories.
- Bottled Water:Reverse osmosis filtration and remineralization dosing systems define quality tiers. Demand clusters in California metropolitan corridors and Northeast corridor states where municipal tap quality perceptions drive substitution. Premium positioning depends on pH stability claims and EPA-compliant source protection narratives.
- Sports Drinks:Electrolyte concentration profiles and carbohydrate loading specifications serve fitness program participants. Health-conscious consumers in Los Angeles and San Francisco corridors prioritize adaptogenic and low-sugar formulations. FDA Nutrition Facts labeling reform pressures sugar reduction without taste compromise.
- Sodas:Carbonation intensity and sweetener systems—cane sugar, beet sugar, or high-fructose corn syrup—determine regional formulation variations. State-level sugar taxes force SKU proliferation for national distribution.
- Juices:Pasteurization methods and pulp content specifications segment not-from-concentrate from reconstituted offerings. USDA organic certification standards create supply chain premiums for clean-label procurement.
Mature deployment sits with Sodas. Newer deployment is concentrated in Bottled Water.
Customer Type:
Purchasing frequency and price elasticity vary sharply across demographic cohorts, reshaping promotional calendar design.
- Health Conscious:Nutritional supplementation and functional performance claims drive repeat purchase. Subscription-based replenishment models capture lifetime value through automated delivery schedules.
- Millennials:Flavor rotation preferences and sustainability credentials influence brand switching. Direct-to-consumer platforms leverage data-driven profiling for micro-batch customization.
- Families:Multi-serve packaging formats and value-oriented pricing dominate purchase criteria. Supermarket private-label placement strategies target routine stock-up occasions.
- Teens:Convenience store and vending channel access shapes impulse-driven selection. Energy-drink-specific caffeine disclosure protocols exceed baseline FDA requirements for this segment.
Volume concentration rests with Families. Margin expansion concentrates among Health Conscious purchasers.
Distribution Channel:
Channel selection determines shelf placement economics, promotional support levels, and inventory velocity requirements.
- Supermarkets:Private-label placement strategies and promotional slotting fees structure competitive access. Low-sugar variants receive disproportionate support from buyers seeking to preempt regulatory scrutiny.
- Online Retail:Direct-to-consumer subscription models capture recurring revenue through personalized hydration deliveries. IoT-enabled inventory tracking optimizes replenishment timing.
- Convenience Stores:Post-mix fountain system modernization enables real-time flavor customization. Northeast corridor states show accelerated adoption of compact filtration units for distributed production.
- Restaurants:Foodservice fountain agreements and bulk syrup contracts lock in volume commitments. Institutional foodservice buyers mandate clean-label procurement with multi-year organic sourcing contracts.
Traditional strength anchors in Supermarkets. Digital migration accelerates through Online Retail.
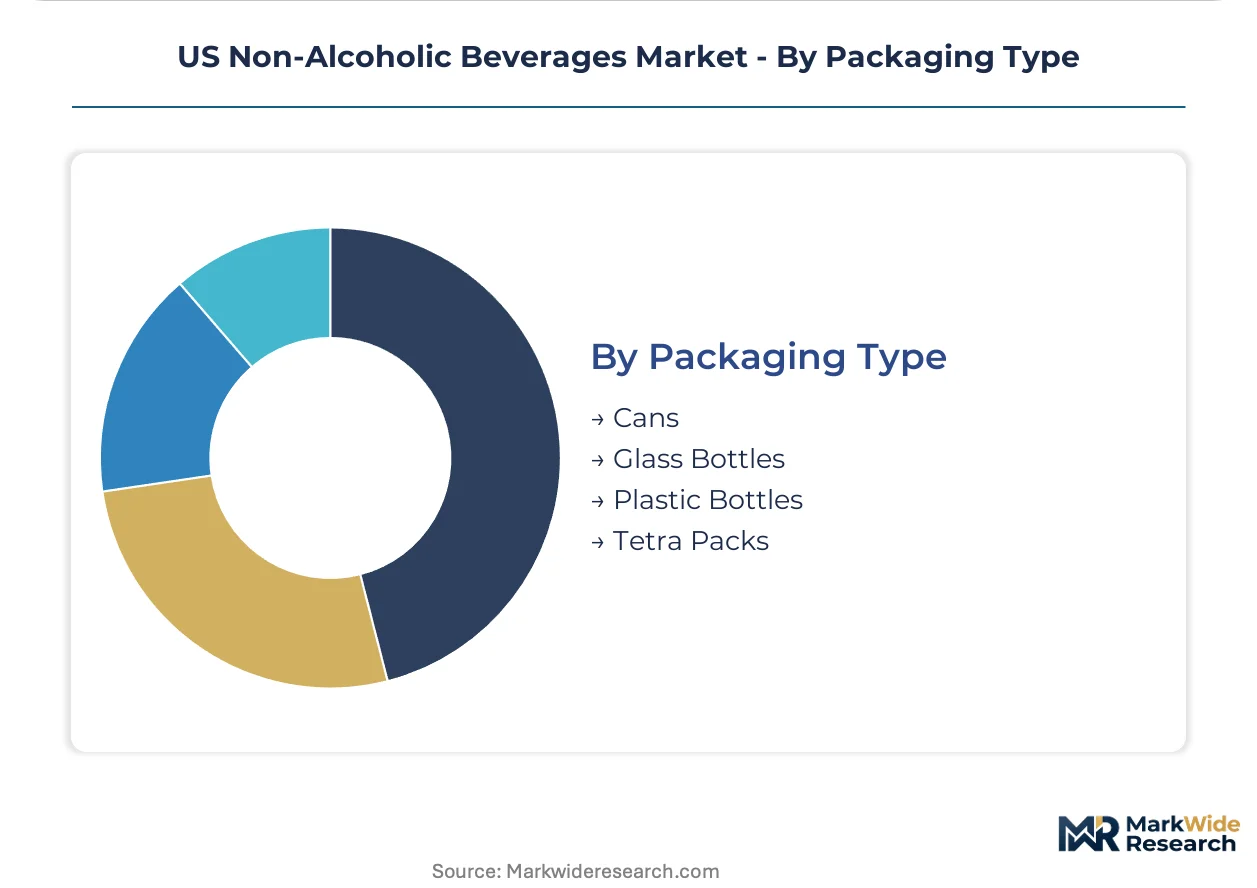
Packaging Type:
Material selection imposes distinct supply chain constraints, recycling infrastructure dependencies, and transportation cost structures.
- Plastic Bottles:Lightweighting technology and rPET content percentages respond to EPA-adjacent state recycling mandates. Shelf-life extension without chemical preservatives depends on barrier layer specifications.
- Cans:Aluminum tariff exposure and domestic smelter capacity shape input cost volatility. Fitness culture penetration drives single-serve adoption for sports drinks.
- Glass Bottles:Premium positioning and reusability narratives command price premiums in California metropolitan demand clusters. Weight-based transportation costs limit distribution radius.
- Tetra Packs:Aseptic filling requirements and multi-layer laminate sourcing create specialized equipment dependencies. Juice and plant-based beverage categories dominate adoption.
Scale concentration remains with Plastic Bottles. Sustainability-driven transition gathers in Cans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in distressed urban census tracts concentrate beverage production facilities seeking federal tax abatements. California's designated zones anchor West Coast manufacturing expansion.
California
Los Angeles and San Francisco metropolitan corridors drive premium functional beverage consumption through fitness culture penetration. The state's CalRecycle mandates impose recycled content thresholds on plastic packaging. San Diego's craft beverage cluster incubates adaptogenic formulation startups serving cross-border Mexican distribution.
Texas
Dallas-Fort Worth and Houston metro areas anchor bulk syrup production and distribution logistics for national foodservice networks. The Texas Commission on Environmental Quality enforces stringent groundwater withdrawal permits for bottling operations. Austin's beverage technology corridor attracts filtration equipment manufacturers and flavor chemistry laboratories.
New York
The New York City metropolitan statistical area commands the highest per-capita consumption of premium bottled water and cold-pressed juices. State-level sugar-sweetened beverage taxes in select jurisdictions force SKU differentiation for metropolitan distribution. Buffalo's legacy manufacturing infrastructure supports contract bottling for emerging regional brands.
Florida
Miami-Dade and Tampa Bay demand clusters prioritize tropical flavor profiles and extended shelf-life formulations for heat-stressed supply chains. The Florida Department of Agriculture and Consumer Services enforces citrus sourcing authenticity standards for juice labeling claims. Orlando's theme park foodservice ecosystem drives fountain system modernization and post-mix equipment deployment.
Illinois
Chicago's central logistics position anchors Midwest distribution networks for national beverage portfolios. The Illinois Environmental Protection Agency monitors industrial discharge from corn syrup processing facilities concentrated along the Mississippi River corridor. Rockford's packaging manufacturing cluster supplies lightweight PET bottle production for regional bottlers.
US Non-Alcoholic Beverages Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation, distribution, and channel access dimensions. The market structure consolidates around multinational beverage corporations with integrated bottling infrastructure and centralized R&D capabilities. Three strategic archetypes dominate: diversified conglomerates with cross-category portfolios, energy-drink specialists with targeted functional positioning, and private-label contract manufacturers serving retail channel buyers. Competitive moves concentrate on portfolio diversification into low-sugar variants and strategic partnerships with direct-to-consumer subscription platforms.
Within the diversified conglomerate tier, The Coca-Cola Company and PepsiCo occupy positions defined by scale-driven distribution economics and multi-brand portfolio management. Monster Beverage Corporation exemplifies the focused specialist archetype, anchoring energy-drink-specific market segmentation through caffeine disclosure protocols that exceed baseline FDA requirements. Nestlé and Danone represent European-origin multinationals competing through mineral water sourcing narratives and organic certification supply chain investments. Keurig Dr Pepper sits within the hybrid category, bridging carbonated soft drinks with single-serve brewing system distribution channels.
| Leading Market Players |
|---|
| Nestlé |
| Monster Beverage Corporation |
| The Coca-Cola Company |
| Unilever |
| Danone |
| PepsiCo |
| Red Bull GmbH |
| Cott Corporation |
| Keurig Dr Pepper |
| Others |
Pricing and Supply Chain Analysis
High-fructose corn syrup futures volatility cascades through the US non-alcoholic beverages supply chain, compressing margin buffers for sweetened carbonated portfolios while elevating premiums for certified organic and low-sugar formulations that command shelf placement in regulated retail environments.
Pricing Analysis
Short lead-time premiums structure pricing for reformulated low-sugar variants as FDA Nutrition Facts compliance deadlines compress procurement cycles. Three-tier pricing structure across premium functional, standard refreshment, and economy private-label levels segments buyer archetypes, with families exhibiting highest price sensitivity and health-conscious consumers showing lowest elasticity. Pricing pressure stems from commodity input hedging costs accumulating across quarterly procurement cycles, forcing national portfolios to absorb regional formulation variations without full cost pass-through.
Supply Chain Analysis
USDA organic certification and EPA water quality standards gate supplier qualification, concentrating certified ingredient sourcing in California's Central Valley agricultural corridors and Midwest corn belt processing hubs. High-fructose corn syrup, aluminum can sheet, and reverse osmosis membrane assemblies constitute critical input dependencies. Single-source vulnerability concentrates in specialized flavor chemist talent pools. Distribution runs through supermarket retail networks anchored by private-label placement strategies and direct-to-consumer subscription platforms capturing recurring revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flavor chemist talent scarcity constrains reformulation capacity, propping pricing power for manufacturers with captive R&D infrastructure and multi-year recruitment pipelines.
For Market Incumbents: Deploy centralized R&D infrastructure to absorb FDA compliance costs across multiple product lines while accelerating backward integration into organic ingredient sourcing contracts. Consolidate bottling network utilization rates against emerging private-label contract manufacturers. Threat substitution from distributed point-of-use filtration systems demands preemptive fountain equipment modernization in convenience store channels. For New Entrants and Emerging Players: Capture white-space in adaptogenic functional beverages targeting Los Angeles and San Francisco fitness corridors where health-conscious consumers prioritize electrolyte-enhanced formulations over legacy sports drink brands. Penetrate direct-to-consumer subscription models through data-driven flavor profiling and automated replenishment scheduling. Go-to-market leverage rests on micro-batch customization capabilities bypassing supermarket slotting fee barriers. For Investors and Strategic Acquirers: The window for entry favors private-label contract manufacturers with multi-regional bottling capacity and established retail channel relationships. Long-term viability hinges on portfolio diversification into low-sugar variants and strategic partnerships with direct-to-consumer subscription platforms. Signal to monitor: FDA front-of-package labeling proposal advancement as inflection trigger for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Investment | Low-sugar variant development secures shelf placement in FDA-regulated supermarket environments. |
| Direct-to-Consumer Launch | Subscription models capture lifetime value through automated replenishment in California and Northeast corridors. |
| Backward Integration | In-house organic ingredient sourcing mitigates USDA certification supply chain premiums and multi-year contract risks. |
| Fountain System Modernization | Post-mix equipment upgrades enable real-time flavor customization in convenience store channels. |
| Certification Investment | Early FDA Nutrition Facts compliance preempts competitive displacement in regulated retail environments. |
Research Methodology
Independent corroboration across bottling plant operations data, supermarket category buyer interviews, and flavor chemistry laboratory technical assessments underwrites the qualitative findings. Primary fieldwork encompassed beverage brand managers, category buyers at national retail chains, supply chain planners at diversified conglomerates, and regulatory affairs specialists navigating FDA food additive approvals. Secondary validation drew from EPA water quality compliance databases, USDA organic certification registries, and Nielsen retail audit data. Bottom-up SKU-level volume modeling triangulated against top-down category expenditure estimates.
Comparable-period anchoring tied projection frameworks to historical reformulation cycle timelines and regulatory implementation windows across the analysis window. Segmentation dimensions modeled encompass product type, customer archetype, distribution channel, and packaging format with regional demand cluster overlays. CAGRs derived from trend extrapolation of fitness culture penetration rates and municipal tap water infrastructure investment patterns. Industry-specific forecast inputs incorporated high-fructose corn syrup commodity price trajectories and state-level sugar tax adoption probabilities.
The model holds under stable FDA regulatory enforcement intensity and continued health-conscious consumer preference evolution; deviation in front-of-package labeling mandate timing or municipal filtration quality breakthroughs would shift volume projections between bottled water and tap substitution categories. A model refresh is warranted upon material change in federal sweetener disclosure requirements or EPA source water protection rulemaking.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Africa Energy Drinks Market
Non-Alcoholic Beverages
Hydrogen Water Pitcher Market
Non-Alcoholic Beverages
Non-Alcoholic Drinks Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Lemonade Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Non-Carbonated Soft Drinks Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
Global Non-Alcoholic RTD Beverages Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market
Non-Alcoholic Beverages
Isotonic Drinks Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
Energy Drinks Market
Non-Alcoholic Beverages
Rtd Bubble Tea Market