
 Global Food Authenticity Testing Market | 2026-2036
Global Food Authenticity Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Authenticity Testing Market Analysis
Subscription-based laboratory information management systems is consolidating how authenticity testing workflows get monetized, shifting capital expenditure into recurring revenue models. Eurofins Scientific leverages its pan-European laboratory network to sustain high-throughput DNA barcoding capacity. SGS Société Générale de Surveillance SA anchors its competitive position through proprietary chain-of-custody protocols that span farm-to-retail traceability.
Food authenticity testing encompasses the analytical verification of declared product attributes including species origin, geographic provenance, and processing method against label claims, employing techniques such as stable isotope ratio mass spectrometry that detects geographic origin through elemental fingerprinting to protect consumer rights and commercial value chains. DNA barcoding dominates routine screening applications for meat and seafood substitution, while mass spectrometry captures premium margin pools in wine and olive oil geographic origin disputes. Polymerase chain reaction methods compete aggressively on speed and cost for dairy protein adulteration cases.
The European Food Safety Authority mandates standardized authentication protocols under the EU Food Fraud Network, while the FDA enforces the Food Safety Modernization Act provisions against intentional adulteration in imported goods. ISO 17025 accreditation requirements shape laboratory market access by defining minimum analytical competence thresholds. Stakeholders must monitor how CRISPR-based detection methods disrupt conventional testing economics before committing capital to platform expansion.
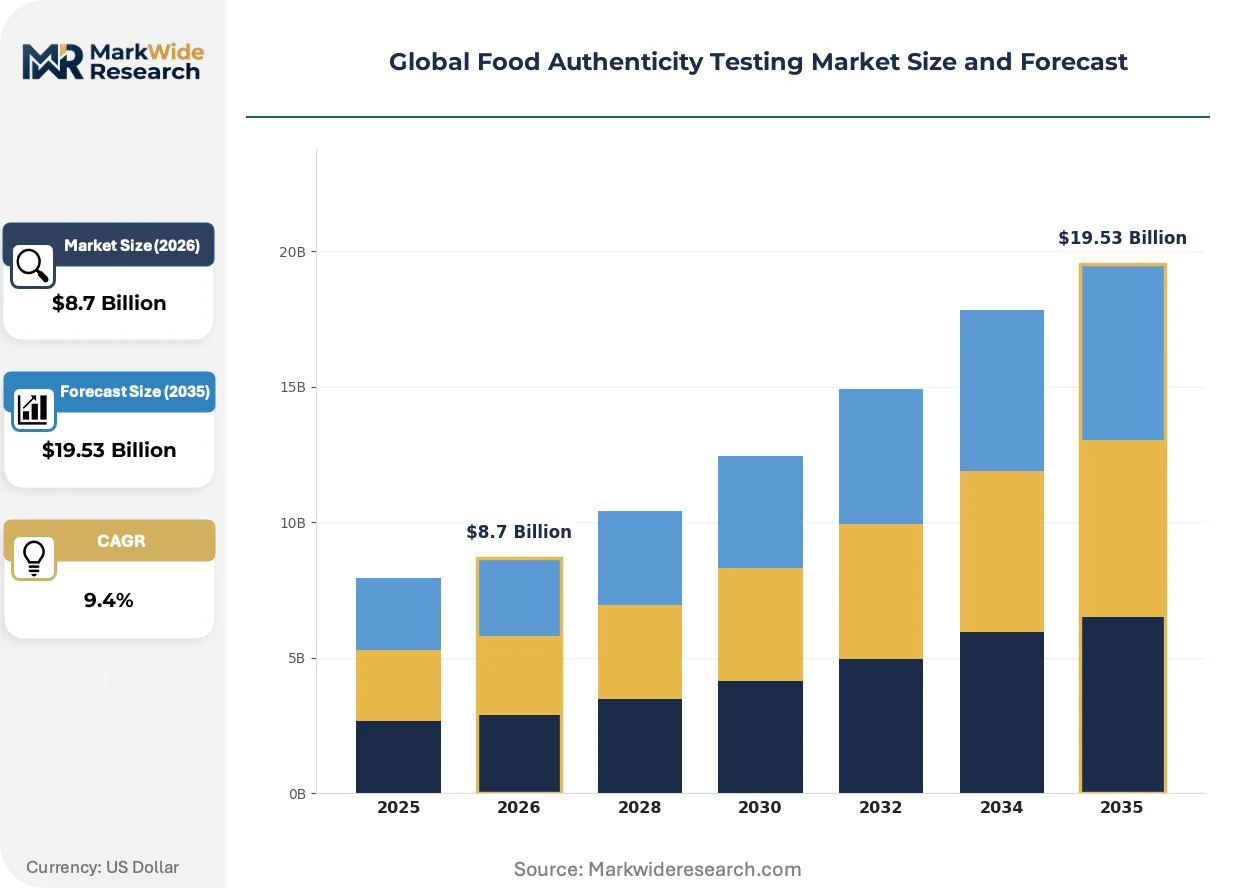
Market Dynamics
Next-generation sequencing platforms are compressing analytical turnaround times from weeks to days, forcing laboratories to reconfigure capital deployment toward high-throughput automation while processed food manufacturers expand testing protocols to defend brand integrity against economically motivated adulteration.
Growth Catalysts
- EU Food Fraud Network Mandates:The European Food Safety Authority enforces standardized authentication protocols that compel manufacturers across member states to maintain documented chain-of-custody records, expanding laboratory service contracts.
- DNA Barcoding Adoption:Meat and seafood processors deploy species identification screening to combat substitution fraud, with stable isotope ratio mass spectrometry capturing premium verification contracts in wine and olive oil geographic origin disputes.
- Germany:The national food regulator enforces strict origin labeling under EU framework rules, concentrating demand for isotopic fingerprinting services in Central European laboratory clusters.
Market Restraints
- Reference Database Gaps:Incomplete genomic libraries for emerging plant-based ingredients limit DNA barcoding accuracy, forcing laboratories to maintain expensive in-house specimen collections.
- Reagent Supply Concentration:Polymerase chain reaction consumables depend on concentrated specialty chemical suppliers, exposing testing facilities to input cost volatility and single-source risk.
- ISO 17025 Accreditation Burden:Laboratory market access requires minimum analytical competence thresholds that extend certification timelines and elevate fixed cost structures for new entrants.
Strategic Opportunities
- India:The Food Safety and Standards Authority of India expands mandatory testing for imported edible oils and spices, creating first-mover advantages for accredited laboratories establishing local presence.
- CRISPR Detection Convergence:Gene-editing derived diagnostic methods promise order-of-magnitude cost reductions versus conventional sequencing, potentially democratizing authenticity screening for mid-tier food processors.
- Blockchain-Linked Verification:Farm-to-retail traceability platforms integrate with isotopic testing data, enabling subscription-based certification services that shift transactional testing into recurring revenue models.
Industry Challenges
- Bioinformatics Talent Scarcity:Shortages of computational biologists capable of interpreting next-generation sequencing outputs constrain laboratory expansion and elevate specialist compensation costs.
- Legacy LIMS Integration:Older laboratory information management systems resist seamless data exchange with cloud-based sequencing platforms, complicating workflow automation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Authenticity Testing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Method: DNA Barcoding, Isotope Analysis, Polymerase Chain Reaction, Mass Spectrometry Food Type: Meat Products, Dairy, Beverages, Fruits & Vegetables Technology: Biochemical Testing, Microbiological Testing, Physical Testing, Chemical Testing End User: Food Manufacturers, Retailers, Restaurants, Regulatory Agencies |
| Companies Covered | Eurofins Scientific, SGS Société Générale de Surveillance SA, Intertek Group plc, Thermo Fisher Scientific Inc., ALS, Mérieux NutriSciences, TÜV SÜD, EMSL Analytical, Inc., LGC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Authenticity Testing Market Emerging Trajectories
Multi-omics approaches are merging genomic, proteomic, and metabolomic data streams to create composite authenticity signatures that resist single-vector adulteration tactics, reshaping how laboratories architect detection platforms.
Portable sequencing devices are consolidating field-based authenticity screening by enabling real-time species verification at ports and processing facilities. Customs agencies in Brazil and Australia deploy handheld DNA analyzers to intercept mislabeled seafood before distribution. This mobility is compressing the traditional laboratory-centric testing model and redistributing analytical capacity toward point-of-inspection locations.
The FDA enforces Food Safety Modernization Act provisions against intentional adulteration in imported goods, requiring foreign suppliers to demonstrate preventive controls through documented testing protocols. Importers of high-risk commodities such as spices and honey must maintain verified laboratory relationships. Domestic distributors are responding by pre-qualifying testing partners in source countries to accelerate customs clearance.
Consolidated procurement of authenticity testing services is displacing transactional relationships as large retail chains centralize supplier verification through preferred laboratory networks. Mass-market grocery operators in the United Kingdom negotiate volume-based testing agreements that bundle multiple product categories. This concentration favors multi-site laboratory groups capable of standardized reporting across geographic jurisdictions.
Global Food Authenticity Testing Market Segmentation
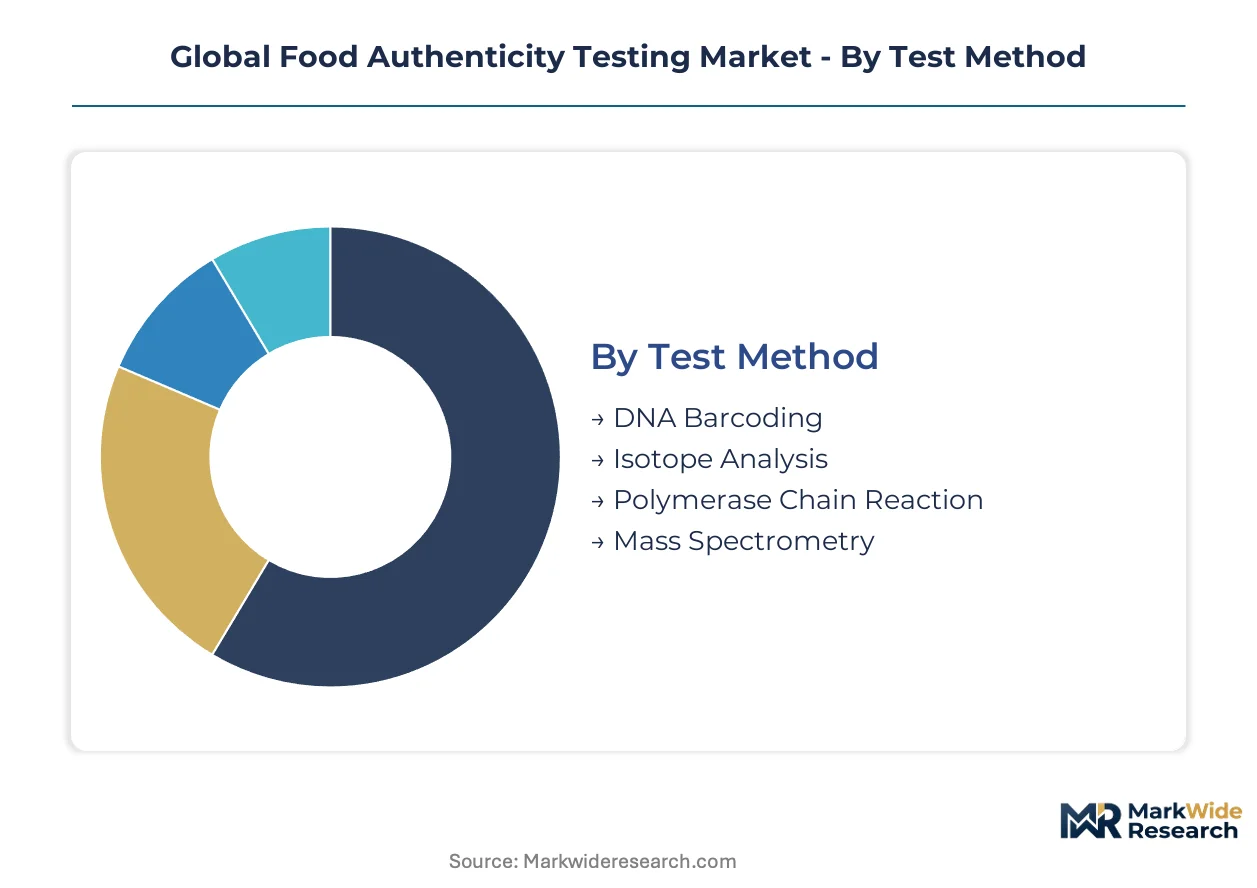
Food authenticity testing segments reveal distinct capital intensity profiles and margin structures. Laboratories configure service portfolios across method, food category, technology platform, and customer type to optimize equipment utilization and accreditation leverage.
Test Method:
The customization-vs-standardization spectrum spans from bespoke isotopic fingerprinting to commoditized PCR screening, with laboratories balancing dedicated instrumentation against flexible multi-platform capacity.
- DNA Barcoding:Mitochondrial gene sequencing identifies species substitution in meat and seafood through standardized barcode regions. Meat processors in Germany and Brazil deploy high-throughput screening to comply with strict origin labeling mandates, compressing per-sample costs through batch automation.
- Isotope Analysis:Stable isotope ratio mass spectrometry maps elemental fingerprints to geographic provenance, commanding premium pricing for wine and olive oil verification. Demand concentrates in Mediterranean laboratory clusters serving EU protected designation of origin enforcement.
- Polymerase Chain Reaction:Amplification-based detection delivers rapid dairy protein adulteration screening at lowest unit economics. Food manufacturers favor PCR for routine incoming material verification where speed outweighs forensic precision.
- Mass Spectrometry:High-resolution molecular profiling resolves complex adulteration matrices in processed foods. The technique anchors dispute-resolution services for contractual arbitration between suppliers and distributors.
Leading the category by volume: Polymerase Chain Reaction. Growing fastest: DNA Barcoding.
Food Type:
Margin concentration follows fraud incident frequency and enforcement intensity, with protein categories commanding higher testing premiums than plant-based segments.
- Meat Products:Species substitution and undeclared offal drive sustained screening demand across beef, pork, and poultry supply chains. Brazilian customs agencies deploy handheld DNA analyzers at ports to intercept mislabeled shipments before domestic distribution.
- Dairy:Milk powder adulteration with melamine and vegetable fats sustains routine testing protocols. Indian regulators under FSSAI mandate expanded verification for imported edible oils and dairy derivatives, redirecting laboratory investment toward South Asian capacity.
- Beverages:Wine geographic origin disputes and spirits dilution generate isotopic verification contracts. Australian wine exporters maintain documented testing records to satisfy EU import documentation requirements.
- Fruits & Vegetables:Organic fraud and geographic mislabeling drive modest testing penetration relative to protein categories. Blockchain-linked traceability platforms are integrating with chemical residue testing to shift transactional verification into subscription certification models.
Highest margin concentration: Meat Products. Steepest expansion trajectory: Beverages.
Technology:
Platform selection determines laboratory staffing models and regulatory compliance scope, with biochemical methods requiring specialized expertise that constrains market entry.
- Biochemical Testing:Enzyme-linked assays and immunoassays detect protein adulteration through antigen-antibody binding. Eurofins Scientific sustains pan-European capacity through standardized reagent procurement and automated plate readers.
- Microbiological Testing:Culture-based and molecular methods verify fermentation authenticity and detect spoilage organism profiles. The segment supports traditional food protected status applications requiring documented microbial terroir.
- Physical Testing:Microscopy and spectroscopic techniques examine structural integrity and particle morphology. These methods serve as rapid preliminary screens preceding confirmatory molecular analysis.
- Chemical Testing:Chromatographic separation identifies undeclared additives, dyes, and preservatives. SGS anchors competitive positioning through proprietary chain-of-custody protocols spanning farm-to-retail chemical verification.
Deepest regulatory integration: Biochemical Testing. Fastest platform refresh: Microbiological Testing.
End User:
Procurement sophistication varies sharply, with regulatory agencies demanding ISO 17025 accreditation while restaurants prioritize speed and minimal documentation overhead.
- Food Manufacturers:Brand protection investments drive comprehensive testing programs spanning incoming materials, in-process controls, and finished product release. Processed food manufacturers expand protocols specifically to defend against economically motivated adulteration incidents.
- Retailers:Consolidated procurement through preferred laboratory networks displaces transactional relationships. United Kingdom mass-market grocery operators negotiate volume-based agreements bundling multiple product categories and jurisdictions.
- Restaurants:Limited direct testing demand concentrates in high-end establishments verifying premium ingredient provenance. Third-party certification substitutes for in-house analytical capacity.
- Regulatory Agencies:FDA enforcement of Food Safety Modernization Act provisions against intentional adulteration compels documented testing protocols for imported spices and honey. EFSA mandates under the EU Food Fraud Network standardize authentication requirements across member states.
Largest contract value: Food Manufacturers. Procurement innovation leader: Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Testing demand concentrates in consuming nations with stringent enforcement, while laboratory capacity clusters in Germany, the United States, and Australia where accreditation infrastructure matured earliest. This geographic split shapes investment flows toward import-gate verification rather than origin-country screening.
Germany
The Federal Office of Consumer Protection and Food Safety enforces strict origin labeling under EU framework rules, compelling meat processors to maintain documented chain-of-custody records. EFSA mandates under the EU Food Fraud Network standardize authentication protocols across member states. Central European laboratory clusters around Munich and Hamburg sustain high-throughput DNA barcoding capacity serving continental supply chains.
United States
Imported spices and honey trigger intensive screening protocols as FDA enforces Food Safety Modernization Act provisions against intentional adulteration. The agency requires foreign suppliers to demonstrate preventive controls through verified laboratory relationships. Domestic distributors pre-qualify testing partners in source countries to accelerate customs clearance at ports of entry.
India
The Food Safety and Standards Authority of India expands mandatory testing for imported edible oils and spices, redirecting laboratory investment toward South Asian capacity. FSSAI regulations create first-mover advantages for accredited laboratories establishing local presence. Mumbai and Delhi-NCR clusters attract capital deployment for high-throughput PCR screening of dairy derivatives.
Brazil
Federal customs agencies deploy handheld DNA analyzers at ports to intercept mislabeled seafood shipments before domestic distribution. ANVISA coordination with agricultural inspection services tightens verification of beef export documentation. São Paulo state concentrates private laboratory capacity serving protein processors defending brand integrity against substitution fraud.
Australia
Wine exporters maintain documented isotopic testing records to satisfy EU import documentation requirements under protected designation of origin enforcement. The country's national food regulator mandates standardized protocols for geographic provenance verification. Adelaide and Melbourne laboratory clusters specialize in stable isotope ratio mass spectrometry for premium beverage authentication.
Global Food Authenticity Testing Market Vendor Landscape
Top-tier vendors anchor multi-site laboratory networks, while regional specialists occupy niche accreditation segments. The market structure favors pan-European and North American groups capable of standardized reporting across jurisdictions. Three archetypes dominate: integrated testing conglomerates with proprietary protocols, technology-agnostic service laboratories renting capacity to brand owners, and equipment manufacturers backward-integrating into analytical services. Competitive intensity concentrates on M&A-driven geographic expansion and subscription-based LIMS monetization shifting capital expenditure into recurring revenue.
Within the integrated testing tier, Eurofins Scientific and SGS Société Générale de Surveillance SA exemplify divergent strategic positioning. Eurofins leverages pan-European laboratory density to sustain high-throughput DNA barcoding economies. SGS anchors competitive position through proprietary chain-of-custody protocols spanning farm-to-retail traceability. Thermo Fisher Scientific Inc. occupies the equipment-manufacturer archetype, representing technology licensors whose platform sales shape downstream laboratory capacity configuration.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS Société Générale de Surveillance SA |
| Intertek Group plc |
| Thermo Fisher Scientific Inc. |
| ALS |
| Mérieux NutriSciences |
| TÜV SÜD |
| EMSL Analytical, Inc. |
| LGC Group |
| Others |
Supply Flow & Price Mechanics
EU Food Fraud Network mandates gate qualified laboratory supply and premium-tier pricing access, as ISO 17025 accreditation requirements restrict service provider pools while concentrating verification contracts among accredited Central European clusters serving processed food manufacturers defending brand integrity.
Pricing Analysis
Cost-down pressure on routine PCR screening accelerates because reagent supply concentration exposes testing facilities to input volatility, forcing laboratories to absorb margin compression or risk volume loss to competitors. Pricing stratifies across premium isotopic fingerprinting for wine and olive oil disputes, standard DNA barcoding for meat and seafood verification, and economy PCR tiers for dairy adulteration cases. Quality grade and certification level differentiate contract values, with FSSAI-accredited laboratories in India commanding premiums over non-accredited rivals. Food manufacturers show highest price sensitivity, while regulatory agencies prioritize analytical precision over unit economics.
Supply Chain Analysis
Reverse-logistics flows for expired reagents and decommissioned sequencing platforms complicate waste disposal compliance, particularly for CRISPR-derived diagnostic consumables lacking established reclamation infrastructure. Specialty chemical manufacturing concentrates in Germany, the United States, and Switzerland, while sequencing instrument assembly centers on Massachusetts and California clusters. Reagent supply draws from concentrated specialty chemical suppliers, creating single-source vulnerability for polymerase chain reaction consumables. Distribution runs through pan-European laboratory networks and regional accreditation hubs, with customs agencies at Brazilian and Australian ports intercepting mislabeled shipments before domestic distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025 accreditation bottlenecks prop pricing power by restricting qualified laboratory supply, creating durable margin pools for incumbent service providers with established certification leverage.
For Market Incumbents: Acquire regional accreditation capabilities in India and Brazil to preempt FSSAI and ANVISA enforcement expansion. Eurofins Scientific and SGS anchor defensive positioning through proprietary chain-of-custody protocols, but emerging portable sequencing device manufacturers threaten equipment-agnostic service models. Incumbents should deepen backward integration into reagent manufacturing to offset specialty chemical supplier concentration risk. For New Entrants and Emerging Players: FSSAI regulations in India open a window for first-mover laboratory establishment in Mumbai and Delhi-NCR clusters, where mandatory testing for imported edible oils and spices outpaces local accredited capacity. Mid-tier food processors in Central Europe represent penetrable demand segments underserved by premium-focused incumbents. A subscription-based LIMS monetization model shifts capital expenditure into recurring revenue, lowering customer acquisition friction. For Investors and Strategic Acquirers: CRISPR-based detection method regulatory approvals are the leading indicator that cost structures will compress order-of-magnitude versus conventional sequencing, democratizing authenticity screening. The five-to-ten-year viability window favors laboratories with multi-omics platform architectures and blockchain-linked verification integrations. Target acquisition archetypes include regional specialists with niche accreditation segments and technology-agnostic service laboratories with flexible capacity models.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Expansion in Emerging Markets | FSSAI enforcement in India redirects laboratory investment toward South Asian capacity clusters. |
| Multi-Omics Platform Integration | Merging genomic, proteomic, and metabolomic data streams creates composite authenticity signatures resisting single-vector adulteration. |
| Blockchain-Linked Verification Services | Farm-to-retail traceability platforms shift transactional testing into subscription-based certification revenue models. |
| Portable Sequencing Device Deployment | Handheld DNA analyzers at Brazilian and Australian ports compress laboratory-centric testing toward point-of-inspection locations. |
| CRISPR Detection Method Development | Gene-editing derived diagnostics promise cost reductions democratizing authenticity screening for mid-tier processors. |
Methodological Framework
EFSA regulatory filings, FDA enforcement actions, and ISO accreditation databases formed the secondary backbone, supplemented by customs records and trade data tracking laboratory equipment imports. Primary interviews with laboratory operations directors, food manufacturer quality assurance heads, regulatory compliance officers, and reagent procurement specialists combined with secondary validation through bottom-up and top-down triangulation approaches.
Historical trendline analysis examined method adoption rates, accreditation expansion patterns, and enforcement intensity shifts across the projection horizon. Segmentation modeling incorporated test method, food category, technology platform, and end-user procurement sophistication dimensions. CAGRs derived from equipment installation rates, reagent consumption volumes, and contract value trajectories, with next-generation sequencing platform deployment and portable device adoption serving as primary forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for CRISPR-based detection would alter the outlook if regulatory approval timelines compress or reagent cost curves steepen. Forecasts reflect assumptions about enforcement intensity continuity and accreditation standard stability. Practitioners should monitor FSSAI laboratory accreditation grants and FDA Food Safety Modernization Act enforcement actions for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Water Activity Instrumentation Market
Food Safety Testing
Amylase Testing Market
Food Safety Testing
Global Lipid Testing Market
Food Safety Testing
Food Authentication Testing Market
Food Safety Testing
Food Allergens and Intolerance Testing Market
Food Safety Testing
Fresh Food Residue Testing Market
Food Safety Testing
US Food Allergen Testing Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Genetically Modified Food Safety Testing Market
Food Safety Testing
Residual Lactose Analyzer Market
Food Safety Testing
Allergen Testing Market
Food Safety Testing
Global Meat Speciation Testing Market
Food Safety Testing
North America Food Safety Testing Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Food Tester Market
Food Safety Testing
Meat Testing Market