
 North America Mezcal Market | 2026-2036
North America Mezcal Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mezcal Market Analytics
Asset-light importing and third-party distribution partnerships is reconfiguring competitive entry barriers for smaller mezcal brands seeking shelf space without distillery ownership. Ilegal Mezcal leverages direct-to-bar relationships in major metropolitan markets to bypass traditional wholesale tiers. El Silencio Holdings anchors its position through vertical integration from Oaxacan palenques to controlled U.S. allocation. Pernod Ricard competes via portfolio breadth, slotting mezcal alongside established tequila labels in negotiated retail placements.
Mezcal denotes a distilled spirit produced from roasted agave hearts, typically cooked in earthen pits and fermented with wild yeasts to yield a smoky, terroir-driven profile with alcohol content generally between 40% and 55% ABV. Joven expressions dominate current volume due to lower price points and faster production cycles, while Reposado and Añejo categories command disproportionate margin pools as consumers trade up within the category. Glass bottle packaging sustains premium positioning despite emerging PET and canned formats targeting outdoor and festival occasions.
The Alcohol and Tobacco Tax and Trade Bureau enforces certificate-of-label approval requirements that distinguish mezcal from broader agave spirits, while the FDA governs ingredient disclosure and allergen protocols for imported bottles. Mexico's Consejo Regulador del Mezcal maintains denomination-of-origin standards that constrain which U.S.-bound products qualify for the protected classification. Stakeholders must monitor evolving trade agreement provisions and state-level control-board listing decisions that determine market access velocity.
Market Dynamics
The Alcohol and Tobacco Tax and Trade Bureau's updated certificate-of-label approval requirements are forcing importers to restructure compliance workflows and consolidate supplier relationships around certified Oaxacan palenques.
Growth Catalysts
- Denominación de Origen enforcement:Mexico's Consejo Regulador del Mezcal certification standards are filtering out non-compliant competitors and elevating price premiums for authenticated exports.
- Mixology program adoption:Premium cocktail bars in Los Angeles, New York, and Toronto are rotating mezcal into core spirits programs, exposing consumers to smoky agave profiles through craft cocktail formats.
- Wild yeast terroir marketing:Producers are highlighting regional fermentation variations to differentiate artisanal batches from industrial tequila, appealing to craft beverage enthusiasts seeking provenance narratives.
Market Restraints
- Agave supply concentration:Wild espadín and tobalá harvesting concentrates in Oaxaca's Central Valleys, exposing pricing to climate volatility and maturation cycle disruptions.
- TTB labeling friction:Certificate-of-label approval timelines stretch 90-120 days for new expressions, delaying seasonal releases and constraining portfolio agility for smaller importers.
- Tequila substitution pressure:Established tequila brands leverage existing distribution slots and consumer familiarity, compressing shelf-space negotiations for mezcal entrants in control states.
Strategic Opportunities
- Canadian provincial expansion:British Columbia and Ontario liquor boards are adding premium agave spirits to core listings, creating first-mover advantages before category saturation.
- Canned format development:Ready-to-drink mezcal cocktails in aluminum formats target outdoor festival and camping occasions where glass bottle restrictions apply.
- Texas borderland positioning:San Antonio and Austin's Mexican heritage consumer base offers concentrated demand for authentic joven expressions at accessible price points.
Industry Challenges
- Maestro mezcalero scarcity:Traditional pit-roasting and wild yeast fermentation expertise concentrates among aging practitioners in rural Oaxaca, constraining quality-scaled production.
- Multi-jurisdiction compliance layering:Importers must simultaneously satisfy Mexico's CRM standards, TTB label approvals, and state-level control board listing requirements with conflicting documentation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mezcal Market |
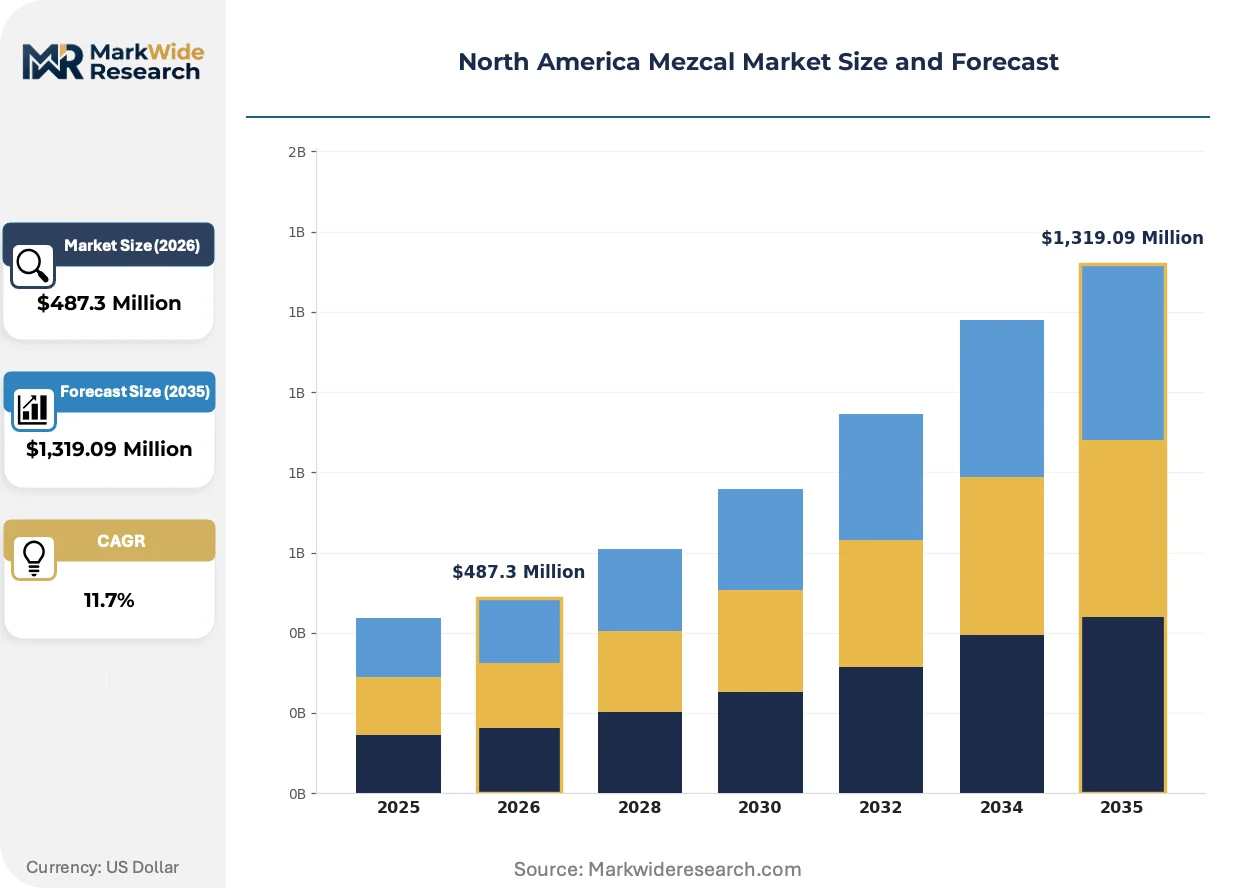
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Joven, Reposado, Añejo, Abocado Distribution Channel: Online, Offline, Retail Stores, Duty-Free Shops Customer Segment: Millennials, Gen X, Baby Boomers, Connoisseurs Packaging Type: Glass Bottle, PET Bottle, Canned, Tetra Pak |
| Companies Covered | Pernod Ricard, Diageo PLC, Davide Campari-Milano N.V., Bacardi Limited, William Grant & Sons, Ilegal Mezcal, Rey Campero, El Silencio Holdings, Mezcal Vago, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mezcal Market Evolving Landscape
Digital traceability systems and alternative packaging formats are compressing traditional supply chain hierarchies while regulatory clarity around agave spirits classification accelerates premium positioning strategies.
Blockchain-based provenance tracking is virtualizing the authentication layer between Oaxacan palenques and U.S. retailers. High-end importers are piloting QR-linked batch records to verify wild agave sourcing and pit-roasting protocols. This technology is virtualizing trust mechanisms previously enforced through personal relationships and third-party audits, enabling direct-to-consumer transparency at scale.
The TTB's clarified agave spirits taxonomy is compressing labeling ambiguity that previously allowed non-certified products to occupy adjacent shelf space. Distillers must now distinguish mezcal from destilado de agave through explicit certification claims on front labels. Small-batch producers in Guerrero and Durango are accelerating CRM compliance investments to access protected classification status in California and Texas markets.
Consumer education investments are displacing wholesale-dependent growth models. Brands are building owned channels through tasting room partnerships and subscription clubs rather than competing for distributor attention. This pattern concentrates in coastal metropolitan markets where craft beverage literacy supports premium pricing for single-village expressions with documented maestro provenance.
North America Mezcal Market Segmentation
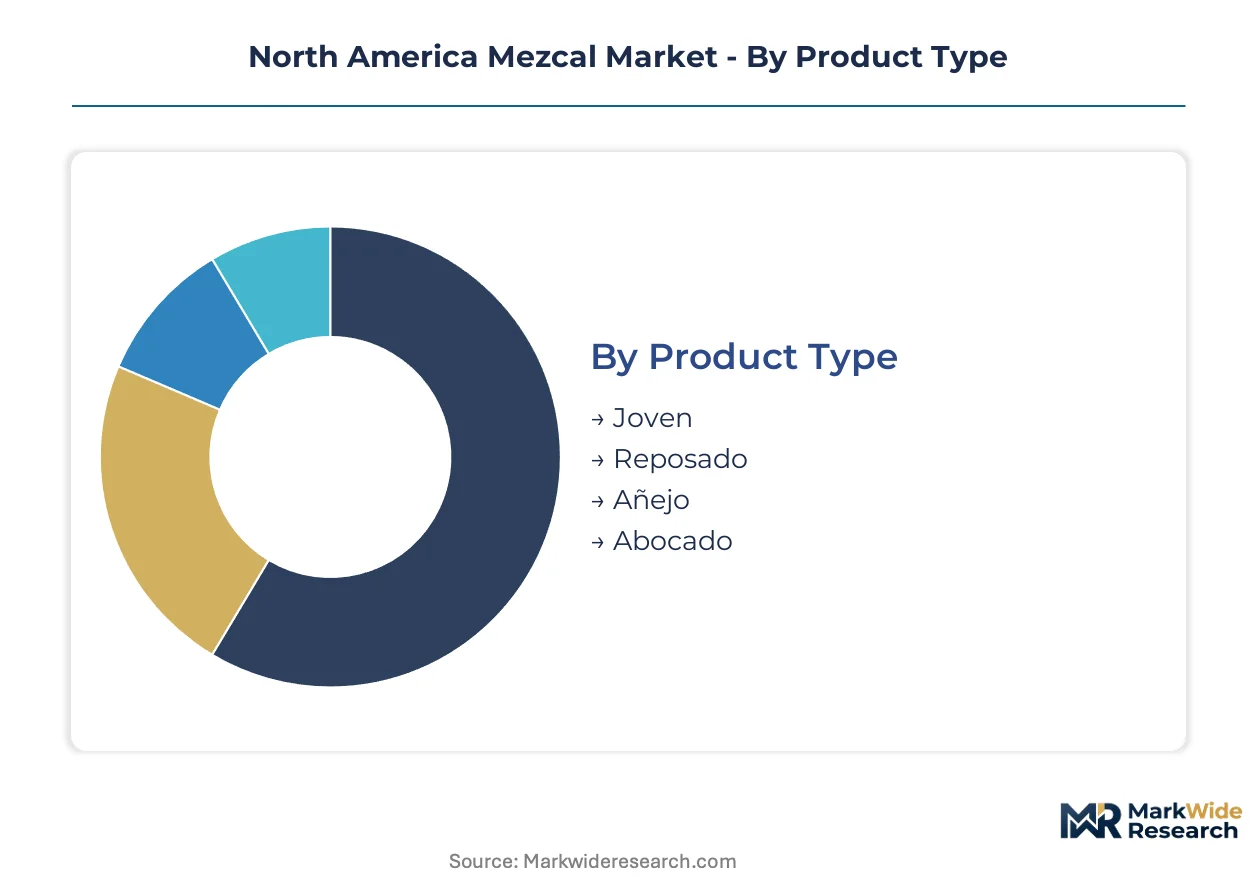
Mezcal segmentation in North America reflects divergent maturation economics and channel access patterns. Cycle times, aging requirements, and compliance burdens create distinct competitive dynamics across product tiers and customer cohorts.
Product Type:
Joven expressions turn inventory fastest with zero barrel time, while extended wood aging stretches Reposado and Añejo cycles to 24-48 months.
- Joven:Unaged mezcal bottled immediately after distillation preserves the raw smoke and agave character that mixologists prize for cocktail applications. Demand concentrates in Texas and California bars where bartenders prioritize flavor intensity over oak complexity, though price compression limits margin expansion for volume-focused brands.
- Reposado:Two-to-twelve months of oak resting softens the smoky edges while adding vanilla and caramel notes that appeal to whiskey crossover drinkers. The segment commands disproportionate shelf space in New York and Ontario premium liquor stores where consumers trade up from entry-level agave spirits.
- Añejo:Minimum one-year oak aging produces sipping-grade expressions with concentrated wood influence and amber coloration.
- Abocado:Traditionally infused variants incorporating maguey worm, herbs, or fruit for localized Oaxacan authenticity.
Joven anchors the volume base while Reposado gains share at the steepest rate.
Distribution Channel:
Cost tiers separate immediate-consumption venues from controlled retail environments with divergent working capital requirements.
- Online:Direct-to-consumer platforms and third-party alcohol delivery services bypass three-tier wholesale markups in permissive states. The channel expands most quickly in California and New York where regulatory frameworks accommodate interstate shipping and subscription club models.
- Offline:On-premise consumption at restaurants, bars, and tasting rooms generates trial and brand education before retail conversion.
- Retail Stores:Licensed package stores and grocery chains in control states require listing fees and TTB-compliant shelf talkers.
- Duty-Free Shops:Airport and border retail captures premium travelers seeking authenticated CRM-certified bottles with origin documentation.
Offline on-premise anchors the volume base while online climbs the fastest.
Customer Segment:
Application patterns vary sharply between occasion-driven casual drinkers and provenance-focused collectors with divergent education thresholds.
- Millennials:Digital-native consumers aged 28-43 demonstrate high craft beverage literacy and willingness to pay premiums for batch-specific transparency. Demand concentrates in Austin, Los Angeles, and Toronto where agave bar density supports exploration of single-village expressions.
- Gen X:Established earners with spirits category experience seek elevated alternatives to premium tequila without abandoning familiar flavor frameworks.
- Baby Boomers:Affluent sippers with decades of whiskey and cognac exposure gravitate toward aged Añejo expressions.
- Connoisseurs:Deep-category enthusiasts pursue limited releases from named maestro mezcaleros with documented wild agave sourcing.
Millennials anchor the volume base while Connoisseurs expand most quickly.
Packaging Type:
Volume economics and occasion portability drive divergence between prestige glass and convenience formats.
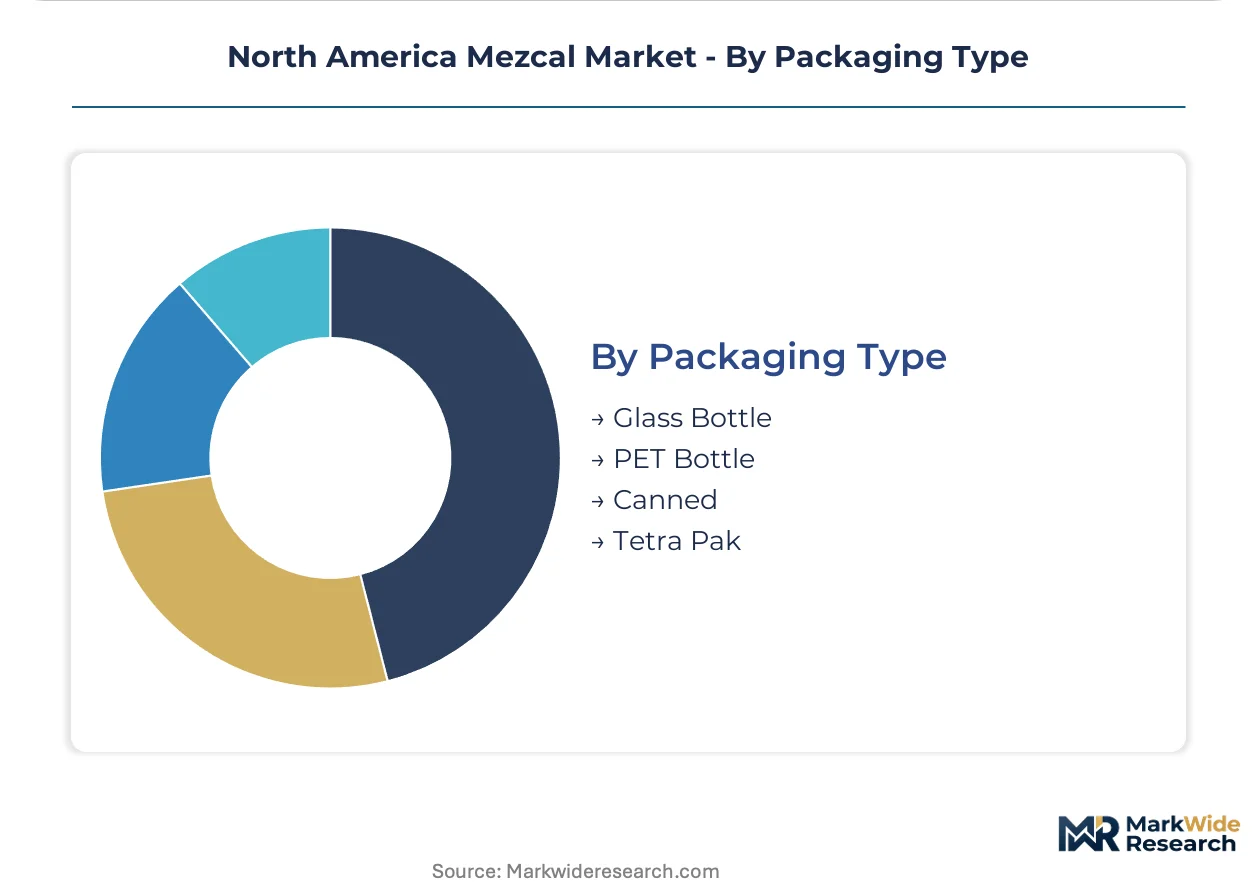
- Glass Bottle:Heavyweight artisanal bottles with hand-applied labels and wax seals sustain premium positioning in gift and collector markets. California and New York retailers mandate glass for super-premium shelf placements despite higher freight costs.
- PET Bottle:Lightweight unbreakable containers target outdoor festivals and poolside venues with glass restrictions.
- Canned:Single-serve aluminum formats enable ready-to-drink mezcal cocktails for camping and concert occasions.
- Tetra Pak:Aseptic cartons offer cost-efficient bulk formats for food service and cocktail program batching.
Glass Bottle anchors the volume base while Canned gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California commands price premiums that Texas and New York cannot replicate, creating a tiered revenue architecture across the North American mezcal trade.
United States
The TTB's certificate-of-label approval requirements filter import velocity through 90-120 day review windows. California's craft cocktail density in Los Angeles and San Francisco generates disproportionate margin capture for authenticated CRM-certified expressions. Texas border markets anchor volume throughput for accessible joven formats.
Canada
British Columbia and Ontario liquor boards are expanding premium agave spirits listings ahead of category saturation. Health Canada governs ingredient disclosure protocols for imported bottles. Toronto's mixology programs drive trial conversion among craft beverage enthusiasts seeking provenance narratives.
Mexico
Oaxaca's Central Valleys concentrate wild espadín and tobalá harvesting for export-bound production. The Consejo Regulador del Mezcal enforces denomination-of-origin standards that constrain which products qualify for protected classification. Guerrero and Durango palenques are accelerating compliance investments to access California and Texas markets.
North America Mezcal Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in palenque-level production. The North America mezcal market structures around three competitive tiers: multinational spirits conglomerates with portfolio breadth, vertically integrated specialists controlling Oaxacan supply chains, and asset-light importers leveraging direct-to-bar relationships. Consolidation pressures concentrate among distributors negotiating retail placements in control states. Dominant competitive moves include backward integration into palenque ownership and geographic expansion through provincial liquor board listings.
Among vertically integrated specialists, El Silencio Holdings anchors its position through captive supply from Oaxacan palenques to controlled U.S. allocation. Ilegal Mezcal occupies the asset-light importer tier, exemplifying direct-to-bar relationship models that bypass traditional wholesale markups. Pernod Ricard represents the multinational platform archetype, competing via portfolio breadth that slots mezcal alongside established tequila labels in negotiated retail placements.
| Leading Market Players |
|---|
| Pernod Ricard |
| Diageo PLC |
| Davide Campari-Milano N.V. |
| Bacardi Limited |
| William Grant & Sons |
| Ilegal Mezcal |
| Rey Campero |
| El Silencio Holdings |
| Mezcal Vago |
| Others |
Value Network & Pricing Analysis
Oaxaca's Central Valleys concentrate wild espadín and tobalá harvesting for export-bound production, anchoring margin capture at the CRM-certified bottling tier while joven expressions face price compression from accelerated inventory turns.
Pricing Analysis
The customization-premium spread separates authenticated single-village expressions from commodity-grade agave spirits. Three-tier pricing structure across premium, standard, and economy levels stratifies by CRM certification status and maestro documentation. Price differentiation rests on batch-specific transparency and controlled allocation scarcity. Pricing pressure stems from tequila substitution in control-state retail slots, with volume-focused importers absorbing the steepest margin compression while connoisseur segments remain price-inelastic.
Supply Chain Analysis
Contract-manufacturing concentration sits with Oaxacan palenque networks and third-party bottling facilities in Guadalajara. Mexico, the United States, and Canada form the geographic supply triangle. Raw material dependencies center on wild agave hearts, earthen pit fuel sourcing, and oak barrel imports. Single-source vulnerability concentrates with aging maestro mezcalero expertise in rural Oaxaca. Distribution runs through three-tier wholesale systems in control states and direct-to-bar relationships in permissive jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against established tequila brands leveraging familiar flavor frameworks and pre-negotiated retail placements.
For Market Incumbents: Pre-empt CRM certification investments in Guerrero and Durango palenques before denomination-of-origin standards tighten. Secure captive supply agreements with named maestro mezcaleros to constrain competitor access to authenticated production. Channel control through direct-to-bar relationships in Los Angeles and New York insulates margin pools from wholesale markups.
For New Entrants and Emerging Players: Pursue Canadian provincial liquor board listings in British Columbia and Ontario where premium agave spirits remain underrepresented. Target ready-to-drink canned formats for festival and outdoor occasions where glass restrictions create white space. Anchor go-to-market through subscription club models in coastal metropolitan markets with craft beverage literacy.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertically integrated specialists controlling Oaxacan palenque-to-allocation pipelines. Long-term viability hinges on authenticated supply scarcity and regulatory moats around CRM certification. Watch for inflection in TTB label approval velocity as indicator of portfolio agility constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| CRM Certification Acceleration | Guerrero and Durango palenques gain protected classification access in California and Texas markets. |
| Direct-to-Bar Channel Expansion | Bypassing three-tier markups captures margin pools in Los Angeles and New York metropolitan clusters. |
| Canned Format Development | Aluminum single-serve targets camping and festival occasions with glass bottle restrictions. |
| Blockchain Provenance Pilot | QR-linked batch records verify wild agave sourcing for connoisseur segment transparency demands. |
| Canadian Provincial Listing Push | British Columbia and Ontario liquor boards create first-mover advantage before category saturation. |
Research Methodology
Initial hypotheses were tested against primary input from maestro mezcaleros, import compliance officers at TTB-certified distributors, premium cocktail bar beverage directors, and provincial liquor board category managers, then refined through secondary validation against CRM certification databases, TTB label approval records, and customs trade documentation. Bottom-up volume triangulation from palenque production estimates converged with top-down market sizing from retail audit data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product maturation tier, distribution channel type, generational cohort, and packaging format. CAGRs derived from production volume trajectories, price elasticity coefficients by customer segment, and regulatory access velocity assumptions. Forecast inputs incorporated agave maturation cycle timelines and TTB approval queue dynamics.
Sensitivities concentrate around climate volatility disrupting wild agave harvests and TTB staffing levels affecting label approval timelines. Quarterly review of CRM certification issuance rates and provincial listing addition frequencies is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Canada Wine Coolers Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
Frozen Cocktails Market
Alcoholic Beverages
Beer Line Cooling System Market
Alcoholic Beverages
Canned Cocktails Market
Alcoholic Beverages
Beer Glass Chillers Market
Alcoholic Beverages
Ethyl Alcohol (Ethanol) Market
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Wine Glass Market
Alcoholic Beverages
Bayberry Wine Market
Alcoholic Beverages
Orange Wine Market
Alcoholic Beverages
Herbal Distillates Market