
 Barware Market | 2026-2036
Barware Market Size, Share, and Industry Trends Forecast 2026-2036
Barware Market Analysis
Bundle configurations in barware sets is shifting how consumers evaluate value, moving from individual piece purchases toward curated collections that reduce decision fatigue. Lifetime Brands, Inc. leverages its multi-brand portfolio to occupy shelf space across price tiers in North American retail. Zwiesel Kristallglas AG anchors its reputation on Tritan crystal technology, competing through durability claims in commercial hospitality channels.
Barware encompasses vessels and tools engineered for beverage preparation, service, and consumption, typically fabricated from soda-lime glass, borosilicate, or 18/8 stainless steel with wall thickness calibrated for thermal stability and mechanical shock resistance. Its primary commercial purpose centers on enhancing sensory presentation while withstanding cyclic mechanical and chemical stress in foodservice environments. Glassware commands the largest revenue pool among product types, sustained by replacement cycles in restaurants and hotels, while stainless steel shakers represent the fastest-expanding segment as craft cocktail programs proliferate. The material split shows glass retaining volume leadership though stainless steel is capturing margin concentration through premium positioning in modern and vintage style categories.
FDA food-contact regulations govern material migration limits for barware distributed in the United States, while REACH compliance in Europe restricts lead and cadmium content in decorative crystal formulations. ISO 7086 standards for glass hollowware provide the baseline mechanical performance benchmarks that commercial buyers reference in procurement specifications. Stakeholders must monitor evolving extended producer responsibility frameworks in the EU and state-level packaging regulations in California as these reshape material selection criteria and supplier qualification requirements.
Market Dynamics
The EU's F-Gas Regulation is forcing manufacturers to abandon fluorinated greenhouse gases in glass tempering and cooling processes, triggering capital reallocation toward electric furnaces and hydrogen-fired production lines across European supply chains.
Growth Catalysts
- Craft cocktail program proliferation:Independent restaurants and hotel beverage programs in Germany, France, and Spain are expanding dedicated bar infrastructure, driving replacement demand for specialized shakers and precision-pour tools.
- REACH compliance differentiation:Crystal manufacturers reformulating lead-free decorative coatings are capturing premium positioning in EU hospitality procurement channels where cadmium restrictions now govern decorative surface treatments.
- Borosilicate thermal shock performance:Laboratory-grade glass technology is migrating into commercial barware as venues prioritize dishwasher durability and rapid temperature cycling resistance.
Market Restraints
- Energy cost volatility:Natural gas and electricity price swings in Czech Republic and Poland glassmaking regions are compressing margins for soda-lime hollowware producers serving mid-market hospitality.
- Raw material concentration:High-purity silica sand deposits in specific Bavarian and Belgian quarries create geographic supply vulnerability for crystal manufacturers dependent on low-iron feedstock.
- Stainless steel price linkage:Nickel and chromium commodity fluctuations on the London Metal Exchange directly transmit into shaker and jigger production costs without hedging mechanisms for smaller fabricators.
Strategic Opportunities
- Portuguese hospitality expansion:Lisbon and Porto hotel development pipelines are under-supplied with artisanal glassware, creating entry points for specialized producers outside Iberia.
- Extended Producer Responsibility frameworks:France's AGEC law and pending EU packaging regulations are creating first-mover advantages for manufacturers with closed-loop recycling and take-back infrastructure.
- Direct-to-venue digital platforms:B2B marketplaces connecting Italian glass artisans with sommelier-led procurement committees are bypassing traditional hospitality distributors in premium segments.
Industry Challenges
- ISO 7086 certification timelines:Mechanical shock and thermal endurance testing protocols require 12-18 month validation cycles, delaying product launches for innovative wall-thickness designs.
- Decorative coating compliance complexity:Multi-jurisdiction food-contact approval requirements for colored and metallic surface treatments create documentation burdens for SKU proliferation strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barware Market |
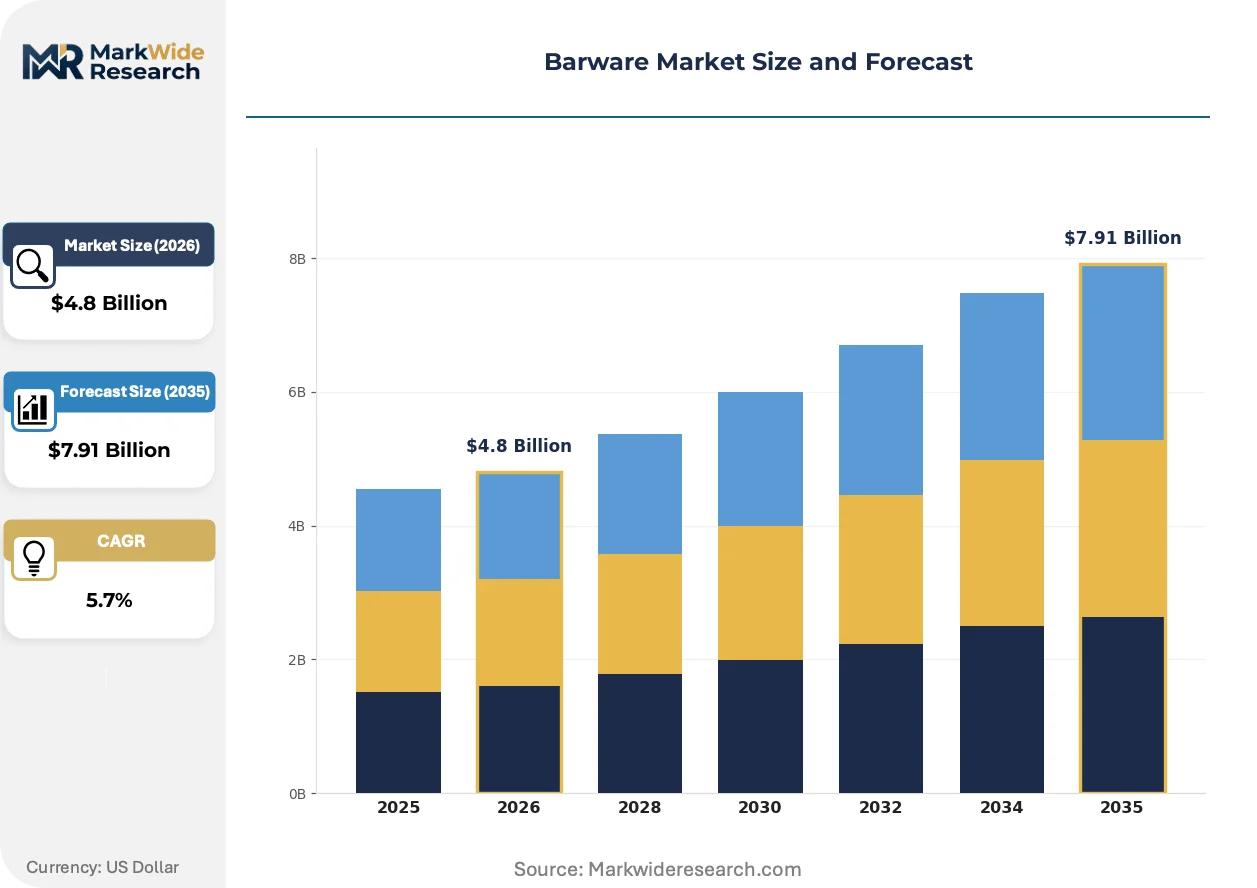
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glassware, Corkscrews, Shakers, Accessories Material: Glass, Stainless Steel, Plastic, Wood Style: Modern, Vintage, Rustic, Themed End User: Home Bars, Restaurants, Hotels, Event Planners |
| Companies Covered | Oneida Ltd., Lifetime Brands, Inc., Libbey, Anhui Deli Daily Glass Co., Ltd, Zwiesel Kristallglas AG, Bormioli Rocco S.p.A., Steelite International, Present Ocean Glass Public Company Limited, Arc International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barware Market Emerging Trajectories
Barware manufacturing is absorbing sustainability mandates and digital traceability requirements simultaneously, compressing traditional material hierarchies while elevating performance specifications across price tiers.
Tritan crystal technology is absorbing impact resistance requirements previously met by thicker-walled soda-lime alternatives. Boutique hotels and Michelin-recognized venues in Austria and Switzerland are specifying Tritan stemware for outdoor service and high-volume tasting menus. This material transition is absorbing warranty cost pools and reducing replacement frequency in commercial accounts.
REACH Annex XVII restrictions on cadmium and lead compounds are compelling Venetian and Bohemian crystal houses to reformulate decorative firing processes. The regulation is accelerating laser-etching and sandblasting techniques as alternatives to metallic surface coatings. Champagne flute and decanter segments are most affected, with producers in Czech Republic investing in electron-beam curing equipment to maintain decorative complexity without restricted substances.
Curated bundle configurations are displacing individual piece procurement in home bar segments. German and Dutch specialty retailers are assembling region-specific collections pairing glassware with tools and recipe cards, capturing gift-market occasions previously served by department store housewares departments. This pattern is most visible in urban centers where apartment downsizing limits storage capacity for expansive individual collections.
Barware Market Segmentation
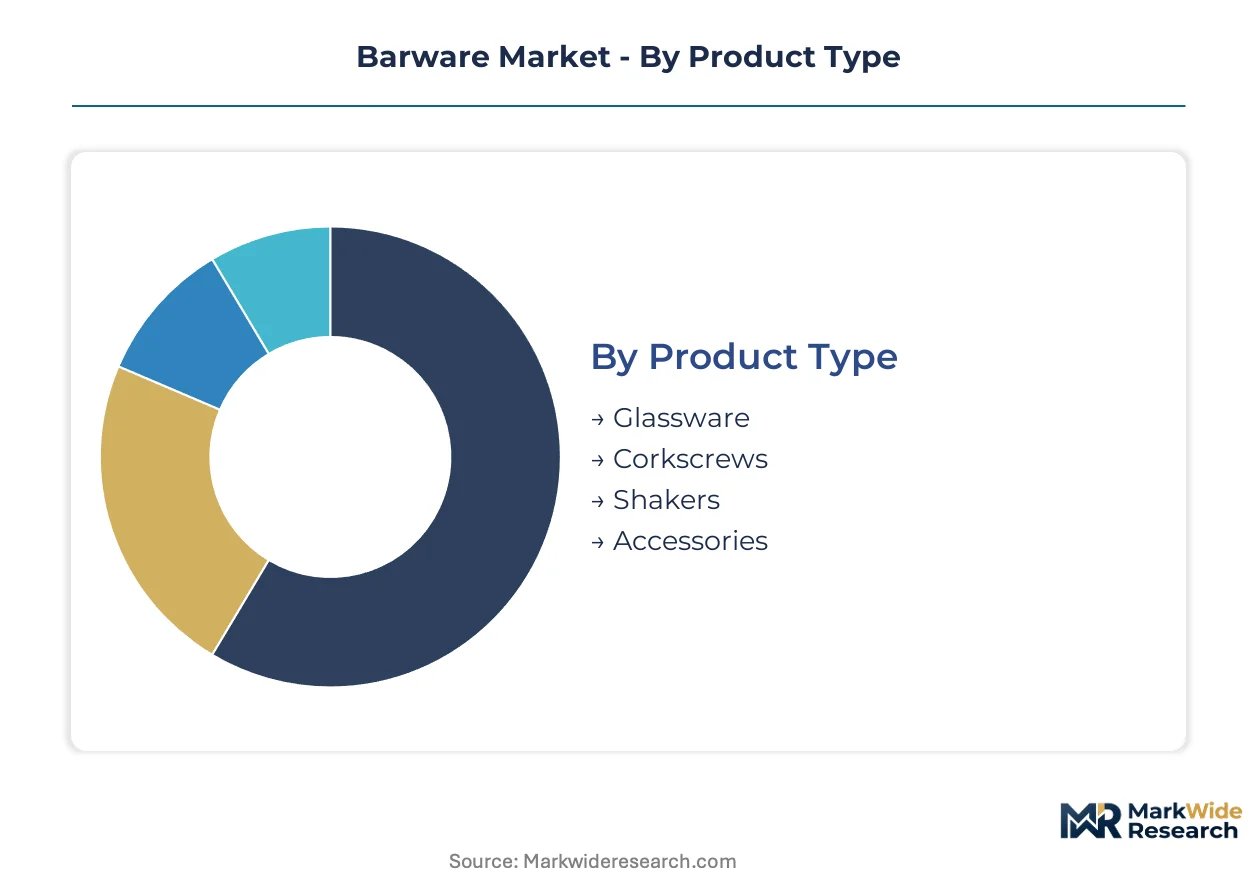
Barware procurement patterns diverge sharply across use contexts, with commercial hospitality prioritizing mechanical durability under ISO 7086 standards while home bar segments favor aesthetic curation and bundle convenience. Material selection and style positioning further fragment supplier strategies across price tiers and replacement cycle expectations.
Product Type:
Supply concentration in hollowware manufacturing clusters favors certain product categories over others, with furnace-scale economies dictating which segments absorb capital investment most aggressively.
- Glassware:Soda-lime and borosilicate vessels calibrated for thermal shock resistance dominate procurement specifications across German and Austrian hospitality channels. Replacement cycles in restaurant and hotel operations sustain volume leadership despite longer purchase intervals than tool categories.
- Shakers:Craft cocktail program proliferation in France and Spain is concentrating demand for precision-engineered stainless steel and weighted tin-on-tin configurations. This segment is climbing the fastest as dedicated bar infrastructure expands in independent venues.
- Corkscrews:Waiter's friend and lever-arm mechanisms retain steady replacement demand through sommelier-led procurement in Italian and Portuguese wine service.
- Accessories:Jiggers, strainers, and muddlers follow shaker purchases in bundled configurations, particularly in Dutch and Belgian home bar retail.
Today's leader: Glassware. Tomorrow's challenger: Shakers.
Material:
Cost tier stratification in raw material procurement is reshaping competitive positioning, with energy-intensive processing favoring certain feedstocks in specific European manufacturing clusters.
- Glass:Tritan crystal technology from Zwiesel Kristallglas AG and lead-free reformulations under REACH Annex XVII are capturing premium positioning in Austrian and Swiss Michelin-recognized venues. High-purity silica dependency from Bavarian quarries creates geographic supply vulnerability.
- Stainless Steel:18/8 and 18/10 grades with nickel and chromium alloying dominate shaker and jigger fabrication, though London Metal Exchange price volatility transmits directly into production costs without hedging coverage for smaller fabricators.
- Plastic:Polycarbonate and Tritan copolyester alternatives serve outdoor and poolside hospitality in Mediterranean climates where breakage risk outweighs aesthetic priorities.
- Wood:Muddler and garnish tool segments utilize hardwoods from sustainably certified forestry, particularly in Nordic markets with strong ESG procurement mandates.
Glass commands volume. Stainless steel captures margin concentration.
Style:
Customer type differentiation between commercial and residential end uses is driving divergent aesthetic requirements, with procurement committees and individual consumers evaluating design coherence through incompatible lenses.
- Modern:Minimalist lines and stemless configurations align with contemporary hotel interiors in Lisbon and Porto development pipelines. This segment is expanding most quickly as new construction favors clean aesthetic profiles.
- Vintage:Cut crystal patterns and weighted base designs serve speakeasy-themed venues in Berlin and Paris where narrative authenticity supports premium pricing.
- Rustic:Hammered metal finishes and irregular glass surfaces target farmhouse and countryside hospitality in Provence and Tuscany regions.
- Themed:Licensed and occasion-specific collections concentrate in German and Dutch gift retail, bundling glassware with recipe cards for reduced decision fatigue.
Modern leads new construction. Vintage defends premium positioning.
End User:
Application-specific performance requirements are fragmenting supplier qualification criteria, with foodservice durability standards diverging sharply from residential convenience priorities.
- Restaurants:ISO 7086 mechanical shock compliance and dishwasher cycling resistance govern procurement in high-volume German and Spanish independent venues. Extended producer responsibility frameworks under France's AGEC law are reshaping supplier selection.
- Hotels:Brand consistency across property portfolios drives centralized procurement for glassware and tool standardization, particularly in Austrian and Swiss boutique chains specifying Tritan for outdoor service.
- Home Bars:Curated bundle configurations and storage-conscious collections are displacing individual piece purchases in urban German and Dutch markets where apartment downsizing limits capacity.
- Event Planners:Rental and disposable alternatives serve high-turnover occasions, with sustainability mandates increasingly influencing material selection for corporate hospitality in Brussels and Amsterdam.
Restaurants anchor commercial volume. Home bars drive bundle innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bohemian glassmaking established the craft's commercial foundations in the 18th century, with Czech artisans pioneering lead crystal techniques that defined luxury barware standards. Contemporary production clusters retain this geographic imprint while adapting to energy transition mandates and hospitality procurement shifts.
Germany
Craft cocktail program expansion in Berlin and Hamburg drives precision tool demand from independent venues. The F-Gas Regulation accelerates furnace electrification in Bavarian manufacturing clusters. Zwiesel Kristallglas AG anchors Tritan crystal production in the Bavarian Forest region, supplying Austrian and Swiss hospitality channels.
France
Paris speakeasy-themed venues prioritize vintage aesthetic glassware for narrative authenticity. France's AGEC law mandates extended producer responsibility frameworks, reshaping supplier qualification for hospitality procurement. Champagne flute specialists in northeastern clusters invest in electron-beam curing to eliminate cadmium from decorative coatings.
Italy
Sommelier-led wine service in Milan and Rome sustains waiter's friend corkscrew replacement cycles. REACH Annex XVII compliance differentiates Venetian crystal houses reformulating lead-free decorative processes. Murano glass artisans face competitive pressure from laser-etching alternatives in neighboring Austrian markets.
Spain
Barcelona and Madrid hotel beverage programs expand dedicated infrastructure for craft cocktail service. ECHA restrictions on food-contact surface treatments complicate SKU proliferation for colored glassware. Basque Country manufacturing retains hollowware furnace economies for mid-market hospitality supply.
Netherlands
Amsterdam and Rotterdam urban downsizing drives curated bundle configurations in home bar retail. EU packaging regulations pending implementation favor manufacturers with closed-loop recycling infrastructure. Dutch specialty retailers assemble region-specific collections pairing glassware with recipe cards for gift-market positioning.
Barware Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material technology and certification compliance dimensions. The vendor base stratifies into three tiers: multi-brand portfolio holders occupying retail shelf space, crystal specialists competing through durability claims, and regional hollowware producers serving price-sensitive hospitality channels. Two dominant competitive moves define current positioning: REACH-compliant reformulation investments capturing EU procurement preference, and direct-to-venue digital platforms bypassing traditional distribution.
Among multi-brand portfolio holders, Lifetime Brands, Inc. represents the diversified archetype spanning price tiers in North American retail. Crystal technology specialists include Zwiesel Kristallglas AG, which exemplifies premium positioning through material innovation claims in commercial hospitality channels. Regional scale players such as Anhui Deli Daily Glass Co., Ltd. occupy positions in mid-market hollowware supply, leveraging furnace-scale economies for volume leadership.
| Leading Market Players |
|---|
| Oneida Ltd. |
| Lifetime Brands, Inc. |
| Libbey |
| Anhui Deli Daily Glass Co., Ltd |
| Zwiesel Kristallglas AG |
| Bormioli Rocco S.p.A. |
| Steelite International |
| Present Ocean Glass Public Company Limited |
| Arc International |
| Others |
Supply Flow & Price Mechanics
Mid-market hospitality procurement committees in Germany and Austria concentrate purchasing volume for soda-lime hollowware, anchoring a contract-based pricing structure that rewards furnace-scale producers with multi-year offtake agreements while squeezing smaller fabricators on margin.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Tritan crystal specifications from borosilicate durability grades from basic soda-lime replacements. Price differentiation hinges on REACH Annex XVII compliance tier and dishwasher cycling certification under ISO 7086 standards. Pricing pressure stems from nickel and chromium commodity volatility on the London Metal Exchange transmitting directly into stainless steel shaker production. Home bar retail segments exhibit highest price sensitivity, while Michelin-recognized venues in Switzerland tolerate premium positioning for material innovation claims.
Supply Chain Analysis
Skilled furnace operator availability constrains capacity expansion in Czech Republic and Polish glassmaking regions, where generational workforce transitions lag automation investment. Supply concentrates in Germany, Czech Republic, and China, with Bavarian quarries providing high-purity silica feedstock for low-iron crystal production. Raw material dependencies center on soda ash, silica sand, and nickel-chromium alloys for stainless steel fabrication. Single-source vulnerability from Belgian and Bavarian silica deposits creates geographic concentration risk. Distribution runs through hospitality distributors in commercial channels and specialty retailers in home bar segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation functions as a regulatory compounder, forcing capital reallocation toward electric furnaces and hydrogen-fired production lines that will permanently reshape supplier cost structures and competitive positioning across European manufacturing clusters.
For Market Incumbents: Anchor market position through backward integration into high-purity silica sourcing from Bavarian quarries to secure feedstock against supply concentration risk. Accelerate Tritan crystal capacity expansion to capture premium positioning as REACH Annex XVII restrictions eliminate decorative coating alternatives. Defend against laser-etching substitution threats from Austrian competitors by investing in electron-beam curing equipment for lead-free decorative complexity.
For New Entrants and Emerging Players: Launch via direct-to-venue digital platforms connecting Italian glass artisans with sommelier-led procurement committees, bypassing traditional hospitality distributors in premium segments. Target Lisbon and Porto hotel development pipelines, where artisanal glassware supply gaps create entry points for specialized producers outside Iberia. Exploit white-space in curated bundle configurations for Dutch and German urban markets where apartment downsizing limits storage capacity.
For Investors and Strategic Acquirers: Multi-brand portfolio holders in North American retail represent the most active acquirer category in this space, seeking geographic expansion and category consolidation opportunities. Acquisition target archetypes include REACH-compliant crystal specialists with electron-beam curing capabilities and closed-loop recycling infrastructure under France's AGEC law. Monitor ECHA regulatory expansion timelines as the primary inflection signal for material reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation Investment | Electron-beam curing equipment purchases enable Venetian and Bohemian crystal houses to eliminate cadmium from decorative coatings. |
| Direct-to-Venue Digital Platform Launch | B2B marketplaces connecting Italian artisans with sommelier procurement committees bypass traditional hospitality distribution. |
| Closed-Loop Recycling Infrastructure Buildout | Take-back programs under France's AGEC law create first-mover advantages in EU hospitality procurement channels. |
| Tritan Crystal Capacity Expansion | Zwiesel Kristallglas AG anchors premium positioning through material durability claims in Austrian and Swiss Michelin venues. |
| Furnace Electrification Transition | EU F-Gas Regulation compliance drives capital reallocation toward electric and hydrogen-fired production lines in Bavarian clusters. |
Methodological Framework
Multiple input streams — primary interviews with hospitality procurement managers, glass manufacturing plant engineers, and specialty retail category buyers, alongside secondary validation from customs trade records, SEC filings of listed housewares companies, and EU regulatory databases — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across volume and value outputs applied segmentation dimensions of material technology, end-use application, style positioning, and regional manufacturing cluster. CAGRs were derived through trend extrapolation anchored in replacement cycle analysis and hospitality investment patterns. Industry-specific forecast inputs included ISO 7086 certification timelines and F-Gas Regulation compliance capital expenditure trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under energy cost volatility in Czech and Polish glassmaking regions and raw material concentration from Bavarian silica deposits. Forecasts reflect assumptions on regulatory implementation timelines and hospitality investment continuity. Material deviation in EU packaging regulation finalization or extended producer responsibility framework enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
Rose Wine Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Flavored Whiskey Market
Alcoholic Beverages
Cognac Market
Alcoholic Beverages
Pub Cellar Equipment Market
Alcoholic Beverages
Premixed Margarita Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
American Oak Barrels Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
Cognac Brandy Market
Alcoholic Beverages
Global Wine Market
Alcoholic Beverages
Wine Fermentation Equipment Market
Alcoholic Beverages
North America Spirits Market