
 Global Soju Market | 2026-2036
Global Soju Market Size, Share, and Industry Trends Forecast 2026-2036
Global Soju Market Outlook
Subscription-based soju discovery boxes and membership clubs is restructuring how producers build direct relationships with overseas consumers. HiteJinro Co., Ltd. leverages its decades-long brand equity to dominate shelf space in Korean-American retail corridors. Mackiss differentiates through hyper-localized flavor profiles targeting Southeast Asian palates. Lotte Chilsung Beverage Co., Ltd. extends its beverage logistics network to secure cold-chain distribution for premium soju lines.
Soju denotes a Korean distilled spirit traditionally produced from rice, wheat, or sweet potatoes, typically bottled at 16-25% alcohol by volume through single or multiple distillation methods, and consumed socially as an accompaniment to meals or in drinking rituals. Classic soju still occupies the largest volume share, though flavored variants now capture the fastest growth trajectory as younger consumers reject harsh ethanol burn. Premium soju commands disproportionate margin pools, with producers using extended aging and artisanal water sourcing to justify price multiples over standard lines.
South Korea's National Tax Service alcohol excise schedules, the FDA's labeling requirements for imported distilled spirits in the United States, and the EU's spirit drinks regulation with protected geographical indication standards collectively shape formulation choices, export compliance costs, and market access timelines for soju producers. Stakeholders must monitor how tightening WHO-aligned alcohol warning label mandates in target export markets interact with soju's traditional positioning as a lighter, sessionable alternative to Western spirits.
Market Dynamics
Korean cultural exports have normalized soju consumption in Southeast Asian markets, while North American urban centers are driving trial rates for flavored variants. Producers now face pressure to reposition portfolios across premium ABV tiers as taxation structures evolve.
Growth Catalysts
- Flavor Innovation Pipeline:Young adult consumers in Vietnamese and Philippine cities reject harsh ethanol burn, accelerating demand for fruit-infused and low-ABV variants that extend session length.
- MFDS Export Certification Streamlining:South Korea's consolidated food and drug safety protocols reduce compliance timelines for soju entering regulated markets, lowering market access friction.
- Korean Wave Cultural Embedding:K-drama and K-pop content distribution through Netflix and regional streaming platforms embeds soju rituals into aspirational lifestyle consumption across Southeast Asia.
Market Restraints
- Rice Input Cost Volatility:Climate-induced harvest variability across Korean and Chinese rice belts compresses margin predictability for traditional grain-based soju lines.
- Single-Market Production Concentration:Over 80% of soju volume originates from South Korean distilleries, creating geopolitical and logistics vulnerability for export-dependent brands.
- Substitute Spirit Competition:Japanese shochu and Chinese baijiu producers target identical Southeast Asian demographics with comparable price positioning and established distribution.
Strategic Opportunities
- Subscription Discovery Channels:Direct-to-consumer membership clubs bypass traditional three-tier alcohol distribution, capturing first-party data and building brand loyalty among diaspora populations.
- US FDA Labeling Harmonization:Simplified ingredient disclosure requirements for distilled spirits under 2023 guidance reduce reformulation costs for Korean exporters targeting American retail.
- Artisanal Water Sourcing Positioning:Premium lines leveraging volcanic spring provenance from Jeju Island command price multiples in Japanese and Australian duty-free channels.
Industry Challenges
- Cold-Chain Infrastructure Gaps:Premium soju variants requiring temperature-controlled logistics face last-mile breakdowns in Philippine and Indonesian distribution networks.
- Master Distiller Talent Scarcity:Traditional fermentation expertise concentrates among aging practitioners in Gyeonggi Province, constraining capacity expansion for heritage-method production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Soju Market |
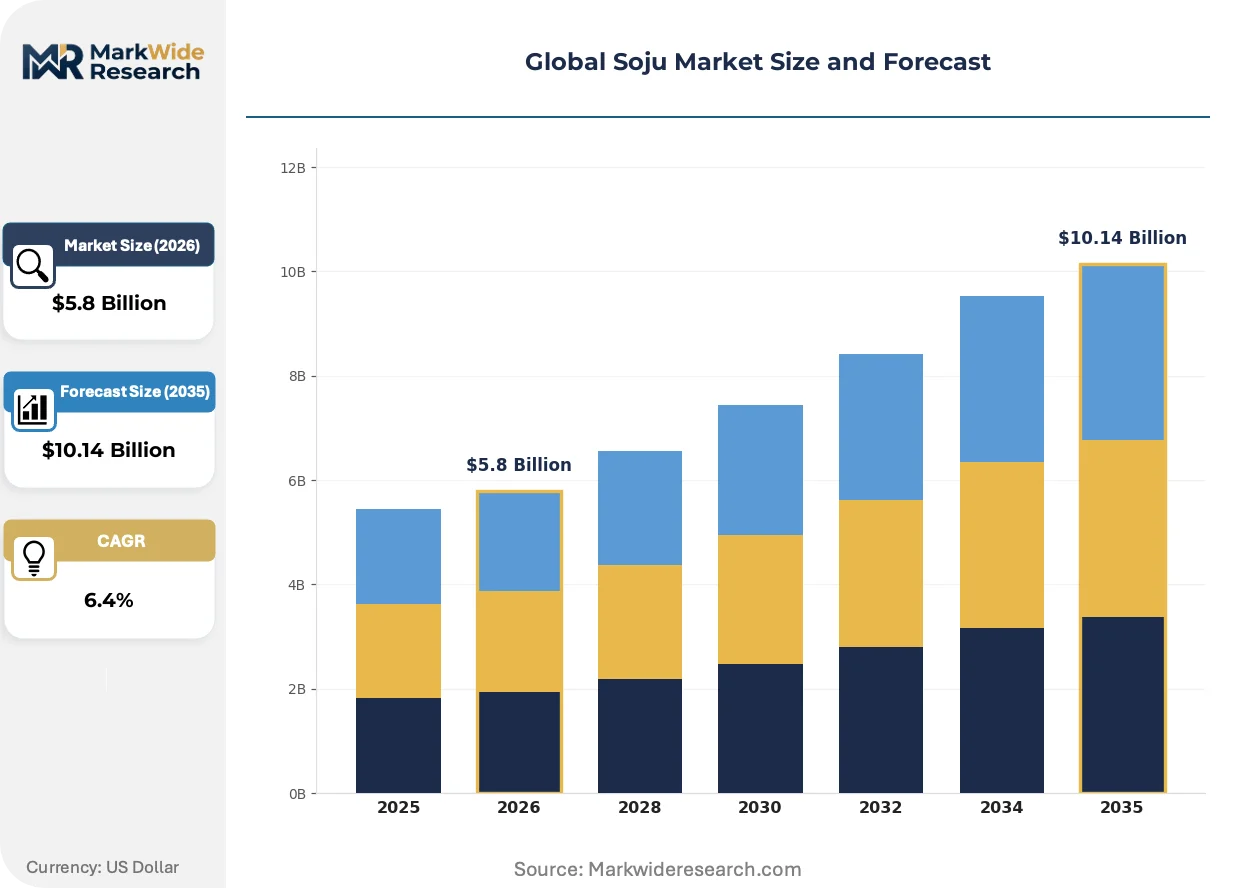
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Flavored, Infused, Premium Packaging Type: Bottle, Can, Carton, Keg Sales Channel: Supermarkets, Online Retail, Bars, Distributors End User: Individuals, Restaurants, Events, Retailers |
| Companies Covered | Muhak, OB Brewing Co., Ltd., HiteJinro Co., Ltd., Mackiss, Bohae, Lotte Chilsung Beverage Co., Ltd., Hwayo, Andong, Korea Alcohol Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Soju Market Strategic Shifts
Soju production is experiencing technology convergence across fermentation control, packaging sustainability, and digital consumer engagement. These shifts are compressing product development cycles while raising capital requirements for competitive positioning.
Precision fermentation monitoring using IoT sensor arrays is integrating into distillery operations across South Korea's major production facilities. Mid-tier producers adopt cloud-connected temperature and pH tracking to reduce batch inconsistency and ethanol waste. This technology is integrating quality control functions that previously required manual sampling, enabling smaller facilities to achieve export-grade certification.
The EU's spirit drinks regulation with protected geographical indication standards is tightening labeling requirements for Asian distilled spirits entering European retail. Korean exporters must now substantiate traditional production method claims through documented supply chain audits. Premium soju lines targeting German and French markets are responding by securing third-party organic and heritage process certifications.
Young consumers in North American metropolitan areas are gravitating toward curated discovery experiences over conventional retail selection. Subscription-based soju clubs and Korean-American grocery partnerships are displacing mainstream liquor store placement as the primary trial channel. This behavioral pivot is most visible in Los Angeles and New York, where direct-to-consumer shipments now outpace traditional distributor growth rates.
Global Soju Market Segmentation
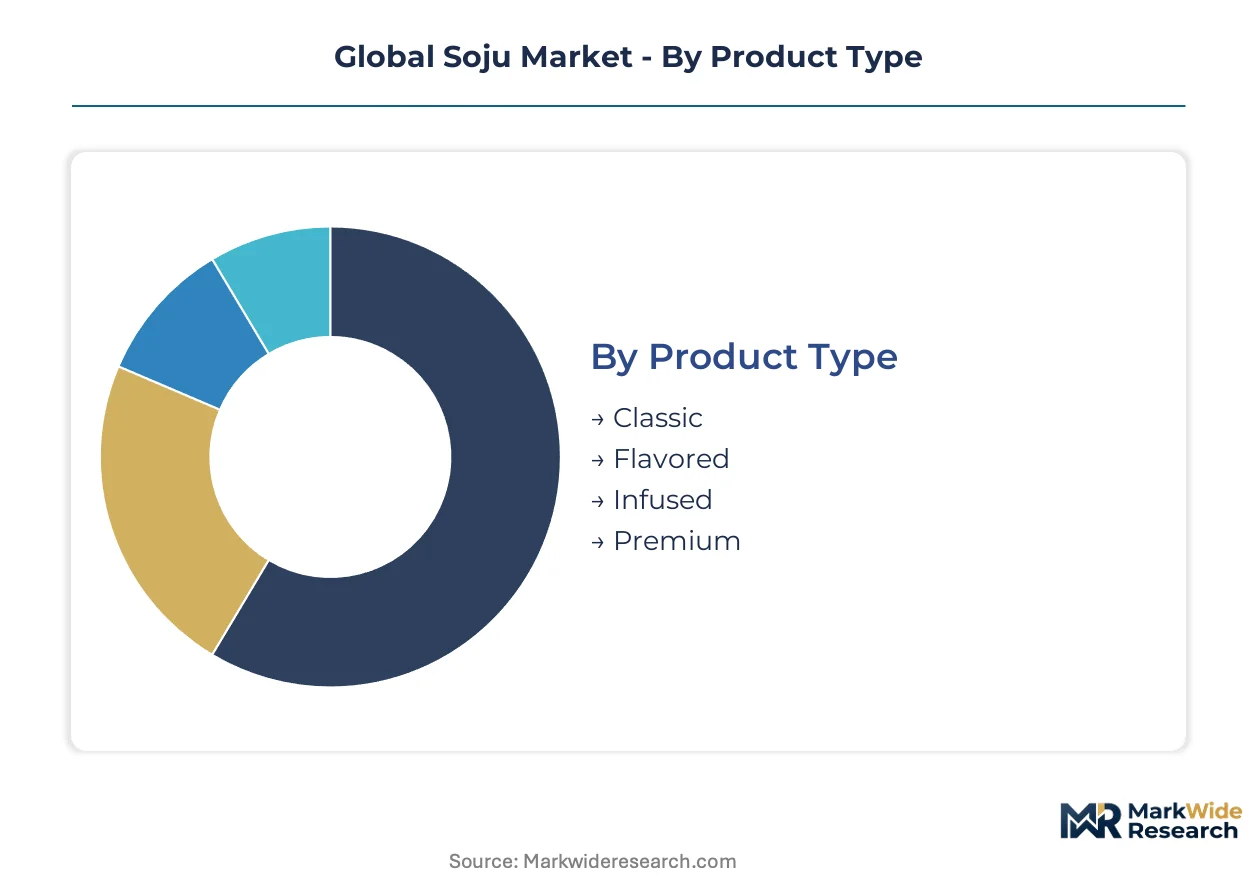
Soju producers allocate capital across distinct production and distribution configurations. Segment boundaries determine where fermentation capacity, packaging lines, and cold-chain investments deliver returns.
Product Type:
Capital intensity peaks with extended aging infrastructure and artisanal water sourcing systems.
- Classic:Traditional rice, wheat, or sweet potato formulations bottled at 16-25% ABV through single or multiple distillation methods. Volume concentrates in South Korean domestic channels and Korean-American retail corridors, constrained by rice input cost volatility across Korean and Chinese harvest belts.
- Flavored:Fruit-infused and low-ABV variants targeting rejection of harsh ethanol burn among young adult consumers. Vietnamese and Philippine cities drive trial acceleration as Korean cultural exports normalize soju rituals.
- Infused:Specialty botanical or herbal formulations requiring secondary maceration vessels.
- Premium:Extended aging and volcanic spring water provenance from Jeju Island commanding price multiples in Japanese and Australian duty-free channels.
Most installed capacity flows through Classic. Expansion is steepest in Flavored.
Packaging Type:
Distribution economics vary sharply by container weight, breakage risk, and temperature sensitivity.
- Bottle:Standard glass packaging dominating Korean-American grocery partnerships and traditional retail placement. Los Angeles and New York metropolitan areas show direct-to-consumer shipment growth outpacing distributor channels.
- Can:Aluminum formats penetrating convenience retail and outdoor consumption occasions in Southeast Asian markets where session length extension drives format experimentation.
- Carton:Multi-serve configurations for restaurant and event channels.
- Keg:On-premise dispensing systems for bars and entertainment venues.
Bottle retains the largest volume share. Can formats are gaining share fastest in urban Vietnamese and Philippine outlets.
Sales Channel:
Channel selection determines regulatory compliance burden and margin capture potential.
- Supermarkets:Mass retail placement requiring FDA labeling harmonization for US market entry under 2023 simplified ingredient disclosure guidance.
- Online Retail:Direct-to-consumer membership clubs capturing first-party data among diaspora populations, bypassing traditional three-tier alcohol distribution constraints.
- Bars:On-premise trial generation through Korean cultural embedding in K-drama and K-pop consumption rituals.
- Distributors:Three-tier system intermediaries facing pressure from subscription discovery channel displacement.
Supermarkets anchor volume throughput. Online Retail shows the steepest growth trajectory among North American urban centers.
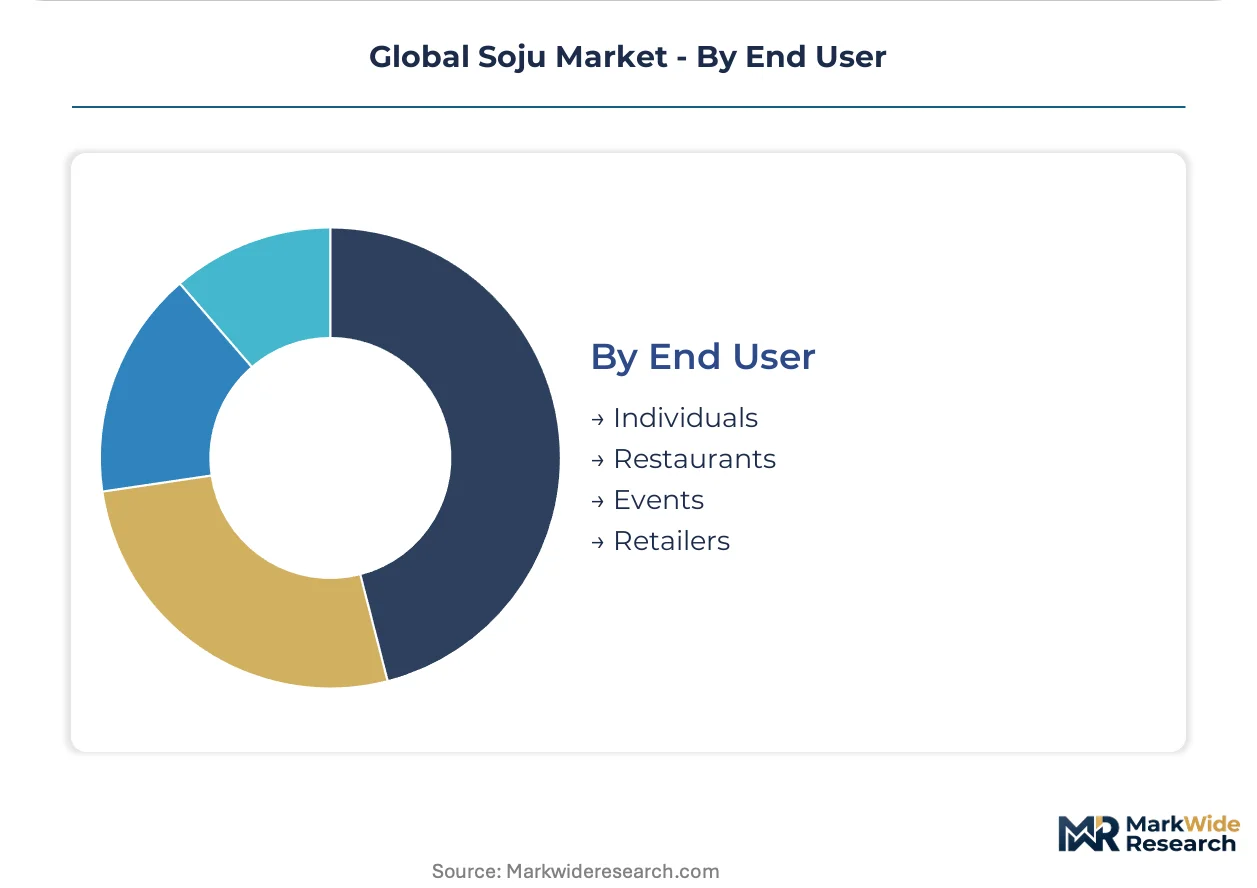
End User:
User categories dictate packaging configuration, ABV positioning, and occasion-based marketing.
- Individuals:Single-serve and discovery-box consumption through subscription channels.
- Restaurants:Bulk procurement with cold-chain reliability requirements.
- Events:Temporary permitting and large-format packaging logistics.
- Retailers:Inventory management and shelf-space negotiation with established Korean-American grocery networks.
Individuals generate the highest per-unit margin. Restaurants concentrate the largest absolute volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's soju consumption trajectory outpaces the United States in percentage terms, though American metropolitan markets generate higher absolute revenue per capita for premium lines. South Korea retains absolute production dominance, while the Philippines and Japan function as critical testbeds for format innovation and duty-free positioning respectively.
United States
Korean-American grocery partnerships in Los Angeles and New York drive direct-to-consumer shipment growth outpacing traditional distributor channels. The FDA's 2023 simplified ingredient disclosure guidance for distilled spirits reduces reformulation costs for Korean exporters targeting American retail. Cold-chain infrastructure investments concentrate in California and New York metro areas where subscription-based discovery clubs capture first-party data among diaspora populations.
South Korea
Domestic consumption anchors global volume, with Seoul Capital Area distilleries supplying over 80 percent of worldwide soju output. The National Tax Service's revised alcohol excise schedules pressure producers toward premium ABV repositioning to optimize tax tier placement. Gyeonggi Province fermentation expertise concentrates among aging practitioners, constraining heritage-method capacity expansion despite export demand acceleration.
Vietnam
Ho Chi Minh City and Hanoi young adult consumers reject harsh ethanol burn, accelerating trial rates for fruit-infused and low-ABV variants. Korean cultural exports through Netflix and regional streaming platforms embed soju rituals into aspirational lifestyle consumption. Can formats penetrate convenience retail and outdoor consumption occasions where session length extension drives format experimentation.
Philippines
Manila and Cebu metropolitan areas normalize soju as mainstream spirits category through K-drama and K-pop cultural embedding. Cold-chain infrastructure gaps create last-mile breakdowns for premium variants requiring temperature-controlled logistics. Aluminum packaging gains share fastest in urban outlets where outdoor consumption occasions favor portable formats.
Japan
Tokyo and Osaka duty-free channels command price multiples for Jeju Island volcanic spring water provenance positioning. The EU's spirit drinks regulation with protected geographical indication standards shapes labeling requirements for Asian distilled spirits entering European retail through Japanese transit. Japanese shochu producers compete for identical Southeast Asian demographics with comparable price positioning.
Global Soju Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with heritage distillers commanding premium shelf space while private-label operators capture volume in price-sensitive channels. The vendor base concentrates among South Korean conglomerates and mid-tier regional specialists, creating tiered competition across ABV positioning and flavor innovation cycles. Three archetypes dominate: legacy fermentation houses with Gyeonggi Province provenance, beverage conglomerates leveraging cross-category logistics networks, and boutique distillers targeting volcanic water terroir differentiation. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing cold-chain alliances to bypass infrastructure gaps in Southeast Asian distribution.
Among South Korea-based heritage specialists, HiteJinro Co., Ltd. and Lotte Chilsung Beverage Co., Ltd. occupy positions reflecting decades-long brand equity accumulation and beverage logistics network extension respectively. Mackiss represents the hyper-localization archetype, with flavor development patterns indicating Southeast Asian palate targeting. These three entities exemplify how scale-driven distribution, cross-category infrastructure leverage, and regional taste adaptation function as distinct competitive vectors within the category.
| Leading Market Players |
|---|
| Muhak |
| OB Brewing Co., Ltd. |
| HiteJinro Co., Ltd. |
| Mackiss |
| Bohae |
| Lotte Chilsung Beverage Co., Ltd. |
| Hwayo |
| Andong |
| Korea Alcohol Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
EU spirit drinks regulation with protected geographical indication standards gates qualified supply and premium-tier pricing access for Korean exporters targeting European retail. Producers must substantiate traditional production method claims through documented supply chain audits to secure organic and heritage process certifications that unlock price multiples in duty-free channels.
Pricing Analysis
Capacity additions in Vietnam and the Philippines are reshaping price floors for flavored soju variants as local bottling partnerships proliferate. Three-tier pricing structure across premium, standard, and economy levels separates Jeju Island volcanic water lines from mass-market formulations from Gyeonggi Province distilleries. Price differentiation hinges on certification grade and volume scale, with subscription discovery channels capturing margin premiums over traditional three-tier distribution. Cost compression in standard ABV tiers is intensifying because rice input volatility across Korean and Chinese harvest belts squeezes margin predictability. Restaurant buyers concentrate the largest absolute volume and exhibit highest price sensitivity, while duty-free consumers in Tokyo and Osaka show least sensitivity to premium positioning.
Supply Chain Analysis
South Korea's domestic-content mandates through MFDS export certification protocols are reshaping sourcing requirements for heritage-method production. Geographic supply concentrates in South Korea, China, and Vietnam, with over 80 percent of global volume originating from Seoul Capital Area distilleries. Raw material dependencies center on rice from Korean and Chinese belts, volcanic spring water from Jeju Island, and aluminum can stock from regional smelters. Single-source vulnerability creates geopolitical and logistics risk for export-dependent brands concentrated in Gyeonggi Province fermentation facilities. Distribution runs through Korean-American grocery partnerships in Los Angeles and New York, subscription-based direct-to-consumer clubs, and three-tier distributor networks facing channel displacement pressure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Demand is shifting toward premium specifications as young adult consumers in Vietnamese and Philippine cities reject harsh ethanol burn and embrace extended aging and artisanal water sourcing.
For Market Incumbents: Anchor heritage-method capacity in Gyeonggi Province against master distiller talent scarcity by securing apprenticeship pipelines with aging practitioners. Deepen backward integration into Jeju Island volcanic spring water sourcing to defend margin position against input cost volatility. Cold-chain infrastructure investments in California and New York metro areas reinforce channel control against subscription discovery displacement. For New Entrants and Emerging Players: Enter via white-space targeting of infused botanical formulations requiring secondary maceration vessels, where heritage incumbents maintain limited capacity. Philippine and Indonesian markets present most penetrable geography given cold-chain infrastructure gaps creating last-mile breakdowns for premium variants. Direct-to-consumer membership clubs offer the clearest go-to-market angle for capturing first-party data among diaspora populations. For Investors and Strategic Acquirers: Roll-up economics work for boutique distillers with volcanic water terroir differentiation because premium-tier pricing access depends on substantiated provenance claims under tightening EU labeling requirements. Long-term viability favors acquisition targets with documented heritage process certifications and established Korean-American grocery partnerships. The signal to watch is MFDS export certification streamlining velocity as indicator of market access friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Premium Tier Introduction | Jeju Island volcanic spring water provenance commands price multiples in Japanese duty-free channels. |
| Direct-to-Consumer Launch | Subscription discovery clubs bypass three-tier constraints and capture first-party data among diaspora populations. |
| Backward Integration | In-house production of heritage-method fermentation capacity secures supply against master distiller talent scarcity. |
| Distribution Channel Expansion | Cold-chain alliances with Vietnamese and Philippine logistics partners address last-mile infrastructure gaps. |
| Sustainability Repositioning | Third-party organic certifications substantiate traditional production claims under EU protected geographical indication standards. |
Study Parameters
Coverage spans South Korea, Vietnam, the Philippines, the United States, and Japan, with primary inputs from each market. The analysis combines structured interviews with distillery operations managers, Korean-American grocery category buyers, cold-chain logistics coordinators, MFDS regulatory affairs specialists, and subscription club membership directors. Secondary validation draws from MFDS export certification databases, FDA distilled spirits labeling guidance, EU spirit drinks regulation filings, and Korean National Tax Service excise schedules. Bottom-up volume triangulation across product type, packaging format, and sales channel dimensions integrates with top-down macroeconomic anchors.
Granularity-level modeling disaggregates volume and value outputs across classic, flavored, infused, and premium product types, with further segmentation by bottle, can, carton, and keg packaging configurations. Supermarket, online retail, bar, and distributor channel dynamics were modeled separately, as were individual, restaurant, event, and retailer end-user categories. CAGRs were derived through trend extrapolation of trial rate acceleration in Vietnamese and Philippine urban centers, tempered by rice input cost volatility assumptions. Industry-specific forecast inputs include K-drama and K-pop content distribution velocity through Netflix and regional streaming platforms.
Inputs from MFDS certification databases and Korean National Tax Service filings were available through the study window; gaps in real-time cold-chain infrastructure investment data for Philippine and Indonesian distribution networks introduce uncertainty bands around premium variant penetration assumptions. Forecasts reflect documented assumptions regarding cultural export embedding rates and taxation tier repositioning timelines. Regulatory tightening of WHO-aligned alcohol warning label mandates and climate-induced harvest variability represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
Wine Cork Market
Alcoholic Beverages
White Spirits Market
Alcoholic Beverages
Champagne Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
Global Liquor Confectionery Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
Wine Filtering Machine Market
Alcoholic Beverages
RTD Canned Cocktail Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Brandy Flavor Market
Alcoholic Beverages
Port Wine Market
Alcoholic Beverages
Whiskey Market
Alcoholic Beverages
India Tequila Market
Alcoholic Beverages
Beer Processing Market
Alcoholic Beverages
Vodka Market