
 South Africa Tequila Market | 2026-2036
South Africa Tequila Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Tequila Market Insights
Buyer concentration among premium hospitality groups is realigning procurement patterns across South Africa's tequila trade. PATRÓN Tequila leverages its luxury positioning to anchor supply agreements with high-end hotel chains and cocktail-forward venues. Diageo competes through portfolio breadth, while José Cuervo dominates mass-market shelf presence in national liquor retailers.
Tequila is a distilled spirit produced exclusively from Weber blue agave, with Blanco expressions bottled immediately after distillation while Reposado and Añejo categories undergo oak maturation of two months to three years. Blanco variants sustain the highest volume throughput in South Africa due to their utility in cocktail programs, yet Añejo and Extra Añejo segments capture disproportionate margin pools as consumers trade up within the category. The distribution channel dimension reveals structural tension: online and retail pathways expand geographic reach beyond traditional bar-centric strongholds, though bars remain critical for brand education and trial conversion.
The Liquor Products Act and National Liquor Authority regulate spirit classification, import documentation, and labeling requirements for tequila entering South Africa, with SARS customs enforcement adding compliance layers at port of entry. BIS-equivalent standards for food-contact materials and the country's national food safety regulator shape packaging and bottling specifications for domestic repackagers. Stakeholders must monitor pending excise adjustments and evolving e-commerce alcohol regulations to calibrate channel investment and pricing architecture.
Market Dynamics
Buyer consolidation among premium hospitality groups in Johannesburg and Cape Town is compressing supplier negotiation cycles and forcing tequila distributors to restructure their route-to-market economics around volume commitments rather than brand proliferation.
Growth Catalysts
- Cocktail-forward venue expansion:Premium bars in Gauteng and the Western Cape are dedicating expanded backbar space to agave spirits, creating dedicated pull-through for higher-margin expressions.
- Liquor Products Act clarity:South Africa's spirit classification framework provides import documentation standards that reduce customs friction for legitimate producers versus gray-market entrants.
- Urban retail density:Concentrated affluent consumer populations in Sandton and Camps Bay generate sufficient throughput to justify specialized tequila SKU allocation.
Market Restraints
- Agave supply concentration:Weber blue agave cultivation concentrates in Mexico's Jalisco highlands, exposing South African importers to single-origin climate and harvest volatility.
- SARS customs enforcement layers:Import documentation requirements at Durban and Cape Town ports create clearance delays that compress distributor working capital cycles.
- Local spirits substitution:South African brandy and cane spirits maintain entrenched price-positioning in mainstream hospitality accounts, limiting tequila's volume penetration.
Strategic Opportunities
- E-commerce alcohol liberalization:Pending regulatory adjustments to online spirits sales could unlock direct-to-consumer channels currently restricted under National Liquor Authority frameworks.
- Añejo education programs:Sustained investment in sipping-culture development among Cape Town's wine-accustomed consumers opens margin expansion beyond cocktail utility.
- Domestic repackaging partnerships:BIS-equivalent food-contact material standards enable local bottling operations that reduce landed cost and improve margin capture.
Industry Challenges
- Agave spirits sommelier scarcity:South Africa's hospitality training infrastructure produces limited specialist expertise in tequila terroir and production differentiation.
- Excise adjustment uncertainty:Pending National Treasury alcohol tax revisions complicate multi-year pricing architecture and inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Tequila Market |
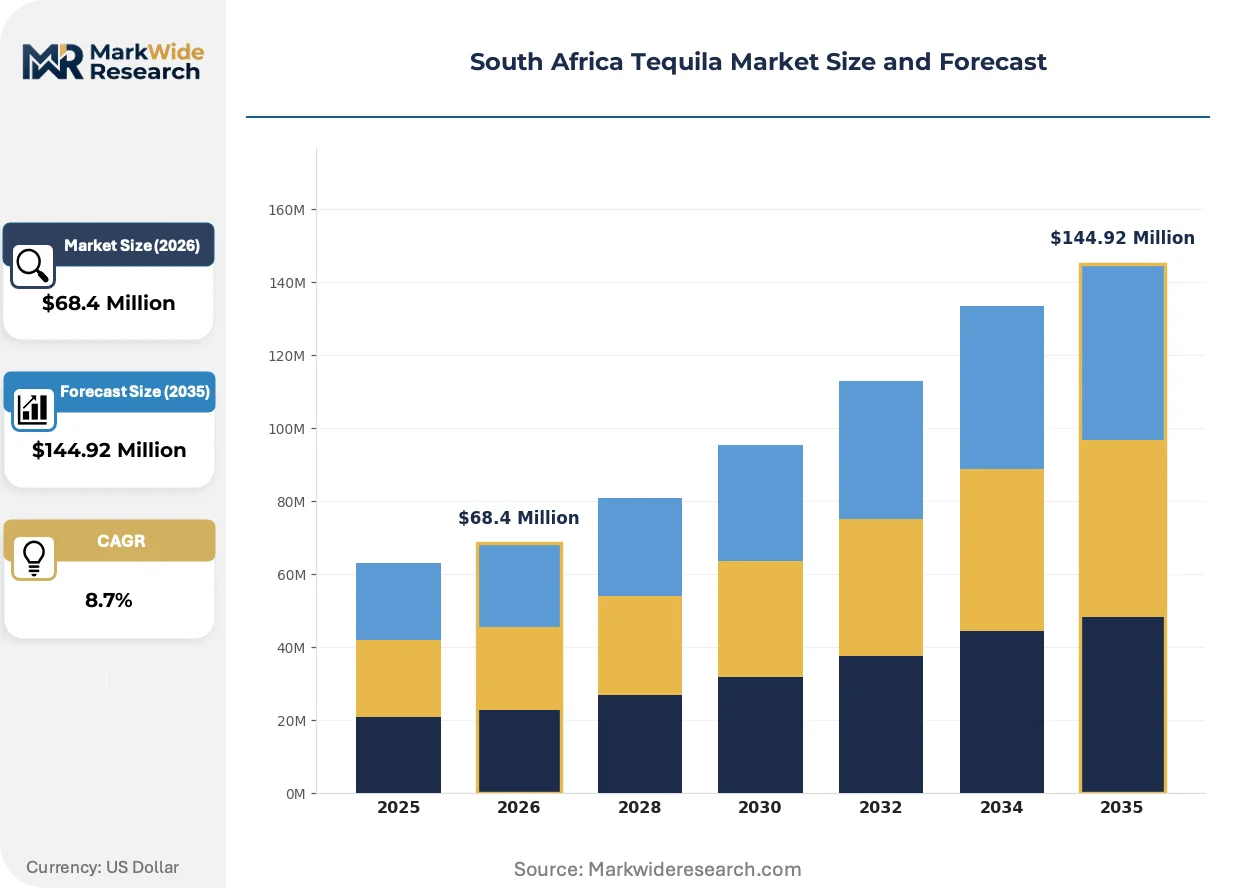
| Market Size in 2026 | $68.4 Million |
| Market Size in 2035 | $144.92 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blanco, Reposado, Añejo, Extra Añejo Distribution Channel: Retail, Online, Wholesalers, Bars Customer Type: Retail Consumers, Distilleries, Exporters, Event Organizers Serving Size: Shot, Cocktail, Mixed Drink, Neat |
| Companies Covered | Casamigos Tequila, PATRÓN Tequila, Campari Group, Pattern Brands, Brown-Forman, Diageo, Pernod Ricard, José Cuervo, Beam Suntory, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Tequila Market Trends and Innovations
Tequila's trajectory in South Africa is absorbing technology from adjacent premium spirits categories while regulatory pressure on packaging and labeling accelerates compliance investment. Three forces are restructuring competitive position.
Additive-free tequila certification is absorbing quality-signaling conventions from the single-malt whisky trade. Premium hospitality buyers in Johannesburg are screening suppliers for diffuser-free production claims and explicit additive disclosures. This filtration is compressing shelf space for mass-market brands that rely on glycerin or caramel coloring.
National Liquor Authority labeling enforcement is tightening origin documentation requirements for all agave spirits entering South African ports. The industrial consequence is accelerated distributor investment in traceability systems that map batch codes to Mexican distillery records. Añejo and Extra Añejo categories face the highest compliance burden due to extended supply chains and oak sourcing documentation.
Volume commitments from hospitality groups are displacing fragmented bar-by-bar procurement. Multi-outlet operators in Cape Town's Atlantic Seaboard corridor are consolidating supplier relationships around single-distributor agreements with guaranteed allocation security. This concentration is most visible in Gauteng, where casino-hotel complexes command dedicated import pipelines.
South Africa Tequila Market Segmentation
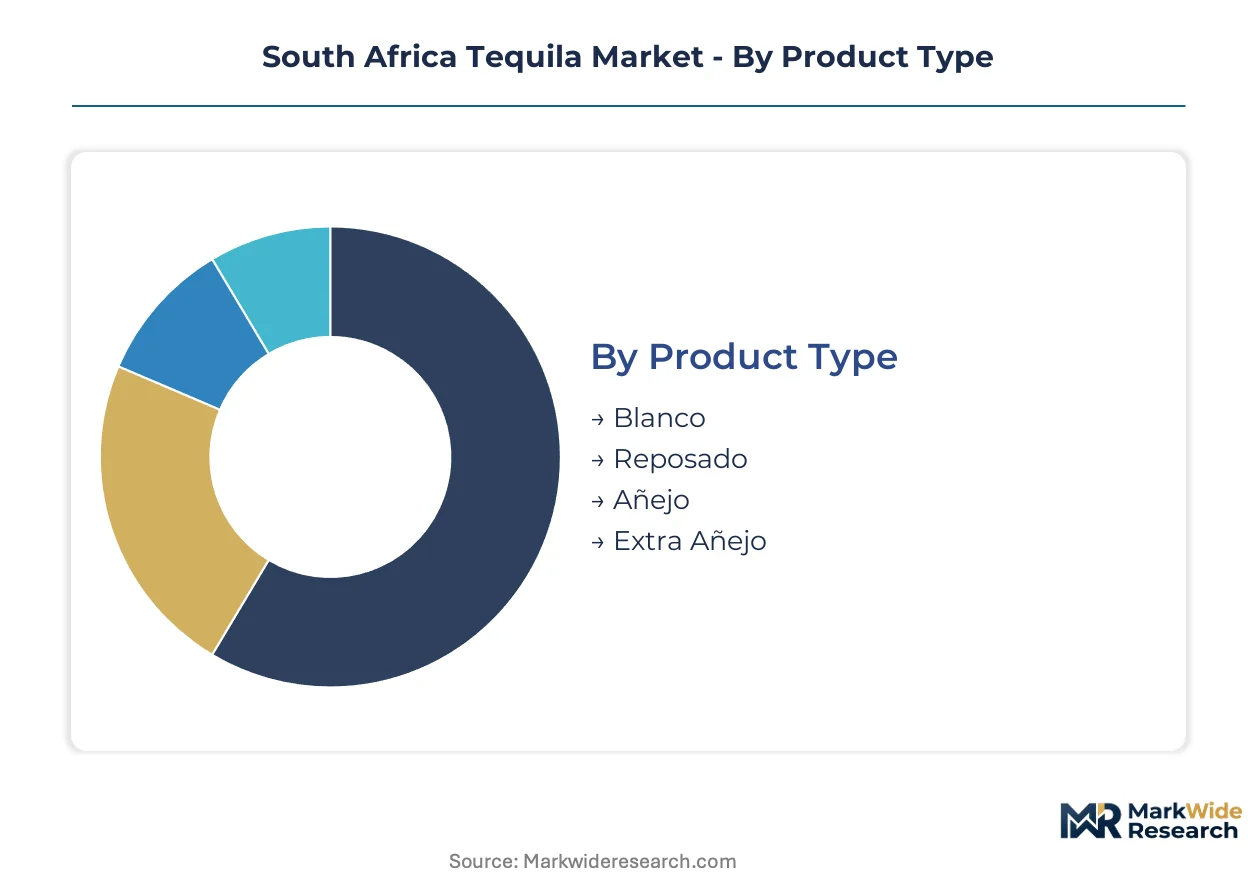
Tequila's commercial structure in South Africa fragments across production methodology, route-to-market economics, and consumption occasion. Each segmentation dimension reveals distinct margin profiles and regulatory exposure that shape distributor investment priorities.
Product Type:
Supply concentration in Jalisco's highlands distorts availability across maturation tiers, forcing South African importers to allocate scarce allocation slots strategically.
- Blanco:Unaged tequila bottled immediately after distillation preserves the purest agave character. Gauteng's cocktail bars in Sandton and Rosebank drive concentrated throughput for this format. The segment anchors volume commitments from premium hospitality groups seeking utility in margarita and paloma programs.
- Añejo:Oak-matured expressions aged one to three years develop vanilla and caramel complexity that commands sipping positioning. Cape Town's Atlantic Seaboard consumers, habituated to wine culture, absorb disproportionate allocation of these higher-margin SKUs. The National Liquor Authority's extended documentation requirements for aged spirits compress working capital cycles for this tier.
- Reposado:Two-to-twelve month oak contact balances agave brightness with wood influence; this intermediate tier serves trial conversion from cocktail to sipping occasions.
- Extra Añejo:Ultra-aged expressions exceeding three years in oak face the most severe supply constraints from Mexican distillery allocation systems.
Blanco absorbs the bulk of installed import capacity; Añejo is expanding most quickly as Cape Town's affluent consumers trade up within the category.
Distribution Channel:
Route-to-market economics in South Africa stratify sharply between on-premise education and off-premise scale, with regulatory friction varying by channel.
- Bars:Premium cocktail venues in Johannesburg and Cape Town function as critical brand education infrastructure. Mixologist training investments by PATRÓN and Diageo concentrate here. The channel generates trial conversion but compresses margin through service labor and glassware costs.
- Retail:National liquor chains and independent bottle stores in Gauteng and the Western Cape capture volume from affluent suburban consumers. Shelf space allocation favors established brands with proven velocity. The Liquor Products Act governs labeling compliance for all retail-facing SKUs.
- Online:E-commerce alcohol sales operate under restricted National Liquor Authority frameworks, with pending regulatory liberalization potentially unlocking direct-to-consumer growth.
- Wholesalers:Bulk distributors serve secondary cities and hospitality accounts outside the Johannesburg-Cape Town corridor, extending geographic reach at reduced margin.
Retail commands the greatest volume throughput; bars maintain the steepest expansion trajectory as dedicated agave programs multiply across premium venues.
Customer Type:
Procurement patterns diverge between end-consumers seeking occasion-specific solutions and commercial buyers optimizing for event or re-export economics.
- Retail Consumers:Urban affluent households in Sandton and Camps Bay purchase for home consumption and entertainment. This segment demonstrates willingness to trade up within the category when educated on production differentiation.
- Distilleries:Domestic bottling operations purchasing bulk tequila for repackaging under BIS-equivalent food-contact material standards.
- Exporters:Regional traders leveraging South Africa's port infrastructure to redistribute into Sub-Saharan African markets.
- Event Organizers:Corporate and private function planners sourcing volume for weddings, festivals, and hospitality activations.
Retail Consumers generate the highest margin per liter; Event Organizers are climbing the fastest as experiential consumption occasions proliferate.
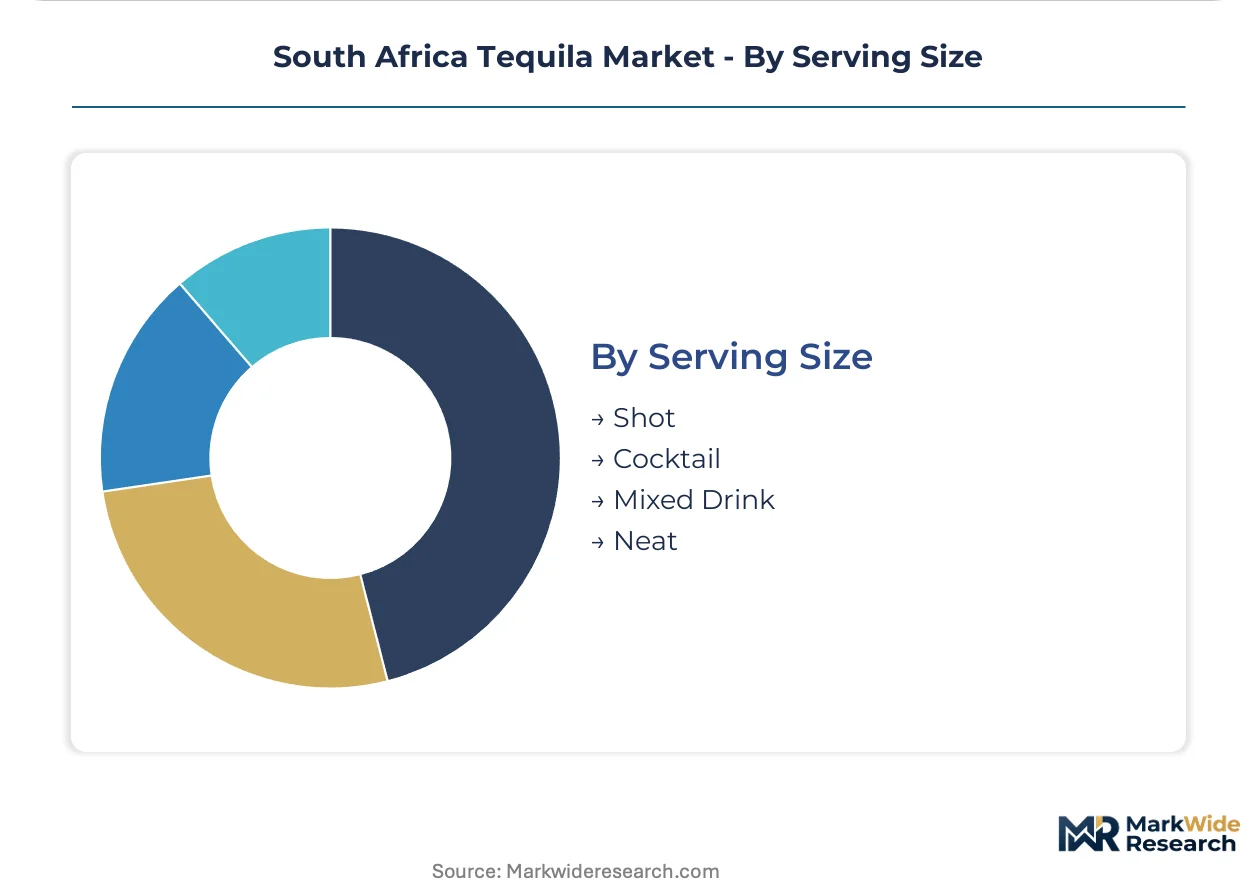
Serving Size:
Consumption format dictates pricing architecture and inventory velocity, with cocktail utility dominating volume and neat positioning capturing premium.
- Cocktail:Mixed serves in margaritas, palomas, and contemporary agave cocktails drive the majority of on-premise volume. Bartender creativity in Cape Town's premium venues expands repertoire beyond classic formats.
- Neat:Sipping occasions concentrate among Añejo and Extra Añejo expressions, with education investments required to shift consumer behavior from ice-and-mixer conventions.
- Shot:Rapid consumption format persists in mainstream nightlife accounts, though premium venues actively discourage this positioning.
- Mixed Drink:Long serves with juice or soda maintain accessibility for entry-level category entrants.
Cocktail serves absorb the bulk of on-premise volume; Neat consumption is gaining share fastest as sipping culture develops among Cape Town's wine-accustomed consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban affluent households in Gauteng and the Western Cape absorb the bulk of South Africa's tequila consumption, with metropolitan retail density and premium hospitality infrastructure driving demand concentration in these provinces.
Gauteng
Sandton and Rosebank's cocktail-forward venues anchor Blanco volume throughput for margarita and paloma programs. The National Liquor Authority's import documentation standards govern spirit classification for all tequila entering through Johannesburg's distribution hubs. Casino-hotel complexes in the province command dedicated import pipelines with guaranteed allocation security from Mexican distilleries.
Western Cape
Cape Town's Atlantic Seaboard consumers, habituated to wine culture, disproportionately absorb Añejo and Extra Añejo allocations for sipping occasions. The Liquor Products Act mandates strict labeling compliance for all retail-facing SKUs in national liquor chains. Camps Bay's premium hospitality groups are consolidating supplier relationships around single-distributor agreements with volume commitments.
KwaZulu-Natal
Durban's port infrastructure handles significant import volumes despite SARS customs enforcement layers creating clearance delays. The province's hospitality training infrastructure produces limited specialist expertise in tequila terroir, constraining brand education capacity. Umhlanga's emerging premium venue scene is expanding backbar space for agave spirits programs.
Eastern Cape
Port Elizabeth and East London's retail liquor channels serve secondary urban markets with established brandy and cane spirits entrenched in mainstream accounts. The province's event organizers are climbing fastest as experiential consumption occasions proliferate for weddings and festivals. Domestic repackaging partnerships under BIS-equivalent standards enable local bottling operations to reduce landed costs.
South Africa Tequila Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue additive-free certification and premium sipping positioning. The vendor base stratifies sharply between mass-market shelf presence and luxury hospitality anchoring. Three archetypes dominate: heritage Mexican distilleries with allocation-controlled scarcity, multinational spirits conglomerates with portfolio breadth, and celebrity-backed entrants with marketing velocity. Competitive moves concentrate on securing volume commitments from consolidated hospitality groups and investing in traceability systems for National Liquor Authority compliance.
Within the heritage distillery tier, PATRÓN Tequila and José Cuervo occupy positions as reference points for quality signaling and mass-market penetration respectively. Among multinational portfolios, Diageo and Pernod Ricard exemplify the conglomerate archetype leveraging distribution scale across Gauteng and Western Cape retail channels. Beam Suntory sits within the premium-standard intersection, representing the mid-tier specialist positioning that balances cocktail utility with sipping-culture development in Cape Town's wine-accustomed consumer base.
| Leading Market Players |
|---|
| Casamigos Tequila |
| PATRÓN Tequila |
| Campari Group |
| Pattern Brands |
| Brown-Forman |
| Diageo |
| Pernod Ricard |
| José Cuervo |
| Beam Suntory |
| Others |
Pricing and Supply Chain Analysis
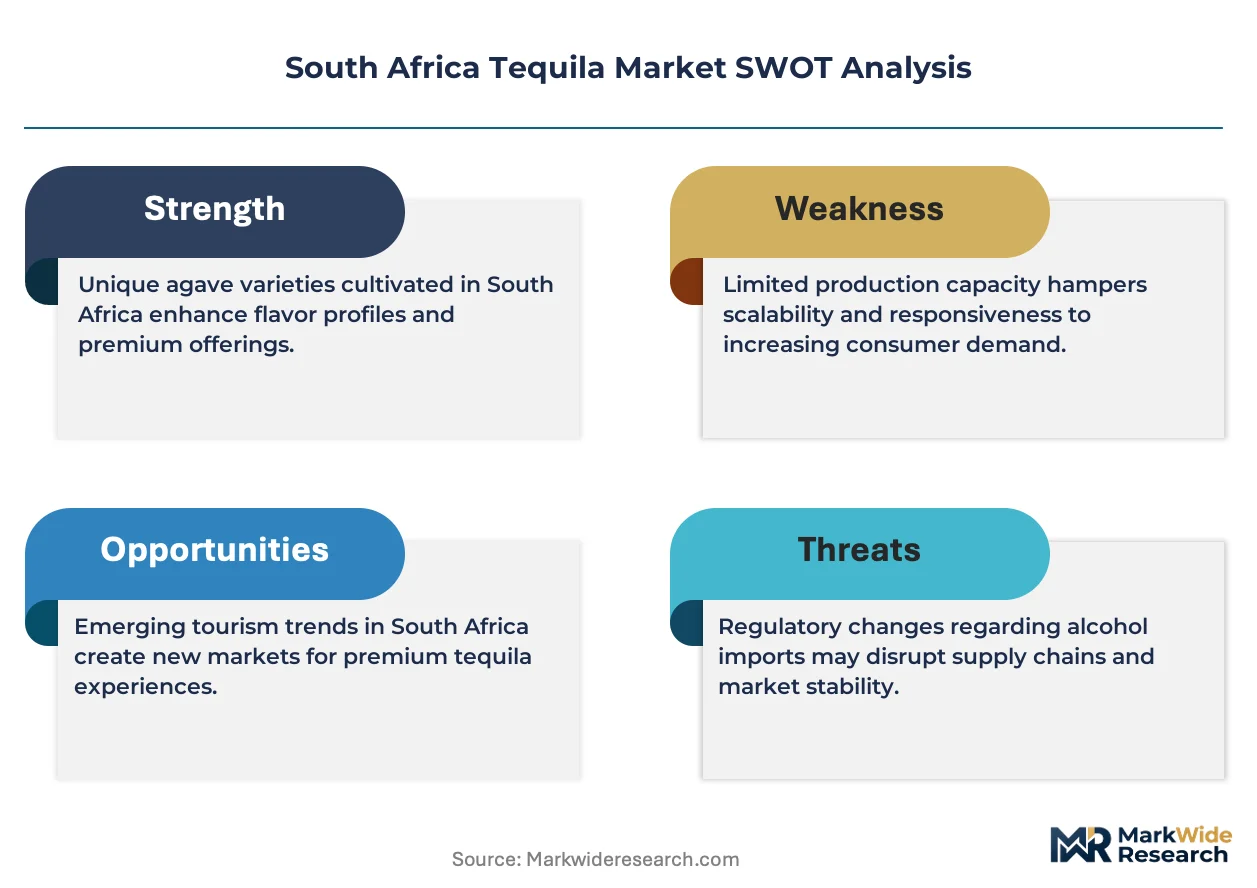
Additive-free certification requirements from Johannesburg's premium hospitality buyers simultaneously inflate production costs for Weber blue agave sourcing and compress margins for mass-market brands dependent on glycerin additives. This production-method transition concentrates pricing power among heritage distilleries with verified diffuser-free credentials while forcing distributors to absorb compliance documentation costs under the Liquor Products Act.
Pricing Analysis
Volume concentrates in Blanco expressions serving Gauteng's cocktail bars, while Añejo and Extra Añejo capture disproportionate margin pools among Cape Town's wine-accustomed sippers. Price differentiation rests on certification grade and brand heritage, with PATRÓN and additive-free entrants commanding premiums over José Cuervo's mass-market positioning. Pricing pressure stems from SARS customs enforcement layers that compress distributor working capital cycles. Retail consumers in Sandton and Camps Bay demonstrate lowest price sensitivity; mainstream nightlife accounts in secondary cities exhibit highest elasticity.
Supply Chain Analysis
South Africa's BIS-equivalent food-contact material standards enable domestic repackaging partnerships that reshape sourcing economics for bulk tequila imports. Supply concentrates in Mexico's Jalisco highlands, with secondary dependencies on American oak for Añejo maturation and European glass for premium bottling. Single-origin agave cultivation exposes importers to climate volatility and harvest cycle disruption. Distribution runs through Johannesburg and Cape Town distribution hubs serving consolidated hospitality groups, with Durban's port infrastructure handling clearance under SARS documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's tequila market is consolidating around volume commitments from premium hospitality groups, with buyer concentration forcing smaller distributors toward exit or acquisition. The National Treasury's pending excise adjustments accelerate this consolidation by complicating multi-year pricing architecture for undercapitalized players.
For Market Incumbents: Deepen backward integration into Mexican distillery allocation agreements to secure guaranteed supply pipelines for Añejo and Extra Añejo expressions. PATRÓN and Diageo should expand mixologist training infrastructure to defend against agave spirits sommelier scarcity, while investing in traceability systems that map batch codes to distillery records for National Liquor Authority compliance.
For New Entrants and Emerging Players: Capture the sipping-culture white space among Cape Town's Atlantic Seaboard consumers habituated to wine terroir education. Target event organizers in the Eastern Cape's proliferating wedding and festival economy with volume pricing for experiential consumption occasions. Lead with additive-free certification and explicit production-method transparency to differentiate from mass-market shelf presence.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier specialists possessing established additive-free credentials and Cape Town hospitality relationships given Añejo's margin expansion trajectory. Long-term viability favors distributors with consolidated casino-hotel complex agreements and compliant traceability infrastructure. Monitor e-commerce alcohol liberalization signals from the National Liquor Authority as direct-to-consumer channel inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Additive-Free Certification Program | Premium hospitality buyers in Johannesburg screen suppliers for glycerin-free claims, compressing shelf space for mass-market brands. |
| Traceability System Investment | Batch-to-distillery mapping satisfies National Liquor Authority labeling enforcement and accelerates SARS customs clearance. |
| Mixologist Training Infrastructure | Specialized agave spirits education addresses sommelier scarcity and drives trial conversion in Cape Town's premium venues. |
| Domestic Repackaging Partnership | BIS-equivalent bottling operations reduce landed costs and improve margin capture for bulk import distributors. |
| E-Commerce Channel Preparation | Direct-to-consumer platform development positions early movers for pending National Liquor Authority regulatory liberalization. |
Research Methodology
Document review covered customs and trade data, National Liquor Authority regulatory filings, and hospitality industry procurement databases, complemented by interviews with brand managers at multinational spirits conglomerates, category buyers at national liquor chains, procurement leads at premium hotel groups, and distribution channel partners. Secondary validation drew from SARS import documentation standards, the Liquor Products Act regulatory framework, and BIS-equivalent food-contact material specifications. Bottom-up volume modeling triangulated against top-down category spend analysis.
Cross-referencing historical import velocity patterns against panel input from distributor allocation managers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include maturation tier, distribution channel, and regional consumption cluster. CAGRs were derived from trend extrapolation adjusted for regulatory and supply-side constraints. Forecast inputs incorporated agave harvest cycle volatility and pending excise adjustment scenarios.
The model holds under stable regulatory enforcement and continued premium hospitality expansion; deviation in National Treasury tax revisions or Jalisco climate disruption would shift volume and value trajectories. Forecasts reflect documented assumptions regarding buyer consolidation and certification adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Wine Filtering Machine Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Global Bourbon Market
Alcoholic Beverages
Moonshine Market
Alcoholic Beverages
N-Hexyl Alcohol Market
Alcoholic Beverages
Asia Pacific Beer Market
Alcoholic Beverages
Mexico Tequila Market
Alcoholic Beverages
Global Wine Coolers Market
Alcoholic Beverages
Gluten-Free Beer Market
Alcoholic Beverages
Rice Wine Market
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
Europe Craft Beer Market