
 Winetainer Market | 2026-2036
Winetainer Market Size, Share, and Industry Trends Forecast 2026-2036
Winetainer Market Analytics
Premium wine packaging is decoupling from commodity bulk transport in both material specification and buyer expectations. Schütz GmbH & Co. KGaA leverages its German manufacturing base to dominate intermediate bulk container quality tiers for industrial wine logistics. Maersk Container Industry anchors ocean-going refrigerated winetainer capacity, sustaining cold-chain integrity for transoceanic bulk shipments. COSCO Container Logistics competes on scale across Asia-Pacific port networks, positioning standardized units for high-volume export corridors.
A winetainer is a specialized shipping or dispensing vessel engineered for wine storage, transport, or service, typically incorporating oxygen-barrier linings, food-grade stainless steel or multilayer polymer construction, and temperature stabilization to preserve organoleptic properties. Bag-in-box configurations employ laminated film bladders with vacuum-sealed taps, extending shelf life post-opening while reducing packaging weight versus glass alternatives. Plastic materials lead volume production due to cost efficiency and shatter resistance, though glass retains margin concentration in premium retail channels where provenance signaling commands price premiums. The restaurant end-user segment represents the fastest-growing demand pool as on-premise operators adopt keg and bag-in-box formats to minimize waste and optimize pour economics.
EU REACH compliance governs chemical migration limits for all polymer winetainers entering European food-contact applications, while FDA regulations under 21 CFR 177 set analogous thresholds for U.S. market access. ISO 22000 and HACCP frameworks further shape manufacturing protocols, with auditors verifying traceability from resin sourcing through final sterilization. Stakeholders must monitor evolving extended producer responsibility mandates in France and Germany, where deposit-return schemes and recycled content quotas are restructuring material selection criteria and supplier qualification requirements.
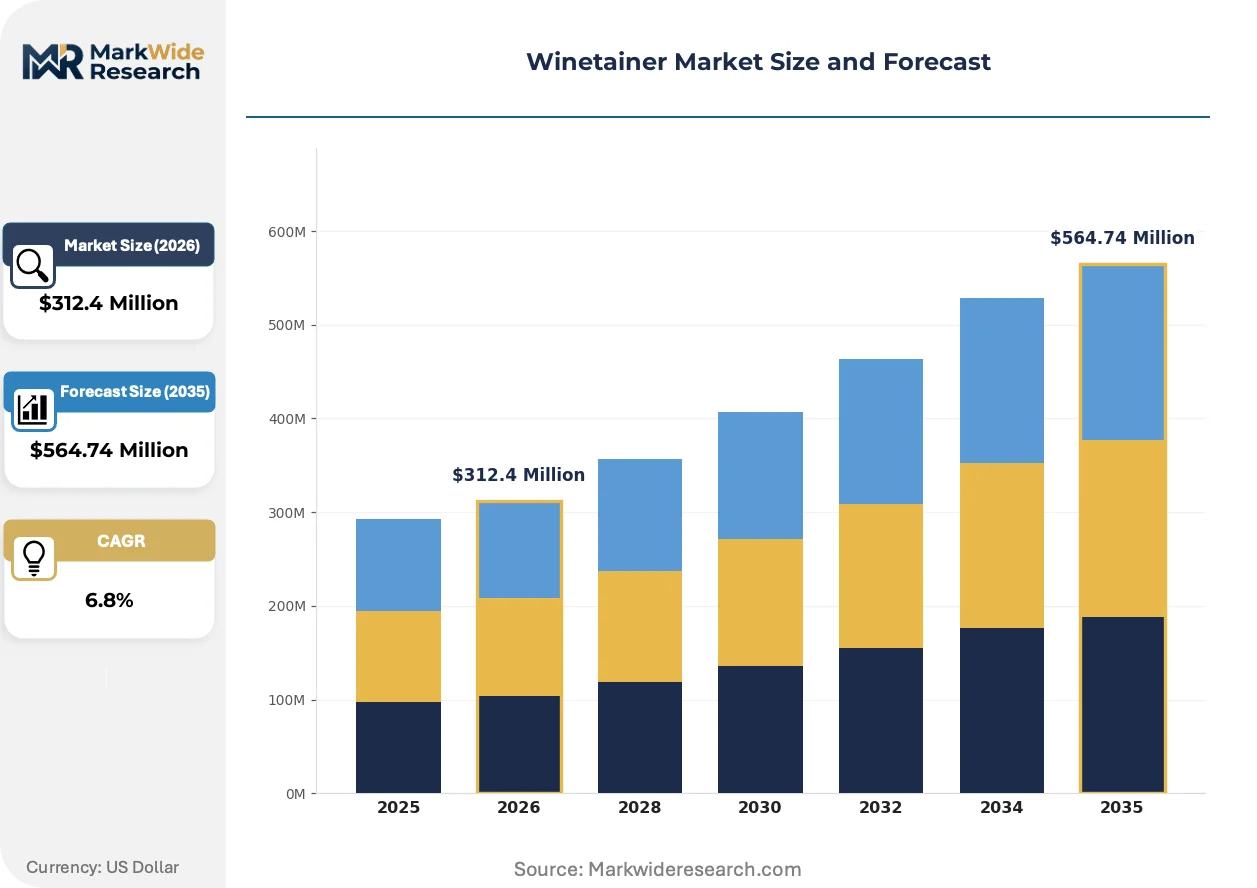
Market Dynamics
The EU F-Gas Regulation is compressing polymer formulation choices across the winetainer supply base, forcing rapid migration toward lower-emission barrier films while recyclability mandates in France and Germany restructure material sourcing protocols.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based barrier technologies is accelerating adoption of bio-based multilayer films in bag-in-box configurations across European food-contact applications.
- Restaurant on-premise segment:Operators in France and Italy are deploying keg and single-serve formats to eliminate spoilage losses and optimize pour economics during high-volume service windows.
- Wine tourism clusters:Refillable stainless steel systems are proliferating in tasting-room environments across Bordeaux and Tuscany where experiential consumption drives container reuse rates.
Market Restraints
- Ethylene-vinyl alcohol copolymer cost volatility:Oxygen-barrier resin prices fluctuate with petrochemical feedstock markets, compressing margins for multilayer film producers serving premium bag-in-box tiers.
- German stainless steel supply concentration:Intermediate bulk container fabrication relies on specialized rolling mills in the Ruhr region, creating geographic vulnerability for cold-chain vessel procurement.
- Glass substitution persistence:Provenance-signaling requirements in high-margin retail channels sustain demand for traditional bottling formats that compete directly with polymer winetainer penetration.
Strategic Opportunities
- Italian wine tourism corridor expansion:Underpenetrated refillable container deployment in Piedmont and Veneto tasting rooms offers white space for stainless steel rental and service models.
- Deposit-return scheme alignment:France's extended producer responsibility mandates create regulatory tailwind for recyclable substrate development and closed-loop collection infrastructure investment.
- Smart tap integration:Convergence of vacuum-seal dispensing with IoT-enabled inventory tracking is opening channel innovation for restaurant technology integrators seeking pour-data analytics.
Industry Challenges
- ISO 22000 auditor scarcity:Qualified food-safety certification bodies face capacity constraints verifying traceability from resin sourcing through sterilization across fragmented European supplier networks.
- REACH compliance timeline compression:Chemical migration testing protocols for novel barrier formulations extend product qualification cycles, delaying market entry for innovative film structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Winetainer Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bag-in-Box, Carton, Bottle, Keg Materials: Plastic, Glass, Aluminum, Composite End User: Retail, Restaurants, Events, Households Capacity: 250ml, 500ml, 750ml, 1L |
| Companies Covered | Schütz GmbH & Co. KGaA, Maersk Container Industry, COSCO Container Logistics, Tricon Containers, Textainer Group, Triton International, Container Applications International, Florens Container Leasing, Seaco Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Winetainer Market Evolving Landscape
Active barrier film electrification is compressing oxygen transmission rate benchmarks while regulatory chemistry restrictions and on-premise operational digitization simultaneously reshape competitive requirements.
Ethylene-vinyl alcohol nanolayer coextrusion is electrifying barrier performance in bag-in-box bladders, enabling sub-1 cc/m²/day oxygen transmission rates. French restaurant groups are adopting these films at accelerated replacement cycles to extend post-opening shelf life. The technology is electrifying margin compression across conventional metallized film suppliers unable to match organoleptic protection at equivalent weight.
EU F-Gas Regulation amendments are prohibiting high-global-warming-potential barrier chemistries in polymer winetainers entering European food-contact channels. Manufacturers must reformulate multilayer structures using bio-based alternatives or forfeit market access. German compounders are responding fastest, leveraging existing pharmaceutical film expertise to migrate wine-specific barrier specifications ahead of enforcement deadlines.
Inventory unbundling is fragmenting traditional procurement relationships between wineries and container suppliers. Restaurant operators now source keg and bag-in-box formats through beverage service intermediaries rather than direct mill relationships, compressing supplier visibility into consumption patterns. This behavioral shift is most visible in Paris and Milan where consolidated hospitality groups centralize packaging procurement across multi-site portfolios.
Winetainer Market Segmentation
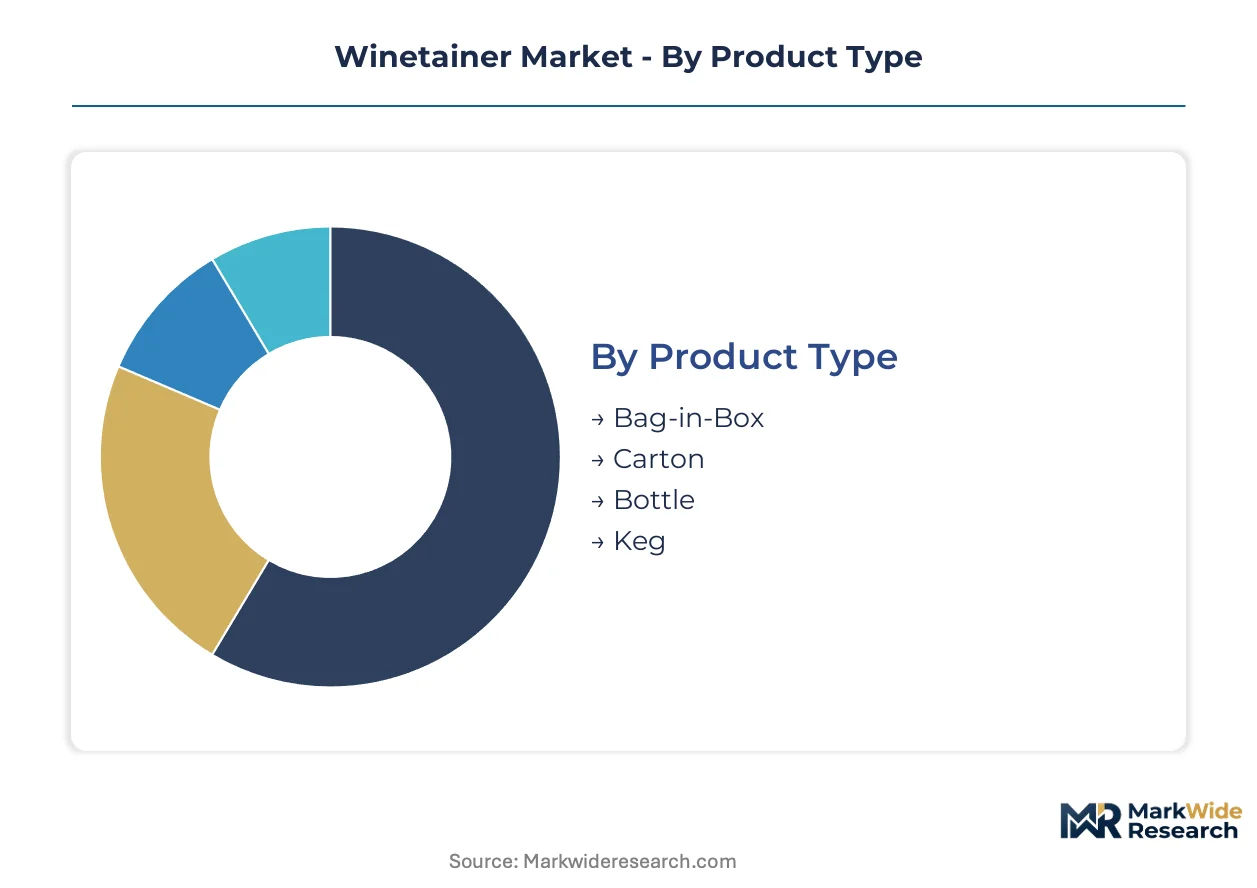
Winetainer segmentation reveals divergent supply chain architectures across product formats and material classes. Each category carries distinct procurement protocols, barrier specifications, and end-user service requirements that reshape supplier qualification criteria.
Product Type:
Supply concentration in bag-in-box film extrusion diverges sharply from stainless steel keg fabrication networks.
- Bag-in-Box:Laminated multilayer bladders with vacuum-sealed taps dominate French and Italian restaurant procurement for portion control and spoilage reduction. Parisian hospitality groups centralize purchasing through beverage service intermediaries, compressing direct mill relationships.
- Keg:Stainless steel vessels with oxygen-barrier linings sustain cold-chain integrity for transoceanic bulk shipments. German rolling mills in the Ruhr region anchor fabrication capacity, creating geographic vulnerability for procurement planning.
- Bottle:Traditional glass formats retain margin concentration in premium retail channels where provenance signaling commands price premiums.
- Carton:Gable-top and brick formats serve entry-tier retail segments with cost-efficient liquid packaging board construction.
Today's leader: Bag-in-Box. Tomorrow's challenger: Keg.
Materials:
Cost tier stratification separates commodity polymer feedstocks from specialized barrier substrates.
- Plastic:Polyethylene and polypropylene resins lead volume production due to cost efficiency and shatter resistance. EU F-Gas Regulation amendments are forcing rapid migration toward lower-emission barrier films and recyclable substrates.
- Glass:Borosilicate and soda-lime compositions retain margin concentration in premium retail channels. Provenance-signaling requirements in high-margin segments sustain demand despite polymer penetration.
- Aluminum:Lightweight barrier protection for single-serve formats in events and outdoor consumption occasions.
- Composite:Multilayer structures combining polymer barriers with structural substrates for optimized performance-to-weight ratios.
Plastic commands volume. Glass commands margin. Composites are gaining share fastest in sustainability-focused procurement.
End User:
Application-specific requirements fragment container specifications across consumption occasions.
- Restaurants:On-premise operators in France and Italy deploy keg and bag-in-box formats to minimize waste and optimize pour economics during high-volume service windows. Inventory unbundling through beverage service intermediaries is reshaping supplier visibility.
- Retail:Supermarket and specialty store channels sustain glass bottle demand for gift and cellar-assortment positioning.
- Events:Outdoor and temporary service occasions favor lightweight plastic and aluminum formats for logistics efficiency.
- Households:Residential consumption patterns concentrate in standard bottle and bag-in-box sizes for refrigerator storage compatibility.
Restaurants drive format innovation. Retail sustains traditional packaging. Events and households follow cost and convenience signals.
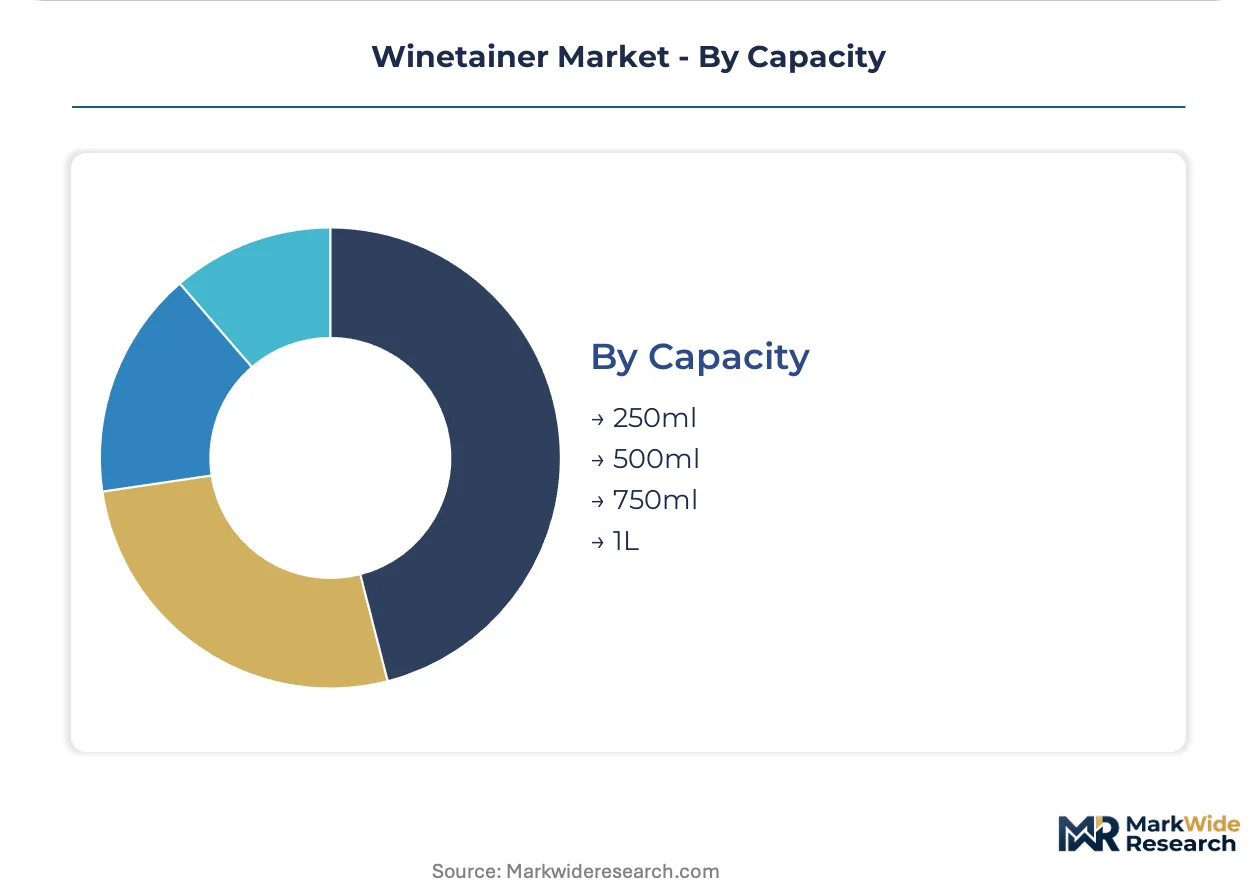
Capacity:
Volume scale determines barrier specification intensity and distribution economics.
- 750ml:Standard retail bottle format matching traditional wine service conventions. Bordeaux and Tuscany tasting rooms deploy refillable stainless steel systems at this scale for experiential consumption.
- 1L:Bag-in-box and carton formats optimize household and restaurant inventory turns with extended post-opening shelf life.
- 250ml:Single-serve portions for airline, hotel, and events channels requiring portion control and waste elimination.
- 500ml:Mid-tier format bridging individual and shared consumption occasions with flexible channel placement.
750ml anchors retail. 1L is climbing the fastest in restaurant and household adoption. 250ml and 500ml serve niche portion-control requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized metallurgical and polymer engineering talent concentrates in Germany's Ruhr industrial basin, anchoring stainless steel winetainer fabrication capacity. French polymer chemists in Lyon and Paris drive multilayer barrier film innovation. Italian mechanical engineers in Emilia-Romagna sustain keg system integration expertise.
Germany
Ruhr-based rolling mills supply cold-rolled stainless steel for intermediate bulk container shells, serving transoceanic wine logistics. REACH compliance mandates govern chemical migration limits for all polymer linings entering European food-contact channels. Bavarian compounders near Munich reformulate bio-based barrier films ahead of EU F-Gas Regulation enforcement deadlines.
France
Parisian hospitality groups centralize bag-in-box procurement through beverage service intermediaries, compressing direct supplier relationships. Extended producer responsibility mandates under France's deposit-return scheme restructure recyclable substrate development priorities. Bordeaux tasting rooms deploy refillable stainless steel systems where experiential consumption drives container reuse rates.
Italy
Tuscan wine tourism clusters sustain refillable container uptake in tasting-room environments across Chianti and Montalcino. ANSM food-contact regulations align with EU-wide chemical safety thresholds for polymer winetainers. Piedmont and Veneto operators represent underpenetrated white space for stainless steel rental and service model expansion.
United States
FDA regulations under 21 CFR 177 set chemical migration thresholds for polymer winetainers accessing American food-contact markets. California's Central Valley wine producers evaluate bag-in-box formats for export logistics efficiency. Pacific Northwest cold-chain operators test refrigerated container specifications for bulk transoceanic shipments.
China
SAMR food-contact standards govern polymer barrier specifications for domestic wine packaging applications. Yangtze River Delta polymer compounders scale multilayer film production for regional bag-in-box demand. Ningbo-Zhoushan port infrastructure supports standardized container deployment across Asia-Pacific export corridors.
Winetainer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent supply chain positions. Stainless steel fabricators anchor cold-chain vessel production with captive metallurgical capacity, while polymer film specialists outsource resin conversion to compounder networks. Three archetypes dominate: integrated metallurgical manufacturers, multilayer film compounders, and container leasing intermediaries. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing rolling mill access or beverage service distribution channels.
Within the integrated manufacturing tier, Schütz GmbH & Co. KGaA exemplifies German-based metallurgical fabrication archetypes, while Maersk Container Industry occupies a position anchoring ocean-going refrigerated capacity. COSCO Container Logistics represents scale-driven Asia-Pacific port network coverage. These three entities illustrate the geographic specialization pattern separating European quality-tier fabrication from Asia-Pacific volume logistics.
| Leading Market Players |
|---|
| Schütz GmbH & Co. KGaA |
| Maersk Container Industry |
| COSCO Container Logistics |
| Tricon Containers |
| Textainer Group |
| Triton International |
| Container Applications International |
| Florens Container Leasing |
| Seaco Global |
| Others |
Value Network & Pricing Analysis
Family-owned German rolling mills in the Ruhr region anchor stainless steel winetainer fabrication, translating captive metallurgical capacity into pricing discipline that resists commodity volatility while polymer film suppliers compete on thinner margins through outsourced resin conversion networks.
Pricing Analysis
The bundled-versus-unbundled service split separates equipment-only transactions from full-service leasing arrangements with maintenance and logistics support. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 22000 certification status and barrier film performance specifications. Pricing pressure stems from ethylene-vinyl alcohol copolymer cost volatility compressing margins for multilayer film producers. Restaurant operators in France and Italy exhibit highest price sensitivity due to inventory unbundling through beverage service intermediaries, while transoceanic bulk shippers prioritize cold-chain integrity over unit cost.
Supply Chain Analysis
Workforce availability constraints in German metallurgical engineering and French polymer chemistry clusters concentrate specialized fabrication capacity in the Ruhr and Lyon regions. Raw material dependencies center on cold-rolled stainless steel from Ruhr mills, bio-based barrier resins from Bavarian compounders, and laminated film substrates from Parisian extrusion facilities. Single-source vulnerability in German stainless steel supply creates geographic concentration risk for intermediate bulk container procurement. Distribution runs through beverage service intermediaries in Paris and Milan, compressing direct mill relationships and fragmenting supplier visibility into consumption patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The winetainer market offers margin expansion through bio-based barrier film adoption that commands premium positioning while EU F-Gas Regulation compliance costs eliminate lower-tier competitors unable to reformulate multilayer structures.
For Market Incumbents: Cement metallurgical fabrication dominance by securing long-term rolling mill capacity agreements in the Ruhr region ahead of regional supply constraints. Deepen backward integration into bio-based barrier resin production to capture margin from EU F-Gas Regulation-driven substitution, while investing in IoT-enabled smart tap inventory systems to defend against technology integrators entering the restaurant channel. For New Entrants and Emerging Players: Enter via underpenetrated Italian wine tourism corridors in Piedmont and Veneto where refillable stainless steel rental models remain nascent. Target Parisian hospitality groups consolidating procurement across multi-site portfolios with closed-loop collection infrastructure aligned to France's extended producer responsibility mandates. Lead with beverage service intermediary relationships rather than direct mill positioning to bypass entrenched supply relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional polymer compounders lacking pharmaceutical film expertise to pivot toward wine-specific barrier specifications. Long-term viability favors entities with demonstrated REACH compliance pathways and established auditor relationships that compress product qualification cycles. Watch Italian tasting-room refillable container deployment rates as the inflection signal indicating experiential consumption model maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Barrier Film Migration | EU F-Gas Regulation enforcement deadlines force rapid reformulation toward lower-emission multilayer structures. |
| Smart Tap IoT Integration | Convergence of vacuum-seal dispensing with inventory analytics opens restaurant technology channel partnerships. |
| Ruhr Rolling Mill Capacity Lock | Geographic concentration in German stainless steel supply creates procurement priority for cold-chain vessel fabricators. |
| Italian Wine Tourism Expansion | Piedmont and Veneto tasting rooms represent white space for refillable container rental and service models. |
| Deposit-return Scheme Alignment | France's extended producer responsibility mandates create regulatory tailwind for recyclable substrate development investment. |
Research Methodology
Bottom-up restaurant and hospitality procurement modeling reconciled against top-down stainless steel and polymer film production tracking forms the analytical core of this study. Primary interviews with beverage service intermediaries, restaurant procurement directors, polymer compounder technical leads, and ISO 22000 certification auditors combined with secondary validation from EU F-Gas Regulation filings, REACH compliance databases, French and German extended producer responsibility scheme disclosures, and customs trade data for wine packaging imports. Triangulation across these sources ensures segmentation integrity across bag-in-box, keg, and refillable format categories.
The input-output matrix maps ethylene-vinyl alcohol resin supply constraints and bio-based barrier film adoption curves against restaurant keg and bag-in-box deployment rates across the analysis window. Segmentation dimensions include product format, material class, end-user application, and capacity tier, with CAGRs derived from trend extrapolation of wine tourism cluster expansion and on-premise operator format conversion. Forecast inputs incorporate EU F-Gas Regulation phasedown timelines and Italian tasting-room refillable system penetration assumptions.
The model holds under stable regulatory enforcement timelines and continued wine tourism recovery; deviation in barrier resin cost volatility or auditor capacity constraints would shift qualification cycle assumptions and market entry timing. Forecasts reflect documented assumptions regarding bio-based film performance parity and restaurant inventory unbundling persistence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Chardonnay Market
Alcoholic Beverages
Hard Tea Market
Alcoholic Beverages
Rotels Market
Alcoholic Beverages
Non-Fuel Grade Alcohol Market
Alcoholic Beverages
Pinot Noir Market
Alcoholic Beverages
US Alcohol E-Commerce Market
Alcoholic Beverages
Instant Wine Chillers and Refreshers Market
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
South Korea Tequila Market
Alcoholic Beverages
Coconut Alcohol Market
Alcoholic Beverages
Canned Alcoholic Beverages Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Global Premium Alcoholic Beverage Market
Alcoholic Beverages
Global Red Wine Market
Alcoholic Beverages
Edible Alcohol Market
Alcoholic Beverages
Beer Bottle Market