
 Beer Bottling Kit Market | 2026-2036
Beer Bottling Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Bottling Kit Market Outlook
Asset-light leasing models for semi-automated bottling lines is reconfiguring competitive entry barriers for craft producers. Krones AG leverages its engineering scale to dominate turnkey systems for mid-size breweries. Craft a Brew specializes in compact, consumer-grade kits that anchor the home brewing channel. Wild Goose Filling competes through counter-pressure technology leadership in canning and bottling hybrids.
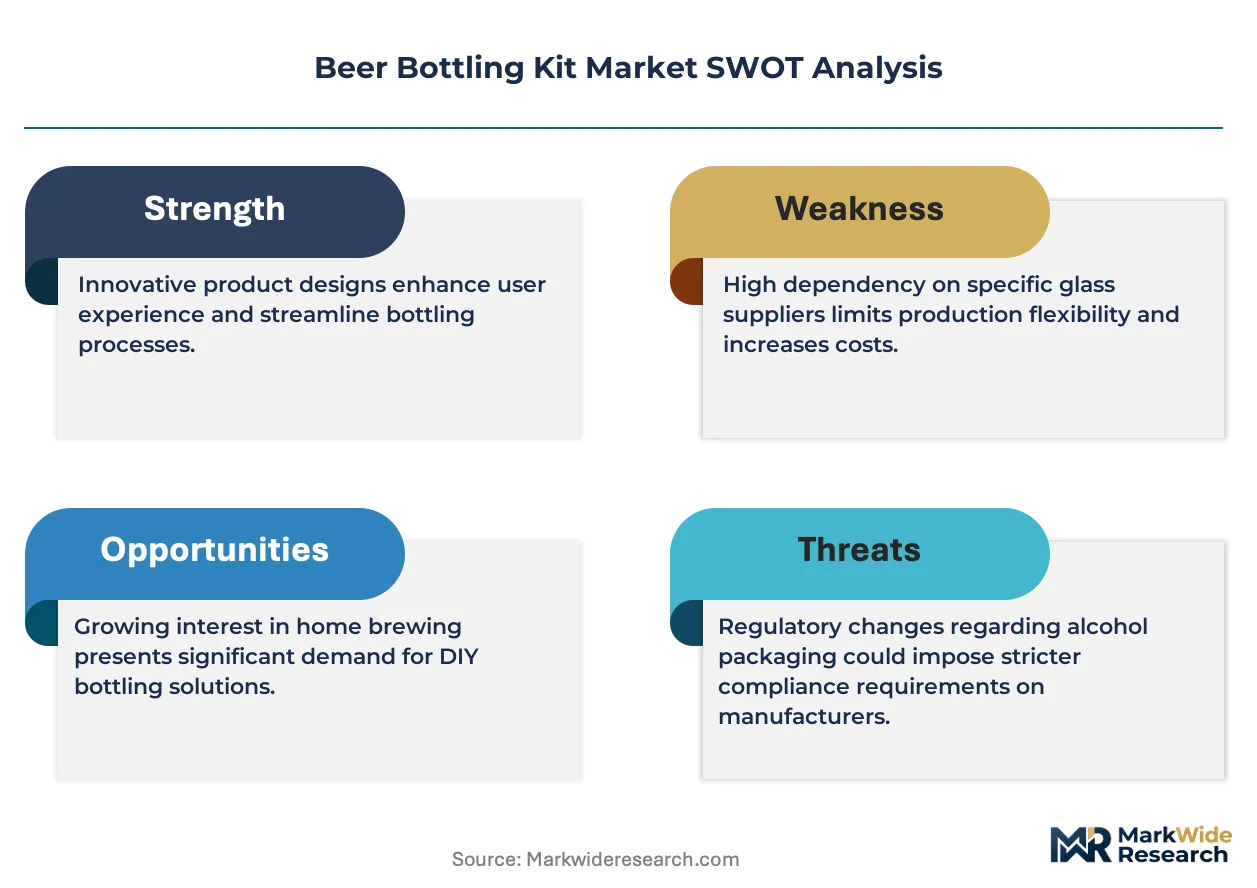
Beer bottling kits comprise integrated equipment assemblies—typically including fillers, cappers, labelers, and conveyance systems—designed to package fermented beverages into sealed containers at volumes ranging from five to five hundred bottles per hour. Their primary purpose spans commercial brewery production, home brewing operations, and foodservice dispensing applications. Stainless steel configurations command premium positioning due to corrosion resistance and compliance with food-contact regulations. Small-format kits targeted at home brewers represent the fastest-expanding segment, while large-scale glass systems sustain mature demand from established European breweries.
EU REACH standards govern chemical safety in food-contact materials, compelling manufacturers to certify stainless steel grades and adhesive formulations. FDA food-contact regulations shape product specifications for kits entering the United States, while Germany's KBA-adjacent equipment safety frameworks influence mechanical design standards. Stakeholders must monitor evolving material compliance requirements across multiple jurisdictions to sustain market access.
Market Dynamics
Asset-light leasing models for semi-automated bottling lines are compressing capital barriers for craft producers, enabling microbreweries to access professional-grade packaging without full equipment ownership.
Growth Catalysts
- EU REACH material compliance:Stainless steel certification requirements under ECHA frameworks are elevating product specifications, creating pull for premium-grade kits in Germany and neighboring markets.
- Home brewing channel expansion:Craft beverage culture diffusion is accelerating small-format kit demand among residential consumers seeking production control.
- Counter-pressure filling technology:Advanced carbonation preservation methods are displacing gravity-fed systems in quality-sensitive applications.
Market Restraints
- Stainless steel input volatility:Nickel and chromium price swings compress margin predictability for equipment manufacturers dependent on food-grade alloys.
- German engineering concentration:KBA-adjacent safety framework expertise clusters in Central Europe, creating supplier geographic lock-in for compliance-critical components.
- Canning substitution pressure:Aluminum canning lines for craft beverages threaten glass bottling kit demand in mobile consumption segments.
Strategic Opportunities
- India craft brewery emergence:FSSAI food-contact regulations and PLI scheme incentives for food processing equipment create white space for mid-scale kit deployment.
- IoT-enabled predictive maintenance:Sensor integration with cloud diagnostics is hybridizing traditional mechanical systems into connected packaging assets.
- Direct-to-consumer channel development:Brewery taproom packaging for retail sale is opening bypass routes around traditional distributor equipment specifications.
Industry Challenges
- Multi-jurisdiction certification timelines:Sequential FDA, EU REACH, and national equipment safety approvals extend product launch cycles by 8-14 months.
- Legacy system integration friction:New modular kits face protocol mismatches with existing brewhouse control architectures, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Bottling Kit Market |
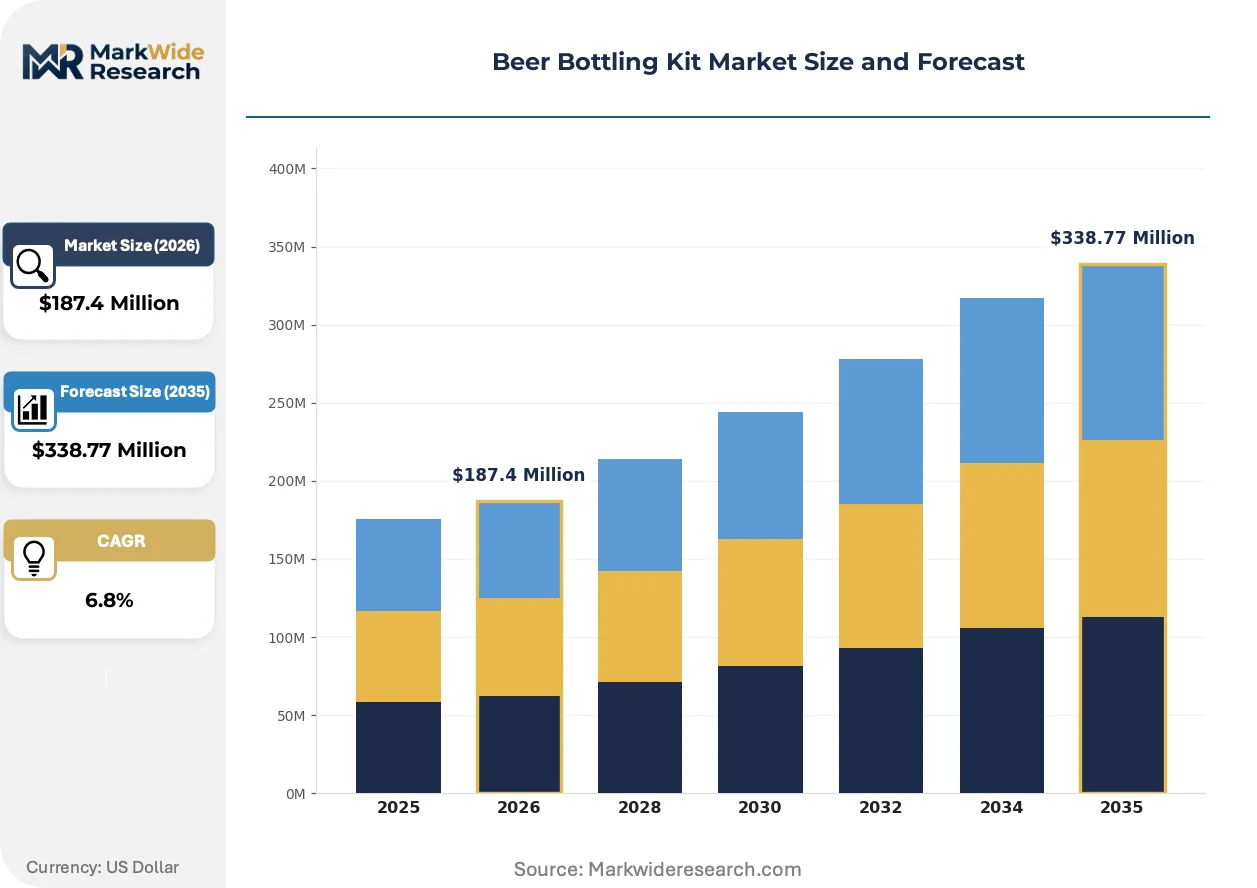
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kits, Bottles, Caps, Labels End User: Brewery, Home Brewer, Restaurant, Distributor Material: Glass, Plastic, Aluminum, Stainless Steel Size: Small, Medium, Large, Extra Large |
| Companies Covered | Krones AG, GEA Group, Alfa Laval, Pall Corporation, Pentair, Northern Brewer, Craft a Brew, Criveller Group, Wild Goose Filling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Bottling Kit Market Strategic Shifts
Equipment manufacturers are converging mechanical precision with digital connectivity, while regulatory frameworks harden material traceability requirements across supply chains.
Counter-pressure filling systems with integrated CO₂ recovery loops are hybridizing traditional bottling mechanics with closed-loop sustainability architectures. Mid-size craft breweries in Belgium and the Czech Republic are adopting these configurations to reduce carbonation loss and meet brewery carbon neutrality pledges. The technology is compressing operating cost differentials between manual and automated lines for sub-10,000 hectoliter producers.
Germany's KBA-adjacent equipment safety frameworks are mandating redundant emergency stop circuits and interlocked guarding on all new bottling installations. Mechanical design costs for CE-marked systems have risen 12-18% as manufacturers re-engineer legacy platforms. Small-format kit suppliers serving home brewing channels face disproportionate compliance burden relative to unit economics.
Taproom canning and bottling for immediate retail sale is fragmenting traditional three-tier distribution equipment procurement. California, Colorado, and Oregon brewers are purchasing compact self-contained lines that bypass distributor quality specifications. This channel disintermediation is compressing equipment decision cycles from 18-month capital planning to 90-day operational procurement.
Beer Bottling Kit Market Segmentation
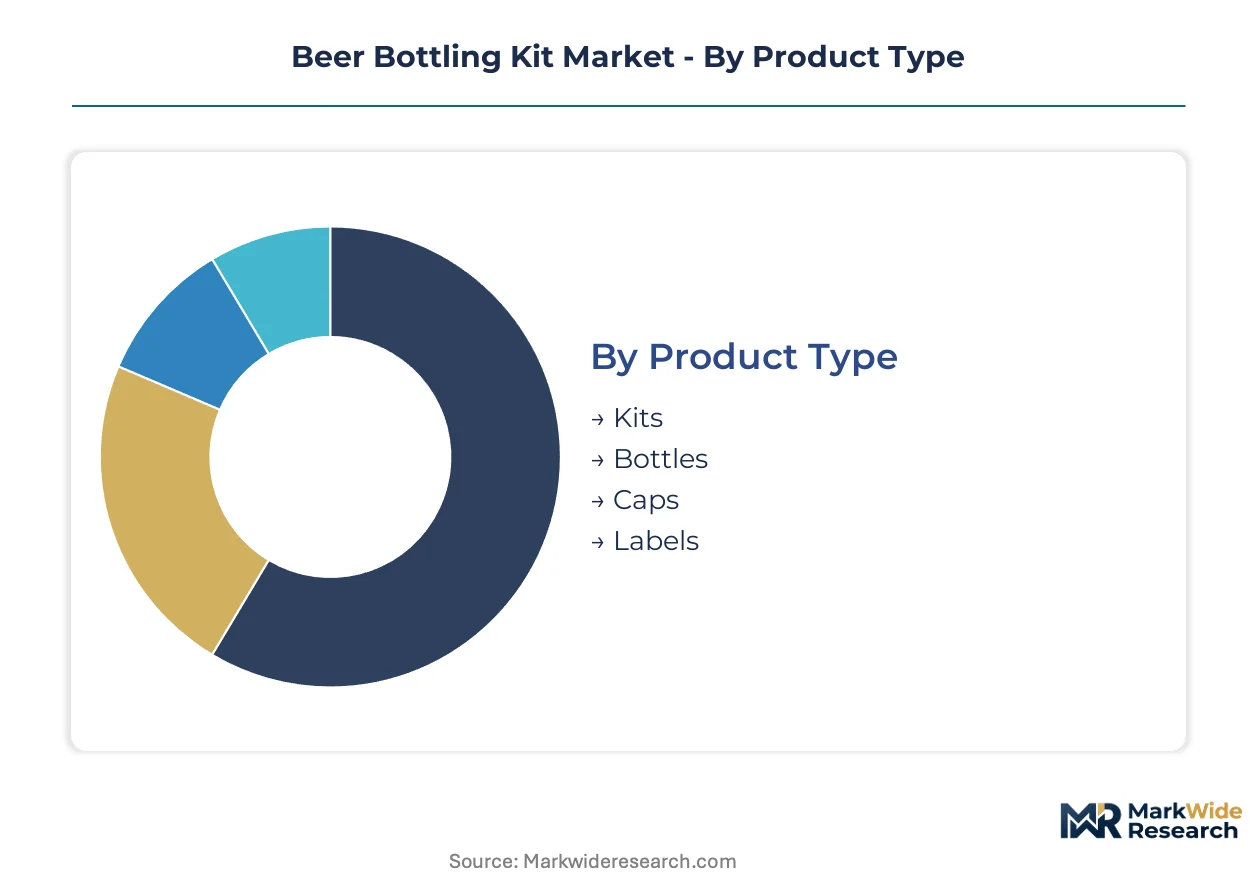
Segmentation in beer bottling kits reflects divergent capital intensities and regulatory exposure across buyer profiles. Equipment specifications fragment sharply between commercial-grade stainless steel systems and consumer-oriented compact assemblies.
Product Type:
Cost tier determines feature depth and automation level across the four product configurations.
- Kits:Integrated assemblies bundling fillers, cappers, and conveyance modules into single procurement packages. Demand concentrates among German home brewers seeking EU REACH-compliant stainless steel configurations as craft beverage culture spreads.
- Bottles:Container supply components including amber glass, clear flint, and specialty shapes for brand differentiation. Belgian and Czech craft breweries are adopting these for taproom retail bypassing traditional distributor specifications.
- Caps:Crown cork and screw-cap sealing mechanisms with oxygen-scavenging liners.
- Labels:Pressure-sensitive and cut-and-stack formats with adhesive formulations governed by FDA and ECHA frameworks.
Kits hold installed capacity. Bottles are rotating up the share rankings.
End User:
Application context shapes equipment scale and compliance burden across four distinct buyer categories.
- Brewery:Commercial production facilities requiring CE-marked systems with KBA-adjacent safety interlocks and redundant emergency stop circuits. German engineering clusters dominate procurement for mid-scale automated lines.
- Home Brewer:Residential consumers operating sub-five-hundred-bottle-per-hour systems. This segment is climbing the fastest as small-format kits penetrate craft beverage enthusiasts in Germany and neighboring markets.
- Restaurant:Foodservice operations packaging house-brewed products for on-premise consumption.
- Distributor:Third-party logistics providers with equipment specifications governing incoming product quality standards.
Brewery holds installed capacity. Home Brewer is rotating up the share rankings.
Material:
Volume throughput and corrosion resistance requirements drive material selection across food-contact applications.
- Glass:Traditional amber and flint containers with inert chemical properties preserving flavor profiles. Established European breweries in Germany sustain mature demand for large-scale glass systems despite aluminum canning substitution pressure.
- Stainless Steel:Food-grade 304 and 316L alloys with nickel and chromium content subject to price volatility. EU REACH certification requirements under ECHA frameworks are elevating specifications for premium-grade kit components.
- Plastic:PET and HDPE formats for lightweight logistics and shatter resistance.
- Aluminum:Canning substrates threatening glass bottling demand in mobile consumption segments.
Glass holds installed capacity. Stainless Steel is rotating up the share rankings.
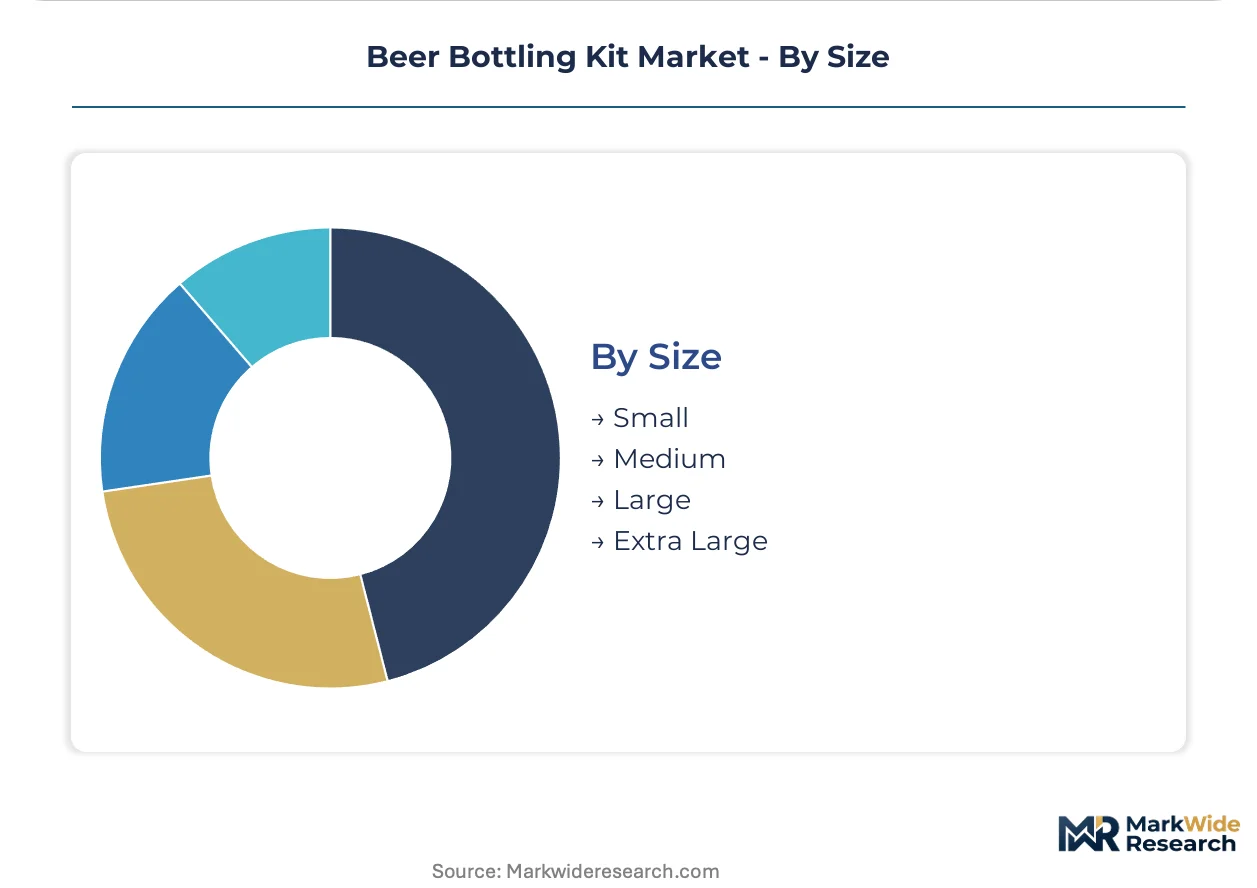
Size:
Customer operational scale and physical footprint constraints segment equipment dimensions.
- Small:Compact countertop systems under fifty bottles per hour for residential brewing operations. California, Colorado, and Oregon brewers are purchasing these for taproom packaging with ninety-day procurement cycles.
- Medium:Floor-standing semi-automated lines serving microbreweries with asset-light leasing models compressing capital barriers.
- Large:Fully automated configurations for regional production facilities.
- Extra Large:Turnkey systems exceeding five hundred bottles per hour for industrial-scale operations.
Large holds installed capacity. Small is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in beer bottling kits tilt toward German engineering dominance, with Central European manufacturers supplying turnkey systems to craft breweries across North America and Asia-Pacific. Import dependency for stainless steel components creates vulnerability to nickel and chromium price volatility in key consuming markets.
Germany
Traditional brewing heritage intersects with precision engineering demand as craft beverage culture spreads. KBA-adjacent safety frameworks mandate redundant emergency stop circuits and interlocked guarding on new installations. Bavaria and North Rhine-Westphalia host dense clusters of mid-scale automated line fabricators serving domestic and export markets.
United States
Taproom packaging for direct retail sale accelerates compact self-contained line procurement across California, Colorado, and Oregon. FDA food-contact regulations shape stainless steel grade specifications for imported kits. Pacific Northwest brewers compress equipment decision cycles from eighteen-month capital planning to ninety-day operational procurement.
Belgium
Carbon neutrality pledges drive adoption of counter-pressure filling systems with integrated CO₂ recovery loops. EU REACH certification requirements under ECHA frameworks elevate material traceability standards. Flemish craft breweries in the sub-10,000 hectoliter segment deploy these configurations to reduce carbonation loss.
India
FSSAI food-contact regulations and PLI scheme incentives for food processing equipment create deployment white space for mid-scale kits. Maharashtra and Karnataka emerge as craft brewery concentration zones. Mumbai and Bangalore host emerging equipment procurement clusters as asset-light leasing models penetrate the market.
Czech Republic
Small-batch equipment adoption accelerates among traditional lager producers diversifying into craft formats. CE marking requirements align with German KBA-adjacent safety standards for cross-border equipment flows. Prague and Plzeň anchor regional demand for hybrid canning-bottling configurations.
Beer Bottling Kit Market Competitive Environment
On the supply side, the industry is bifurcated between engineering-scale turnkey specialists and compact-format residential kit fabricators. Tiered competitive positioning separates premium stainless steel system architects from economy-grade plastic assembly suppliers. Strategic archetypes include full-line automation integrators, counter-pressure technology specialists, and direct-to-consumer home brewing equipment marketers. Dominant competitive moves center on geographic licensing partnerships and modular platform diversification.
Among German engineering-scale players, Krones AG exemplifies the turnkey system archetype for mid-size breweries. GEA Group occupies a position within the industrial processing equipment tier. Wild Goose Filling represents the counter-pressure technology specialist segment with canning-bottling hybrid configurations. These anchors illustrate how competitive positioning fragments across automation depth and buyer scale vectors.
| Leading Market Players |
|---|
| Krones AG |
| GEA Group |
| Alfa Laval |
| Pall Corporation |
| Pentair |
| Northern Brewer |
| Craft a Brew |
| Criveller Group |
| Wild Goose Filling |
| Others |
Value Chain & Pricing Dynamics
Bavaria and North Rhine-Westphalia engineering clusters anchor European capacity for CE-marked stainless steel systems, concentrating upstream fabrication power among German turnkey specialists who command premium positioning against Asian competitors serving economy-tier segments.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Stainless steel certification grade under EU REACH and FDA food-contact tier differentiation separate Krones AG-engineered systems from compact residential kits. Cost compression in mid-scale automated lines is intensifying because nickel and chromium price volatility feeds directly into food-grade alloy input costs. Home brewers exhibit highest price sensitivity, while established Bavarian breweries absorb premium positioning for KBA-adjacent safety compliance.
Supply Chain Analysis
Contract manufacturing for mechanical assemblies concentrates among precision metalworking foundries in Germany, Czech Republic, and Austria. Food-grade 304 and 316L stainless steel draws from specialized European mills, with electronic control modules sourced from industrial automation suppliers. Single-source vulnerability sits with nickel supply concentration for corrosion-resistant alloys. Distribution runs through direct brewery sales teams for large turnkey systems and specialized home brewing retailers for compact residential kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum canning line substitution threatens glass bottling kit incumbents across mobile consumption segments, forcing defensive repositioning around taproom-direct and carbonation-preservation technology differentiation.
For Market Incumbents: Insulate core brewery relationships by deepening counter-pressure filling technology moats and securing backward integration into stainless steel component fabrication. Krones AG-scale engineering specialists should anchor capacity addition in Czech Republic and Austria to dilute German geographic lock-in costs. Certification investment in FSSAI compliance opens India craft brewery white space before regional players consolidate.
For New Entrants and Emerging Players: Pursue asset-light leasing model penetration among Maharashtra and Karnataka craft breweries where PLI scheme incentives reduce equipment procurement friction. California, Colorado, and Oregon taproom packaging channels offer fastest penetrable geography given compressed ninety-day procurement cycles versus traditional distributor specifications. Direct-to-consumer home brewing equipment marketing through specialty retailers anchors viable go-to-market angle against Northern Brewer and Craft a Brew incumbency.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because engineering-scale automation specialists with KBA-adjacent safety expertise face irreplicable capability scarcity against Asian cost competitors. Target acquisition archetype: mid-scale Czech or Belgian counter-pressure technology specialists with CO₂ recovery loop integration. Monitor aluminum canning line adoption rates among sub-10,000 hectoliter craft breweries as inflection signal for glass bottling kit demand erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Counter-Pressure Technology Licensing | Belgian and Czech craft breweries adopt CO₂ recovery loops to meet carbon neutrality pledges. |
| Backward Integration into Stainless Steel Fabrication | GEA Group-scale players secure food-grade alloy supply chains against nickel price volatility. |
| Asset-Light Leasing Model Expansion | Maharashtra craft breweries access professional-grade packaging without full equipment ownership. |
| FSSAI Certification Investment | Wild Goose Filling-type specialists unlock India deployment white space ahead of regional consolidation. |
| IoT-Enabled Predictive Maintenance Platform | Sensor integration with cloud diagnostics hybridizes traditional mechanical systems into connected assets. |
Study Parameters
Operator-level perspectives from brewery operations managers, home brewing equipment retailers, stainless steel procurement leads, and food-contact regulatory consultants anchored the qualitative base. Primary interview intelligence combined with secondary validation from ECHA REACH substance databases, FDA food-contact substance notifications, German KBA equipment safety directives, and customs trade records for stainless steel processing machinery. Bottom-up equipment unit economics triangulated against top-down addressable market sizing across the analysis window.
Scenario-bracketing framed volume and value outputs over the projection horizon across product type, end user scale, material grade, and equipment size segmentation dimensions. CAGRs derived from equipment replacement cycle analysis, craft brewery formation rates, and home brewing channel penetration curves. Stainless steel input cost trajectories and EU REACH compliance timeline assumptions fed industry-specific forecast sensitivity testing.
Macroeconomic conditions sit as an overlay; deviation in nickel and chromium commodity prices, euro-dollar exchange rates, or craft beverage consumption sentiment would shift the trajectory. Forecasts reflect documented assumptions about regulatory approval timelines and technology substitution rates. Quarterly review of aluminum canning line adoption indicators, EU ECHA substance restriction proposals, and India PLI scheme equipment eligibility revisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Canada Alcohol E-Commerce Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Airport Duty-Free Liquor Market
Alcoholic Beverages
Beer Fermenter Market
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Moonshine Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
Gluten Free Alcoholic Drinks Market
Alcoholic Beverages
Dark Spirits Market
Alcoholic Beverages
Gin and Tonic Tea Market
Alcoholic Beverages
Pressurized Wine Filter System Market
Alcoholic Beverages
Beer Pasteurization Equipment Market
Alcoholic Beverages
Hard Tea Market
Alcoholic Beverages
Europe Tequila Market
Alcoholic Beverages
Luzhou-Flavor Liquor Market