
 North America Occupancy Sensors Market | 2026-2036
North America Occupancy Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Occupancy Sensors Market Analytics
Mexico's expanding manufacturing corridor for building automation components is reconfiguring regional supply availability for North American integrators. Johnson Controls leverages its vertically integrated building management portfolio to anchor large-scale commercial deployments across the United States. Schneider Electric competes through deep energy management software integration that extends hardware functionality into subscription-based service models. Lutron Electronics specializes in premium wireless control architectures that differentiate its occupancy sensing suites in high-end commercial and residential channels.
Occupancy sensors are electro-optical or acoustic detection devices that identify human presence within defined spatial zones through passive infrared detection, ultrasonic wave emission, or hybrid signal processing, typically operating at detection ranges of fifteen to thirty feet with adjustable time delays of five to thirty minutes before automatic load disconnection. Their primary commercial purpose is to eliminate energy waste from artificial lighting, HVAC conditioning, and ventilation in unoccupied building zones. Infrared sensors dominate unit shipments due to lower per-unit cost and simpler installation protocols, though dual technology sensors command superior margin pools where false-trigger immunity justifies premium positioning. Wired installations still occupy the majority of existing building stock, yet wireless technology segments are gaining fastest in new construction and deep retrofit applications where cabling costs prove prohibitive.
The United States Department of Energy enforces appliance and equipment standards that directly shape sensor performance thresholds and labeling requirements, while Canada's Natural Resources Canada administers parallel energy efficiency regulations through its EnerGuide and ENERGY STAR certification frameworks. State-level codes such as California Title 24 and ASHRAE Standard 90.1 impose mandatory automatic shutoff requirements that functionally mandate occupancy sensor deployment in commercial construction. Stakeholders must monitor divergence between emerging federal efficiency standards and patchwork state amendments that could fragment product certification requirements across provincial and state boundaries.
Market Dynamics
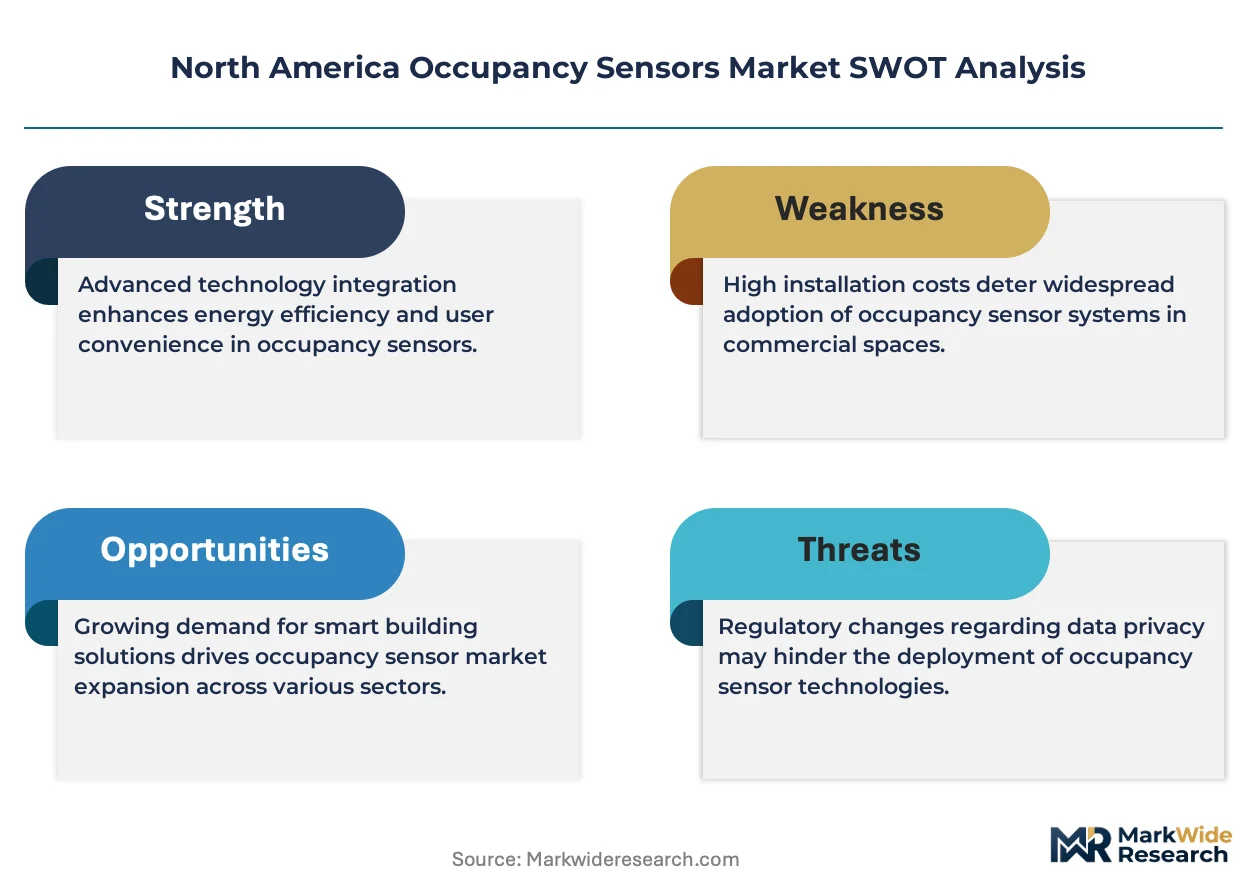
California Title 24 and ASHRAE Standard 90.1 are functionally mandating occupancy sensor deployment in commercial construction, compressing installation timelines and rewiring procurement priorities across the United States and Canada.
Growth Catalysts
- California Title 24:Mandatory automatic shutoff requirements in commercial buildings are accelerating retrofit activity in the state's existing building stock.
- Passive infrared sensors:Lower per-unit cost and simpler installation protocols are driving unit shipment volumes across Texas and Florida commercial corridors.
- Utility rebate programs:Canada's provincial utilities are subsidizing smart building technology procurement, reinforcing adoption momentum in Ontario and British Columbia.
Market Restraints
- Copper and semiconductor input costs:Volatility in wiring and chip pricing compresses hardware margins for wired installation segments.
- Dual technology sensor premiums:Ultrasonic-infrared hybrid units face demand elasticity constraints where false-trigger immunity does not justify price positioning.
- Wireless protocol fragmentation:Competing standards between Zigbee, Z-Wave, and proprietary mesh networks create integration friction for multi-vendor deployments.
Strategic Opportunities
- Mexico manufacturing corridor:Expanding component production capacity is reconfiguring supply availability for North American systems integrators seeking shorter lead times.
- Deep retrofit wireless adoption:Cabling cost avoidance in existing commercial buildings is opening fastest-growth deployment channels where hardwired infrastructure replacement proves prohibitive.
- Subscription service models:Energy management software integration is enabling recurring revenue streams that extend hardware functionality beyond initial equipment sales.
Industry Challenges
- Certification divergence:Patchwork amendments between federal efficiency standards and state-level codes threaten to fragment product certification requirements across California, Texas, and Canadian provincial boundaries.
- Legacy HVAC integration:Building automation protocol incompatibility with 1990s-era pneumatic control systems forces expensive gateway hardware or full system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Occupancy Sensors Market |
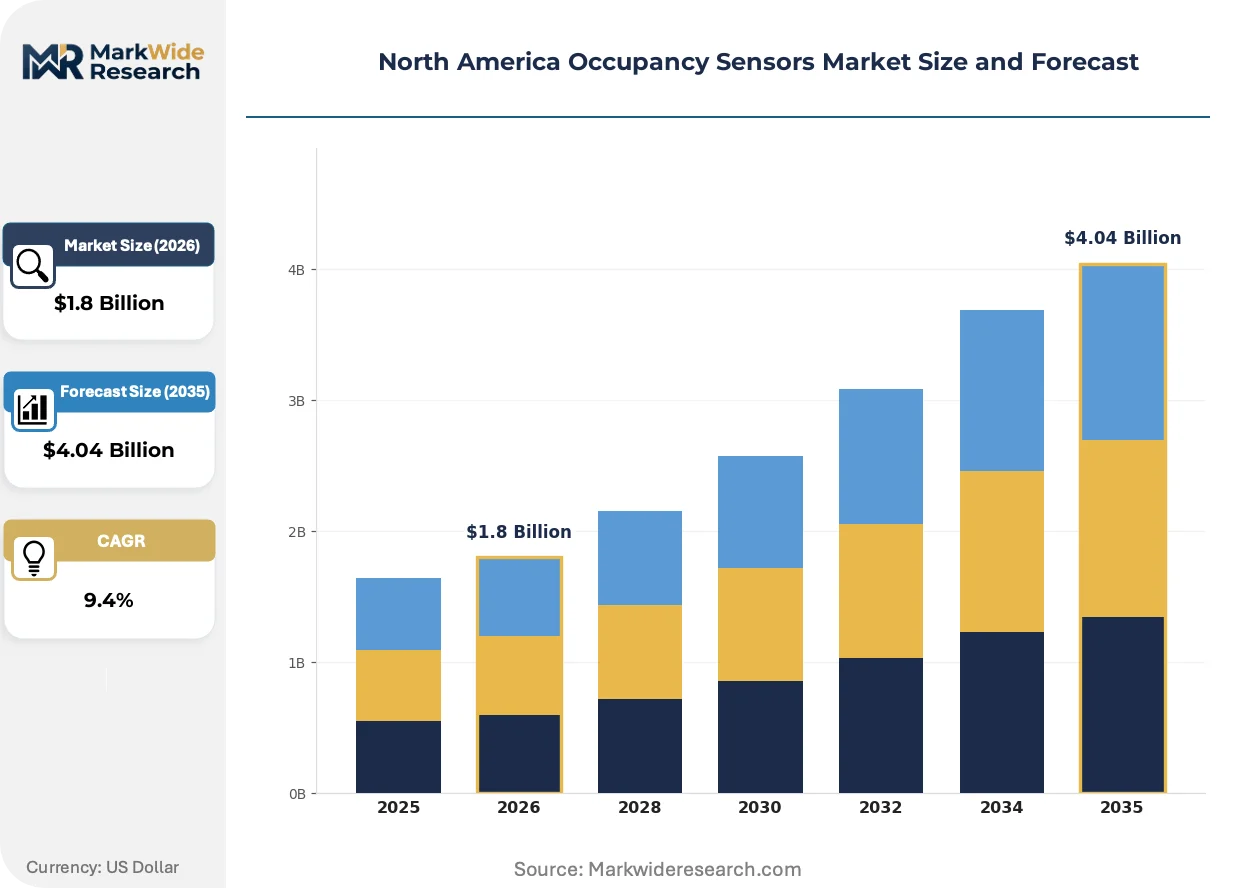
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Sensors, Ultrasonic Sensors, Dual Technology Sensors, Ceiling Sensors Installation Type: Indoor, Outdoor, Wall-mounted, Ceiling-mounted End User: Commercial Buildings, Residential Buildings, Industrial Facilities, Government Institutions Technology: Passive Infrared, Microwave, Hybrid, Wired |
| Companies Covered | Johnson Controls, Honeywell International, Schneider Electric, Eaton, Legrand, Signify Holding, Acuity Brands, Leviton Manufacturing, Lutron Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Occupancy Sensors Market Evolving Landscape
Sensor intelligence is migrating from hardware-defined detection zones to software-configurable spatial analytics, compressing the traditional boundary between physical infrastructure and digital building management platforms.
Machine learning inference at the edge is virtualizing occupancy detection from fixed PIR and ultrasonic hardware into adaptive algorithms that learn spatial usage patterns. Large commercial facility operators in Texas and California are piloting these systems at accelerated procurement cycles. This shift is virtualizing the traditional sensor hardware market into software-defined service layers that capture margin from analytics rather than device shipments.
ASHRAE Standard 90.1 updates are tightening mandatory automatic shutoff thresholds for lighting and HVAC loads in commercial buildings. The industrial consequence is specification lock-in for dual-technology sensors capable of meeting heightened false-trigger immunity requirements. New construction segments in California and New York are responding by front-loading sensor procurement into design-phase budgets rather than treating controls as value-engineering candidates.
Facility managers are unbundling after-sales service contracts from hardware procurement, demanding separate pricing for commissioning, calibration, and firmware update subscriptions. Distribution channels serving mid-size commercial portfolios are being disrupted by direct manufacturer-to-integrator digital platforms that bypass traditional electrical wholesale intermediaries. This pattern is most visible in the United States Sun Belt, where rapid commercial construction expansion outpaces established distributor coverage density.
North America Occupancy Sensors Market Segmentation
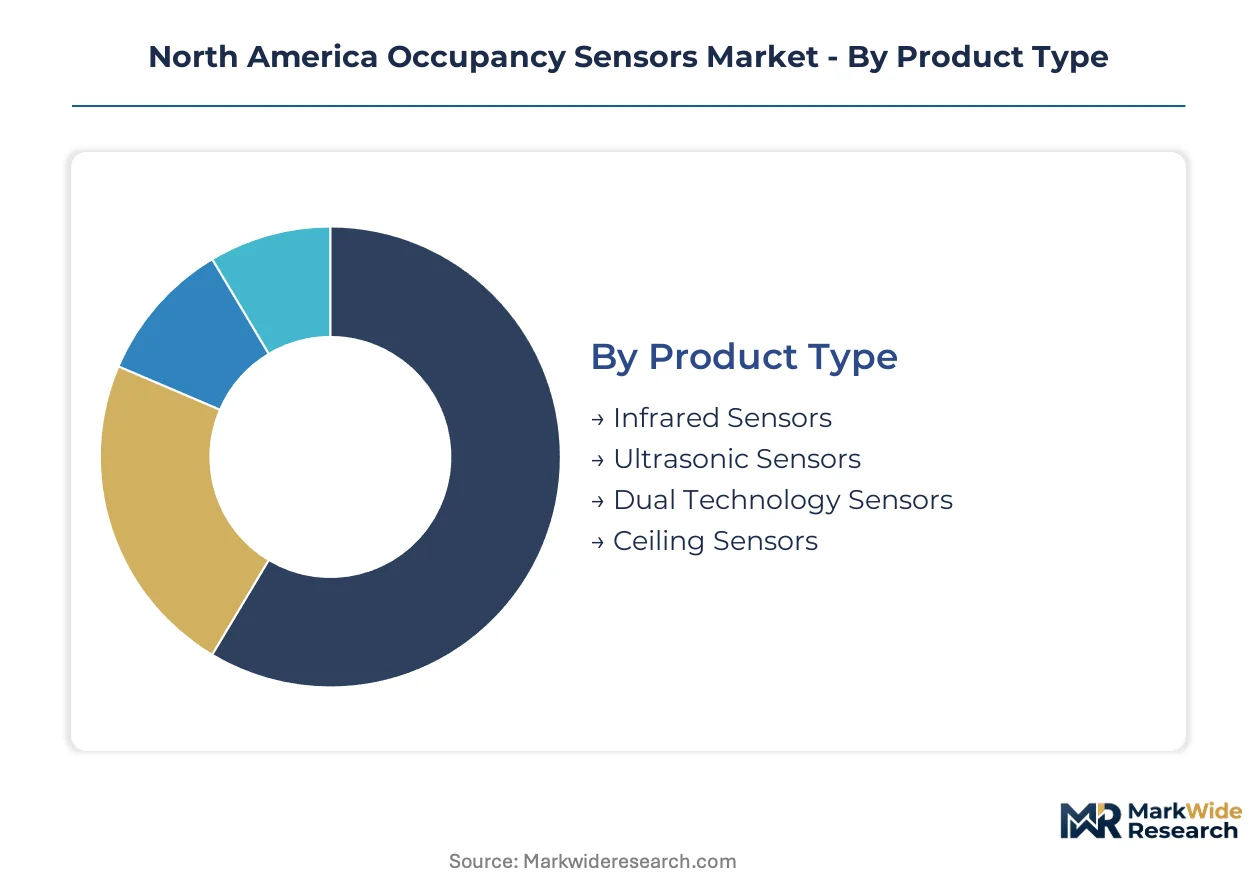
Occupancy sensor segmentation in North America reflects divergent procurement priorities across retrofit and new construction cycles. Product type and installation configuration choices cascade directly into compliance outcomes under California Title 24 and ASHRAE 90.1 mandates.
Product Type:
Mature infrared architectures dominate installed base economics while emerging dual-technology platforms capture specification upgrades in high-performance buildings.
- Infrared Sensors:Passive infrared detection operates through pyroelectric sensing of thermal differentials within 15-30 foot ranges. Texas and Florida commercial corridors are absorbing volume shipments where simpler installation protocols and lower per-unit procurement costs align with budget-constrained retrofit programs.
- Dual Technology Sensors:Hybrid ultrasonic-infrared processing layers acoustic wave emission with thermal detection to eliminate false triggers in complex occupancy patterns. California Class A office construction is specifying these units where ASHRAE 90.1 false-trigger immunity requirements functionally mandate premium positioning despite cost elasticity constraints.
- Ultrasonic Sensors:These units emit high-frequency sound waves to detect motion through Doppler shift measurement, serving niche applications in glass-partitioned spaces where infrared line-of-sight fails.
- Ceiling Sensors:Form-factor-optimized housings integrate detection modules into suspended ceiling grids, streamlining aesthetic compliance in open-plan commercial interiors across Canadian provincial construction.
Infrared Sensors retain volume leadership; Dual Technology Sensors hold the steepest expansion curve.
Installation Type:
Cost tier stratification separates hardwired infrastructure from wireless retrofit alternatives where cabling economics dominate procurement decisions.
- Indoor:Climate-controlled interior mounting accounts for the overwhelming majority of unit deployments, with wall and ceiling configurations sub-segmenting by spatial coverage requirements.
- Outdoor:Weatherized housings with IP-rated enclosures serve parking structures, loading docks, and exterior lighting control across Sun Belt commercial portfolios where humidity and temperature cycling demand hardened electronics.
- Wall-mounted:Surface and flush-mount junction box installations provide localized detection for private offices and conference rooms, leveraging existing electrical infrastructure in 1990s-era building stock.
- Ceiling-mounted:Suspended grid and surface canopy configurations maximize coverage zones per sensor count, reducing hardware density in open-plan environments where labor costs dominate total installation economics.
Indoor configurations command absolute volume share; Outdoor specifications are climbing fastest as building envelope automation extends beyond interior zones.
End User:
Application-driven specification divergence separates code-mandated commercial deployment from discretionary residential adoption.
- Commercial Buildings:Office, retail, and hospitality facilities face mandatory automatic shutoff requirements under California Title 24 and ASHRAE 90.1, compressing procurement timelines and eliminating value-engineering flexibility in design-phase budgets.
- Residential Buildings:Single-family and multifamily installations operate without equivalent regulatory mandates, relying on utility rebate programs and smart home integration to justify incremental hardware costs.
- Industrial Facilities:Manufacturing and warehouse applications prioritize detection reliability in high-bay environments with significant air movement, where false-trigger immunity justifies sensor premiums despite limited energy code pressure.
- Government Institutions:Federal, state, and municipal buildings combine energy efficiency mandates with extended procurement cycles, creating specification inertia that favors established vendor relationships over technology transitions.
Commercial Buildings anchor absolute demand; Industrial Facilities are expanding most quickly as warehouse automation extends occupancy-responsive environmental control.
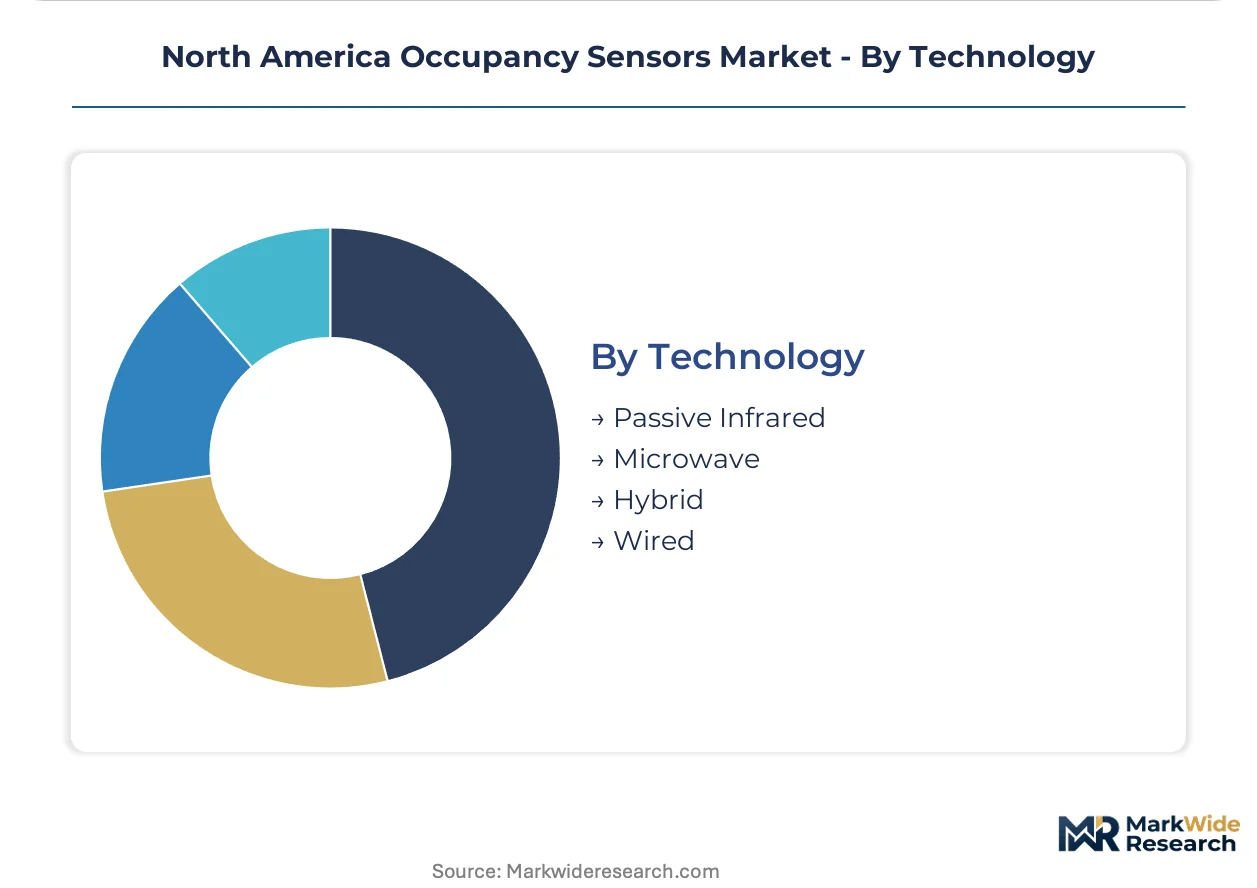
Technology:
Supply concentration in semiconductor inputs shapes cost trajectories across detection methodologies and connectivity architectures.
- Passive Infrared:Pyroelectric crystal arrays detect thermal signatures without active emission, minimizing power consumption and component count for battery-operated wireless deployments.
- Microwave:Doppler radar sensing penetrates physical barriers that block infrared line-of-sight, serving specialized applications in partitioned interiors where coverage continuity overrides false-trigger risk.
- Hybrid:Multi-modal signal processing combines detection methodologies through onboard logic, enabling adaptive sensitivity adjustment that responds to spatial usage learning.
- Wired:Line-voltage and low-voltage hardwired connectivity maintains reliability in permanent infrastructure while constraining retrofit flexibility where conduit access proves prohibitively expensive.
Wired connectivity retains installed base dominance; Hybrid processing architectures are gaining share fastest as edge intelligence virtualizes hardware-defined detection zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters in Mexico's northern states are shortening procurement lead times for systems integrators across the continent. This supply-side reconfiguration channels hardware through distribution networks serving Texas and California construction corridors. Facility managers in both countries now source from regional assembly points rather than trans-Pacific suppliers.
United States
California and Texas concentrate deployment volume through distinct regulatory pathways. The Department of Energy enforces appliance standards that shape sensor performance thresholds nationwide. Dallas-Fort Worth and Houston commercial construction pipelines are absorbing infrared sensor volumes where simpler installation protocols align with accelerated project timelines.
Canada
Ontario and British Columbia procurement is accelerating through provincial utility rebate programs for smart building technologies. Natural Resources Canada administers EnerGuide and ENERGY STAR certification frameworks that parallel US efficiency regulations. Toronto's commercial retrofit sector is specifying ceiling-mounted configurations that streamline aesthetic compliance in open-plan interiors.
Mexico
Nuevo León and Baja California manufacturing corridors are expanding building automation component production for North American integrators. The country's industrial clusters serve cross-border supply chains seeking shorter lead times and tariff-advantaged sourcing. Monterrey-based assembly operations are reconfiguring regional availability for wired and wireless sensor platforms.
North America Occupancy Sensors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in detection hardware and connectivity modules. The vendor base separates into three tiers: diversified building management conglomerates with vertically integrated portfolios, specialized controls manufacturers with deep energy software integration, and regional component fabricators serving price-sensitive retrofit channels. Consolidation pressure is intensifying as facility managers unbundle after-sales service contracts from hardware procurement. Strategic partnerships between sensor manufacturers and energy management software providers are displacing traditional electrical wholesale intermediaries.
Among diversified building technology conglomerates, Johnson Controls and Schneider Electric anchor the platform tier through system-level deployment capabilities. Lutron Electronics occupies a specialist position in premium wireless control architectures. These three represent distinct competitive archetypes: the vertically integrated building manager, the software-integrated energy services provider, and the premium wireless controls specialist.
| Leading Market Players |
|---|
| Johnson Controls |
| Honeywell International |
| Schneider Electric |
| Eaton |
| Legrand |
| Signify Holding |
| Acuity Brands |
| Leviton Manufacturing |
| Lutron Electronics |
| Others |
Value Network & Pricing Analysis
Monterrey's expanding manufacturing corridor for building automation components is compressing procurement lead times while intensifying price competition among North American systems integrators seeking tariff-advantaged sourcing alternatives.
Pricing Analysis
California Title 24 dictates the pricing tier structure across the North American occupancy sensors market, with compliance-grade dual-technology sensors commanding premium positioning against standard infrared alternatives. Three-tier pricing structure across premium, standard, and economy levels separates ASHRAE 90.1-certified hybrids from basic PIR units and commodity imports. Cost compression in the standard tier is intensifying because Mexico-based assembly operations are flooding Texas and Sun Belt markets with lower-cost alternatives. Small commercial retrofit contractors exhibit highest price sensitivity, while Class A office developers in California and New York demonstrate lowest elasticity due to code-mandated specification requirements.
Supply Chain Analysis
Semiconductor wafer and pyroelectric crystal feedstock dependencies draw from Taiwan, South Korea, and Japan for sensor core components, with copper wiring and plastic housing materials sourced domestically or from Mexico. Raw material dependencies center on silicon chips, rare-earth pyroelectric elements, and copper conductors for wired installation segments. Single-source vulnerability concentrates in advanced microcontroller units from Taiwan-based foundries, exposing lead time volatility across North American assembly operations. Distribution runs through electrical wholesale intermediaries in legacy channels, while direct manufacturer-to-integrator digital platforms are displacing traditional intermediaries in high-growth Sun Belt corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation between federal efficiency standards and state-level amendments is creating specialized certification niches that reward targeted technical investment over broad portfolio coverage.
For Market Incumbents: Harden specification lock-in through deeper energy management software integration that extends hardware functionality into subscription-based service models. Invest in California and Texas certification pre-approval programs to compress competitor response windows under accelerated Title 24 procurement timelines. Acquire wireless protocol specialists to neutralize integration friction from Zigbee-Z-Wave fragmentation threatening multi-vendor deployment margins.
For New Entrants and Emerging Players: Pursue deep retrofit wireless adoption channels where cabling cost avoidance opens fastest-growth deployment corridors in 1990s-era commercial building stock. Target mid-size commercial portfolios in the United States Sun Belt where rapid construction expansion outpaces established distributor coverage density. Deploy direct-to-integrator digital platforms that bypass electrical wholesale intermediaries and capture margin from unbundled after-sales service contracts.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because mandatory automatic shutoff requirements functionally mandate sensor deployment regardless of economic cycles. Acquisition candidates with hybrid detection technology and edge-AI capabilities offer the strongest defensive positioning as machine learning virtualizes hardware-defined detection zones. Monitor divergence between emerging federal efficiency standards and patchwork state amendments as the signal for certification arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Energy Management Software Integration | Extends hardware margins into recurring subscription revenue streams beyond initial equipment sales. |
| Mexico Manufacturing Footprint Expansion | Shortens lead times for North American integrators while reducing tariff exposure on finished goods. |
| Wireless Protocol Standardization | Eliminates integration friction for multi-vendor deployments under competing Zigbee and Z-Wave architectures. |
| Dual-Technology Sensor Development | Captures specification upgrades in California Class A office construction under tightened ASHRAE 90.1 thresholds. |
| Direct Digital Platform Launch | Disrupts electrical wholesale intermediaries serving mid-size commercial portfolios in underserved Sun Belt markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with building automation systems integrators, facility management executives, electrical contractors, and energy code compliance officers; and secondary validation against Department of Energy appliance standards filings, California Energy Commission Title 24 documentation, Natural Resources Canada EnerGuide certifications, and ASHRAE Standard 90.1 technical amendments. Bottom-up shipment estimates triangulated against top-down construction spending allocations across commercial, industrial, and residential end-use segments.
Forecast inputs considered product type segmentation across infrared, ultrasonic, and dual-technology platforms; installation configuration splits between wired and wireless architectures; and end-user categorization by commercial, residential, industrial, and government building types across the projection horizon. CAGRs derived from regression analysis of historical code adoption curves, utility rebate program expansion timelines, and construction pipeline data. Modeled variables included semiconductor input cost trajectories, wireless protocol adoption rates, and deep retrofit penetration assumptions in existing building stock.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified building management conglomerates would shift outcomes through accelerated subscription service model deployment. Cross-checking against regional construction permit databases and utility incentive program disbursement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
MEMS Market
Sensors and Controls
Piezoelectric Actuators Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
MEMS Accelerometer and Gyroscope Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Glucose Sensor Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
Magnetometer Sensor Market
Sensors and Controls
Signal Calibrators Market
Sensors and Controls
Global E-Compass Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
Vibration Sensor Market
Sensors and Controls
Millimeter Wave Sensors Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
HVAC Sensor Market