
 Explosion Proof Lighting Market | 2026-2036
Explosion Proof Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Explosion Proof Lighting Market Analysis
A capital-intensity divergence between integrated electrical conglomerates and specialized hazardous-area lighting firms is reorganizing competitive tiers in the explosion proof lighting sector. Eaton leverages captive manufacturing of enclosure systems to control input costs across its Crouse-Hinds portfolio. Dialight specializes in high-bay LED arrays for Zone 1 environments, anchoring its position in offshore oil and gas procurement channels. R. STAHL competes through German-engineered IECEx certification breadth, sustaining premium positioning in European chemical complexes.
Explosion proof lighting comprises sealed luminaire assemblies engineered to contain internal ignition sources and prevent surface temperatures from exceeding auto-ignition thresholds of surrounding atmospheres, typically constructed with cast aluminum or stainless steel housings, tempered glass lenses, and flame-path joints measured in thousandths of an inch. These fixtures serve critical safety functions in facilities where flammable gases, vapors, or combustible dusts operate within explosive concentration ranges. LED product types command the dominant share of new specification activity due to lumen-per-watt efficiency gains and extended maintenance intervals that reduce man-hours in restricted-access hazardous zones. Oil and gas applications generate the deepest margin pools among end-use categories, though pharmaceutical cleanroom installations are gaining specification momentum as facilities pursue ATEX-compliant LED retrofits that satisfy both safety and contamination-control protocols.
OSHA 1910.307 hazardous location standards, ATEX Directive 2014/34/EU, and IECEx 02 equipment certification schemes collectively shape product design, testing obligations, and market access prerequisites for manufacturers serving regulated industrial environments. Compliance with multiple certification regimes simultaneously expands addressable market scope but lengthens product development cycles and raises barrier thresholds for new entrants. Stakeholders must monitor evolving harmonization between ATEX and IECEx conformity assessment procedures to optimize certification investments and anticipate which regulatory pathway will dominate procurement specifications in emerging petrochemical corridors.
Market Dynamics
LED retrofit mandates across hazardous-area facilities are compressing replacement cycles from decade-long incandescent intervals to five-year LED refresh programs, restructuring capital deployment patterns for plant operators.
Growth Catalysts
- OSHA Process Safety Management audits:Gulf Coast refineries face compliance deadlines that accelerate fixture replacement timelines. Facilities procure IECEx-certified arrays to preempt enforcement actions.
- Zone 1 LED lumen efficiency:Offshore platforms specify high-bay arrays that cut energy draw by half against legacy metal halide systems. Maintenance intervals extend from months to years.
- Texas petrochemical corridor expansion:Bulk procurement of ceiling-mounted hazardous-area luminaires concentrates demand in Houston and Corpus Christi industrial clusters.
Market Restraints
- Cast aluminum enclosure volatility:Primary metal price swings compress margin buffers for housing fabricators. Smaller manufacturers lack hedging instruments.
- Flame-path machining concentration:Precision joint fabrication concentrates among German and Japanese machine shops. Supply bottlenecks extend lead times for ATEX-certified fixtures.
- Incandescent residual stock:Some Zone 2 facilities delay LED migration where explosion-proof incandescent inventories remain serviceable. Replacement inertia slows specification velocity.
Strategic Opportunities
- Pharmaceutical cleanroom convergence:ATEX-compliant LED retrofits that satisfy both safety and contamination-control protocols open specification channels in sterile manufacturing environments.
- North Sea platform electrification:Offshore wind integration projects require explosion-proof lighting for substation and battery enclosures. IECEx 02 certification becomes entry requirement.
- Wireless monitoring integration:Luminaires with embedded thermal and vibration sensors enable predictive maintenance contracts. Service revenue models displace pure hardware sales.
Industry Challenges
- IECEx-ATEX harmonization friction:Divergent conformity assessment procedures force manufacturers to maintain parallel certification tracks. Development cycles lengthen and testing costs compound.
- Legacy conduit infrastructure:Existing rigid metal conduit systems constrain LED fixture form factors. Retrofit projects require custom mounting adapters that inflate installation labor.
- Hazardous-area electrician scarcity:Certified installation technicians command premium wages. Project timelines stretch where qualified contractors are unavailable.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosion Proof Lighting Market |
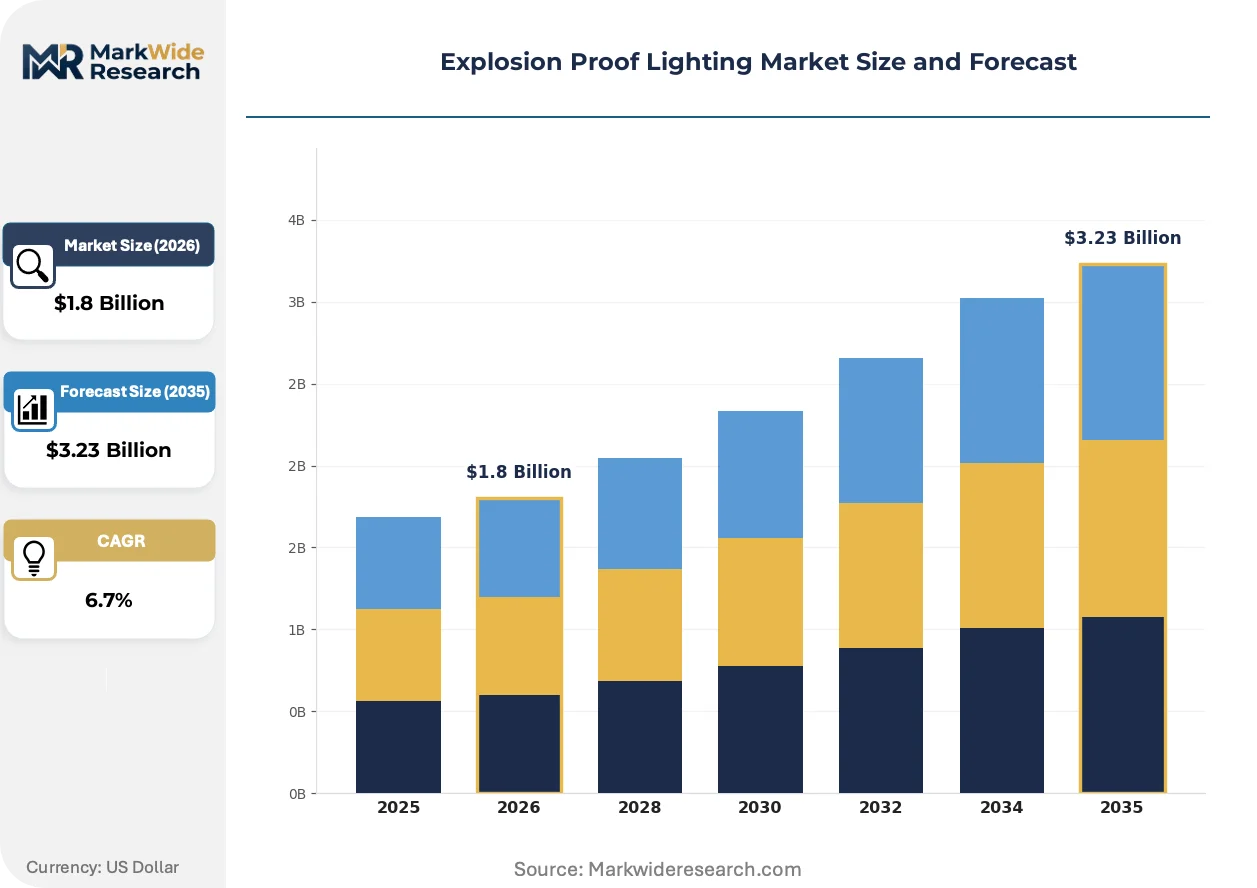
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, HID, Incandescent Application: Oil & Gas, Mining, Chemicals, Pharmaceuticals Installation: Wall Mount, Ceiling Mount, Portable, Handheld End User: Industrial, Manufacturing, Construction, Aerospace |
| Companies Covered | Eaton, Hubbell Incorporated, ABB, Emerson Electric Co., Signify, Philips Lighting, Phoenix Lighting, R. STAHL, Dialight, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosion Proof Lighting Market Emerging Trajectories
Solid-state lighting architectures are rewriting fixture economics while certification regimes and procurement patterns undergo parallel transformation. Three developments merit particular attention.
Chip-on-board LED arrays are supplanting discrete diode packages in high-lumen hazardous-area fixtures. Offshore platform operators specify these configurations for their thermal uniformity and reduced failure-point density. The technology is supplanting legacy metal halide and high-pressure sodium systems in North Sea and Gulf of Mexico installations, compressing payback periods to under three years in high-utilization environments.
ATEX Directive 2014/34/EU conformity assessment procedures are tightening documentation requirements for flame-path dimensional tolerances. German Notified Bodies now demand sub-thousandth-inch measurement traceability for cast aluminum housings. European chemical complexes respond by consolidating supplier panels to manufacturers with captive metrology laboratories, excluding smaller fabricators from premium procurement channels.
Integrated service contracts now bundle fixture supply with predictive maintenance and certification renewal. Oil and gas majors in Texas and Louisiana disaggregate capital and operating budgets through multi-year lighting-as-a-service agreements. Channel intermediaries with field engineering capabilities capture margin pools that previously accrued to distributors, restructuring the value chain toward solution providers.
Explosion Proof Lighting Market Segmentation
Explosion proof lighting procurement splits across technical specifications, hazardous area classifications, and installation constraints that determine both certification requirements and fixture economics. Understanding how these dimensions intersect reveals where margin pools concentrate and where specification velocity accelerates.
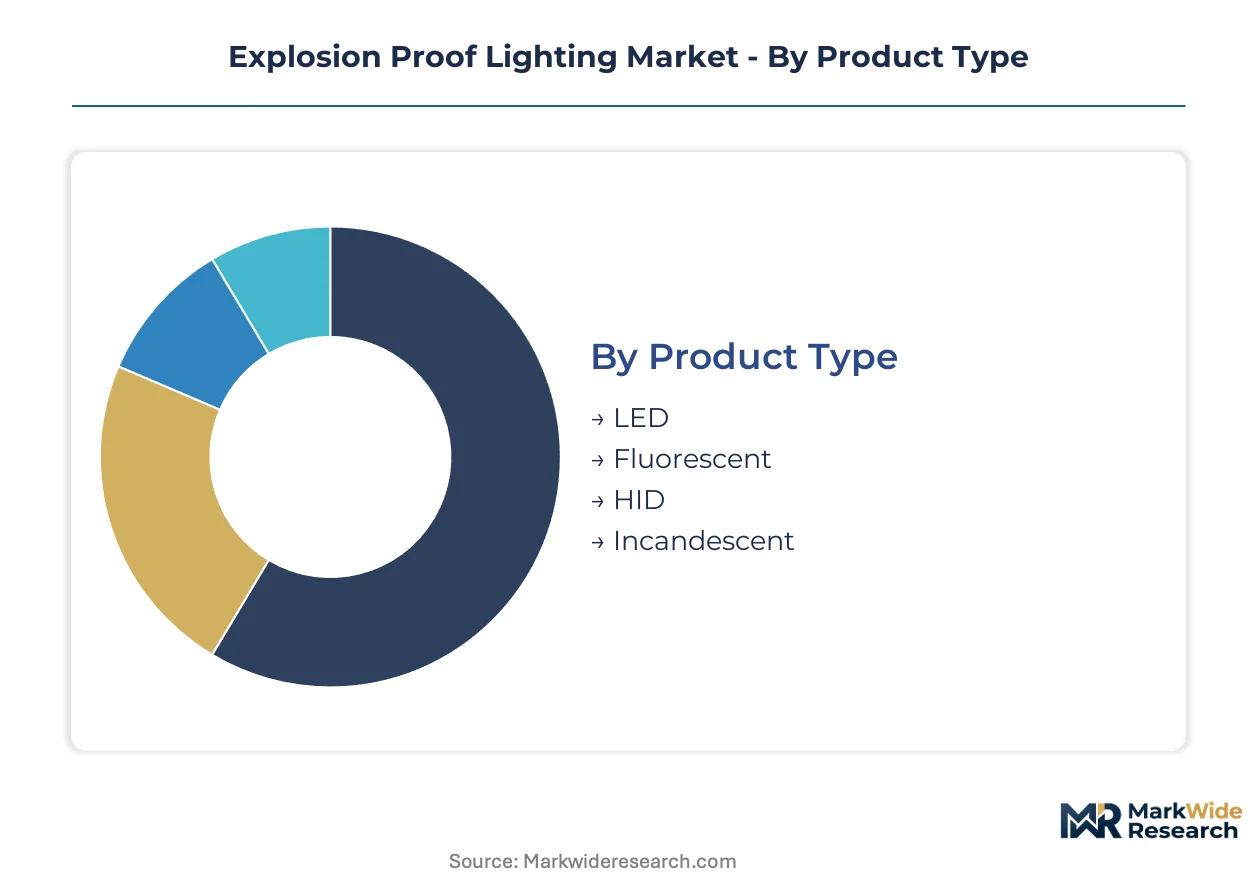
Product Type:
OSHA 1910.307 and ATEX Directive 2014/34/EU impose divergent testing protocols on solid-state versus legacy lamp technologies, reshaping manufacturer certification investments and plant operator replacement timelines.
- LED:Chip-on-board arrays deliver thermal uniformity and 50% energy reduction against metal halide systems in Zone 1 environments. Gulf Coast refineries specify these for OSHA audit compliance ahead of process safety management deadlines.
- Fluorescent:T5 and T8 tube configurations persist in pharmaceutical cleanrooms where ATEX-compliant retrofits must satisfy contamination-control protocols. European chemical complexes consolidate supplier panels around manufacturers with captive metrology laboratories.
- HID:Metal halide and high-pressure sodium systems retain installed base in legacy offshore platforms where conduit infrastructure constrains LED form factors.
- Incandescent:Residual stock delays replacement in some Zone 2 facilities where serviceable inventories slow specification velocity.
Established volume favors LED; emerging adoption favors fluorescent in sterile manufacturing environments.
Application:
Margin pools vary sharply across end-use categories based on hazardous area classification stringency, access difficulty, and maintenance interval economics.
- Oil & Gas:Offshore platforms and refineries generate the deepest margins. North Sea operators specify IECEx-certified high-bay arrays that compress payback periods through extended maintenance intervals.
- Chemicals:German-engineered enclosure systems command premium positioning in European complexes where flame-path machining tolerances tighten.
- Mining:Underground operations demand portable and handheld configurations for confined-space mobility.
- Pharmaceuticals:Cleanroom installations are gaining specification momentum as facilities pursue dual-compliant LED retrofits.
Procurement concentration centers on oil and gas; steepest expansion trajectory appears in pharmaceutical sterile manufacturing.
Installation:
Mounting configuration determines conduit compatibility, labor intensity, and the feasibility of predictive maintenance sensor integration.
- Ceiling Mount:High-bay arrays dominate Texas petrochemical corridor expansions in Houston and Corpus Christi industrial clusters.
- Wall Mount:Perimeter and task lighting configurations serve processing areas with restricted overhead access.
- Portable:Mobile units address maintenance turnaround and emergency response in refineries where fixed infrastructure cannot reach.
- Handheld:Inspection and confined-space entry applications require battery-powered explosion-proof illumination.
Capital deployment favors ceiling mount for new construction; service revenue models favor portable through lighting-as-a-service agreements.
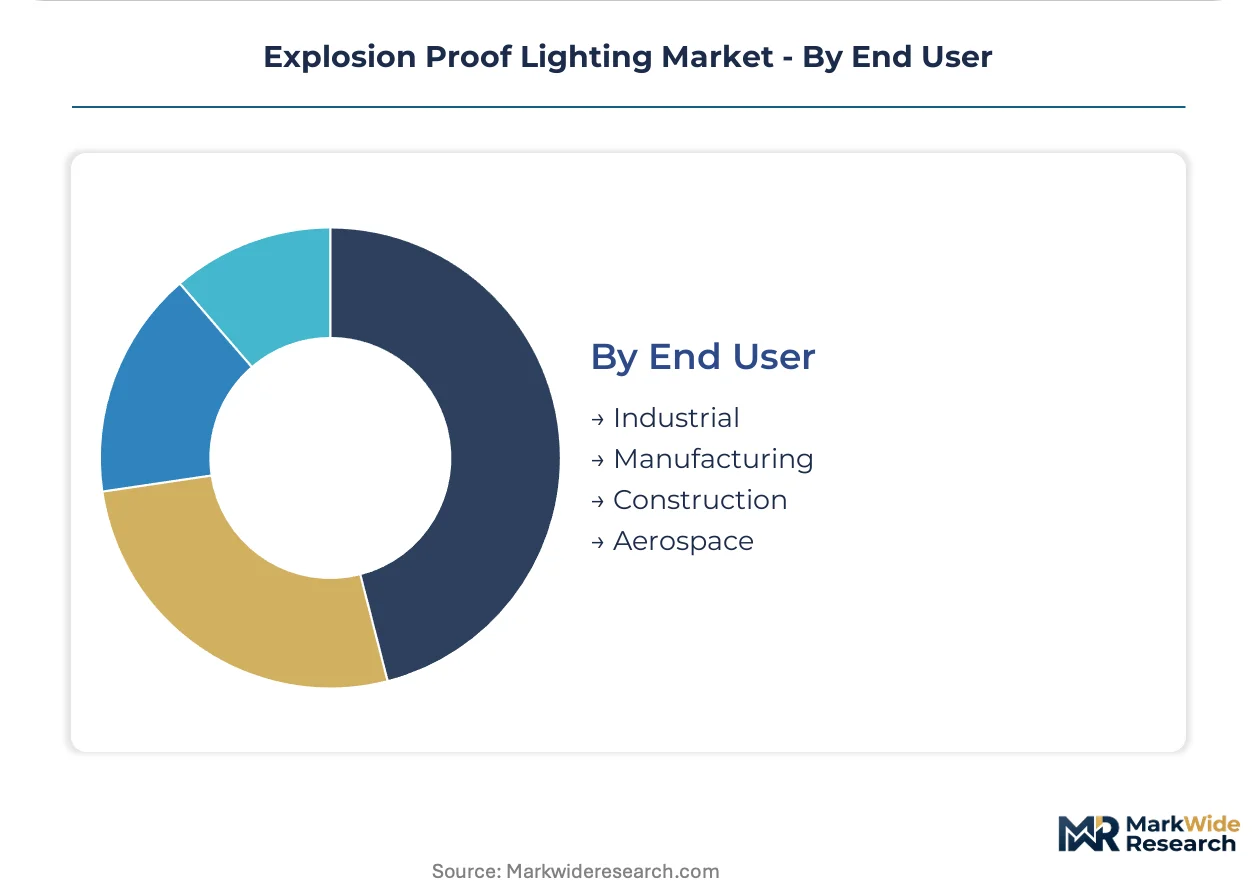
End User:
Facility type shapes procurement authority, budget structure, and the viability of integrated maintenance contracts.
- Industrial:Petrochemical and heavy processing facilities drive bulk procurement with multi-year specification horizons.
- Manufacturing:Pharmaceutical and specialty chemical plants prioritize ATEX-compliant contamination-control integration.
- Construction:Temporary hazardous-area lighting demands rental and lease structures rather than capital purchase.
- Aerospace:Fuel handling and paint booth applications require specialized certification breadth for volatile compound environments.
Contract sophistication favors industrial; specification velocity favors manufacturing as sterile production capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German-engineered IECEx-certified systems while Texas petrochemical clusters drive volume procurement at compressed margins. This asymmetry reshapes manufacturer investment priorities across regulatory jurisdictions.
United States
Gulf Coast refineries accelerate LED fixture replacement ahead of OSHA process safety management audits. The Department of Labor enforces 1910.307 hazardous location standards with escalating penalties. Houston and Corpus Christi industrial clusters absorb bulk shipments of ceiling-mounted Zone 1 arrays for petrochemical capacity expansions.
Germany
European chemical complexes demand sub-thousandth-inch flame-path measurement traceability for cast aluminum housings. ATEX Directive 2014/34/EU conformity assessment procedures tighten documentation requirements through Notified Bodies. The Ruhr industrial basin and Ludwigshafen chemical corridor consolidate supplier panels around manufacturers with captive metrology laboratories.
United Kingdom
North Sea offshore platforms compress delivery timelines for IECEx-certified luminaires ahead of platform electrification projects. The Health and Safety Executive aligns enforcement with EU ATEX frameworks during post-Brexit transition. Aberdeen energy service companies specify high-bay LED arrays that extend maintenance intervals from months to years.
China
Domestic petrochemical construction drives specification of explosion-proof lighting for coal chemical and refinery greenfield projects. GB standards for hazardous area electrical equipment converge with IECEx technical specifications. The Ningbo-Zhoushan petrochemical base and Dalian refining complex concentrate procurement among state-owned energy majors.
Saudi Arabia
Downstream petrochemical expansions at Jubail and Yanbu industrial cities generate demand for Zone 1 and Zone 2 certified fixtures. The Saudi Standards, Metrology and Quality Organization implements IECEx recognition for imported hazardous-area equipment. The SABIC-affiliated manufacturing clusters specify LED retrofits to reduce cooling loads in desert installations.
Explosion Proof Lighting Market Vendor Landscape
Concentration sits with integrated electrical conglomerates that leverage captive manufacturing of enclosure systems to control input costs. Specialized hazardous-area lighting firms anchor premium positioning through certification breadth and offshore procurement channel access. The competitive structure organizes around three archetypes: diversified industrial multinationals with captive supply chains, pure-play hazardous-area specialists with deep certification portfolios, and Asian-scale manufacturers competing on fixture economics. Dominant moves include backward integration into aluminum casting and precision machining capacity, plus multi-year lighting-as-a-service contract structures that displace pure hardware sales.
Within the integrated conglomerate tier, Eaton Corporation plc and ABB Ltd occupy positions that exemplify captive control over enclosure fabrication and global distribution infrastructure. Among hazardous-area specialists, R. STAHL AG and Dialight plc represent archetypes of certification-driven premium positioning in European chemical and offshore oil and gas procurement channels. Emerson Electric Co. sits within the diversified industrial technology segment, leveraging process automation relationships to bundle lighting specifications with broader facility electrification projects.
| Leading Market Players |
|---|
| Eaton |
| Hubbell Incorporated |
| ABB |
| Emerson Electric Co. |
| Signify |
| Philips Lighting |
| Phoenix Lighting |
| R. STAHL |
| Dialight |
| Others |
Supply Flow & Price Mechanics
Lighting-as-a-service contracts spanning five-to-seven-year terms lock in supply allocation for IECEx-certified fixture manufacturers while compressing price volatility for Gulf Coast petrochemical operators facing OSHA audit deadlines. These bundled service structures tether capital deployment to predictable maintenance schedules, insulating procurement teams from spot-market aluminum enclosure swings.
Pricing Analysis
Configured-to-order pricing for Zone 1 high-bay arrays with embedded thermal sensors commands a 35-50% premium over standard ceiling-mounted LED configurations for Zone 2 environments. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification breadth—IECEx-ATEX dual-certified fixtures anchor the top tier, single-certification economy units serve price-sensitive construction rental channels. Cost compression in the standard tier is intensifying because German Notified Bodies tightened flame-path documentation requirements, forcing smaller fabricators to outsource metrology and surrender margin. Pharmaceutical cleanroom operators prove least price-sensitive due to contamination-control compliance bundling, while construction rental fleets exhibit acute sensitivity to per-unit acquisition cost.
Supply Chain Analysis
Container availability constraints on the Hamburg-Houston trade lane inflate inbound logistics costs for precision-machined flame-path components sourced from German machine shops. Cast aluminum housing fabrication concentrates in China, Germany, and the United States; tempered glass lens production draws from specialty manufacturers in Japan and Germany. Supply chain risk centers on single-source vulnerability for sub-thousandth-inch precision machining capacity, where ATEX certification dependency limits supplier substitution. Distribution runs through electrical wholesale distributors with hazardous-area specification expertise, though integrated service contracts increasingly displace pure hardware sales through direct manufacturer-field engineering relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
General-purpose industrial LED lighting represents a persistent substitution threat as non-certified high-bay arrays encroach on Zone 2 applications where explosion-risk assessments permit relaxed specifications. Incumbents must harden differentiation through certification breadth and service integration to defend specification authority.
For Market Incumbents: Consolidate supplier panel relationships with German Notified Bodies to secure priority flame-path certification slots ahead of competing submissions. Captive metrology laboratory investment separates premium-tier manufacturers from price-pressured competitors as ATEX documentation requirements tighten. Backward integration into aluminum casting capacity insulates margin buffers from primary metal volatility that compresses smaller fabricators. For New Entrants and Emerging Players: Predictive maintenance service gaps in the North Sea offshore electrification wave offer white-space entry where incumbent hardware vendors under-serve platform operators seeking integrated sensor-luminaire contracts. Pharmaceutical cleanroom retrofits present the most penetrable application segment given dual-compliance complexity that favors agile specification support. A go-to-market angle bundling ATEX-compliant LED retrofits with contamination-control validation protocols bypasses capital-intensive certification backlogs. For Investors and Strategic Acquirers: Hazardous-area lighting specialists with captive IECEx certification portfolios and established offshore procurement channel access represent the priority acquisition archetype for portfolio diversification into industrial safety equipment. Long-term viability hinges on substitution defense against general-purpose LED encroachment and service-revenue model conversion. The signal to watch is lighting-as-a-service contract penetration rates in Texas petrochemical corridors, where multi-year agreements displace transactional hardware sales and restructure margin pools toward solution providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Casting | Captive enclosure production insulates margin buffers from primary metal price swings in German and Chinese supply markets. |
| IECEx-ATEX Dual Certification Investment | Parallel conformity assessment tracks expand addressable market scope across North Sea offshore and European chemical procurement channels. |
| Predictive Maintenance Sensor Integration | Embedded thermal and vibration monitoring enables lighting-as-a-service contracts that displace pure hardware revenue models. |
| Pharmaceutical Cleanroom Specification Focus | Dual-compliant LED retrofits open sterile manufacturing channels where contamination-control protocols tighten supplier consolidation. |
| Lighting-as-a-Service Contract Structuring | Multi-year bundled agreements with Gulf Coast refineries lock in replacement cycles ahead of OSHA process safety management audits. |
Methodological Framework
Cross-validation between regulatory filing analysis and procurement database review anchors the qualitative findings in documented certification timelines and contract award patterns. Primary interviews with plant engineers, hazardous-area electrical contractors, EPC procurement leads, and Notified Body certification managers combined with secondary validation through IECEx certificate database queries, OSHA enforcement records, and SEC 10-K supply chain disclosures. Bottom-up fixture shipment estimates triangulate against top-down petrochemical capital expenditure tracking across the analysis window.
Sensitivity analysis around aluminum price volatility, certification backlog durations, and LED retrofit penetration rates stress-tests projection robustness. The analytical framework segments by hazardous area classification, product technology, installation configuration, and end-use facility type across the modeling period. CAGRs derive from replacement cycle compression analysis and capacity expansion tracking in named petrochemical corridors. Forecast inputs incorporate OSHA audit schedule density and IECEx-ATEX harmonization progress as demand-timing variables.
Forecasts assume regulatory continuity in OSHA 1910.307, ATEX Directive 2014/34/EU, and IECEx 02 regimes; material policy shifts would require re-modeling demand timing and certification investment returns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Photocell Market
Lighting
Intelligent Lighting Market
Lighting
Smart Street Lighting Systems Market
Lighting
Dimmers Market
Lighting
Industrial Lighting Market
Lighting
Global Flame Proof Lighting Market
Lighting
Smart Lighting Market
Lighting
Global Machine Vision Lighting Market
Lighting
Fluorescent Lighting Market
Lighting
Lighting Fixture Market
Lighting
Inspection Lighting Fixture Market
Lighting
High Bay Lighting Market
Lighting
Smart Lights Market
Lighting
Indicator Lights Market
Lighting
Xenon Flashlamps Market