
 Lighting Product Market | 2026-2036
Lighting Product Market Size, Share, and Industry Trends Forecast 2026-2036
Lighting Product Market Intelligence
High-efficacy LED specification tiers is rotating demand away from basic replacement bulbs toward connected, sensor-integrated systems. Signify Holding leverages its Interact platform to dominate connected professional installations across Europe and North America. Acuity Brands, Inc. sustains technology leadership in tunable white and human-centric lighting for healthcare and education verticals. ams-OSRAM AG anchors the premium tier through advanced LED chip architectures and automotive-grade reliability standards.
Lighting products encompass electrically powered devices engineered to produce controlled illumination through solid-state, gas-discharge, or thermal radiation mechanisms, with luminous efficacy, color rendering index, and correlated color temperature serving as critical performance parameters for commercial and industrial deployment. LED product types now command the dominant revenue position due to operational longevity and declining lumens-per-watt cost curves, while OLED segments occupy niche architectural applications where surface-emitting aesthetics justify premium positioning. Application demand in street lighting and warehouse environments is expanding fastest as municipalities and logistics operators prioritize energy recovery timelines, whereas museum and sports arena installations represent mature, specification-intensive margin pools where optical precision commands sustained pricing power.
The U.S. Department of Energy enforces efficacy benchmarks through ENERGY STAR and DLC qualification requirements that gate utility rebate access and federal procurement eligibility. The EU Ecodesign Directive and RoHS restrictions eliminate mercury-containing fluorescent sources while mandating minimum performance thresholds for products sold in member states. China's GB standards and MIIT circular economy directives accelerate domestic LED conversion timelines. Stakeholders must monitor regulatory phase-out calendars against inventory positions and certify supply chain compliance across multiple jurisdiction-specific labeling regimes to avoid market exclusion.
Market Dynamics
LED retrofit mandates across commercial building codes are compressing replacement cycles and concentrating procurement power among facility management consortia, while legacy fluorescent inventory devaluation accelerates distributor consolidation.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficacy thresholds for light sources sold in member states are eliminating mercury-containing fluorescent tubes and forcing commercial estate managers toward solid-state retrofits.
- Warehouse automation:Logistics operators in Germany and India are specifying high-bay LED arrays with integrated daylight harvesting to compress energy recovery timelines below three years.
- Smart city infrastructure:Municipal procurement in China is bundling street lighting with sensor networks for traffic and air quality monitoring, expanding fixture specification beyond illumination-only functionality.
Market Restraints
- LED chip supply concentration:Epitaxial wafer production clusters in East Asia create vulnerability to export control disruptions and freight cost volatility for European and North American luminaire assemblers.
- Copper and aluminum input costs:Heat sink and driver housing materials expose fixture manufacturers to commodity price swings that compress gross margins on fixed-price municipal contracts.
- Compatibility limitations:Legacy dimming infrastructure using phase-cut protocols fails to interface with modern LED drivers, forcing complete system replacement rather than lamp-level retrofit.
Strategic Opportunities
- Human-centric lighting:Healthcare and education verticals in North America are specifying tunable white systems that modulate correlated color temperature across circadian cycles, opening premium specification tiers.
- Li-Fi convergence:Integration of visible light communication transceivers into commercial fixtures offers data transmission infrastructure without RF spectrum licensing, attractive to secure facility operators.
- Rural electrification programs:Off-grid solar-LED packages for unelectrified settlements in India and sub-Saharan Africa represent volume expansion outside grid-connected replacement demand saturation.
Industry Challenges
- Optical engineering talent scarcity:Compound lens design and glare control modeling expertise concentrates among aging specialists in Germany and Japan, constraining product development velocity for mid-tier manufacturers.
- Multi-jurisdiction certification timelines:Securing ENERGY STAR, DLC, and CE marking in parallel extends product launch schedules by eight to fourteen months, delaying revenue recognition against competitor first-mover advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lighting Product Market |
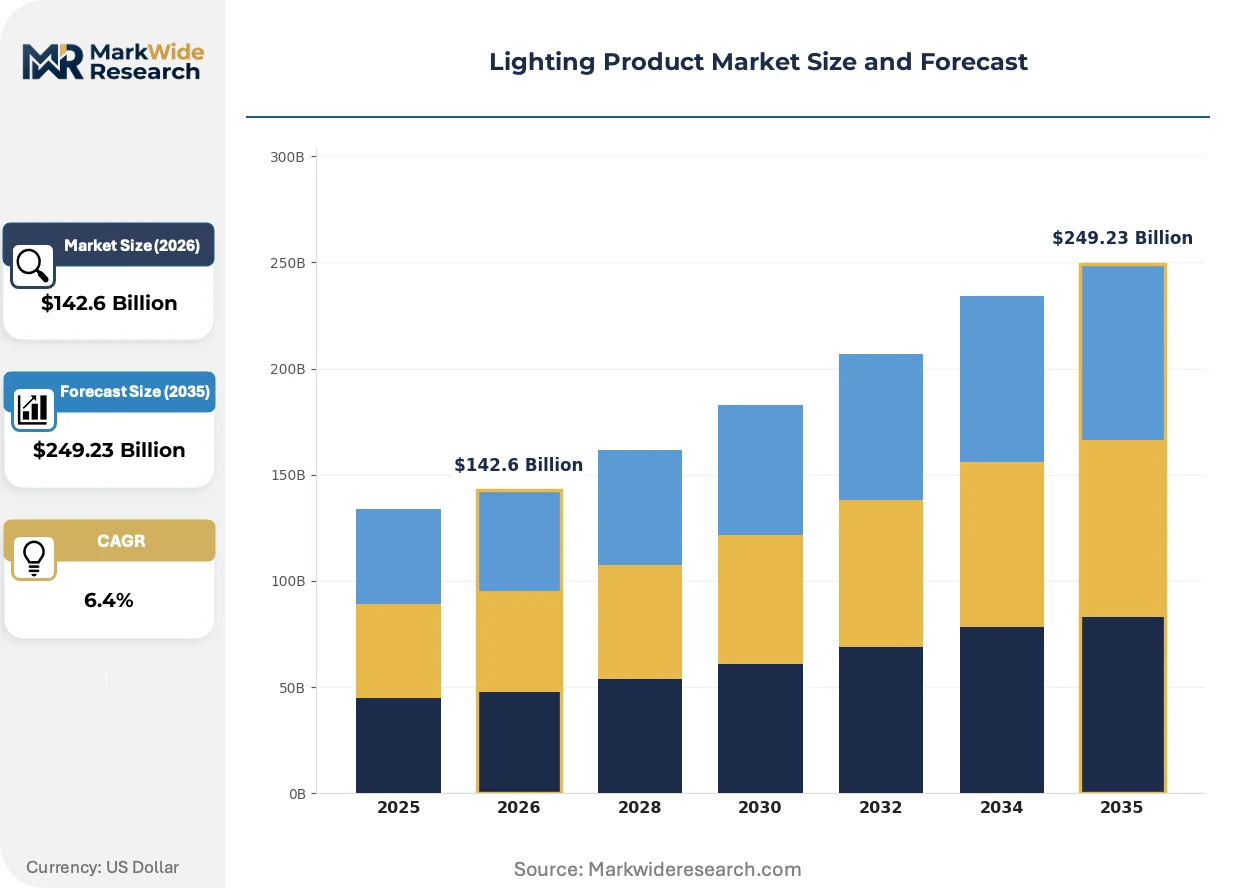
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $249.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Halogen, Incandescent, HID, OLED Application: Street Lighting, Office Buildings, Retail Outlets, Sports Arenas, Museums, Warehouses Installation: Surface Mounted, Recessed, Pendant, Track, Pole Mounted, Cove Lighting End User: Commercial Complexes, Educational Institutions, Hospitality Venues, Transportation Hubs, Government Facilities, Residential Buildings |
| Companies Covered | Signify Holding, Acuity Brands, Inc., ams-OSRAM AG, Panasonic Holdings Corporation, Cree Lighting USA LLC, Zumtobel Group, GE Lighting, Hubbell Incorporated, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lighting Product Market Strategic Shifts & Innovations
Connected lighting platforms are absorbing sensor and control functionality that previously resided in separate building automation systems, collapsing the traditional boundary between illumination and infrastructure management.
Li-Fi technology is bifurcating the commercial fixture market between pure illumination products and dual-use data transmission nodes. Secure facility operators in defense and healthcare verticals are specifying integrated transceiver arrays to eliminate RF interference vulnerabilities. This convergence is compressing demand for standalone wireless access point infrastructure while expanding fixture specification complexity.
China's GB standards for solid-state lighting efficacy are tightening minimum lumens-per-watt thresholds faster than IEC baseline schedules, forcing export-oriented manufacturers to maintain dual product lines. Domestic producers gain compliance cost advantages while foreign competitors face technical barrier adjustments. The divergence most impacts basic replacement bulb categories where margin compression already limits R&D absorption capacity.
Facility management consortia are consolidating procurement authority previously dispersed across individual building operators. Large German and US real estate investment trusts now negotiate enterprise lighting service agreements spanning multi-year maintenance and energy performance guarantees. This concentration shifts vendor selection criteria toward balance sheet strength and service network density rather than unit product specifications alone.
Lighting Product Market Segmentation
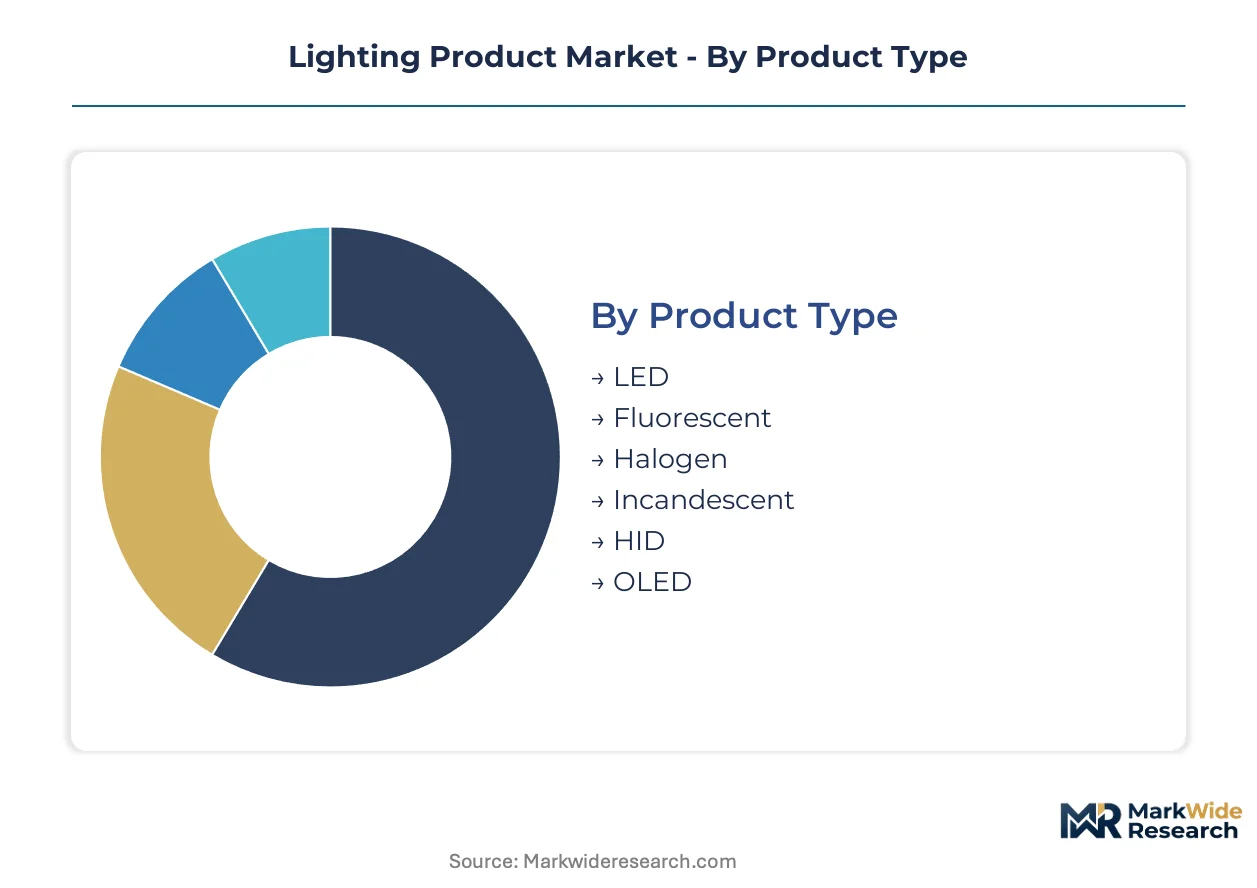
Segmentation in lighting products tracks the divergence between legacy replacement demand and specification-driven procurement for connected infrastructure. Procurement patterns split sharply between commodity retrofit volumes and premium-tier systems requiring optical engineering and software integration.
Product Type:
LED sources dominate domestic installation across China, India, and Germany while OLED and premium architectural segments remain export-led to North American and Gulf state projects.
- LED:Solid-state sources with efficacy exceeding 150 lumens per watt and operational lifespans surpassing 50,000 hours. Demand concentrates in warehouse and street lighting applications across Germany and India where energy recovery timelines drive specification. Municipal procurement in China bundles LED fixtures with sensor networks for traffic monitoring.
- OLED:Surface-emitting organic panels delivering uniform luminance without point-source glare. Architectural practices in Dubai and Singapore specify OLED for hospitality and museum installations where aesthetic differentiation commands premium positioning.
- Fluorescent:Mercury-containing linear tubes facing phased elimination under EU Ecodesign Directive and China's GB standards. Remaining demand clusters in legacy industrial facilities with incompatible dimming infrastructure.
- Halogen:Tungsten-halogen sources with high color rendering index but poor efficacy. Niche retention in residential accent lighting and theatrical applications where instant dimming response outweighs energy cost.
- HID:High-intensity discharge lamps including metal halide and high-pressure sodium. Stadium and large-area floodlighting in India and Brazil maintain specification for lumen packages exceeding LED thermal management limits.
- Incandescent:Thermal radiation sources with near-perfect color rendering but sub-20 lumen per watt efficacy. Decorative and heritage lighting segments in Europe resist complete phase-out for aesthetic authenticity requirements.
LED holds the largest share; momentum sits with OLED in premium architectural specification.
Application:
Cost tier stratification separates commodity street and warehouse retrofit from specification-intensive museum and sports arena installations where optical precision sustains margin.
- Street Lighting:Pole-mounted roadway illumination with photocell and wireless control compatibility. Smart city investments in China and India bundle fixtures with air quality sensors and traffic monitoring, expanding specification beyond illumination-only functionality.
- Warehouses:High-bay LED arrays with integrated daylight harvesting and occupancy sensing. Logistics operators in Germany specify systems compressing energy recovery below three years against fixed-price municipal contracts.
- Office Buildings:Troffer and linear pendant installations for task illumination. Human-centric lighting specification in North American healthcare and education verticals drives tunable white system adoption.
- Retail Outlets:Track and spotlight systems emphasizing merchandise color rendering. Fashion and luxury brands in Milan and Paris specify 95+ CRI sources for skin tone and fabric accuracy.
- Sports Arenas:Floodlighting with broadcast television compatibility and glare control for athlete safety. FIFA and Olympic venue standards mandate flicker-free operation and uniform horizontal illuminance.
- Museums:Conservation-grade sources with UV and infrared filtration protecting light-sensitive artifacts. The Louvre and Uffizi Galleries specify custom spectral power distributions minimizing photochemical degradation.
Warehouses and street lighting command volume leadership; museums and sports arenas sustain premium margin pools.
Installation:
Customer type divides between facility management consortia specifying enterprise service agreements and individual building operators procuring unit replacements.
- Surface Mounted:Direct ceiling or wall attachment without plenum penetration. Commercial retrofit in aging German and US building stock avoids structural modification costs.
- Recessed:Downlight and troffer integration with suspended ceiling systems. Office and healthcare verticals in North America specify for clean aesthetic and reduced ceiling clutter.
- Pendant:Suspended luminaires for task and ambient layering. Hospitality and retail designers in London and Tokyo leverage pendant forms for spatial definition.
- Track:Adjustable rail systems for retail and gallery flexibility. Museum curators require repositioning capability for rotating exhibition layouts.
- Pole Mounted:Street and area lighting with structural engineering for wind loading. Municipal procurement in India and Brazil emphasizes vandal resistance and tool-less maintenance access.
- Cove Lighting:Concealed indirect illumination washing ceiling planes. Luxury residential and hotel lobbies in Dubai and Singapore specify for atmospheric effect without visible source.
Surface mounted and recessed capture retrofit volume; cove and pendant gain share in new construction specification.
End User:
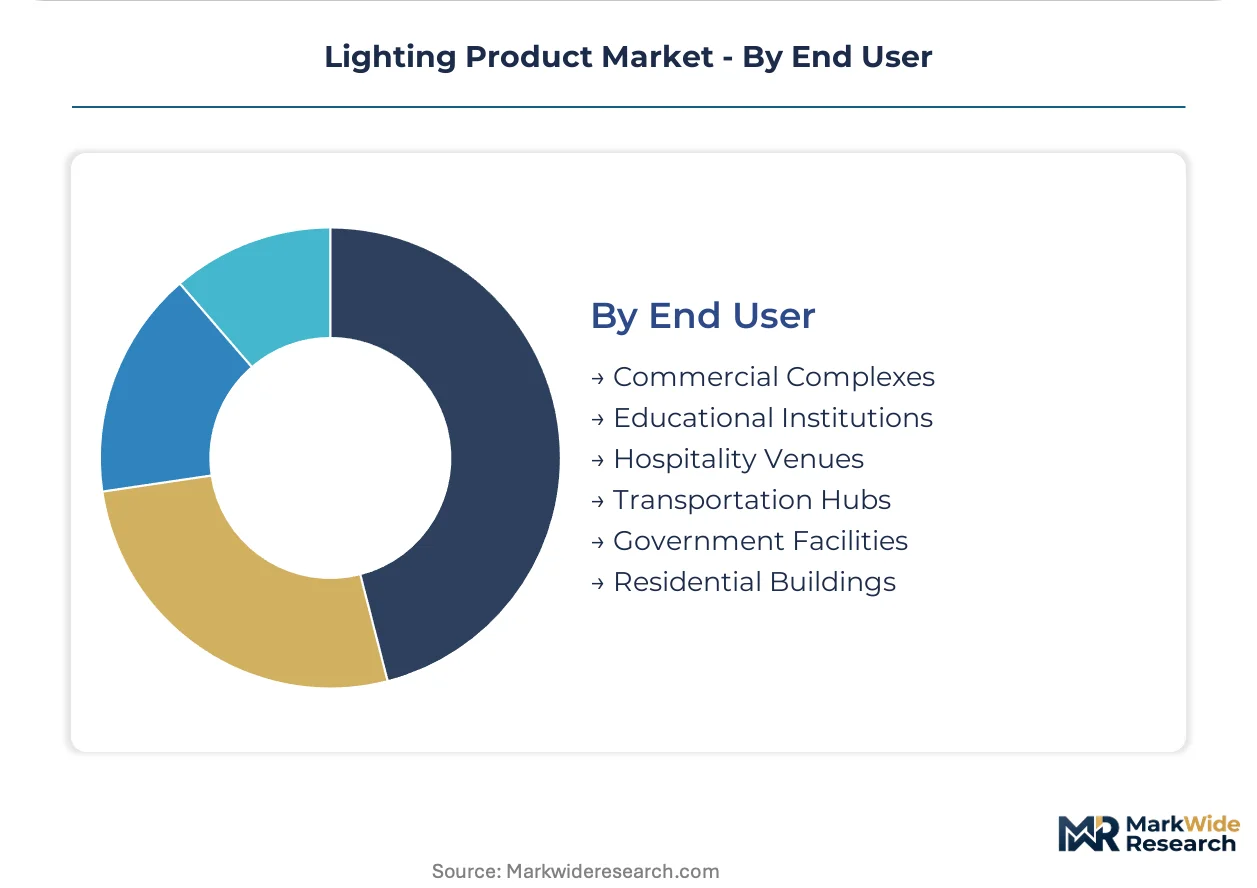
Supply concentration clusters with commercial complexes and government facilities consolidating procurement authority, while residential and hospitality remain fragmented.
- Commercial Complexes:Multi-tenant office and mixed-use developments with centralized facility management. German and US real estate investment trusts negotiate enterprise lighting service agreements spanning maintenance and energy performance guarantees.
- Government Facilities:Federal, state, and municipal buildings with ENERGY STAR and DLC procurement eligibility requirements. US Department of Energy efficacy benchmarks gate utility rebate access.
- Educational Institutions:K-12 and university campuses specifying tunable white for circadian health. North American school districts prioritize human-centric lighting in new construction.
- Transportation Hubs:Airport, rail station, and port illumination with 24-hour operational demands. Dubai International and Singapore Changi specify for wayfinding clarity and security imaging compatibility.
- Hospitality Venues:Hotels, restaurants, and entertainment spaces emphasizing atmosphere and brand identity. Boutique properties in Paris and Kyoto invest in custom fixture design.
- Residential Buildings:Single-family and multi-family dwellings with fragmented procurement through electrical distributors and big-box retail. Smart home integration drives connected fixture specification in premium segments.
Commercial complexes and government facilities concentrate procurement power; educational institutions represent the steepest expansion trajectory for human-centric specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in lighting products tilt toward net exporters with dominant LED component manufacturing bases, while import-dependent markets concentrate procurement authority through facility management consortia and government procurement frameworks.
China
MIIT circular economy directives accelerate domestic LED conversion timelines while GB standards tighten efficacy thresholds faster than IEC baselines. Export-oriented manufacturers in Guangdong and Zhejiang provinces maintain dual product lines to serve divergent compliance regimes, with domestic producers gaining cost advantages in basic replacement categories.
Germany
Real estate investment trusts negotiate enterprise lighting service agreements spanning multi-year maintenance and energy performance guarantees. The EU Ecodesign Directive eliminates mercury-containing fluorescent sources while mandating minimum performance thresholds. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate optical engineering expertise for premium specification tiers.
United States
The Department of Energy enforces efficacy benchmarks through ENERGY STAR and DLC qualification requirements that gate utility rebate access. Human-centric lighting specification in healthcare and education verticals drives tunable white system adoption in California and Northeast corridor markets. Facility management consolidation shifts vendor selection toward balance sheet strength.
India
Off-grid solar-LED packages for unelectrified settlements represent volume expansion outside grid-connected replacement demand saturation. Bureau of Energy Efficiency standards and smart city investments reshape municipal procurement in Maharashtra and Karnataka. Logistics operators specify high-bay LED arrays with integrated daylight harvesting to compress energy recovery timelines.
Japan
METI efficiency standards and aging building stock drive retrofit demand concentrated in Tokyo and Osaka metropolitan areas. Optical engineering talent scarcity constrains product development velocity as compound lens design expertise concentrates among aging specialists. Premium architectural OLED specifications serve hospitality and museum installations.
Lighting Product Market Key Industry Players
Concentration sits with diversified electrical conglomerates and specialized lighting technology groups that span component supply through systems integration. The vendor base separates into three strategic archetypes: platform-integrated service providers, component-specialized technology licensors, and regional installation-focused distributors. Competitive moves center on strategic partnerships for sensor network integration and geographic expansion through local assembly partnerships to circumvent freight cost volatility.
Among platform-integrated service providers, Signify Holding and Acuity Brands exemplify the enterprise service agreement model, while ams-OSRAM AG occupies the component-specialized tier with advanced LED chip architectures. These three entities anchor distinct competitive vectors—connected infrastructure management, tunable application systems, and premium semiconductor supply—without overlapping core value propositions.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands, Inc. |
| ams-OSRAM AG |
| Panasonic Holdings Corporation |
| Cree Lighting USA LLC |
| Zumtobel Group |
| GE Lighting |
| Hubbell Incorporated |
| Schneider Electric |
| Others |
Cost & Logistics Intelligence
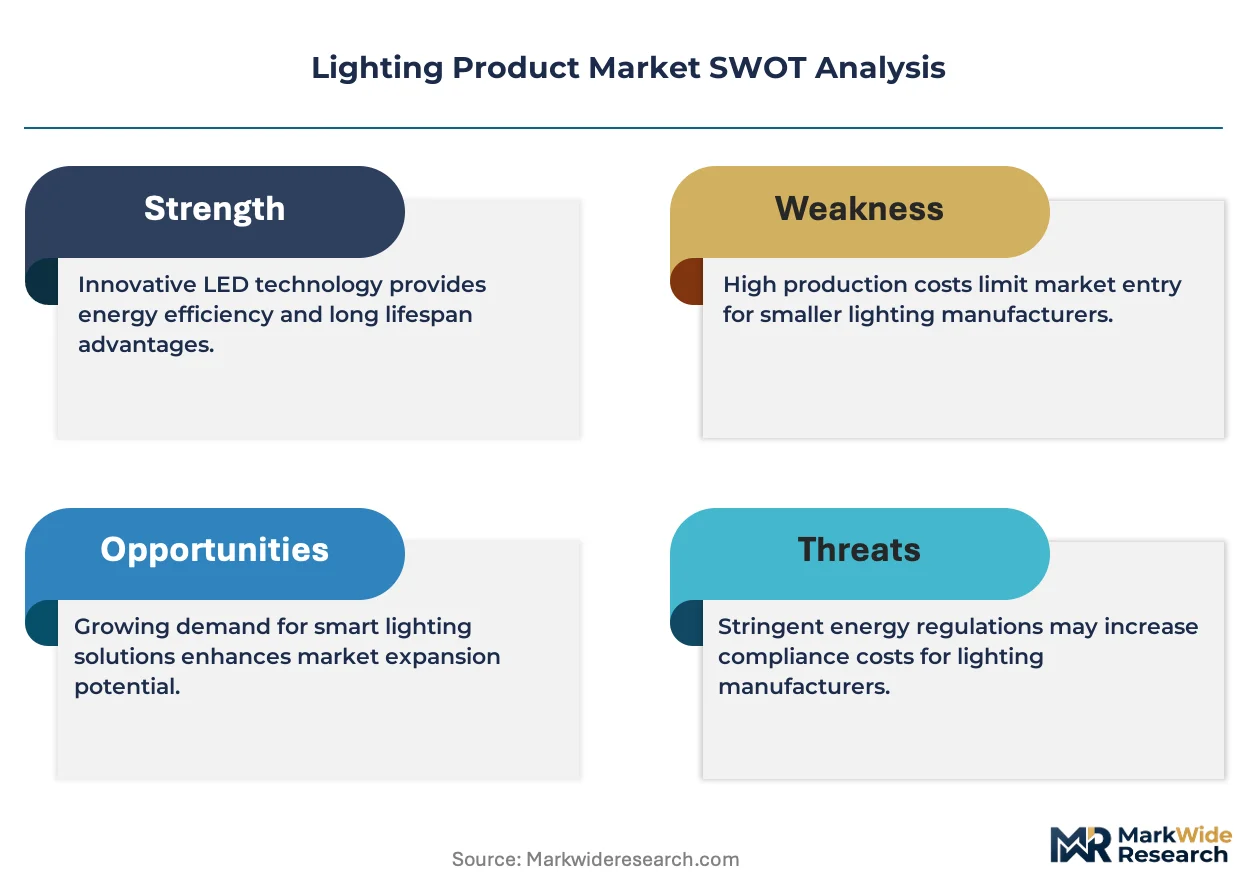
LED chip substitution for legacy fluorescent sources simultaneously relocates manufacturing gravity toward East Asian epitaxial wafer clusters and compresses fixture-level pricing power as lumens-per-watt commoditization accelerates. This displacement concentrates margin capture upstream while downstream assemblers face fixed-price municipal contract exposure against volatile copper and aluminum heat sink costs.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by ENERGY STAR certification tier and volume scale procurement. Cost compression in economy-tier replacement bulbs intensifies because Chinese domestic producers exploit GB standard compliance advantages against export-oriented dual-product-line manufacturers. Municipal facility managers exhibit highest price sensitivity due to fixed-budget procurement cycles, while healthcare specification engineers prioritize circadian performance over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites LED component flows from Guangdong and Zhejiang provinces to European and North American luminaire assemblers. Epitaxial wafer production draws from China, Taiwan, and South Korea, with sapphire substrate and MOCVD equipment dependencies creating single-source vulnerability for mid-tier manufacturers. Distribution runs through facility management consortia and electrical distributor networks serving commercial retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where regulatory entrenchment through multi-jurisdiction certification requirements creates switching costs that protect incumbent positions against pure-play commoditization.
For Market Incumbents: Compound platform integration advantages by embedding sensor networks and control software deeper into enterprise service agreements, defending against modular disaggregation from specialized controls vendors. Extend optical engineering capabilities through targeted acquisition of German and Japanese lens design specialists facing generational talent attrition.
For New Entrants and Emerging Players: Anchor in rural electrification white space across unelectrified Indian and sub-Saharan African settlements, where solar-LED package demand sits outside incumbent service network coverage. Pursue Li-Fi transceiver integration as a specification wedge in defense and healthcare secure facilities, bypassing established RF infrastructure relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward component-specialized technology licensors with captive LED chip architectures and automotive-grade reliability certifications, positioned for premium-tier margin extraction over the coming decade. Monitor EU Ecodesign Directive phase-out calendar acceleration as an inflection signal for fluorescent inventory devaluation velocity and distributor consolidation opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Network Integration | Signify's Interact platform demonstrates how connected infrastructure absorbs building automation functionality. |
| Optical Engineering Acquisition | German and Japanese lens design expertise concentrates among aging specialists creating talent arbitrage. |
| Li-Fi Transceiver Development | Defense and healthcare secure facilities specify visible light communication to eliminate RF interference vulnerabilities. |
| Rural Electrification Packaging | Off-grid solar-LED systems in India and sub-Saharan Africa expand volume outside grid-connected saturation. |
| Human-Centric Certification Investment | Tunable white specification in North American healthcare and education verticals gates premium procurement access. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across facility management consortia, electrical distributor procurement leads, municipal lighting engineers, and optical product development directors. Secondary validation incorporated ENERGY STAR qualification databases, DLC product listings, EU Ecodesign Directive regulatory filings, and customs trade flow records. Bottom-up segment sizing and top-down macroeconomic triangulation were cross-referenced to constrain variance.
Across the analysis window, projections were developed through segmented modeling across product type, application, installation method, and end-user vertical, with regional regulatory cluster overlays. CAGRs were derived from installed base replacement cycle compression, smart city infrastructure investment trajectories, and efficacy standard escalation curves. Forecast inputs incorporated copper and aluminum commodity price scenarios alongside LED chip cost experience curves.
Decision-makers should treat outputs as directional under sustained regulatory phase-out enforcement and supply chain geographic concentration assumptions; material deviation would warrant model refresh. Specific risks include export control disruptions affecting epitaxial wafer availability and accelerated GB standard divergence from IEC baselines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
North America Smart Lighting Market
Lighting
Lighting Management System Market
Lighting
Vintage Bulb Market
Lighting
Connected Lighting Platform Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Smart Lighting Market
Lighting
Connected (Smart) Street Lighting Market
Lighting
US Indoor LED Lighting Market
Lighting
Solar Spotlights Market
Lighting
Directional Luminaire Market
Lighting
Global Machine Vision Lighting Market
Lighting
Architectural Lighting Market
Lighting
Plasma Lighting Market
Lighting
Intelligent Lighting Market
Lighting
Global Headlight Control Module Market
Lighting
Cleanroom Lighting Market