
 Intelligent Lighting Market | 2026-2036
Intelligent Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Lighting Market Foresight
China is narrowing its cost advantage in LED module assembly while expanding upstream chip fabrication. Signify anchors European demand through professional channel dominance in commercial retrofit projects. Cree Lighting specializes in high-performance chip-on-board arrays for industrial and horticultural applications. Acuity Brands controls North American specification-grade distribution through its agency network and digital design tools.
Intelligent lighting denotes luminaire systems integrating solid-state emitters, networked sensors, and programmable control logic to enable automated dimming, spectral tuning, and occupancy-responsive operation. These systems typically operate below 50W per node, communicate via mesh protocols, and incorporate photosensors with detection thresholds of 10-500 lux for daylight harvesting. LED product type holds the largest installed base but controllers capture disproportionate margin pools through software recurring revenue. Wi-Fi technology leads residential penetration for its smartphone compatibility, while Zigbee dominates commercial deployments where mesh reliability and gateway density matter more than consumer convenience.
The EU Ecodesign Directive and CE marking requirements enforce minimum luminous efficacy and standby power limits, effectively filtering non-compliant imports from European tenders. In the United States, the EPA ENERGY STAR program and DOE appliance standards shape procurement specifications for federal and utility-rebate-backed projects. China's GB standards and MIIT circular economy directives mandate recyclability and rare-earth recovery rates for domestic manufacturers. Stakeholders must weigh protocol interoperability against cybersecurity certification burdens as building automation converges with IT infrastructure.
Market Dynamics
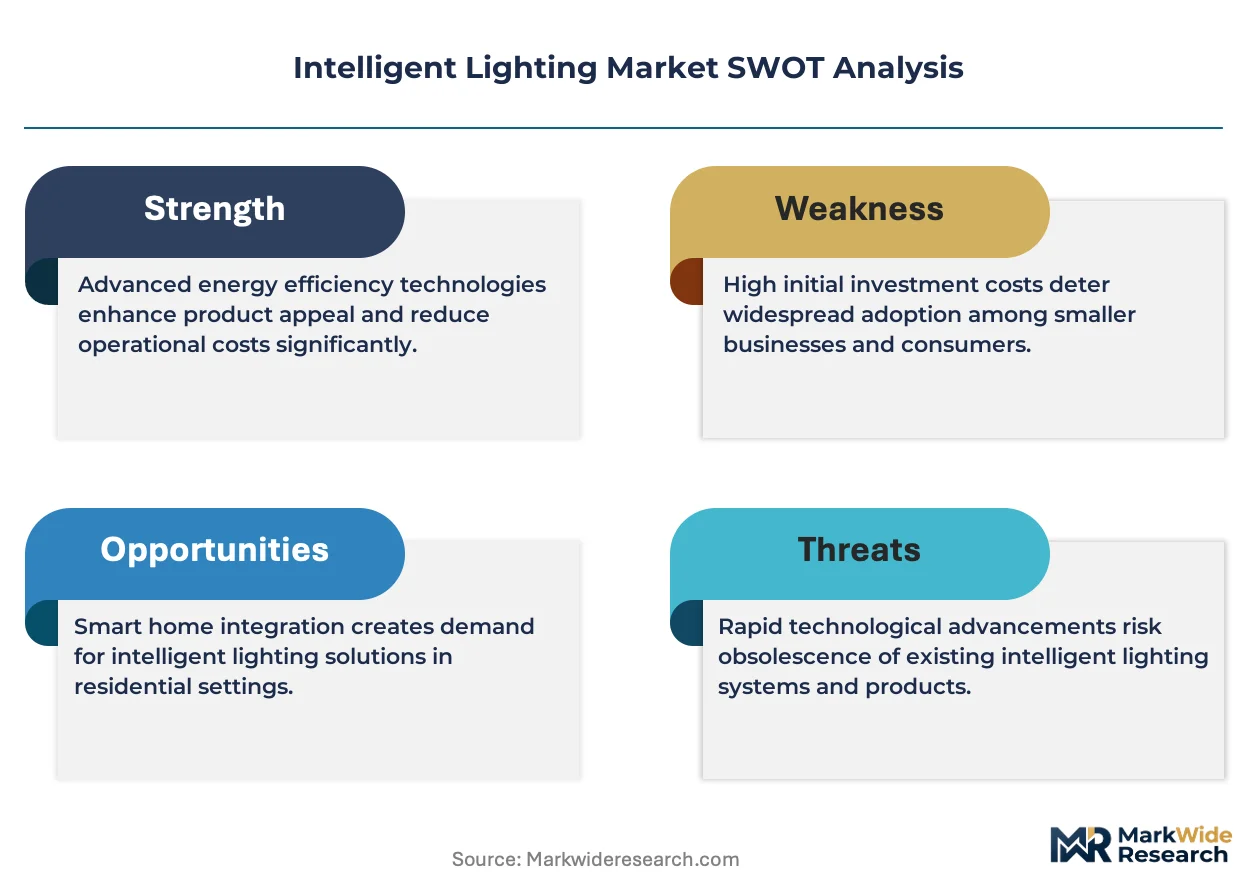
Building automation convergence with IT infrastructure is compressing procurement cycles and forcing luminaire vendors to certify for cybersecurity frameworks previously foreign to lighting hardware.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficacy mandates are filtering non-compliant imports from European tenders and accelerating retrofit demand in commercial stock.
- Smart city infrastructure:Municipal deployments in China are integrating networked lighting with traffic and environmental sensors at district scale.
- Mesh protocol reliability:Zigbee's gateway density advantages are displacing proprietary RF in commercial building specifications where uptime guarantees dominate.
Market Restraints
- Rare-earth supply concentration:Phosphor and magnet dependencies tied to Chinese processing capacity create input cost volatility for LED module assembly.
- Protocol fragmentation:Competing connectivity standards (Zigbee, Thread, Matter, proprietary mesh) force multi-certification burdens that inflate controller BOM costs.
- Legacy fluorescent installed base:Extended replacement cycles in institutional buildings delay intelligent system penetration where capital budgets are constrained.
Strategic Opportunities
- Horticultural lighting:Spectral tuning capabilities are opening controlled-environment agriculture applications with precision photosynthetic photon flux delivery.
- Software recurring revenue:Cloud-based lighting management platforms are capturing margin pools that hardware-only vendors cannot access.
- India's smart city mission:Municipal digitization programs are creating tender pipelines for networked street lighting with integrated air quality monitoring.
Industry Challenges
- Cybersecurity certification complexity:IEC 62443 and NIST framework compliance requires firmware architecture redesigns that extend product development timelines.
- Legacy BAS integration:BACnet and Modbus protocol translation introduces commissioning friction that inflates deployment costs in retrofit commercial projects.
- Optical engineering talent scarcity:Human-centric lighting design requires spectral biologists and circadian rhythm specialists that traditional electrical engineering programs do not produce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Lighting Market |
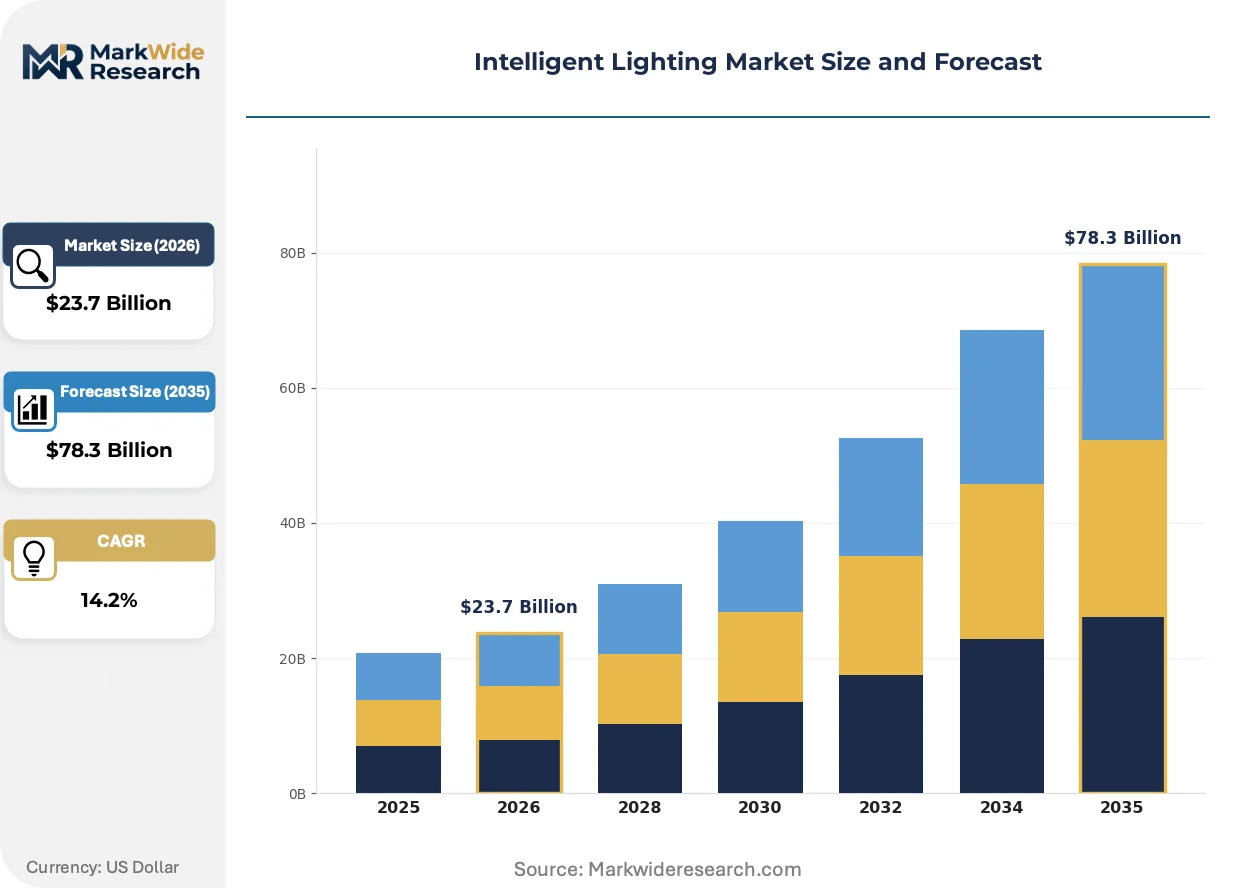
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Smart Bulbs, Fixtures, Controllers Technology: Wi-Fi, Zigbee, Bluetooth, Li-Fi Application: Residential, Commercial, Industrial, Outdoor End User: Homeowners, Businesses, Contractors, Government |
| Companies Covered | Cree Lighting, Honeywell International, Signify, Nanoleaf, LG Electronics, Schneider Electric, OSRAM, Govee, Acuity Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Lighting Market Shifts & Advancements
Intelligent lighting is absorbing adjacent building systems into unified control planes, collapsing the distinction between illumination infrastructure and environmental sensing networks.
Li-Fi visible light communication is hybridizing illumination and data transmission functions. Commercial aviation and defense contractors are piloting cabin and secure-facility deployments where RF congestion or electromagnetic interference prohibits conventional wireless. This convergence is compressing the addressable market for standalone access point hardware by embedding connectivity into luminaire form factors.
China's MIIT circular economy directives are mandating rare-earth recovery rates and recyclability standards that domestic manufacturers must meet for government tender eligibility. These rules are reshaping supply chain relationships between luminaire assemblers and component recyclers. Export-oriented vendors serving European and North American markets are adopting these standards preemptively to maintain cross-border shipment eligibility.
Facility managers are unbundling lighting maintenance from traditional mechanical service contracts and awarding standalone performance-based agreements to specialized controls integrators. This procurement pattern shift is disintermediating electrical distributors who historically captured recurring maintenance revenue. The trend is most visible in US commercial office portfolios where institutional ownership demands granular energy attribution and predictive failure analytics.
Intelligent Lighting Market Segmentation
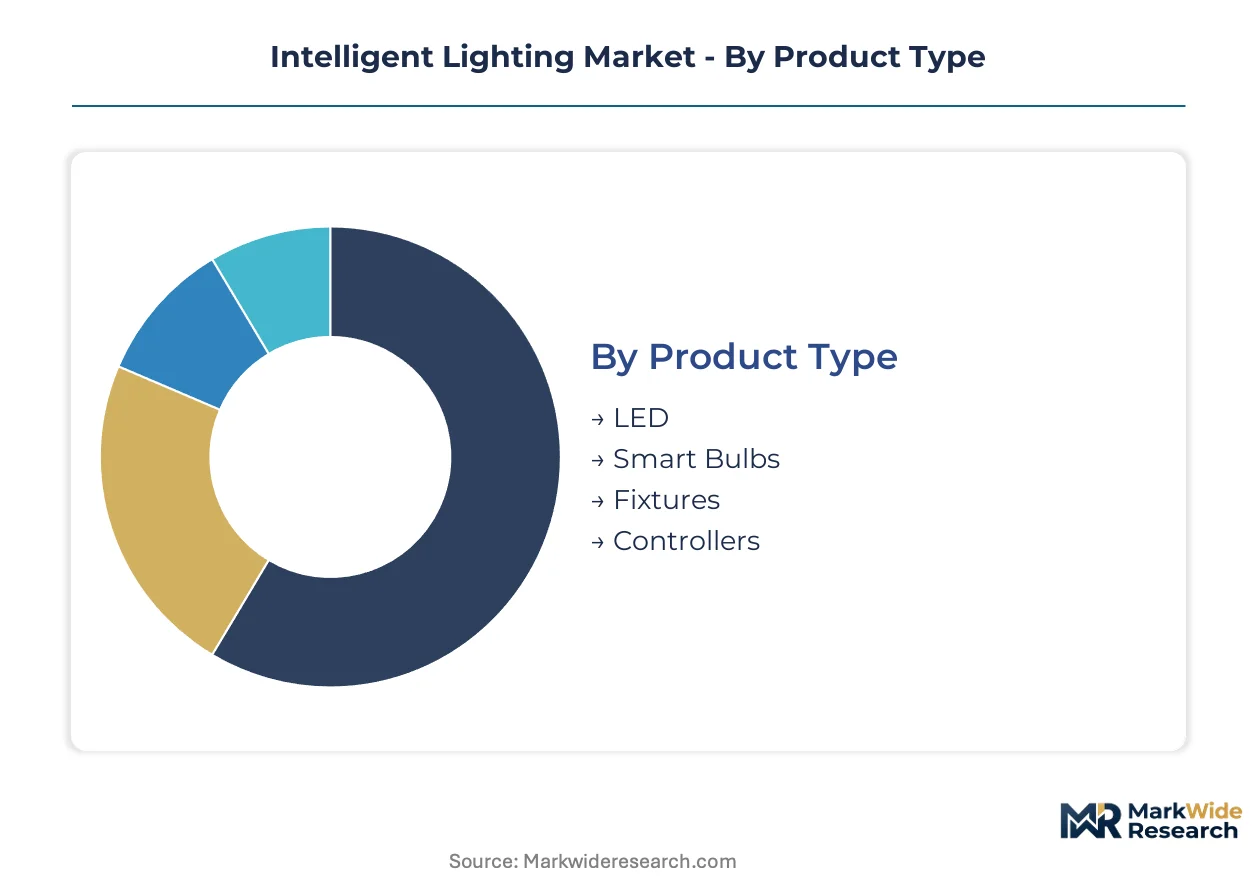
Intelligent lighting vendors engineer service intensity differently across product categories. LED modules demand minimal post-installation support while controller ecosystems generate recurring software maintenance contracts. Segmentation strategy must align hardware margin profiles with lifetime service revenue potential.
Product Type:
After-sales-service intensity escalates sharply from passive luminaires to networked control systems requiring firmware updates and cloud subscription management.
- LED:Solid-state emitter modules with luminous efficacy exceeding 150 lm/W dominate installed base volume. Demand concentrates in Chinese commercial retrofit projects where domestic supply chains compress procurement cycles and GB standards mandate recyclability compliance.
- Controllers:Programmable gateway and zone-control hardware with mesh protocol translation capabilities capture disproportionate margin pools. European commercial building operators drive specification-grade procurement as EU Ecodesign Directive enforcement tightens efficacy and standby power requirements.
- Smart Bulbs:Consumer-grade retrofit lamps with embedded wireless radios for smartphone app pairing.
- Fixtures:Luminaire housings integrating heat dissipation, optical distribution, and sensor mounting infrastructure.
LED holds the largest share; momentum sits with Controllers.
Technology:
Protocol selection dictates hardware bill-of-materials cost tier and determines which customer segments become accessible.
- Zigbee:Mesh networking protocol with self-healing topology and sub-GHz penetration through building materials dominates commercial specifications. Gateway density requirements favor integrators serving US office portfolios where uptime guarantees override consumer convenience priorities.
- Wi-Fi:IP-native connectivity leveraging existing infrastructure enables fastest residential deployment. Smartphone compatibility drives homeowner adoption in North American retrofit markets where router density eliminates gateway hardware costs.
- Bluetooth:Low-energy beaconing and direct device-to-phone pairing for proximity-based control scenarios.
- Li-Fi:Visible light modulation for electromagnetic-sensitive environments including aviation cabins and defense facilities.
Zigbee commands commercial specification; Wi-Fi expands most quickly in residential penetration.
Application:
End-use environment determines performance certification requirements and installation labor intensity.
- Commercial:Integrated daylight harvesting and occupancy-responsive dimming systems for office, retail, and hospitality environments. Building automation convergence in US federal facilities shapes procurement specifications around EPA ENERGY STAR and DOE appliance standards.
- Industrial:High-bay and hazardous-location luminaires with extreme temperature tolerance and vibration resistance. Horticultural spectral tuning applications in controlled-environment agriculture drive precision photosynthetic photon flux demand.
- Residential:Consumer retrofit and new construction lighting with app-based scene programming.
- Outdoor:Street and area lighting with integrated environmental sensing for municipal smart city infrastructure.
Commercial generates the largest revenue concentration; industrial applications gain share fastest.
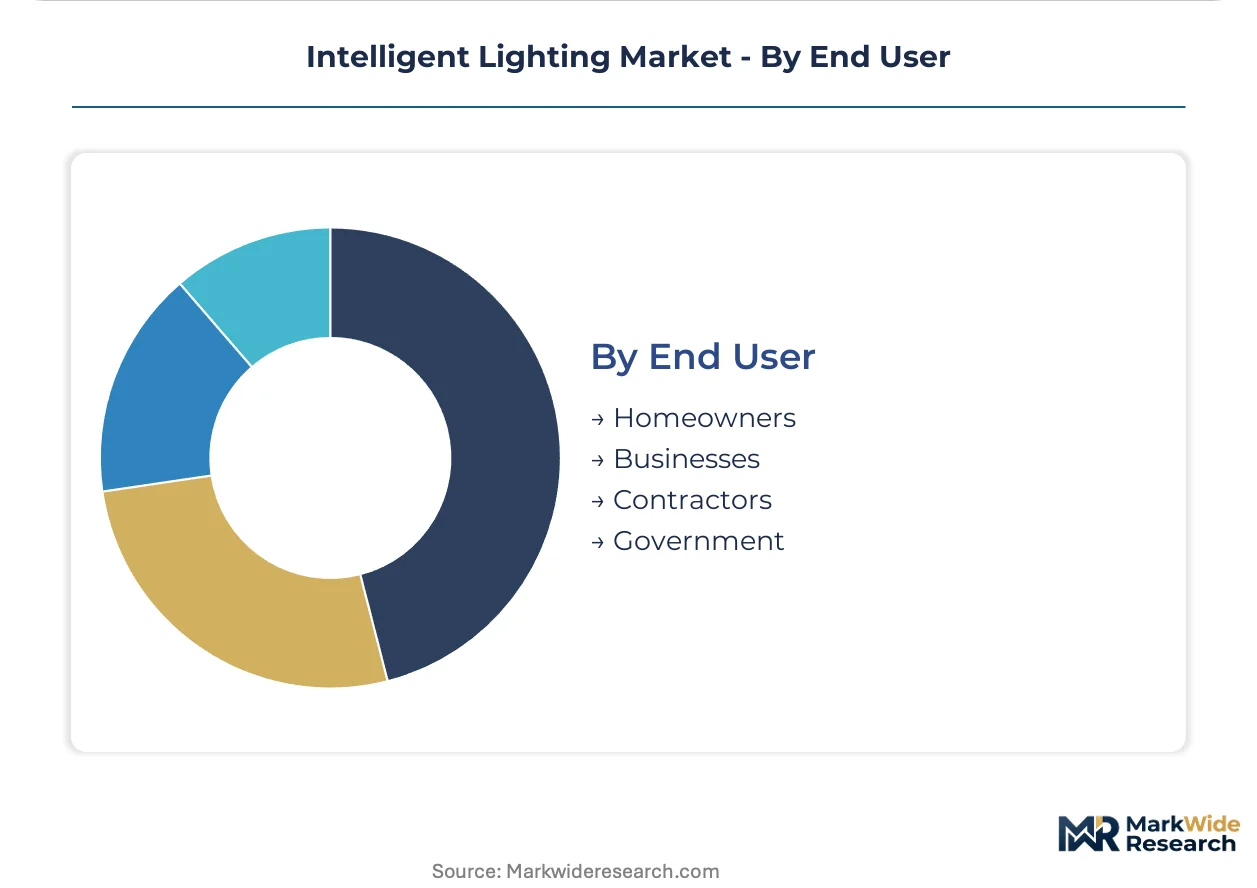
End User:
Customer type determines procurement channel structure and contract terms from spot purchasing to multi-year performance agreements.
- Businesses:Corporate and institutional facility managers unbundling lighting maintenance from mechanical service contracts. US commercial office portfolios award standalone performance-based agreements to specialized controls integrators demanding granular energy attribution.
- Government:Municipal and federal procurement with cybersecurity certification requirements under IEC 62443 and NIST frameworks. China's smart city mission creates tender pipelines for networked street lighting with integrated air quality monitoring.
- Homeowners:Individual consumers purchasing through retail and e-commerce channels.
- Contractors:Electrical installation firms specifying products for new construction and retrofit projects.
Businesses account for the dominant procurement volume; government tenders exhibit the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT circular economy directives are reshaping procurement eligibility for government tenders in China, the world's largest intelligent lighting installation base. The report tracks demand concentration across five countries where regulatory enforcement and industrial clustering converge.
United States
Commercial building operators unbundle lighting maintenance from mechanical service contracts, awarding standalone performance-based agreements. EPA ENERGY STAR and DOE appliance standards shape federal procurement specifications. Greater Boston and Pacific Northwest tech corridors drive specification-grade controller demand through institutional ownership portfolios.
China
Smart city infrastructure deployments integrate networked lighting with traffic and environmental sensors at district scale. MIIT mandates rare-earth recovery rates and recyclability standards for domestic manufacturer eligibility. Yangtze River Delta and Pearl River Delta clusters compress LED module procurement cycles through captive upstream chip fabrication.
Germany
EU Ecodesign Directive enforcement tightens efficacy and standby power requirements for commercial retrofit specifications. CE marking requirements filter non-compliant imports from European tenders. Bavaria and North Rhine-Westphalia anchor professional channel dominance in commercial building automation convergence projects.
Japan
METI efficiency standards and JIS certification requirements shape premium-tier procurement for human-centric lighting applications. Kanto and Kansai regions concentrate optical engineering talent for circadian rhythm design. Tokyo's commercial real estate portfolios drive specification-grade mesh protocol deployments.
India
Municipal digitization programs under the Smart Cities Mission create tender pipelines for networked street lighting with integrated air quality monitoring. BIS energy efficiency standards and CEA grid integration norms shape procurement specifications. Maharashtra and Gujarat industrial corridors drive controller assembly localization.
Intelligent Lighting Market Competitive Landscape
Lighting-heritage conglomerates and electrical-component multinationals split the market between luminaire manufacturing and control system integration. The vendor base concentrates around three strategic archetypes: legacy lamp manufacturers pivoting toward software services, building-automation specialists extending into lighting controls, and consumer-electronics entrants capturing residential retrofit volume. Dominant competitive moves include strategic partnerships with cloud platform providers and backward integration into LED chip fabrication to secure phosphor supply chains.
Within the lighting-heritage tier, Signify and OSRAM exemplify European professional-channel dominance, while Cree Lighting occupies a position among North American specialists in high-performance emitter arrays. Acuity Brands anchors specification-grade distribution through agency network control in US commercial building markets.
| Leading Market Players |
|---|
| Cree Lighting |
| Honeywell International |
| Signify |
| Nanoleaf |
| LG Electronics |
| Schneider Electric |
| OSRAM |
| Govee |
| Acuity Brands |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese LED chip fabrication is compressing module pricing globally while forcing suppliers toward controller software and service bundling to defend margin pools. This utilization dynamic simultaneously erodes hardware-only vendor viability and rewards integrated platform providers with recurring revenue architecture.
Pricing Analysis
Geographic price spreads between Chinese domestic tenders and European specification-grade projects exceed three-to-one for comparable lumen packages, reflecting certification overhead and cybersecurity compliance burdens. Three-tier pricing structure across premium, standard, and economy levels stratifies by IEC 62443 certification tier and gateway software capability rather than raw luminous output. Pricing pressure stems from Yangtze River Delta module oversupply feeding into export markets. Government procurement offices exhibit highest price sensitivity; data center operators demonstrate lowest sensitivity due to energy attribution requirements.
Supply Chain Analysis
Upstream feedstock concentration in Chinese rare-earth processing for phosphor materials and gallium nitride substrates creates input cost volatility that module assemblers cannot easily hedge. Manufacturing draws from China, Taiwan, and South Korea for emitter chips; Malaysia and Mexico for final luminaire assembly. Phosphor rare-earths, aluminum nitride substrates, and silicon carbide wafers represent critical dependencies. Single-source vulnerability in Chinese magnet supply for driver components threatens production continuity. Distribution runs through electrical distributors in North America, professional systems integrators in Europe, and direct municipal tender channels in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intelligent lighting represents a high-growth disruption where building automation convergence and cybersecurity certification mandates are restructuring competitive viability around software platforms rather than hardware volume.
For Market Incumbents: Entrench controller ecosystem dominance through backward integration into LED chip fabrication and exclusive agency network control in specification-grade commercial channels. Threat from consumer-electronics entrants with Wi-Fi-native platforms demands preemptive Zigbee mesh certification density in US federal facilities. Channel control through digital design tools and performance-based maintenance contracts constitutes the critical defensive lever.
For New Entrants and Emerging Players: Build out horticultural spectral tuning capabilities and India's Smart Cities Mission tender pipelines where incumbent lighting-heritage vendors lack localized controller integration expertise. India's municipal digitization programs present the most penetrable geography given fragmented incumbent presence and BIS compliance gaps. Go-to-market through specialized controls integrators unbundling from traditional electrical distributors captures procurement pattern shifts in institutional ownership portfolios.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among controller platform providers with cloud-based lighting management subscriptions and firmware update architectures. Long-term viability favors vendors with cybersecurity certification pre-positioning for IEC 62443 and NIST framework convergence. Acquisition target archetype: mid-cap mesh protocol specialists with gateway density advantages in commercial building specifications. Signal to watch: facility manager unbundling of lighting maintenance from mechanical service contracts accelerating performance-based agreement awards.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Chip Fabrication | Captures phosphor supply chain and secures MIIT circular economy directive compliance for Chinese tender eligibility. |
| Cybersecurity Certification Investment | IEC 62443 and NIST framework positioning unlocks US federal and critical infrastructure procurement specifications. |
| Cloud Platform Partnership | Software recurring revenue capture exceeds hardware margin pools through lighting management subscription architectures. |
| Horticultural Spectral Tuning Development | Controlled-environment agriculture applications deliver precision photosynthetic photon flux with premium pricing power. |
| India Smart City Localization | Municipal digitization tender pipelines require controller assembly localization and BIS energy efficiency standard alignment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry association disclosures across the intelligent lighting value chain. Primary interviews engaged lighting controls engineers, commercial facility managers, municipal procurement officers, and electrical distribution channel heads. Secondary validation drew from EPA ENERGY STAR product databases, EU Ecodesign Directive implementing measures, China MIIT circular economy directives, and SEC 10-K disclosures from publicly traded lighting-heritage conglomerates. Bottom-up project pipeline enumeration triangulates against top-down market sizing from installed base replacement cycles.
Forecast inputs incorporate protocol adoption curves, efficacy mandate enforcement timelines, and smart city infrastructure deployment schedules across the projection horizon. Segmentation dimensions modeled include product type, connectivity technology, application environment, and end-user procurement channel. CAGRs derive from regression against historical retrofit penetration rates and regulatory-driven replacement mandates. Industry-specific inputs include rare-earth price volatility indices and building automation convergence adoption thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive moves by consumer-electronics platforms or cybersecurity-native entrants would shift outcomes beyond modeled ranges. Cross-checking against utility rebate program disbursement data and federal facilities procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Miniature Bulbs Market
Lighting
Indicator Lights Market
Lighting
Ambient Lighting Market
Lighting
Global Commercial Lighting Market
Lighting
Fluorescent Lighting Market
Lighting
Inspection Lighting Fixture Market
Lighting
Global Lighting Control System Market
Lighting
High-End Lighting Market
Lighting
Global Stadium Lighting Market
Lighting
Photocell Market
Lighting
North America Street Lighting Market
Lighting
Bacteriological Light Market
Lighting
Circadian Lighting Market
Lighting
Intelligent Lighting Controls Market
Lighting
Lighting As a Service (Laas) Market