
 Mexico LED Lighting Market | 2026-2036
Mexico LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico LED Lighting Market Outlook
NOM-013-ENER-2013 is expanding addressable demand by prohibiting inefficient incandescent and halogen sales, compelling facility managers to specify LED retrofits. Signify N.V. leverages its Philips brand equity and distribution depth to anchor the professional channel across Mexican metropolitan zones. Cree Lighting sustains technology leadership through silicon carbide substrate innovation that improves thermal performance in high-temperature industrial settings. Grupo Construlita Iluminación S.A. de C.V. dominates domestic specification-grade projects with localized manufacturing and rapid custom fixture turnaround.
Mexico LED lighting comprises solid-state semiconductor devices that emit visible light when electrical current passes through gallium nitride or indium gallium nitride junctions, typically operating at 80-150 lumens per watt with rated lifespans exceeding 50,000 hours. These systems serve primary purposes of reducing kilowatt-hour consumption, extending maintenance intervals, and enabling digital control protocols in built environments. Residential application growth reflects rising mortgage penetration and federal Infonavit green housing incentives that specify LED package minimums. Smart lighting technology leads margin pools through sensor integration and networked management platforms, while traditional LED segments occupy volume leadership in price-sensitive retrofit channels.
CONUEE (Comisión Nacional para el Uso Eficiente de la Energía) administers appliance labeling and verification testing that determines market access for imported luminaires. CFE (Comisión Federal de Electricidad) utility rebate programs shape procurement economics through verified savings calculations tied to measured wattage reductions. Stakeholders must monitor proposed NOM-030-ENER updates addressing connected lighting standby power and cybersecurity interoperability requirements.
Market Dynamics
Federal energy efficiency mandates are compressing replacement cycles across Mexico's built environment, compelling facility managers to abandon legacy fluorescent and incandescent systems ahead of natural end-of-life. NOM-013-ENER-2013's luminous efficacy thresholds function as a technology-forcing mechanism that redistributes procurement budgets toward solid-state lighting.
Growth Catalysts
- NOM-013-ENER-2013 efficacy mandates:Federal minimums prohibit inefficient lamp sales, redirecting commercial and residential demand toward LED retrofits.
- Maquiladora LEED certification drives:Northern industrial facilities pursue green building credentials that specify high-performance luminaires with verified efficacy ratings.
- Silicon carbide substrate advances:Improved thermal management enables LED deployment in high-temperature manufacturing environments previously hostile to solid-state lighting.
Market Restraints
- Import-dependent driver supply:Mexico lacks domestic semiconductor fabrication capacity for LED control electronics, exposing assemblers to Asia-Pacific supply volatility.
- Upfront capex burden:Quality LED retrofits require 3-4x initial investment versus relamping with legacy technology, constraining adoption in price-sensitive residential segments.
- CONUEE verification bottlenecks:Appliance labeling testing queues delay market access for imported luminaires, compressing effective selling seasons.
Strategic Opportunities
- Smart lighting convergence:Sensor integration and networked management platforms command premium positioning in commercial specification channels.
- Infonavit green housing incentives:Federal mortgage subsidies tied to LED package minimums accelerate residential penetration in emerging urban developments.
- Utility rebate program expansion:CFE verified savings calculations tied to measured wattage reductions improve retrofit project economics for industrial energy managers.
Industry Challenges
- Electrical engineering talent scarcity:Solid-state lighting design, thermal modeling, and control protocol integration skills remain concentrated in Mexico City and Monterrey metropolitan zones.
- Legacy system integration complexity:DALI and 0-10V control retrofits in existing commercial buildings require specialized commissioning expertise that outstrips installer capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico LED Lighting Market |
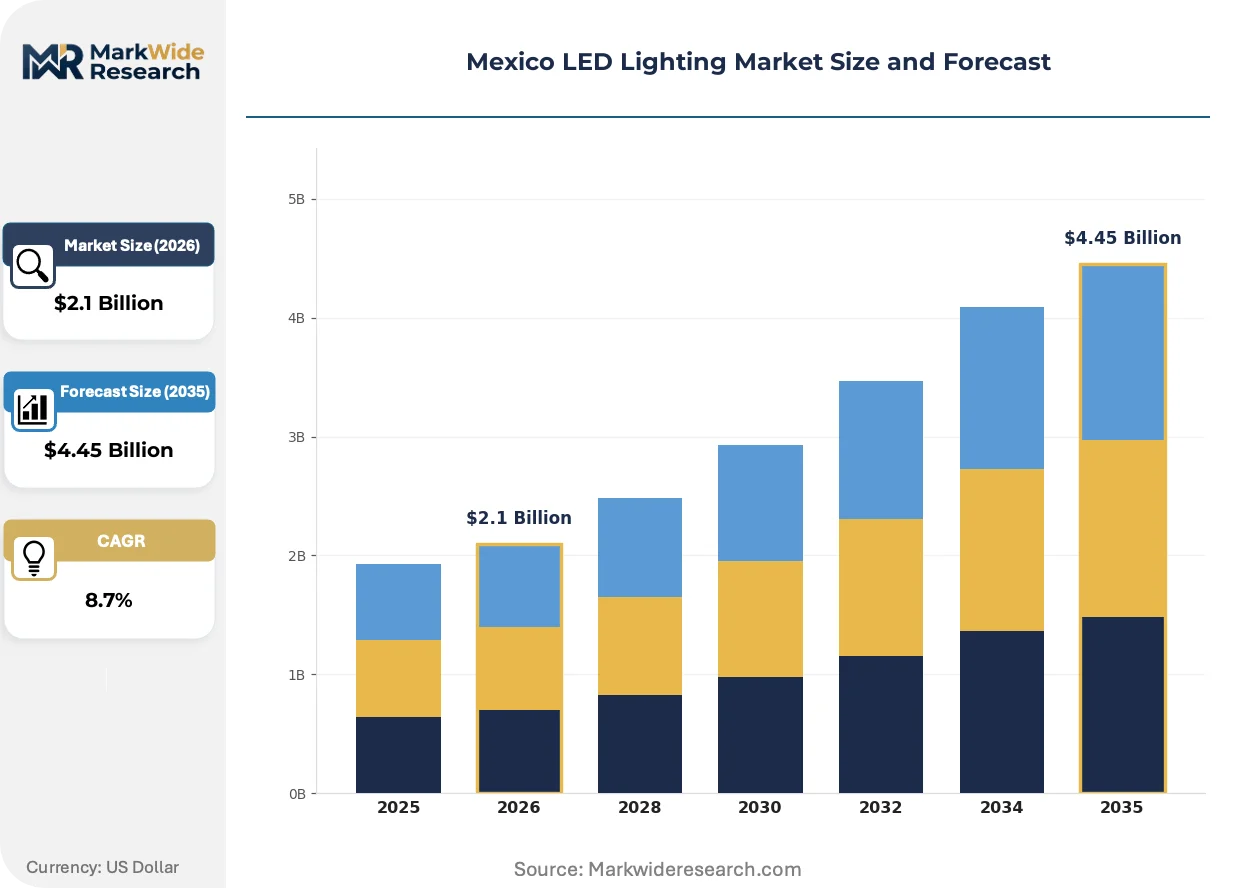
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Panels, Downlights, Fixtures Application: Residential, Commercial, Industrial, Architectural Technology: Smart Lighting, Solar LED, OLED, Traditional LED End User: Retailers, Government, Manufacturers, Hospitality |
| Companies Covered | Acuity Brands Lighting, Inc., Cree Lighting, Signify N.V., Optima Energia, LEDVANCE, Osram Licht AG, Grupo Construlita Iluminación S.A. de C.V., Illux, Samsung Electronics Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico LED Lighting Market Strategic Shifts
Digital control protocols and networked sensor architectures are displacing standalone luminaire sales, restructuring how lighting value is captured across installation, commissioning, and operational phases.
Modular LED engine platforms are modularizing fixture architecture, separating light source modules from housing and optical systems. Commercial real estate developers across Guadalajara and Monterrey specify swappable LED engines to extend fixture chassis life across multiple technology generations. This modularity is modularizing supplier relationships, enabling building owners to source engines, drivers, and controls from specialized vendors rather than single-brand ecosystems.
Proposed NOM-030-ENER updates addressing connected lighting standby power and cybersecurity interoperability requirements are tightening market access standards. Manufacturers must redesign driver electronics and firmware architectures to meet standby consumption ceilings. Professional channel distributors in Mexico City metropolitan zones are pre-qualifying suppliers against draft requirements to avoid inventory obsolescence.
Facility managers are unbundling lighting maintenance from capital procurement, contracting energy service companies for performance-guaranteed retrofits. CFE rebate program verification requirements favor this model, as third-party measurement and verification protocols satisfy utility documentation standards. Northern industrial corridors demonstrate the strongest traction, where maquiladora energy directors prioritize budget predictability over asset ownership.
Mexico LED Lighting Market Segmentation
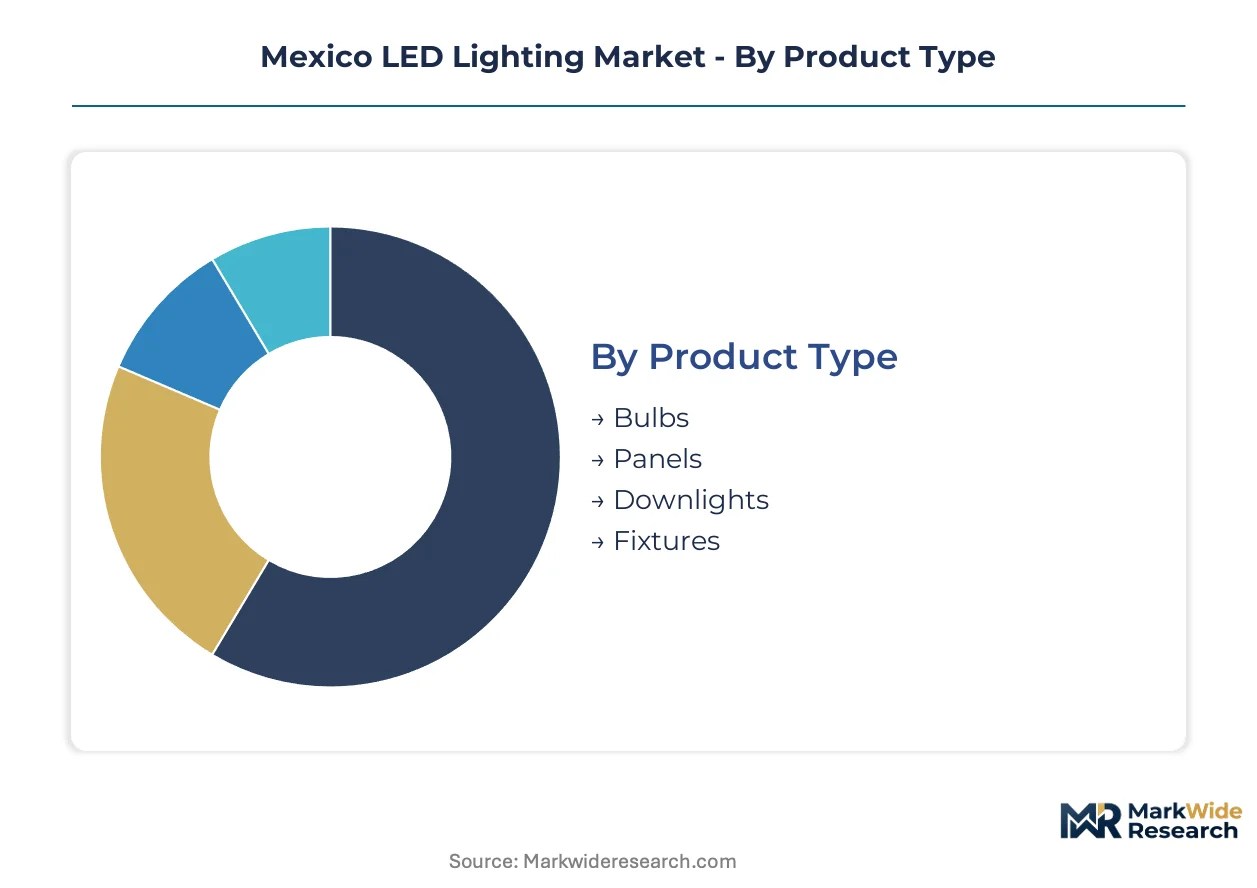
LED lighting procurement in Mexico diverges sharply across buyer types, with federal mandates and utility economics driving specification patterns that fragment vendor strategies. Understanding these segment boundaries reveals where margin pools concentrate versus where volume commoditization accelerates.
Product Type:
Price-performance tradeoffs dominate fixture selection, with procurement committees weighing upfront capital against NOM-013-ENER-2013 compliance verification costs.
- Bulbs:Standard A19 and PAR configurations serve residential retrofits and relamping programs. Demand clusters in Infonavit-subsidized housing developments across Mexico City metropolitan zones where package minimums mandate LED adoption.
- Panels:Edge-lit and backlit flat-panel architectures deliver uniform illumination for open-plan commercial interiors. Guadalajara corporate office builds specify these for glare-controlled workstation environments, with efficacy ratings determining specification eligibility.
- Downlights:Recessed ceiling luminaires integrate thermal management for high-ambient installations. Hospitality projects in Monterrey and Cancun prioritize dimming compatibility and color consistency for guest experience.
- Fixtures:Complete luminaire systems span linear, high-bay, and decorative categories. Industrial maquiladora facilities in northern border states drive specification through CFE rebate program eligibility requirements.
Panels lead on scale; downlights lead on momentum.
Application:
Building code enforcement intensity varies by use case, creating regulatory gradients that reshape competitive positioning.
- Residential:Single-family and multi-family housing units account for volume leadership through Infonavit green mortgage incentives. Mortgage penetration growth in emerging urban peripheries accelerates fixture replacement in new construction.
- Commercial:Office, retail, and institutional facilities dominate value capture. Mexico City Class A developments pursue LEED certification that mandates networked controls and high-efficacy luminaires.
- Industrial:Manufacturing and warehouse environments require thermal resilience and vibration resistance. Silicon carbide substrate advances enable deployment in high-temperature maquiladora production floors previously unsuitable for solid-state lighting.
- Architectural:Monumental and aesthetic illumination projects command premium positioning. Historic center renovations in Guadalajara and Puebla integrate tunable white and dynamic color systems.
Commercial commands revenue concentration; industrial is climbing the fastest.
Technology:
Control protocol maturity separates premium positioning from commodity replacement cycles.
- Smart Lighting:Sensor-integrated and networked management platforms enable occupancy-based dimming and daylight harvesting. CFE rebate verification protocols favor these systems for documented savings calculations.
- Solar LED:Off-grid and hybrid photovoltaic luminaires serve rural electrification and backup power applications. Remote communities beyond CFE grid extension rely on these for public lighting infrastructure.
- OLED:Organic electroluminescent panels deliver thin-form-factor and surface-emitting characteristics. Limited deployment concentrates in high-end hospitality and museum applications where color rendering precision justifies cost premiums.
- Traditional LED:Non-connected solid-state replacements for legacy lamps and fixtures. Price-sensitive retrofit channels in residential and small commercial segments sustain volume despite margin compression.
Traditional LED leads on scale; smart lighting leads on margin expansion.
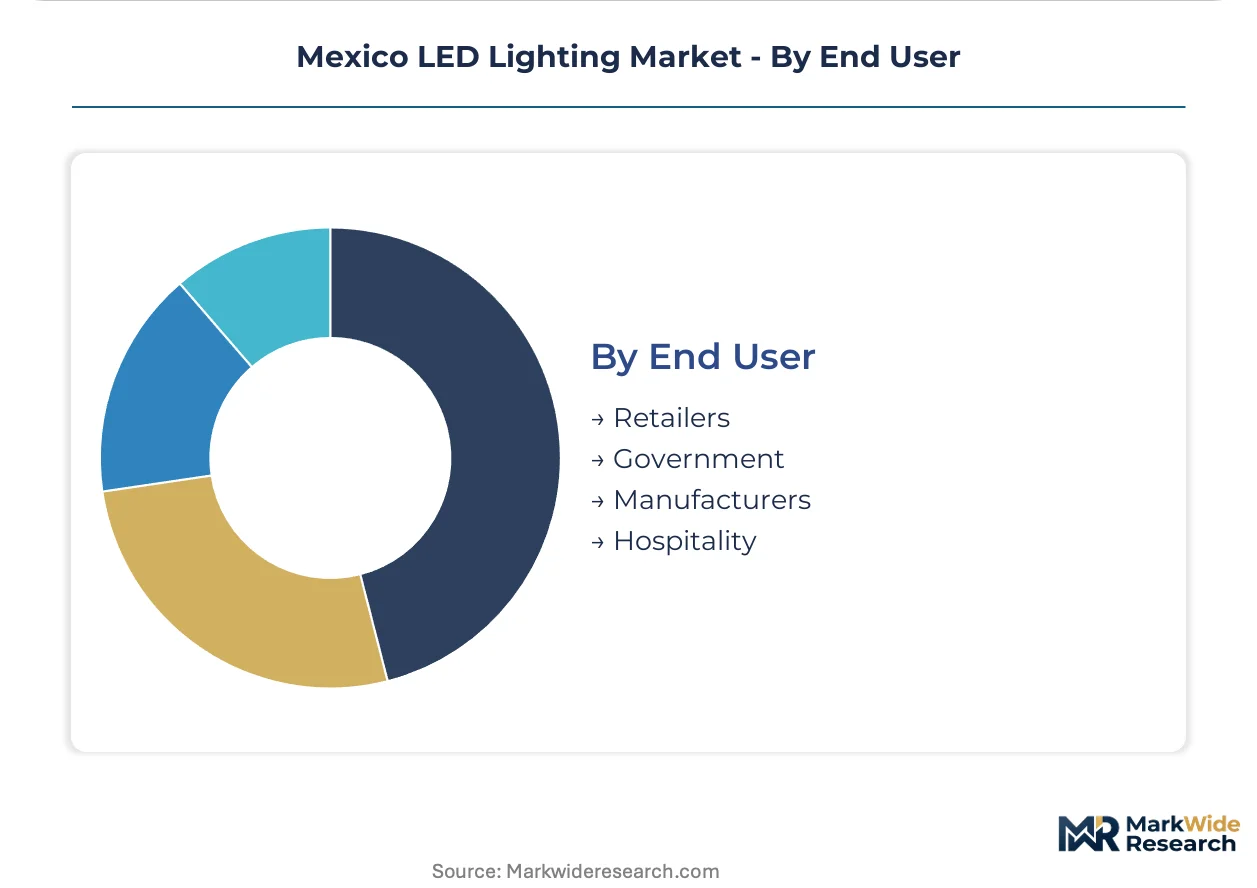
End User:
Procurement authority centralization determines specification influence and vendor relationship depth.
- Retailers:Home improvement chains and electrical distributors stock consumer-facing SKUs. Private label programs and rebate program participation drive assortment decisions.
- Government:Federal, state, and municipal procurement offices administer public lighting tenders. CONUEE labeling compliance and local content requirements filter supplier eligibility.
- Manufacturers:Industrial facility energy managers execute retrofit programs with measured savings guarantees. Performance contracting models transfer technology risk to energy service companies.
- Hospitality:Hotel operators and restaurant groups prioritize guest experience through ambiance control and maintenance reduction. Brand standards from international chains dictate specification consistency across properties.
Government leads on contract value; manufacturers lead on retrofit velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's LED lighting industry traces its modern scale to the 2013 federal energy reform era, when NOM-013-ENER-2013 established efficacy mandates that forced technology transition across the national built environment.
Mexico City Metro
Class A commercial developments and federal government procurement concentrate specification-grade demand. CONUEE labeling compliance filters import access, while Infonavit-subsidized housing accelerates residential fixture penetration in peripheral municipalities.
Nuevo León
Monterrey's industrial corridor drives high-bay and thermal-resilient luminaire demand through maquiladora LEED certification programs. CFE rebate verification protocols favor performance-contracting models that transfer technology risk to energy service companies.
Jalisco
Guadalajara's corporate office construction specifies glare-controlled panel architectures for open-plan interiors. Modular LED engine platforms gain traction among developers pursuing fixture chassis longevity across technology generations.
Northern Border States
Chihuahua, Tamaulipas, and Baja California manufacturing facilities deploy silicon carbide substrate luminaires in high-temperature production environments. Utility rebate economics and nearshoring facility expansion sustain retrofit velocity.
Bajío Region
Querétaro and Guanajuato automotive supplier parks generate specification demand for vibration-resistant industrial lighting. Federal green mortgage incentives in emerging urban peripheries extend residential market development.
Mexico LED Lighting Market Competitive Environment
Premium-margin players sit above commodity-margin players across specification depth and control protocol integration. The vendor base stratifies into three tiers: multinational lighting groups with distribution infrastructure, domestic assemblers with rapid customization capability, and import-dependent traders serving price-sensitive retrofit channels. Dominant competitive moves include strategic partnerships for smart lighting convergence and backward integration into driver electronics to reduce Asia-Pacific supply exposure.
Within the multinational tier, Signify N.V. and Cree Lighting occupy positions anchored by brand equity and substrate technology specialization respectively. Grupo Construlita Iluminación S.A. de C.V. exemplifies the domestic specification-grade archetype through localized manufacturing presence. LEDVANCE and Osram Licht AG represent European-origin groups competing on efficacy certification and rebate program eligibility.
| Leading Market Players |
|---|
| Acuity Brands Lighting, Inc. |
| Cree Lighting |
| Signify N.V. |
| Optima Energia |
| LEDVANCE |
| Osram Licht AG |
| Grupo Construlita Iluminación S.A. de C.V. |
| Illux |
| Samsung Electronics Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide substrate migration in high-bay industrial luminaires compresses thermal management costs while concentrating premium-tier production among substrate specialists in Asia-Pacific and North American facilities. This dual shift simultaneously elevates entry barriers for standard-tier assemblers and rewards backward-integrated players with captive semiconductor sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs fixture procurement, with NOM-013-ENER-2013 certification grade and CFE rebate eligibility serving as primary price differentiation drivers. Pricing pressure stems from import-dependent driver supply volatility that compresses assembler margins in the economy tier. Residential retrofit channels exhibit highest price sensitivity, while maquiladora energy managers under performance contracts demonstrate lowest sensitivity due to guaranteed savings structures.
Supply Chain Analysis
Electrical engineering talent scarcity in Guadalajara and Monterrey metropolitan zones constrains domestic assembly scaling despite proximity to U.S. border demand. China, South Korea, and Taiwan concentrate gallium nitride wafer and LED driver production, with Mexico drawing from these hubs for control electronics. Single-source vulnerability in silicon carbide substrates poses structural risk. Distribution runs through professional channel distributors in Mexico City metropolitan zones and electrical supply houses serving northern industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart lighting convergence enables margin expansion through sensor-integrated premium tiers, while modular LED engine standardization reduces fixture replacement costs across technology generations.
For Market Incumbents: To counter emerging domestic assemblers with rapid custom fixture turnaround, anchor specification-grade positioning through CONUEE pre-certification of connected lighting portfolios against draft NOM-030-ENER standby power requirements. Deepen backward integration into driver electronics to reduce Asia-Pacific supply exposure and defend margin position in CFE rebate-eligible industrial channels. For New Entrants and Emerging Players: Enter via architectural and hospitality segments in Guadalajara and Puebla historic center renovations, where tunable white and dynamic color systems command premium positioning with limited incumbent specification lock-in. Pursue white-label partnerships with domestic electrical distributors to bypass CONUEE verification bottlenecks and accelerate market access. For Investors and Strategic Acquirers: Valuations sit cheapest among import-dependent traders serving price-sensitive residential retrofit channels, while domestic specification-grade assemblers with localized manufacturing command scarcity premiums. Long-term viability favors targets with modular LED engine platforms and smart lighting firmware capabilities. Monitor proposed NOM-030-ENER cybersecurity interoperability finalization as inflection indicator for connected lighting market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver Electronics | Reduces Asia-Pacific supply volatility exposure for Mexican assemblers serving CFE rebate programs. |
| Smart Lighting Platform Integration | Enables occupancy-based dimming and daylight harvesting that satisfy CFE verified savings calculations. |
| CONUEE Pre-Certification Investment | Accelerates market access for imported luminaires ahead of NOM-030-ENER standby power mandate implementation. |
| Modular LED Engine Standardization | Extends fixture chassis life across technology generations for Guadalajara commercial real estate developers. |
| Performance-Contracting Model Expansion | Transfers technology risk to energy service companies serving maquiladora LEED certification drives in Nuevo León. |
Study Parameters
Multiple input streams — facility manager interviews, distributor channel assessments, regulatory filing analysis, and utility program documentation — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged commercial real estate developers, maquiladora energy directors, electrical contractors, and CONUEE certification specialists across Mexico City, Monterrey, and Guadalajara metropolitan zones. Secondary validation drew from CFE rebate program filings, Infonavit green housing incentive records, NOM-013-ENER compliance databases, and import customs data. Bottom-up fixture shipment estimates were cross-referenced against top-down construction spending allocations.
Historical efficacy mandate adoption curves were cross-referenced against panel input from specification-grade project architects and industrial procurement committees. Segmentation modeling spanned product type, application, technology, and end-user authority across the analysis window. CAGRs were derived from regression-adjusted replacement cycle compression rates and new construction fixture intensity ratios. Industry-specific forecast inputs included maquiladora LEED certification velocity and Infonavit mortgage penetration trajectories in emerging urban peripheries.
Inputs from CFE rebate program administrators and CONUEE labeling offices were available through the study window; gaps in real-time distributor inventory positioning introduce uncertainty bands around quarterly demand inflection timing. Forecasts reflect assumptions regarding NOM-030-ENER implementation sequencing and silicon carbide substrate cost curves. Practitioners should monitor northern border state nearshoring facility announcements and draft cybersecurity interoperability publication timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
China Outdoor LED Lighting Market
LED
LED Encapsulation Market
LED
Bluetooth LED Bulb Market
LED
Superluminescent Diodes Market
LED
LED High Bay Drivers Market
LED
Dual-Digit 7 Segment LED Displays Market
LED
LED Driver Market
LED
LED Services Market
LED
LED Street Light Drivers Market
LED
LED Display Market
LED
Linear LED Strip Fixture Market
LED
Vietnam LED Lighting Market
LED
Global Outdoor LED Lighting Market
LED
Gan Micro LED Market
LED
Global Chip on Board (COB) Light Emitting Diode Market
LED
Middle East and Africa Indoor LED Lighting Market