
 Hazardous Location LED Lighting Market | 2026-2036
Hazardous Location LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Hazardous Location LED Lighting Market Foresight
UL 844 certification for hazardous location electrical equipment is reorganizing competitive dynamics as smaller fixture makers struggle with recurring recertification costs. Eaton leverages extensive in-house testing laboratories to sustain rapid UL listing turnaround for custom flood light configurations. Dialight anchors its position through backward integration into LED driver design, reducing dependency on third-party semiconductor suppliers. Nemalux Inc. specializes in compact linear fixtures for confined-space chemical processing environments where clearance dimensions are severely constrained.
Hazardous location LED lighting denotes sealed luminaires engineered with explosion-proof housings, typically constructed from die-cast aluminum with tempered glass lenses, designed to contain internal arcs and operate at surface temperatures below auto-ignition thresholds of surrounding flammable gases or dusts. These fixtures serve critical safety functions in Zone 1 and Zone 2 classified areas where traditional lighting sources present ignition risks from hot surfaces or electrical sparks. Linear lights dominate volume shipments across petrochemical facilities due to standardized conduit mounting patterns and ease of relamping in long corridor configurations. Smart LED technology with integrated remote monitoring capabilities is expanding fastest as operators seek predictive maintenance data from vibration and thermal sensors embedded in high bay fixtures above catalytic cracking units.
The US Occupational Safety and Health Administration (OSHA) mandates adequate illumination levels in hazardous work areas under 29 CFR 1926.56, while the National Electrical Code (NEC) Article 500 series defines precise classification methodologies for gas, dust, and fiber hazards that directly determine fixture selection criteria. The EPA's Risk Management Plan (RMP) regulations further compel facilities to document lighting system integrity as part of process safety management audits, creating sustained replacement demand rather than discretionary upgrade cycles. Stakeholders must weigh the capital efficiency of wireless control retrofits against full fixture replacement timelines driven by evolving IECEx certification harmonization pressures.
Market Dynamics
UL 844 recertification cycles are compressing supplier margins and forcing consolidation among smaller fixture manufacturers who lack captive testing infrastructure.
Growth Catalysts
- NESHAP Illumination Mandates:The US EPA's tightened volatile organic compound handling zone requirements are forcing Gulf Coast refineries into accelerated fixture replacement schedules.
- Petrochemical Capacity Expansion:Texas, Louisiana, and Oklahoma are adding catalytic cracking and polyethylene units that require Zone 1 and Zone 2 certified lighting installations.
- Smart Sensor Integration:Embedded vibration and thermal monitoring in LED drivers is enabling predictive maintenance contracts that extend supplier revenue streams beyond hardware sales.
Market Restraints
- Aluminum Die-Cast Input Volatility:Explosion-proof housing fabrication depends on primary aluminum prices that fluctuate with Chinese smelter output and LME warehouse movements.
- Semiconductor Supply Concentration:LED driver ICs and power management chips source predominantly from Taiwanese and South Korean foundries, creating single-geography exposure.
- IECEx Harmonization Friction:Divergent certification timelines between North American UL 844 and European ATEX standards delay product launches and inflate compliance overhead.
Strategic Opportunities
- Permian Basin Infrastructure:West Texas and southeastern New Mexico wellpad electrification and gas processing buildouts remain underpenetrated for hazardous-rated LED retrofits.
- Wireless Control Retrofits:Bluetooth mesh and LoRa-enabled dimming systems allow operators to upgrade legacy fixtures without full conduit replacement, opening mid-cycle revenue.
- OSHA 29 CFR 1926.56 Enforcement:Heightened inspection activity in chemical processing corridors is converting discretionary lighting assessments into mandatory capital projects.
Industry Challenges
- Explosion-Proof Engineering Talent Scarcity:Fixture design requires specialized knowledge of flame-path geometry and pressure-purging mechanics that few mechanical engineering programs emphasize.
- Legacy Magnetic Ballast Integration:Retrofit projects in aging petrochemical facilities must reconcile LED driver electronics with existing HID wiring topologies and control voltages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hazardous Location LED Lighting Market |
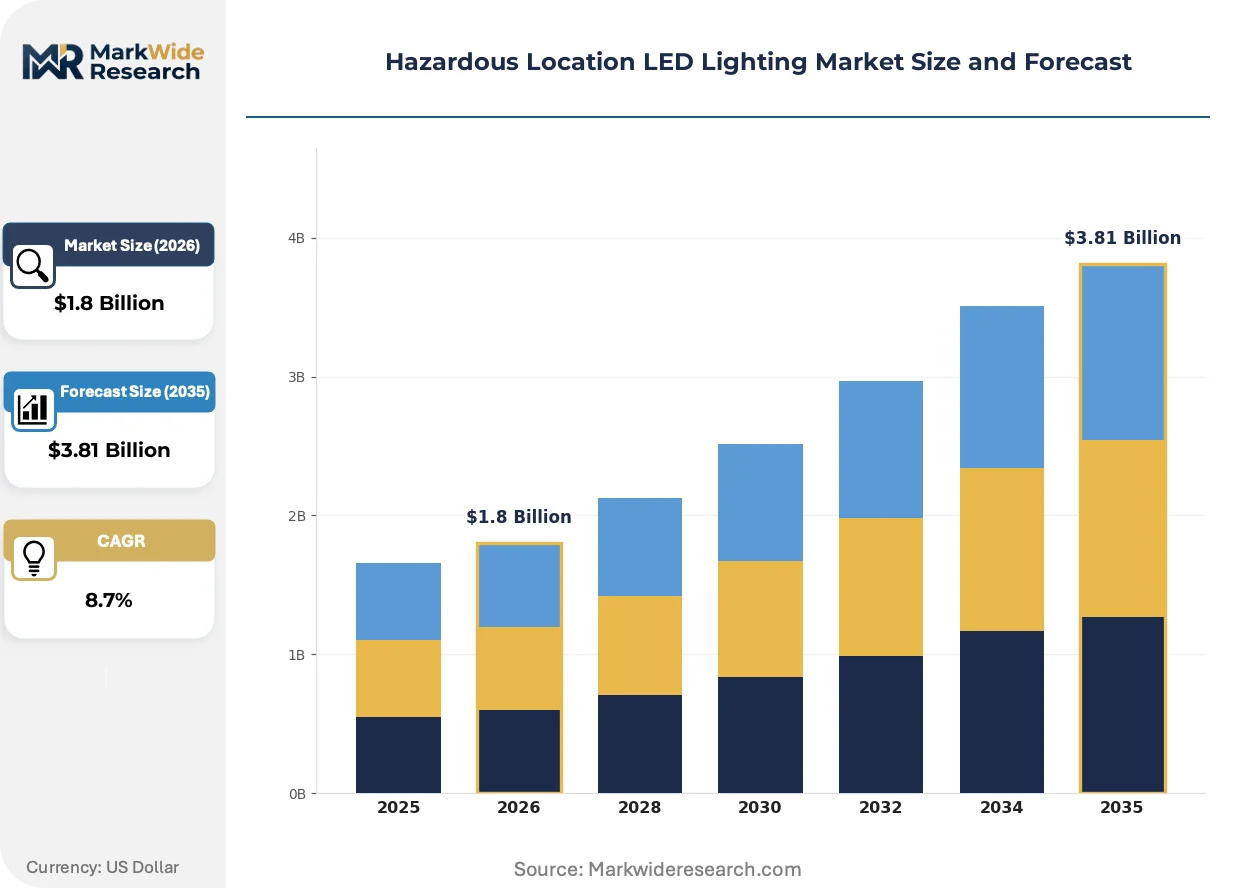
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flood Lights, Linear Lights, High Bay Lights, Atomized Lights Technology: Smart LED, Dimming Systems, Wireless Controls, Remote Monitoring End User: Oil & Gas, Chemical Plants, Mining, Pharmaceutical Installation: Ceiling Mounted, Wall Mounted, Portable, Embedded |
| Companies Covered | RAB Lighting, DCD Technologies ME FZCO, Eaton, WAROM Technology MENA FZCO, Luceco Middle East FZCO, Dialight, Nemalux Inc., Shenzhen CESP Co., Ltd, Hubbell Lighting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hazardous Location LED Lighting Market Shifts & Advancements
Digitalization of fixture intelligence is redistributing value from luminaire hardware toward data services, while certification complexity deepens the moat around established suppliers.
Modular LED engine architectures are fragmenting the traditional monolithic fixture market. Petrochemical operators now specify field-replaceable light modules and driver cartridges that reduce mean-time-to-repair in elevated flare stack applications. This modularity is fragmenting supplier relationships as end-users mix component vendors rather than sourcing complete fixtures from single manufacturers.
The EPA's Risk Management Plan audit documentation requirements are tightening process safety management protocols. Facilities must now maintain lighting system integrity records as part of five-year compliance cycles. Chemical processing corridors above catalytic crackers and alkylation units face the most intensive scrutiny, driving demand for fixtures with embedded operational data logging.
Specification authority is migrating from facility maintenance departments toward corporate engineering standards groups. Centralized procurement teams at integrated oil majors now mandate pre-approved vendor lists and standardized lumen packages across refinery networks. This concentration is most visible along the Texas Gulf Coast, where ExxonMobil, Chevron, and LyondellBasell have consolidated lighting specifications into master service agreements with penalty clauses for non-compliance.
Hazardous Location LED Lighting Market Segmentation
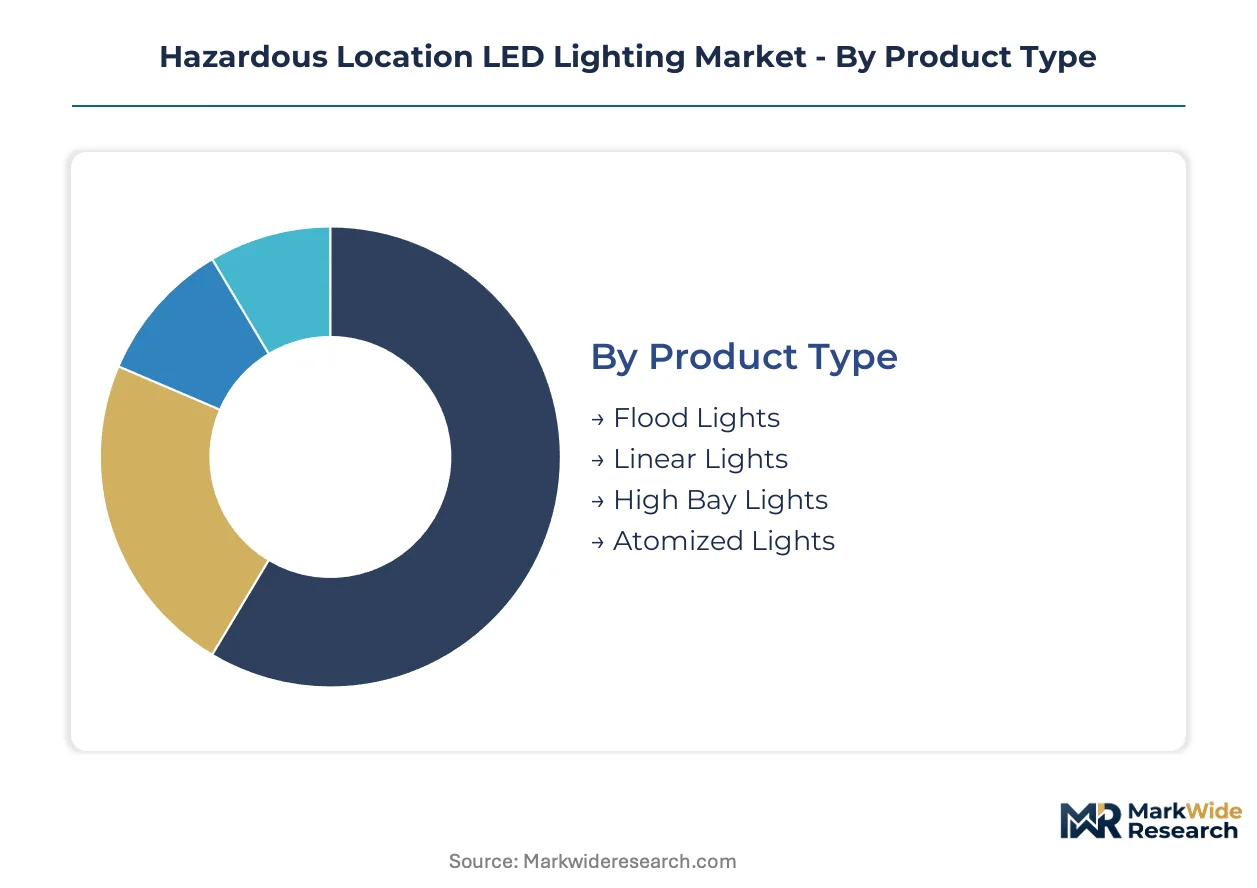
Fixture segmentation in hazardous location LED lighting determines certification pathways, housing materials, and service revenue potential. Product architecture choices cascade into installation complexity, maintenance protocols, and regulatory compliance documentation.
Product Type:
Margin pools concentrate in high-output flood configurations where explosion-proof engineering commands premium pricing over standardized linear formats.
- Flood Lights:Die-cast aluminum housings with tempered glass lenses deliver concentrated lumen packages for flare stacks and tank farm perimeters. Gulf Coast refineries specify these for NESHAP-compliant illumination of volatile organic compound handling zones where beam control reduces fixture count.
- Linear Lights:Standardized conduit mounting patterns dominate petrochemical corridor installations. Texas and Louisiana facilities favor these for catalytic cracking unit walkways where continuous rows simplify relamping and reduce inventory complexity.
- High Bay Lights:Elevated mounting above alkylation units requires vibration-resistant suspension systems.
- Atomized Lights:Compact form factors address confined-space chemical processing with severe clearance constraints.
Flood lights hold installed capacity. Linear lights are rotating up the share rankings.
Technology:
Revenue is shifting toward data-enabled systems that extend supplier relationships beyond hardware transactions into recurring service contracts.
- Smart LED:Embedded thermal and vibration sensors in LED drivers generate predictive maintenance telemetry. Operators above Permian Basin gas processing units leverage this data to schedule replacements before catalytic cracking corridor failures trigger OSHA 29 CFR 1926.56 violations.
- Dimming Systems:0-10V and DALI protocols allow lumen adjustment during non-operational periods.
- Wireless Controls:Bluetooth mesh and LoRa networks enable retrofit upgrades without conduit replacement.
- Remote Monitoring:Cloud-connected fixtures stream operational status to centralized maintenance dashboards.
Smart LED maintains technology leadership. Remote monitoring is climbing the fastest.
End User:
Application severity dictates housing specifications, with hydrocarbon processing demanding the most rigorous Zone 1 certifications.
- Oil & Gas:Offshore platforms and onshore wellpads require fixtures rated for hydrogen sulfide exposure and salt spray corrosion. Permian Basin electrification projects in West Texas and southeastern New Mexico drive replacement of legacy HID installations with UL 844-certified LED alternatives.
- Chemical Plants:Alkylation and polymerization units need fixtures operating below auto-ignition thresholds for flammable vapor concentrations.
- Mining:Underground coal operations specify dust-ignition-proof housings for methane-rich atmospheres.
- Pharmaceutical:Cleanroom-compatible sealed luminaires prevent particulate contamination in solvent handling areas.
Oil and gas commands specification authority. Chemical plants are gaining share fastest.
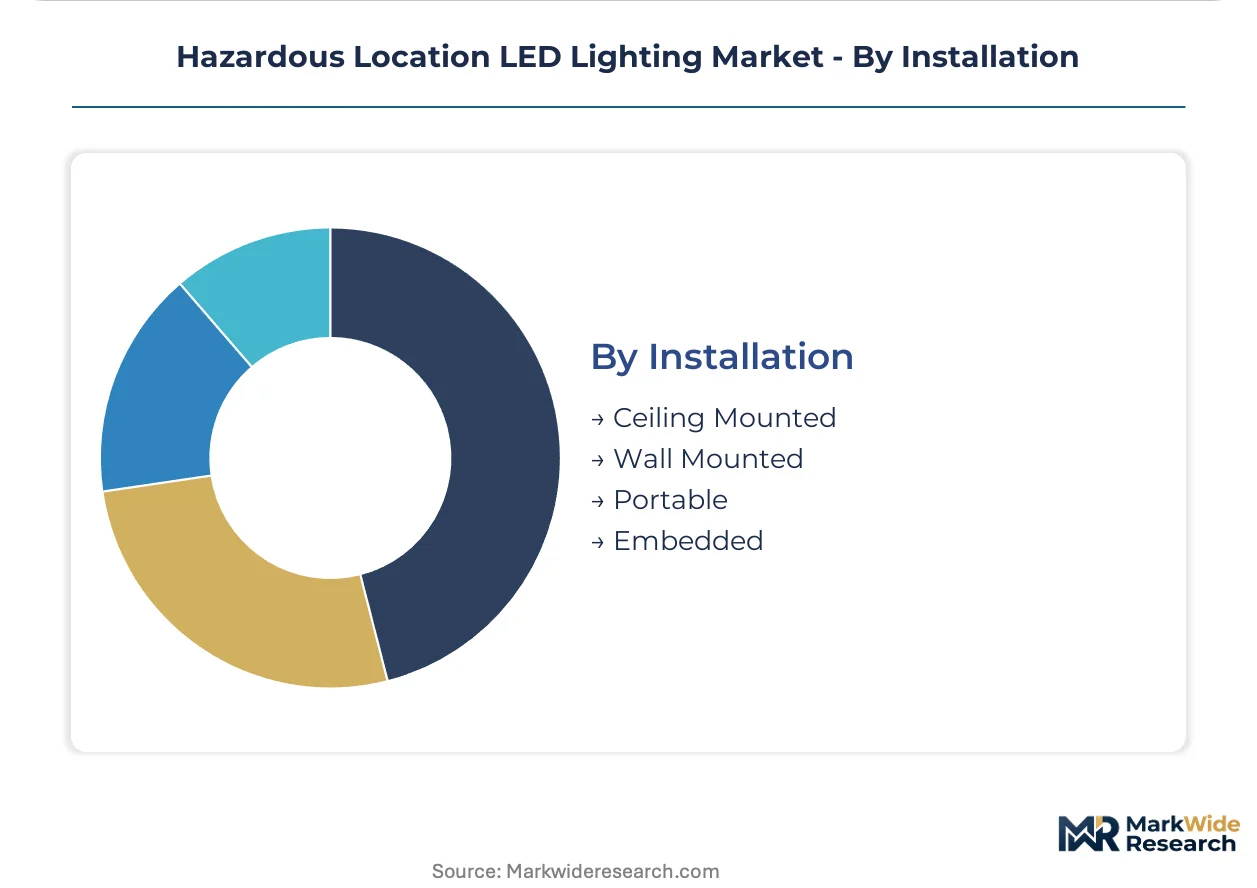
Installation:
Mounting method determines labor intensity and retrofit feasibility, with ceiling configurations dominating new construction.
- Ceiling Mounted:Pendant and chain-suspended fixtures predominate in high-bay processing halls. Oklahoma petrochemical expansions specify these for polyethylene unit warehouses where standardized hanging patterns accelerate construction schedules.
- Wall Mounted:Bracket installations serve perimeter security and emergency egress lighting.
- Portable:Carts and tripod-mounted fixtures support maintenance turnaround activities.
- Embedded:Recessed housings integrate into cleanroom ceilings and controlled environment panels.
Ceiling mounted holds volume leadership. Portable is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA's National Emission Standards for Hazardous Air Pollutants is accelerating fixture replacement cycles across petrochemical corridors. Gulf Coast refineries face tightened illumination mandates in volatile organic compound handling zones. Texas, Louisiana, and Oklahoma concentrate capacity expansion activity.
United States
Gulf Coast petrochemical buildouts in Texas and Louisiana drive Zone 1 and Zone 2 certified lighting demand. OSHA's 29 CFR 1926.56 mandates adequate illumination in hazardous work areas, compelling facilities into documented compliance cycles. The Permian Basin in West Texas and southeastern New Mexico sees wellpad electrification and gas processing buildouts requiring UL 844-certified retrofits.
Canada
Alberta's oil sands operations and Sarnia's chemical valley require explosion-proof fixtures for hydrogen sulfide and bitumen processing environments. Health Canada aligns hazardous product regulations with EPA NESHAP frameworks, creating cross-border certification efficiency. Ontario's petrochemical corridor along the St. Clair River maintains steady replacement demand from aging infrastructure.
Germany
Ludwigshafen's BASF complex and the Ruhr industrial basin anchor European demand for ATEX-certified hazardous lighting. The EU's Industrial Emissions Directive tightens monitoring requirements in volatile chemical handling zones. Bavaria's specialty chemical producers specify IECEx-harmonized fixtures to streamline export compliance into North American markets.
Saudi Arabia
Jubail Industrial City and Yanbu petrochemical complexes on the Red Coast expand polyethylene and catalytic cracking capacity. The Saudi Standards, Metrology and Quality Organization mandates SASO certification for electrical equipment in hazardous zones. Eastern Province gas processing facilities replace legacy HID installations with LED alternatives to reduce maintenance cycles in extreme heat conditions.
China
Ningbo and Shanghai petrochemical zones drive domestic fixture demand for ethylene and refinery expansions. The Ministry of Ecology and Environment enforces stricter volatile organic compound containment standards in chemical processing corridors. Shandong Province's independent refineries accelerate LED retrofits under provincial environmental inspection campaigns.
Hazardous Location LED Lighting Market Competitive Landscape
Player mix skews toward diversified electrical conglomerates with captive testing infrastructure. UL 844 recertification cycles compress margins and force consolidation among smaller fixture manufacturers. Two strategic archetypes dominate: vertically integrated lighting specialists with in-house LED driver design, and diversified industrial electrical suppliers leveraging existing hazardous location equipment portfolios. Competitive moves center on certification harmonization investments and predictive maintenance service contracts that extend revenue beyond hardware sales.
Within the diversified electrical tier, Eaton occupies a position exemplifying rapid UL listing turnaround through extensive laboratory infrastructure. Dialight represents backward integration into LED driver design, reducing semiconductor supply dependency. Among compact fixture specialists, Nemalux Inc. anchors the confined-space chemical processing segment where clearance constraints demand specialized engineering.
| Leading Market Players |
|---|
| RAB Lighting |
| DCD Technologies ME FZCO |
| Eaton |
| WAROM Technology MENA FZCO |
| Luceco Middle East FZCO |
| Dialight |
| Nemalux Inc. |
| Shenzhen CESP Co., Ltd |
| Hubbell Lighting |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day LED driver lead times from Taiwanese foundries concentrate pricing power with vertically integrated fixture manufacturers who buffer inventory against semiconductor allocation volatility. This inventory positioning advantage allows captive-testing suppliers to command certification-premium spreads while smaller competitors absorb spot-market aluminum die-cast housing cost swings.
Pricing Analysis
Certification level creates the primary spread between UL 844-listed fixtures and uncertified alternatives. Three-tier pricing structure across premium Zone 1 explosion-proof, standard Zone 2 rated, and economy general-purpose tiers reflects testing overhead recovery. Cost compression in mid-tier linear fixtures intensifies as Gulf Coast petrochemical buyers consolidate procurement into master service agreements. Refinery maintenance departments show highest price sensitivity; corporate engineering standards groups prioritize certification compliance over unit cost.
Supply Chain Analysis
Strategic stockpiling of aluminum die-cast billets and LED driver ICs distinguishes suppliers with captive testing infrastructure from just-in-time competitors exposed to LME price volatility. Fixture assembly concentrates in China, Mexico, and the United States; semiconductor sourcing draws from Taiwan and South Korea. Single-source vulnerability in Taiwanese foundry capacity for power management chips threatens production continuity. Distribution runs through electrical wholesale distributors serving industrial MRO channels and direct OEM relationships with integrated oil majors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hazardous location LED lighting market sits in early-cycle expansion as EPA NESHAP enforcement converts discretionary lighting assessments into mandatory capital projects across Gulf Coast petrochemical corridors.
For Market Incumbents: Compound certification infrastructure advantages by accelerating UL 844 listing turnaround through expanded in-house testing laboratories. Absorb smaller fixture manufacturers facing recurring recertification cost pressures to consolidate specification authority with integrated oil majors. Defend against modular LED engine fragmentation by locking in master service agreements with penalty clauses for non-compliance. For New Entrants and Emerging Players: Predictive maintenance service gaps where incumbents under-serve present white-space entry points. Target Permian Basin wellpad electrification projects in West Texas and southeastern New Mexico where UL 844-certified retrofit penetration remains incomplete. Lead with Bluetooth mesh wireless control retrofits that bypass full conduit replacement barriers in aging facilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial electrical conglomerates seeking to divest non-core lighting portfolios. Long-term viability hinges on certification moat sustainability and smart sensor recurring revenue attachment rates. Watch OSHA 29 CFR 1926.56 enforcement intensity as the inflection signal converting maintenance deferrals into capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| UL 844 Certification Acceleration | Rapid listing turnaround captures NESHAP-driven replacement cycles before competitors complete testing protocols. |
| Smart Sensor Integration | Embedded thermal and vibration monitoring extends supplier relationships into predictive maintenance service contracts. |
| Wireless Control Retrofit Deployment | Bluetooth mesh and LoRa networks unlock mid-cycle revenue without full conduit replacement in aging petrochemical facilities. |
| Backward Integration into LED Driver Design | In-house semiconductor specification reduces dependency on Taiwanese foundry allocation and compresses bill-of-materials cost. |
| Permian Basin Geographic Expansion | West Texas and southeastern New Mexico wellpad electrification remains underpenetrated for hazardous-rated LED retrofits. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, maintenance directors at Gulf Coast refineries, electrical procurement leads, UL certification specialists, and distribution channel managers. Secondary validation drew from EPA NESHAP regulatory filings, OSHA enforcement databases, SEC 10-K disclosures from listed electrical equipment manufacturers, and petrochemical capacity expansion announcements. Bottom-up fixture shipment estimates triangulated against top-down petrochemical capital expenditure patterns.
Across the analysis window, volume and value outputs reflect segmentation modeling by fixture type, certification zone rating, technology tier, end-use application severity, and installation configuration. CAGRs were derived from regression analysis of historical replacement cycles against regulatory mandate timelines. Forecast inputs incorporated aluminum LME price trajectories, semiconductor foundry capacity utilization, and EPA Risk Management Plan audit frequency assumptions.
Forecasts assume regulatory continuity in EPA NESHAP and OSHA 29 CFR 1926.56 enforcement regimes; material policy shifts would require re-modeling. Aluminum price volatility, Taiwanese foundry supply disruption, or IECEx-UL harmonization friction represent specific revision triggers. Revision becomes warranted when UL 844 recertification cycle compression accelerates beyond current margin absorption capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Smart Street Lighting Systems Market
Lighting
Connected (Smart) Street Lighting Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
UAE Smart Lighting Market
Lighting
Germany Indoor LED Lighting Market
Lighting
Dimmer and Color Tunable Market
Lighting
Bacteriological Light Market
Lighting
Programmable Stage Lighting Market
Lighting
Smart Lamp Market
Lighting
Lighting Management System Market
Lighting
Solar Lights Market
Lighting
Industrial Lighting Market
Lighting
GCC Smart Lighting Market
Lighting
EV Lighting Market
Lighting
Cleanroom Lighting Market
Lighting
Flexible Lighting Foils Market