
 Directional Luminaire Market | 2026-2036
Directional Luminaire Market Size, Share, and Industry Trends Forecast 2026-2036
Directional Luminaire Market Outlook
Aluminum die-cast housings replacing stamped steel enclosures is recalibrating thermal management costs and fixture weight profiles across the directional luminaire category. Signify Holding leverages captive LED module production to sustain margin structures in premium downlight segments. Acuity Brands anchors its North American position through deep specification relationships with electrical contractors and lighting designers. ams OSRAM competes at the component tier, supplying high-efficacy COB arrays that dictate lumen-per-watt thresholds for downstream fixture assemblers.
A directional luminaire is a lighting fixture engineered to emit illumination within a defined beam angle, typically incorporating reflectors, lenses, or adjustable gimbals to control light distribution for accent, task, or display purposes; LED variants now dominate new specifications with system efficacies exceeding 130 lumens per watt and correlated color temperatures tunable from 2700K to 5000K. Downlights and track lights command the largest revenue pools in commercial retrofit channels where existing ceiling infrastructure limits installation flexibility. LED technology is displacing fluorescent and halogen alternatives fastest in retail environments where color rendering indices above 90 drive merchandise presentation standards.
The EU Ecodesign Directive and REACH frameworks constrain hazardous substance content and mandate minimum luminous efficacy thresholds for luminaires sold across member states, while the US Department of Energy enforces efficacy standards through ENERGY STAR certification and state-level building codes. China's GB standards and MIIT efficiency labeling requirements shape export competitiveness for manufacturers serving domestic and overseas markets. Stakeholders must monitor regulatory divergence between efficiency mandates and circular economy material recovery rules when configuring product platforms for multi-region deployment.
Market Dynamics
The EU Ecodesign Directive's phase-out of halogen and fluorescent technologies is compressing specification timelines and forcing rapid LED retrofit decisions across commercial real estate portfolios in Germany, the United States, and China.
Growth Catalysts
- Building energy codes:Germany's EnEV standards and California's Title 24 mandate minimum efficacy thresholds that accelerate LED specification in new construction and renovation projects.
- Smart lighting infrastructure subsidies:China's MIIT efficiency labeling program and utility rebate structures in the United States reduce upfront capital barriers for networked luminaire deployments.
- Retail color rendering demands:Merchandise presentation standards above CRI 90 in luxury and fashion retail pull premium COB LED configurations into high-traffic commercial environments.
Market Restraints
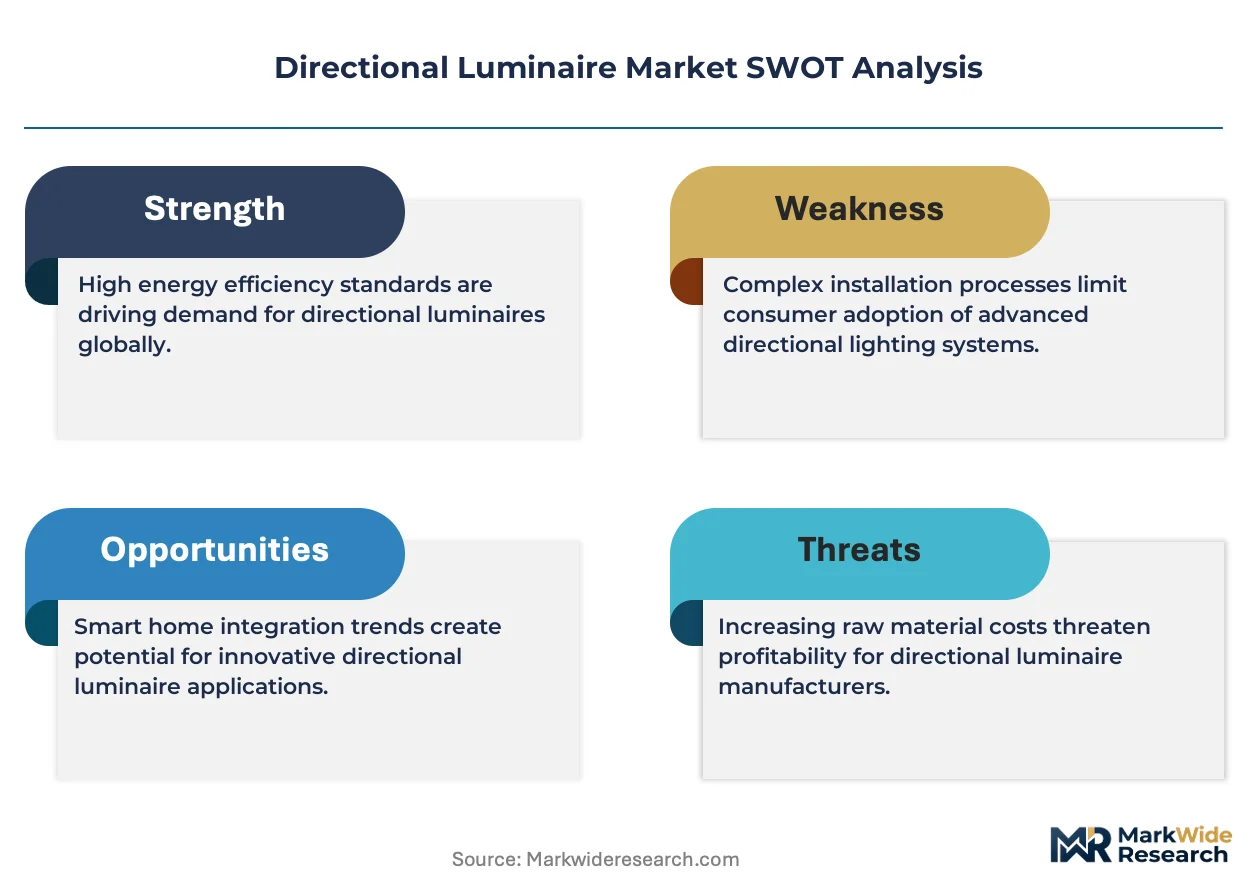
- Aluminum die-cast housing costs:Thermal management migration from stamped steel to aluminum die-cast enclosures elevates bill-of-materials pressure and compresses margin structures for mid-tier fixture assemblers.
- COB array supply concentration:High-efficacy chip-on-board LED sourcing clusters among a limited tier of component specialists, creating vulnerability for downstream fixture manufacturers without captive module production.
- REACH substance constraints:The European Chemicals Agency's hazardous substance restrictions complicate phosphor and encapsulant selection, extending qualification timelines for products targeting EU member states.
Strategic Opportunities
- Human-centric lighting convergence:Tunable white and circadian rhythm protocols are absorbing demand from wellness-focused workplace and healthcare segments seeking dynamic CCT adjustment from 2700K to 5000K.
- LiDAR and sensor integration:Occupancy detection and daylight harvesting algorithms embedded at the luminaire level open specification channels in intelligent building platforms.
- Service-based revenue models:Lighting-as-a-service contracts decouple capital expenditure from energy performance, aligning vendor incentives with sustained efficacy outcomes in commercial retrofit channels.
Industry Challenges
- Optical engineering talent scarcity:Precision reflector design and gimbal mechanism expertise concentrates among aging specialist workforces, constraining product development velocity for adjustable beam fixtures.
- Multi-region certification complexity:Divergent testing protocols between ENERGY STAR, CE marking, and China's GB standards fragment product platform strategies and inflate compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Directional Luminaire Market |
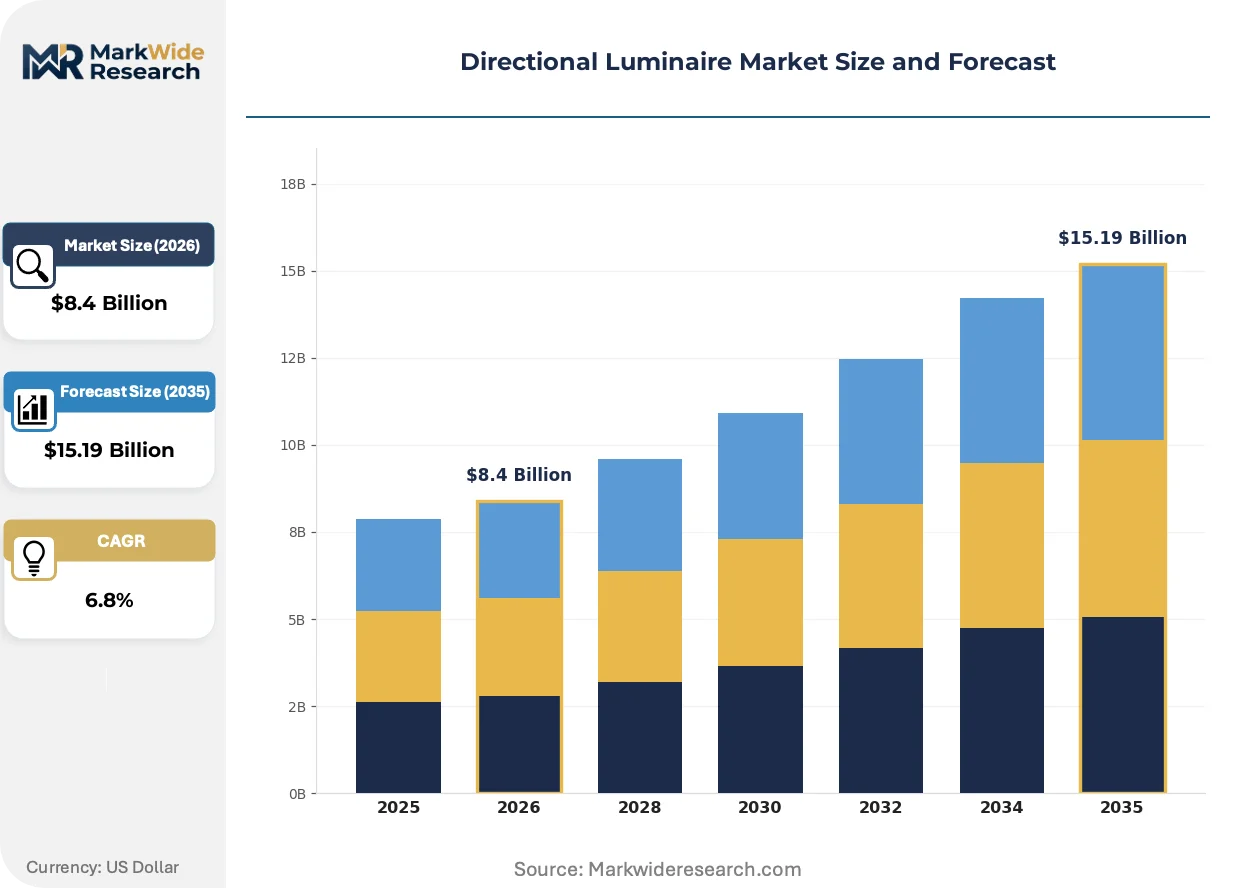
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Downlights, Spotlights, Wall Washers, Track Lights Technology: LED, Fluorescent, Halogen, Incandescent Application: Commercial Spaces, Residential Areas, Outdoor Lighting, Retail Environments Installation: Surface Mounted, Recessed, Pendant, Wall Mounted |
| Companies Covered | Signify Holding, Acuity Brands, ams OSRAM, Cree Lighting, Hubbell, Zumtobel Group, Dialight, Eaton, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Directional Luminaire Market Strategic Shifts
Three forces are actively reshaping directional luminaire development: thermal material substitution, regulatory efficacy compression, and procurement model unbundling. Each trend is reconfiguring competitive advantage around component integration depth rather than fixture assembly scale.
Laser-etched micro-reflector surfaces are absorbing specification share from traditional spun aluminum and Miro silver reflectors in precision downlight segments. Museum and gallery lighting designers specify these surfaces for beam angle control below 15 degrees. The technology is absorbing margin from conventional optical component suppliers while enabling fixture brands to differentiate on photometric performance.
REACH framework updates and RoHS substance restrictions are tightening phosphor composition and solder alloy specifications for luminaires sold across European Union member states. Manufacturers serving Germany, France, and the Netherlands must requalify supply chains for cadmium-free quantum dot and lead-free die-attach materials. The regulatory pressure is compressing qualification timelines and elevating testing costs for multi-region product platforms.
Electrical contractors and lighting designers are consolidating specification influence through direct digital procurement channels, disintermediating traditional wholesale distribution for standardized LED downlight SKUs. Large commercial retrofit programs in the United States and China now route volume purchases through vendor-managed inventory agreements linked to project milestone schedules. The channel shift is compressing distributor margin pools while rewarding fixture brands with specification-grade digital configurators and rapid-sample logistics capabilities.
Directional Luminaire Market Segmentation
Directional luminaire procurement decisions split across specification-grade architectural channels and volume-driven retrofit programs. Technology migration and mounting infrastructure constraints create divergent margin profiles across segment boundaries.
Product Type:
Beam control precision and ceiling infrastructure compatibility drive specification priorities across fixture architectures.
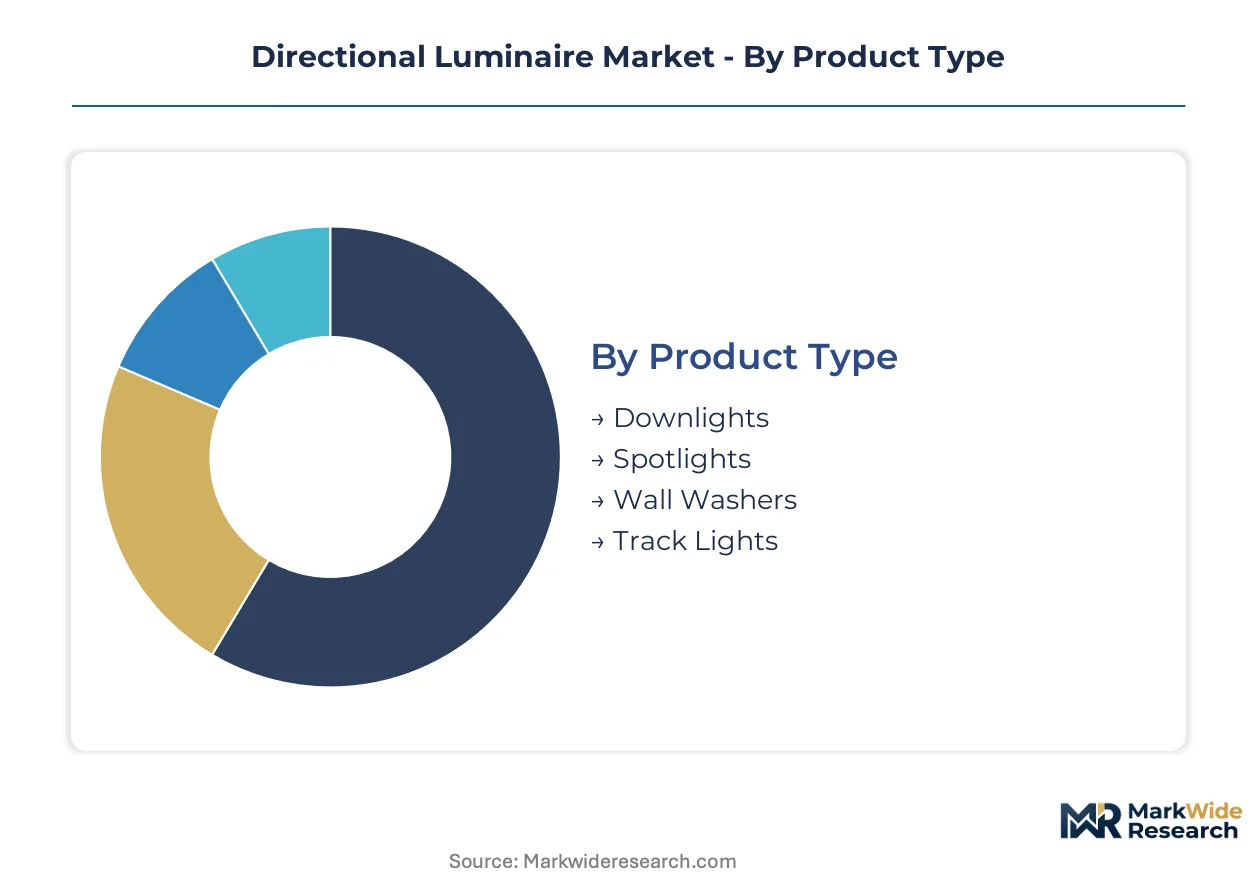
- Downlights:Fixed or adjustable ceiling-recessed fixtures with integrated reflectors deliver 15-to-60-degree beam angles for general illumination. Commercial real estate retrofit programs in Germany and the United States concentrate volume here, constrained by existing drywall and suspended ceiling infrastructure.
- Track Lights:Linear electrified rail systems with adjustable gimbal-mounted heads enable flexible accent positioning. Retail environments in China pull premium three-circuit configurations for merchandise presentation flexibility.
- Spotlights:Narrow-beam directional fixtures for accent and display applications.
- Wall Washers:Asymmetric optic luminaires designed for vertical surface illumination.
Mature deployment sits with Downlights. Newer deployment is concentrated in Wall Washers.
Technology:
Light source efficacy and regulatory phase-out timelines determine platform investment horizons.
- LED:Solid-state modules exceeding 130 lumens per watt with tunable CCT from 2700K to 5000K. China's MIIT efficiency labeling and California's Title 24 compress specification timelines toward LED-only portfolios.
- Halogen:Tungsten-halogen sources with CRI 100 but efficacy below 25 lumens per watt. The EU Ecodesign Directive's phase-out provisions eliminate new fixture development for member states.
- Fluorescent:Compact and linear sources facing parallel regulatory displacement.
- Incandescent:Legacy filament sources restricted to specialty vintage-aesthetic segments.
Volume concentration rests with LED. Regulatory compression is accelerating fastest for Halogen.
Application:
End-use environment dictates photometric performance thresholds and durability specifications.
- Commercial Spaces:Office, hospitality, and institutional environments requiring networked controls and daylight harvesting integration.
- Retail Environments:Merchandise presentation applications demanding CRI above 90 and tight beam angle consistency.
- Residential Areas:Decorative and task lighting with aesthetic finish priorities.
- Outdoor Lighting:Weather-rated directional fixtures for facade and landscape accent.
Specification complexity peaks in Commercial Spaces. Margin expansion is climbing the fastest in Retail Environments.
Installation:
Mounting method constrains thermal management geometry and electrical access requirements.
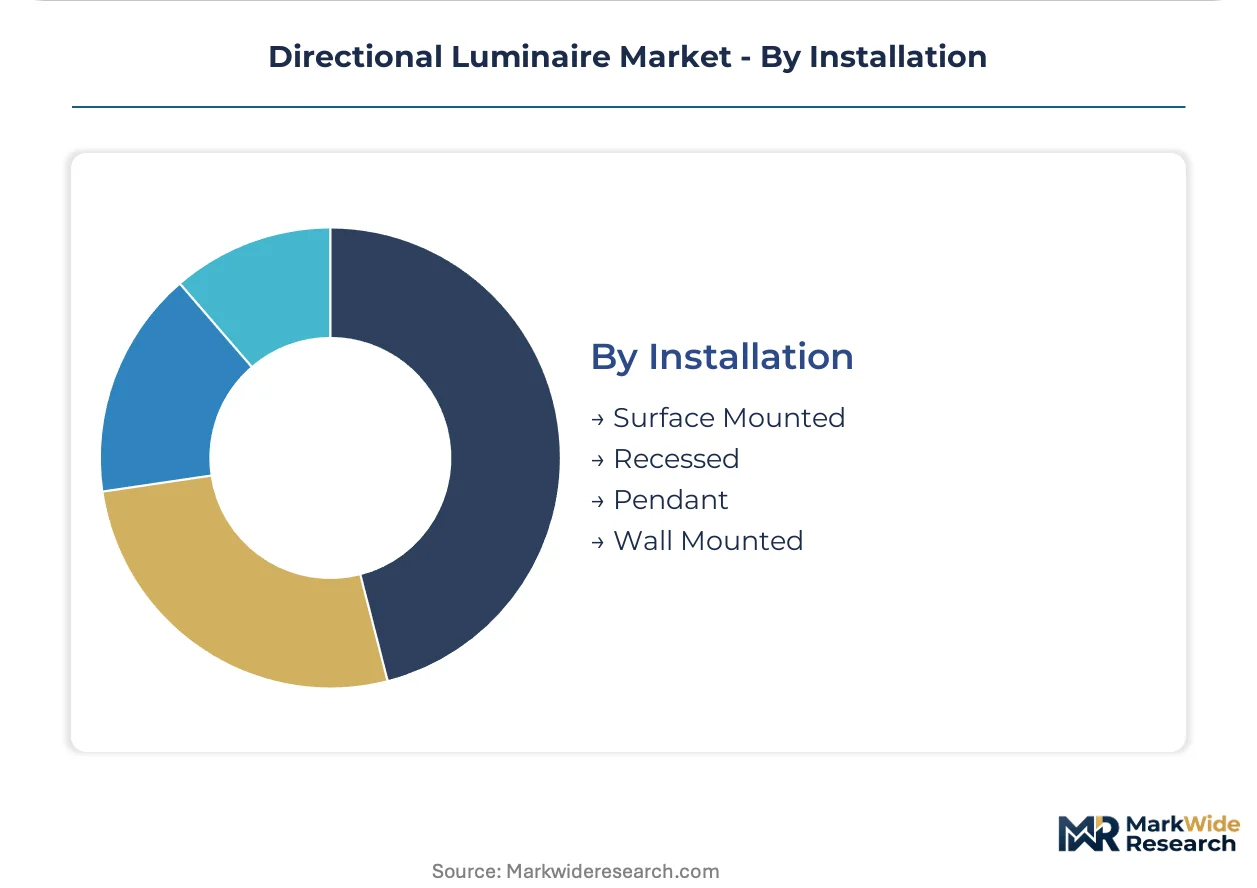
- Recessed:Ceiling-integrated housings requiring plenum-rated thermal management and junction-box proximity.
- Surface Mounted:Direct-ceiling attachment for concrete or structural slab environments without plenum access.
- Pendant:Suspended cable or rod mounting for high-ceiling atrium and circulation spaces.
- Wall Mounted:Vertical surface attachment for asymmetric wash and grazing applications.
Retrofit volume aggregates in Surface Mounted. New construction specification is tilting toward Recessed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial real estate retrofit programs concentrate demand in Germany, the United States, and China, where building energy codes and utility rebate structures accelerate LED specification timelines.
Germany
Office and hospitality portfolios drive specification volume for downlight and track light retrofits. The EU Ecodesign Directive's halogen phase-out compresses replacement cycles across commercial installations. Industrial clusters in Bavaria and North Rhine-Westphalia host fixture assemblers integrating aluminum die-cast thermal management for premium architectural channels.
United States
Electrical contractors consolidate influence through direct digital procurement for large-scale retrofit programs. California's Title 24 mandates minimum efficacy thresholds that accelerate LED-only portfolios in new construction and renovation. Specification-grade activity clusters in the Northeast Corridor and Pacific Northwest where lighting designers prioritize tunable white configurations for workplace wellness applications.
China
MIIT efficiency labeling requirements and utility rebate structures reduce upfront capital barriers for networked luminaire deployments in commercial and retail environments. Manufacturing concentration in the Yangtze River Delta and Pearl River Delta supports both domestic consumption and export-oriented fixture assembly for global brands.
United Kingdom
Commercial building renovation programs pull specification-grade downlights into heritage office conversions and hospitality refurbishments. REACH framework updates constrain phosphor and encapsulant selection for luminaires targeting EU-adjacent compliance. London and Southeast England concentrate specification influence among lighting designers and architectural practices.
Japan
Retail environments in Tokyo and Osaka demand premium COB LED configurations with CRI above 90 for luxury merchandise presentation. METI efficiency standards shape domestic procurement criteria while supporting export competitiveness for component specialists. Kanto and Kansai regions anchor both end-use demand and precision optical engineering capabilities.
Directional Luminaire Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated lighting groups commanding premium architectural channels and OEM assemblers serving volume retrofit programs. The vendor base organizes around three strategic archetypes: captive LED module producers, specification-grade fixture brands, and component-tier optical specialists. Competitive dynamics center on backward integration into LED sourcing and rapid-sample logistics capabilities for contractor-direct procurement.
Among integrated lighting groups, Signify Holding and Acuity Brands exemplify the specification-grade archetype with deep electrical contractor relationships, while ams OSRAM occupies a position at the component tier supplying high-efficacy COB arrays. These three entities represent divergent margin structures across the value chain.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands |
| ams OSRAM |
| Cree Lighting |
| Hubbell |
| Zumtobel Group |
| Dialight |
| Eaton |
| Panasonic |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between ENERGY STAR-qualified architectural fixtures and unlabeled commodity imports manifests in both pricing power and supply chain sourcing strategies. Premium tier manufacturers anchor pricing through captive LED module production and specification-grade digital configurators, while mid-tier assemblers absorb aluminum die-cast cost inflation without equivalent pricing leverage.
Pricing Analysis
Volume-vs-margin split separates high-volume retrofit programs from specification-grade architectural channels. Three-tier pricing structure across premium, standard, and economy levels tracks certification tier and thermal management material quality. Pricing pressure stems from aluminum die-cast housing cost inflation compressing mid-tier fixture assembler margins. Electrical contractors driving large-scale retrofit programs exhibit highest price sensitivity, while museum and gallery lighting designers demonstrate lowest sensitivity given photometric performance priorities.
Supply Chain Analysis
Single-source vulnerability sits with high-efficacy COB array suppliers concentrated among limited component specialists. Manufacturing gravity centers on China, Germany, and the United States for fixture assembly, with Taiwan and South Korea anchoring LED chip fabrication. Raw material dependencies span aluminum die-cast enclosures, phosphor compositions, and lead-free solder alloys constrained by REACH substance restrictions. Tariff exposure on aluminum and electronic components presents structural risk. Distribution runs through direct digital procurement channels consolidating electrical contractor influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as aluminum die-cast cost inflation and REACH compliance overhead force weaker mid-tier assemblers toward exit or acquisition.
For Market Incumbents: Anticipate margin compression from COB array supply concentration by securing captive LED module production or long-term supply agreements with ams OSRAM-tier suppliers. Reinforce specification-grade positioning through rapid-sample logistics capabilities and tunable white R&D investment targeting human-centric lighting protocols.
For New Entrants and Emerging Players: Electrical contractors represent the most accessible channel partner type for wedge positioning against established wholesale distribution. Target surface-mounted retrofit volume in commercial real estate portfolios where infrastructure constraints limit recessed fixture competition. Penetrate through vendor-managed inventory agreements linked to project milestone schedules.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier fixture assemblers possessing aluminum die-cast thermal management capabilities given consolidation catalyst from REACH compliance cost escalation. Long-term viability favors entities with backward integration into LED sourcing or specification-grade digital procurement platforms. Monitor MIIT efficiency labeling enforcement in China as inflection indicator for export competitiveness shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive LED Module Production | Backward integration into COB arrays insulates margin structures from component supply concentration. |
| Specification-Grade Digital Configurator | Rapid-sample logistics capabilities align with electrical contractor direct procurement consolidation. |
| Human-Centric Lighting R&D | Tunable white protocols from 2700K to 5000K capture wellness-focused workplace and healthcare demand. |
| Aluminum Die-Cast Thermal Management | Precision thermal geometry differentiates premium architectural channels from stamped steel commodity tiers. |
| REACH Compliance Platform | Cadmium-free quantum dot and lead-free die-attach qualification secures EU market access against regulatory compression. |
Study Parameters
Independent corroboration across lighting designer interviews, electrical contractor procurement data, and component supplier disclosures underwrites the qualitative findings. Primary fieldwork engaged specification-grade fixture brand executives, aluminum die-cast housing manufacturers, and MIIT efficiency labeling officials. Secondary validation drew from ENERGY STAR certification databases, EU Ecodesign Directive implementation reports, and customs trade data for LED module flows. Bottom-up channel volume estimates triangulated against top-down building energy code adoption timelines.
Comparable-period anchoring linked projection horizons to historical efficacy standard phase-out cycles and retrofit program completion patterns. Segmentation modeling spanned product architecture, light source technology, end-use environment, and mounting method across the analysis window. CAGRs derived from installed base replacement curves and regulatory mandate enforcement schedules. Forecast inputs incorporated aluminum commodity price trajectories and REACH substance restriction update timelines.
Caveats apply where MIIT subsidy modifications or EU Ecodesign Directive acceleration could materially shift the outlook. Forecasts assume sustained efficacy standard enforcement without regulatory rollback. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
OLED Lightening Panels Market
Lighting
Lighting Fixture Market
Lighting
Industrial LiDAR Integrated Lighting Market
Lighting
Graphene Lighting Market
Lighting
North America Smart Lighting Market
Lighting
Lighting Product Market
Lighting
Solar Lights Market
Lighting
Global Machine Vision Lighting Market
Lighting
Circadian Lighting Market
Lighting
Flexible Lighting Foils Market
Lighting
Lighting As a Service (Laas) Market
Lighting
Germany Indoor LED Lighting Market
Lighting
UAE Smart Lighting Market
Lighting
Smart Lights Market
Lighting
Residential Lighting Fixtures Market
Lighting
Asia-Pacific Lighting Control Market