
 Global Commercial Lighting Market | 2026-2036
Global Commercial Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Lighting Market Foresight
Aftermarket service revenue is reshaping margin capture across the commercial lighting value chain, shifting profitability from one-time fixture sales toward recurring software subscriptions and remote diagnostics. Signify Holding leverages its Interact platform to anchor long-term client relationships through cloud-based energy management. Acuity Brands competes by extending its building-automation software stack beyond illumination into integrated sensor networks. ams-OSRAM specializes in high-performance LED components that dominate the premium tier of human-centric lighting specifications.
Commercial lighting encompasses engineered luminaire systems, control electronics, and optical components designed to deliver specified illuminance levels, color rendering indices, and power densities across non-residential built environments. These systems typically incorporate solid-state emitters operating at correlated color temperatures between 2700 K and 6500 K, with efficacy targets now routinely exceeding 130 lumens per watt in new LED fixtures. LED Fixtures command the dominant share of product-level revenue as fluorescent phase-outs accelerate across OECD markets. Smart Lighting within the technology dimension is recording the fastest expansion, driven by PoE Lighting integration that collapses installation costs by carrying both power and data over Ethernet cabling. Wireless Controls are maturing into a baseline expectation rather than a premium upgrade in Class A office refurbishments.
The EU Green Deal and its Ecodesign Working Plan set mandatory minimum efficacy thresholds and circularity requirements for luminaires sold across member states, while the U.S. Department of Energy administers ENERGY STAR and FEMP procurement standards that shape federal and utility rebate programs. China's GB standards for building illumination, enforced by SAMR, mandate specific power density limits for commercial spaces that directly determine fixture specification sheets. Stakeholders must monitor how converging regulatory timelines for embodied-carbon disclosure and interoperable control protocols will reshape supplier qualification criteria and project bidding requirements.
Market Dynamics
Power-over-Ethernet (PoE) lighting infrastructure is collapsing installation economics by converging power and data transmission onto single cabling runs, compressing project timelines and rewiring contractor relationships across commercial construction.
Growth Catalysts
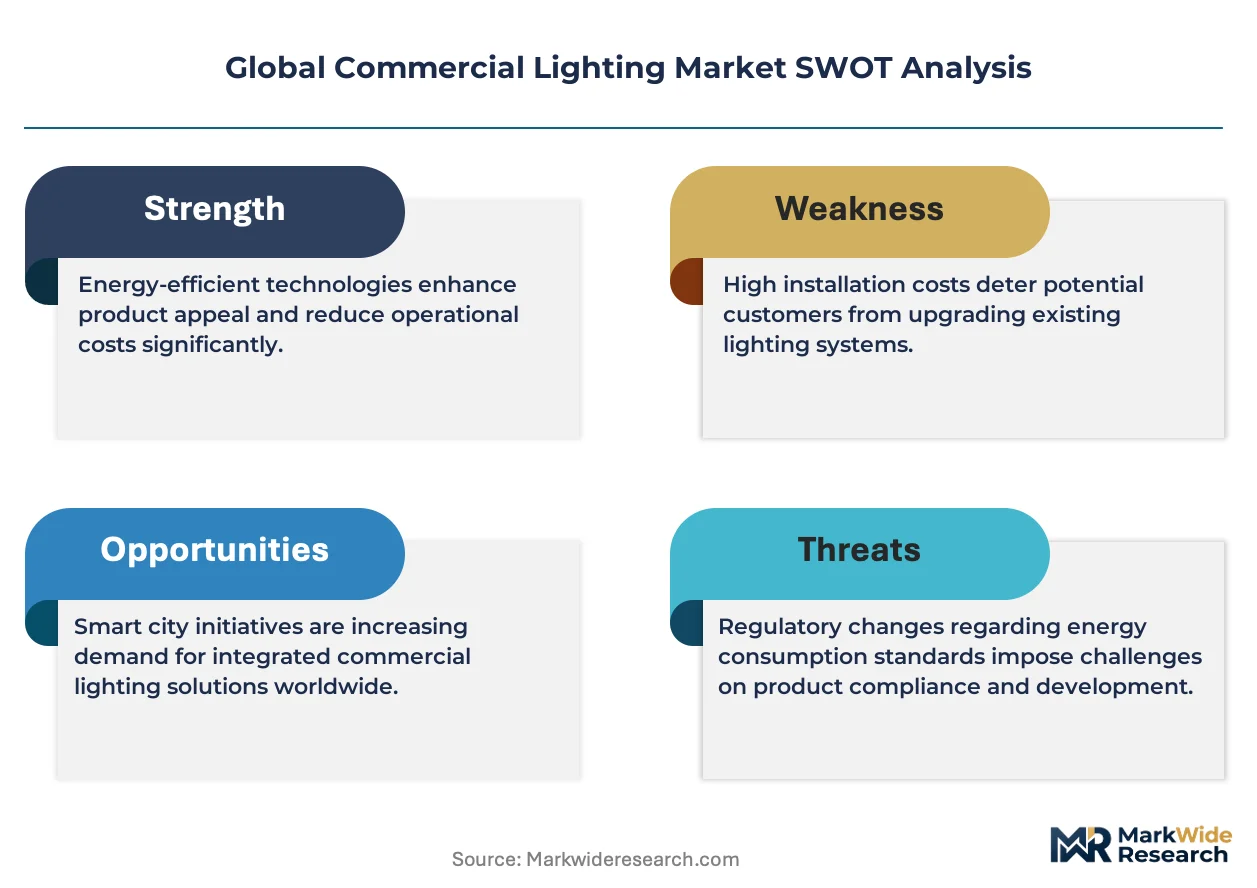
- EU Ecodesign mandates:Minimum efficacy thresholds under the EU Green Deal's Working Plan are accelerating fluorescent phase-outs across member states, forcing wholesale LED retrofits in office and retail portfolios.
- Smart-city procurement:Municipal programs in China are driving large-scale connected luminaire deployments, with industrial park expansions specifying networked control systems as baseline infrastructure.
- Building energy codes:Rising stringency in United States jurisdictions is tightening power density limits for commercial spaces, mandating fixture replacements that exceed 130 lumens per watt efficacy targets.
Market Restraints
- Semiconductor supply concentration:Dependence on concentrated LED driver IC manufacturing in East Asia creates vulnerability to regional logistics disruptions and input cost volatility.
- Copper and aluminum input costs:Thermal management components and electrical conductors face commodity price swings that compress fixture margins without proportional pricing power.
- Fluorescent inventory overhang:Existing installed bases and distributor stockpiles in certain OECD markets delay replacement cycles despite regulatory deadlines.
Strategic Opportunities
- Human-centric lighting specifications:Circadian rhythm optimization and tunable white systems are penetrating healthcare and education verticals, commanding premium positioning through health and wellness claims.
- India building code enforcement:Expanded BIS illumination standards for commercial construction are creating specification opportunities as domestic real estate development accelerates.
- Software subscription anchoring:Cloud-based energy management platforms are shifting revenue from one-time fixture sales toward recurring service relationships with facility managers.
Industry Challenges
- Interoperability protocol fragmentation:Competing wireless control standards (Zigbee, Bluetooth Mesh, proprietary systems) complicate system integration and lock-in risks for specifiers.
- Embodied-carbon disclosure requirements:Emerging mandates for lifecycle emissions reporting demand supply chain traceability that many luminaire manufacturers lack infrastructure to provide.
- Legacy building electrical infrastructure:Aging distribution systems in Class B and C commercial stock require costly preparatory work before advanced controls can be deployed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Lighting Market |
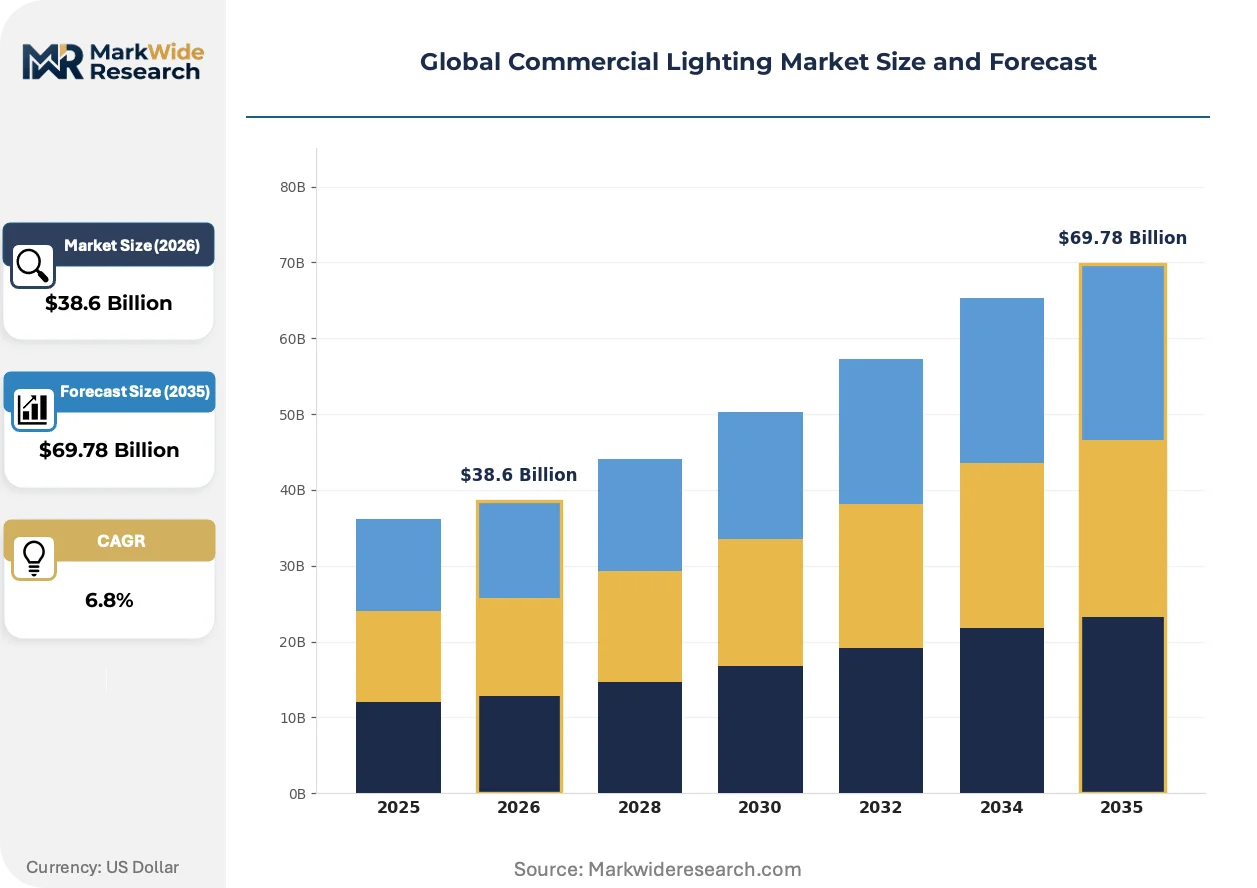
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Fixtures, Fluorescent Lamps, Halogen Bulbs, HID Lamps, Incandescent Bulbs, Neon Lights Technology: Smart Lighting, Wireless Controls, Motion Sensors, Daylight Harvesting, DALI Systems, PoE Lighting Application: Office Spaces, Retail Outlets, Hospitality Venues, Educational Institutions, Warehouses, Sports Facilities End User: Property Management, Facility Operators, Government Buildings, Event Organizers, Corporate Campuses, Transportation Hubs |
| Companies Covered | Signify Holding, Acuity Brands, ams-OSRAM, Cree Lighting, Zumtobel Group, Hubbell Incorporated, Panasonic Corporation, Dialight, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Lighting Market Shifts & Advancements
Digital twin integration is transforming how lighting systems are commissioned, operated, and maintained, collapsing the boundary between physical installation and virtual simulation environments.
LiDAR-enabled occupancy sensing is virtualizing spatial analytics within luminaire housings, embedding room-geometry mapping and people-flow tracking directly into ceiling-mounted fixtures. Corporate real estate teams in Class A office towers are specifying these sensor-dense deployments to optimize space utilization without standalone hardware investments. The technology is virtualizing the market for discrete building automation sensors, compressing vendor ecosystems into consolidated lighting-and-sensor procurement decisions.
CSRD disclosure requirements are mandating granular energy consumption reporting for commercial building portfolios, forcing landlords to install sub-metered lighting circuits that feed automated sustainability dashboards. The regulation is tightening procurement specifications to require native data export capabilities in all new luminaire purchases. German and French property funds are responding fastest, embedding these requirements into tenant improvement allowance structures.
Facility managers are unbundling maintenance contracts from original equipment supply agreements, creating independent service markets for predictive diagnostics and remote troubleshooting. This purchasing pattern is displacing traditional warranty-dependent relationships with lighting manufacturers. The shift is most pronounced in United States multi-site retail chains, where centralized procurement teams now separate capital expenditure for fixtures from operational expenditure for ongoing system management.
Global Commercial Lighting Market Segmentation
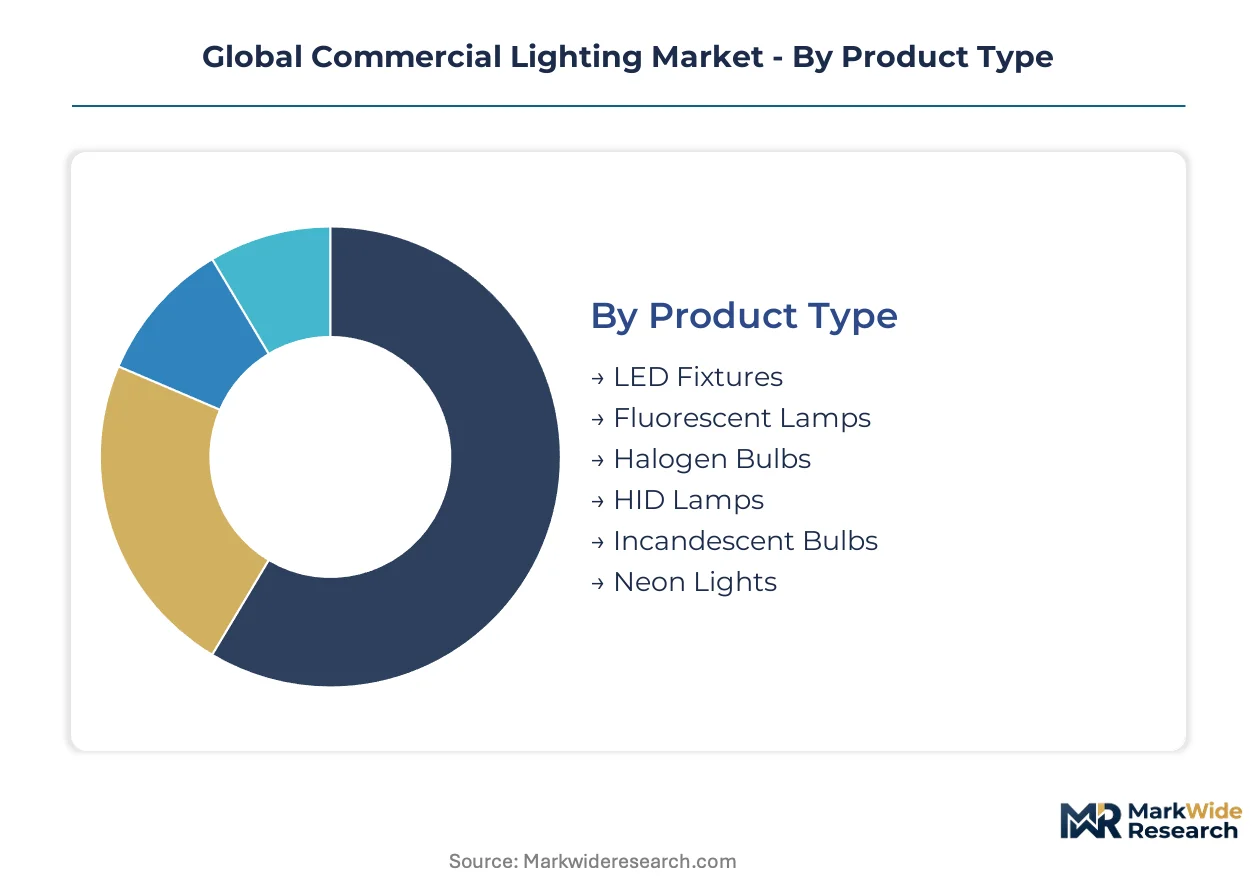
Segmentation in commercial lighting reveals how revenue migrates from hardware sales toward recurring service models. Distinct product, technology, application, and end-user dimensions each carry different margin profiles and contract renewal potential.
Product Type:
After-sales service intensity varies sharply across lamp technologies, with LED retrofits commanding multi-year maintenance contracts while legacy formats face phase-out.
- LED Fixtures:Solid-state luminaires with efficacy exceeding 130 lumens per watt dominate new construction and retrofit specifications. Office towers in Germany and retail chains in the United States are consolidating procurement around standardized LED platforms to simplify facility management.
- Fluorescent Lamps:Linear and compact fluorescent technologies face accelerated replacement under EU Ecodesign mandates. Inventory overhangs in certain OECD markets delay full phase-out despite regulatory deadlines.
- Halogen Bulbs:Tungsten-halogen sources retain niche accent lighting roles in hospitality and museum applications where color rendering precision justifies higher operating costs.
- HID Lamps:High-intensity discharge systems including metal halide and high-pressure sodium persist in warehouse and sports facility high-bay installations.
- Incandescent Bulbs:General-service incandescent technology has been largely eliminated from commercial specifications through successive efficacy regulations.
- Neon Lights:Cold-cathode signage applications survive in architectural and retail branding contexts where aesthetic differentiation outweighs efficiency concerns.
By volume, LED Fixtures leads. By growth pace, connected LED systems with embedded controls is ahead.
Technology:
Cost tier stratification separates premium integrated systems from commodity retrofit controls, with mid-tier wireless solutions capturing volume in Class B office refurbishments.
- Smart Lighting:Networked luminaire systems with cloud-based energy management anchor long-term client relationships through subscription revenue. China's municipal smart-city programs specify these as baseline infrastructure.
- Wireless Controls:Zigbee and Bluetooth Mesh protocols enable retrofit deployment without dedicated control wiring. United States Class A office refurbishments now treat wireless as standard rather than premium.
- Motion Sensors:Passive infrared and ultrasonic occupancy detection reduce energy consumption in intermittently used spaces.
- Daylight Harvesting:Photosensor-driven dimming circuits adjust artificial output based on available natural illumination.
- DALI Systems:Digital Addressable Lighting Interface provides wired control granularity for complex multi-zone installations.
- PoE Lighting:Power-over-Ethernet convergence collapses installation economics by carrying power and data over single cabling runs.
By installed base, Wireless Controls dominates. By expansion trajectory, PoE Lighting is climbing fastest in new construction.
Application:
Customer type differentiation separates capital-project owners from operational leaseholders, with divergent procurement authority and payback period requirements.
- Office Spaces:Corporate real estate teams specify human-centric lighting with tunable white and circadian optimization. Healthcare and education verticals in France command premium positioning through wellness claims.
- Retail Outlets:Merchandise presentation demands high color rendering indices and flexible accent positioning. United States multi-site chains separate fixture capex from ongoing system management opex.
- Hospitality Venues:Hotels and restaurants prioritize dimming performance and aesthetic fixture design over raw efficacy metrics.
- Educational Institutions:Schools and universities balance first-cost constraints against maintenance accessibility and student performance lighting research.
- Warehouses:High-bay industrial applications prioritize lumen maintenance and thermal management in unconditioned environments.
- Sports Facilities:Arena and stadium installations require broadcast-quality flicker-free output and instant restrike capability.
By project count, Office Spaces leads. By specification value, Sports Facilities is gaining share fastest.
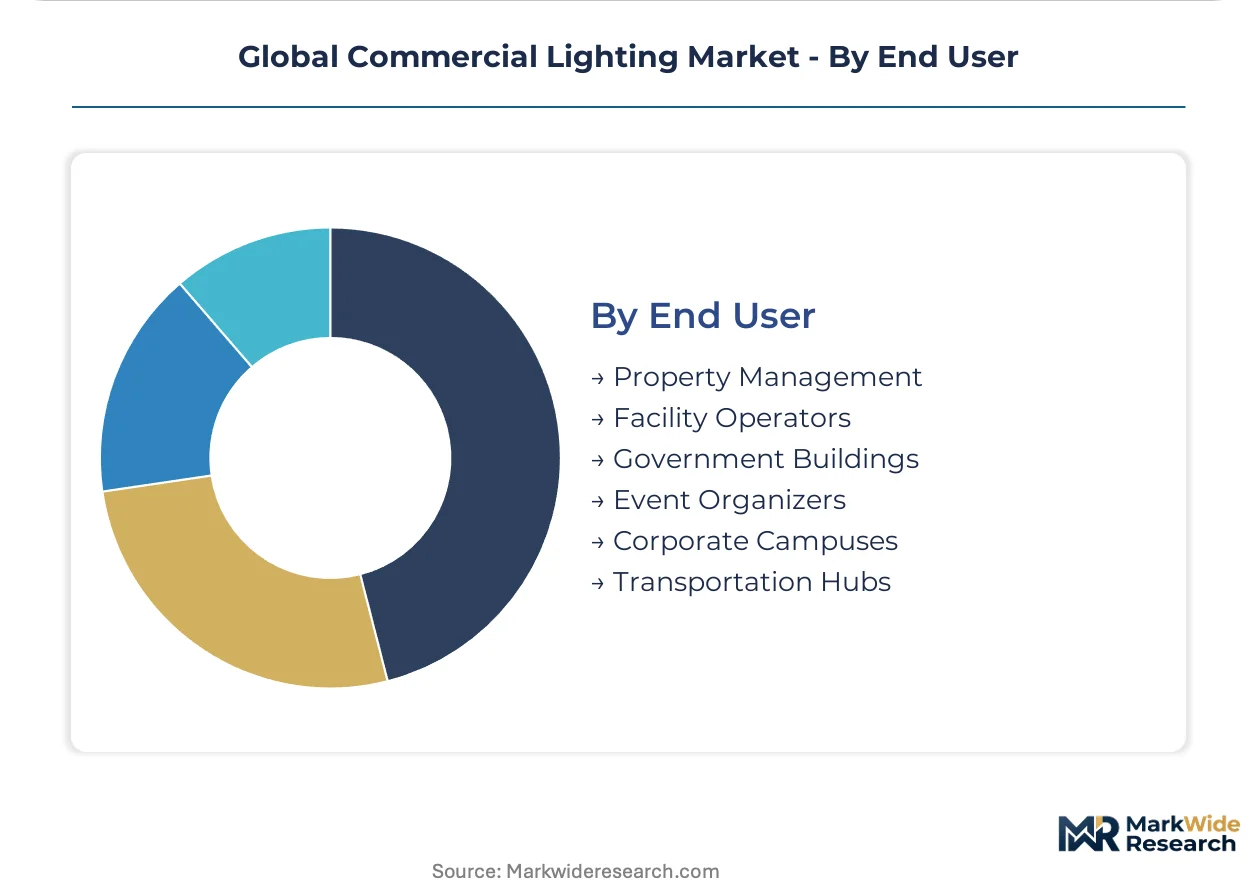
End User:
Supply concentration shapes vendor relationships, with concentrated facility operators commanding volume pricing while fragmented property managers face higher per-unit costs.
- Property Management:Third-party building operators prioritize standardization across portfolios to reduce spare parts inventory and technician training.
- Facility Operators:In-house corporate real estate teams at technology and financial services firms drive smart lighting adoption with direct sustainability reporting obligations.
- Government Buildings:Federal and municipal procurement in the United States follows ENERGY STAR and FEMP standards that shape rebate program eligibility.
- Event Organizers:Temporary installation specialists require rapid deployment and strike capabilities with minimal infrastructure modification.
- Corporate Campuses:Single-tenant owner-occupied facilities justify integrated building automation with lighting as a sensor network node.
- Transportation Hubs:Airports and rail terminals demand 24/7 operational reliability with centralized monitoring and maintenance dispatch.
By contract volume, Property Management leads. By technology sophistication, Corporate Campuses is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys commercial lighting as networked municipal infrastructure, while the United States treats it as building-level operational technology, and Germany frames it within circular-economy compliance obligations.
United States
Class A office refurbishments in Manhattan and Chicago specify PoE lighting as baseline infrastructure, collapsing installation timelines for corporate sustainability mandates. The Department of Energy administers ENERGY STAR and FEMP procurement standards that determine utility rebate eligibility across federal and state programs. Dallas-Fort Worth and Atlanta clusters concentrate distribution channel headquarters where procurement teams separate fixture capex from ongoing system management opex.
Germany
Frankfurt and Munich property funds embed CSRD disclosure requirements into tenant improvement allowances, mandating sub-metered lighting circuits with native data export capabilities. The EU Green Deal's Ecodesign Working Plan enforces minimum efficacy thresholds and circularity requirements for luminaires sold across member states. The Ruhr industrial corridor hosts retrofit specialists targeting fluorescent phase-outs in legacy manufacturing facilities.
China
Municipal smart-city programs in Shenzhen and Hangzhou specify connected luminaire systems as baseline infrastructure for industrial park expansions. SAMR enforces GB standards for building illumination that mandate specific power density limits for commercial spaces. The Yangtze River Delta concentrates LED component manufacturing and systems integration capacity for domestic and export markets.
India
Domestic real estate development in Mumbai and Bangalore creates specification opportunities as BIS illumination standards for commercial construction expand enforcement scope. The national building code mandates specific lighting power density limits that determine fixture selection for new construction permits. The Delhi-NCR corridor concentrates facility management companies standardizing procurement across multi-site corporate portfolios.
France
Healthcare and education verticals in Paris and Lyon command premium positioning for human-centric lighting with circadian rhythm optimization claims. ANSM and CNIL oversight shapes data governance requirements for connected lighting systems processing occupancy information. The Lyon-Grenoble cluster hosts sensor integration specialists serving European building automation markets.
Global Commercial Lighting Market Competitive Landscape
Capability concentration sits with component specialists mastering optical engineering and thermal management; scale advantage sits with diversified industrial conglomerates leveraging distribution breadth and project finance capacity. The vendor base organizes into three tiers: platform-anchored service providers, component-dominant technology licensors, and regionally focused fixture integrators. Consolidation pressure operates through vertical acquisition of controls software capabilities and horizontal expansion into adjacent building automation categories.
Among platform-anchored service providers, Signify Holding and Acuity Brands exemplify the shift from hardware sales toward recurring software subscription relationships with facility managers. The component-specialist tier includes ams-OSRAM, which occupies a position supplying high-performance LED emitters for premium-tier human-centric lighting specifications. These three companies represent distinct competitive vectors: cloud-based energy management anchoring, building-automation software stack extension, and upstream optical component dominance.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands |
| ams-OSRAM |
| Cree Lighting |
| Zumtobel Group |
| Hubbell Incorporated |
| Panasonic Corporation |
| Dialight |
| Eaton Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in China's Yangtze River Delta LED component manufacturing is compressing supplier margins and forcing tiered pricing strategies across export markets, while utilization rates below 75 percent in legacy fluorescent assembly plants are accelerating exit decisions among European fixture integrators.
Pricing Analysis
Long-term service contracts with recurring SaaS-tiered revenue dominate smart lighting procurement, separating fixture capex from cloud-based energy management subscriptions. Price differentiation hinges on certification grade (UL versus CE marking tiers) and volume scale across multi-site retail portfolios. Cost compression in commodity LED retrofits is intensifying because of aluminum and copper input volatility. Facility managers at multi-site property operators exhibit highest price sensitivity, while corporate campuses with direct sustainability reporting obligations accept premium positioning for human-centric specifications.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for luminaire manufacturers serving North American specifications. Component manufacturing concentrates in China, South Korea, and Taiwan, with final assembly and thermal management sourcing from Mexico and Vietnam to mitigate duty exposure. The ecosystem draws from gallium nitride substrates, aluminum heat sinks, and copper electrical conductors as critical inputs. Single-source vulnerability persists in specialized LED driver IC fabrication. Distribution runs through electrical wholesale channels and direct specification relationships with facility management firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global commercial lighting sits in early-cycle expansion as fluorescent phase-outs accelerate replacement velocity and smart-city procurement normalizes connected luminaire infrastructure as baseline specification.
For Market Incumbents: Entrench platform-anchored service relationships by extending cloud-based energy management subscriptions beyond illumination into integrated sensor networks. Capture backward integration into high-performance LED emitters to defend margin position against component specialists. Prioritize certification investment for EU Ecodesign and CSRD disclosure compliance as qualification barriers tighten. For New Entrants and Emerging Players: India's domestic real estate development in Mumbai and Bangalore offers underpenetrated specification opportunities as BIS illumination standards expand enforcement scope. Target mid-tier wireless controls for Class B office refurbishments where incumbents have ceded price-competitive positioning. Pursue partnership routes with facility management companies standardizing procurement across multi-site corporate portfolios. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-centric lighting platforms as recurring service revenue displaces hardware-dependent cash conversion cycles. Long-term viability favors acquisition targets with embedded sensor integration capabilities and established cloud infrastructure. Monitor municipal smart-city procurement velocity in China as the inflection signal for connected luminaire demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cloud-based energy management anchors recurring revenue with facility managers across Class A office portfolios. |
| Backward Integration | In-house LED emitter production defends margin compression from gallium nitride substrate cost volatility. |
| Certification Investment | EU Ecodesign and CSRD compliance creates qualification barriers against non-compliant import competition. |
| Geographic Expansion | India BIS standard enforcement opens specification windows for domestic real estate development acceleration. |
| Strategic Partnership | Sensor integration alliances with building automation vendors consolidate procurement decisions into single-vendor relationships. |
Research Methodology
Desk research of trade association filings, customs records, and regulatory databases preceded structured interviews with facility management executives, electrical contractor procurement leads, luminaire manufacturer product managers, and smart building integration specialists. Primary fieldwork combined with secondary validation from SEC 10-K disclosures, EU Ecodesign implementing measures, and SAMR GB standard documentation. Bottom-up project pipeline assessment and top-down macroeconomic overlay were triangulated to derive segment-level outputs.
Assumptions held fixed include regulatory enforcement timelines for fluorescent phase-outs and power density limits, while variables tested included copper and aluminum commodity price trajectories and municipal smart-city procurement acceleration rates. Segmentation modeling spanned product type, technology architecture, application vertical, and end-user procurement authority. CAGRs were derived from installed base replacement velocity and new construction specification penetration. Industry-specific inputs encompassed LED efficacy improvement curves and PoE lighting adoption thresholds in Class A office refurbishments.
Macroeconomic conditions sit as an overlay; deviation in commercial construction lending rates and corporate real estate capital allocation cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance timelines and technology substitution elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Art and Museum Lighting Market
Lighting
Specialty Lighting Market
Lighting
Architectural Lighting Market
Lighting
Studio Lighting Equipment Market
Lighting
Global Lamps Market
Lighting
Softbox Lighting Kit Market
Lighting
Explosion Proof Lighting Market
Lighting
Vintage Bulb Market
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
Industrial UV-C Disinfection Lighting Market
Lighting
Cleanroom Lighting Market
Lighting
Solid-State Lighting Source Market
Lighting
Hazardous Location LED Lighting Market
Lighting
Graphene Lighting Market
Lighting
Recessed Lighting Market
Lighting
Eye-Illuminating Gadgets Market