
 Smart Street Lighting Systems Market | 2026-2036
Smart Street Lighting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Street Lighting Systems Market Analytics
The EU Green Deal is recalibrating municipal procurement standards across European cities, mandating connected lighting infrastructure that cuts energy consumption through real-time dimming and fault detection. Signify Holding leverages its Interact platform to anchor large-scale urban deployments in Amsterdam and Copenhagen. Telensa Limited specializes in narrowband wireless control systems that dominate UK county council tenders. Eaton competes through integrated power management solutions that extend from luminaire hardware to cloud-based asset monitoring.
Smart street lighting systems comprise networked LED luminaires, environmental sensors, and centralized management software that communicate via cellular, RF mesh, or power-line carrier protocols to enable remote dimming, outage alerting, and traffic-responsive illumination. These systems primarily serve municipalities seeking to reduce electricity expenditure, lower maintenance truck rolls, and generate data revenue from pole-mounted IoT devices. LED technology leads installed base volumes due to retrofit economics and lumen-per-watt performance, while adaptive control architectures represent the fastest-expanding margin pool as cities prioritize software-defined lighting zones. Smart poles as a deployment mode concentrate investment from telecommunications carriers seeking 5G small cell attachment points alongside illumination.
The US Department of Energy's Better Buildings program and FERC demand-response frameworks shape utility co-funding structures for municipal lighting upgrades, while the EU F-Gas Regulation and Ecodesign directives constrain legacy high-pressure sodium replacement pathways. China's MIIT issues GB standards for networked lighting interoperability that determine product certification for domestic smart city bids. Stakeholders must monitor how spectrum allocation decisions for IoT protocols affect communication module selection and long-term platform lock-in across multi-decade infrastructure contracts.
Market Dynamics
Adaptive control architectures are compressing procurement cycles as municipalities abandon siloed hardware tenders in favor of integrated platform contracts that bundle luminaires, sensors, and software subscriptions into single-voltage agreements spanning fifteen to twenty years.
Growth Catalysts
- EU Green Deal energy efficiency mandates:The framework requires real-time dimming capabilities and fault detection in all new municipal lighting installations across member states, eliminating specification ambiguity for networked systems.
- China's dual carbon goals:Provincial smart city corridors in Jiangsu and Guangdong now embed GB-standard interoperability requirements directly into infrastructure procurement documents, accelerating domestic vendor certification.
- Narrowband wireless protocols:RF mesh and power-line carrier technologies reduce cellular subscription costs for mid-sized municipalities, expanding addressable market beyond tier-one cities.
Market Restraints
- Semiconductor supply concentration:Communication module production clusters in Taiwan create procurement vulnerability for RF mesh and cellular gateways during foundry allocation cycles.
- Legacy high-pressure sodium asset stranding:The EU F-Gas Regulation constrains refurbishment pathways for existing sodium vapor infrastructure, forcing complete luminaire replacement rather than control retrofits.
- LED driver cost volatility:Rare earth element pricing fluctuations in Chinese processing facilities compress hardware margins for luminaire manufacturers.
Strategic Opportunities
- Telecommunications carrier smart pole attachment:5G small cell co-location contracts transform street lighting assets into revenue-generating telecommunications infrastructure in dense urban corridors.
- India's municipal bond market expansion:Urban local bodies in Maharashtra and Gujarat now access green bond financing for LED retrofit programs, unlocking procurement previously constrained by fiscal deficits.
- Sensor fusion convergence:Integration of air quality, acoustic, and thermal imaging modules onto unified pole-mounted platforms creates data monetization streams beyond illumination services.
Industry Challenges
- Interoperability certification timelines:China's MIIT GB standards and the EU's Ecodesign directives impose non-harmonized testing protocols, extending product launch cycles by eight to fourteen months.
- Legacy analog control integration:Municipalities with existing DALI or 0-10V dimming infrastructure face firmware bridging complexity when upgrading to IP-based centralized management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Street Lighting Systems Market |
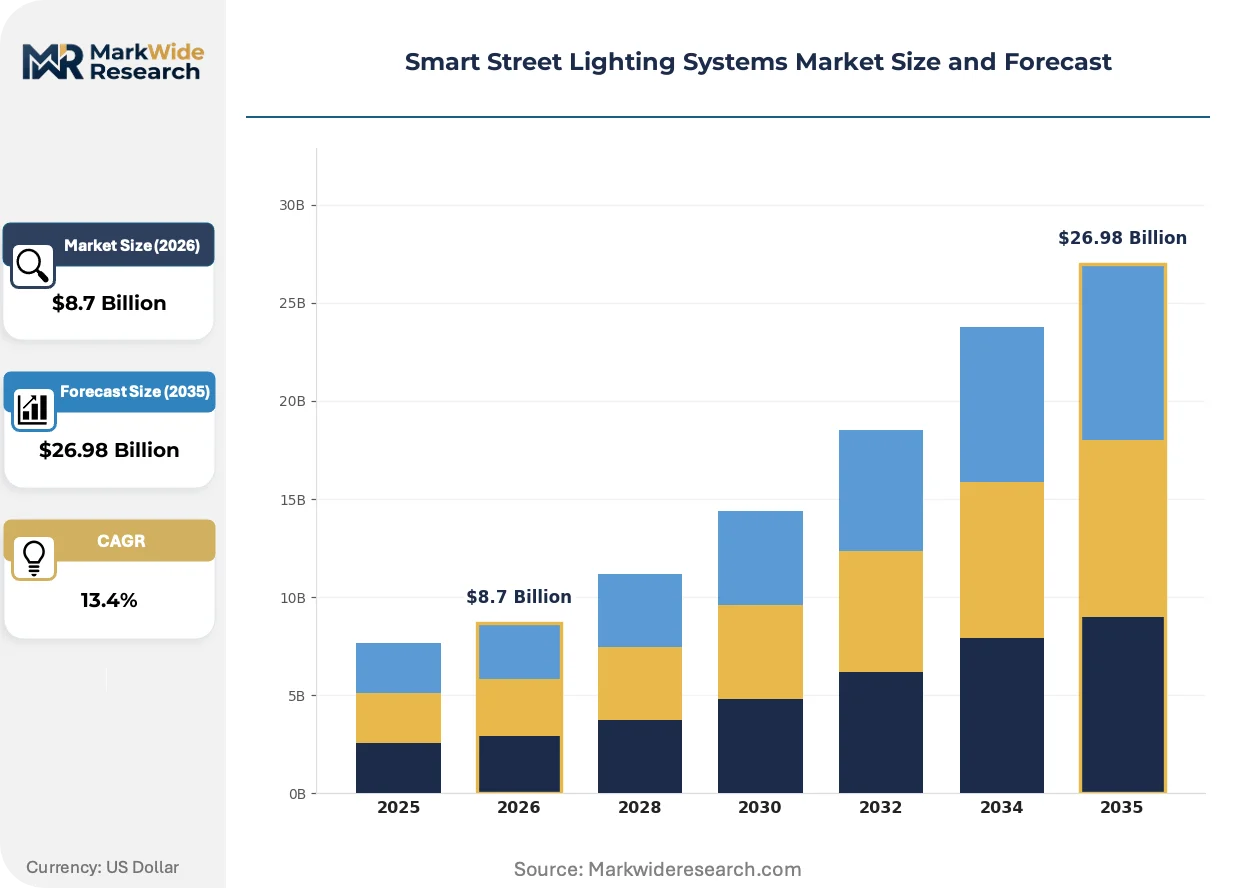
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LED, Solar, Smart Sensors, Adaptive Control Application: Urban Areas, Residential Streets, Commercial Zones, Highway Lighting Deployment: On-street Installations, Smart Poles, Integrated Solutions, Centralized Systems End User: Municipalities, Private Enterprises, Utility Companies, Community Organizations |
| Companies Covered | Acuity Brands, DimOnOff, Signify Holding, Flashnet SA, gridComm, Telensa Limited, Current Powered by GE, Eaton, Itron Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Street Lighting Systems Market Evolving Landscape
Software-defined lighting zones are displacing fixed-schedule illumination as the default design paradigm, with municipalities now specifying adaptive algorithms before selecting hardware vendors.
Edge computing nodes embedded within luminaire housings are unifying local sensor processing with real-time dimming decisions. German municipal utilities in Bavaria and Baden-Württemberg are deploying these architectures to reduce cloud latency for traffic-responsive illumination. This unification is compressing the traditional separation between lighting control and IoT data platforms into single-vendor ecosystems.
The EU AI Act's risk classification framework is recalibrating procurement specifications for computer vision-enabled street lighting. Systems incorporating pedestrian or vehicle recognition now require conformity assessments and bias testing documentation. French and Dutch municipalities are rewriting tender documents to mandate algorithmic transparency clauses for adaptive control systems.
Performance-based service contracts are displacing capital expenditure procurement in North American mid-sized cities. Cleveland and Pittsburgh now contract for guaranteed lumen-hour delivery rather than purchasing luminaires outright. This shift concentrates vendor risk on uptime and energy savings achievement while transferring maintenance liability from municipal workforces to platform operators.
Smart Street Lighting Systems Market Segmentation
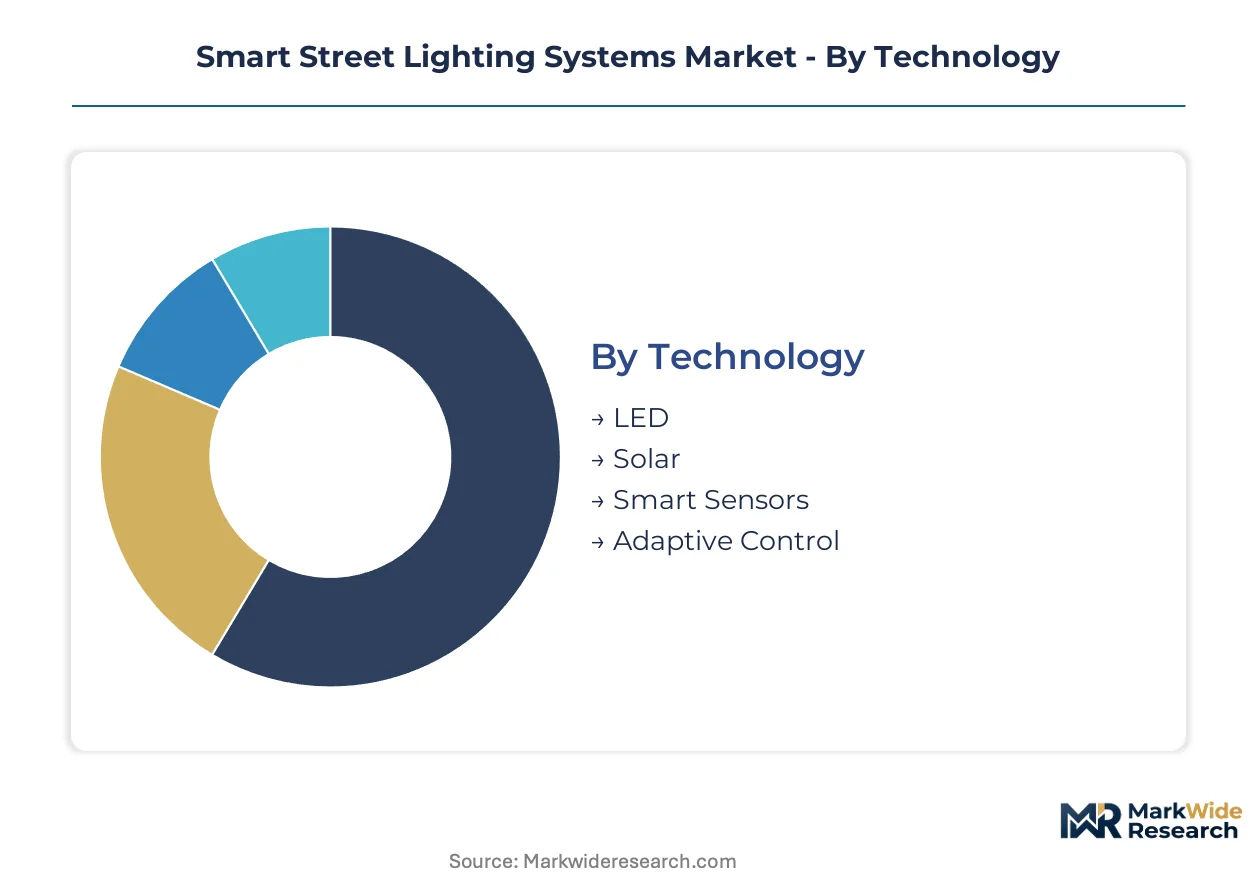
Technology choices in smart street lighting determine certification pathways and procurement eligibility across jurisdictions. Municipal buyers segment specifications by interoperability standards, energy performance tiers, and long-term service architectures rather than hardware alone.
Technology:
LED and adaptive control systems face divergent regulatory burdens under EU Ecodesign directives and China's MIIT GB standards, while solar and sensor modules navigate additional environmental certification requirements.
- LED:Solid-state luminaires with lumen-per-watt performance exceeding legacy sodium vapor by 50-70%. German municipal retrofit programs in Bavaria and North Rhine-Westphalia concentrate procurement volume here, driven by EU Green Deal energy efficiency mandates that disqualify non-LED replacements.
- Adaptive Control:Software-defined dimming algorithms and real-time fault detection capabilities. Demand clusters in Dutch and Danish urban corridors where municipalities now specify IP-based centralized management before selecting hardware vendors, compressing procurement cycles toward integrated platform contracts.
- Solar:Photovoltaic-powered luminaires with battery storage for off-grid illumination.
- Smart Sensors:Environmental and traffic detection modules enabling responsive illumination.
Leading the category by volume: LED. Growing fastest: Adaptive Control.
Application:
Application scope determines sensor fusion complexity and data monetization potential, with highway and commercial deployments requiring higher-grade connectivity certifications than residential installations.
- Urban Areas:Dense corridor illumination with multi-sensor pole platforms integrating air quality, acoustic, and thermal imaging. Chinese smart city corridors in Jiangsu and Guangdong embed GB-standard interoperability requirements directly into infrastructure procurement, accelerating domestic vendor certification for these deployments.
- Highway Lighting:High-lumen, wide-coverage systems with traffic-responsive algorithms and emergency override protocols. US state transportation departments under FERC demand-response frameworks prioritize these installations for utility co-funding eligibility.
- Residential Streets:Lower-density illumination with basic dimming schedules.
- Commercial Zones:Mixed-use illumination supporting retail security and pedestrian safety.
Urban Areas command the largest installed base. Highway Lighting is climbing the fastest as transportation electrification drives corridor modernization.
Deployment:
Deployment mode shapes fifteen-to-twenty-year contract structures, with smart poles and centralized systems locking municipalities into single-vendor ecosystems while on-street retrofits preserve procurement flexibility.
- Smart Poles:Unified platforms combining illumination with 5G small cell attachment points and edge computing nodes. Telecommunications carriers in dense US and European urban corridors drive investment here, transforming street lighting assets into revenue-generating telecommunications infrastructure.
- Centralized Systems:Cloud-based management platforms with city-wide visibility and predictive maintenance algorithms. Mid-sized North American municipalities favor these architectures under performance-based service contracts that transfer maintenance liability from municipal workforces to platform operators.
- On-street Installations:Individual luminaire replacements with minimal networking infrastructure.
- Integrated Solutions:Bundled hardware-software-service packages from single vendors.
Smart Poles show the steepest expansion trajectory. On-street Installations retain the dominant share of annual unit volume.
End User:
End user type determines financing mechanisms and contract risk allocation, with municipalities leveraging green bond markets while utilities prioritize demand-response integration.
- Municipalities:City and county governments procuring through retrofit programs or performance-based service contracts. India's urban local bodies in Maharashtra and Gujarat now access green bond financing for LED programs, unlocking procurement previously constrained by fiscal deficits.
- Utility Companies:Electricity distributors seeking demand-response assets and grid-edge visibility. These stakeholders shape US Department of Energy Better Buildings program co-funding structures and prioritize systems with FERC-compliant demand-response capabilities.
- Private Enterprises:Commercial developers and campus operators.
- Community Organizations:Neighborhood associations and non-profit operators.
Municipalities represent the dominant revenue pool. Utility Companies are gaining share fastest as grid modernization accelerates platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware fabrication clusters in China and Taiwan supply communication modules and LED drivers to municipal retrofit programs across Germany, the United States, and India. Consumption concentrates in jurisdictions with binding energy efficiency mandates and accessible green financing instruments.
United States
State transportation departments under FERC demand-response frameworks prioritize highway corridor modernization for utility co-funding eligibility. The Department of Energy's Better Buildings program shapes municipal procurement specifications in Cleveland and Pittsburgh, where performance-based service contracts now dominate. Midwestern cities concentrate deployment of centralized management platforms with predictive maintenance algorithms.
Germany
Bavarian and North Rhine-Westphalian municipal utilities drive LED retrofit volume through procurement programs that mandate EU Ecodesign compliance. The EU Green Deal's real-time dimming requirements eliminate specification ambiguity for networked systems. Baden-Württemberg deploys edge computing nodes within luminaire housings to reduce cloud latency for traffic-responsive illumination.
China
Provincial smart city corridors in Jiangsu and Guangdong embed MIIT GB-standard interoperability requirements directly into infrastructure procurement documents. The country's dual carbon goals accelerate domestic vendor certification for adaptive control architectures. Yangtze River Delta municipalities specify IP-based centralized management before selecting hardware vendors.
India
Urban local bodies in Maharashtra and Gujarat access green bond financing for LED programs, unlocking procurement previously constrained by fiscal deficits. The Bureau of Indian Standards issues certification protocols for networked lighting interoperability that determine product eligibility for municipal tenders. Western states concentrate deployment of solar-powered luminaires with battery storage for off-grid illumination.
United Kingdom
County council tenders favor narrowband wireless control systems that reduce cellular subscription costs for mid-sized municipalities. Telensa Limited anchors deployment patterns across English counties. The EU F-Gas Regulation constrains refurbishment pathways for legacy sodium vapor infrastructure, forcing complete luminaire replacement rather than control retrofits.
Smart Street Lighting Systems Market Competitive Landscape
The competitive structure tilts toward integrated platform providers that bundle hardware, software, and long-term service subscriptions into fifteen-to-twenty-year municipal contracts. Signify Holding and Eaton occupy positions as full-stack vendors with cloud-based asset monitoring capabilities. Eaton competes through power management solutions that extend from luminaire hardware to centralized visibility. Flashnet SA and gridComm represent specialists in narrowband wireless protocols that reduce connectivity costs for tier-two cities. Strategic moves concentrate on smart pole partnerships with telecommunications carriers and performance-based contract structures that transfer maintenance liability from municipal workforces to platform operators.
Among platform-integrated providers, Signify Holding exemplifies the full-stack archetype through its Interact platform anchoring large-scale urban deployments in Amsterdam and Copenhagen. Telensa Limited occupies a specialist position within the narrowband wireless tier, serving UK county council tenders with RF mesh architectures. Eaton represents the power management-integrated archetype, extending from luminaire hardware through cloud-based monitoring. These three companies illustrate the market's segmentation between comprehensive platform operators, connectivity specialists, and infrastructure-integrated power management providers.
| Leading Market Players |
|---|
| Acuity Brands |
| DimOnOff |
| Signify Holding |
| Flashnet SA |
| gridComm |
| Telensa Limited |
| Current Powered by GE |
| Eaton |
| Itron Inc. |
| Others |
Value Network & Pricing Analysis
Rare earth element processing costs in Chinese facilities flow downstream through LED driver manufacturing tiers, compressing hardware margins for luminaire producers while amplifying price stratification between premium adaptive control platforms and basic retrofit units. Municipal procurement offices in Germany and the United States absorb these input fluctuations through fifteen-to-twenty-year performance contracts that transfer component cost volatility to platform operators.
Pricing Analysis
Guaranteed lumen-hour delivery anchors municipal contract valuations, with Cleveland and Pittsburgh contracting for uptime assurance rather than hardware ownership. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform subscriptions from standalone luminaire sales and basic retrofit kits. Cost compression in economy-tier hardware intensifies because rare earth pricing volatility squeezes driver manufacturing margins. Mid-sized municipalities in the United Kingdom exhibit highest price sensitivity due to narrowband wireless protocol alternatives that slash cellular subscription burdens.
Supply Chain Analysis
China's MIIT GB standards and India's BIS certification protocols reshape sourcing patterns by mandating domestic content shares for smart city corridor eligibility. Communication module fabrication clusters in Taiwan and LED driver production in China draw from rare earth processing facilities and semiconductor foundry capacity. Single-source vulnerability concentrates in Taiwanese RF mesh gateway supply during foundry allocation cycles. Distribution runs through municipal procurement departments, utility co-funding structures, and telecommunications carrier smart pole partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry allocation cycles constrain communication module availability, propping pricing power for vendors with captive component supply or long-term foundry commitments.
For Market Incumbents: Deepen backward integration into LED driver manufacturing to insulate margins from rare earth pricing volatility in Chinese processing facilities. Secure MIIT GB-standard and EU Ecodesign certification portfolios ahead of interoperability mandate expansions. Counter emerging narrowband wireless specialists by bundling predictive maintenance algorithms into centralized platform subscriptions.
For New Entrants and Emerging Players: Enter via India's green bond-financed municipal retrofit programs in Maharashtra and Gujarat, where fiscal deficit constraints previously locked out established vendors. Target solar-powered luminaire deployments in western Indian states with battery storage requirements underserved by incumbent platform architectures. Pursue sensor fusion convergence opportunities by integrating air quality and acoustic modules onto unified pole-mounted platforms.
For Investors and Strategic Acquirers: Provincial smart city corridor tender releases in Jiangsu and Guangdong are the leading indicator that domestic vendor certification timelines are compressing, accelerating platform adoption velocity. Five-to-ten-year viability favors narrowband wireless specialists with RF mesh architectures and utility-scale deployment track records. Monitor EU AI Act conformity assessment documentation requirements as the inflection signal for algorithmic transparency clause proliferation in adaptive control procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Pole Partnership Formation | Telecommunications carriers in dense US and European urban corridors transform lighting assets into revenue-generating 5G infrastructure attachment points. |
| Performance-Based Contract Conversion | Mid-sized North American municipalities transfer maintenance liability from municipal workforces to platform operators through guaranteed lumen-hour delivery structures. |
| Interoperability Certification Acceleration | China's MIIT and EU Ecodesign non-harmonized testing protocols extend product launch cycles, favoring vendors with pre-certified platform architectures. |
| Edge Computing Node Integration | German municipal utilities in Bavaria and Baden-Württemberg deploy luminaire-embedded processing to reduce cloud latency for traffic-responsive illumination. |
| Sensor Fusion Platform Development | Integration of air quality, acoustic, and thermal imaging modules creates data monetization streams beyond core illumination services for urban corridor deployments. |
Research Methodology
Document review covered EU F-Gas Regulation implementation guidance, MIIT GB-standard interoperability protocols, and FERC demand-response framework filings, complemented by interviews with municipal procurement directors, utility planning officers, smart city program managers, and telecommunications carrier infrastructure leads. Secondary validation drew from Department of Energy Better Buildings program disclosures, Bureau of Indian Standards certification bulletins, and customs trade data on LED driver and communication module flows. Bottom-up unit economics triangulated against top-down infrastructure spending commitments across the analysis window.
Cross-referencing historical deployment trajectories against expert panel input shaped the analytical framework across technology, application, deployment mode, and end-user segmentation dimensions. CAGRs were derived from installed base replacement cycles, green bond issuance velocity, and smart city procurement pipeline conversion rates. Forecast inputs incorporated narrowband wireless protocol adoption curves, edge computing node penetration assumptions, and performance-based contract conversion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption scenarios or accelerated EU AI Act risk classification enforcement. Assumptions reflect documented municipal procurement specifications, regulatory mandate implementation schedules, and carrier 5G small cell deployment commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Solar Column Headlight Market
Lighting
Studio Lighting Equipment Market
Lighting
Photocell Market
Lighting
North America Street Lighting Market
Lighting
India Lighting Market
Lighting
Portable Lamps Market
Lighting
Display Light Control Film Market
Lighting
Directional Luminaire Market
Lighting
North America Outdoor Lighting Market
Lighting
Miniature Bulbs Market
Lighting
Digital Light Processing Technology Market
Lighting
GCC Smart Lighting Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Global Flame Proof Lighting Market
Lighting
Architectural Lighting Market
Lighting
Germany Indoor LED Lighting Market