
 North America Street Lighting Market | 2026-2036
North America Street Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Street Lighting Market Analytics
Subscription-based lighting-as-a-service is broadening what municipalities purchase, shifting capital budgets toward operational expenditure models with remote monitoring bundled into long-term contracts. Signify Holding leverages its Interact platform to anchor recurring revenue streams across U.S. city contracts. Cree Lighting differentiates through vertical manufacturing control over LED chips and optics. Hubbell Incorporated sustains distributor relationships that dominate the contractor channel across the Midwest and Southeast.
Street lighting encompasses pole-mounted luminaires, control systems, and networked infrastructure designed to illuminate roadways, pedestrian zones, and public spaces with specified color temperatures, lumen outputs, and uniformity ratios. LED product type leads installed base conversions due to efficacy thresholds exceeding 130 lumens per watt and compatibility with dimming protocols. Smart lighting technology captures margin pools through software licensing and data analytics layers, while retrofit installation type dominates near-term project pipelines as cities delay full network overhauls. Solar product type remains niche but grows fastest in off-grid rural corridors and tribal lands across the Southwest.
The U.S. Department of Energy enforces minimum efficacy standards through its SSL Quality Advocates program, while the FCC governs wireless spectrum allocation for connected luminaires and Canada's NRCan administers energy performance verification under its Energy Efficiency Regulations. These frameworks shape demand by disqualifying non-compliant products from utility rebate eligibility and municipal procurement lists. Stakeholders must monitor evolving cybersecurity requirements for networked infrastructure as NIST guidelines harden into enforceable procurement criteria.
Market Dynamics
The U.S. Department of Energy's SSL Quality Advocates program is compressing replacement cycles by disqualifying sub-130 lumens-per-watt fixtures from utility rebate eligibility, forcing municipalities into accelerated procurement timelines.
Growth Catalysts
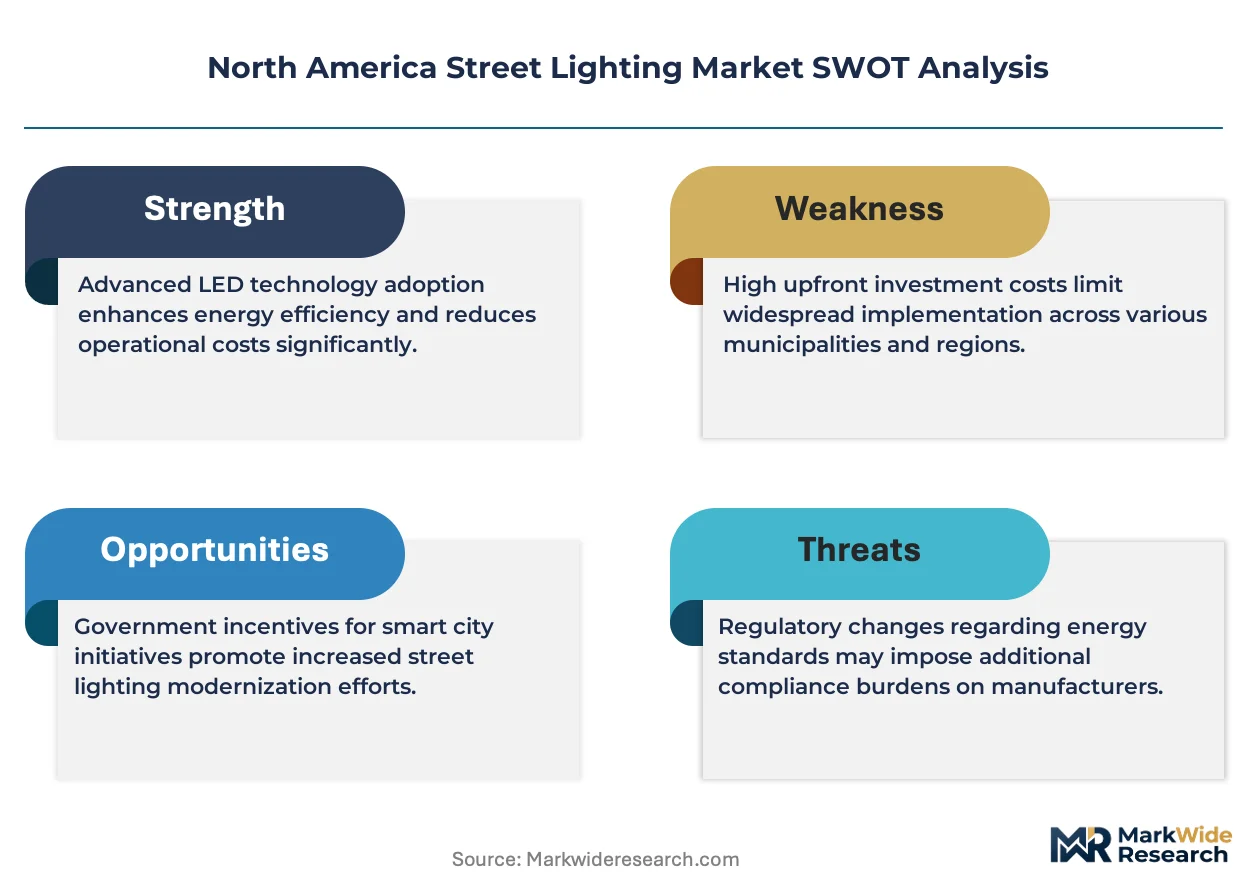
- California Title 24 mandates:The state's building energy code requires adaptive outdoor lighting controls in new construction and major renovations, creating guaranteed demand for networked LED systems across municipal and commercial installations.
- Tribal lands electrification:Off-grid solar street lighting deployments across Navajo Nation and Southwest reservations address infrastructure gaps while bypassing centralized grid dependency entirely.
- Texas utility rebate stacking:Oncor and CenterPoint Energy programs allow municipalities to layer federal, state, and local incentives, reducing net project costs below legacy HID maintenance expenses.
Market Restraints
- Semiconductor input volatility:LED driver ICs and power management chips face price instability from concentrated Taiwan and South Korea foundry capacity, squeezing fixture margins.
- FCC spectrum allocation friction:Unlicensed 900 MHz and 2.4 GHz band congestion in dense urban corridors degrades mesh network reliability for connected luminaires.
- HID residual inventory:Municipal warehouses hold 18-24 months of legacy high-pressure sodium lamp stockpiles, delaying full LED conversion commitments.
Strategic Opportunities
- Canadian smart city clusters:Toronto and Vancouver pilot programs fund integrated street lighting with EV charging and environmental sensing, opening multi-revenue infrastructure contracts.
- LiDAR-camera convergence:Mounting autonomous vehicle perception hardware on lighting poles creates new tenant revenue streams from mobility companies.
- Lighting-as-a-service channel:Energy service companies bundle installation, maintenance, and software licensing into 10-15 year municipal contracts, displacing traditional capital procurement.
Industry Challenges
- NIST cybersecurity compliance:Networked infrastructure must meet evolving encryption and access control standards, extending product development timelines and certification costs.
- Legacy control protocol fragmentation:DALI, 0-10V, and proprietary wireless standards create integration complexity when retrofitting mixed-vintage installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Street Lighting Market |
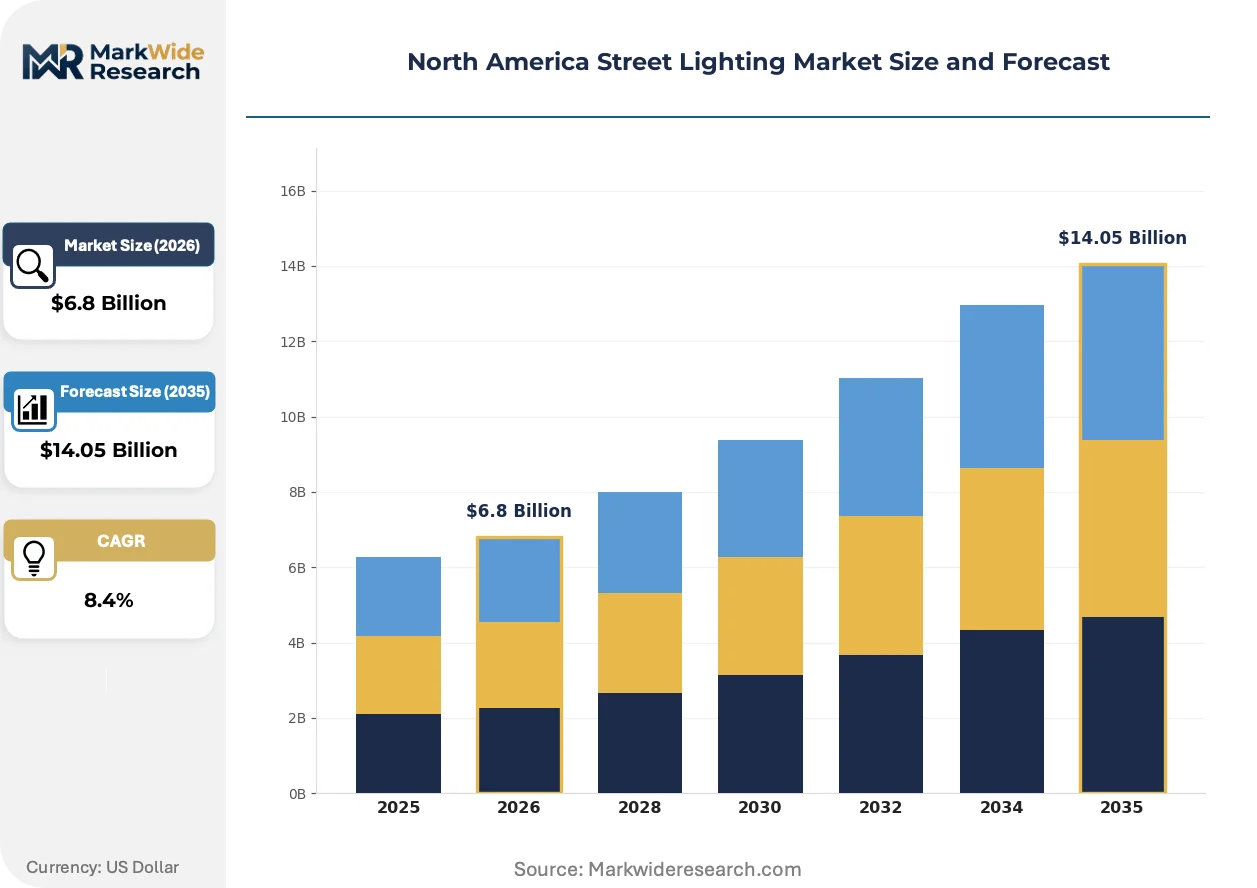
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Solar, HID, Smart Lighting End User: Municipalities, Urban Planners, Contractors, Utility Companies Technology: IoT, Wireless, Automated Systems, Adaptive Lighting Installation Type: New Installation, Retrofit, Replacement, Maintenance |
| Companies Covered | Acuity Brands, Inc., Cree Lighting, General Electric Company, Hubbell Incorporated, Eaton Corporation PLC, Signify Holding, Cooper Lighting, Itron Inc., Leotek Electronics USA, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Street Lighting Market Evolving Landscape
Adaptive control architectures are rewriting how municipalities specify and pay for illumination, compressing the boundary between hardware procurement and ongoing software service relationships.
Edge-computing nodes embedded in luminaire housings are decentralizing traffic management and public safety analytics away from centralized cloud servers. Arizona DOT and Texas DOT pilot programs deploy these units along interstate corridors, processing vehicle flow data locally to reduce latency. This architecture is decentralizing the historical vendor-customer relationship by enabling smaller software providers to compete against integrated lighting giants.
The U.S. Department of Energy's pending Connected Lighting System specification will mandate interoperable APIs and standardized data exchange formats for all federally funded projects. This rule compresses proprietary ecosystem advantages held by incumbent platform providers. California and New York municipalities are pre-emptively adopting these requirements, forcing manufacturers to open previously closed control architectures.
Municipal finance departments now favor performance contracting that ties vendor payments to verified energy savings rather than equipment delivery. Ohio and Illinois cities lead this transition, with Chicago's Department of Assets leveraging third-party measurement and verification protocols. This restructuring is concentrating vendor selection criteria on historical operational data rather than upfront capital cost bids, disadvantaging newer market entrants without established track records.
North America Street Lighting Market Segmentation
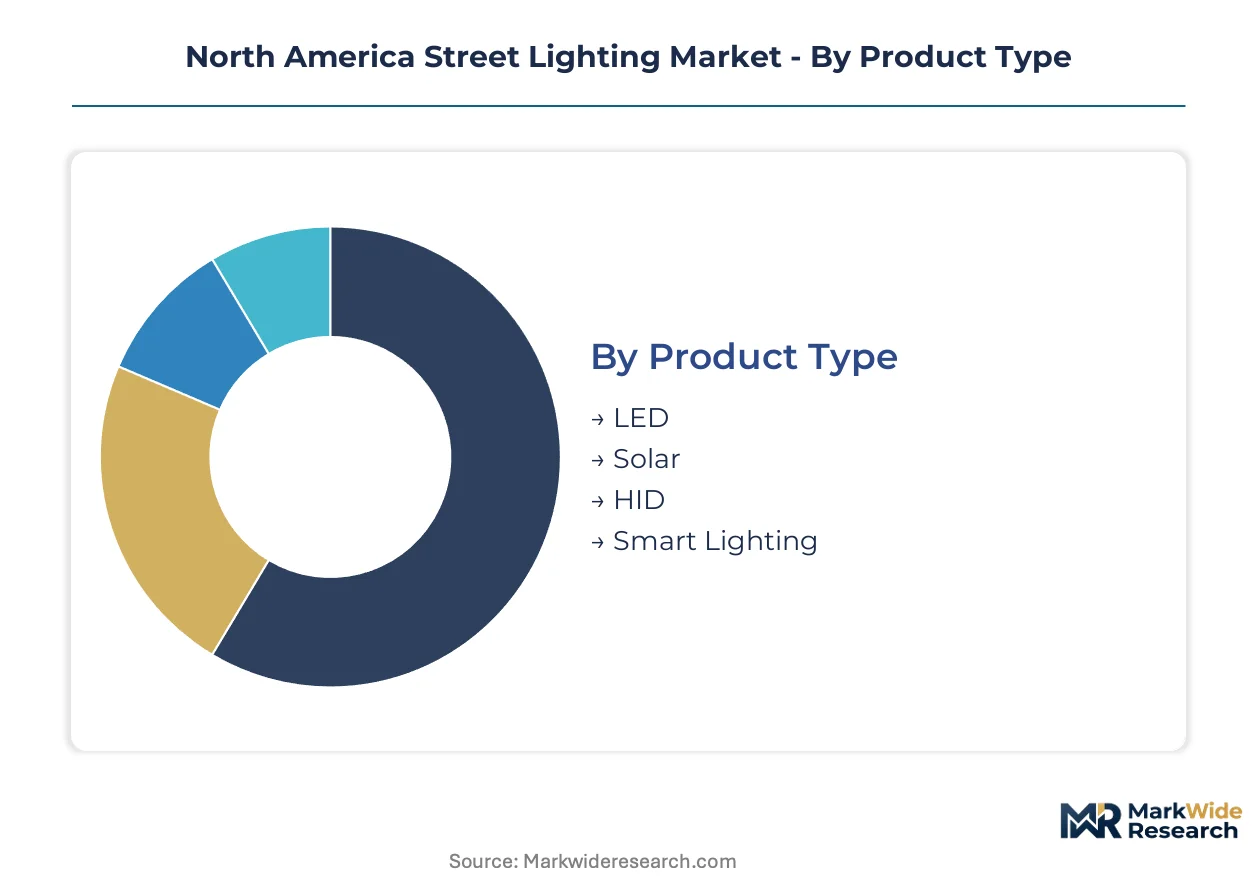
Street lighting procurement in North America fragments across hardware specifications, control architectures, and contract structures. Each segmentation axis shapes vendor selection criteria and margin capture differently across municipal, utility, and commercial channels.
Product Type:
Technology specifications determine rebate eligibility and lifecycle economics across North American jurisdictions.
- LED:Solid-state luminaires delivering efficacy thresholds exceeding 130 lumens per watt with dimming protocol compatibility. California Title 24 mandates and Texas utility rebate programs concentrate demand in these high-efficiency fixtures, displacing legacy alternatives through operational cost savings.
- Smart Lighting:Networked systems integrating sensors, software platforms, and remote management capabilities. Toronto and Vancouver pilot programs anchor multi-revenue infrastructure contracts combining illumination with environmental sensing and EV charging integration.
- Solar:Off-grid photovoltaic-powered luminaires with battery storage for autonomous operation. Navajo Nation and Southwest tribal lands deploy these units to bypass centralized grid dependency entirely.
- HID:Legacy high-pressure sodium and metal halide fixtures with established maintenance infrastructure. Municipal warehouses across the Midwest and Southeast retain 18-24 months of residual lamp inventory, delaying full conversion timelines.
LED leads on scale; Smart Lighting leads on momentum.
End User:
Procurement authority concentrates in entities controlling capital budgets and operational expenditure frameworks.
- Municipalities:City and county governments specifying networked LED conversions through performance contracting tied to verified energy savings. Chicago's Department of Assets and Ohio cities pioneer third-party measurement protocols that restructure vendor selection around historical operational data.
- Utility Companies:Investor-owned and municipal utilities administering rebate programs and infrastructure ownership models. Oncor and CenterPoint Energy in Texas allow incentive stacking that reduces net project costs below legacy HID maintenance expenses.
- Urban Planners:Regional authorities integrating street lighting with smart city master plans and mobility infrastructure. Arizona DOT and Texas DOT pilot edge-computing nodes for decentralized traffic analytics.
- Contractors:Electrical installation firms executing retrofit and new construction projects through distributor relationships dominating the Midwest and Southeast channels.
Municipalities control procurement volume; Utility Companies shape financing structures.
Technology:
Control architectures determine interoperability requirements and cybersecurity compliance burdens.
- IoT:Internet-connected sensor networks enabling centralized monitoring and predictive maintenance. The pending U.S. Department of Energy Connected Lighting System specification mandates interoperable APIs for all federally funded projects.
- Adaptive Lighting:Real-time dimming and color temperature adjustment responding to traffic patterns and ambient conditions. California Title 24 mandates require these controls in new construction and major renovations.
- Wireless:Mesh and star-topology radio networks operating in unlicensed spectrum bands. FCC spectrum allocation friction in dense urban corridors degrades 900 MHz and 2.4 GHz reliability.
- Automated Systems:Rule-based control logic executing scheduled and event-triggered illumination adjustments without human intervention.
IoT dominates installed base expansion; Adaptive Lighting faces regulatory tailwinds.
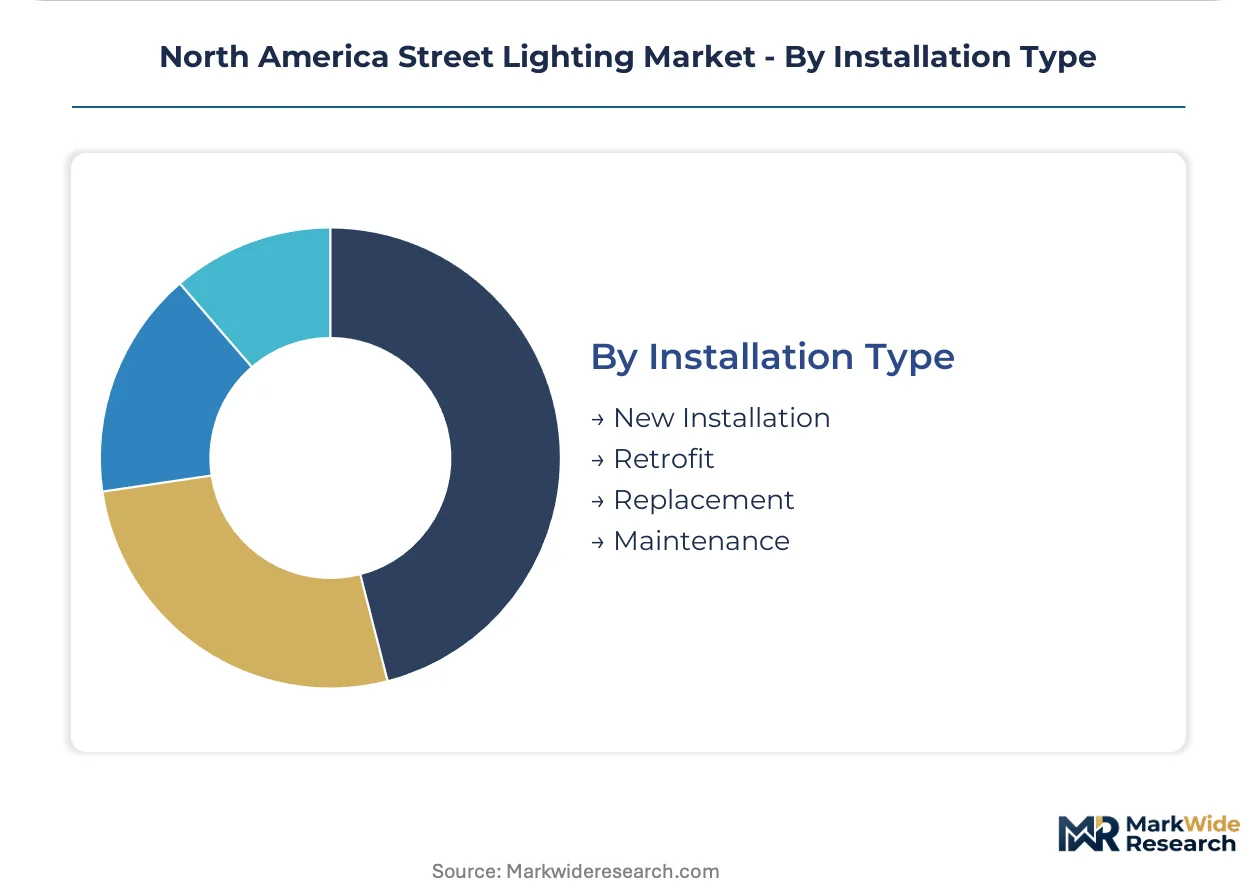
Installation Type:
Project delivery methods reflect municipal fiscal constraints and network upgrade sequencing.
- Retrofit:LED conversion of existing pole infrastructure without full network replacement. Near-term pipelines concentrate here as cities delay comprehensive overhauls while capturing immediate energy savings.
- New Installation:Complete pole, wiring, and luminaire deployment for roadway expansion and greenfield development. Green building codes in California and New York accelerate specification of networked controls.
- Replacement:End-of-life fixture swaps maintaining existing control architectures and pole positions.
- Maintenance:Ongoing lamp replacement, cleaning, and repair services bundled into long-term service contracts.
Retrofit commands near-term volume; New Installation captures margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the largest installed base of street lighting infrastructure while Canada accelerates faster on smart city integration per capita. Mexico presents emerging retrofit potential as federal energy efficiency programs expand.
United States
California Title 24 mandates and Texas utility rebate stacking drive municipal procurement of networked LED systems. The U.S. Department of Energy's SSL Quality Advocates program enforces minimum efficacy thresholds that disqualify legacy fixtures from federal funding eligibility. Chicago's Department of Assets and Ohio cities pioneer performance contracting tied to third-party measurement and verification protocols.
Canada
Toronto and Vancouver pilot programs fund integrated street lighting with EV charging and environmental sensing capabilities. Natural Resources Canada administers energy performance verification under Energy Efficiency Regulations that shape utility rebate eligibility. Ontario concentrates deployment through provincial smart city clusters while British Columbia emphasizes adaptive control architectures.
Mexico
Federal energy efficiency initiatives and grid modernization programs accelerate LED conversion timelines in major metropolitan zones. The national electricity utility CFE administers rebate structures that reduce upfront capital barriers for municipal procurement. Mexico City Metro and Nuevo León industrial corridors anchor initial deployment clusters before national program expansion.
North America Street Lighting Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers capturing recurring revenue streams while component fabricators compete on fixture economics. The vendor base concentrates around three strategic tiers: full-stack lighting platforms, verticalized LED manufacturers, and distributor-anchored electrical suppliers. Competitive positioning hardens through M&A activity consolidating control software capabilities and strategic partnerships bundling installation with long-term service obligations.
Among North American headquartered providers, Acuity Brands, Inc. and Cree Lighting exemplify contrasting archetypes within the LED conversion wave, while Signify Holding occupies a position representing the platform-centric recurring revenue model. Hubbell Incorporated anchors the distributor-channel segment through contractor relationship density across Midwest and Southeast markets. Eaton Corporation PLC sits within the diversified electrical infrastructure tier, leveraging broad industrial exposure to cross-sell street lighting into municipal accounts. These three named entities collectively represent the strategic spectrum from component supply through integrated service delivery.
| Leading Market Players |
|---|
| Acuity Brands, Inc. |
| Cree Lighting |
| General Electric Company |
| Hubbell Incorporated |
| Eaton Corporation PLC |
| Signify Holding |
| Cooper Lighting |
| Itron Inc. |
| Leotek Electronics USA, LLC |
| Others |
Value Network & Pricing Analysis
Networked LED control architectures are compressing fixture economics while redistributing margin capture toward software layers, simultaneously concentrating supply leverage among semiconductor foundries and diluting pricing power for pure hardware vendors.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for LED driver ICs and power management components. Three-tier pricing structure across premium, standard, and economy levels segments procurement by efficacy certification and control sophistication. Cost compression in economy-tier fixtures is intensifying because municipal buyers prioritize upfront capital minimization over lifecycle optimization. Utility rebate-eligible smart systems show least price sensitivity; off-grid solar deployments in tribal corridors show greatest.
Supply Chain Analysis
LED chip supply rests on concentrated fabrication capacity in Taiwan, South Korea, and China. Aluminum extrusions for pole housings and lithium-ion cells for solar storage anchor raw material dependencies. Single-source vulnerability in Taiwan foundry capacity creates exposure to geopolitical disruption. Distribution runs through electrical distributor networks across the Midwest and Southeast, with direct municipal contracting gaining share in California and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America street lighting market compounds steadily as federal efficacy mandates force replacement cycles regardless of economic cyclicality.
For Market Incumbents: Anticipate margin compression in commodity LED fixtures by securing captive supply of driver ICs through foundry partnerships or inventory pre-positioning. Deepen software platform stickiness through Interact-style recurring revenue architectures that lock municipalities into decade-long service relationships. The threat of open API mandates from the U.S. Department of Energy erodes proprietary ecosystem advantages. For New Entrants and Emerging Players: Launch via lighting-as-a-service contracts that bypass capital procurement committees and align vendor compensation with verified energy savings. Target tribal lands and rural Southwest corridors where solar off-grid systems bypass incumbent distributor relationships entirely. The most penetrable segment combines EV charging integration with environmental sensing in Canadian smart city pilots. For Investors and Strategic Acquirers: Valuations sit cheapest among component fabricators without software layer attachment. Five-to-ten-year viability favors platform providers with established municipal performance records over pure hardware vendors. The signal to watch is NIST cybersecurity compliance hardening into enforceable procurement criteria, which will consolidate vendor qualification lists.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Signify's Interact architecture anchors recurring revenue across U.S. municipal contracts. |
| Backward Integration | Cree Lighting's captive LED chip production insulates margins from foundry price volatility. |
| Channel Control | Hubbell's distributor density across Midwest and Southeast dominates contractor procurement. |
| Geographic Expansion | Toronto and Vancouver pilot programs open multi-revenue infrastructure contracts. |
| Certification Investment | DOE Connected Lighting System compliance opens federal funding eligibility. |
Research Methodology
Multiple input streams — municipal procurement officer interviews, utility rebate program administrators, electrical distributor channel heads, and smart city technology vendors — were reconciled against secondary validation from U.S. Department of Energy SSL Quality Advocates filings, FCC spectrum allocation records, Natural Resources Canada energy efficiency databases, and SEC 10-K disclosures from listed electrical infrastructure providers. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates.
Historical deployment trajectories were cross-referenced against expert panel assessments of replacement cycle acceleration. Segmentation dimensions modeled include product type, control technology, installation method, and end-user procurement authority across the analysis window. CAGRs derived from curve-fitting observed conversion rates and projected efficacy mandate compliance deadlines. Forecast inputs incorporated utility rebate stacking eligibility rules and tribal lands electrification program expansion.
Several conditions sit outside the modeled scope, including unannounced federal infrastructure stimulus packages, semiconductor trade restriction escalations, and autonomous vehicle perception hardware mounting standards. Forecasts reflect documented assumptions about replacement cycle timing and rebate program continuity. A small set of named triggers warrants ongoing watch: NIST cybersecurity guideline enforcement, FCC spectrum reallocation proceedings, and concentrated foundry capacity disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Tritium Light Source Market
Lighting
Hazardous Location LED Lighting Market
Lighting
Photography Light Box Market
Lighting
Xenon Headlights Market
Lighting
Photocell Market
Lighting
Miniature Bulbs Market
Lighting
Flexible Lighting Foils Market
Lighting
COB Photo Light Market
Lighting
Germany Indoor LED Lighting Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
Global Headlight Control Module Market
Lighting
Smart Lighting Market
Lighting
Lighting Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
Softbox Lighting Kit Market
Lighting
Lamps and Lighting Market