
 Global Work Lights Market | 2026-2036
Global Work Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Global Work Lights Market Foresight
IP65 ingress protection certification is collapsing the competitive field for portable work lights, forcing smaller assemblers out of hazardous-environment bidding. Signify leverages its Lumileds captive LED supply chain to control component costs across European project channels. Larson Electronics dominates explosion-proof fixture specifications for oilfield and petrochemical buyers in North America. Bayco Products sustains its position in rechargeable handheld segments through direct law-enforcement and utility procurement relationships.
Work lights are portable or fixed luminaires engineered to deliver task-specific illuminance measured in lux or foot-candles, typically employing LED arrays rated from 1,000 to 10,000 lumens with color temperatures between 4,000K and 6,500K for visual accuracy in low-ambient conditions. Construction sites and mining operations anchor volume demand, while emergency services applications generate premium pricing due to NFPA and ATEX compliance requirements. LED technology leads type segmentation with superior efficacy and runtime, though halogen retains niche share where instant full output and low capital outlay matter; tripod-mounted configurations command higher average prices than handheld units due to integrated power management and stability engineering.
OSHA enforces minimum illumination standards for general construction and shipyard operations, directly shaping product lumen output and placement requirements for contractors. ECHA REACH restrictions on hazardous substances in electrical equipment and China's GB standards for luminaire safety create parallel compliance tracks for multinational suppliers. The EU F-Gas Regulation indirectly pressures HID work light manufacturers toward LED conversion. Stakeholders must monitor evolving photobiological safety standards and battery transport regulations as cordless designs expand runtime expectations.
Market Dynamics
LED efficacy gains above 150 lumens per watt are compressing fixture form factors while extending runtime, forcing incumbent suppliers to redesign thermal management architectures and battery integration strategies.
Growth Catalysts
- OSHA Illumination Mandates:United States construction contractors must maintain minimum foot-candle levels across active zones, driving systematic replacement schedules for outdated halogen units.
- ATEX Certification Requirements:European petrochemical and mining operators face mandatory explosion-proof specifications, creating captive demand for IP65+ rated portable fixtures.
- Rechargeable Lithium-Ion Chemistry:Energy density improvements enable cordless designs replacing generator-tethered legacy systems on remote job sites.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium processing clusters in China create input cost volatility for high-efficiency LED driver assemblies.
- REACH Substance Restrictions:ECHA limitations on lead content and flame retardants in electrical equipment force reformulation of PCB substrates and housing polymers.
- Halogen Persistence:Instant full-output performance and sub-$20 price points sustain residual demand from price-sensitive residential and small commercial buyers.
Strategic Opportunities
- India Infrastructure Build-Out:National highway and metro rail projects generate concentrated demand for ruggedized temporary lighting with localized voltage tolerance.
- EU F-Gas Regulation Phase-Down:HID work light manufacturers face forced conversion timelines, opening retrofit revenue streams for LED-native suppliers.
- Smart Connectivity Integration:Bluetooth mesh and DALI-2 protocols enable centralized zone control, appealing to large-scale industrial facilities in Germany and Japan.
Industry Challenges
- Photobiological Safety Certification:IEC 62471 blue-light hazard testing extends product validation timelines by four to six months for high-lumen arrays.
- UN 38.3 Battery Transport Compliance:Lithium-ion pack certification for air and sea freight adds documentation burden and shipping cost variability.
- Legacy Fixture Integration:Tripod-mounted LED retrofits must maintain mechanical compatibility with existing stands and power distribution boxes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Work Lights Market |
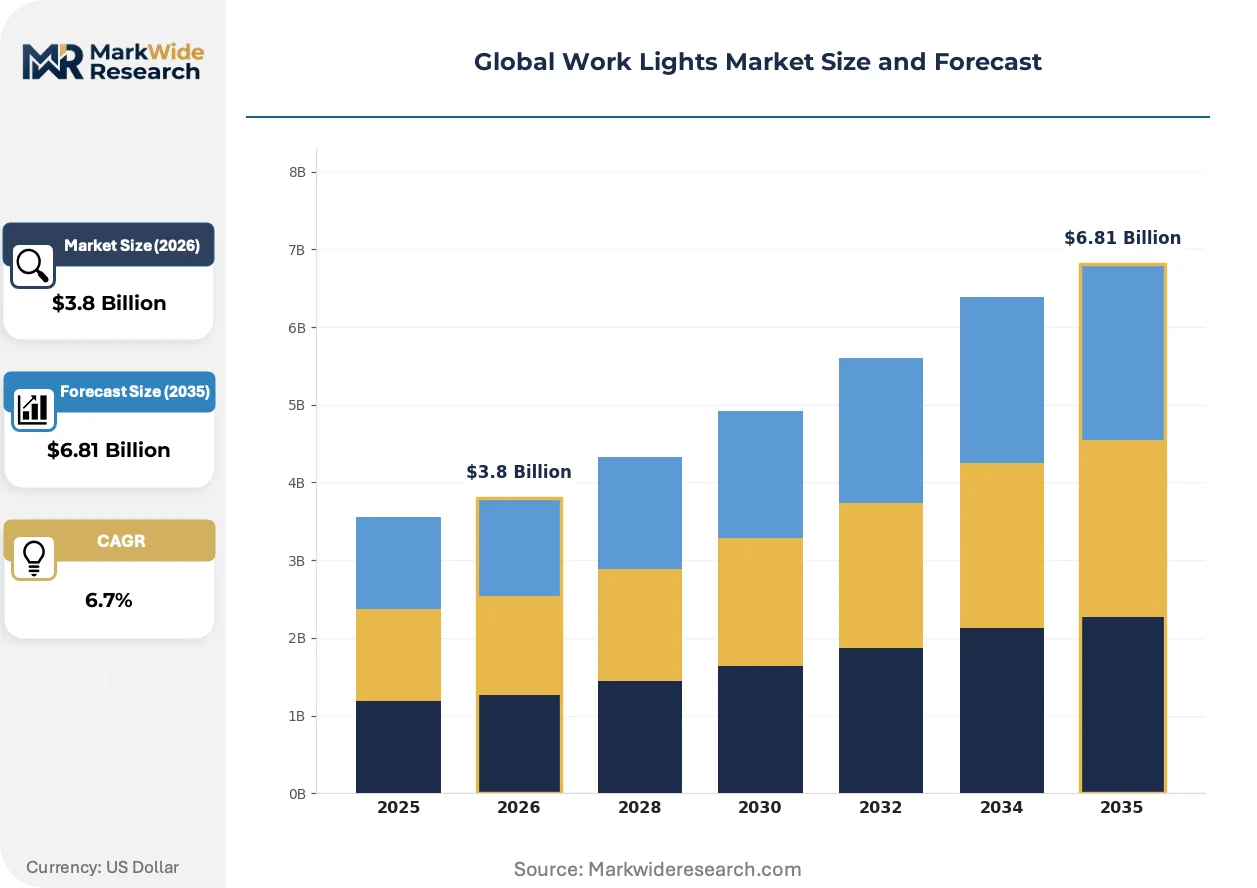
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: LED, Halogen, Fluorescent, HID, Incandescent Application: Construction Sites, Mining Operations, Emergency Services, Film Production, Agricultural Fields Mounting Style: Tripod, Handheld, Magnetic Base, Clamp-On, Wall-Mounted End User: Contractors, Utility Providers, Event Organizers, Public Works, Surveyors |
| Companies Covered | Bayco Products, Signify, Stanley Black & Decker, Techtronic Industries, Cooper Industries, Larson Electronics, Streamlight, Eaton, Luceco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Work Lights Market Shifts & Advancements
Active power management and spectral tuning are redefining performance benchmarks, shifting buyer evaluation from raw lumen output to task-appropriate illuminance quality and operational runtime.
Chip-on-board LED arrays with ceramic substrates are displacing discrete SMD packages in high-output portable fixtures. Oilfield services contractors in Texas and Alberta specify these designs for thermal stability in ambient temperatures exceeding 50°C. The technology is displacing conventional metal-core PCB assemblies that suffer solder joint fatigue under thermal cycling.
ECHA REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing housing material transitions from conventional ABS to glass-filled polyamide compounds. German industrial luminaire manufacturers face reformulation costs and supply base qualification delays. The regulation most affects explosion-proof enclosure suppliers serving North Sea offshore platforms.
Rental and leasing models for temporary site lighting are gaining traction among European construction consortiums managing multi-year infrastructure contracts. Equipment service firms in France and the Netherlands now bundle fixture deployment with maintenance and compliance documentation. This pattern is most visible in German wind farm construction, where project durations exceed standard product depreciation cycles.
Global Work Lights Market Segmentation
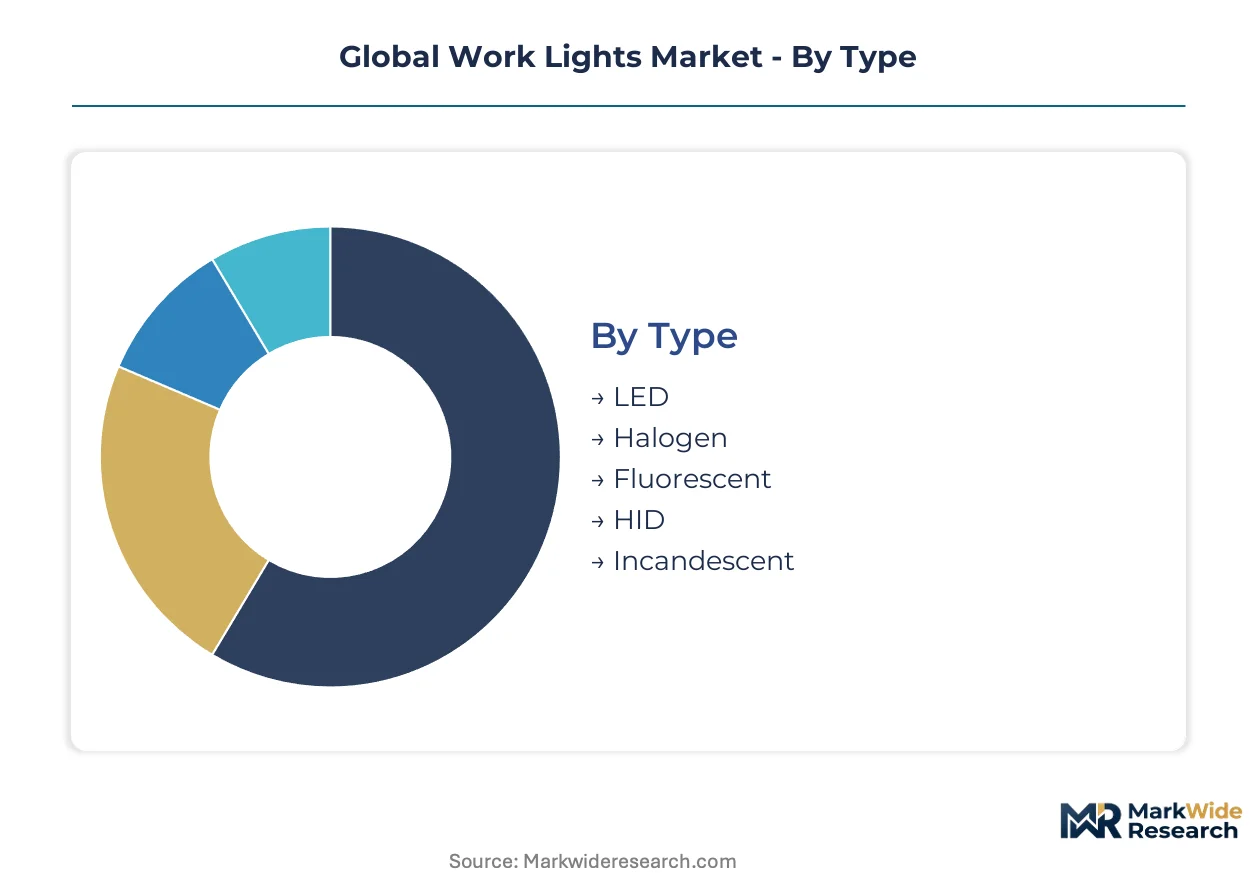
Work lights manufacturers configure product portfolios across four intersecting dimensions. Type and mounting style decisions determine thermal engineering and power architecture, while application and end-user targeting shape certification requirements and distribution channel selection.
Type:
LED sources dominate domestic manufacturing footprints across Germany, China, and the United States, while halogen and HID production concentrates in export-oriented facilities serving price-sensitive emerging markets.
- LED:Chip-on-board arrays with ceramic substrates deliver 150+ lumens per watt efficacy. Construction contractors in Texas and Alberta specify these for ambient temperatures exceeding 50°C where thermal stability determines runtime reliability.
- Halogen:Tungsten-halogen filaments provide instant full output without warm-up delay. Small commercial buyers in India and Southeast Asia sustain demand where capital constraints outweigh operating cost considerations.
- Fluorescent:Linear tube configurations retain niche presence in fixed workshop installations requiring diffuse, shadow-minimized illumination across large surface areas.
- HID:High-intensity discharge metal halide and sodium vapor systems persist in mining operations where lumen density per fixture outweighs energy efficiency priorities.
- Incandescent:Legacy tungsten filament technology survives only in specialized film production applications requiring specific color rendering characteristics unavailable from solid-state sources.
LED holds the largest share; momentum sits with chip-on-board configurations displacing conventional metal-core PCB assemblies.
Application:
Volume concentration varies sharply by project duration and regulatory exposure, with long-cycle infrastructure work favoring rental models and emergency response demanding outright purchase.
- Construction Sites:Temporary illumination for building, highway, and energy infrastructure projects. German wind farm developments drive specification for IP65+ portable fixtures with multi-year depreciation alignment.
- Mining Operations:Underground and open-pit extraction sites require explosion-proof certification. ATEX compliance mandates in European petrochemical and mining sectors create captive demand for specialized enclosure designs.
- Emergency Services:Fire, rescue, and disaster response units prioritize rapid deployment and battery autonomy. NFPA compliance requirements in the United States support premium pricing for certified portable units.
- Film Production:Cinematic and broadcast applications demand precise color temperature control and flicker-free output for high-frame-rate capture.
- Agricultural Fields:Seasonal harvesting and livestock operations in the United States Midwest and Australian grain belts utilize ruggedized fixtures for extended nighttime work periods.
Construction Sites command the greatest volume; Emergency Services deliver the steepest expansion trajectory as climate-related disaster response budgets climb.
Mounting Style:
Price tier stratification runs from sub-$20 handheld units through $400+ tripod systems with integrated power management, with magnetic and clamp configurations occupying the mid-market.
- Tripod:Three-legged stands with telescoping masts and integrated battery compartments. Oilfield services contractors in North America specify these for stability in uneven terrain where generator tethering proves impractical.
- Handheld:Compact pistol-grip or lantern-form factors for personal task illumination. Law enforcement and utility field technicians in the United States drive rechargeable lithium-ion specifications.
- Magnetic Base:High-strength rare-earth magnet attachments for ferrous surface mounting. Automotive repair and metal fabrication shops favor these for hands-free positioning flexibility.
- Clamp-On:Spring-loaded or screw-adjustable clamps for temporary attachment to pipes, scaffolding, and vehicle doors. Event production crews utilize these for rapid repositioning during load-in and strike operations.
- Wall-Mounted:Permanent bracket installations for workshops, warehouses, and maintenance bays requiring fixed-position task lighting.
Tripod configurations generate the highest average selling prices; Handheld units are gaining share fastest as battery chemistry improvements extend cordless runtime expectations.
End User:
Procurement authority concentrates with contractors and utility providers specifying through distributor relationships, while public works and event organizers increasingly adopt rental and leasing arrangements.
- Contractors:General and specialty construction firms with OSHA-mandated illumination compliance obligations. United States infrastructure spending packages are accelerating replacement schedules for outdated halogen inventories.
- Utility Providers:Electric, gas, and telecommunications operators with emergency response and maintenance requirements. Lineworker safety protocols in Germany and Japan specify explosion-proof ratings for substation and vault entry.
- Event Organizers:Concert, festival, and corporate event producers with temporary power and lighting needs. European equipment service firms in France and the Netherlands now bundle fixture deployment with maintenance documentation.
- Public Works:Municipal and state agencies responsible for road maintenance, snow removal, and emergency infrastructure repair.
- Surveyors:Geomatics and construction layout professionals requiring precise visual conditions for measurement instrument operation.
Contractors represent the largest addressable base; Utility Providers show the strongest specification discipline driving premium product adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infrastructure stimulus programs and workplace safety mandates are reshaping procurement patterns across the largest construction economies. Contractors in industrialized markets face accelerated replacement cycles for legacy halogen inventories, while emerging economies prioritize cost-efficient LED adoption for new-build projects.
United States
OSHA enforcement of minimum foot-candle standards on construction sites drives systematic fixture replacement among general contractors. The Infrastructure Investment and Jobs Act channels federal spending toward highway and energy projects, expanding temporary lighting requirements. Houston and Midland-Odessa oilfield clusters generate concentrated demand for explosion-proof portable units with generator-free operation.
Germany
Wind farm construction in the North Sea and Baltic coastal zones sustains multi-year demand for IP65-rated tripod systems with depreciation-aligned leasing structures. ECHA REACH restrictions on short-chain chlorinated paraffins force housing material transitions from ABS to glass-filled polyamide compounds. Industrial luminaire manufacturers in Bavaria and North Rhine-Westphalia absorb reformulation costs while qualifying new polymer supply bases.
China
GB standards for luminaire safety and the national dual carbon goals accelerate LED displacement of halogen in domestic construction. Rare earth processing concentration in Inner Mongolia and Jiangxi creates input cost volatility for high-efficiency LED driver assemblies. Shenzhen and Dongguan electronics manufacturing clusters dominate chip-on-board LED array production for export markets.
India
National highway and metro rail expansion under the PM Gati Shakti initiative generates demand for ruggedized temporary lighting with localized voltage tolerance. BIS certification requirements for electrical equipment create compliance barriers for uncertified imports. Mumbai and Delhi construction corridors concentrate volume procurement through contractor-distributor relationships.
Japan
METI efficiency standards and industrial facility modernization programs support premium LED adoption in manufacturing maintenance applications. JIS standards for portable electrical equipment shape product specifications for domestic suppliers. Osaka and Nagoya industrial zones drive specification discipline for explosion-proof fixtures in petrochemical and semiconductor cleanroom environments.
Global Work Lights Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and channel control. The vendor base stratifies into three tiers: diversified electrical conglomerates with captive LED supply chains, mid-scale specialists focused on hazardous-environment certifications, and regional assemblers serving price-sensitive replacement demand. Strategic moves concentrate on backward integration into LED component sourcing and geographic expansion through distributor acquisition in high-growth construction corridors.
Within the certification-specialist tier, Larson Electronics and Bayco Products exemplify divergent positioning strategies. Larson Electronics anchors explosion-proof fixture specifications for oilfield and petrochemical buyers through ATEX and NFPA compliance depth. Bayco Products occupies a position in rechargeable handheld segments sustained by direct law-enforcement and utility procurement relationships. Signify represents the conglomerate archetype, leveraging Lumileds captive LED supply to control component costs across European project channels.
| Leading Market Players |
|---|
| Bayco Products |
| Signify |
| Stanley Black & Decker |
| Techtronic Industries |
| Cooper Industries |
| Larson Electronics |
| Streamlight |
| Eaton |
| Luceco |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day LED driver lead times from Shenzhen suppliers compress margin flexibility for European assemblers while amplifying pricing power for chip-on-board array manufacturers with captive ceramic substrate capacity. This inventory tension concentrates cost pressure on mid-tier portable fixture producers without backward integration into LED sourcing.
Pricing Analysis
Certification level creates the primary spread across the work lights market, with ATEX and NFPA compliance adding substantial premiums over standard IP65 units. Three-tier pricing structure across premium explosion-proof, standard industrial-grade, and economy halogen levels reflects differential testing burden and liability exposure. Cost compression in handheld rechargeable segments is intensifying because lithium-ion cell commoditization erodes battery pack differentiation. Small commercial buyers in India and Southeast Asia exhibit highest price sensitivity, while oilfield contractors in Texas and Alberta show lowest sensitivity due to safety-specification rigidity.
Supply Chain Analysis
Forty-five-day raw material inventory cycles at Dongguan assembly plants expose the work lights supply chain to rare earth magnet price volatility from Inner Mongolia processing clusters. Production concentrates in China, Germany, and the United States, with chip-on-board LED arrays drawing from Jiangxi rare earth deposits and Bavarian ceramic substrate specialists. Single-source vulnerability sits with neodymium-dysprosium processing concentration. Distribution runs through industrial distributor networks in North America and direct contractor relationships in European wind farm corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated European construction consortiums with multi-year infrastructure contracts, fragmenting procurement authority away from single-project contractors. This consolidation demands volume-commitment pricing and bundled service offerings from suppliers.
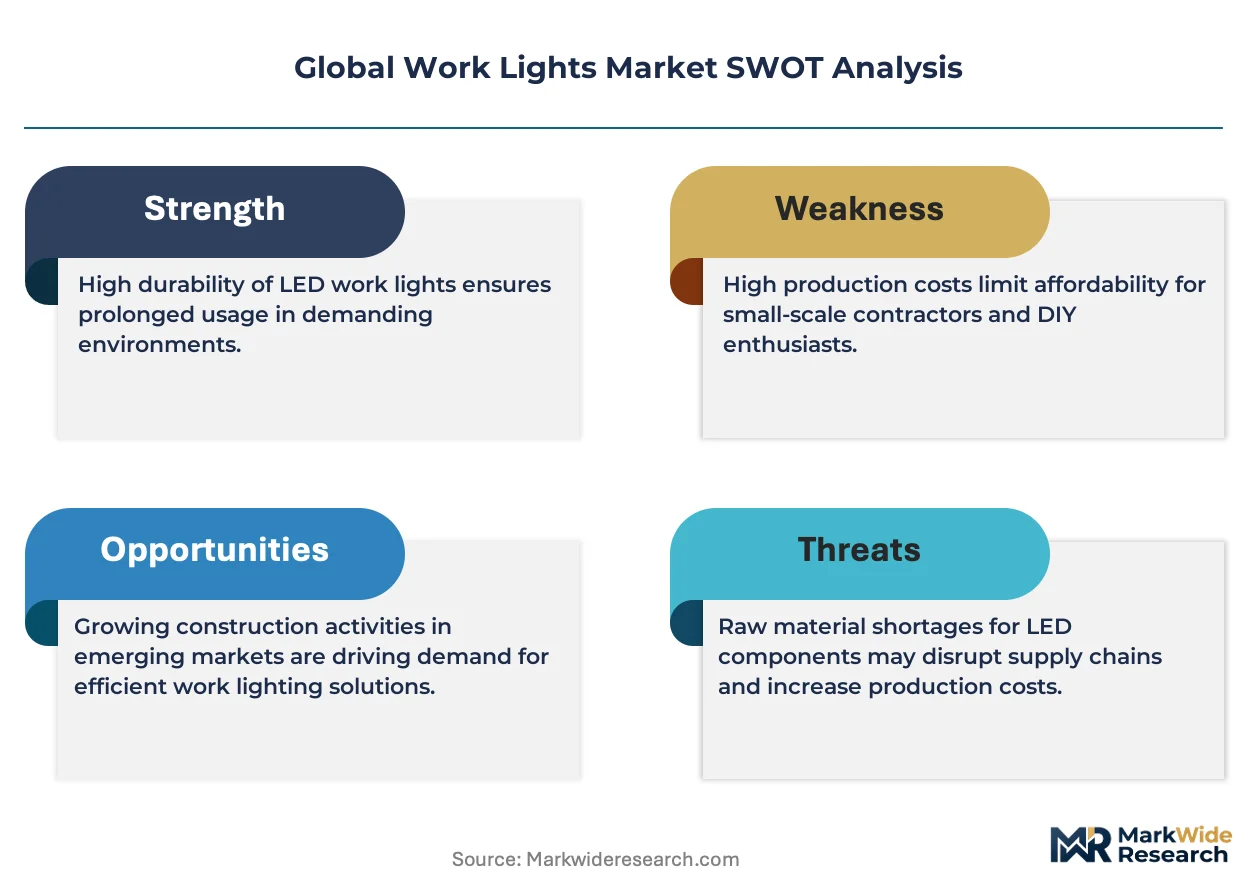
For Market Incumbents: Shield certification depth as the primary defensive moat by accelerating IEC 62471 photobiological safety validation for high-lumen arrays. Prioritize backward integration into ceramic substrate sourcing to offset rare earth cost volatility from Chinese processing clusters. Channel control through distributor acquisition in German wind farm and Texas oilfield corridors reinforces specification capture against emerging LED-native competitors. For New Entrants and Emerging Players: Differentiate on smart connectivity integration as the entry axis, targeting Japanese and German industrial facilities with Bluetooth mesh and DALI-2 protocol compatibility. The most penetrable white space sits in India's PM Gati Shakti highway and metro projects, where localized voltage tolerance requirements favor agile assemblers over legacy multinational inventories. A rental-and-service bundling go-to-market angle bypasses capital-constrained contractor procurement cycles. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance compounder play because OSHA, ATEX, and ECHA REACH mandates create recurring replacement demand with limited technology substitution risk. Acquisition targets should display captive LED supply chain relationships or hazardous-environment certification depth rather than pure assembly scale. The signal to watch is F-Gas Regulation enforcement timelines forcing HID-to-LED conversion velocity in European industrial accounts.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | ATEX and NFPA compliance depth locks in oilfield and petrochemical specification capture against uncertified competitors. |
| Backward Integration | Captive ceramic substrate and LED chip sourcing insulates margin from rare earth processing volatility in China. |
| Rental Model Expansion | Equipment-service bundling aligns with European construction consortium depreciation cycles and compliance documentation needs. |
| Smart Connectivity Integration | Bluetooth mesh and DALI-2 protocol adoption opens Japanese and German industrial facility centralized zone control budgets. |
| Geographic Distributor Acquisition | Channel control in Houston-Midland and North Sea wind corridors secures specification influence with concentrated buyer clusters. |
Research Methodology
Operator-level perspectives from construction procurement managers, oilfield safety officers, industrial distributor principals, and lighting specification engineers anchored the qualitative base. These primary insights combined with secondary validation from OSHA enforcement records, ECHA REACH substance restriction filings, GB standards documentation, and customs trade data for LED fixture imports. Bottom-up demand modeling across contractor replacement cycles and top-down supply analysis through chip-on-board LED production capacity triangulated volume estimates.
Sensitivity analysis tested forecast robustness across rare earth price volatility scenarios and regulatory enforcement timing variations. Segmentation dimensions modeled include light source technology, mounting configuration, application environment, and end-user procurement authority across the projection horizon. CAGRs derived from fitted trend extrapolation against historical replacement cycle data and infrastructure spending correlation analysis. Industry-specific inputs incorporated lithium-ion energy density improvement curves and photobiological safety certification timeline assumptions.
The analysis sits within stated boundaries; outcomes outside sustained OSHA enforcement intensity or accelerated EU F-Gas phase-down timelines would require recalibration. Forecasts reflect documented assumptions regarding LED efficacy improvement rates and rare earth supply concentration persistence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Saudi Arabia Smart Lighting Market
Lighting
Tritium Light Source Market
Lighting
Solar Rope Light Market
Lighting
Europe Decorative Lighting Market
Lighting
Art and Museum Lighting Market
Lighting
Solid State Lighting System Market
Lighting
Lighting Management System Market
Lighting
Global Plasma Lamp Market
Lighting
Bacteriological Light Market
Lighting
Solar Column Headlight Market
Lighting
Lighting Product Market
Lighting
Smart Industrial Illumination Market
Lighting
Global Commercial Lighting Market
Lighting
Hazardous Lighting Market
Lighting
Explosion Proof Lighting Market
Lighting
Directional Luminaire Market