
 Malaysia LED Lighting Controllers Market | 2026-2036
Malaysia LED Lighting Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia LED Lighting Controllers Market Outlook
Malaysia's domestic electronics manufacturing belt is fragmenting as LED controller assembly spreads from Penang to Johor Bahru industrial zones. Philips Lighting Malaysia leverages its Penang-based R&D facility to sustain technology leadership in DMX protocol integration. Schneider Electric Malaysia anchors its position through deep channel control across building automation integrators. Signify Malaysia competes aggressively on manufacturing scale, operating one of Southeast Asia's largest lighting component plants in Shah Alam.
LED lighting controllers are electronic devices that regulate power delivery, color temperature, and dimming curves across solid-state lighting installations, typically managing outputs from milliamps to multiple amperes through PWM or analog signal processing. These controllers serve as the command layer between sensors, user interfaces, and luminaire drivers in commercial and architectural environments. Wi-Fi controllers lead residential and small commercial deployments where existing network infrastructure eliminates dedicated gateway costs. Zigbee controllers capture premium commercial projects requiring mesh reliability across large floorplates with hundreds of nodes. DMX controllers dominate theatre and entertainment venues where precise multi-channel synchronization demands deterministic latency performance.
Malaysia's Energy Commission enforces Minimum Energy Performance Standards that disqualify standalone non-dimmable fixtures from new commercial construction, directly expanding addressable controller demand. SIRIM QAS International administers product certification under MS IEC standards, creating compliance barriers for uncertified imports while privileging established local assemblers. BEE certification requirements for smart building components are tightening ahead of the national net-zero pathway. Stakeholders must monitor how Bumiputera procurement quotas in government infrastructure projects reshape competitive access to public sector lighting contracts.
Market Dynamics
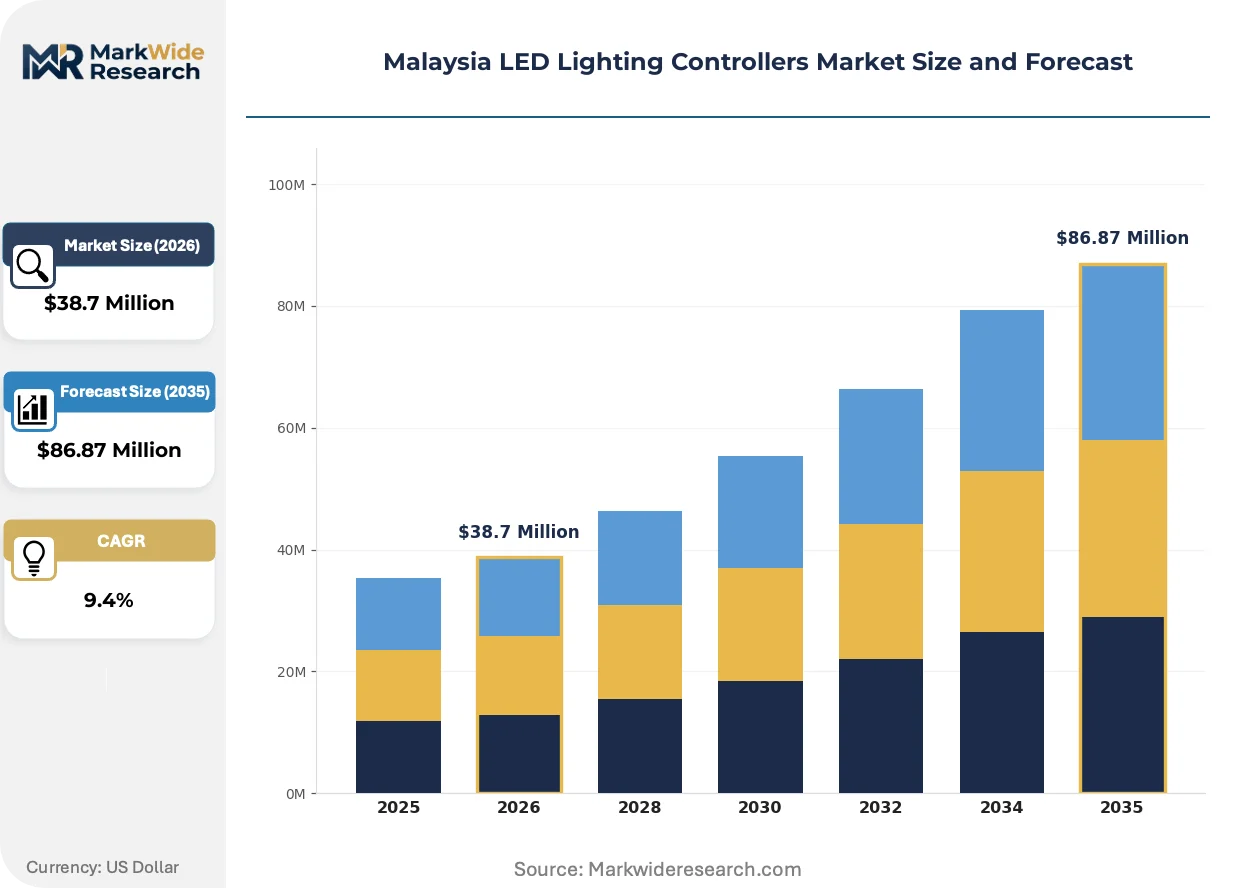
Malaysia's LED controller market is compressing around the Energy Commission's MEPS enforcement timeline, which disqualifies non-dimmable fixtures from new commercial builds and forces facility managers into accelerated procurement cycles.
Growth Catalysts
- Klang Valley Development Pipeline:Mixed-use towers across Kuala Lumpur and Petaling Jaya specify networked lighting management platforms as standard fit-outs, creating baseline demand for DALI and Zigbee controllers.
- MEPS Standards Expansion:The Energy Commission's Minimum Energy Performance Standards now mandate dimming capability for all commercial fixtures above specified lumen outputs, directly expanding addressable controller volume.
- Wi-Fi Infrastructure Leverage:Existing enterprise wireless networks in Malaysian SMEs eliminate dedicated gateway procurement, lowering adoption barriers for cloud-managed lighting systems.
Market Restraints
- Semiconductor Input Volatility:Controller manufacturing depends on PMIC and MCU supply chains concentrated in Taiwan and mainland China, exposing Malaysian assemblers to lead-time fluctuations.
- SIRIM Certification Bottlenecks:MS IEC testing protocols administered by SIRIM QAS International create six-to-twelve month approval windows for new controller SKUs, delaying product launches.
- Legacy Fluorescent Stockpiles:Commercial building operators in secondary cities retain functional magnetic ballast installations, deferring controller-enabled LED retrofits.
Strategic Opportunities
- Johor Bahru Industrial Zone:Manufacturing facility greenfield builds across Iskandar Malaysia specify integrated building management systems, opening controller bundling opportunities with HVAC and security vendors.
- Bumiputera Procurement Quotas:Government infrastructure contracts reserve tender access for majority-Malay-owned firms, creating partnership pathways for technology licensors seeking public sector penetration.
- DMX-IoT Convergence:Entertainment venue operators seek unified platforms managing both theatrical lighting and facility-wide energy monitoring, collapsing previously separate procurement categories.
Industry Challenges
- Embedded Firmware Talent Scarcity:Malaysian universities produce limited graduates with Zigbee stack and PWM driver programming expertise, forcing controller manufacturers into expensive Singaporean or expatriate hiring.
- Multi-Protocol Integration Complexity:Facility managers demand seamless coexistence of DALI, DMX, and wireless mesh networks, requiring controller vendors to maintain expensive interoperability testing labs.
- BEE Certification Timelines:The national Building Energy Efficiency labeling scheme imposes documentation burdens on smart lighting component suppliers, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia LED Lighting Controllers Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $86.87 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Controller Type: Wi-Fi Controllers, Zigbee Controllers, DMX Controllers, Bluetooth Controllers Application: Residential Lighting, Commercial Lighting, Architectural Lighting, Theatre Lighting Power Rating: Low Power, Medium Power, High Power, Ultra-High Power Distribution Channel: Online Retail, Direct Sales, Distributor, Installer |
| Companies Covered | Lutron Electronics, Acuity Brands, Philips Lighting Malaysia, Eaton Corporation, ABB Malaysia, Schneider Electric Malaysia, Osram Malaysia, Legrand Malaysia, Signify Malaysia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia LED Lighting Controllers Market Strategic Shifts
Digital control architectures are displacing analog dimming circuits across Malaysian commercial installations, compressing hardware margins while expanding software and service revenue pools for ecosystem vendors.
Power-over-Ethernet lighting controllers are digitizing luminaire management by delivering both DC power and data through standard CAT6 cabling. Large-format office developers in Petaling Jaya and Cyberjaya specify PoE-native fixtures for new builds, eliminating separate electrical and control contractor coordination. This convergence is digitizing procurement patterns by collapsing lighting, IT infrastructure, and building automation into single vendor relationships.
Malaysia's Energy Commission is tightening MEPS enforcement through scheduled compliance audits of commercial buildings above specified floor areas. Facility operators failing efficiency benchmarks face operational restrictions, accelerating controller retrofits in aging stock. The policy is reshaping distributor inventories, with electrical wholesalers in Shah Alam and Penang prioritizing dimmable driver-controller bundles over standalone fixtures.
Building operators are consolidating lighting procurement under integrated facilities management contracts rather than discrete capital expenditure approvals. Property management firms including those servicing KLCC and Mid Valley commercial portfolios now specify performance-based lighting service agreements. This shift is most visible in Grade A office towers where annual lux-level guarantees replace traditional equipment ownership models.
Malaysia LED Lighting Controllers Market Segmentation
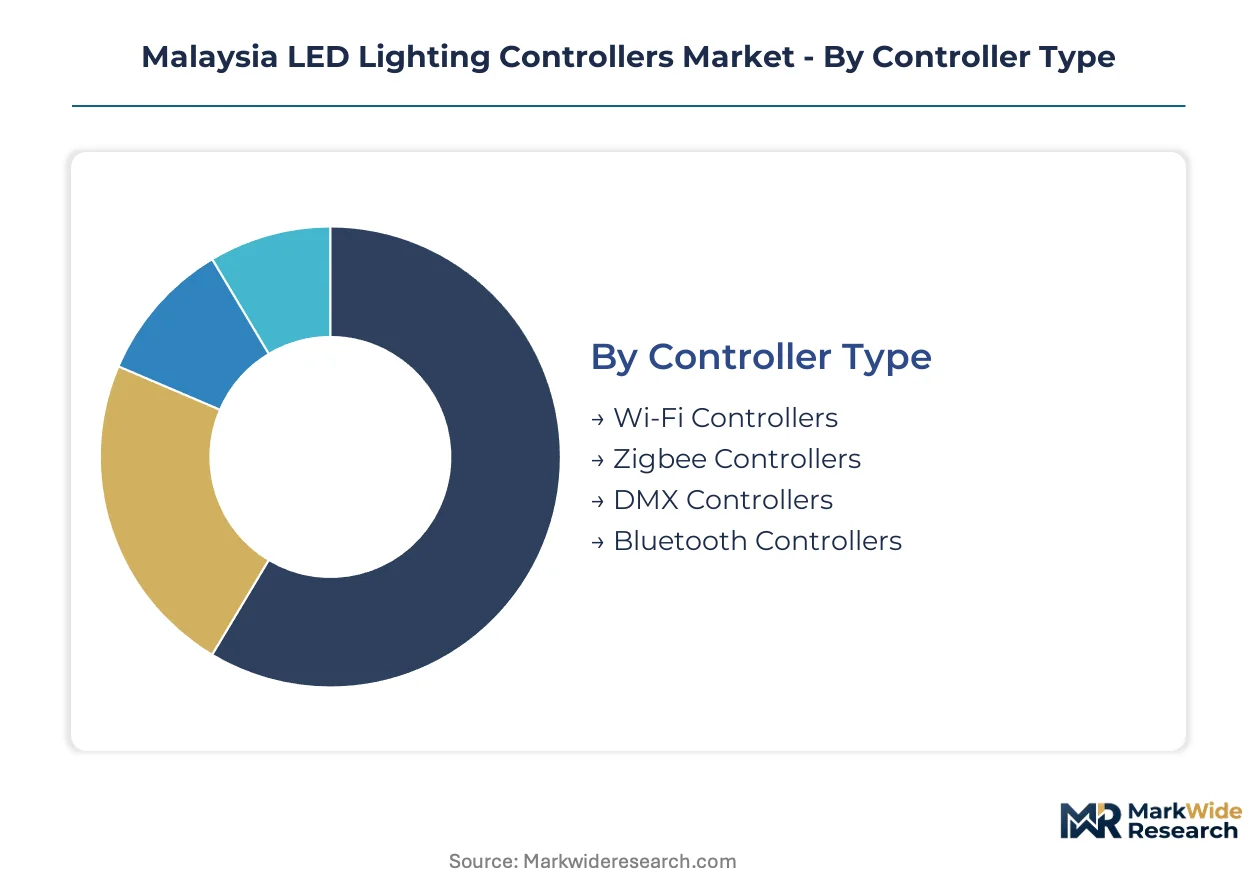
Malaysia's LED controller market fragments across protocol standards, power architectures, and procurement pathways. Each dimension carries distinct margin profiles and replacement cadences that reshape vendor positioning.
Controller Type:
Cycle times diverge sharply across protocol ecosystems, with consumer-grade wireless platforms refreshing every 18-24 months while industrial DMX installations persist for 7-10 years.
- Wi-Fi Controllers:These units leverage existing enterprise infrastructure to eliminate gateway costs, typically handling 2.4GHz and 5GHz bands with cloud-native management stacks. Malaysian SMEs in Selangor and Penang favor these for rapid deployment without dedicated IT integration. SIRIM certification delays often compress product lifecycles before market exit.
- Zigbee Controllers:Mesh networking architectures deliver sub-50ms latency across 500+ node floorplates, essential for Klang Valley Grade A office towers. The Energy Commission's MEPS audits are accelerating specification of these controllers in new commercial builds where reliability failures trigger operational penalties.
- DMX Controllers:Deterministic 512-channel protocols dominate Istana Budaya and Petronas Philharmonic Hall installations where frame-accurate synchronization is non-negotiable.
- Bluetooth Controllers:Point-to-point architectures serve residential retrofits in Mont Kiara and Damansara Heights where smartphone-native control eliminates wall-switch rewiring.
Wi-Fi controllers anchor the volume base while Zigbee controllers gain share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive commercial specifications from price-sensitive residential procurement, with architectural and theatrical segments commanding 3-4x hardware premiums.
- Residential Lighting:Single-room dimming and color-temperature adjustment for landed properties and high-rise condominiums. Johorean developers in Iskandar Malaysia specify these in mass-market housing projects where buyer price elasticity limits controller budgets.
- Commercial Lighting:Networked management platforms for office towers, retail malls, and hospitality venues across Kuala Lumpur's Golden Triangle. The shift toward integrated facilities management contracts is collapsing equipment ownership into performance-based service agreements.
- Architectural Lighting:Façade and landscape illumination for KLCC, Putrajaya government complexes, and Penang heritage restorations requiring weatherized IP67+ enclosures.
- Theatre Lighting:Precision multi-scene control for performing arts venues where cue-to-cue reliability failures are commercially catastrophic.
Commercial lighting absorbs the largest absolute spend while architectural applications deliver the highest per-unit margins.
Power Rating:
Supply concentration intensifies at higher wattages, with ultra-high power controllers depending on discrete semiconductor inputs that Malaysian assemblers source exclusively from Taiwanese foundries.
- Low Power:Sub-50W units for residential downlights and decorative fixtures, typically integrating PWM dimming at 1-10V or phase-cut protocols. These dominate Shah Alam distributor inventories where electrical contractors purchase in 500-unit lots.
- Medium Power:50-200W drivers for commercial panel and troffer installations across Petaling Jaya office parks. MEPS compliance mandates are forcing rapid displacement of magnetic ballast equivalents in this bracket.
- High Power:200-500W architectures for industrial high-bay and floodlight applications in Johor Bahru manufacturing zones.
- Ultra-High Power:500W+ systems for stadium and infrastructure illumination requiring active thermal management and redundant driver channels.
Medium power controllers generate the broadest revenue base while ultra-high power units face the most severe lead-time volatility.
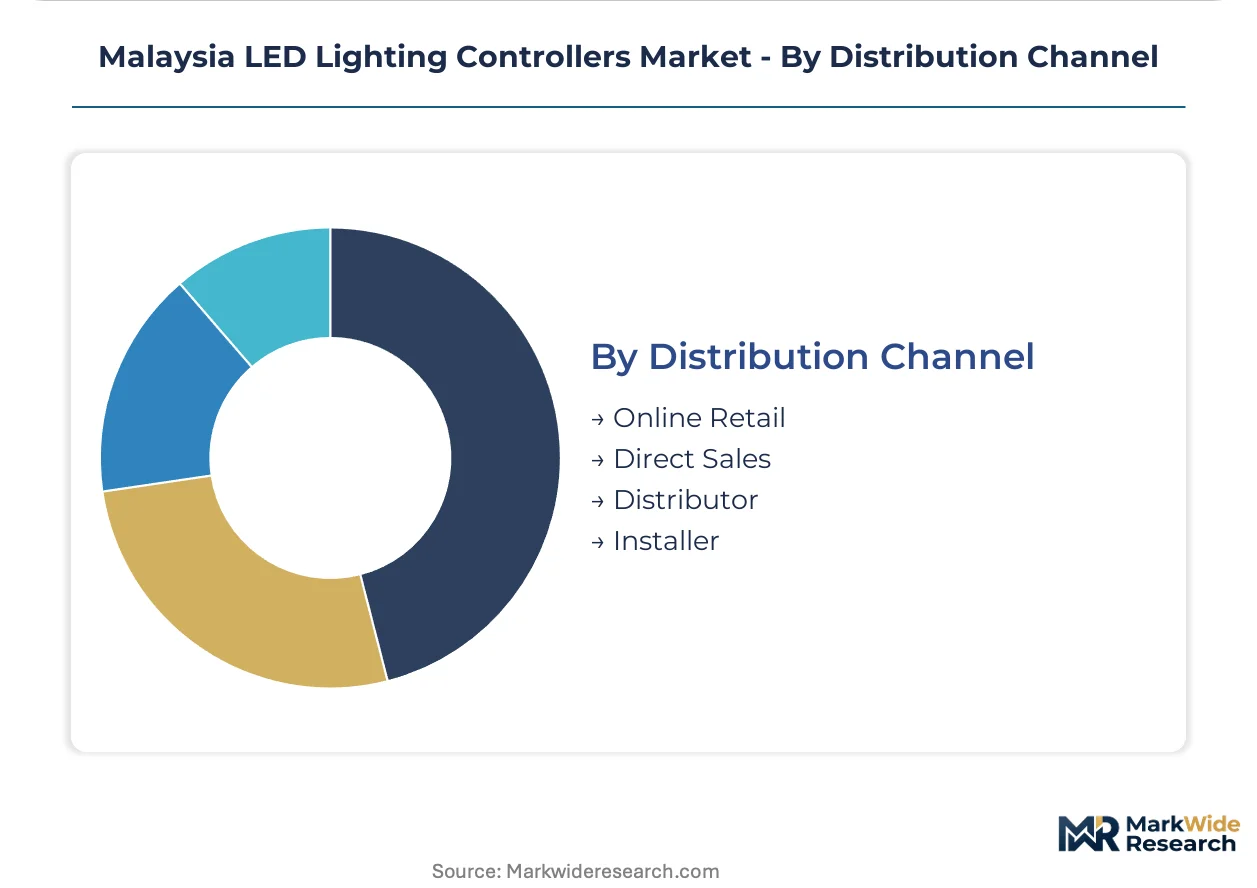
Distribution Channel:
Customer type fragmentation separates specification-driven direct procurement from transactional retail, with installer channels capturing the highest attach rates for commissioning services.
- Online Retail:E-commerce platforms including Lazada and Shopee serve DIY residential buyers in urban centers, though SIRIM certification visibility remains inconsistent across marketplace listings.
- Direct Sales:Manufacturer-led specification for large developers and government tenders, particularly Bumiputera-quota projects requiring local partnership structures.
- Distributor:Electrical wholesalers in Penang and Selangor maintain physical inventory for contractor walk-in trade, with MEPS-compliant bundles displacing standalone fixture sales.
- Installer:Certified electrical contractors who specify, procure, and commission controller systems, capturing recurring maintenance contracts in commercial portfolios.
Distributor channels move the highest unit volumes while installer relationships secure the longest revenue tails through service attach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian controller assembly concentrates in Penang and Johor Bahru industrial zones, with demand clustering in the Klang Valley corridor where Kuala Lumpur's commercial tower pipeline drives specification intensity.
Klang Valley
Mixed-use developments across Kuala Lumpur and Petaling Jaya mandate networked lighting management platforms as baseline fit-outs. The Energy Commission's MEPS enforcement compels facility managers into accelerated retrofit procurement cycles. Grade A office towers in KLCC and Mid Valley portfolios specify performance-based service agreements rather than equipment ownership.
Penang
Electronics manufacturing heritage supports controller R&D and assembly operations serving both domestic and export markets. SIRIM QAS International certification protocols administered from Selangor create compliance barriers privileging established local assemblers. Bayan Lepas industrial zones host technology licensing partnerships with multinational lighting vendors.
Johor Bahru
Iskandar Malaysia greenfield manufacturing facilities specify integrated building management systems bundling lighting with HVAC and security controls. Bumiputera procurement quotas in government infrastructure contracts reshape competitive access for technology licensors seeking public sector penetration. Pasir Gudang industrial corridors drive high-bay and floodlight controller demand.
East Malaysia
Secondary city commercial operators in Kuching and Kota Kinabalu retain functional magnetic ballast installations, deferring controller-enabled LED retrofits. Federal infrastructure spending on government complexes accelerates specification of architectural lighting controllers for façade and landscape illumination. Local electrical wholesalers prioritize MEPS-compliant dimmable driver bundles over standalone fixtures.
Malaysia LED Lighting Controllers Market Competitive Environment
Multinational technology licensors and domestic assembly specialists split the market across distinct value-capture tiers. The vendor structure concentrates around building automation integrators and electrical distribution channels rather than direct end-user relationships. Three archetypes dominate: global lighting conglomerates leveraging manufacturing scale, regional automation specialists bundling controllers into broader building management portfolios, and local assemblers exploiting Bumiputera procurement preferences. Competitive dynamics center on SIRIM certification speed and channel control depth rather than pure price positioning.
Within the multinational tier, Philips Lighting Malaysia and Schneider Electric Malaysia occupy positions reflecting divergent strategic emphases. Signify Malaysia anchors the manufacturing-scale vector through its Shah Alam production footprint. These entities exemplify how technology leadership and channel architecture separate premium positioning from commodity assembly competition.
| Leading Market Players |
|---|
| Lutron Electronics |
| Acuity Brands |
| Philips Lighting Malaysia |
| Eaton Corporation |
| ABB Malaysia |
| Schneider Electric Malaysia |
| Osram Malaysia |
| Legrand Malaysia |
| Signify Malaysia |
| Others |
Value Chain & Pricing Dynamics
Taiwanese PMIC and MCU foundries concentrate upstream supply for Malaysian LED controller assemblers, compressing margin capture at the Penang and Johor Bahru manufacturing nodes while shifting value pools toward SIRIM-certified brands with channel control.
Pricing Analysis
Malaysia's Energy Commission MEPS standards dictate the pricing tier structure across the LED controller market, separating SIRIM-certified premium controllers from uncertified economy imports. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Pricing pressure stems from semiconductor input volatility and compressed hardware margins in Wi-Fi controller segments. Residential buyers in Iskandar Malaysia mass housing projects exhibit highest price sensitivity, while Grade A office developers in KLCC demonstrate lowest elasticity due to operational penalty risks under MEPS audits.
Supply Chain Analysis
Upstream feedstock for Malaysian controller manufacturing draws from Taiwanese semiconductor foundries, Chinese passive component suppliers, and South Korean display driver specialists. Critical inputs include power management ICs, ARM-core microcontrollers, and GaN switching elements. Single-source vulnerability concentrates in Taiwan-based MCU supply, exposing Shah Alam assemblers to lead-time volatility. Distribution runs through electrical wholesalers in Penang and Selangor, with certified installer channels capturing recurring service revenue in commercial portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where SIRIM certification entrenchment and MEPS compliance switching costs protect incumbent positions against price-based disruption.
For Market Incumbents: Build certification moats by accelerating MS IEC pre-testing investments ahead of SKU launches, compressing six-to-twelve month SIRIM windows. Deepen channel control across building automation integrators to capture bundling opportunities with HVAC and security vendors. Counter Zigbee firmware talent scarcity through Singaporean R&D partnerships or expatriate technical hiring.
For New Entrants and Emerging Players: Build out Bumiputera partnership structures to access government infrastructure quotas in Putrajaya and East Malaysia federal complexes. Target secondary city commercial operators in Kuching and Kota Kinabalu where legacy fluorescent stockpiles delay incumbent retrofit capture. Pursue DMX-IoT convergence opportunities in entertainment venues seeking unified theatrical and facility management platforms.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional automation specialists bundling controllers into broader building management portfolios. Long-term viability hinges on software and service revenue migration as hardware margins compress across the projection horizon. Monitor Johor Bahru industrial zone greenfield specifications as inflection signal for integrated system demand.
| Strategic Initiative | Industry Significance |
|---|---|
| SIRIM Certification Acceleration | Compresses approval timelines from twelve to six months, privileging established assemblers over import competitors. |
| Zigbee Stack R&D Investment | Addresses firmware talent scarcity through captive programming capabilities for mesh network deployments. |
| Bumiputera Partnership Structuring | Unlocks tender access to government infrastructure contracts under Malay-ownership procurement quotas. |
| PoE-Native Controller Development | Captures Petaling Jaya and Cyberjaya office developer demand for converged power-data infrastructure. |
| Installer Channel Certification Programs | Secures recurring maintenance revenue through certified commissioning relationships in commercial portfolios. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SIRIM QAS International certification databases, Energy Commission MEPS enforcement schedules, and customs import records for lighting electronics. Primary interviews encompassed facility managers at KLCC and Mid Valley commercial towers, electrical contractors across Selangor distributor networks, and procurement leads at Johor Bahru industrial developers. Secondary validation drew from BEE certification documentation, building automation integrator technical specifications, and semiconductor trade flow data. Bottom-up controller shipment estimates triangulated against top-down construction pipeline valuations across the Klang Valley corridor.
Forecast inputs span protocol type adoption curves, MEPS compliance timeline enforcement intensity, and Power-over-Ethernet penetration rates in new commercial builds. Segmentation dimensions include controller protocol standard, power rating tier, application vertical, and distribution channel structure. CAGRs derived from weighted scenario analysis across conservative and accelerated MEPS enforcement pathways. Industry-specific inputs incorporate Bumiputera procurement quota policy stability and Taiwanese semiconductor supply lead-time assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive certification pre-investment by emerging assemblers or sudden MEPS timeline acceleration would shift outcomes materially. Cross-checking against Iskandar Malaysia industrial development permit filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
Gesture Control Light Market
Lighting
Vintage Bulb Market
Lighting
Smart Lamp Market
Lighting
Wireless Lighting Market
Lighting
Portable Lamps Market
Lighting
Bacteriological Light Market
Lighting
Smart Lighting Market
Lighting
Photography Light Box Market
Lighting
Street Lighting Market
Lighting
Germany Indoor LED Lighting Market
Lighting
Street and Roadway Lighting Market
Lighting
Dimmers Market
Lighting
COB Photo Light Market
Lighting
Europe Lighting Control Systems Market
Lighting
Bulb Market