
 North America Seed Coating Materials Market | 2026-2036
North America Seed Coating Materials Market Size, Share, and Industry Trends Forecast 2026-2036
North America Seed Coating Materials Market Analytics
Agricultural input distribution is fragmenting across North America as seed companies, cooperatives, and direct-to-farm channels compete for grower relationships. Corteva Agriscience leverages its integrated seed and trait pipeline to bundle coating services with proprietary genetics. Syngenta AG anchors its position through crop protection cross-selling into seed treatment workflows. BASF SE competes on polymer innovation, particularly in controlled-release film coatings for nutrient delivery.
Seed coating materials encompass functional layers applied to seeds to enhance germination uniformity, protect against soilborne pathogens, and enable precision placement of agrochemicals. Polymer coatings typically comprise vinyl polymers, polyurethanes, or emerging bio-based formulations applied through rotary drum or fluidized bed processes at thicknesses of 1–5% by seed weight. Polymer Coatings dominate value capture due to recurring reformulation cycles and premium pricing for specialty film architectures. Agronomic Seeds generate the largest volume base, though Vegetable Seeds command higher per-unit coating values due to smaller seed sizes and intensive treatment protocols.
EPA regulates treated seeds under FIFRA and pesticide tolerance frameworks, while Health Canada/PMRA governs analogous registrations for the Canadian market. USDA and CFIA seed certification programs influence coating acceptance standards for interstate and cross-border commerce. Stakeholders must monitor evolving biopesticide registration pathways and state-level neonicotinoid restrictions that could redirect active ingredient selection in coating formulations.
Market Dynamics
EPA's evolving interpretation of treated article exemptions under FIFRA is compressing formulation timelines while state-level neonicotinoid bans in New York and Minnesota force active ingredient pivots in the US Corn Belt.
Growth Catalysts
- Neonicotinoid replacement chemistry:New York's Article 15 restrictions and Minnesota's pollinator protection rules accelerate investment in biological active ingredients for early-season pest management in soybean and corn systems.
- Canada's Prairie canola expansion:Health Canada/PMRA streamlined registration pathways for seed-applied fungicides support coated seed adoption across Saskatchewan and Manitoba as blackleg and clubroot pressure intensifies.
- Controlled-release polymer architectures:Film coatings enabling staggered nutrient delivery are pulling premium pricing from row crop producers seeking to reduce in-furrow fertilizer rates.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane and vinyl polymer coatings face margin compression when propylene and isocyanate prices spike, squeezing mid-tier formulators without long-term supply contracts.
- Midwest application service concentration:Commercial seed treaters in Iowa and Illinois control 60% of toll-coating capacity, creating bottlenecks during compressed spring planting windows.
- Cross-border registration divergence:EPA and Health Canada/PMRA tolerance mismatches for novel biological actives delay simultaneous US-Canada product launches by 18-24 months.
Strategic Opportunities
- Texas High Plains cotton:Underpenetrated coated seed adoption in West Texas offers expansion potential as thrips and seedling disease pressure mount in reduced-tillage systems.
- USDA Climate-Smart Commodities funding:Federal cost-share programs for nutrient use efficiency incentivize polymer-coated fertilizer integration into seed coating protocols for carbon credit eligibility.
- Direct-to-farm digital channels:E-commerce platforms and farm management software integrations enable coating service bypass of traditional cooperative distribution in the Corn Belt.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in bio-based polymer synthesis and active ingredient compatibility testing outpaces university pipeline output in the US Midwest.
- Seed lab certification backlogs:AOSA and SCST germination testing protocols for coated seed create 6-8 week delays during peak season, compressing inventory positioning.
- Legacy equipment retrofit costs:Fluidized bed and rotary drum treaters require $150,000-$400,000 upgrades to handle multi-layer film coatings, straining regional seed company capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Seed Coating Materials Market |
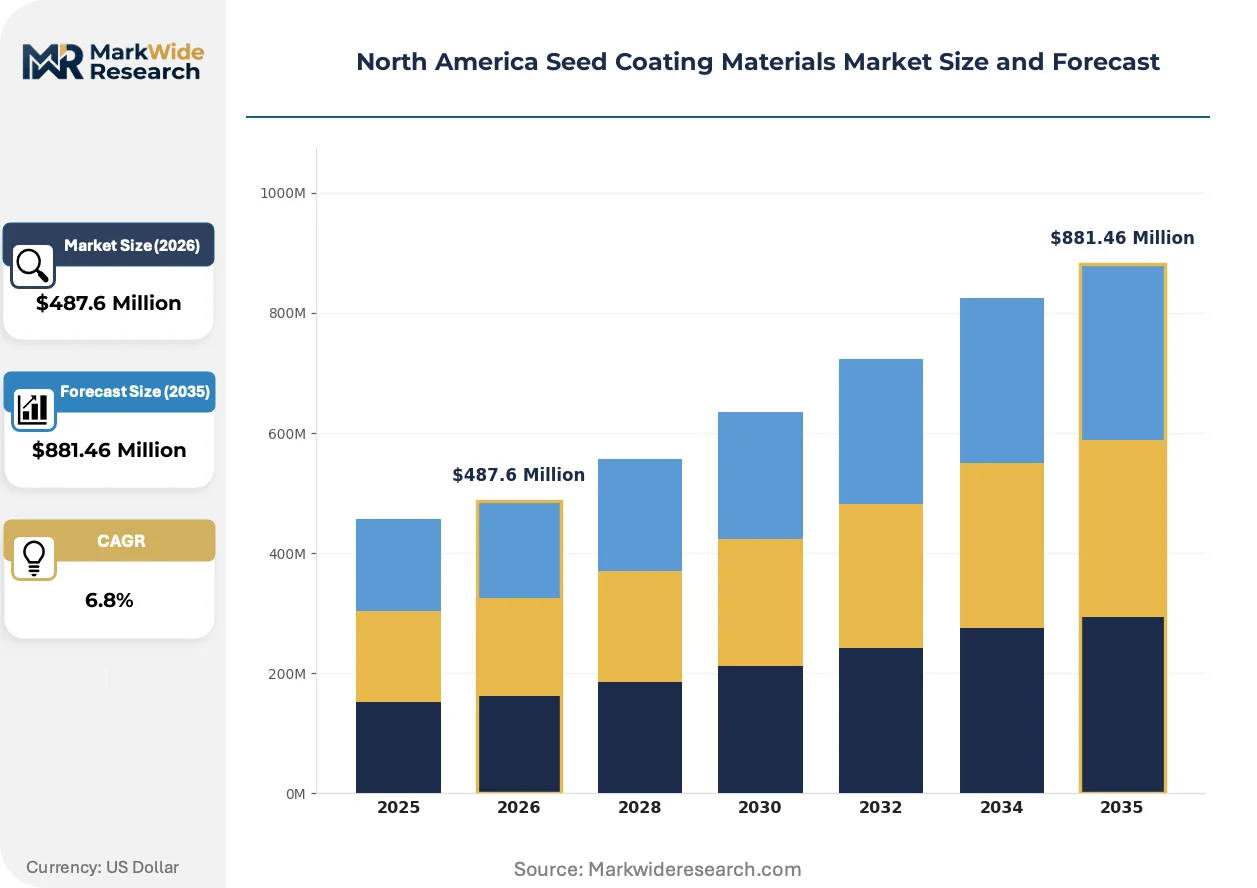
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Coatings, Colorants, Nutrient Coatings, Fungicides Application: Agronomic Seeds, Vegetable Seeds, Flower Seeds, Turf Seeds End User: Farmers, Seed Companies, Agricultural Cooperatives, Retailers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Corteva Agriscience, Syngenta AG, Clariant International, Croda International, Germains Seed Technology, Chromatech Incorporated, BrettYoung, Precision Laboratories, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Seed Coating Materials Market Evolving Landscape
Bio-based polymer feedstocks and precision application hardware are converging to redefine coating performance benchmarks while regulatory pressure on conventional chemistries accelerates formulation turnover.
Aliphatic polyurethanes derived from castor oil and other non-petroleum feedstocks are penetrating premium vegetable seed segments where European import customers demand supply chain decarbonization documentation. Specialty seed companies in California's Salinas Valley and Florida's Belle Glade are specifying these materials for tomato and pepper programs. Petroleum-derived polyurethane dominance in commodity row crops is rendering obsolete as scope-three emissions reporting requirements propagate through food processor procurement specifications.
EPA's revised Endangered Species Act consultation requirements for seed treatment pesticides are extending registration review timelines and triggering label amendments that restrict application timing in Midwest watersheds. The agency's 2024 biological evaluation templates now require aquatic toxicity modeling that most legacy neonicotinoid formulations fail without expensive mitigation. Corn and soybean seed treatment portfolios face the steepest reformulation burden as these crops occupy the largest treated acreage base subject to renewed scrutiny.
Cooperative agronomists and independent crop consultants are consolidating seed treatment recommendations into bundled input prescriptions that privilege integrated coating-trait-chemistry packages over standalone product selection. This advisory channel concentration disadvantages unbundled coating material suppliers lacking direct breeder relationships. The shift is most pronounced in Iowa and Illinois where two cooperatives account for 40% of farmer-facing agronomic recommendations during winter input planning meetings.
North America Seed Coating Materials Market Segmentation
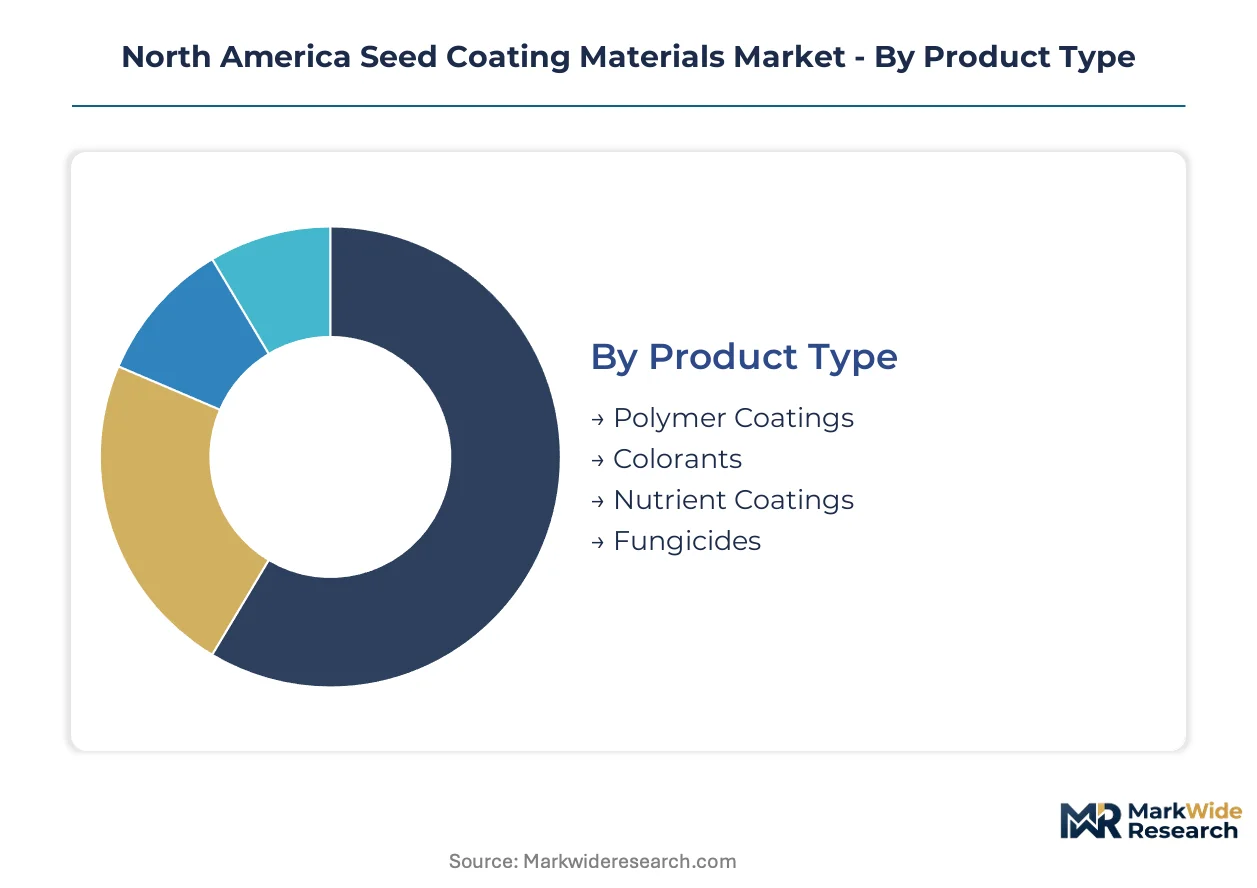
Segmentation in North American seed coating materials reflects divergent technical requirements across crop categories and channel economics. Coating specifications for commodity row crops differ fundamentally from vegetable seed protocols, while procurement patterns split between integrated seed company programs and cooperative distribution.
Product Type:
Cost tier differentiation separates commodity polymer formulations from premium bio-based architectures and functional additive layers.
- Polymer Coatings:Vinyl polymers and polyurethanes form the structural film matrix at 1–5% seed weight application rates. Demand concentrates in US Corn Belt corn and soybean programs where controlled-release architectures reduce in-furrow fertilizer rates. Petrochemical feedstock volatility squeezes mid-tier formulators without long-term supply contracts.
- Colorants:Pigment dispersions enable visual identification of treated seed and brand differentiation at retail. Prairie canola growers in Saskatchewan and Manitoba specify colorant-coated seed for blackleg management program tracking. EPA treated article exemption interpretations compress formulation timelines for pigment-active ingredient combinations.
- Nutrient Coatings:Micronutrient and macronutrient layers applied as secondary films.
- Fungicides:Seed-applied active ingredients for soilborne pathogen protection.
Polymer Coatings command the established base. The steepest expansion runs through bio-based polyurethane alternatives.
Application:
Volume scale inversely correlates with per-unit coating value, creating distinct margin architectures across crop categories.
- Agronomic Seeds:Corn, soybean, wheat, and canola seeds generate the largest coating volume base through rotary drum and fluidized bed processing. Midwest commercial seed treaters in Iowa and Illinois control 60% of toll-coating capacity, creating spring planting window bottlenecks. Neonicotinoid replacement chemistry accelerates biological active ingredient integration.
- Vegetable Seeds:Tomato, pepper, and lettuce programs command highest per-unit coating values due to smaller seed sizes and intensive multi-layer protocols. California's Salinas Valley and Florida's Belle Glade specialty seed companies specify castor oil-derived polyurethanes for European export decarbonization documentation. Scope-three emissions reporting requirements propagate through food processor procurement specifications.
- Flower Seeds:Ornamental and landscape seed coating for uniform germination.
- Turf Seeds:Golf course and residential lawn applications with specialized establishment requirements.
Agronomic Seeds anchor volume throughput. Vegetable Seeds capture margin expansion.
End User:
Customer type determines technical specification authority and procurement channel access.
- Farmers:Direct purchasers of coated seed through retail and cooperative channels, with growing e-commerce platform adoption. Texas High Plains cotton producers represent underpenetrated expansion potential as thrips and seedling disease pressure mount in reduced-tillage systems. USDA Climate-Smart Commodities cost-share programs incentivize polymer-coated fertilizer integration.
- Seed Companies:Integrated genetics and coating service providers bundling proprietary trait pipelines. Corteva Agriscience leverages captive coating capacity with breeder relationships. Syngenta AG anchors position through crop protection cross-selling into treatment workflows.
- Agricultural Cooperatives:Consolidated agronomic recommendation channels in Iowa and Illinois.
- Retailers:Farm supply stores and independent dealers with seasonal inventory positioning.
Seed Companies control specification authority. Farmers represent channel disruption opportunity through digital procurement.
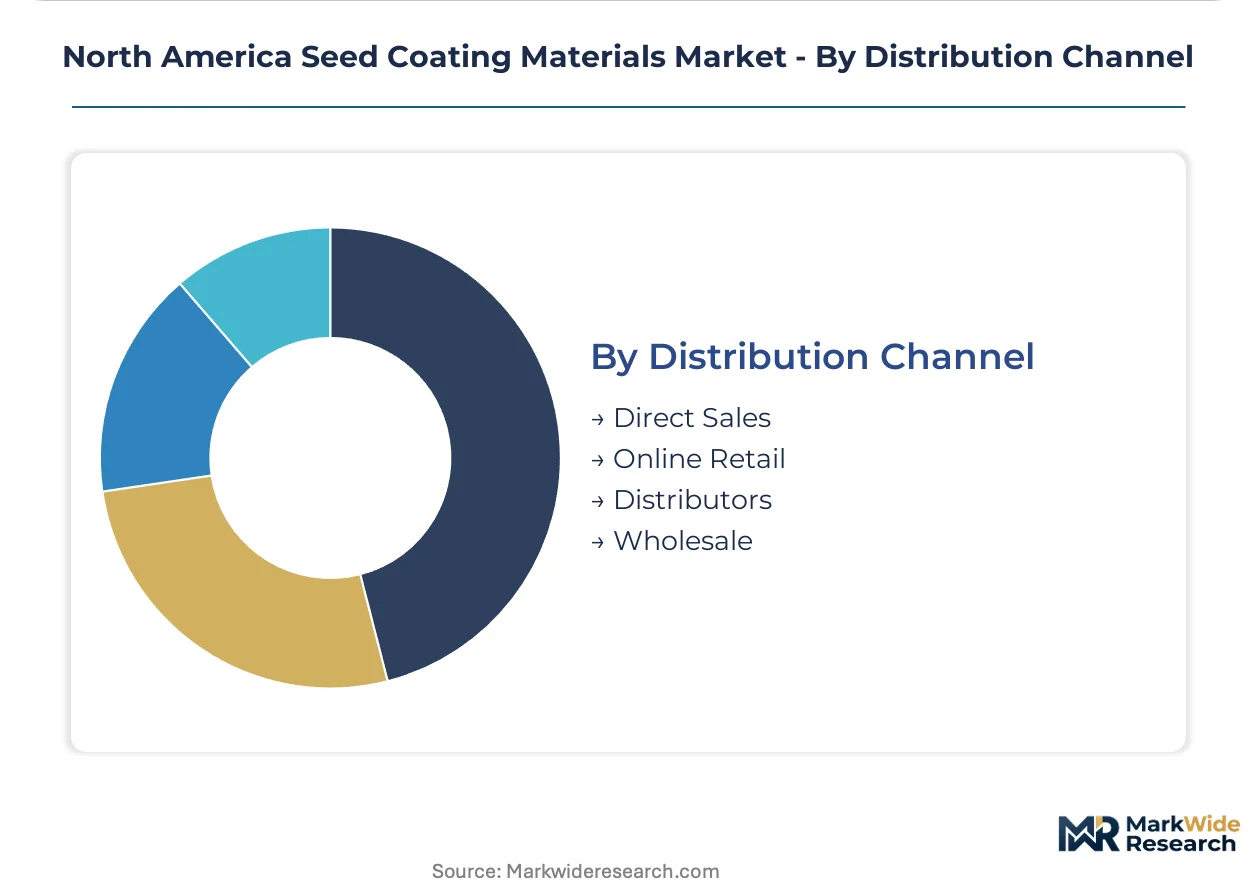
Distribution Channel:
Supply concentration in legacy cooperative networks faces direct-to-farm platform encroachment.
- Direct Sales:Seed company field representatives and technical agronomists specifying integrated coating-trait-chemistry packages. This channel privileges bundled offerings over standalone coating material selection. Advisory concentration disadvantages unbundled suppliers lacking direct breeder relationships.
- Distributors:Regional agricultural input wholesalers with inventory and logistics infrastructure.
- Online Retail:E-commerce platforms and farm management software integrations enabling coating service bypass of traditional cooperative distribution. Direct-to-farm digital channels expand fastest in Corn Belt input planning windows.
- Wholesale:Bulk procurement for large-scale farming operations and export programs.
Direct Sales maintains relationship control. Online Retail gains share fastest through platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA's FIFRA framework and Health Canada/PMRA registration pathways anchor regulatory oversight across the dominant geographies, with state-level neonicotinoid restrictions and federal cost-share programs redirecting regional demand patterns.
United States
Corn Belt producers in Iowa and Illinois drive polymer coating volume for controlled-release nutrient delivery, while New York's Article 15 neonicotinoid restrictions and Minnesota's pollinator protection rules force active ingredient pivots toward biological alternatives. EPA's revised Endangered Species Act consultation requirements extend registration review timelines for legacy chemistries. Commercial seed treaters in the Midwest control 60% of toll-coating capacity, creating spring planting bottlenecks.
Canada
Prairie canola expansion across Saskatchewan and Manitoba intensifies demand for seed-applied fungicides targeting blackleg and clubroot pressure. Health Canada/PMRA streamlined registration pathways accelerate coated seed adoption relative to US-Canada tolerance mismatches that delay simultaneous product launches. Alberta and Manitoba seed processing clusters concentrate formulation expertise for export-oriented grain programs.
Mexico
Sinaloa and Sonora vegetable seed production for US winter markets adopts intensive multi-layer coating protocols for tomato and pepper export programs. Mexican regulators align with EPA tolerance frameworks for cross-border treated seed commerce, though enforcement capacity varies by state. Guadalajara-area seed distributors serve as regional logistics hubs for Central American re-export.
North America Seed Coating Materials Market Competitive Landscape
Integrated seed-chemistry bundlers and standalone polymer specialists split the market along vertical integration fault lines. Three strategic archetypes dominate: captive seed company coating divisions, independent formulation houses, and agricultural input distributors with toll-treating capacity. Competitive moves concentrate on M&A for breeder relationships and capacity expansion in compressed spring windows.
Within the integrated agriscience tier, Corteva Agriscience and Syngenta AG exemplify archetypes combining proprietary genetics with captive coating workflows. BASF SE anchors the polymer innovation segment. Independent specialists including Germains Seed Technology and Precision Laboratories occupy positions serving unbundled coating demand from regional seed companies lacking in-house treatment infrastructure.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Syngenta AG |
| Clariant International |
| Croda International |
| Germains Seed Technology |
| Chromatech Incorporated |
| BrettYoung |
| Precision Laboratories |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock volatility compresses both margin structures and sourcing strategies across the North American seed coating materials landscape. Propylene and isocyanate price spikes force mid-tier formulators into long-term supply contracts or bio-based pivots, while buyers face widening spreads between commodity vinyl polymer formulations and premium castor oil-derived alternatives.
Pricing Analysis
Configured-to-order pricing for bio-based polyurethane film coatings commands substantial premiums over standard petroleum-derived vinyl formulations in vegetable seed programs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with California specialty seed companies absorbing the highest per-unit costs for European export compliance. Cost compression in commodity row crop tiers is intensifying because toll-coating capacity bottlenecks during spring planting windows shift bargaining power toward commercial seed treaters in Iowa and Illinois. Cooperative agronomists demonstrate lowest price sensitivity when bundling coating services with proprietary genetics, while independent regional seed companies face acute pressure during inventory positioning delays.
Supply Chain Analysis
Upstream polyurethane feedstock production concentrates in the US Gulf Coast and German chemical corridors, with vinyl polymer resin supply anchored in Texas and Louisiana petrochemical complexes. Formulators draw from propylene derivatives, isocyanate intermediates, and emerging castor oil bio-refineries in Brazil and India as non-petroleum alternatives scale. Single-source vulnerability in Midwest toll-coating capacity creates spring planting bottlenecks when Iowa and Illinois commercial treaters control sixty percent of regional throughput. Distribution runs through integrated seed company field representatives, cooperative agronomists, and accelerating direct-to-farm digital channels that bypass legacy cooperative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
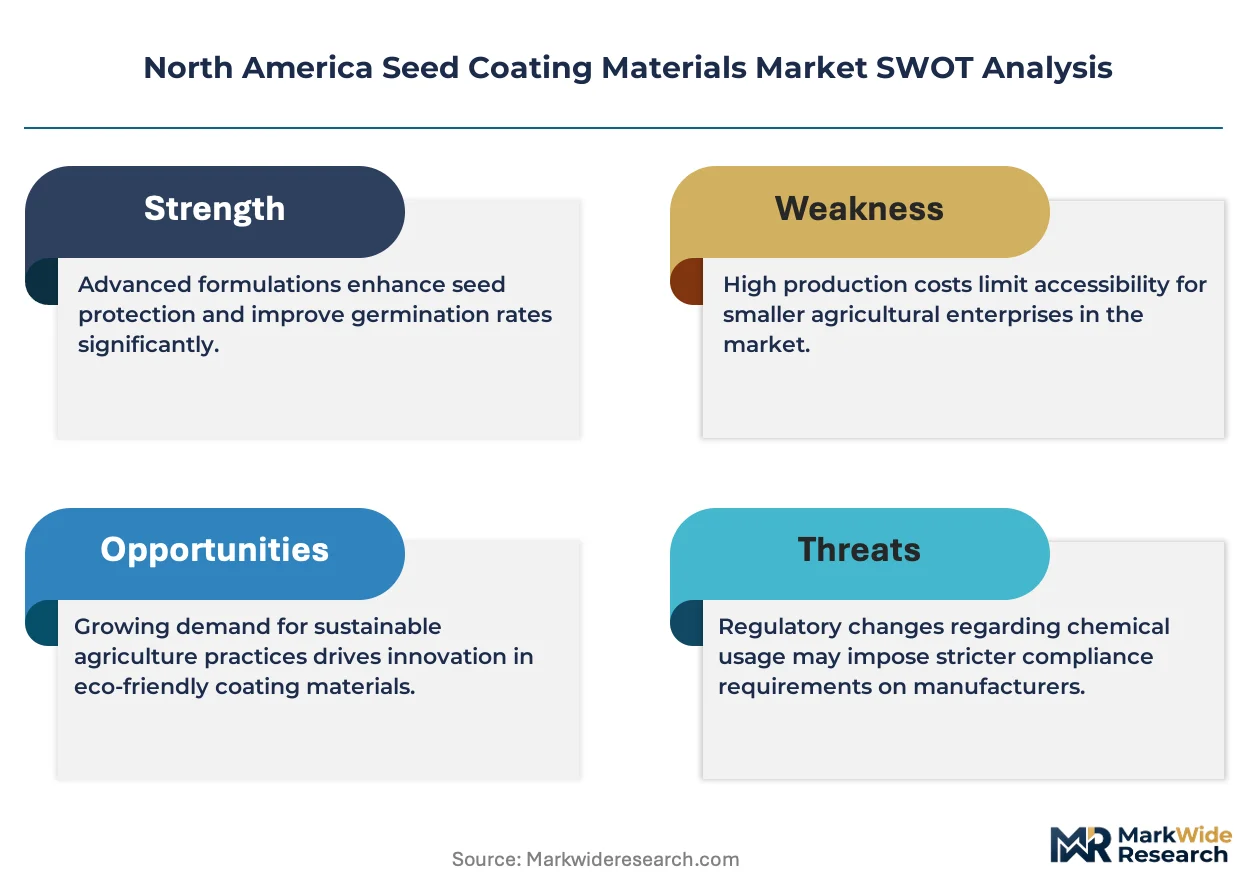
North American seed coating materials sit in early-cycle expansion as biological active ingredient adoption accelerates under state-level neonicotinoid restrictions. USDA Climate-Smart Commodities funding pulls polymer-coated nutrient delivery into carbon credit eligibility frameworks, expanding addressable demand beyond traditional crop protection applications.
For Market Incumbents: Pre-empt formulation chemist scarcity by captive hiring from Midwest university polymer programs or acquisition of regional bio-based synthesis specialists. Corteva Agriscience and Syngenta AG should deepen backward integration into castor oil supply chains before European scope-three emissions reporting propagates through processor procurement specifications. Defensive patent positioning around controlled-release film architectures protects premium pricing tiers from mid-tier formulators seeking upgrade pathways. For New Entrants and Emerging Players: Establish a beachhead in Texas High Plains cotton, where thrips pressure and reduced-tillage expansion create underpenetrated coated seed demand absent dominant integrated seed company presence. Target biological active ingredient compatibility testing services for regional seed companies lacking in-house formulation expertise, leveraging digital agronomy platforms for direct farmer engagement bypassing cooperative recommendation concentration in Iowa and Illinois. For Investors and Strategic Acquirers: EPA's revised Endangered Species Act consultation requirements reshape the acquisition landscape by extending registration timelines for legacy neonicotinoid portfolios and privileging biological active ingredient pipelines. Long-term viability centers on formulators with demonstrated Health Canada/PMRA parallel registration capabilities to circumvent eighteen-to-twenty-four month US-Canada tolerance mismatch delays. Monitor state-level pollinator protection rule propagation as the signal indicating acceleration of biological chemistry investment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Castor oil supply chain control secures premium vegetable seed positioning against European decarbonization mandates. |
| Capacity Expansion in Prairie Provinces | Saskatchewan and Manitoba toll-coating infrastructure captures canola fungicide coating demand from blackleg pressure intensification. |
| Biological Active Ingredient Registration | Health Canada/PMRA streamlined pathways accelerate coated seed adoption ahead of EPA tolerance alignment delays. |
| Direct-to-Farm Digital Platform Integration | E-commerce and farm management software bypasses cooperative recommendation concentration in Corn Belt input planning. |
| Controlled-Release Film Coating R&D | Staggered nutrient delivery architectures capture USDA Climate-Smart Commodities cost-share eligibility for carbon credit positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA registration databases, Health Canada/PMRA submission filings, USDA seed certification records, and SEC 10-K disclosures from listed agriscience companies. Primary interviews engaged seed company formulation directors, commercial seed treater operations managers, cooperative agronomists, polymer procurement leads at regional formulators, and vegetable seed quality assurance heads in California and Florida. Bottom-up coating volume estimates triangulate against top-down agronomic seed acreage projections and per-unit application rate assumptions across crop categories.
Forecast inputs incorporate polymer feedstock price trajectory modeling, regulatory registration timeline assumptions, and adoption curve projections for biological active ingredients across the analysis window. Segmentation dimensions include product type tier, crop category application, end user procurement channel, and regional regulatory cluster. CAGRs derive from iterative reconciliation of historical coating penetration rates against forward-looking acreage shifts and treatment intensity assumptions, with specific sensitivity to neonicotinoid replacement chemistry transition speeds and Prairie canola expansion trajectories.
Sensitivities concentrate around EPA Endangered Species Act consultation timeline extensions, propylene price volatility spikes, and cross-border registration divergence between EPA and Health Canada/PMRA tolerance frameworks. Forecasts embed assumptions regarding biological active ingredient efficacy parity and farmer willingness to absorb premium pricing for bio-based polymer architectures. Cross-checking against USDA National Agricultural Statistics Service planting intention surveys and commercial seed treater capacity utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
India Seed Treatment Market
Seed Technology
Seed Quality Imaging and Germination Prediction Test Systems Market
Seed Technology
Asia-Pacific Seed Coating Materials Market
Seed Technology
China Seed Treatment Market
Seed Technology
Europe Seed Coating Materials Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
North America Cotton Seed Treatment Market
Seed Technology
Seed Coating Ingredients Market
Seed Technology
Japan Seed Treatment Market
Seed Technology
Seed Storage Systems Market
Seed Technology
Seed Additives Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
Seed Coating Materials Market
Seed Technology
Protein Content Optimizing Cereal Fertility Program Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
Canada Seed Treatment Market