
 China Seed Treatment Market | 2026-2036
China Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
China Seed Treatment Market Outlook
Multi-source procurement of active ingredients is repositioning how domestic formulators secure supply chains. Syngenta AG leverages its global R&D pipeline to introduce advanced fungicide combinations for corn and soybean. CAC Nantong Chemical Co. Ltd anchors regional production with captive manufacturing of technical-grade materials. Yuan Longping High-Tech Agriculture Co. Ltd specializes in integrating seed treatment with its hybrid rice distribution network.
Seed treatment encompasses the application of chemical or biological agents to seeds before planting to protect against soil-borne pathogens, insect pests, and abiotic stress, with formulations typically containing active concentrations between 0.5% and 50% by weight depending on target pest and crop type. The process employs film-coating, pelleting, or slurry application to ensure uniform coverage without impairing germination. Biologicals represent the fastest-expanding product type as farmers seek alternatives to synthetic chemistry under tightening environmental scrutiny. Liquid formulations dominate volume due to ease of application and compatibility with high-speed treaters, while granule demand sustains growth in manual-planting regions. Row crops command the largest application share, though vegetable seed treatment attracts premium pricing from protected cultivation operators.
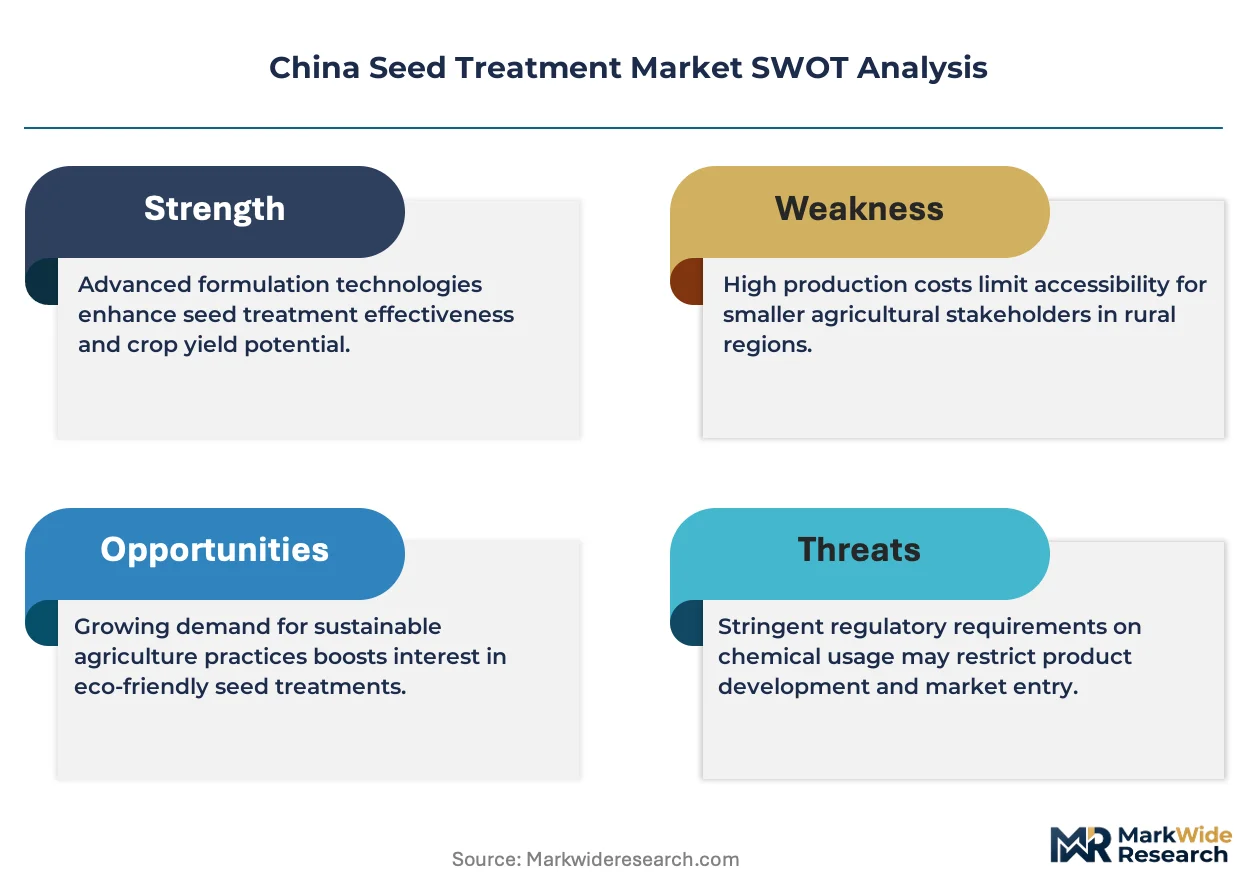
China's Ministry of Agriculture and Rural Affairs sets maximum residue limits that directly filter which chemistries gain registration, while GB standards mandate seed quality benchmarks that treated products must meet. The National Agro-Tech Extension Service Center channels subsidy preferences toward low-toxicity biological formulations, redirecting procurement patterns at provincial levels. Stakeholders must track how China's dual carbon targets reshape subsidy eligibility and which formulation technologies align with emerging carbon-accounting protocols for agricultural inputs.
Market Dynamics
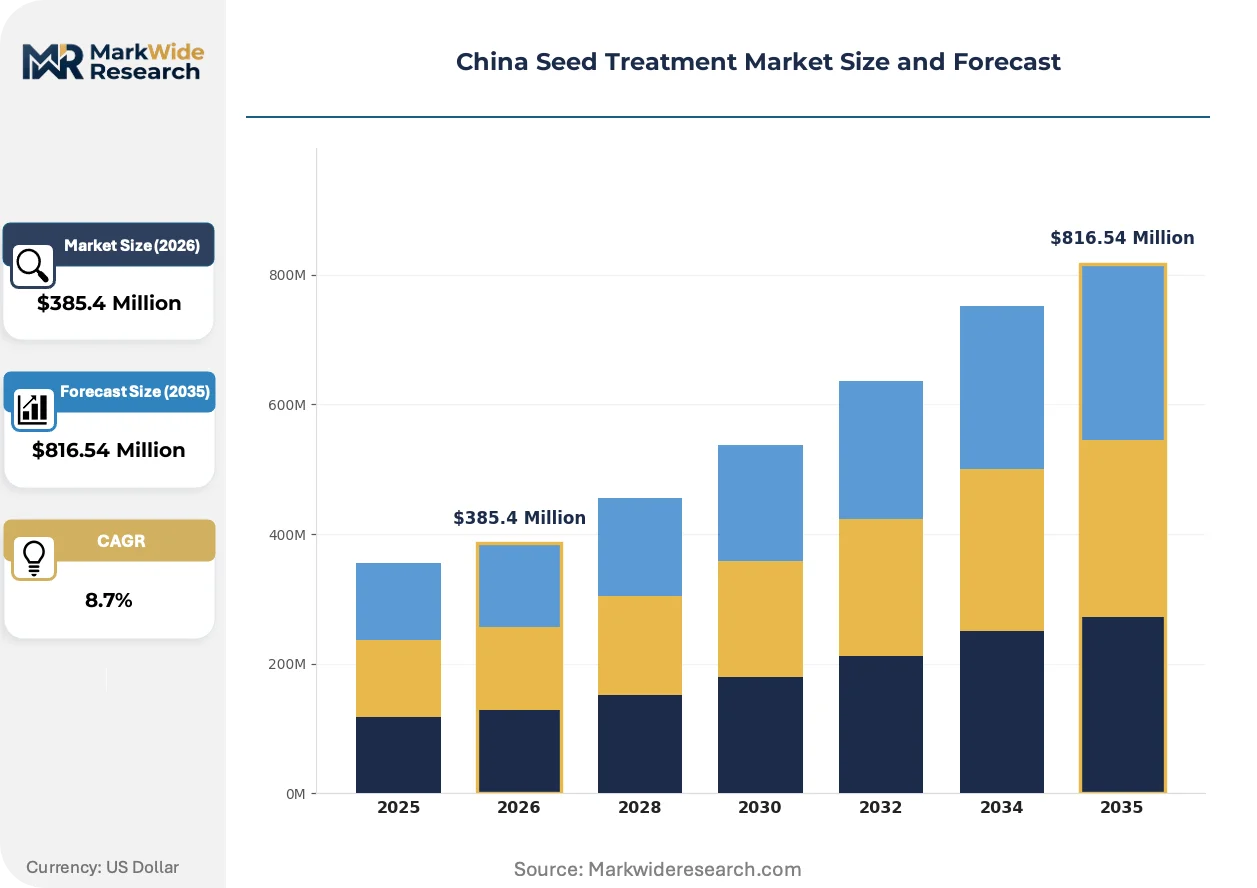
China's seed treatment sector is compressing around residue-limit enforcement and carbon-accounting protocols that filter which chemistries survive registration. The Ministry of Agriculture and Rural Affairs is tightening maximum residue limits while provincial subsidy channels redirect procurement toward low-toxicity biological formulations.
Growth Catalysts
- Dual carbon policy framework:China's national carbon neutrality targets are accelerating microbial inoculant demand across the Yangtze River Basin, where rice seed treatment applications concentrate under new carbon-accounting protocols for agricultural inputs.
- Heilongjiang soybean expansion:Biological seed treatment adoption is widening among soybean growers in this northeastern province as chemical residue limits tighten and export-access requirements harden.
- Film-coating technology diffusion:High-speed treater compatibility is driving liquid formulation uptake, enabling uniform active ingredient distribution without germination impairment across mechanized planting zones.
Market Restraints
- Technical-grade material concentration:Captive manufacturing of active ingredients anchors with a limited set of domestic chemical producers, creating supply vulnerability when environmental inspections interrupt production.
- GB standard compliance friction:Mandatory seed quality benchmarks under national standards create registration bottlenecks that delay new biological product commercialization by 18-24 months.
- Substitution pressure from bare-seed alternatives:Cost-sensitive vegetable growers in manual-planting regions continue selecting untreated seed when residue testing requirements do not mandate treatment.
Strategic Opportunities
- Guangdong protected cultivation:Vegetable seed treatment commands premium pricing from greenhouse operators seeking pathogen suppression in high-value tomato and pepper production systems.
- National Agro-Tech Extension subsidy redirection:Provincial procurement preferences now favor biological formulations, creating first-mover advantage for microbial inoculant developers that secure early registration.
- Granule-manual planting convergence:Sichuan and Yunnan hillside farming zones sustain demand for solid formulations, opening distribution partnerships with regional seed cooperatives bypassing high-speed treater infrastructure.
Industry Challenges
- Carbon-accounting protocol integration:Agricultural input suppliers lack standardized methodologies to document emission reductions from biological seed treatments, complicating subsidy eligibility verification.
- Microbial strain stability:Shelf-life consistency for bacterial inoculants under variable storage temperatures remains unresolved, limiting distribution radius from production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Seed Treatment Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicides, Insecticides, Biologicals, Seed Coatings Application: Row Crops, Vegetables, Fruits, Grains Formulation: Granules, Liquids, Powders, Emulsions Distribution Channel: Online Retail, Agrochemical Stores, Distributors, Others |
| Companies Covered | Syngenta AG, Bayer AG, BASF SE, Corteva Agriscience, FMC Corporation, UPL, CAC Nantong Chemical Co. Ltd, Anhui Tsuen Yin Hi-Tech Seed Industry Co. Ltd, Yuan Longping High-Tech Agriculture Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Seed Treatment Market Strategic Shifts
Formulation chemistry and application machinery are converging to reduce environmental load while maintaining efficacy thresholds. Biological active ingredients are displacing synthetic chemistry in registration pipelines as carbon metrics enter procurement scoring.
Microbial consortia containing Trichoderma and Bacillus species are integrating into rice seed treatment protocols across the Yangtze River Basin. Provincial extension services in Jiangsu and Hubei are accelerating field trials of these combinations. The technology is integrating carbon sequestration claims into product positioning, enabling premium pricing against chemical alternatives where dual carbon compliance documentation is required.
GB standards for seed quality are tightening film-coating thickness tolerances and germination retention requirements. The Ministry of Agriculture and Rural Affairs is enforcing these benchmarks through provincial inspection regimes. Corn and soybean seed processors in Heilongjiang and Jilin are retrofitting treater lines to meet new uniformity specifications, compressing equipment replacement cycles.
Buyer concentration among state-owned seed enterprises is consolidating procurement decisions at provincial level. These entities are unbundling treatment services from seed sales, creating standalone application service contracts. The shift is most visible in Xinjiang cotton seed channels, where treatment providers now bid separately from genetic suppliers, fragmenting historical bundled relationships.
China Seed Treatment Market Segmentation
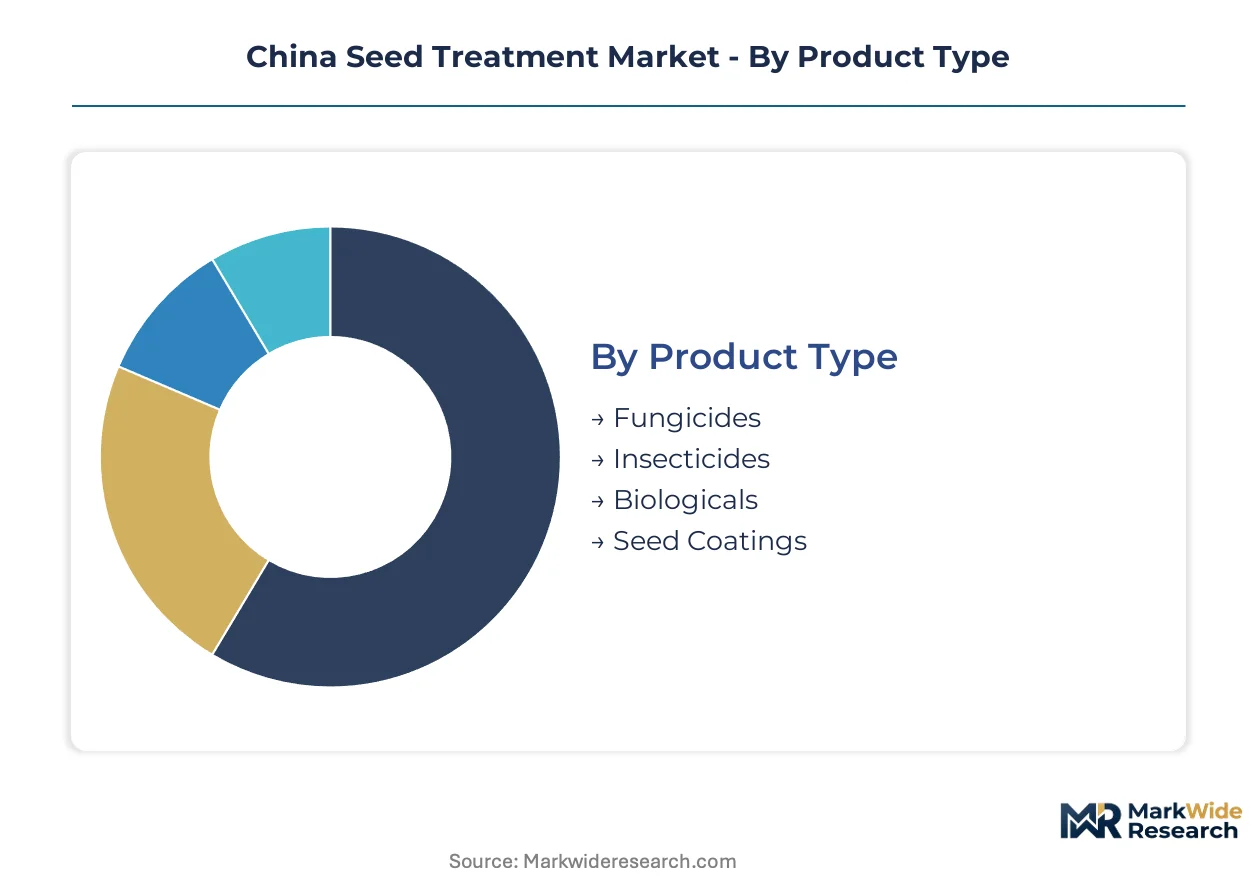
China's seed treatment market segments reflect divergent technical requirements across crop systems and application infrastructure. Formulation choices and distribution pathways filter which products reach Heilongjiang soybean growers versus Guangdong greenhouse operators.
Product Type:
Standalone chemistries dominate commodity crop protection, while biologicals embed into carbon-accounting compliance systems for premium market access.
- Fungicides:Synthetic azole and strobilurin combinations protect against soil-borne pathogens in corn and soybean systems. Demand concentrates in Heilongjiang and Jilin provinces where high-value seed stocks justify chemical investment against fusarium and rhizoctonia pressure.
- Biologicals:Microbial inoculants containing Trichoderma and Bacillus species integrate into rice seed treatment protocols across the Yangtze River Basin. Jiangsu and Hubei provincial extension services are accelerating field trials as dual carbon protocols enable premium pricing against chemical alternatives.
- Insecticides:Neonicotinoid and pyrethroid formulations target early-season pest pressure in cotton and corn systems, subject to tightening GB residue limits.
- Seed Coatings:Polymer-based film coatings ensure uniform active ingredient distribution without germination impairment in mechanized planting zones.
Volume placements concentrate in fungicides; the faster expansion belongs to biologicals.
Application:
Cost tiers separate mechanized row crop systems from labor-intensive protected cultivation where manual planting sustains distinct formulation demand.
- Row Crops:Corn, soybean, and cotton seed treatment commands the largest volume share through state-owned seed enterprise procurement channels. Xinjiang cotton processors are unbundling treatment services from genetic sales, creating standalone application contracts.
- Vegetables:Tomato and pepper seed treatment attracts premium pricing from Guangdong greenhouse operators seeking pathogen suppression in high-value protected cultivation systems.
- Fruits:Citrus and apple nursery stock treatment concentrates in Sichuan and Shandong provinces where grafting operations require disease-free rootstock.
- Grains:Rice seed treatment applications cluster in the Yangtze River Basin under carbon-accounting protocols that favor microbial inoculants.
Revenue concentration sits with row crops; margin expansion is steepest in vegetables.
Formulation:
Application machinery compatibility determines whether liquid film-coating or solid granule formats penetrate specific planting geographies.
- Liquids:Film-coating emulsions enable uniform active ingredient distribution across high-speed treater lines. Heilongjiang and Jilin corn processors are retrofitting equipment to meet tightening GB thickness tolerance standards.
- Granules:Solid formulations sustain demand in Sichuan and Yunnan hillside farming zones where manual planting bypasses high-speed treater infrastructure.
- Powders:Dust formulations retain niche use in smallholder vegetable systems with limited equipment access.
- Emulsions:Water-based suspensions balance coverage uniformity with reduced solvent load under environmental inspection pressure.
Mechanized zones favor liquids; hillside agriculture sustains granule demand.
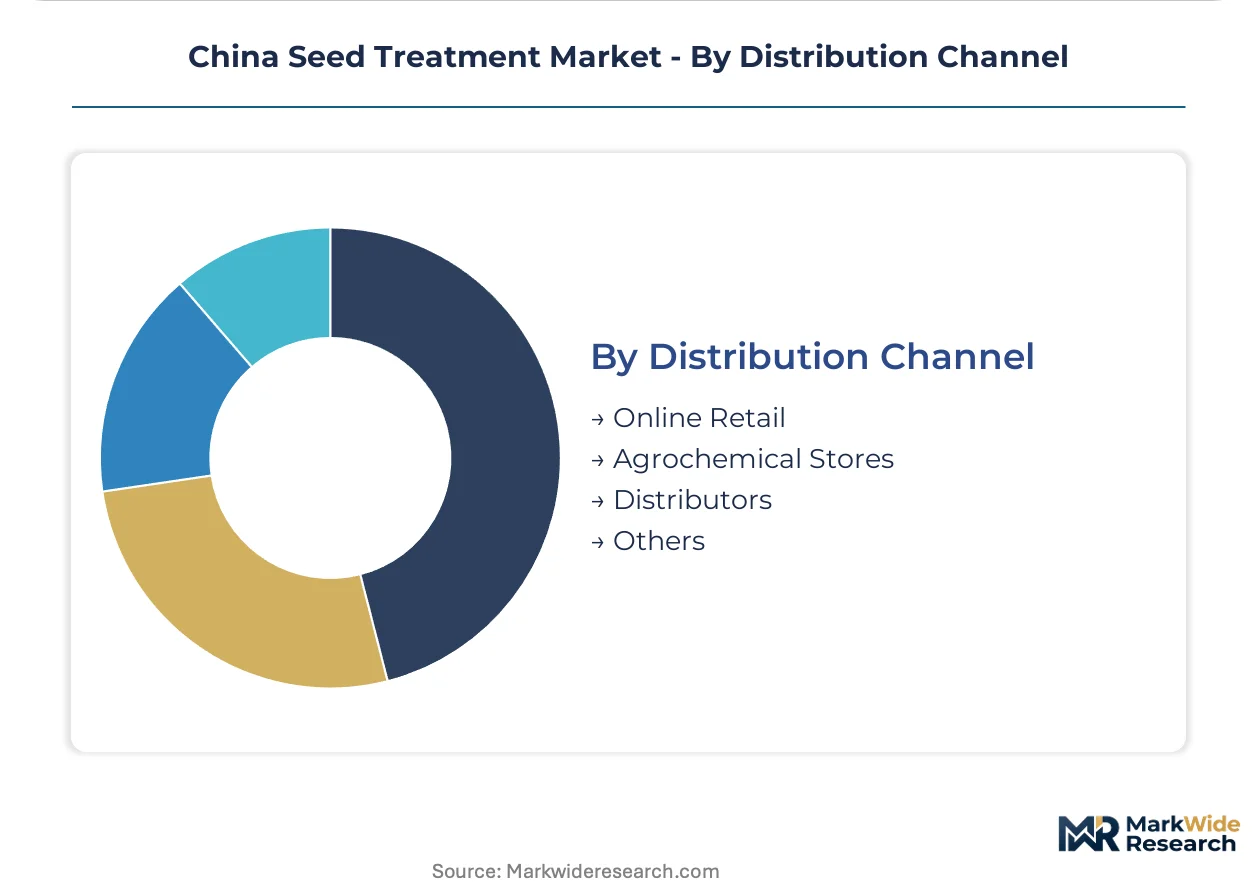
Distribution Channel:
Procurement authority consolidation among provincial state-owned enterprises is compressing traditional distributor roles while opening digital channels.
- Agrochemical Stores:County-level retail networks remain the primary channel for smallholder access in manual-planting regions.
- Distributors:Regional wholesalers face margin pressure as state-owned seed enterprises centralize procurement decisions.
- Online Retail:E-commerce platforms are gaining traction for biological product access where carbon-compliance documentation requires digital traceability.
- Others:Direct supply contracts with agricultural cooperatives bypass traditional retail in concentrated production zones.
Transaction volume flows through agrochemical stores; channel expansion is fastest online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical-grade active ingredient production clusters in Jiangsu and Shandong provinces anchor supply security for formulators serving the northeastern grain belt and southern greenhouse belts alike.
Heilongjiang Province
Soybean seed treatment demand concentrates here as export-oriented growers face tightening chemical residue limits from destination markets. The Ministry of Agriculture and Rural Affairs enforces maximum residue limits that filter registered chemistries. Harbin-based processors are retrofitting high-speed treater lines to meet new GB standard thickness tolerances.
Jiangsu Province
Rice seed treatment applications cluster in this Yangtze River Delta hub under dual carbon protocols favoring microbial inoculants. Provincial extension services accelerate field trials of Trichoderma and Bacillus consortia. Nanjing and Nantong manufacturing zones anchor technical-grade fungicide production for domestic formulators.
Guangdong Province
Protected cultivation operators in this Pearl River Delta hub command premium pricing for vegetable seed treatments suppressing pathogens in tomato and pepper systems. The province's agricultural modernization programs channel subsidies toward low-toxicity biological formulations. Shenzhen and Guangzhou greenhouse clusters drive specification standards for film-coating uniformity.
Xinjiang Uygur Autonomous Region
Cotton seed treatment volumes concentrate in this northwestern production zone where state-owned enterprises are unbundling treatment services from genetic sales. The National Agro-Tech Extension Service Center redirects procurement preferences toward biological formulations. Urumqi and Shihezi processing hubs fragment historical bundled relationships between genetic and treatment suppliers.
Sichuan Province
Hillside farming zones in this southwestern province sustain granule formulation demand where manual planting bypasses high-speed treater infrastructure. GB seed quality standards create registration bottlenecks delaying new biological commercialization. Chengdu distribution partnerships with regional seed cooperatives open channels for solid formulation penetration.
China Seed Treatment Market Competitive Environment
Global majors compete with regional champions across registration capacity and provincial subsidy channel access. The vendor base compresses around state-owned seed enterprise procurement consolidation and Ministry of Agriculture residue-limit enforcement. Three archetypes dominate: multinational agrochemical conglomerates with global R&D pipelines, domestic chemical producers with captive technical-grade manufacturing, and hybrid seed specialists integrating treatment with genetic distribution. Competitive moves center on early biological registration securing under redirected subsidy protocols and film-coating technology licensing for GB compliance retrofitting.
Among multinational agrochemical conglomerates, Syngenta AG and Bayer AG exemplify the global R&D archetype with fungicide combination pipelines. BASF SE occupies a position within this tier through formulation chemistry capabilities. Domestic chemical producers include CAC Nantong Chemical Co. Ltd, which anchors regional production with technical-grade material supply. Yuan Longping High-Tech Agriculture Co. Ltd represents the hybrid seed integration archetype, embedding treatment services within rice distribution networks. These three company types—multinational R&D leaders, domestic chemical manufacturers, and seed-treatment integrators—map onto the market's tripartite procurement structure.
| Leading Market Players |
|---|
| Syngenta AG |
| Bayer AG |
| BASF SE |
| Corteva Agriscience |
| FMC Corporation |
| UPL |
| CAC Nantong Chemical Co. Ltd |
| Anhui Tsuen Yin Hi-Tech Seed Industry Co. Ltd |
| Yuan Longping High-Tech Agriculture Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Captive manufacturing of technical-grade active ingredients anchors both supply security and pricing power for domestic formulators serving Heilongjiang soybean processors and Guangdong greenhouse operators. This backward integration choice insulates CAC Nantong Chemical and similar producers from import cost volatility while compressing margins for non-integrated competitors facing GB standard compliance investments.
Pricing Analysis
Unbundling of treatment services from genetic seed sales is fragmenting historical bundled pricing models across Xinjiang cotton channels and Heilongjiang corn systems. Three-tier pricing structure across premium, standard, and economy levels separates carbon-compliant biological formulations from conventional chemistries and bare-seed alternatives. Price differentiation stems from certification grade under Ministry of Agriculture residue protocols and volume scale through state-owned enterprise procurement. Cost compression in economy tiers is intensifying because smallholder vegetable growers in manual-planting regions substitute untreated seed when testing requirements permit. State-owned seed enterprises exhibit lowest price sensitivity; hillside vegetable cooperatives in Sichuan and Yunnan face acute cost pressure.
Supply Chain Analysis
Freight cost differentials between Jiangsu-Shandong manufacturing hubs and Heilongjiang processing centers concentrate formulation economics in coastal production zones. Technical-grade fungicide production draws from Jiangsu and Shandong chemical parks; microbial inoculant cultivation feeds from Yangtze River Basin fermentation facilities. Supply chain risk centers on single-source vulnerability when Ministry of Ecology and Environment inspections interrupt active ingredient production. Distribution runs through provincial state-owned seed enterprises consolidating procurement decisions, with county-level agrochemical stores serving residual smallholder demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's seed treatment sector is consolidating around registration capacity and subsidy channel access, with Ministry of Agriculture residue-limit enforcement eliminating formulators lacking early biological product pipelines.
For Market Incumbents: Acquire microbial strain libraries and carbon-accounting documentation capabilities before provincial subsidy redirection completes. Defensive positioning requires retrofitting film-coating lines to meet tightening GB thickness tolerances in Heilongjiang and Jilin. Threat substitution from bare-seed alternatives in vegetable segments demands channel control through agricultural cooperative partnerships. For New Entrants and Emerging Players: Begin with granule formulation development targeting Sichuan and Yunnan hillside zones where manual planting bypasses high-speed treater infrastructure. White-space concentration sits in microbial consortia for rice seed treatment under Yangtze River Basin dual carbon protocols. Go-to-market execution should prioritize digital traceability platforms enabling carbon-compliance documentation for online retail channels. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational agrochemical conglomerates seeking biological registration assets in China. Long-term viability favors targets with integrated strain development and provincial subsidy channel relationships. Signal to monitor involves National Agro-Tech Extension Service Center publication of revised biological procurement scoring methodologies.| Strategic Initiative | Industry Significance |
|---|---|
| Microbial Strain Library Acquisition | Secures carbon-compliant product pipelines ahead of provincial subsidy redirection. |
| Film-Coating Line Retrofit | Enables GB standard compliance for Heilongjiang corn and soybean processors. |
| Provincial Seed Enterprise Partnership | Locks in procurement channel access as buyer concentration accelerates. |
| Carbon-Accounting Protocol Development | Documents emission reductions for biological formulations seeking premium positioning. |
| Hillside Distribution Network Buildout | Captures granule demand in Sichuan and Yunnan manual-planting zones. |
Study Parameters
Independent corroboration across Ministry of Agriculture registration filings, provincial subsidy disbursement records, and GB standard revision drafts underwrites the qualitative findings in this study. Primary interviews engaged seed treatment formulators, provincial extension service officers, state-owned seed enterprise procurement directors, and agricultural cooperative managers. Secondary validation drew from customs trade data, National Agro-Tech Extension Service Center technical bulletins, and corporate sustainability disclosures. Bottom-up volume modeling across formulation types and top-down expenditure reconciliation anchored market sizing.
Comparable-period anchoring linked historical registration timelines to projected biological product commercialization cycles across the analysis window. Segmentation modeling addressed product type, crop application, formulation technology, and provincial regulatory cluster. CAGRs were derived from slope analysis of adoption curves calibrated to subsidy redirection timing and residue-limit enforcement phases. Forecast inputs incorporated film-coating equipment replacement cycles and microbial strain stability parameters.
Underlying measurement precision varies by segment; biological product pipelines carry tighter precision than commodity fungicide volumes given registration uncertainty. Forecasts reflect assumptions regarding subsidy continuity and GB standard implementation pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
Seed Coating Materials Market
Seed Technology
Protein Content Optimizing Cereal Fertility Program Market
Seed Technology
North America Seed Coating Materials Market
Seed Technology
Europe Seed Coating Materials Market
Seed Technology
Seed Additives Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
Seed Coating Ingredients Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
Seed Storage Systems Market
Seed Technology
Japan Seed Treatment Market
Seed Technology
Seed Quality Imaging and Germination Prediction Test Systems Market
Seed Technology
Asia-Pacific Seed Coating Materials Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
France Seed Treatment Market
Seed Technology
Mexico Seed Treatment Market
Seed Technology
India Seed Treatment Market