
 Seed Coating Materials Market | 2026-2036
Seed Coating Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Coating Materials Market Analysis
Consolidation among North American row-crop cooperatives and large-scale farming operations is rebalancing procurement power toward volume-contract buyers. BASF SE leverages its integrated crop science pipeline to bundle coating chemistry with seed genetics, sustaining pull-through demand across dealer networks. Croda International Plc anchors its position through bio-based surfactant specialization, while Clariant competes via colorant and pigment expertise that supports traceability requirements in commercial seed lots.
Seed coating materials comprise functional layers applied to seeds to enhance germination, protect against pests and pathogens, and enable precision delivery of nutrients or crop protection actives, typically formulated from polymer binders, colorants, and active ingredients at application rates of one to ten percent by seed weight. Polymer coatings dominate commercial volumes due to their controlled-release properties and compatibility with high-speed treaters, while organic coatings capture expanding share as bio-based binder chemistry matures and regulatory pressure on synthetic microplastics intensifies. Agricultural farming applications generate the largest revenue pool, though horticulture segments command premium pricing for specialized microencapsulated formulations.
The EPA governs pesticide-treated seed registrations under FIFRA, while REACH and the EU Green Deal constrain permissible polymer chemistries in European markets, and Brazil's national agricultural regulator enforces phytosanitary standards that shape import and formulation requirements for multinational suppliers. Compliance with diverging regional frameworks is fragmenting product portfolios and elevating R&D overhead for formulators seeking cross-border approvals. Stakeholders must monitor evolving biodegradability mandates and active ingredient reauthorization timelines to align coating investments with regulatory trajectories.
Market Dynamics
Polymer chemistry constraints under the EU Green Deal are fragmenting product portfolios and forcing formulators to rebuild binder systems around biodegradable alternatives, reshaping R&D allocation and cross-border approval strategies.
Growth Catalysts
- Climate volatility in Brazilian cerrado:Erratic rainfall patterns are pushing row-crop operators toward coated seeds with enhanced moisture retention and stress-tolerance actives.
- REACH polymer restrictions:European regulatory pressure on synthetic microplastics is accelerating commercialization of bio-based binder alternatives and opening formulation partnerships with specialty chemical suppliers.
- Precision agriculture hardware:Variable-rate planting equipment is unifying seed treatment data with field-level application maps, creating pull-through for coated seed lots with embedded traceability markers.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and polyurethane binder precursors face price swings tied to crude oil markets, compressing margin stability for commodity coating formulations.
- Active ingredient reauthorization timelines:EFSA and EPA review cycles for neonicotinoid and fungicide actives are extending registration gaps and freezing product line investments.
- High-speed treater compatibility limits:Bio-based polymer films exhibit inferior adhesion and flow characteristics on legacy equipment, constraining adoption in dealer networks without capital upgrade cycles.
Strategic Opportunities
- Horticulture microencapsulation:Vegetable and flower seed producers in the Netherlands and Italy command premium pricing for controlled-release nutrient coatings that reduce transplant shock.
- India's PLI scheme for agrochemicals:Production-linked incentives for domestic formulation capacity are attracting coating material suppliers to establish local blending operations.
- Carbon accounting integration:Seed cooperatives are beginning to request coating carbon footprints for Scope 3 reporting, creating first-mover advantage for suppliers with certified lifecycle data.
Industry Challenges
- Formulation chemist scarcity:The intersection of polymer science, seed physiology, and regulatory toxicology requires rare cross-trained talent that seed companies and suppliers compete to secure.
- Multi-jurisdiction dossier compilation:Divergent data requirements between EPA FIFRA, REACH, and Brazil's national agricultural regulator are inflating registration costs and delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Coating Materials Market |
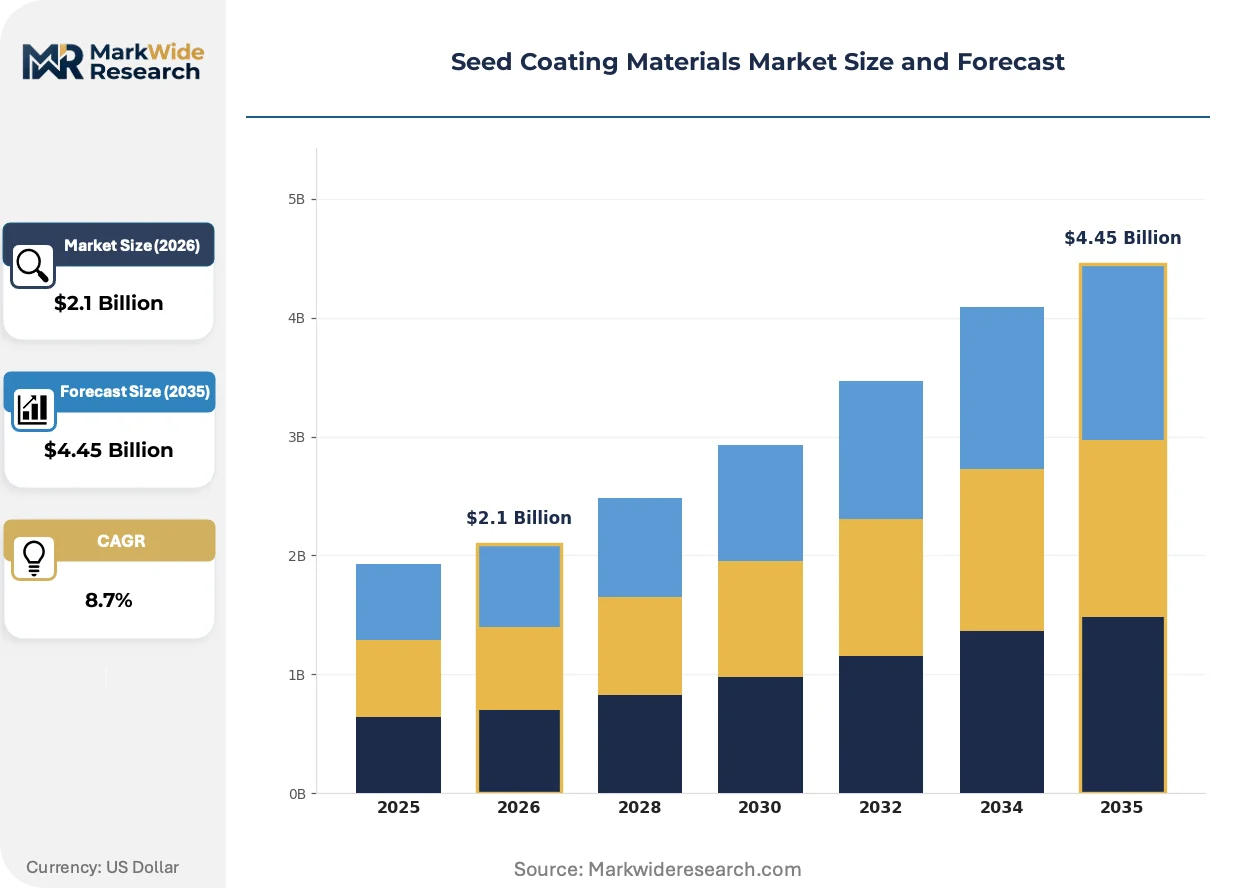
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Polymer Coatings, Organic Coatings, Inorganic Coatings, Nutrient Coatings Application: Agricultural Farming, Horticulture, Turf & Ornamental, Forestry Formulation: Liquid Formulation, Powder Formulation, Granular Formulation, Microencapsulated Formulation End User: Farmers, Agricultural Cooperatives, Seed Producers, Distributors |
| Companies Covered | BASF SE, Croda International Plc, Clariant, Solvay, Incotec Group, Germains Seed Technology, Chromatech Incorporated, Precision Laboratories LLC, Lanxess AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Coating Materials Market Emerging Trajectories
Active ingredient delivery mechanisms and environmental compliance frameworks are converging to redefine coating architecture, with formulators racing to integrate biological actives and biodegradable carriers before regulatory deadlines crystallize.
Microencapsulation technology is unifying fungicide and insecticide actives within single polymer shells, enabling staged release synchronized with germination timelines. Large-scale corn and soybean operations in Iowa and Illinois are piloting these formulations to reduce multiple field passes. The structural consequence is compressing traditional separate-treatment workflows into single-seed solutions that alter dealer service revenue models.
EU Green Deal biodegradability mandates are forcing polymer suppliers to abandon acrylic backbones in favor of polylactic acid and starch-derivative binders. Industrial consequence includes reformulation costs and performance validation cycles that extend 18-24 months. Horticulture seed houses in Spain and Poland are most affected, responding by consolidating supplier relationships to share testing burdens.
Volume-contract procurement is consolidating purchasing power among North American agricultural cooperatives and Brazilian land-holding companies, displacing spot-market seed treatment purchases. Dealer networks are responding by unbundling coating services from seed genetics and offering transparent per-acre pricing. This pattern is most visible across the US corn-soy belt and Mato Grosso soybean expansion zones.
Seed Coating Materials Market Segmentation
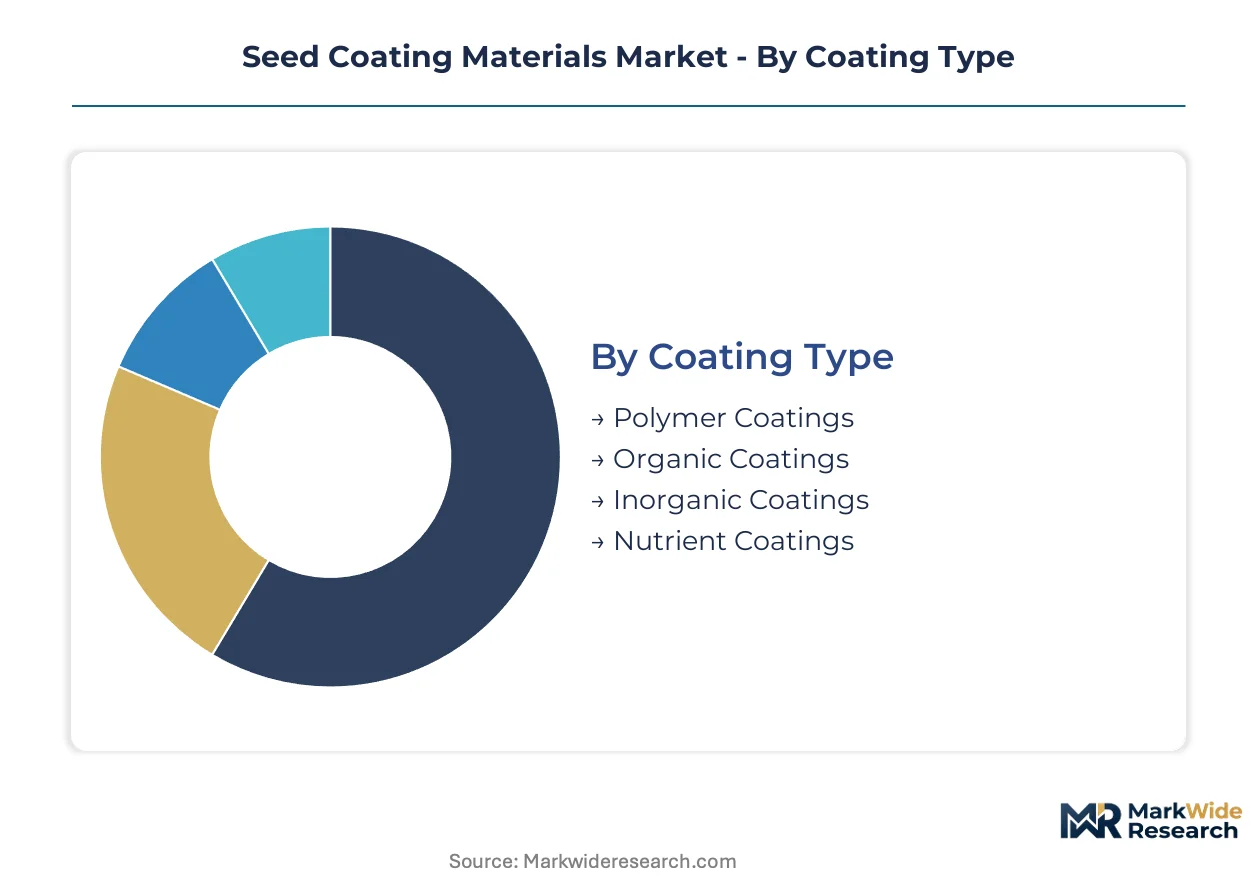
Segmentation in seed coating materials reflects divergent technical requirements across crop types, equipment compatibility constraints, and regulatory pressure points that reshape formulation priorities. Understanding these divisions clarifies where R&D investment concentrates and which customer segments command premium pricing.
Coating Type:
Customization intensity varies sharply across this category, from standardized polymer systems for commodity row crops to highly tailored organic formulations for certified organic operations.
- Polymer Coatings:Acrylic, polyurethane, and polylactic acid binders form controlled-release films that protect actives during planting and early germination. Demand concentrates in Iowa and Illinois corn-soy operations where high-speed treaters require consistent flow characteristics and adhesion under mechanical stress. REACH restrictions on synthetic microplastics are forcing European suppliers toward biodegradable polymer backbones.
- Organic Coatings:Bio-based binders derived from starch derivatives, lignin, and microbial polysaccharides serve organic-certified farming systems and EU markets facing Green Deal compliance deadlines. Spanish and Polish horticulture seed houses are consolidating supplier relationships to share 18-24 month reformulation validation burdens.
- Inorganic Coatings:Mineral-based treatments including lime, talc, and clay function as low-cost carriers for fungicide dusts in developing markets with limited treater infrastructure.
- Nutrient Coatings:Micronutrient-impregnated layers address specific soil deficiencies in Brazilian cerrado expansion zones with erratic rainfall patterns.
Most installed capacity flows through Polymer Coatings. Expansion is steepest in Organic Coatings.
Application:
Margin structure and volume scale operate in inverse proportion across this category, with agricultural farming delivering tonnage and horticulture capturing value per treated seed.
- Agricultural Farming:Corn, soybean, wheat, and rice seed treatments constitute the volume foundation, with application rates of one to ten percent by seed weight standardizing procurement around cost-per-acre metrics. Brazilian land-holding companies and North American cooperatives are consolidating volume-contract purchasing power.
- Horticulture:Vegetable and flower seeds command premium pricing for microencapsulated nutrient coatings that reduce transplant shock in Netherlands and Italy greenhouse operations. Controlled-release synchronization with germination timelines justifies three to five-fold price multiples over commodity formulations.
- Turf & Ornamental:Golf course and landscape seed producers require uniform colorant dispersion for visual quality assurance during establishment phases.
- Forestry:Reforestation programs in Nordic countries and Canada drive demand for rodent-repellent coatings on conifer seeds with extended storage requirements.
Agricultural Farming absorbs the majority of raw material throughput. Horticulture generates the highest contribution margins per kilogram applied.
Formulation:
Equipment compatibility and active ingredient stability requirements determine formulation selection, with liquid systems dominating commercial treaters and microencapsulation capturing precision agriculture segments.
- Liquid Formulation:Suspension concentrates and emulsifiable concentrates integrate with continuous-flow treaters at dealer networks across the US corn-soy belt, enabling real-time adjustment of application rates based on seed lot size and weather windows.
- Powder Formulation:Dry flowable powders serve smallholder markets in India and Sub-Saharan Africa with limited water access and manual treatment methods.
- Granular Formulation:Dust-free granules address occupational safety requirements in Brazilian phytosanitary regulations and EU worker protection directives.
- Microencapsulated Formulation:Staged-release polymer shells unify fungicide and insecticide actives within single coatings, piloted in Iowa and Illinois to compress multiple field passes into single-seed solutions. Variable-rate planting equipment creates pull-through for embedded traceability markers.
Liquid Formulation maintains the broadest installed equipment base. Microencapsulated Formulation is climbing the fastest as precision agriculture hardware penetrates row-crop operations.
End User:
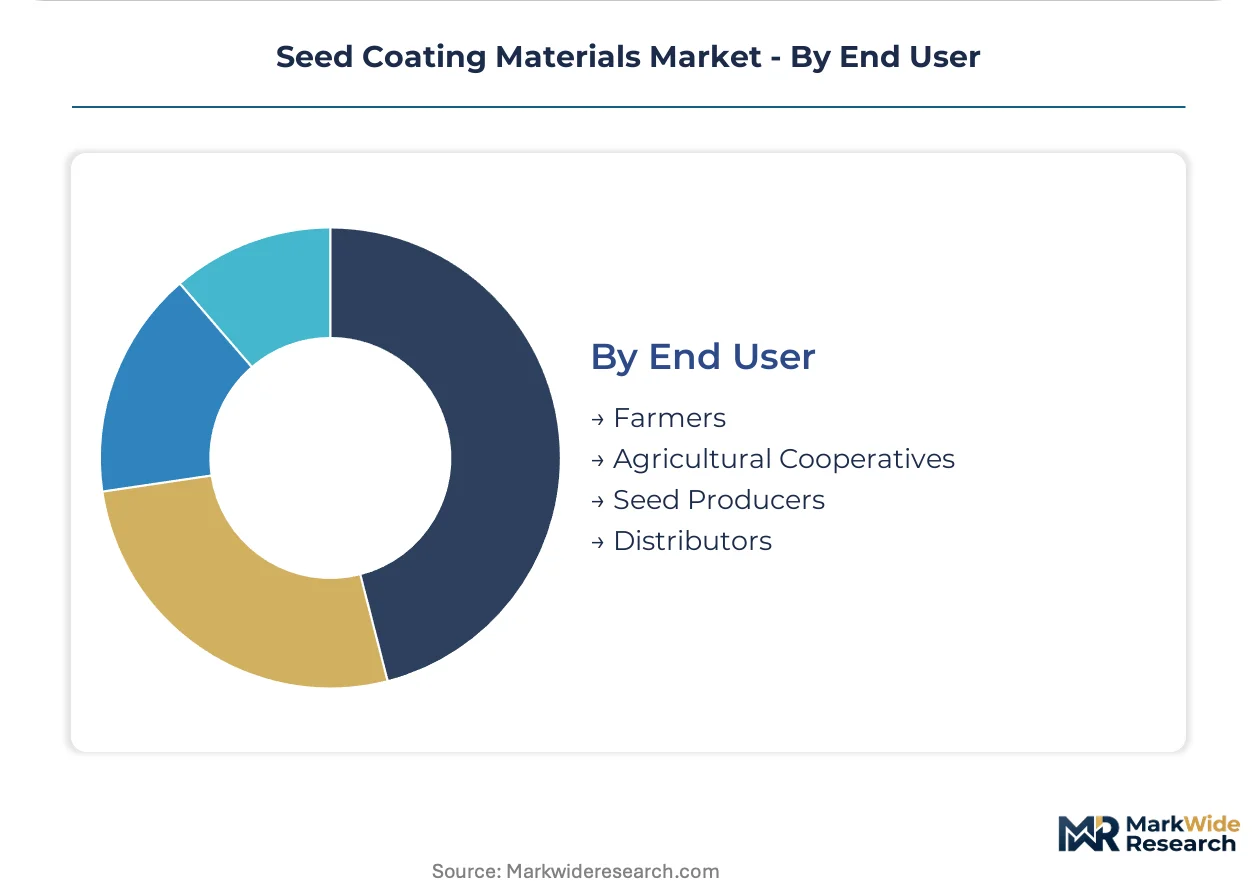
Procurement sophistication and technical specification authority vary dramatically, from price-sensitive individual farmers to seed producers with captive formulation capabilities.
- Farmers:Individual operators in developing markets and smaller US operations rely on dealer-applied treatments with limited specification input, driving spot-market purchasing patterns.
- Agricultural Cooperatives:Consolidated buying power among North American row-crop cooperatives and Brazilian land-holding companies is displacing spot-market purchases and forcing transparent per-acre pricing from coating service providers.
- Seed Producers:Major genetics companies maintain in-house formulation development or exclusive supplier relationships, integrating coating chemistry with seed genetics in bundled offerings.
- Distributors:Dealer networks are unbundling coating services from seed genetics and investing in high-speed treater upgrades to capture service revenue from cooperative outsourcing.
Seed Producers command the deepest technical integration with suppliers. Agricultural Cooperatives are gaining share fastest as procurement consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian land-holding companies outpace individual US operators in coated seed procurement consolidation, while EU regulatory pressure on synthetic polymers outstrips enforcement intensity in North American markets.
United States
Iowa and Illinois corn-soy operations drive polymer coating demand through high-speed treater networks requiring consistent flow characteristics. EPA FIFRA registrations govern pesticide-treated seed approvals, with review cycles extending for neonicotinoid actives. Dealer networks across the Midwest are unbundling coating services from seed genetics and adopting transparent per-acre pricing models.
Brazil
Mato Grosso soybean expansion zones and cerrado row-crop operators purchase coated seeds with moisture-retention actives as rainfall volatility intensifies. ANVISA enforces phytosanitary standards that shape import requirements and formulation specifications for multinational suppliers. Land-holding companies in the central-west region are consolidating volume-contract purchasing power and displacing spot-market seed treatment transactions.
Germany
Industrial seed treater manufacturers and polymer chemistry suppliers anchor the European formulation development pipeline. REACH restrictions on synthetic microplastics and EU Green Deal biodegradability mandates are forcing acrylic-to-polylactic acid binder transitions. Research clusters in North Rhine-Westphalia coordinate 18-24 month validation cycles for bio-based polymer alternatives.
Netherlands
Greenhouse vegetable and flower seed producers command premium pricing for microencapsulated nutrient coatings that reduce transplant shock. EFSA review timelines for active ingredient reauthorization are freezing product line investments across horticulture segments. Wageningen-area seed houses are consolidating supplier relationships to share reformulation testing burdens.
India
Domestic formulation capacity expansion under the PLI scheme for agrochemicals is attracting coating material suppliers to establish local blending operations. The Central Insecticides Board and Registration Committee govern pesticide approvals with divergent data requirements from Western regulators. Maharashtra and Gujarat industrial corridors are emerging as blending hubs for smallholder-accessible powder formulations.
Seed Coating Materials Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where integrated crop science pipelines pull through bundled offerings while independent coating houses capture service revenue from cooperative outsourcing. The vendor base organizes around three archetypes: integrated agrochemical-seed genetics conglomerates, specialty chemical suppliers with bio-based binder expertise, and regional coating service providers with treater network access. Dominant competitive moves include capacity expansion in biodegradable polymer systems and strategic partnerships between seed producers and specialty chemical suppliers to share regulatory testing burdens.
Within the integrated conglomerate tier, BASF SE exemplifies the bundled crop science model, while Croda International Plc and Clariant occupy positions as specialty chemical anchors with differentiated expertise in surfactant and colorant systems respectively.
| Leading Market Players |
|---|
| BASF SE |
| Croda International Plc |
| Clariant |
| Solvay |
| Incotec Group |
| Germains Seed Technology |
| Chromatech Incorporated |
| Precision Laboratories LLC |
| Lanxess AG |
| Others |
Supply Flow & Price Mechanics
Acrylic resin price indices on European commodity exchanges cascade through polymer coating supply chains into three-tier pricing structures across premium bio-based, standard synthetic, and economy mineral-based tiers. Brazilian land-holding companies and North American agricultural cooperatives exploit volume-contract leverage to compress margins on commodity formulations while horticulture seed houses in the Netherlands absorb premium pricing for microencapsulated nutrient coatings.
Pricing Analysis
Capacity additions in Germany and India's industrial corridors are reshaping price floors for biodegradable polymer binders as REACH restrictions on synthetic microplastics accelerate commercialization timelines. Three-tier pricing structure across premium bio-based, standard synthetic, and economy mineral-based levels differentiates offerings, with certification grade under EU Green Deal mandates and volume scale driving spreads. Cost compression in standard synthetic tiers is intensifying because petrochemical feedstock volatility feeds through acrylic and polyurethane precursor markets. Individual farmers in developing markets exhibit highest price sensitivity, while seed producers with captive formulation capabilities show least sensitivity due to backward integration into binder chemistry.
Supply Chain Analysis
Formulation chemist scarcity in German industrial clusters and Maharashtra-Gujarat corridors constrains batch optimization and quality control throughput for multinational suppliers. Manufacturing concentrates in Germany, India, and Brazil, with raw material dependencies spanning Brazilian cerrado-sourced starch derivatives, Indian lignin processors, and German polylactic acid polymerization facilities. Single-source vulnerability sits with European bio-based binder validation cycles that extend 18-24 months. Distribution runs through dealer network treater infrastructure across the US corn-soy belt and Mato Grosso expansion zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The seed coating materials market functions as a regulatory compounder where EU Green Deal biodegradability mandates and REACH polymer restrictions are accelerating demand displacement from synthetic to bio-based formulation platforms.
For Market Incumbents: Extend bio-based polymer capacity in German research clusters to preempt REACH enforcement timelines and defend against specialty chemical entrants capturing horticulture premium segments. Deepen captive supply of starch-derivative binders through exclusive Brazilian supplier relationships. Channel control over high-speed treater networks in Iowa and Illinois corn-soy operations anchors volume-contract renewal rates against cooperative purchasing consolidation. For New Entrants and Emerging Players: Begin with India's PLI scheme for agrochemicals to establish local blending operations serving Maharashtra and Gujarat smallholder markets with powder formulations accessible without legacy treater infrastructure. White-space targets include microencapsulated nutrient coatings for Italian greenhouse vegetable producers and carbon-accounting-integrated offerings for North American seed cooperatives requesting Scope 3 lifecycle data. Go-to-market angle centers on transparent per-acre pricing models that unbundle coating services from seed genetics. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty chemical suppliers possessing validated bio-based binder platforms and established EFSA dossier compilation capabilities. Long-term viability over a multi-year horizon hinges on regulatory testing burden-sharing partnerships with major seed producers. Acquisition target archetype includes regional coating service providers with treater network access in Brazilian central-west land-holding company zones. Signal to watch: EFSA neonicotinoid reauthorization timelines that would freeze or liberate product line investments across horticulture segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Captive supply of Brazilian starch derivatives and Indian lignin secures REACH-compliant binder raw material access. |
| Capacity Expansion in Biodegradable Polymer Systems | German industrial clusters anchor polylactic acid formulation development for EU Green Deal compliance deadlines. |
| Long-Term Supply Agreement with Agricultural Cooperatives | Volume-contract purchasing consolidation in Iowa and Illinois corn-soy belts locks in multi-season coating service revenue. |
| Joint Venture for Regulatory Dossier Sharing | Polish and Spanish horticulture seed houses split EFSA validation burdens for microencapsulated nutrient coatings. |
| Geographic Expansion via India's PLI Scheme | Maharashtra and Gujarat blending hubs capture smallholder-accessible powder formulation demand under domestic incentive structures. |
Methodological Framework
Direct dialogue with seed company formulation directors, agricultural cooperative procurement officers, polymer chemistry R&D leads, and dealer network operations managers grounded qualitative assessments in operational reality. Secondary validation drew from ANVISA phytosanitary filings, EFSA active ingredient reauthorization databases, EPA FIFRA registration records, and EU Green Deal implementation directives. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the analysis window.
Output projections span coating type, application, formulation, and end-user segments across the projection horizon. CAGRs derived from regression analysis of historical procurement patterns and regulatory milestone impacts. Industry-specific inputs included high-speed treater equipment penetration rates in North American dealer networks and rainfall volatility indices for Brazilian cerrado row-crop operators.
Several conditions sit outside the modeled scope, including abrupt EFSA or EPA active ingredient bans, trade restriction impositions on Brazilian starch derivative exports, and capital equipment upgrade cycles that would accelerate bio-based polymer adoption in legacy treater infrastructure. Forecasts reflect documented assumptions regarding regulatory timeline adherence and feedstock price stability. Material deviation in neonicotinoid reauthorization outcomes or EU microplastic enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
Mexico Seed Treatment Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
North America Seed Coating Materials Market
Seed Technology
India Seed Treatment Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
Seed Coating Ingredients Market
Seed Technology
Europe Seed Coating Materials Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
China Seed Treatment Market
Seed Technology
France Seed Treatment Market
Seed Technology
Seed Storage Systems Market
Seed Technology
Seed Quality Imaging and Germination Prediction Test Systems Market
Seed Technology
Protein Content Optimizing Cereal Fertility Program Market
Seed Technology
Seed Treatment Market
Seed Technology
Japan Seed Treatment Market