
 North America Soybean Seed Treatment Market | 2026-2036
North America Soybean Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Soybean Seed Treatment Market Analytics
Agrochemical distribution through cooperatives and farm retail networks is reconfiguring as growers consolidate acreage and demand bundled seed-plus-treatment packages. Bayer CropScience leverages its seed genetics pipeline to anchor premium treatment formulations at origin. BASF SE competes through specialized fungicide coatings targeting sudden death syndrome pressure zones. Syngenta Group extends its biologicals portfolio to capture regenerative agriculture commitments across the Mississippi River basin.
North America soybean seed treatment encompasses chemical and biological formulations applied to soybean seeds prior to planting, typically involving active ingredients such as neonicotinoids, pyrethroids, or Bacillus subtilis at application rates measured in fluid ounces per hundredweight of seed, designed to protect germinating seedlings from soilborne pathogens and early-season insect feeding. The primary commercial purpose centers on reducing replant risk and optimizing stand establishment in high-value row-crop systems where seed costs exceed historical benchmarks. Fungicide coatings dominate current product type revenue given established efficacy against Phytophthora and Rhizoctonia, while biologicals represent the fastest-expanding category as growers face pollinator protection mandates. Coating methods lead treatment method deployment due to compatibility with high-speed planting equipment, though injection systems gain share where precision agriculture adoption deepens.
EPA pesticide registration requirements under FIFRA govern active ingredient approval timelines and label restrictions, directly constraining which chemistries enter the soybean seed treatment pipeline. USDA conservation program incentives for integrated pest management practices shape grower willingness to substitute biological alternatives for conventional chemistry. NHTSA transport regulations for hazardous agricultural materials influence regional distribution logistics and treatment facility siting decisions. Stakeholders must track evolving state-level pollinator protection plans and seed-treatment stewardship certifications to anticipate which distribution channels and product formulations will retain market access.
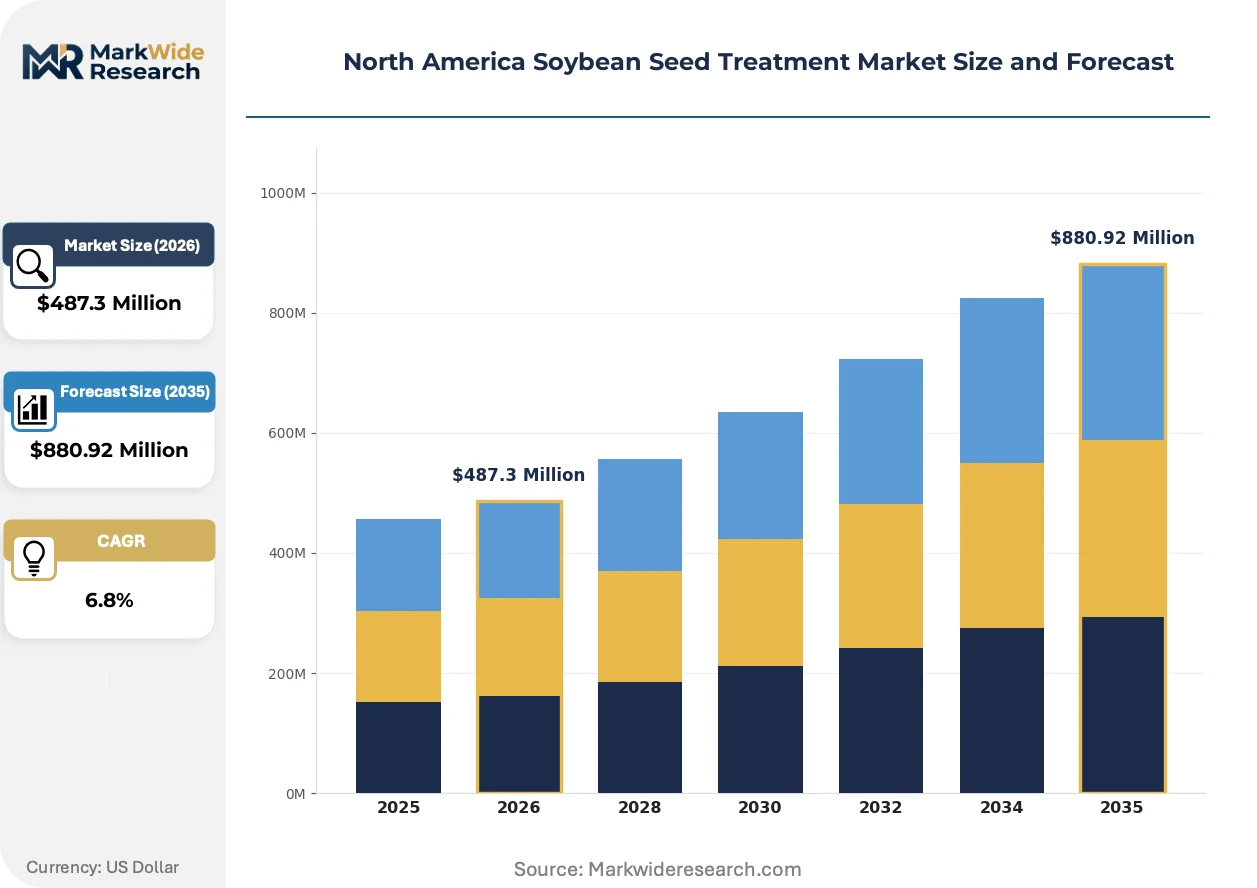
Market Dynamics
EPA neonicotinoid restrictions are compressing the chemical seed treatment pipeline while forcing rapid biological formulation development across the Corn Belt and Mississippi River basin.
Growth Catalysts
- USDA Conservation Reserve Program incentives:Federal cost-share programs for integrated pest management accelerate biological seed treatment adoption in Iowa and Illinois row-crop operations.
- High-speed planting equipment compatibility:Coating application technologies calibrated to 15+ mph planting speeds enable uniform treatment distribution across consolidated Midwest acreage.
- Replant risk economics:Seed costs exceeding $60 per acre in commercial soybean systems drive grower willingness to pay for stand establishment protection.
Market Restraints
- Active ingredient concentration:EPA FIFRA registration timelines averaging 18-24 months delay new chemistry commercialization and compress R&D payback windows.
- Biological formulation stability:Bacillus subtilis and Trichoderma viability constraints limit shelf life and complicate inventory management at farm retail cooperatives.
- Pollinator buffer mandates:State-level pollinator protection plans in Minnesota and Wisconsin restrict treated seed use within specified distances of blooming crops.
Strategic Opportunities
- Precision agriculture convergence:Variable-rate seed treatment systems paired with prescription planting maps enable zone-specific biological application across heterogeneous soils.
- Regenerative agriculture commitments:Food processor and grain elevator sustainability sourcing requirements create pull-through demand for biological-treated seed in the Mississippi River basin.
- Canadian prairie expansion:Manitoba and Saskatchewan soybean acreage growth offers underpenetrated territory for fungicide-biological combination products.
Industry Challenges
- Application technician certification:Seed-treatment stewardship programs require specialized training that farm retail networks struggle to staff at scale during compressed planting windows.
- Treatment facility siting:NHTSA hazardous materials transport regulations and EPA air quality permits complicate regional treatment hub placement near concentrated demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Soybean Seed Treatment Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticides, Fungicides, Herbicides, Biologicals Treatment Method: Coating, Soaking, Injection, Granular Application Application Area: Field, Greenhouse, Laboratory, Research Trials Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | BASF SE, Bayer CropScience, Corteva Agriscience, Syngenta Group, UPL Limited, FMC Corporation, Nufarm Limited, Albaugh LLC, Valent USA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Soybean Seed Treatment Market Evolving Landscape
Biological active ingredients are displacing conventional chemistry as the primary growth vector, while precision application hardware and sustainability-linked procurement reshape competitive positioning.
RNA interference seed treatments targeting specific soilborne pathogens are collapsing the historical trade-off between broad-spectrum chemical efficacy and biological selectivity. Pioneer and university extension programs in Indiana and Ohio are field-testing these formulations for 2026 commercial launch. The technology is collapsing resistance management timelines by enabling season-specific pathogen targeting rather than multi-year chemical rotation strategies.
EPA's 2024 revised pollinator risk assessment methodology for neonicotinoid seed treatments imposes additional data requirements on registrants seeking label renewals. The agency's endangered species consultation mandates now trigger automatic county-level use restrictions in critical habitat zones. Soybean growers in Minnesota's drift-prone regions face the most immediate operational adjustments as state departments of agriculture align enforcement protocols.
Grain elevator sustainability certification programs are restructuring procurement specifications to require documented seed treatment inputs. Archer Daniels Midland and Cargill origination facilities in Iowa now preference suppliers with biological treatment documentation for regenerative agriculture premium programs. This specification cascade is most visible in the Corn Belt where processor concentration enables rapid standard diffusion across contracted acreage.
North America Soybean Seed Treatment Market Segmentation
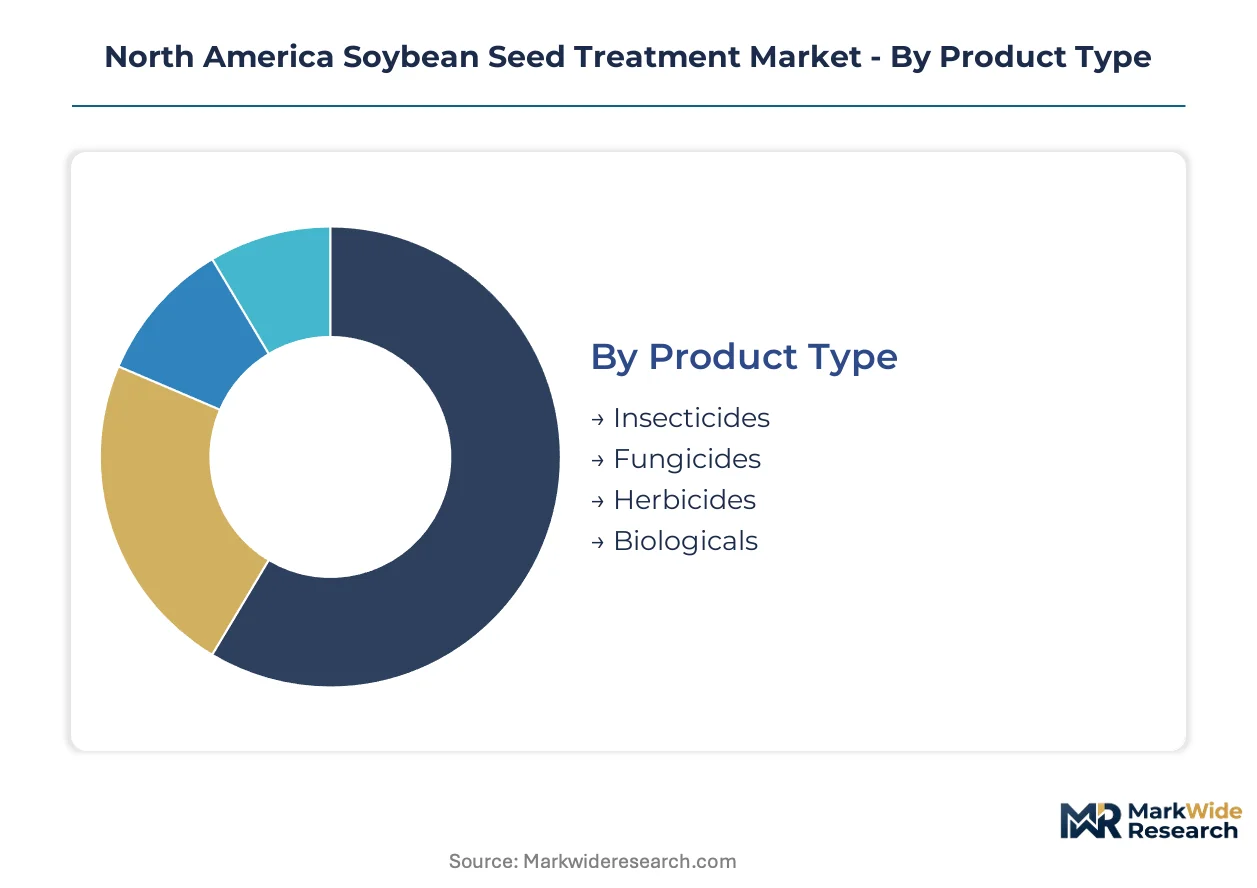
Segmentation in North America soybean seed treatment reveals how product chemistry, application hardware, and procurement channels align with distinct grower risk profiles and operational scales across the Corn Belt and Mississippi River basin.
Product Type:
Formulation chemistry spans synthetic protection and biological alternatives, with EPA registration status and pollinator mandates driving portfolio rebalancing across Iowa and Illinois operations.
- Fungicides:Azoxystrobin, metalaxyl, and fludioxonil coatings deliver systemic protection against Phytophthora sojae and Rhizoctonia solani. Demand concentrates in Minnesota and Wisconsin where cool, wet springs elevate seed rot pressure and replant risk economics justify premium treatment costs.
- Biologicals:Bacillus subtilis, Trichoderma harzianum, and Pseudomonas fluorescens formulations colonize root zones to outcompete soilborne pathogens. Adoption accelerates across the Mississippi River basin where grain elevator sustainability certifications and USDA conservation program incentives reward documented biological inputs.
- Insecticides:Neonicotinoid and pyrethroid chemistries target early-season aphid and bean leaf beetle feeding, though EPA pollinator risk assessments compress label availability in drift-prone counties.
- Herbicides:Seed-applied safeners and resistance-management chemistries complement pre-emergence spray programs, serving specialty systems where weed pressure demands layered control.
Established volume favors fungicides; emerging adoption favors biologicals.
Treatment Method:
Application hardware selection hinges on planting speed compatibility, treatment uniformity requirements, and capital investment thresholds across consolidated Midwest acreage.
- Coating:Film-coating and encrusting technologies deposit active ingredients in uniform layers compatible with 15+ mph high-speed planters. Equipment manufacturers in Indiana and Ohio calibrate systems for 80,000+ seeds per acre application rates.
- Injection:In-furrow liquid delivery systems enable variable-rate biological application tied to prescription planting maps. Precision agriculture adopters in Nebraska and Kansas deploy these systems where soil heterogeneity demands zone-specific treatment intensity.
- Soaking:Immersion protocols serve research trials and greenhouse propagation where small batch sizes and precise dosage control outweigh throughput constraints.
- Granular Application:Box-and-hopper systems deliver treatment in dry form, persisting in older equipment fleets and specialty seed operations with lower volume throughput.
Coating dominates commercial throughput; injection climbs fastest where precision agriculture investment deepens.
Application Area:
End-use context determines formulation specification, regulatory compliance burden, and performance validation requirements across the value chain.
- Field:Commercial row-crop deployment in Iowa, Illinois, and Indiana drives 90%+ of volume, with treatment specifications calibrated to local pathogen pressure and planting date windows.
- Research Trials:University extension programs and seed company R&D stations in Ohio and Missouri test novel active ingredients under controlled conditions, generating efficacy data for EPA registration submissions.
- Greenhouse:Controlled-environment propagation for seed stock multiplication requires specialized low-phytotoxicity formulations with abbreviated re-entry intervals.
- Laboratory:Quality control testing and formulation stability validation occur at regional treatment hubs prior to commercial release.
Field deployment anchors revenue; research trials shape tomorrow's commercial pipeline.
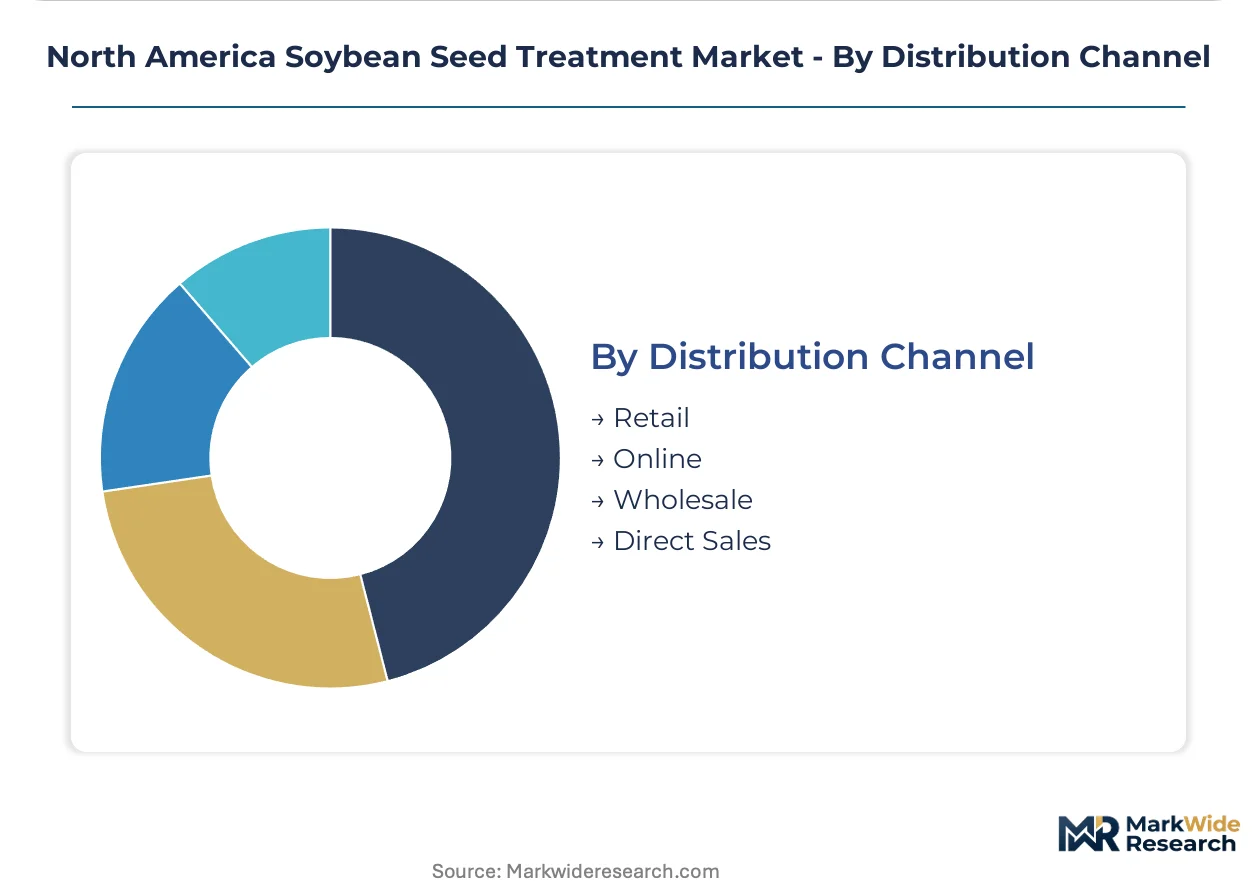
Distribution Channel:
Procurement pathway selection reflects grower scale, information access preferences, and bundled service requirements across the North American soybean belt.
- Retail:Farm supply cooperatives and independent dealers in Minnesota and Wisconsin dominate, offering seed-plus-treatment packages with application services and agronomic consultation.
- Direct Sales:Major seed genetics companies bypass intermediaries for large commercial growers exceeding 5,000 acres, delivering custom treatment formulations at origin.
- Wholesale:Regional distributors supply smaller retail networks and treatment facilities with bulk active ingredients and coating polymers.
- Online:Digital procurement platforms gain traction among younger operators seeking price transparency, though treated seed transport regulations limit pure-play e-commerce penetration.
Retail retains volume leadership; direct sales capture margin in the largest operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Midwest Corn Belt where consolidated acreage and cooperative distribution networks command premium treatment packages, while Canadian prairie expansion operates at thinner margins driven by acreage growth rather than input intensity.
United States
Commercial growers across Iowa and Illinois drive 80% of regional volume through bundled seed-plus-treatment procurement at farm retail cooperatives. EPA's 2024 revised pollinator risk assessment methodology triggers automatic county-level use restrictions in critical habitat zones, compressing neonicotinoid availability. Treatment facilities cluster around Des Moines and Peoria to serve concentrated demand within 150-mile distribution radii.
Canada
Manitoba and Saskatchewan soybean acreage expansion creates underpenetrated territory for fungicide-biological combination products as growers transition from canola-dominant rotations. Health Canada PMRA registration timelines align with EPA FIFRA protocols, enabling simultaneous North American label submissions. Winnipeg-based distribution hubs coordinate cross-border formulation supply from US Midwest manufacturing centers.
Mexico
Sinaloa and Sonora irrigation districts anchor Pacific coast soybean production for export markets, with treatment adoption lagging US benchmarks by 3-5 years. The country's national agricultural regulator enforces pesticide residue standards tied to EU and US export requirements. Guadalajara serves as formulation packaging hub for regional redistribution across Central American markets.
North America Soybean Seed Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in active ingredient supply. The vendor base organizes around three strategic tiers: multinational agrochemical conglomerates with captive seed genetics pipelines, mid-scale formulation specialists targeting regional pathogen pressures, and biological technology developers commercializing novel microbials. Competitive intensity concentrates on M&A activity to secure biological R&D capabilities and strategic partnerships between equipment manufacturers and treatment applicators.
Among European-based conglomerates, BASF SE and Bayer CropScience occupy positions as platform integrators leveraging seed genetics pipelines to anchor premium treatment formulations. Syngenta Group represents the biologicals-focused archetype, extending its portfolio to capture regenerative agriculture procurement specifications across the Mississippi River basin.
| Leading Market Players |
|---|
| BASF SE |
| Bayer CropScience |
| Corteva Agriscience |
| Syngenta Group |
| UPL Limited |
| FMC Corporation |
| Nufarm Limited |
| Albaugh LLC |
| Valent USA |
| Others |
Value Network & Pricing Analysis
Mississippi River barge freight corridors govern active ingredient transport economics between Midwest manufacturing hubs and Gulf Coast export terminals, concentrating pricing power among treatment facilities within 150-mile distribution radii of Des Moines and Peoria while forcing downstream price differentiation between bundled seed-plus-treatment packages and standalone treatment services.
Pricing Analysis
The customization-premium spread separates standard fungicide coatings from precision-calibrated biological-injection systems, with three-tier pricing structure across premium, standard, and economy levels anchored by treatment uniformity guarantees and planting-speed compatibility. Price differentiation hinges on EPA registration tier and volume scale, with cooperative procurement pools commanding 15-20% standard discounts. Pricing pressure stems from biological formulation stability costs compressing margins at farm retail cooperatives. Commercial growers exceeding 5,000 acres exhibit lowest price sensitivity due to replant risk economics, while smaller operators in Minnesota and Wisconsin face highest sensitivity to per-acre treatment premiums.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for neonicotinoid technical-grade imports and biological fermentation feedstocks. Geographic supply concentration centers on Iowa, Illinois, and Indiana for formulation blending, with Germany and Switzerland anchoring specialized polymer coating inputs. Raw material dependencies include azoxystrobin technical, Bacillus subtilis fermentation cultures, and film-coating polymers. Distribution runs through farm retail cooperative networks and direct sales channels from major seed genetics companies to large commercial operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
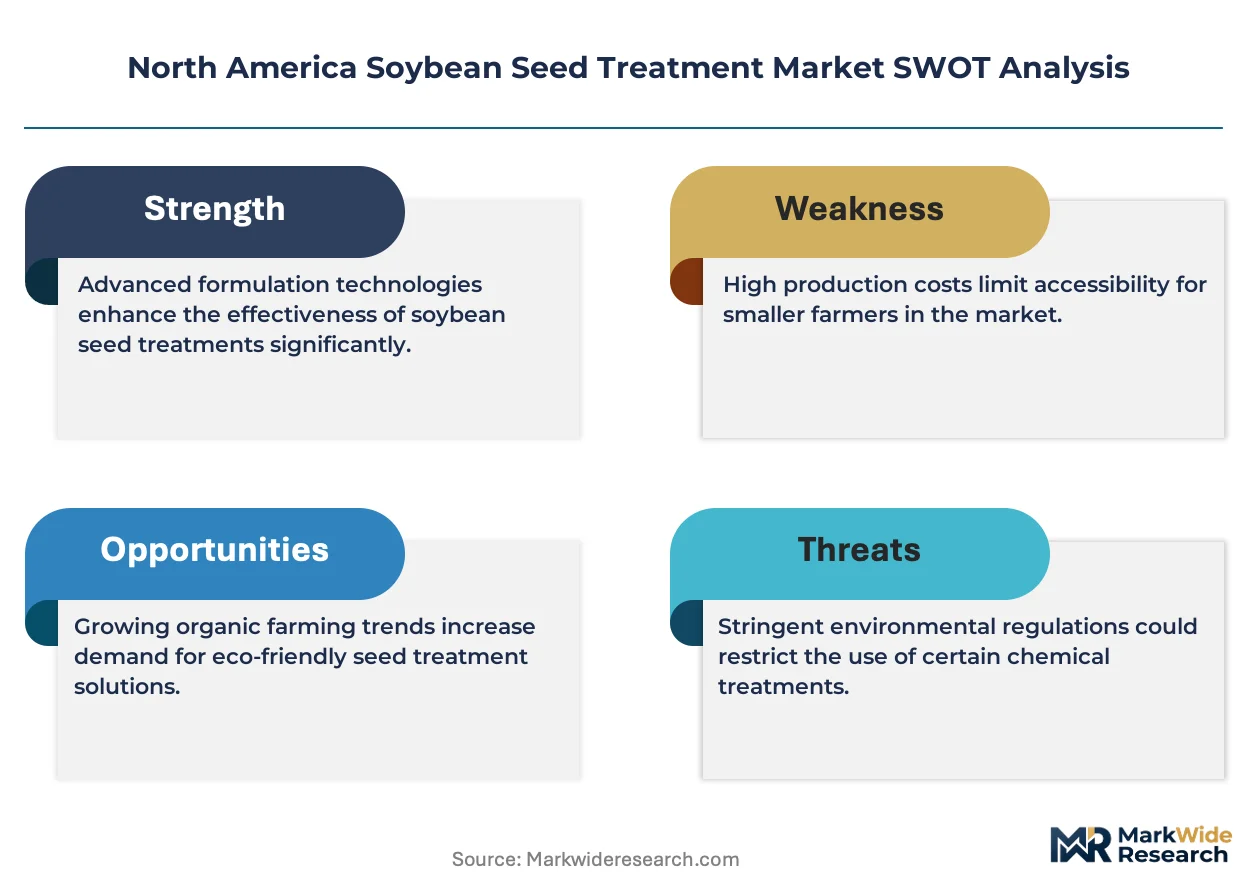
The North America soybean seed treatment market represents an early-cycle expansion story, with biological formulation adoption accelerating across the Corn Belt as EPA pollinator mandates compress conventional chemistry availability and grain elevator sustainability certifications create procurement pull-through.
For Market Incumbents: Pre-empt biological R&D capability gaps by acquiring specialized microbial formulation developers before registration timelines compress further. Anchor backward integration into Bacillus subtilis fermentation capacity to secure supply chain control against single-source vulnerability from contract manufacturers. Defensive consolidation around seed genetics-treatment bundling will neutralize margin pressure from pure-play biological entrants targeting regenerative agriculture premiums. For New Entrants and Emerging Players: Canadian prairie soybean acreage in Manitoba and Saskatchewan represents the most penetrable entry point, with fungicide-biological combination products serving growers transitioning from canola-dominant rotations. Variable-rate injection system deployment in Nebraska and Kansas offers equipment-anchored go-to-market positioning where soil heterogeneity demands zone-specific biological application. Precision agriculture partnerships with planting equipment manufacturers provide channel access without cooperative network dependency. For Investors and Strategic Acquirers: Biological technology developers with EPA-registration-ready formulations and Health Canada PMRA submission capability offer the strongest acquisition target archetype for North American market access. Long-term viability over the next decade hinges on pollinator protection mandate trajectory and regenerative agriculture procurement specification diffusion. Signal to watch: state-level pollinator buffer mandate expansion beyond Minnesota and Wisconsin into Iowa and Illinois, which would accelerate biological substitution timelines and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Formulation Registration | EPA FIFRA submission capability secures market access as neonicotinoid restrictions tighten across drift-prone counties. |
| Seed Genetics Pipeline Integration | Bundled seed-plus-treatment packages at origin capture premium pricing and lock in cooperative distribution channels. |
| Precision Agriculture Partnership | Variable-rate injection system compatibility with prescription planting maps enables zone-specific biological application. |
| Canadian Distribution Hub Establishment | Winnipeg-based formulation packaging captures Manitoba and Saskatchewan acreage expansion with cross-border supply efficiency. |
| Regenerative Agriculture Certification | Documented biological treatment inputs satisfy Archer Daniels Midland and Cargill sustainability procurement specifications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with seed treatment facility managers, farm retail cooperative procurement directors, EPA regulatory affairs specialists, and grain elevator sustainability program coordinators. Secondary validation drew from USDA conservation program databases, EPA FIFRA registration filings, Health Canada PMRA submission records, and Mississippi River barge freight rate indices. Bottom-up acreage estimates and top-down chemical input demand models were triangulated to calibrate market sizing.
Calibration against historical adoption curves and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry, application hardware type, procurement channel structure, and grower operational scale tier. CAGRs were derived from regression analysis of planted acreage trends, input cost inflation patterns, and biological substitution elasticity estimates. Industry-specific forecast inputs incorporated EPA pollinator risk assessment revision schedules and grain elevator sustainability certification diffusion rates.
Practitioners should monitor EPA endangered species consultation triggers and state pollinator protection plan enforcement protocols for early signals of county-level use restriction expansion. Forecasts reflect assumptions regarding biological formulation stability improvement and cooperative network consolidation trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Processing Innovations
Maize Seed Treatment Market
Seed Processing Innovations
Seed Sorting Machine Market
Seed Processing Innovations
Sprouted Durum Wheat for Pasta Applications Market
Seed Processing Innovations
Brazil Seed Treatment Market
Seed Processing Innovations
Argentina Seed Treatment Market
Seed Processing Innovations
South America Seed Treatment Market
Seed Processing Innovations
Fenugreek Seed Extract Market
Seed Processing Innovations
Rice Seed Treatment Market
Seed Processing Innovations
Soybean Seed Treatment Market
Seed Processing Innovations
North America Seed Treatment Market
Seed Processing Innovations
United States Seed Treatment Market
Seed Processing Innovations
Asia-Pacific Seed Treatment Market
Seed Processing Innovations
India Seed and Grain Cleaning and Grading Machine Market
Seed Processing Innovations
Kiwi Seed Extract Market
Seed Processing Innovations
Alfalfa Seed Extract Market
Seed Processing Innovations
Oilseed Processing Market