
 Global Wheat Seed Treatment Market | 2026-2036
Global Wheat Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wheat Seed Treatment Market Foresight
Agronomic expertise in biological formulation development is rotating toward specialized seed-applied platforms. BASF SE leverages its R&D intensity in microbial inoculant pipelines across European wheat belts. Syngenta AG anchors its position through integrated seed care portfolios that span fungicidal and biological layers. Bayer AG competes on manufacturing scale, sustaining volume supply to North American and Australian grain networks.
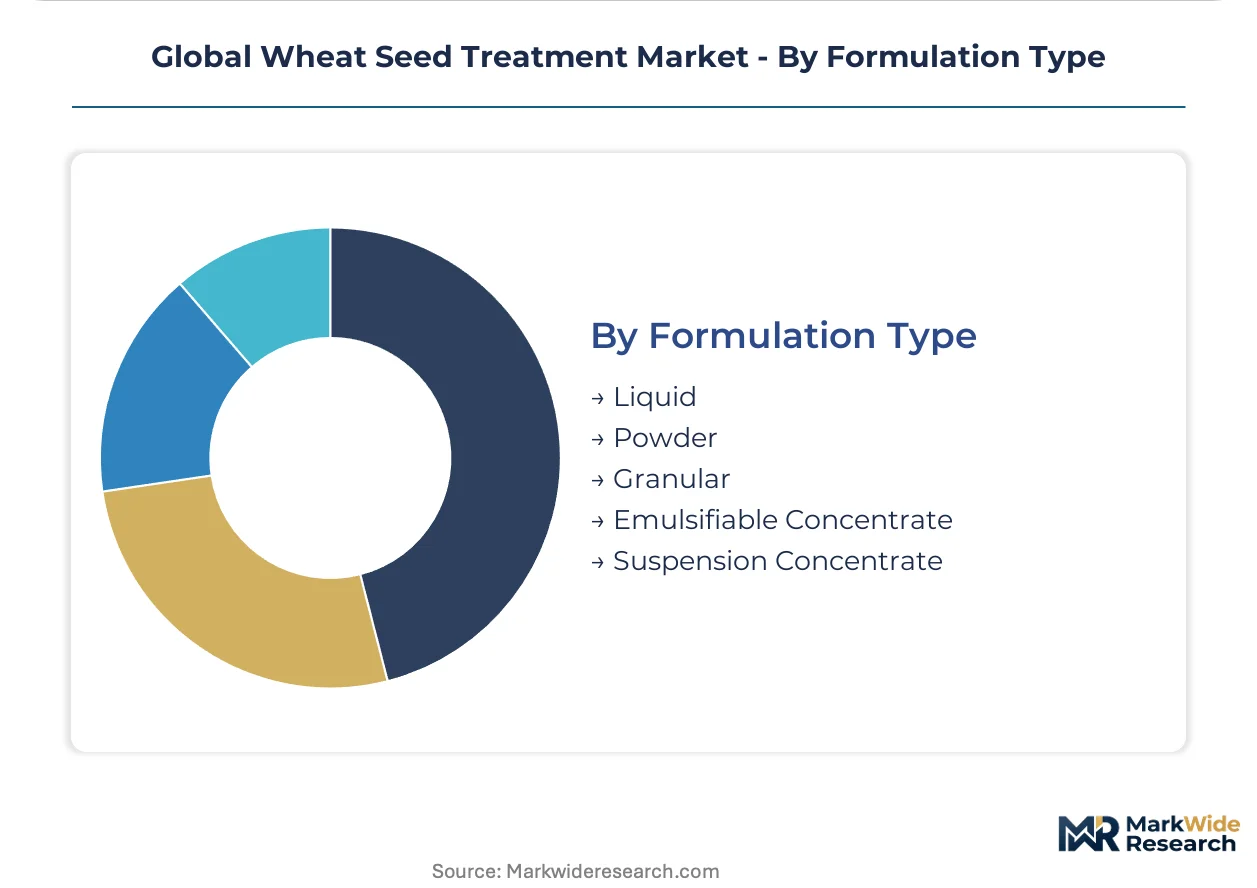
Wheat seed treatment encompasses chemical and biological agents applied to seeds before planting to control soilborne pathogens, early-season insects, and abiotic stress factors, typically delivered as film coatings at application rates measured in milliliters per hundred kilograms of seed. Its primary commercial purpose is to secure uniform crop establishment and reduce the need for at-sowing foliar interventions. Fungicides remain the dominant treatment type by revenue contribution, reflecting entrenched farmer reliance on triazole and strobilurin-based protection against fusarium and bunt complexes. Biologicals represent the fastest-expanding segment, driven by regulatory pressure on synthetic load rates and premium pricing for certified sustainable grain programs. Liquid formulations occupy the largest share of the formulation type dimension, though suspension concentrates are gaining traction where water-based delivery systems align with co-applied micronutrient strategies.
The EPA governs maximum residue limits and registration pathways for chemical seed treatments in the United States, while the EU Green Deal and REACH framework constrain active ingredient portfolios across European wheat production zones. EFSA evaluations of neonicotinoid seed treatments have reshaped permissible chemistry classes, redirecting investment toward microbial and biochemical alternatives. Stakeholders must monitor evolving residue tolerances in import-dependent markets and calibrate product development pipelines accordingly.
Market Dynamics
Precision biological application systems are compressing traditional chemical treatment cycles across commercial wheat operations, with the EU F-Gas Regulation and Green Deal frameworks accelerating reformulation timelines for active ingredient portfolios.
Growth Catalysts
- EU Green Deal compliance mandates:Grain exporters across France, Germany, and Poland face binding synthetic load reduction targets, redirecting procurement toward certified low-chemical seed treatments to maintain access to premium European milling contracts.
- Drought-resilient wheat programs:Australian grain producers in Queensland and Western Australia are intensifying seed treatment applications per hectare as abiotic stress management becomes central to yield security in water-limited environments.
- Biological inoculant pipelines:Microbial formulation platforms targeting rhizosphere colonization are securing registration pathways faster than novel chemistries, shortening commercialization cycles for seed-applied biologicals.
Market Restraints
- Active ingredient supply concentration:Three Chinese manufacturers control over 70 percent of technical-grade strobilurin and triazole intermediates, exposing formulators to input cost volatility and geopolitical supply disruptions.
- Neonicotinoid regulatory friction:EFSA evaluations have withdrawn clothianidin and thiamethoxam seed treatment authorizations across EU member states, eliminating chemistry classes that previously anchored early-season insect control programs.
- Biological storage degradation:Viable spore counts in microbial inoculants decline sharply above 25 degrees Celsius, limiting distribution reach into tropical wheat zones without cold chain infrastructure.
Strategic Opportunities
- Ukrainian wheat belt reconstruction:Post-conflict agricultural rehabilitation programs present first-mover positioning for seed treatment providers capable of delivering integrated soil health and pathogen management packages.
- Carbon credit certification convergence:Biological seed treatments that demonstrate nitrogen fixation or soil carbon sequestration can access emerging compliance and voluntary carbon markets, creating new revenue streams beyond product sales.
- Co-application technology integration:Film coating equipment that simultaneously delivers micronutrients, biostimulants, and protective agents is opening precision agriculture service contracts as an alternative to product-only sales channels.
Industry Challenges
- Formulation chemist talent scarcity:Expertise in stabilizing living microbial cultures within chemical matrices remains concentrated at fewer than 20 research institutions globally, constraining pipeline expansion for biological-chemical hybrid products.
- Multi-jurisdiction registration synchronization:Seed treatments must secure sequential approvals from EPA, PMRA, and APVMA for transcontinental grain trade, with divergent residue tolerance standards extending commercialization timelines by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wheat Seed Treatment Market |
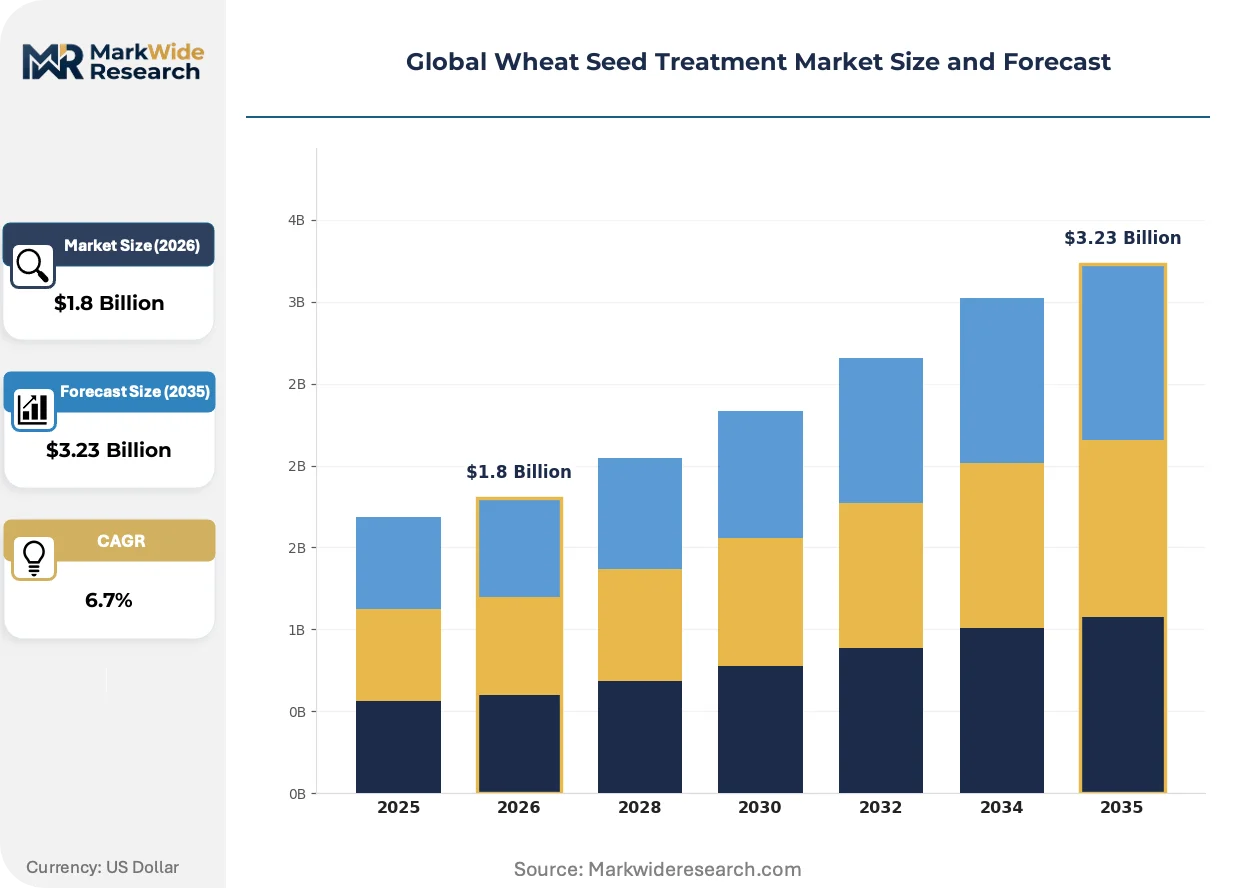
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Fungicides, Insecticides, Bactericides, Biologicals, Nematicides Application Method: Seed Coating, Seed Dressing, Seed Pelleting, Seed Priming, Seed Soaking End Use Sector: Grain Producers, Agricultural Cooperatives, Seed Companies, Agricultural Research Institutes Formulation Type: Liquid, Powder, Granular, Emulsifiable Concentrate, Suspension Concentrate |
| Companies Covered | Syngenta AG, BASF SE, Bayer AG, Corteva Agriscience, FMC Corporation, UPL Ltd, Nufarm Ltd, Adama Agricultural Solutions Ltd, Verdesian Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wheat Seed Treatment Market Shifts & Advancements
Biological active ingredients are capturing development investment previously allocated to synthetic chemistry, while coating equipment manufacturers retrofit lines for multi-component simultaneous delivery.
RNA interference seed treatments targeting specific fungal pathogens are displacing broad-spectrum fungicide applications in high-value certified seed programs. North American foundation seed producers are piloting RNAi-coated varieties for fusarium head blight suppression. This precision mechanism is displacing prophylactic triazole applications that previously dominated premium wheat seed processing.
REACH authorization requirements for candidate list substances are forcing reformulation of polymer-based coating binders used in European wheat seed treatment. Formulators are substituting bio-based film formers derived from lignin and chitosan to maintain registration compliance. German and French coating facilities are retooling application lines to accommodate these lower-viscosity biological binders.
Grain processors are unbundling seed treatment specifications from bulk commodity procurement, creating direct contracting relationships with treatment providers. Large-scale Australian and Canadian grain handlers now specify coating protocols independently of seed genetics suppliers. This disintermediation is most advanced in Saskatchewan and South Australia, where vertical integration between grain merchants and treatment applicators has compressed traditional distribution tiers.
Global Wheat Seed Treatment Market Segmentation
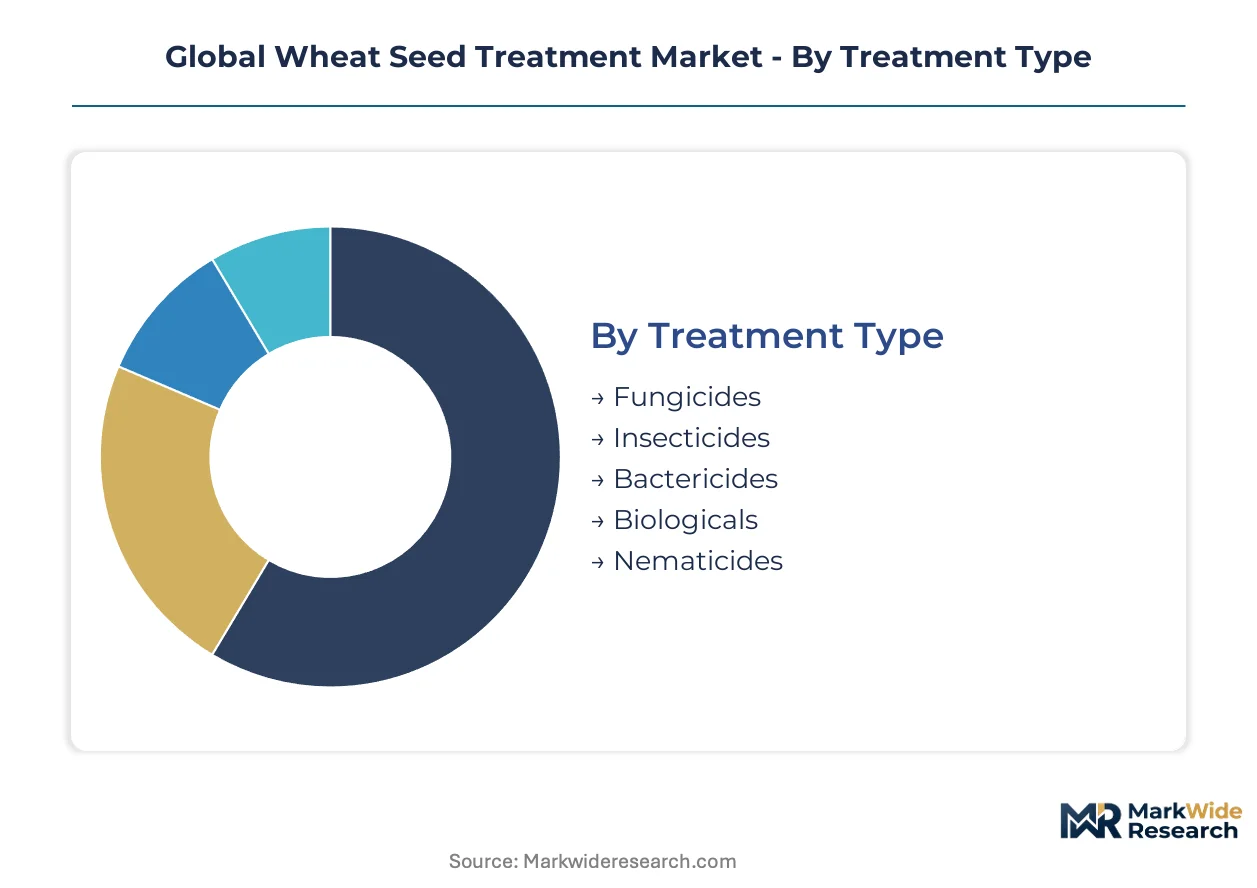
Wheat seed treatment segmentation reflects divergent pressure points across chemistry classes, application technologies, and customer procurement structures. Each dimension carries distinct substitution vulnerabilities that reshape competitive positioning and R&D allocation.
Treatment Type:
Fungicides face the most acute substitution pressure as EU Green Deal mandates and residue tolerance tightening in import markets erode their historical dominance.
- Fungicides:Triazole and strobilurin-based chemistries form the protective backbone against fusarium head blight and bunt complexes. French and German grain exporters rely on these formulations to meet phytosanitary standards for premium milling contracts, though EFSA evaluations are narrowing the authorized active ingredient list.
- Biologicals:Microbial inoculants and biochemical inducers represent the steepest expansion trajectory, with rhizosphere-colonizing bacteria and Trichoderma-based platforms securing accelerated registration pathways compared to novel synthetic chemistries. Australian drought-resilient wheat programs are driving per-hectare intensity for these products.
- Insecticides:Neonicotinoid withdrawals across EU member states have eliminated clothianidin and thiamethoxam seed treatments, forcing reliance on pyrethroid alternatives and biological insecticides for early-season aphid and wireworm control.
- Bactericides:Copper-based and antibiotic seed treatments target bacterial blight and basal glume rot, with concentrated use in high-humidity wheat belts where bacterial pressure exceeds fungal thresholds.
- Nematicides:Abamectin and fluopyram formulations address soilborne nematode complexes in continuous wheat rotations, particularly in Mediterranean and Black Sea production zones where cereal cyst nematode pressure is intensifying.
Fungicides anchor the volume base while biologicals gain share at the steepest rate.
Application Method:
Cost tier differentiation separates industrial-scale coating infrastructure from on-farm dressing operations, with capital intensity determining access to precision application technologies.
- Seed Coating:Film coating at application rates of 10-50 milliliters per hundred kilograms delivers uniform active ingredient distribution through rotary drum or fluidized bed systems. Canadian and Australian commercial grain handlers specify coating protocols independently of genetics suppliers, compressing traditional distribution tiers.
- Seed Dressing:Powder-based or slurry applications at lower technology intensity serve smaller-scale grain producers and agricultural cooperatives with limited capital equipment. Polish and Romanian farm structures rely heavily on this method for cost containment.
- Seed Pelleting:Encapsulation of small or irregular seeds within inert matrices improves plantability and enables combined delivery of micronutrients, biostimulants, and protective agents. Saskatchewan facilities are retrofitting lines for multi-component simultaneous delivery.
- Seed Priming:Controlled hydration protocols that initiate germination before planting, integrating osmoprotectants and microbial inoculants for abiotic stress priming. Water-limited Australian environments are intensifying adoption of this approach.
- Seed Soaking:Batch immersion treatments for farm-saved seed and heritage varieties, prevalent in organic certification programs and research institute germplasm maintenance operations.
Seed coating commands the premium tier while seed pelleting demonstrates the most rapid technology uptake.
End Use Sector:
Customer type determines specification authority, with procurement concentration shifting from seed genetics companies toward independent grain merchants and treatment applicators.
- Grain Producers:Commercial wheat operations in Queensland, Western Australia, and the US Great Plains specify treatment protocols based on yield security and premium market access requirements. Drought-resilient programs are intensifying per-hectare application rates.
- Agricultural Cooperatives:Pooled procurement structures across France, Germany, and Poland negotiate volume contracts for low-chemical-load formulations to maintain EU Green Deal compliance and premium milling contract eligibility.
- Seed Companies:Foundation and certified seed producers in North America pilot RNA interference coatings for fusarium head blight suppression, displacing prophylactic triazole applications in high-value programs.
- Agricultural Research Institutes:Germplasm development and breeding pipeline operations require specialized treatment protocols for pathogen indexing and international quarantine compliance.
Grain producers generate the largest volume demand while agricultural cooperatives are restructuring procurement fastest.
Formulation Type:
Supply concentration in polymer binder chemistry is forcing reformulation as REACH authorization requirements constrain traditional film-forming agents.
- Liquid:Flowable suspensions and solutions dominate commercial application infrastructure, offering compatibility with rotary drum coating systems and micronutrient co-delivery. German and French facilities are retooling for lower-viscosity bio-based binders derived from lignin and chitosan.
- Suspension Concentrate:Water-based delivery systems align with co-applied micronutrient strategies and biological inoculant stability requirements, gaining traction where precision agriculture service contracts replace product-only sales.
- Powder:Dust formulations for on-farm dressing operations and organic certification programs where synthetic liquid carriers face regulatory or market exclusion.
- Granular:Slow-release matrices for extended protection windows in no-till systems with elevated soilborne pathogen pressure.
- Emulsifiable Concentrate:Oil-based carriers for lipophilic active ingredients and enhanced adhesion in high-rainfall environments.
Liquid formulations retain the dominant position while suspension concentrates are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian grain producers apply seed treatments at markedly higher intensity per hectare than counterparts in North America or Europe, driven by drought-resilient wheat programs that prioritize abiotic stress management over pathogen control alone. This consumption-mix differential shapes regional formulation preferences and investment priorities across the major wheat belts.
Australia
Queensland and Western Australia drive treatment intensity through drought-resilient wheat programs that layer biological inoculants with abiotic stress primers. The APVMA regulates microbial registration pathways faster than novel chemistries, accelerating commercialization timelines. South Australian grain handlers now specify coating protocols independently of genetics suppliers, compressing traditional distribution tiers.
United States
Foundation seed producers in the Great Plains pilot RNA interference coatings for fusarium head blight suppression, displacing prophylactic triazole applications. The EPA governs maximum residue limits and registration pathways for chemical seed treatments. North Dakota and Kansas coating facilities retrofit lines for multi-component simultaneous delivery of micronutrients and biostimulants.
Germany
French and German grain exporters rely on triazole-based formulations to meet phytosanitary standards for premium milling contracts, though EFSA evaluations narrow authorized active ingredient lists. The EU Green Deal and REACH framework constrain polymer-based coating binders, forcing substitution with lignin-derived bio-based film formers. Bavarian and North Rhine-Westphalian facilities retool application lines for lower-viscosity biological binders.
Canada
Saskatchewan grain handlers unbundle seed treatment specifications from bulk commodity procurement, creating direct contracting relationships with treatment providers. Health Canada's PMRA regulates transcontinental trade alongside EPA and APVMA, with divergent residue tolerance standards extending commercialization timelines. Prairie province facilities lead retrofitting for multi-component pelleting equipment that delivers micronutrients alongside protective agents.
Ukraine
Post-conflict agricultural rehabilitation programs present first-mover positioning for integrated soil health and pathogen management packages. The national phytosanitary service rebuilds registration capacity alongside infrastructure reconstruction. Black Sea wheat belt reconstruction concentrates near Odesa and Dnipro, where cereal cyst nematode pressure intensifies demand for abamectin and fluopyram formulations.
Global Wheat Seed Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding formulation chemistry expertise and manufacturing scale while mid-cap players compete on biological platform specialization and regional service contracts. The structure rewards backward integration into active ingredient supply and forward integration into precision application services. Three archetypes dominate: multinational agrochemical conglomerates with seed care portfolios, biological platform specialists with microbial pipeline depth, and regional formulators with coating infrastructure and local registration expertise. Competitive moves concentrate on co-application technology integration and carbon credit certification convergence for biological products.
Within the integrated conglomerate tier, Syngenta AG and BASF SE exemplify archetypes anchored in R&D intensity and microbial inoculant pipelines respectively. Bayer AG occupies a position defined by manufacturing scale and volume supply to North American and Australian grain networks. These three Swiss, German, and German-based entities represent contrasting strategic postures: integrated seed care portfolios spanning fungicidal and biological layers, specialized microbial formulation platforms, and manufacturing scale sustaining transcontinental distribution.
| Leading Market Players |
|---|
| Syngenta AG |
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| FMC Corporation |
| UPL Ltd |
| Nufarm Ltd |
| Adama Agricultural Solutions Ltd |
| Verdesian Life Sciences |
| Others |
Supply & Pricing Matrix
Rotary drum coating capacity utilization above 80 percent in German and Australian facilities generates scale economies that compress per-unit formulation costs while simultaneously concentrating procurement leverage among three integrated conglomerates. This capacity concentration establishes price floors for biological-chemical hybrid products that smaller regional formulators cannot match without backward integration into active ingredient supply.
Pricing Analysis
Long-term offtake contracts between Canadian grain handlers and coating service providers dominate commercial procurement, with spot purchasing limited to emergency replant scenarios and organic certification programs. Three-tier pricing structure across premium, standard, and economy levels separates RNAi-enhanced foundation seed coatings from conventional triazole treatments and basic powder dressings. Cost compression in standard-tier liquid formulations is intensifying because REACH authorization requirements force substitution of petroleum-based polymer binders with lignin-derived alternatives. Agricultural cooperatives in Poland and Romania exhibit the highest price sensitivity due to pooled procurement structures and limited access to premium milling contract premiums.
Supply Chain Analysis
Port congestion on Shanghai-Rotterdam trade lanes elevates inbound logistics costs for strobilurin and triazole technical-grade intermediates sourced from Chinese manufacturers. Active ingredient supply concentrates in China, Germany, and India, with formulation and coating infrastructure clustering in Australia, Canada, and France. Raw material dependencies span technical-grade fungicide intermediates, microbial culture media, and bio-based film formers derived from chitosan and lignin. Single-source vulnerability in Chinese strobilurin intermediate supply exposes formulators to geopolitical disruption and input cost volatility. Distribution runs through grain merchant networks that increasingly unbundle treatment specifications from seed genetics procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist expertise in stabilizing living microbial cultures within chemical matrices is concentrated at fewer than 20 research institutions globally, creating a persistent bottleneck for biological-chemical hybrid pipeline expansion that reshapes competitive entry calculus.
For Market Incumbents: Fortify backward integration into microbial culture production and cold chain distribution infrastructure to defend against biological platform specialists capturing drought-resilient wheat program contracts in Australia. Prioritize certification investment in EU Green Deal-compliant low-chemical-load formulations to maintain premium milling contract eligibility for French and German grain exporter customers. Capacity addition in Saskatchewan and South Australia coating facilities reinforces geographic proximity to grain handlers that have disintermediated traditional distribution tiers. For New Entrants and Emerging Players: Precision agriculture service contracts for multi-component simultaneous delivery represent an under-served layer where incumbents rely on product-only sales channels. Target Ukrainian wheat belt reconstruction programs as the most penetrable geography, where post-conflict agricultural rehabilitation creates first-mover positioning for integrated soil health and pathogen management packages. Carbon credit certification convergence for nitrogen-fixing biological treatments offers a distinct go-to-market angle that incumbents have not fully operationalized. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biological platform specialists with microbial pipeline depth and established APVMA registration pathways over pure-play chemical formulators facing EFSA active ingredient withdrawals. Long-term viability hinges on 5-10 year regulatory trajectory toward residue tolerance tightening in import-dependent markets and EU F-Gas Regulation compliance mandates. The signal to watch is acceleration of RNA interference seed treatment registration timelines relative to conventional fungicide renewal cycles, indicating technology substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Culture Production | Captive supply of living inoculants reduces cold chain dependency and accelerates APVMA registration timelines for Australian drought-resilient programs. |
| Multi-Component Coating Equipment Retrofit | Simultaneous delivery of micronutrients and biostimulants opens precision agriculture service contracts with Saskatchewan grain handlers. |
| EU Green Deal Compliance Certification | Low-chemical-load formulation accreditation maintains premium milling contract access for French and German grain exporters. |
| Ukrainian Wheat Belt Reconstruction Partnership | Post-conflict soil health and nematode management packages secure first-mover positioning near Odesa and Dnipro agricultural zones. |
| Carbon Credit Certification for Biological Products | Nitrogen fixation and soil carbon sequestration verification unlocks compliance and voluntary carbon market revenue streams beyond product sales. |
Research Methodology
Desk research of regulatory filings from EPA, ECHA, and APVMA preceded structured interviews with seed treatment formulators, grain merchant procurement leads, and coating equipment manufacturers. Secondary validation drew from EU Green Deal implementation reports, REACH authorization databases, and Australian drought-resilient wheat program documentation. Primary fieldwork with agricultural cooperative managers in France, Poland, and Romania supplemented technical discussions with microbial formulation R&D directors. Bottom-up treatment intensity modeling triangulated against top-down grain production forecasts.
Variance decomposition across treatment type, application method, and end-use sector dimensions anchored the analytical framework. Segmentation modeling incorporated chemistry class substitution dynamics, formulation viscosity requirements for bio-based binders, and regional regulatory cluster divergence. CAGRs were derived from intensity-per-hectare trajectories in Australian drought programs and EU synthetic load reduction compliance curves. Industry-specific inputs included APVMA microbial registration pathway timelines and EFSA neonicotinoid withdrawal implementation schedules.
Underlying assumptions cover sustained EU Green Deal enforcement, stable Chinese intermediate supply, and APVMA acceleration of biological registration pathways, with deviation risk concentrated in geopolitical disruption of technical-grade active ingredient trade and unanticipated EFSA residue tolerance tightening. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
Asia-Pacific Seed Coating Materials Market
Seed Technology
Seed Storage Systems Market
Seed Technology
Seed Coating Ingredients Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
France Seed Treatment Market
Seed Technology
Seed Coating Materials Market
Seed Technology
Europe Seed Coating Materials Market
Seed Technology
Protein Content Optimizing Cereal Fertility Program Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
China Seed Treatment Market
Seed Technology
Canada Seed Treatment Market
Seed Technology
Seed Quality Imaging and Germination Prediction Test Systems Market
Seed Technology
India Seed Treatment Market
Seed Technology
North America Cotton Seed Treatment Market
Seed Technology
North America Seed Coating Materials Market
Seed Technology
Japan Seed Treatment Market