
 India Seed Treatment Market | 2026-2036
India Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
India Seed Treatment Market Outlook
The India seed treatment landscape is shifting between premium biological formulations and commodity chemical coatings as farmer willingness to pay diverges by crop value. Bayer AG leverages its global germplasm-treatment integration to sustain premium positioning in hybrid cotton and maize segments. UPL Limited anchors its competitive stance through deep distribution networks across tier-two and tier-three agricultural markets. Rallis India Ltd differentiates via technical-grade manufacturing scale and backward integration into active ingredient sourcing.
Seed treatment encompasses the application of protective or growth-enhancing agents to seeds prior to sowing, typically involving film-coating at <0.5 mm thickness to preserve germination viability while delivering targeted pesticide, fertilizer, or microbial payload at the seed-soil interface. The primary commercial purpose is to reduce early-stage crop mortality from soil-borne pathogens and pests, thereby improving stand establishment and reducing replanting costs. Pesticides retain the dominant value share due to entrenched farmer reliance on chemical protection against termites and fungal wilt, though biopesticides represent the fastest-expanding margin pool as organic certification requirements tighten. Seed coating leads application methods by volume because of equipment compatibility with existing farmer drill systems and lower labor intensity relative to pelleting or drenching.
The Central Insecticides Board (CIB) under the Ministry of Agriculture regulates product registration and residue limits, while the Food Safety and Standards Authority of India (FSSAI) monitors treated seed-derived food chain compliance. The Bureau of Indian Standards (BIS) prescribes physical purity and germination benchmarks that treated products must meet for commercial sale. Stakeholders must monitor evolving biopesticide registration pathways and state-level subsidy reallocations between chemical and biological treatments to anticipate demand migration.
Market Dynamics
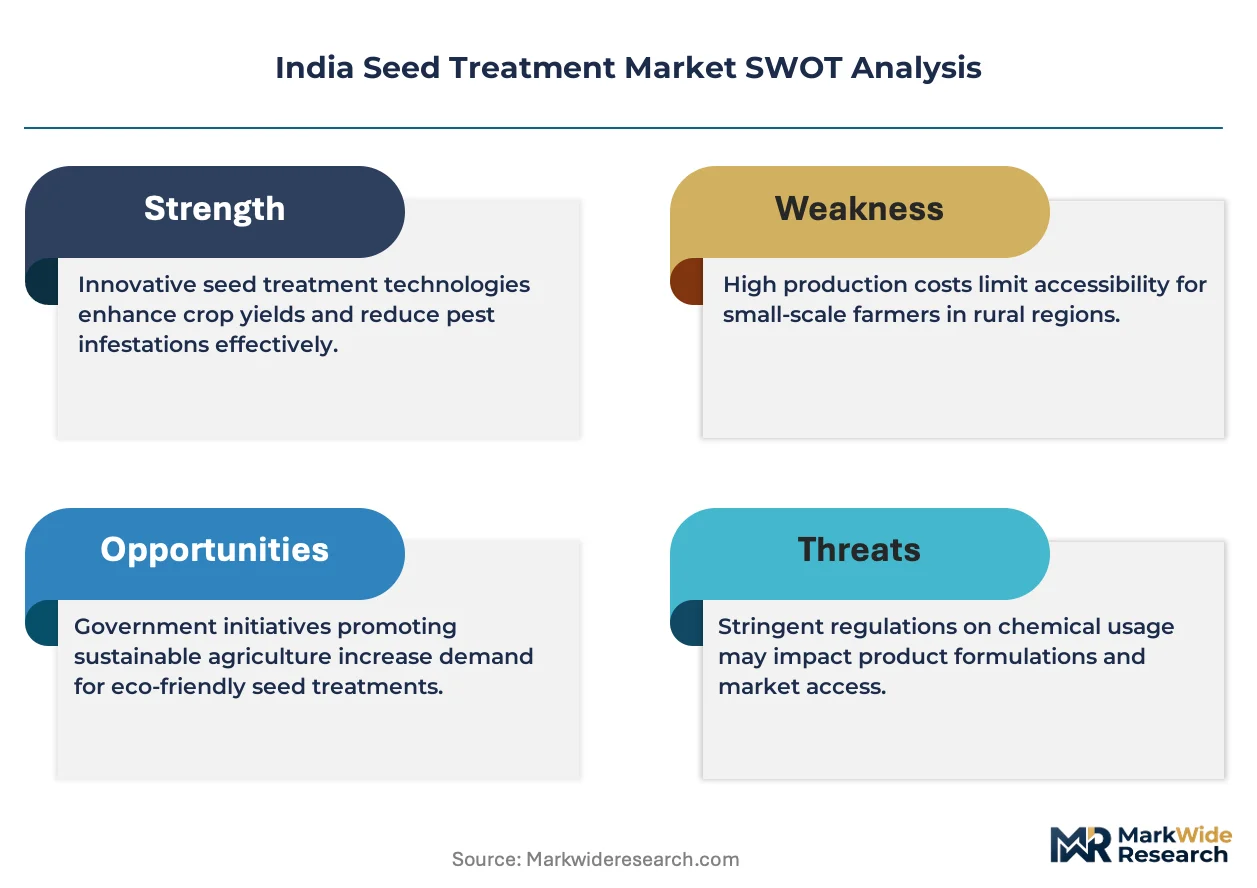
The India seed treatment sector pivots on PLI scheme incentives redirecting capital toward domestic active ingredient manufacturing, compressing import dependency while amplifying price competition between biological and chemical formulation tiers.
Growth Catalysts
- Maharashtra commercial farming intensity:Cotton and soybean growers in this state demonstrate highest willingness to pay for premium treated seed, driving volume concentration and supplier prioritization of distribution infrastructure here.
- FSSAI residue compliance tightening:Food chain safety mandates from this regulator accelerate farmer migration toward biopesticide coatings that carry lower maximum residue limit risk in export-bound commodity crops.
- Film-coating equipment compatibility:Existing drill systems across Gujarat and Punjab handle this application method without capital retrofit, removing adoption friction for smallholder cooperatives.
Market Restraints
- Technical-grade import concentration:Active ingredient sourcing for chemical treatments clusters with Chinese suppliers, exposing formulators to tariff volatility and currency fluctuation risk.
- BIS germination benchmark stringency:Physical purity and viability standards for treated seeds create compliance cost burdens that squeeze margin at the economy formulation tier.
- Biological shelf-life limitation:Microbial viability degradation in tropical storage conditions constrains distribution radius for biopesticide suppliers and elevates cold-chain expenditure.
Strategic Opportunities
- Punjab paddy seed treatment underpenetration:Basmati export zones in this state currently underutilize protective coatings relative to cotton belts, presenting whitespace for residue-compliant biological entrants.
- CIB biopesticide registration pathway streamlining:Regulatory process acceleration for microbial and botanical actives creates first-mover advantage for domestic manufacturers with technical dossier capabilities.
- Drone-based seed coating convergence:Precision application hardware marrying UAV platforms with micro-dosing technology enables treatment-as-a-service models for scattered landholding patterns.
Industry Challenges
- Formulation chemist scarcity:Technical talent capable of optimizing seed-soil interface delivery systems remains concentrated with multinational incumbents, constraining domestic competitor R&D velocity.
- Seed company integration complexity:Treatment application timing coordination with germplasm conditioning and packaging lines demands capital-intensive facility reconfiguration that mid-tier formulators struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Seed Treatment Market |
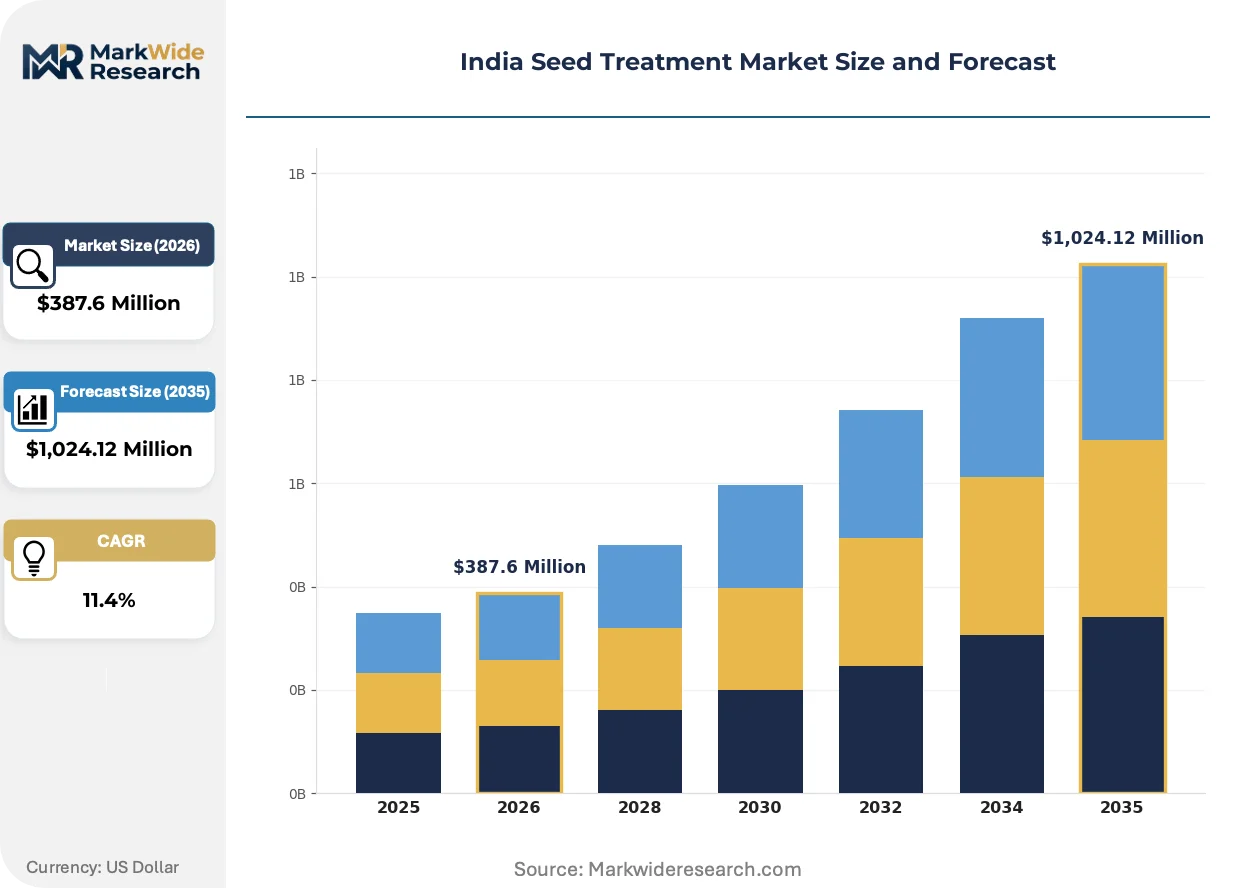
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pesticides, Fertilizers, Biopesticides, Inoculants Application Method: Seed Coating, Seed Drenching, Seed Pelleting, Foliar Spray Crop Type: Cereals, Pulses, Oilseeds, Vegetables Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | ADAMA Agricultural Solutions Ltd, UPL Limited, FMC Corporation, Crystal Crop Protection Ltd, Syngenta Group, Rallis India Ltd, Bayer AG, Corteva Agriscience, PI Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Seed Treatment Market Strategic Shifts
Biological payload engineering and application automation are compressing the cost-performance gap against chemical standards while regulatory pressure on residue accumulation intensifies formulation R&D priorities.
Micro-encapsulation of Trichoderma and Pseudomonas strains is decentralizing biological efficacy by extending field persistence to match chemical durability windows. Gujarat cotton cooperatives adopt these formulations at accelerating pace as export certification requirements tighten. The technology is decentralizing biological market share from niche organic segments into mainstream commercial farming procurement.
FSSAI maximum residue limit enforcement for food grains is tightening compliance windows for chemical treatment suppliers. This regulatory pressure compresses the registration timeline advantage for biopesticide dossiers with faster toxicology clearance pathways. Basmati-exporting clusters in Punjab and Haryana respond by specifying treated seed documentation in procurement contracts.
Farmer purchasing for protective seed inputs compresses toward harvest-season credit-linked bundling with fertilizer and pesticide distributors. The traditional standalone seed treatment transaction fragments as channel intermediaries consolidate input procurement decisions. This concentration is most visible in Maharashtra's cotton belt where dealer networks now specify treatment specifications in annual grower agreements.
India Seed Treatment Market Segmentation
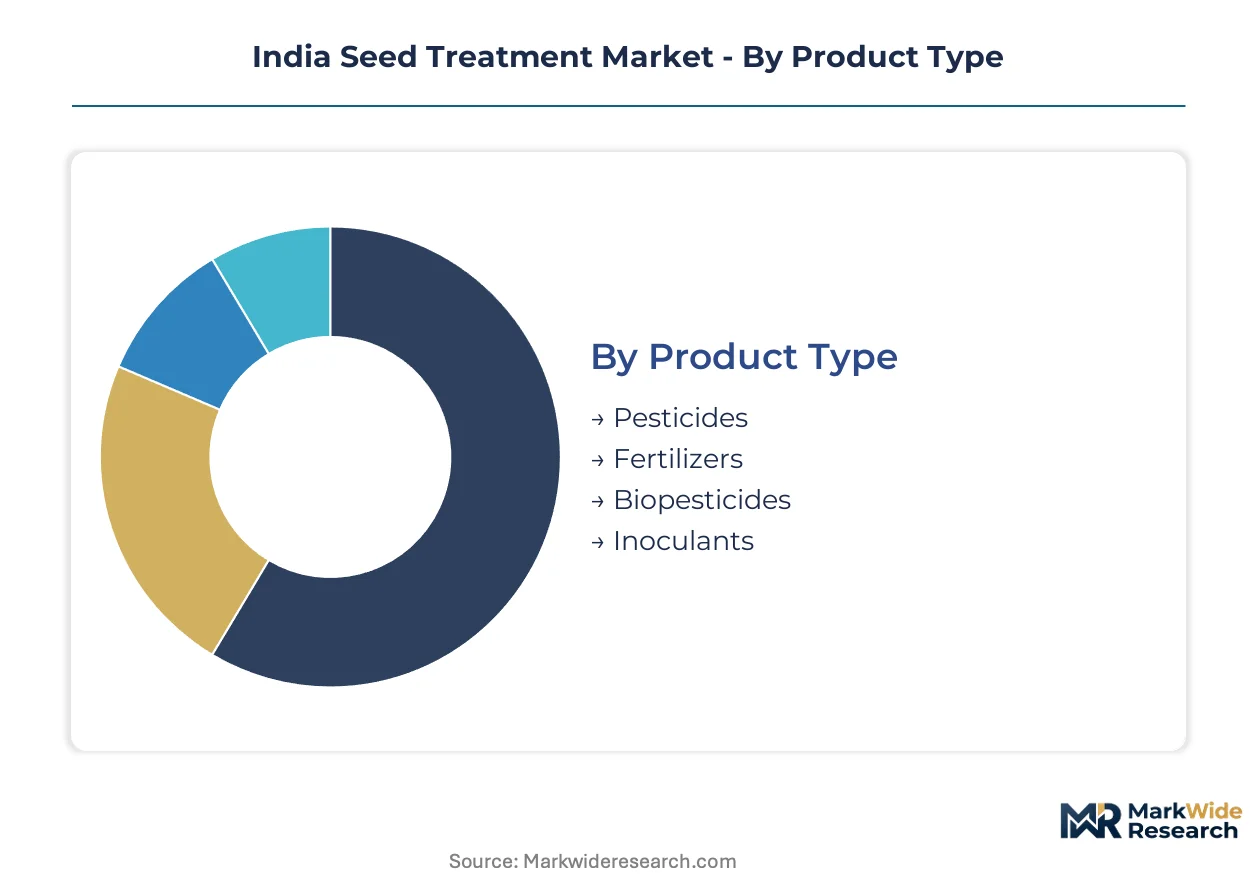
Segmentation in India's seed treatment market reveals how farmer purchasing power, cropping intensity, and regulatory exposure fragment demand across distinct technical and commercial tiers. Treatment specifications diverge sharply between export-oriented commercial farms and subsistence operations, creating parallel supply chains with minimal overlap.
Product Type:
Chemical-biological formulation splits map directly onto farmer risk tolerance and certification requirements across Maharashtra, Gujarat, and Punjab cropping belts.
- Pesticides:Synthetic chemical coatings dominate commercial cotton and soybean cultivation in Maharashtra, where termite and fungal wilt pressure justifies premium outlays. FSSAI residue compliance tightening in Basmati export corridors is compressing addressable market for older organophosphate chemistries.
- Biopesticides:Microbial and botanical formulations gain procurement share fastest. Trichoderma and Pseudomonas encapsulation technologies now match chemical durability windows in Gujarat cotton cooperatives responding to organic certification mandates.
- Fertilizers:Micronutrient seed coatings address zinc and boron deficiency in Punjab paddy soils, though adoption lags behind protective treatments due to less visible yield impact.
- Inoculants:Rhizobium and phosphate-solubilizing bacterial preparations concentrate in pulse-growing regions of Madhya Pradesh and Uttar Pradesh where nitrogen fixation economics favor biological investment.
Leading the category by volume: Pesticides. Growing fastest: Biopesticides.
Application Method:
Equipment capital requirements and labor intensity stratify adoption across cooperative versus individual farmer landholding patterns.
- Seed Coating:Film-coating at sub-millimeter thickness preserves germination viability while delivering targeted payload. Existing drill systems across Gujarat and Punjab handle this method without retrofit, removing adoption friction for smallholder cooperatives.
- Seed Drenching:Liquid suspension application demands higher water access and drying infrastructure, limiting penetration to commercial farming enterprises with dedicated treatment facilities.
- Seed Pelleting:Encapsulation in inert materials improves handling and planting precision for small-seeded vegetable crops in Karnataka and Telangana greenhouse clusters.
- Foliar Spray:Post-emergence application circumvents seed treatment entirely, serving farmers who source untreated saved seed or prioritize flexibility over stand establishment assurance.
Dominant by installed equipment base: Seed Coating. Steepest expansion trajectory: Seed Pelleting in vegetable seed exports.
Crop Type:
Commercial value per hectare and export market access determine farmer willingness to pay for protective seed investment.
- Cereals:Wheat and rice treatment penetration concentrates in Punjab and Haryana where procurement price supports justify input expenditure, though paddy seed treatment remains underpenetrated relative to cotton belts.
- Pulses:Chickpea and pigeon pea growers in Madhya Pradesh and Maharashtra adopt inoculant treatments where residual moisture stress elevates biological nitrogen fixation returns.
- Oilseeds:Soybean and mustard seed treatment commands premium pricing in Madhya Pradesh and Rajasthan due to high early-stage mortality risk from soil-borne pathogens.
- Vegetables:Tomato, chili, and okra seed treatment in Karnataka and Telangana greenhouse operations specifies residue-compliant biological coatings for European export certification.
Highest value concentration: Oilseeds. Fastest biological transition: Vegetables.
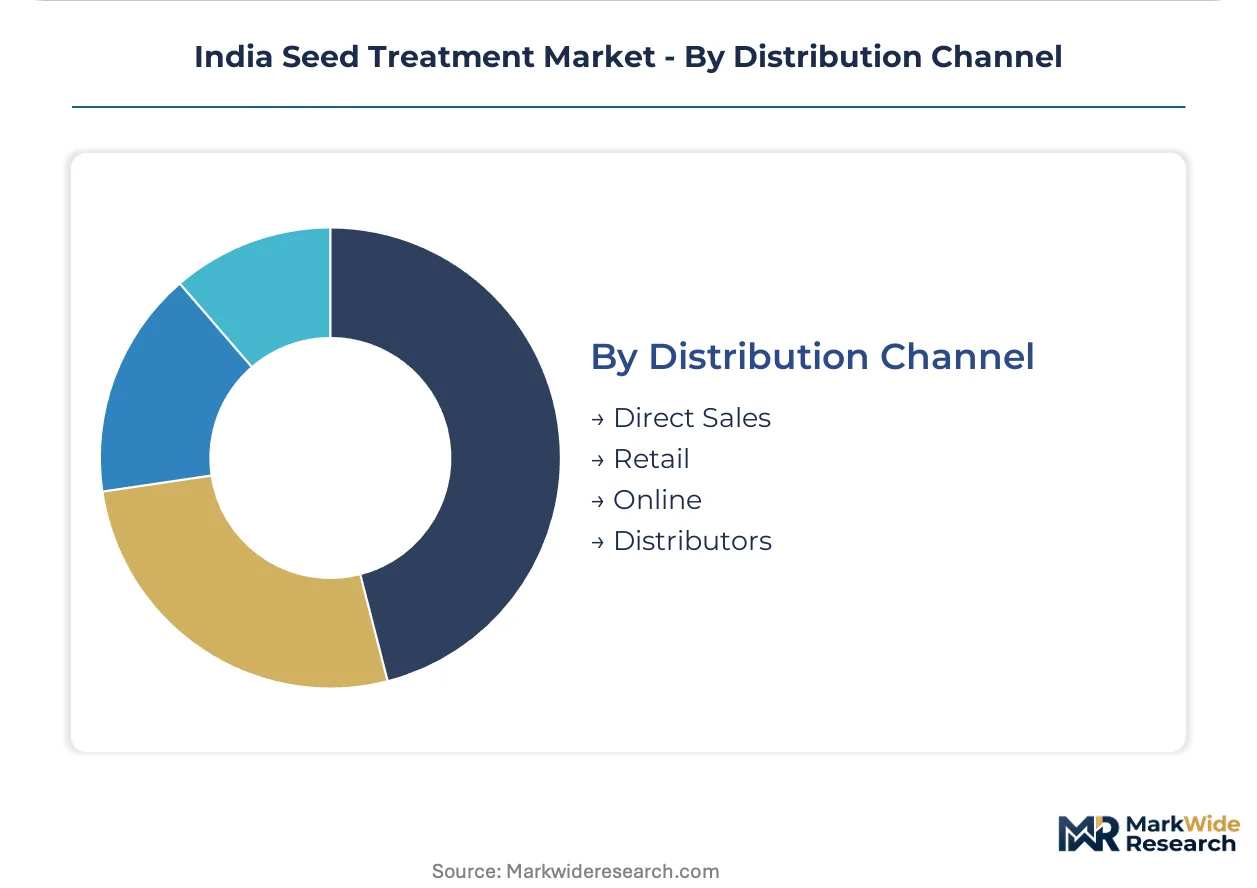
Distribution Channel:
Channel control determines specification authority and margin capture between formulators and intermediaries.
- Direct Sales:Seed company integration of treatment into germplasm conditioning lines captures margin and quality control, requiring capital-intensive facility reconfiguration that favors large integrated players.
- Retail:Mom-and-pop agri-input shops in tier-three towns remain dominant transaction point for smallholders, though treatment specification authority increasingly concentrates with dealer networks.
- Online:E-commerce platforms penetrate slowly due to farmer preference for physical seed inspection and credit-linked purchasing, with traction limited to urban periphery greenhouse operators.
- Distributors:Regional warehousing networks bridge formulator production scale to retail fragmentation, with biological shelf-life limitations constraining viable distribution radius for microbial products.
Controlling procurement volume: Distributors. Gaining specification authority fastest: Direct Sales through seed company bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nagpur anchors Maharashtra's seed treatment procurement intensity, where cotton and soybean commercial farming generates premium formulation demand unmatched elsewhere in the country.
Maharashtra
Cotton and soybean growers in the Vidarbha and Marathwada belts demonstrate the highest willingness to pay for protective seed coatings. The state's PLI scheme for agrochemicals redirects investment toward domestic manufacturing facilities near Nagpur and Aurangabad. Seed company distribution infrastructure concentrates in these corridors to serve cooperative procurement networks.
Gujarat
Cotton cooperatives in the Saurashtra region adopt micro-encapsulated biological formulations at accelerating pace. FSSAI residue compliance tightening for export-bound commodities drives specification migration toward biopesticide coatings. Film-coating equipment compatibility with existing drill systems removes adoption friction for smallholder associations in Anand and Rajkot districts.
Punjab
Basmati export zones in the Amritsar-Gurdaspur belt currently underutilize protective seed coatings relative to cotton-growing states. The state's procurement price supports for wheat justify input expenditure, though paddy seed treatment penetration remains below potential. Dealer networks now specify residue-compliant biological treatments in annual grower agreements.
Karnataka
Vegetable greenhouse operations around Bengaluru and Hoskote specify biological coatings for European export certification compliance. Tomato, chili, and okra seed treatment commands premium pricing in these clusters. Seed pelleting adoption concentrates here for small-seeded vegetable crops requiring precision planting.
Madhya Pradesh
Soybean and mustard cultivation in the Malwa region faces elevated early-stage mortality from soil-borne pathogens. Pulse growers in the Nimar and Bundelkhand belts adopt Rhizobium inoculant treatments where nitrogen fixation economics favor biological investment. State-level subsidy reallocations between chemical and biological treatments shape demand migration patterns.
India Seed Treatment Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation sophistication and germplasm integration depth. Multinational incumbents with captive R&D infrastructure occupy the premium tier, while domestic formulators compete on distribution reach and technical-grade sourcing scale. Three archetypes define the competitive set: integrated seed-chemistry conglomerates, standalone agrochemical formulators, and regional distribution specialists. Capacity expansion in domestic active ingredient manufacturing and strategic partnerships for biological payload engineering represent the dominant competitive moves.
Among the integrated tier, Bayer AG and Syngenta Group exemplify germplasm-treatment bundling strategies that capture margin through proprietary hybrid platforms. UPL Limited and Rallis India Ltd occupy positions bridging technical-grade manufacturing scale with deep distribution networks across tier-two and tier-three agricultural markets. ADAMA Agricultural Solutions Ltd and Crystal Crop Protection Ltd represent the formulator archetype competing on application-specific portfolio breadth.
| Leading Market Players |
|---|
| ADAMA Agricultural Solutions Ltd |
| UPL Limited |
| FMC Corporation |
| Crystal Crop Protection Ltd |
| Syngenta Group |
| Rallis India Ltd |
| Bayer AG |
| Corteva Agriscience |
| PI Industries |
| Others |
Value Chain & Pricing Dynamics
Captive germplasm-treatment integration by multinational seed-chemistry conglomerates anchors both supply security and premium pricing power across Maharashtra and Gujarat cotton belts. This vertical control over active ingredient sourcing and hybrid platform bundling compresses margin capture for standalone formulators competing on technical-grade scale alone.
Pricing Analysis
Yield-outcome anchoring dominates farmer willingness to pay, with stand establishment assurance commanding premium outlays in commercial cotton and soybean cultivation. Pricing stratifies across residue-compliant biological tiers, standard chemical coatings, and economy organophosphate formulations based on FSSAI certification grade and export market access. Cost compression in economy chemical tiers is intensifying because Chinese technical-grade import dependency exposes formulators to currency fluctuation. Smallholder cooperatives in tier-three markets exhibit highest price sensitivity, while export-oriented commercial farms in Basmati corridors demonstrate lowest sensitivity due to certification compliance requirements.
Supply Chain Analysis
Active ingredient supply rests on Chinese specialty chemical producers for synthetic pesticide coatings, Indian domestic manufacturers for PLI-scheme incentivized technical-grade production, and European biotech specialists for microbial strain encapsulation technologies. Key input dependencies include neonicotinoid technicals, Trichoderma fermentation cultures, and film-coating polymer substrates. Tariff exposure on Chinese sourcing creates margin volatility for commodity chemical formulators lacking backward integration into active ingredient production. Distribution runs through regional warehousing networks bridging formulator production scale to fragmented retail channels across tier-two and tier-three agricultural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological payload engineering is displacing legacy chemical coating standards as FSSAI residue enforcement tightens compliance windows across export-oriented cropping belts. Micro-encapsulation technologies now match chemical durability while satisfying organic certification mandates.
For Market Incumbents: Hedge germplasm-treatment bundling advantages by accelerating CIB biopesticide registration dossiers before regulatory pathway streamlining erodes first-mover timing. Defend channel control through seed company integration investments that coordinate treatment application timing with germplasm conditioning lines, countering standalone formulator encroachment on direct sales specifications. For New Entrants and Emerging Players: E-commerce platform penetration offers route to bypass dealer network consolidation and reach urban periphery greenhouse operators in Karnataka and Telangana with residue-compliant biological coatings. Punjab paddy seed treatment underpenetration presents most penetrable whitespace, with Basmati export zones specifying treated seed documentation in procurement contracts. Pursue drone-based seed coating convergence as treatment-as-a-service model for scattered landholding patterns lacking capital-intensive facility investment. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated seed-chemistry conglomerates seeking biological payload engineering capabilities and CIB registration expertise. Long-term viability favors domestic manufacturers with technical dossier capabilities and PLI-scheme aligned active ingredient production scale. Watch state-level subsidy reallocations between chemical and biological treatments as inflection indicator for demand migration velocity across Maharashtra and Gujarat cooperative procurement networks.| Strategic Initiative | Industry Significance |
|---|---|
| CIB Biopesticide Registration Acceleration | First-mover advantage for microbial dossier capabilities ahead of pathway streamlining. |
| Backward Integration into Active Ingredients | PLI scheme alignment reduces import dependency and compresses economy-tier pricing exposure. |
| Drone-Based Application Partnership | UAV-microdosing convergence enables service models for fragmented landholding patterns. |
| Seed Company Facility Integration | Captures margin and specification authority through germplasm-treatment bundling control. |
| Microbial Encapsulation R&D Scale-Up | Extends biological field persistence to match chemical durability in tropical storage conditions. |
Study Parameters
Regulatory filings with CIB and FSSAI, customs trade data on technical-grade imports, and BIS seed quality standards formed the secondary backbone for market sizing validation. Primary interviews with seed company R&D directors, agrochemical formulator procurement leads, cooperative procurement managers, and dealer network operators combined with secondary triangulation to ground-truth volume estimates across Maharashtra, Gujarat, and Punjab cropping belts.
Bottom-up crop hectare estimates and treatment penetration rates were cross-validated against top-down agrochemical industry revenue allocations across the projection horizon. Segmentation modeling incorporated product type, application method, crop category, and distribution channel dimensions with PLI scheme incentive flow assumptions and state-level subsidy reallocation patterns. CAGRs were derived from regression analysis of historical adoption curves and regulatory inflection timing.
The model holds under sustained FSSAI residue enforcement and PLI scheme continuity; deviation in biopesticide registration delays or Chinese tariff escalation would shift biological transition velocity and chemical pricing dynamics. Forecasts reflect documented assumptions on farmer credit access and cooperative procurement consolidation. A small set of named triggers—CIB pathway streamlining pace, state subsidy reallocation timing, and microbial shelf-life technology breakthroughs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
North America Seed Coating Materials Market
Seed Technology
Mexico Seed Treatment Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
Seed Treatment Market
Seed Technology
Seed Quality Imaging and Germination Prediction Test Systems Market
Seed Technology
Seed Coating Materials Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
Japan Seed Treatment Market
Seed Technology
Europe Seed Coating Materials Market
Seed Technology
France Seed Treatment Market
Seed Technology
Protein Content Optimizing Cereal Fertility Program Market
Seed Technology
China Seed Treatment Market
Seed Technology
Seed Coating Ingredients Market
Seed Technology
North America Cotton Seed Treatment Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
Chitosan-based Seed Coatings Market