
 Seed Quality Imaging and Germination Prediction Test Systems Market | 2026-2036
Seed Quality Imaging and Germination Prediction Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Quality Imaging and Germination Prediction Test Systems Market Insights
Equipment leasing and pay-per-test service models are narrowing the capital barrier for mid-sized seed producers seeking automated imaging systems. Eurofins Scientific leverages its distributed laboratory network to offer regional seed testing with standardized imaging protocols. SGS anchors its competitive position through backward integration into proprietary germination prediction algorithms. Intertek Group differentiates by combining thermal imaging with multispectral analysis for drought-resistance screening.
Seed quality imaging and germination prediction test systems deploy optical sensors, machine vision cameras, and spectral detectors to capture morphological and biochemical seed characteristics without destructive sampling, typically resolving features at 10-50 micron resolution for viability classification. These systems serve breeding programs and commercial seed operations by replacing manual germination counts with rapid, non-invasive throughput assessment. Machine vision and artificial intelligence segments command premium positioning due to their integration into fully automated sorting lines where real-time decisioning replaces batch laboratory processing. Portable devices and on-field systems represent the fastest-expanding deployment category as breeders seek to reduce logistics costs and preserve seed freshness. Cloud-based platforms are maturing into data aggregation hubs that connect distributed testing networks across multinational seed companies.
The EU Seed Marketing Regulations and OECD Seed Schemes establish varietal purity and germination standards that mandate certified laboratory testing for commercial seed lots. The USDA Federal Seed Act and state-level seed certification programs in the United States require documented germination rates on all labeled seed shipments. China's National Seed Law and GB standards enforced by the Ministry of Agriculture and Rural Affairs are expanding mandatory quality testing for imported germplasm. Stakeholders must weigh capital deployment between centralized laboratory automation and distributed field-deployable systems as regulatory jurisdictions diverge in testing location requirements.
Market Dynamics
Equipment-as-a-service business models are compressing capital deployment timelines for automated seed imaging systems, while regulatory divergence between laboratory certification and field-deployable testing standards forces producers into dual-track compliance investments.
Growth Catalysts
- OECD Seed Schemes:Cross-border varietal certification mandates in Europe are expanding throughput requirements for commercial laboratories serving multinational breeders.
- Hyperspectral imaging:Non-destructive biochemical detection at 10-50 micron resolution is replacing manual germination counts in Dutch research clusters.
- Cloud-based aggregation platforms:Distributed testing networks at multinational seed companies are standardizing data protocols across breeding stations.
Market Restraints
- Optical sensor supply concentration:German and Japanese precision component manufacturers control critical machine vision camera supply chains.
- USDA Federal Seed Act documentation requirements:State-level certification program fragmentation creates interstate testing location friction.
- Manual germination protocols:Destructive sampling methods persist as reference standards for regulatory appeals, slowing full automation adoption.
Strategic Opportunities
- Portable on-field deployment:Battery-powered multispectral units are opening logistics-cost reduction pathways for remote breeding stations in Brazil and Argentina.
- EU AI Act compliance frameworks:Standardized algorithmic transparency requirements are creating first-mover advantages for predictive germination model developers.
- Pay-per-test service models:Regional laboratory networks are capturing mid-sized seed producers previously excluded from automated imaging capital expenditure.
Industry Challenges
- Machine learning engineering talent scarcity:Breeding programs lack in-house expertise to retrain viability classification models for new crop varieties.
- Legacy laboratory information management system integration:Proprietary data formats from 1990s-era seed testing infrastructure block real-time cloud platform connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Quality Imaging and Germination Prediction Test Systems Market |
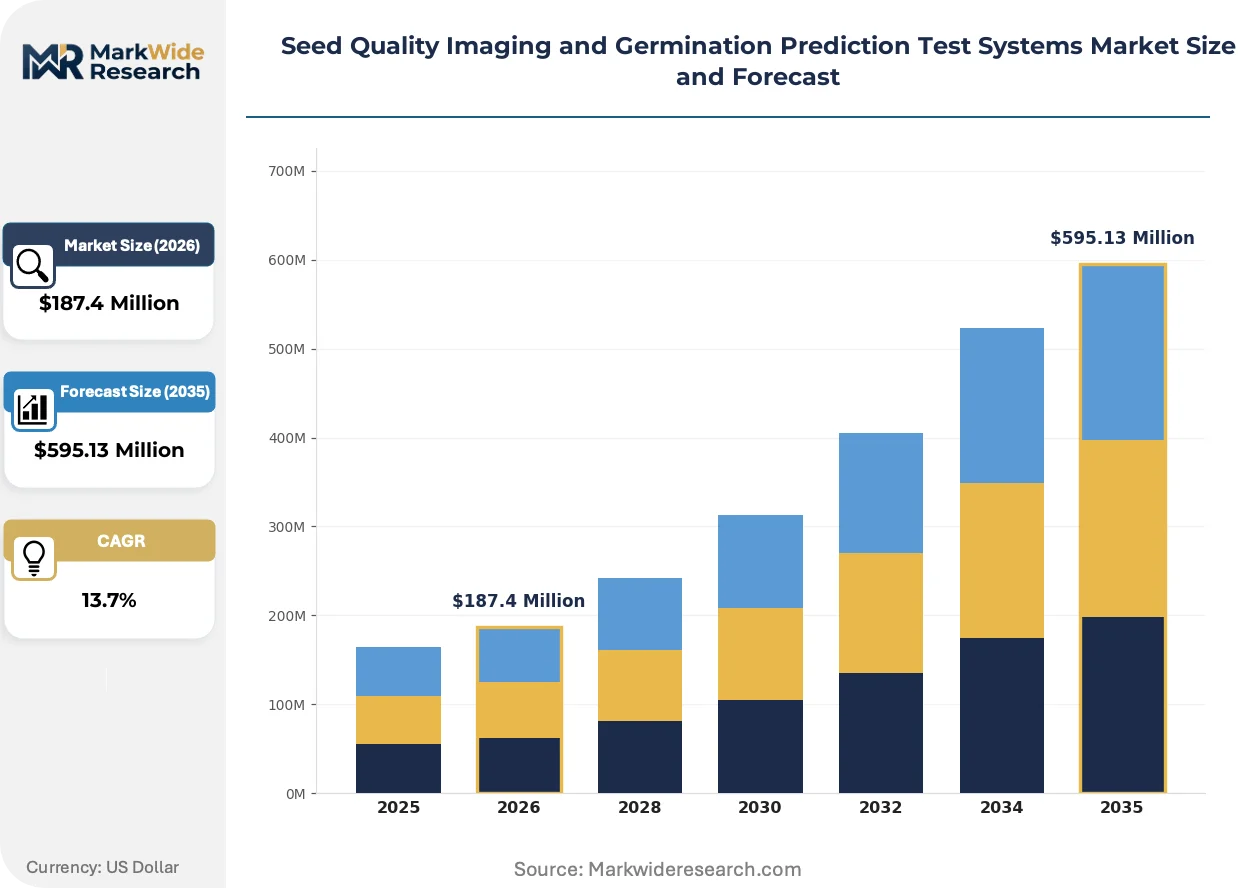
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $595.13 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hyperspectral Imaging, Machine Vision, Artificial Intelligence, Thermal Imaging, Multispectral Imaging Application: Seed Viability Assessment, Germination Rate Prediction, Defect Detection, Quality Control, Seed Sorting End User Type: Seed Producers, Agricultural Research Institutes, Plant Breeders, Seed Testing Laboratories, Contract Testing Services Deployment Mode: Laboratory Systems, Portable Devices, On-Field Systems, Cloud-Based Platforms, Automated Sorting Lines |
| Companies Covered | Eurofins Scientific, SGS, Intertek Group, ALS Limited, Bureau Veritas, R J Hill Laboratories, 20/20 Seed Labs, AMM Seed Testing, PGRO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Quality Imaging and Germination Prediction Test Systems Market Trends and Innovations
Artificial intelligence is compressing the seed-to-data pipeline from weeks to hours, while hardware miniaturization and edge computing are relocating analytical capacity from central laboratories to breeding field stations.
Deep learning architectures trained on morphological seed feature libraries are rendering obsolete the batch-processing laboratory model where samples accumulated for weekly germination counts. Large-scale vegetable and field crop breeders in the Netherlands and United States are deploying these systems directly onto automated sorting lines for real-time viability-based binning. The structural compression of decision latency is eliminating inventory holding costs and reducing seed freshness degradation during logistics chains.
REACH chemical substance restrictions and EU F-Gas Regulation phase-down schedules are forcing imaging equipment manufacturers to reformulate thermal camera cooling systems and optical coating chemistries. Industrial consequence includes extended product recertification timelines and supply chain requalification costs concentrated among European-domiciled equipment suppliers. German and Swiss precision optics producers are accelerating solid-state thermoelectric cooling adoption to maintain thermal imaging performance without regulated refrigerants.
Seed producers are unbundling after-sales service contracts from equipment purchases, preferring subscription-based algorithm update and calibration maintenance agreements. Traditional capital-sale distributors in North America are repositioning as recurring-revenue service platforms, displacing one-time commission structures. This behavioral shift is most visible among mid-sized commercial seed operations in the US Corn Belt seeking to convert fixed imaging asset costs into variable per-test expenses aligned with seasonal volume fluctuations.
Seed Quality Imaging and Germination Prediction Test Systems Market Segmentation
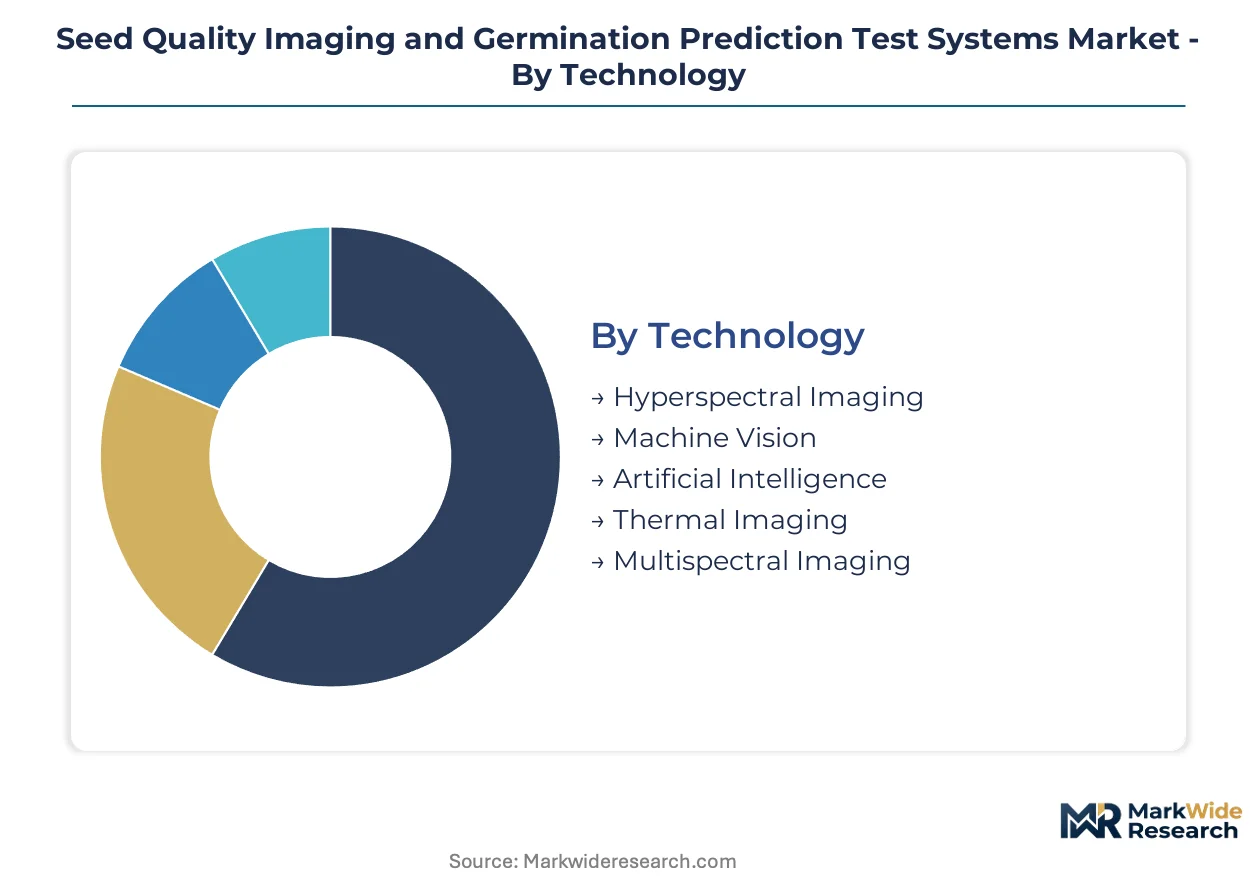
Segmentation in seed quality imaging systems reveals distinct capital cycles and decision timelines across technology tiers. Breeding programs prioritize deployment modes with shortest validation periods, while regulatory compliance drives slower replacement schedules in laboratory infrastructure.
Technology:
Cycle times vary dramatically: AI and machine vision refresh every 18-24 months with algorithm updates, while thermal and multispectral hardware platforms persist 7-10 years before replacement.
- Hyperspectral Imaging:Captures contiguous spectral bands across 400-2500nm wavelengths to detect biochemical markers of seed viability without chemical staining. Dutch vegetable breeding clusters in Wageningen deploy these systems for real-time oil and protein content mapping, constrained by data throughput bottlenecks in high-volume grain operations.
- Machine Vision:Employs CCD and CMOS cameras with structured lighting to resolve morphological features at 10-50 micron resolution for automated defect classification. US Corn Belt seed producers integrate these into conveyor-based sorting lines where sub-second decision latency eliminates batch accumulation delays.
- Artificial Intelligence:Deep learning architectures trained on morphological feature libraries enable predictive germination scoring without destructive sampling. Cloud-based model retraining cycles compress validation timelines for new crop varieties.
- Thermal Imaging:Detects seed coat integrity and moisture gradients through infrared emission signatures. Solid-state thermoelectric cooling adoption accelerates as REACH and EU F-Gas regulations phase out legacy refrigerants.
- Multispectral Imaging:Captures discrete spectral bands at lower cost than hyperspectral systems, trading chemical specificity for throughput speed. Battery-powered portable units are penetrating remote breeding stations in Brazil and Argentina.
Machine Vision dominates installed base through decade-long sorting line integrations. Artificial Intelligence is where expansion concentrates as breeders seek to compress seed-to-data pipelines from weeks to hours.
Application:
Cost tier stratification separates premium viability prediction from commodity quality control, with defect detection occupying a mid-market position shaped by automation penetration.
- Seed Viability Assessment:Non-destructive prediction of germination potential through optical and spectral signatures. OECD Seed Scheme certification requirements in the Netherlands and Germany mandate documented viability rates for cross-border varietal trade.
- Germination Rate Prediction:Machine learning models extrapolate germination percentages from morphological and biochemical seed characteristics. Cloud-based platforms at multinational seed companies standardize prediction protocols across distributed breeding stations.
- Defect Detection:Automated identification of physical damage, disease lesions, and developmental abnormalities via high-resolution imaging. Integration into automated sorting lines enables real-time binning decisions without manual inspection.
- Quality Control:Batch-level verification of seed lot uniformity and purity against certification standards. USDA Federal Seed Act documentation requirements drive recurring testing volume in US interstate seed commerce.
- Seed Sorting:Real-time mechanical separation based on viability classification outputs from upstream imaging modules. Fully automated lines in large-scale vegetable breeding operations eliminate inventory holding costs during seasonal processing peaks.
Quality Control commands the broadest installed base through regulatory mandate coverage. Germination Rate Prediction is climbing the fastest as AI-enabled throughput replaces manual count protocols.
End User Type:
Customer type determines procurement modality: capital purchase dominates seed producers and plant breeders, while service contracts prevail among contract testing services and smaller research institutes.
- Seed Producers:Commercial operations requiring high-throughput automated systems for seasonal processing volumes. US Corn Belt and Netherlands-based vegetable seed multinationals deploy fully integrated sorting lines with real-time viability-based binning.
- Agricultural Research Institutes:Public and semi-public institutions conducting foundational germplasm characterization. EU Horizon-funded projects at Wageningen University drive hyperspectral imaging adoption for biochemical trait mapping.
- Plant Breeders:Private breeding programs prioritizing rapid generation turnover and seed freshness preservation. Portable on-field systems reduce logistics costs for remote station networks in South America.
- Seed Testing Laboratories:Certified facilities performing regulatory compliance testing under OECD Seed Schemes and national seed laws. Eurofins Scientific and SGS operate distributed networks with standardized imaging protocols.
- Contract Testing Services:Third-party providers offering pay-per-test models to mid-sized producers excluded from capital expenditure. Equipment-as-a-service business models compress adoption timelines for automated imaging systems.
Seed Testing Laboratories dominate installed base through regulatory certification concentration. Contract Testing Services represent the steepest expansion trajectory as leasing models narrow capital barriers.
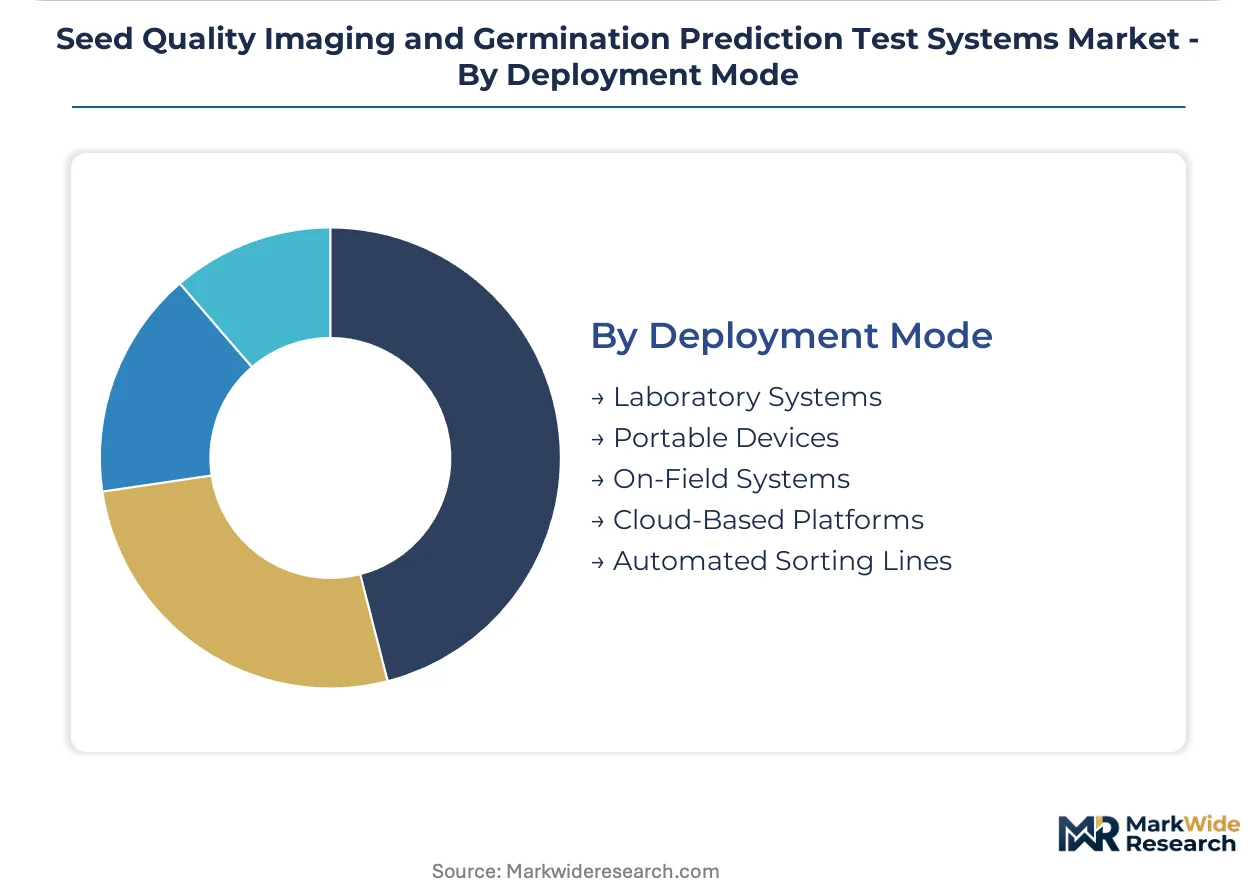
Deployment Mode:
Supply concentration in German and Japanese precision optics manufacturers shapes geographic availability, with cloud-based platforms decoupling analytical capacity from hardware location.
- Laboratory Systems:Centralized high-throughput installations with environmental control and reference-standard calibration protocols. OECD Seed Scheme certification requirements perpetuate laboratory deployment for official varietal purity documentation.
- Portable Devices:Battery-powered multispectral and thermal imaging units for field-deployable testing. Brazilian and Argentine breeding stations adopt these to preserve seed freshness and reduce logistics costs from remote locations.
- On-Field Systems:Weather-hardened installations at breeding station perimeters for immediate post-harvest assessment. Edge computing architectures relocate analytical capacity from central laboratories to distributed field locations.
- Cloud-Based Platforms:Data aggregation hubs connecting distributed testing networks with standardized protocols and centralized model retraining. Multinational seed companies deploy these to harmonize viability classification across breeding stations.
- Automated Sorting Lines:Fully integrated conveyor systems with real-time imaging and mechanical separation modules. Netherlands and US vegetable seed producers eliminate inventory holding costs through sub-second decision latency.
Laboratory Systems dominate installed base through regulatory certification persistence. Portable Devices are gaining share fastest as breeders seek to reduce logistics costs and preserve seed freshness in remote locations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented seed certification regimes in the Netherlands and Germany generate sustained demand for automated imaging systems, while import-dependent markets in Brazil and Argentina prioritize portable field-deployable units to reduce perishability losses during transit.
Netherlands
Wageningen University research clusters and multinational vegetable breeding headquarters concentrate precision agriculture investment. The EU Seed Marketing Regulations mandate documented varietal purity for cross-border trade, compelling commercial laboratories to expand throughput capacity. Dutch seed exporters deploy fully automated sorting lines with real-time viability-based binning to eliminate inventory holding costs during seasonal processing peaks.
United States
US Corn Belt commercial seed producers integrate machine vision systems into conveyor-based sorting infrastructure for sub-second decision latency. The USDA Federal Seed Act requires documented germination rates on all labeled interstate shipments, perpetuating laboratory certification demand. Greater Des Moines and Greater Lincoln serve as logistics hubs where seed testing laboratories consolidate regional sample processing volumes.
Germany
German precision optics manufacturers control critical machine vision camera supply chains for hyperspectral and thermal imaging platforms. REACH chemical substance restrictions and EU F-Gas Regulation phase-down schedules force equipment recertification timelines and supply chain requalification costs. Bavarian and Baden-Württemberg industrial clusters accelerate solid-state thermoelectric cooling adoption to maintain thermal imaging performance without regulated refrigerants.
Brazil
Brazilian soybean and maize breeding stations adopt battery-powered multispectral portable devices to preserve seed freshness and reduce logistics costs from remote locations. The country's national agricultural regulator enforces expanding quality certification requirements for commercial seed lots. São Paulo State and Mato Grosso research stations represent the primary deployment sites for on-field edge computing architectures.
China
China's Ministry of Agriculture and Rural Affairs expands mandatory quality testing for imported germplasm under National Seed Law and GB standards enforcement. Domestic breeding programs prioritize cloud-based platform adoption to harmonize viability classification protocols across distributed stations. Yangtze River Delta and Shandong Peninsula clusters concentrate public agricultural research institute procurement of hyperspectral imaging systems for foundational germplasm characterization.
Seed Quality Imaging and Germination Prediction Test Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in optical sensor and machine vision camera manufacturing. The vendor base stratifies between multinational testing service networks with distributed laboratory footprints and precision equipment manufacturers with captive algorithm development. Three archetypes dominate: integrated laboratory service platforms, equipment manufacturers with proprietary germination prediction software, and component suppliers with standardized imaging module sales. Competitive intensity concentrates on backward integration into predictive algorithm development and geographic expansion of certified testing facility networks.
Among laboratory service platforms, Eurofins Scientific, SGS, and Intertek Group exemplify the integrated testing network archetype. Eurofins Scientific leverages its distributed laboratory infrastructure to offer regional seed testing with standardized imaging protocols. SGS anchors its competitive position through upstream control over proprietary germination prediction algorithms. Intertek Group occupies a differentiated position by combining thermal imaging with multispectral analysis capabilities. These three entities represent the prevailing competitive configuration where service scale and algorithmic specialization determine procurement decisions among multinational seed producers.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS |
| Intertek Group |
| ALS Limited |
| Bureau Veritas |
| R J Hill Laboratories |
| 20/20 Seed Labs |
| AMM Seed Testing |
| PGRO |
| Others |
Pricing and Supply Chain Analysis
German precision optics clusters in Bavaria and Baden-Württemberg control machine vision camera supply chains, concentrating upstream pricing power among a handful of component manufacturers serving downstream seed imaging system integrators. This geographic supply concentration enables premium pricing for hyperspectral and thermal imaging modules while forcing equipment vendors into extended payment term negotiations to secure volume allocations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Price differentiation hinges on certification grade under OECD Seed Schemes and after-sales service bundling, with fully validated laboratory systems commanding substantial premiums over portable field units. Cost compression in the mid-tier equipment segment is intensifying because mid-sized seed producers are migrating toward equipment-as-a-service contracts that convert fixed capital outlays into variable per-test expenses. Contract testing services exhibit the highest price sensitivity due to thin margins on high-volume regulatory compliance work, while multinational breeding operations show relative price inelasticity for real-time automated sorting lines.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard procurement instruments as German and Japanese precision component manufacturers tighten credit conditions for imaging equipment assemblers. Geographic supply concentration centers on Germany, Japan, and Switzerland for optical sensors, machine vision cameras, and solid-state thermoelectric cooling systems. Raw material dependencies include rare-earth elements for thermal camera lenses, high-purity silicon for CMOS sensors, and specialized optical coatings subject to REACH chemical substance restrictions. Single-source vulnerability runs through Japanese CMOS sensor foundries. Distribution runs through certified laboratory networks and OEM direct sales channels serving breeding operations and seed producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cloud-based algorithm platforms that displace hardware-dependent viability assessment, requiring defensive positioning around data network effects and regulatory certification moats.
For Market Incumbents: Entrench algorithmic differentiation through backward integration into proprietary germination prediction models that lock in switching costs among multinational breeding operations. Pursue certification investment under expanding EU AI Act transparency requirements to create compliance barriers against emerging software-only entrants. Capacity addition in Brazilian and Argentine field-deployable system manufacturing would counter logistics-cost advantages of portable equipment specialists. For New Entrants and Emerging Players: Remote breeding stations in Brazil's Mato Grosso and Argentina's Pampas region represent the most penetrable white-space target, where battery-powered multispectral units address unmet freshness-preservation needs. Portable on-field deployment for soybean and maize germplasm assessment offers the fastest path to revenue traction. A pay-per-test service model targeting mid-sized South American seed producers excluded from capital expenditure would circumvent incumbent laboratory network dominance. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors equipment manufacturers with captive algorithm development and established OECD Seed Scheme certification pathways. Long-term viability over the next decade rests on convergence between edge computing architectures and cloud-based model retraining platforms. Acquisition targets should demonstrate distributed testing network scale or proprietary spectral signature libraries. The signal to watch is regulatory divergence between laboratory certification mandates and field-deployable testing standards, which would favor agile portable system developers over centralized laboratory incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Algorithms | SGS and Eurofins Scientific are anchoring competitive differentiation through captive germination prediction model development. |
| Portable On-Field System Launch | Battery-powered multispectral units from Dutch and German manufacturers are penetrating Brazilian remote breeding stations. |
| EU AI Act Compliance Investment | Standardized algorithmic transparency requirements are creating first-mover certification barriers for predictive model developers. |
| Cloud-Based Platform Integration | Multinational seed companies are deploying data aggregation hubs to harmonize viability protocols across distributed breeding networks. |
| Geographic Expansion into South America | Equipment-as-a-service models are compressing adoption timelines among mid-sized Argentine and Brazilian seed producers. |
Research Methodology
Initial hypotheses were tested against primary input from seed testing laboratory directors, plant breeding program managers, agricultural research institute procurement officers, and precision optics manufacturing executives, and refined through secondary validation. Primary interviews explored equipment procurement timelines, regulatory compliance workflows, and algorithm retraining protocols across breeding operations. Secondary sources included USDA Federal Seed Act documentation requirements, EU Seed Marketing Regulations, OECD Seed Scheme certification standards, and customs data on optical sensor trade flows. Bottom-up triangulation across installed base estimates and top-down validation against seed industry capital expenditure patterns ensured analytical robustness.
Demand-supply balance modeling across the projection horizon incorporated technology segmentation by deployment mode, application tier from quality control to germination prediction, and end-user type from multinational seed producers to contract testing services. CAGRs were derived from regression analysis of historical equipment shipment data against seed industry revenue growth and regulatory mandate expansion timelines. Industry-specific forecast inputs included breeder adoption curves for AI-enabled viability assessment and REACH chemical restriction impacts on thermal imaging equipment recertification schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native algorithm platforms or Chinese optical component manufacturers would shift outcomes. Macroeconomic contraction in agricultural commodity prices, regulatory acceleration of field-deployable testing standards, or breakthroughs in non-optical viability detection would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
North America Seed Coating Materials Market
Seed Technology
Asia-Pacific Seed Coating Materials Market
Seed Technology
Japan Seed Treatment Market
Seed Technology
Mexico Seed Treatment Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
Seed Additives Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
China Seed Treatment Market
Seed Technology
France Seed Treatment Market
Seed Technology
Seed Coating Ingredients Market
Seed Technology
Canada Seed Treatment Market
Seed Technology
Seed Treatment Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
Seed Storage Systems Market
Seed Technology
India Seed Treatment Market