
 Protein Content Optimizing Cereal Fertility Program Market | 2026-2036
Protein Content Optimizing Cereal Fertility Program Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Content Optimizing Cereal Fertility Program Market Insights
North American specialty fertilizer producers is repositioning around variable-rate application technologies for high-protein wheat contracts. Yara International leverages its controlled-release nitrogen portfolio to capture premium protein-linked pricing in the US Northern Plains. Nutrien anchors its agronomic services through soil testing networks that tie fertility prescriptions to end-use protein premiums. BASF competes via biological inoculant integrations that reduce synthetic nitrogen rates without yield penalty.
Protein Content Optimizing Cereal Fertility Programs combine soil amendment, foliar feeding, and biological inoculant protocols calibrated to cereal grain protein accumulation curves, typically targeting 12-14% protein content in hard red wheat through split nitrogen applications timed at stem elongation and grain fill. Nutrient Management programs dominate current deployment due to their direct linkage to elevator protein premiums, while Biological Inoculants represent the fastest-expanding category as growers seek to reduce synthetic nitrogen rates under emerging carbon accounting protocols. Seed Treatment applications command margin concentration because they lock in program loyalty prior to planting decisions.
The EPA regulates fertilizer runoff under the Clean Water Act, while the EU Green Deal's Farm to Fork strategy mandates 20% fertilizer reduction targets that reshape product registration priorities. USDA's Climate-Smart Commodities program creates payment pathways for protein-optimized fertility that documents nitrogen-use efficiency. Stakeholders must monitor how protein premium structures at grain elevators evolve relative to carbon intensity scoring requirements from food manufacturers.
Market Dynamics
The EU Green Deal's fertilizer reduction mandates are compressing synthetic nitrogen rates while protein premiums at grain elevators intensify, forcing fertility programs to document nitrogen-use efficiency through split-application protocols calibrated to cereal protein accumulation curves.
Growth Catalysts
- Protein Premium Structures:Milling buyers in Germany's cereal belt now tie contract pricing to 12-14% protein thresholds, creating direct financial linkage between fertility investment and farm revenue.
- USDA Climate-Smart Commodities:Payment pathways for documented nitrogen-use efficiency incentivize growers to adopt precision nutrient management that tracks carbon intensity alongside protein optimization.
- Variable-Rate Application Hardware:Planter-mounted sensors and prescription algorithms enable stem elongation and grain-fill nitrogen timing with sub-field resolution, reducing waste while hitting protein targets.
Market Restraints
- Phosphate and Potash Price Volatility:Concentrated supply from Moroccan and Russian producers creates input cost instability that erodes program margin predictability for fertility service providers.
- Biological Inoculant Efficacy Variance:Field performance inconsistency across soil microbiome conditions limits grower confidence in nitrogen-fixing alternatives to synthetic applications.
- EU Fertilizer Registration Friction:ECHA's evolving criteria for novel biostimulant classifications delay product commercialization timelines by 18-36 months compared to conventional chemistries.
Strategic Opportunities
- Carbon Accounting Protocol Integration:Emerging verification frameworks for Scope 3 agricultural emissions create premium pricing tiers for protein-optimized grain with documented low-carbon fertility footprints.
- Seed Treatment Channel Lock-In:Pre-plant biological and nutrient coating applications establish program loyalty before growers commit to seasonal fertility decisions, capturing lifetime value.
- Remote Sensing Convergence:Satellite-derived nitrogen stress indices combined with in-field tissue testing enable real-time prescription adjustments during the narrow grain-fill protein accumulation window.
Industry Challenges
- Agronomic Data Integration Complexity:Synthesizing soil test results, weather forecasts, protein models, and carbon accounting requirements demands specialized systems integration expertise scarce among retail agronomists.
- Split-Application Logistics Coordination:Timely stem elongation and grain-fill passes require equipment availability and labor scheduling precision that conflicts with compressed planting and harvest windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Content Optimizing Cereal Fertility Program Market |
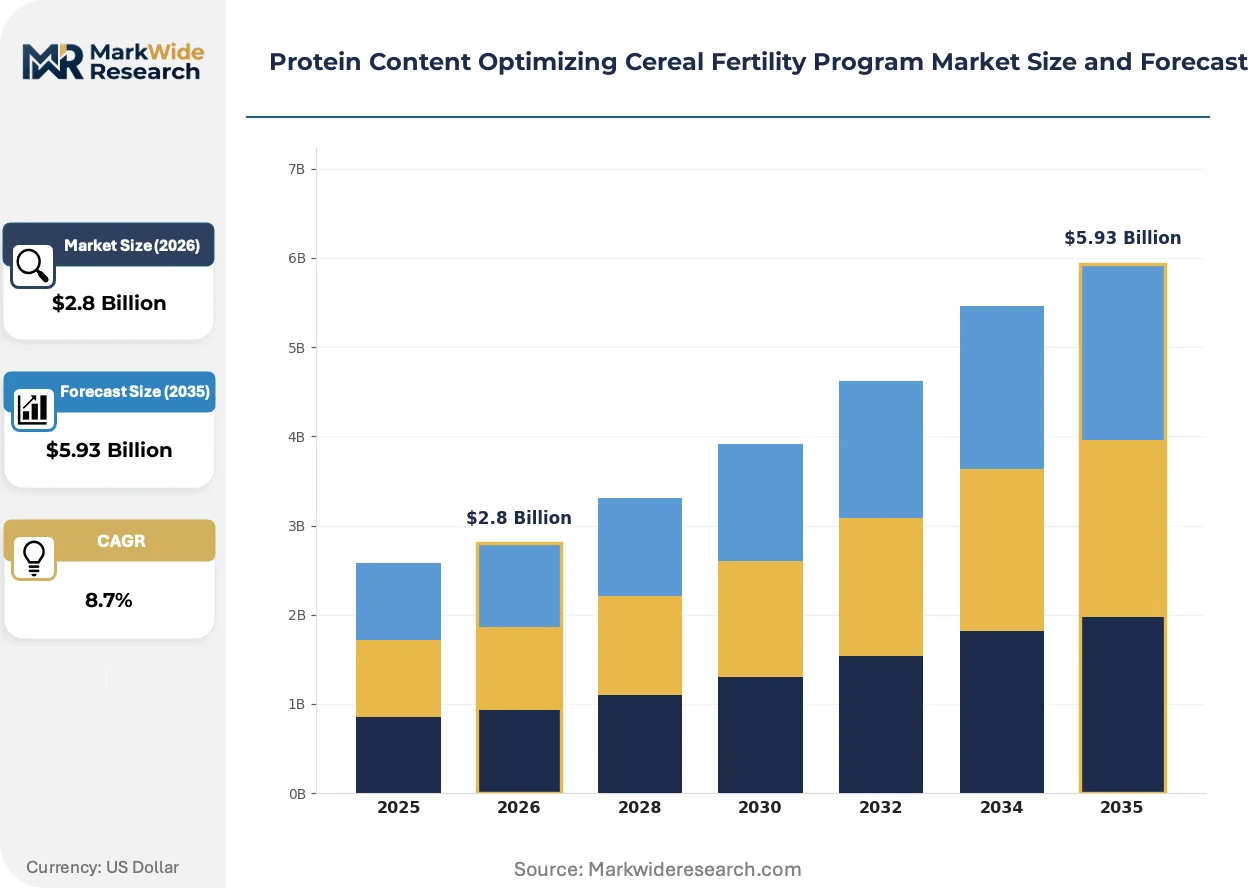
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Program Type: Soil Amendment, Nutrient Management, Crop Rotation, Biological Inoculants, Foliar Feeding Crop Focus: Wheat, Barley, Oats, Rye, Sorghum Application Method: Broadcasting, Drip Irrigation, Seed Treatment, Aerial Spraying, Fertigation End User: Grain Producers, Seed Producers, Agricultural Cooperatives, Crop Consultants |
| Companies Covered | Yara International, Nutrien, ICL Group, Haifa Group, BASF, Syngenta, Corteva Agriscience, Bayer, Koch Agronomic Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Content Optimizing Cereal Fertility Program Market Trends and Innovations
Digital agronomy platforms are rewiring how fertility decisions connect to end-use protein contracts, compressing the information lag between field application and elevator quality testing.
Controlled-release nitrogen formulations with polymer coatings are expanding into high-protein wheat production zones where growers face EU-mandated fertilizer rate ceilings. Kansas and North Dakota hard red wheat producers are retrofitting air seeders with enhanced-efficiency nitrogen attachments at accelerating adoption curves. This technology is expanding into premium contract structures by enabling documented nitrogen-use efficiency scores required by food manufacturer carbon disclosure programs.
REACH authorization processes for novel biostimulant active ingredients are tightening data requirements on environmental fate and ecotoxicology. Formulation developers must now generate chronic soil organism studies that extend registration timelines and capital requirements. German and French cereal growers seeking 20% synthetic nitrogen reductions under Farm to Fork targets are pressuring suppliers to accelerate biological product pipelines despite regulatory friction.
Grain elevator protein testing is compressing payment cycles from harvest delivery to real-time dockage adjustments. Large-scale milling buyers in the US Northern Plains now mandate third-party protein verification at intake, displacing grower-reported quality estimates. This behavioral shift concentrates demand for fertility programs with proven track records in specific protein bands, rewarding documented performance over brand recognition.
Protein Content Optimizing Cereal Fertility Program Market Segmentation
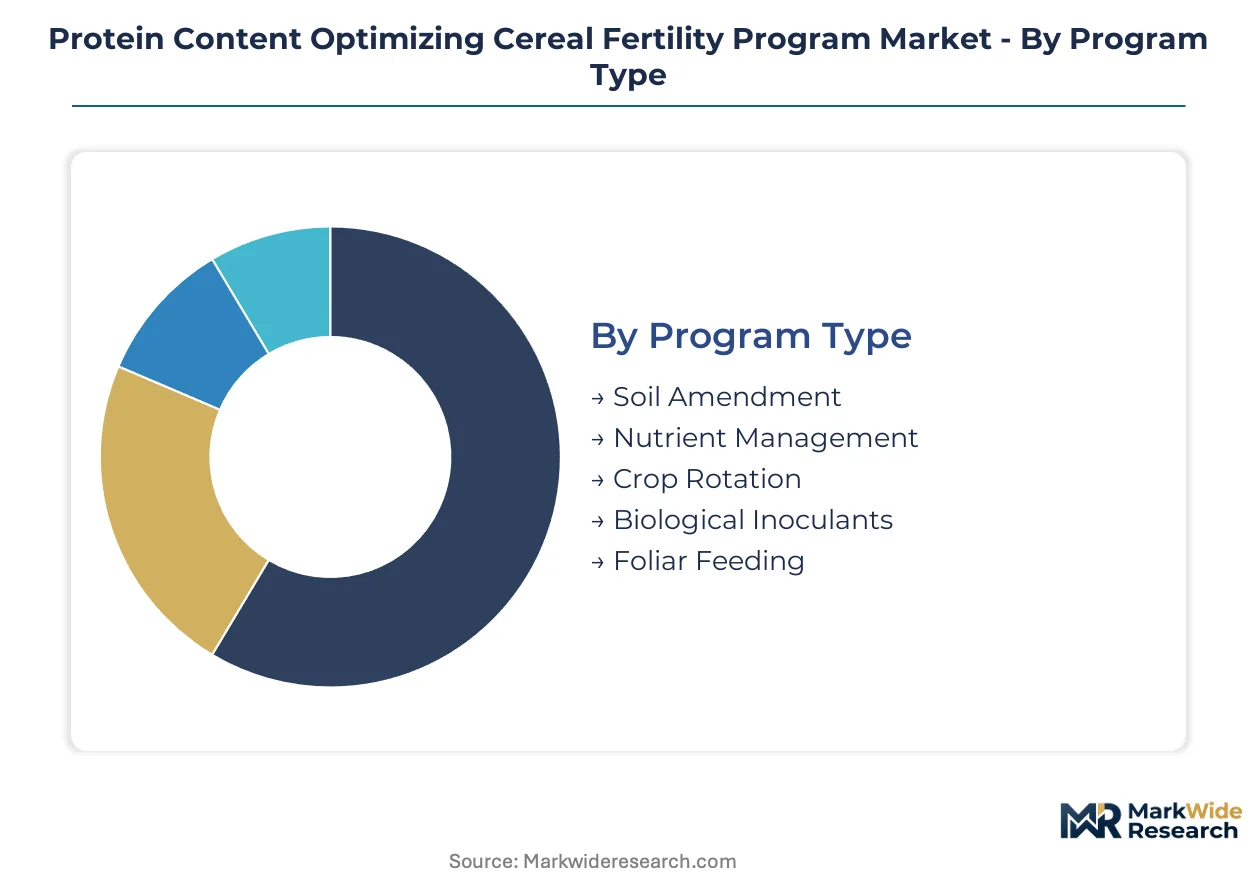
Protein Content Optimizing Cereal Fertility Program providers structure offerings around four distinct segmentation axes. Program Type determines the technical approach to nitrogen timing and source selection. Crop Focus dictates protein accumulation targets and application windows. Application Method shapes equipment requirements and labor scheduling. End User profiles drive service intensity and pricing architecture.
Program Type:
Volume concentration sits with programs that tie directly to elevator protein premiums, while biological alternatives command development investment despite smaller current share.
- Nutrient Management:Combines soil testing, variable-rate nitrogen prescriptions, and split-application timing calibrated to stem elongation and grain-fill protein accumulation curves. Kansas and North Dakota hard red wheat growers anchor demand through contracts requiring 12-14% protein thresholds. USDA Climate-Smart Commodities payments reinforce adoption by documenting nitrogen-use efficiency.
- Biological Inoculants:Deploy nitrogen-fixing microbes and biostimulant cocktails to reduce synthetic nitrogen rates 15-30% without yield penalty. German cereal belt growers under EU Green Deal Farm to Fork mandates drive fastest category expansion despite ECHA registration friction extending commercialization timelines 18-36 months.
- Soil Amendment:pH correction and organic matter enhancement protocols that precondition mineralization rates for subsequent nitrogen uptake.
- Foliar Feeding:Late-season micronutrient and nitrogen topdressing targeting the narrow grain-fill protein synthesis window.
- Crop Rotation:Legume integration and fallow management strategies that build residual nitrogen credits for cereal phases.
Today's leader: Nutrient Management. Tomorrow's challenger: Biological Inoculants.
Crop Focus:
Application complexity scales with protein premium structures, separating commodity grain from contract-driven specialty production.
- Wheat:Hard red winter and spring varieties dominate program deployment due to established protein premiums at US Northern Plains and German cereal belt elevators. Split nitrogen timing at stem elongation (Zadoks 30-32) and grain fill (Zadoks 71-75) requires precise equipment coordination. Milling buyer contracts now mandate third-party protein verification at intake, concentrating demand on programs with documented 12-14% performance track records.
- Barley:Malting quality specifications drive moderate protein management intensity, with brewers imposing maximum thresholds that invert the optimization logic from wheat.
- Oats:Food-grade and feed markets split application intensity, with human consumption channels requiring lower protein focus than wheat or barley.
- Rye:Smaller planted area limits dedicated program development, with fertility protocols typically adapted from wheat frameworks.
- Sorghum:Drought-tolerant production zones in US Southern Plains apply modified nitrogen timing due to different phenological stages and end-use feed focus.
Revenue concentrates in wheat. Technology transfer opportunities sit with barley.
Application Method:
Equipment access and labor availability separate scalable broadcast approaches from precision placement systems.
- Broadcasting:Surface nitrogen spreading with subsequent incorporation or rainfall activation remains the volume deployment mode across US Great Plains dryland production. Variable-rate spreader technology upgrades enable sub-field prescription execution without full precision planting infrastructure.
- Seed Treatment:Pre-plant biological and nutrient coatings establish program loyalty prior to seasonal fertility decisions, capturing lifetime customer value through locked-in protocol adherence.
- Fertigation:Center-pivot and drip integration enables multiple in-season nitrogen passes with precise timing control, limited to irrigated acreage in Nebraska and Kansas.
- Drip Irrigation:Subsurface delivery systems concentrate in high-value specialty crop zones with limited cereal penetration.
- Aerial Spraying:UAV and manned aircraft foliar applications address the narrow grain-fill protein accumulation window when ground equipment risks crop damage.
Broadcasting captures current volume. Seed Treatment secures future retention.
End User:
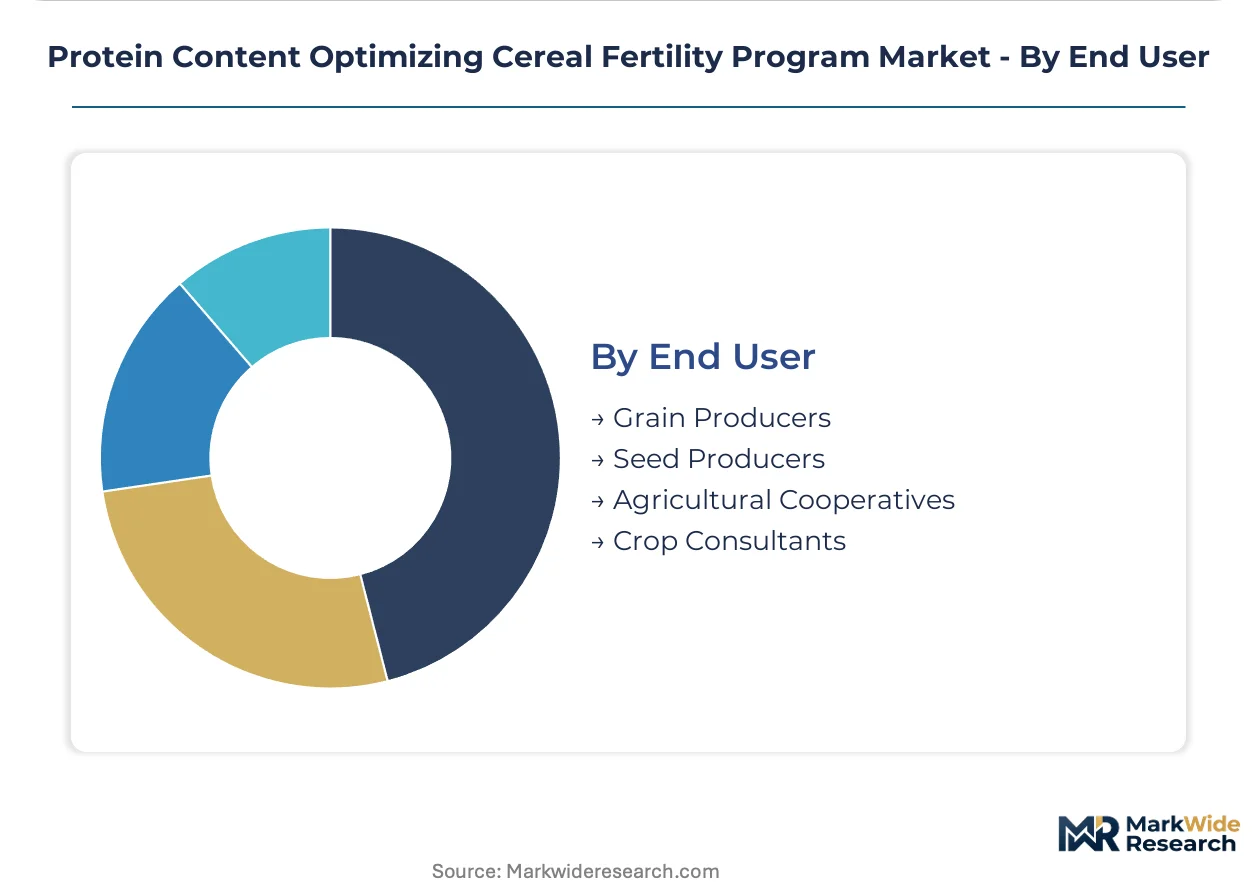
Decision authority and technical sophistication shape service delivery models across customer types.
- Grain Producers:Individual farm operators managing 500-5,000 cereal acres represent the core customer base, with protein premium contracts directly linking fertility investment to revenue. Precision agriculture adoption correlates with farm size and elevator proximity.
- Agricultural Cooperatives:Member-owned input suppliers aggregate demand across thousands of acres, enabling equipment sharing and bulk purchasing that reduces per-acre program costs.
- Seed Producers:Foundation and certified seed operations require stringent quality protocols that extend fertility management to germination standards and varietal purity.
- Crop Consultants:Independent agronomists and retail agronomy services prescribe programs across client portfolios, acting as influential intermediaries between technology providers and growers.
Grain Producers drive current revenue. Agricultural Cooperatives scale fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting cereal fertility investment toward jurisdictions where nitrogen-use efficiency compliance costs diverge from protein premium returns. Growers in regions with stringent EU-mandated rate ceilings face compressed margins against US Northern Plains competitors accessing USDA Climate-Smart Commodities payments. This cost-of-compliance gap is reshaping where precision nutrient management technology deploys first.
United States
Kansas and North Dakota hard red wheat growers anchor North American demand through elevator contracts requiring 12-14% protein verification. The USDA's Climate-Smart Commodities program reimburses documented nitrogen-use efficiency, accelerating variable-rate adoption across the Northern Plains. Fargo-Moorhead and Wichita serve as agronomic service hubs where soil testing networks tie prescriptions to end-use premiums.
Germany
The EU Green Deal's Farm to Fork strategy mandates 20% synthetic nitrogen reductions across the cereal belt, intensifying demand for biological inoculant alternatives. ECHA registration friction extends product timelines 18-36 months, favoring incumbents with established portfolios. Lower Saxony and Bavaria concentrate milling buyer procurement where protein premiums now structure contract pricing.
France
Paris Basin wheat producers face parallel Farm to Fork compliance pressures with weaker protein premium infrastructure than Germany. The national agricultural regulator enforces fertilizer reduction targets through regional water agency directives. Île-de-France grain cooperatives are piloting split-application protocols calibrated to carbon intensity scoring from food manufacturers.
Canada
Saskatchewan and Manitoba spring wheat operations apply modified protein optimization due to shorter growing windows and different phenological stages. Health Canada's PMRA regulates enhanced-efficiency fertilizer registrations with environmental fate requirements. Winnipeg-based agricultural retailers are integrating prairie-wide soil testing networks with elevator protein verification systems.
Australia
New South Wales and Victoria winter cereal zones deploy precision fertility against variable rainfall patterns that complicate split nitrogen timing. The national agricultural regulator oversees biostimulant claims under evolving organic certification interfaces. Dubbo and Wagga Wagga cluster agronomic advisory services linking in-field tissue testing to export protein specifications.
Protein Content Optimizing Cereal Fertility Program Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biological inoculant specializations under carbon accounting protocols. The vendor base stratifies between multinational input suppliers with controlled-release nitrogen portfolios and regional agronomic service firms with soil testing network density. Three archetypes dominate: precision application technology integrators, biological efficacy researchers, and cooperative-owned input distributors. Consolidation pressure runs through seed treatment channel acquisitions and variable-rate hardware partnerships.
Within the precision nutrient management tier, Yara International and Nutrien exemplify divergent strategic positioning. Yara leverages Norwegian-originated controlled-release formulations to capture protein-linked pricing in high-premium contract zones. Nutrien anchors North American market presence through retail agronomy networks that convert soil test data into prescription algorithms. BASF occupies a biological integration position, reducing synthetic nitrogen dependence through microbial inoculant protocols that align with emerging Scope 3 verification frameworks.
| Leading Market Players |
|---|
| Yara International |
| Nutrien |
| ICL Group |
| Haifa Group |
| BASF |
| Syngenta |
| Corteva Agriscience |
| Bayer |
| Koch Agronomic Services |
| Others |
Pricing and Supply Chain Analysis
Phosphate and potash feedstock costs cascade through fertilizer formulation tiers, compressing margins for biological inoculant developers while concentrating pricing power with Moroccan and Russian phosphate rock suppliers and Canadian potash exporters. Elevator protein premiums in Kansas and North Dakota create value-based pricing corridors that reward documented nitrogen-use efficiency, separating premium fertility program tiers from commodity broadcast applications.
Pricing Analysis
Distributor margins in the US Great Plains anchor the pricing architecture, with agronomic service providers capturing 15-25 point markups on controlled-release nitrogen formulations tied to hard red wheat protein contracts. Price differentiation separates seed treatment bundled programs from standalone nutrient management prescriptions, with volume scale and carbon intensity certification emerging as secondary tiering mechanisms. Pricing pressure stems from phosphate and potash input volatility eroding program margin predictability. Grain producers managing under 2,000 acres exhibit highest price sensitivity, while cooperative aggregators leverage bulk purchasing to secure standard-tier discounts.
Supply Chain Analysis
Single-source vulnerability sits with Moroccan phosphate rock and Russian potash concentrate, exposing formulation developers to geopolitical supply disruptions and freight cost spikes. Raw material dependencies center on ammonia feedstock, polymer coating resins, and microbial culture substrates for biological inoculant production. Supply chain risk concentrates in tariff exposure on Chinese-sourced enhanced-efficiency fertilizer components. Distribution runs through cooperative-owned retail networks in the US Northern Plains and Germany's cereal belt, with seed treatment channels capturing pre-plant customer lock-in.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Protein Content Optimizing Cereal Fertility Program Market functions as a stable compounder, with protein premium structures at grain elevators generating recurring revenue visibility for precision nutrient management providers.
For Market Incumbents: Extend controlled-release nitrogen formulation pipelines into carbon-accounting-certified tiers, securing USDA Climate-Smart Commodities payment eligibility before biological inoculant challengers achieve ECHA registration scale. Deepen soil testing network density in Saskatchewan and Manitoba to preempt Canadian spring wheat competitors. Vertical integration into seed treatment coating capacity locks in program loyalty prior to seasonal fertility decisions. For New Entrants and Emerging Players: Launch via drone-enabled aerial foliar application services targeting the narrow grain-fill protein accumulation window, bypassing capital-intensive ground equipment requirements. White-space opportunities concentrate in Australian winter cereal zones with variable rainfall patterns complicating split nitrogen timing. Paris Basin wheat producers under Farm to Fork compliance pressures represent the most penetrable EU geography given weaker protein premium infrastructure than Germany. For Investors and Strategic Acquirers: Consolidation pressure builds where biological inoculant developers face ECHA registration friction extending commercialization timelines 18-36 months, creating distressed acquisition targets with viable efficacy data but exhausted capital reserves. Long-term viability favors precision application technology integrators with satellite-derived nitrogen stress indices and real-time prescription algorithms. The signal to watch is grain elevator protein testing compression from harvest delivery to real-time dockage adjustments, which concentrates demand on programs with documented performance track records.| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced-Efficiency Fertilizer Registration | EPA and ECHA approvals unlock premium pricing in nitrogen-rate-constrained jurisdictions. |
| Seed Treatment Channel Acquisition | Pre-plant biological coatings establish customer lifetime value before seasonal decisions. |
| Remote Sensing Platform Integration | Satellite-derived nitrogen stress indices enable real-time grain-fill prescription adjustments. |
| Carbon Accounting Protocol Certification | Scope 3 verification creates premium tiers for low-carbon fertility footprints. |
| Cooperative Distribution Partnership | Member-owned input suppliers aggregate demand across thousands of acres for equipment sharing. |
Research Methodology
Multiple input streams — agronomist interviews, grain elevator procurement manager consultations, and biological product developer technical assessments — were reconciled against customs data on phosphate and potash trade flows, USDA Climate-Smart Commodities program disclosures, and ECHA biostimulant registration databases. Secondary validation drew from EPA Clean Water Act enforcement patterns, EU Farm to Fork strategy implementation reports, and elevator protein premium contract structures. Bottom-up acreage estimates for precision nutrient management adoption were cross-checked against top-down fertilizer industry shipment data.
Historical adoption curves for variable-rate application technology were cross-referenced against panel input from precision agriculture equipment manufacturers and cooperative agronomy directors. Segmentation modeling tracked program type, crop focus, application method, and end user across the projection horizon. CAGRs were derived from protein premium spread trajectories, nitrogen-use efficiency documentation requirements, and biological inoculant pipeline progression rates. Forecast inputs incorporated split-application equipment deployment cycles and carbon intensity scoring adoption by food manufacturers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA regulatory acceleration or abrupt phosphate supply disruption scenarios. Forecasts reflect documented assumptions on protein premium persistence and biological efficacy variance across soil microbiome conditions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
Seed Treatment Market
Seed Technology
North America Cotton Seed Treatment Market
Seed Technology
North America Seed Coating Materials Market
Seed Technology
Mexico Seed Treatment Market
Seed Technology
Seed Coating Ingredients Market
Seed Technology
India Seed Treatment Market
Seed Technology
Seed Coating Materials Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
China Seed Treatment Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
Asia-Pacific Seed Coating Materials Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
Seed Additives Market
Seed Technology
France Seed Treatment Market
Seed Technology
Canada Seed Treatment Market
Seed Technology
Seed Storage Systems Market