
 Europe Seed Coating Materials Market | 2026-2036
Europe Seed Coating Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Seed Coating Materials Market Foresight
Modular coating configurations—stacking polymer films with micronutrient and biological layers—is broadening buyer choice across seed producers and agricultural companies. BASF SE leverages its polymer science portfolio to anchor premium coating formulations for oilseed applications. Bayer CropScience AG sustains R&D intensity in biological seed treatment integration, while Croda International PLC specializes in sustainable bio-based coating chemistries that navigate tightening EU environmental standards.
Europe seed coating materials encompass functional films and treatments applied to seed surfaces to improve handling, germination uniformity, and protection against soil-borne pathogens, typically comprising polymer binders, active ingredients, and filler materials applied through rotary pan or fluidized bed processes. Polymer coatings dominate value capture due to their role in precision placement and dust reduction, while biological coatings represent the fastest-expanding margin pool as bacterial and fungal inoculants displace synthetic chemistries. Clay coatings retain cost-sensitive share among grain farmers, though micronutrient coatings are gaining traction where soil deficiencies drive agronomic prescriptions.
The EU Green Deal and REACH framework restrict persistent biocide use in seed treatments, compelling reformulation toward biological actives and low-toxicity polymers. EFSA residue assessments and national implementations of the Sustainable Use of Pesticides Directive shape product registration timelines and market access conditions across member states. Stakeholders must monitor evolving biodegradability certifications and carbon accounting rules for agricultural inputs to anticipate which coating platforms retain commercial viability.
Market Dynamics
Polymer film stacking is compressing the distinction between functional and biological seed coatings, forcing formulators to integrate micronutrient layers with bacterial inoculants in single-pass application systems. This convergence is reconfiguring R&D priorities across European agricultural input suppliers.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Biocide restrictions under EFSA residue assessments are redirecting formulation investment toward bacterial and fungal inoculants, expanding addressable demand for biological coating platforms.
- Precision sowing equipment penetration:Large-scale arable operations in Germany and France require polymer-coated seeds for uniform placement, sustaining premium coating volumes.
- Soil deficiency mapping:Micronutrient coatings tailored to zinc and manganese deficits in Polish loess soils are creating prescription-driven coating demand.
Market Restraints
- Petrochemical polymer feedstock volatility:Polyurethane and acrylic binder costs fluctuate with naphtha pricing, compressing margin stability for coating manufacturers.
- Registration timeline friction:REACH substance authorization and EFSA residue assessments extend product commercialization cycles by 18-36 months.
- Clay coating substitution:Cost-sensitive grain farmers in Eastern Europe retain uncoated or clay-dusted seed practices, capping biological coating penetration.
Strategic Opportunities
- Romanian and Bulgarian expansion:Consolidating arable farms in these accession markets lack coating infrastructure, creating first-mover installation opportunities.
- Carbon accounting integration:CSRD disclosure requirements for agricultural inputs are positioning bio-based coatings as Scope 3 reduction instruments for food processors.
- Biological-polymer convergence:Fluidized bed systems that apply polymer films with live bacterial cultures in single-pass operations are opening premium formulation tiers.
Industry Challenges
- Formulation chemist scarcity:Cross-disciplinary expertise spanning polymer science and microbial viability is concentrated among senior researchers at German and Dutch institutes.
- Biodegradability certification complexity:Divergent national implementations of EU fertilizing product regulations create fragmented compliance pathways across member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Seed Coating Materials Market |
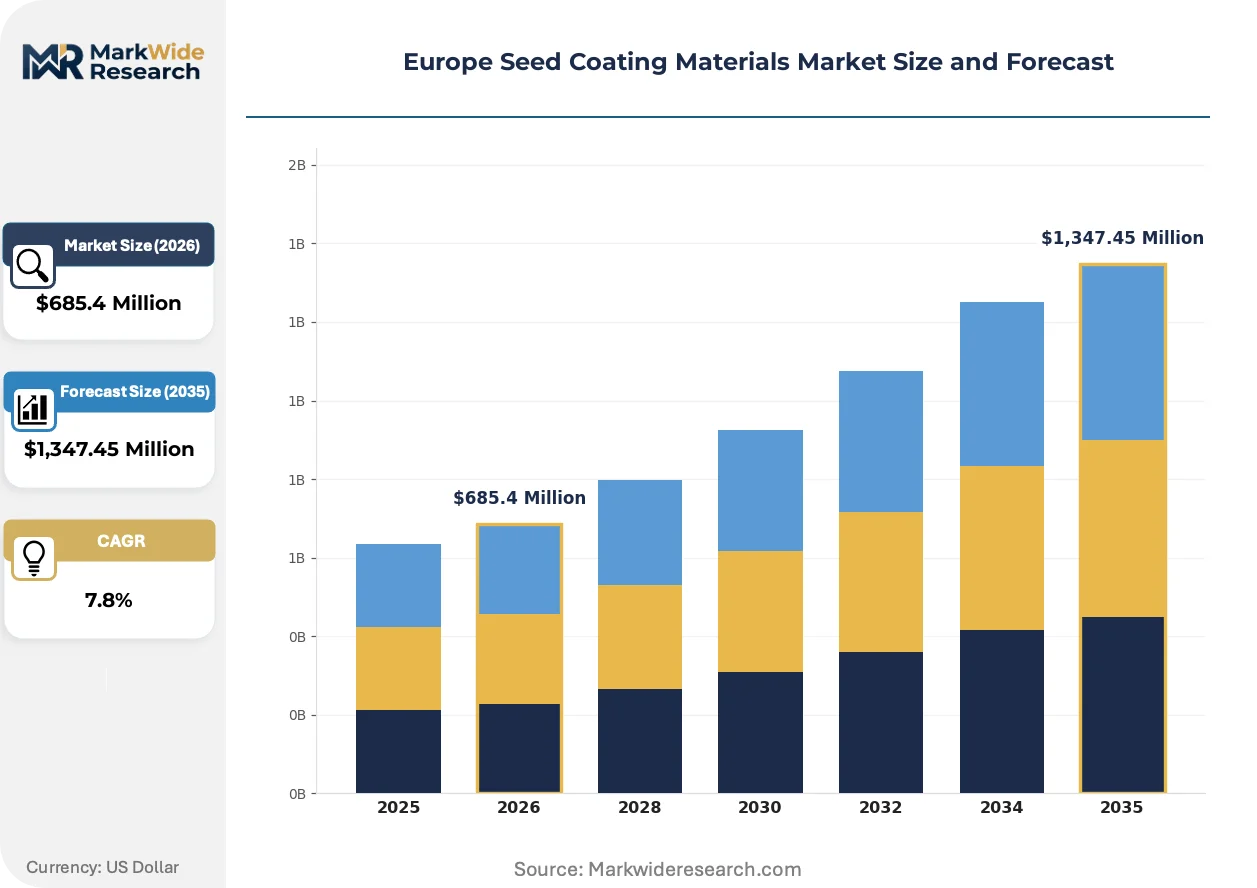
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,347.45 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Coatings, Clay Coatings, Micronutrient Coatings, Biological Coatings Application: Fruits, Vegetables, Grains, Oilseeds End User: Farmers, Agricultural Companies, Seed Producers, Retailers Distribution Channel: Online Sales, Direct Sales, Distributors, Retail Stores |
| Companies Covered | BASF SE, Bayer CropScience AG, Clariant International Ltd, Croda International PLC, Germains Seed Technology, Incotec Group, Syensqo, Lanxess AG, Chromatech Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Seed Coating Materials Market Shifts & Advancements
Multi-layer coating architectures are displacing single-function treatments as the default technical specification. This shift is compressing equipment upgrade cycles and elevating technical service intensity in supplier-customer relationships.
Encapsulated rhizobium inoculants integrated with polymer binders are electrifying biological seed treatment adoption among oilseed rape producers. French and German farmers are specifying these dual-function coatings for autumn sowing programs. The technology is electrifying margin capture for formulators capable of maintaining bacterial viability through film-curing temperatures.
REACH restriction proposals on microplastic-containing seed coatings are compelling polymer reformulation toward bio-based alginates and chitosan derivatives. Coating manufacturers must resubmit technical dossiers for existing product lines. Oilseed applications face the most acute substitution pressure due to film thickness requirements for large seed geometry.
Buyer consolidation among European agricultural cooperatives is compressing procurement negotiation cycles and elevating volume-commitment contracting. Smaller coating houses are losing access to preferential polymer supply terms. This concentration is most visible in the Netherlands and Denmark where farmer-owned purchasing groups control 60% of coated seed volumes.
Europe Seed Coating Materials Market Segmentation
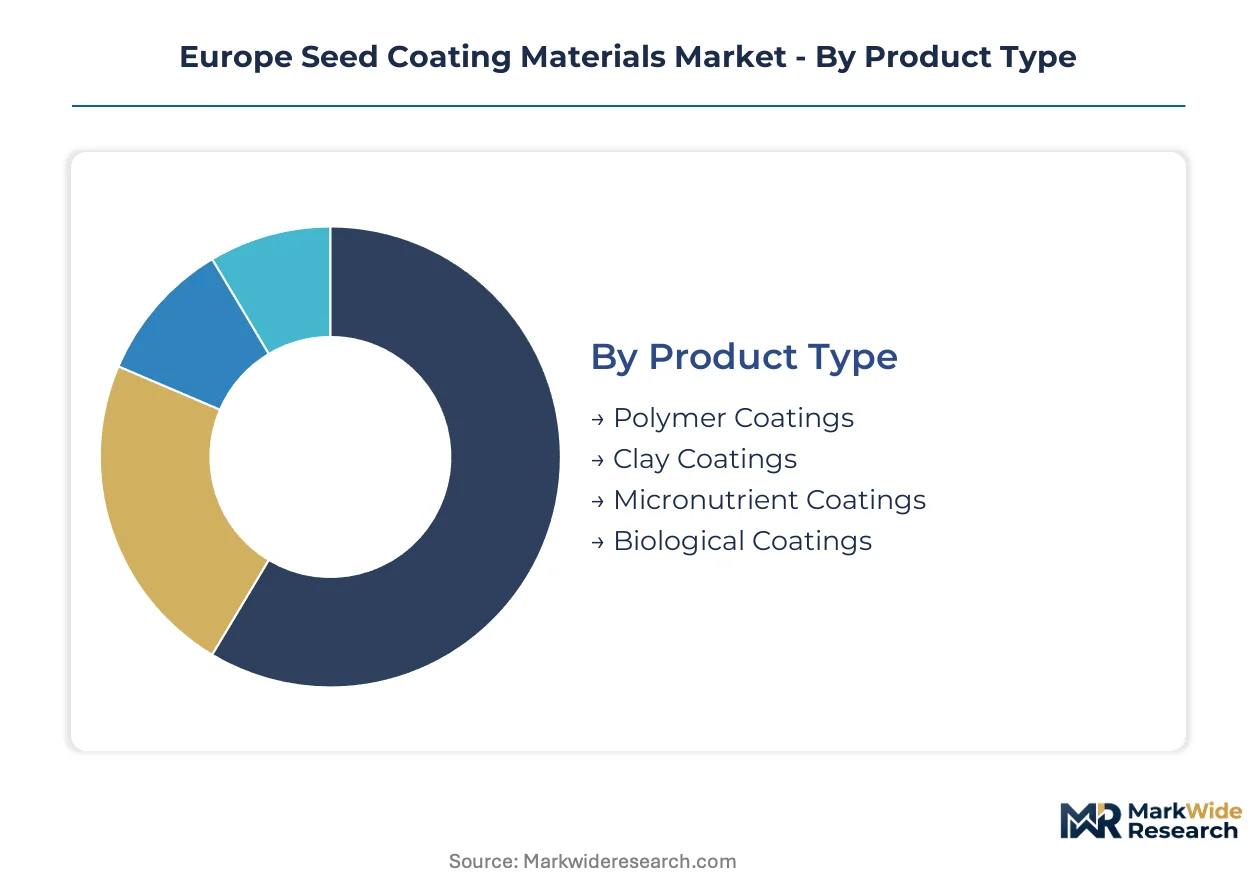
Coating specification choices determine machinery compatibility, regulatory compliance pathways, and agronomic return thresholds across European farming operations. Segment boundaries are blurring as multi-layer formulations stack polymer films with biological actives and micronutrients in single-pass application systems.
Product Type:
Polymer chemistry specifications anchor functional performance in precision sowing equipment, while biological viability requirements introduce formulation complexity that separates premium from commodity coating tiers.
- Polymer Coatings:Polyurethane and acrylic binder systems deliver dust reduction and uniform seed flow for precision drills. German and French arable operations specify these for oilseed rape and maize sowing programs where placement accuracy drives establishment rates. REACH restriction proposals on microplastic-containing formulations are compelling reformulation toward bio-based alginates.
- Biological Coatings:Bacterial and fungal inoculants—particularly encapsulated rhizobium for oilseed applications—displace synthetic chemistries under EU Green Deal biocide restrictions. French autumn sowing programs are specifying these dual-function coatings, though maintaining microbial viability through film-curing temperatures elevates technical service intensity.
- Micronutrient Coatings:Zinc and manganese layers tailored to Polish loess soil deficiencies create prescription-driven demand among precision agriculture adopters.
- Clay Coatings:Cost-sensitive grain farmers in Eastern Europe retain this traditional practice, capping penetration of advanced coating platforms.
Mature deployment sits with Polymer Coatings. Newer deployment is concentrated in Biological Coatings.
Application:
Crop value per hectare and seed size geometry shape coating specification intensity, with high-value horticultural crops justifying multi-layer treatments that grain operations cannot amortize.
- Oilseeds:Large seed geometry demands thicker polymer films for handling protection and precision placement. Autumn-sown oilseed rape in France and Germany commands premium coating tiers integrating rhizobium inoculants with micronutrient layers. REACH microplastic restrictions hit this segment hardest due to film thickness requirements.
- Grains:Wheat and barley sowing across Polish and Romanian farms prioritizes cost efficiency, with clay-dusted or uncoated seed retaining significant share. Consolidating arable operations in Bulgaria are upgrading to basic polymer coatings as precision drill penetration advances.
- Vegetables:High seed value and transplant establishment requirements drive specification of multi-layer treatments among Dutch and Spanish protected cropping operations.
- Fruits:Specialty rootstock and propagation material in Italian and Greek orchards utilizes biological coatings for soil-borne pathogen suppression.
Volume concentration rests with Grains. Margin expansion concentrates in Oilseeds.
End User:
Procurement scale and technical capability determine whether coating decisions flow through centralized R&D functions or decentralized farm-level purchasing.
- Seed Producers:Multinational breeding companies in the Netherlands and Denmark specify proprietary coating formulations as competitive differentiation, controlling 60% of coated seed volumes through farmer-owned purchasing groups.
- Agricultural Companies:Input distributors with technical service arms prescribe coating packages tied to soil testing and precision agriculture subscriptions.
- Farmers:Large-scale arable operations in Germany conduct direct procurement of coated seed, while smaller Polish holdings rely on cooperative aggregation.
- Retailers:Garden center and amenity channels move pre-packaged consumer seed with basic film coatings.
Technical specification authority sits with Seed Producers. Volume aggregation runs through Agricultural Companies.
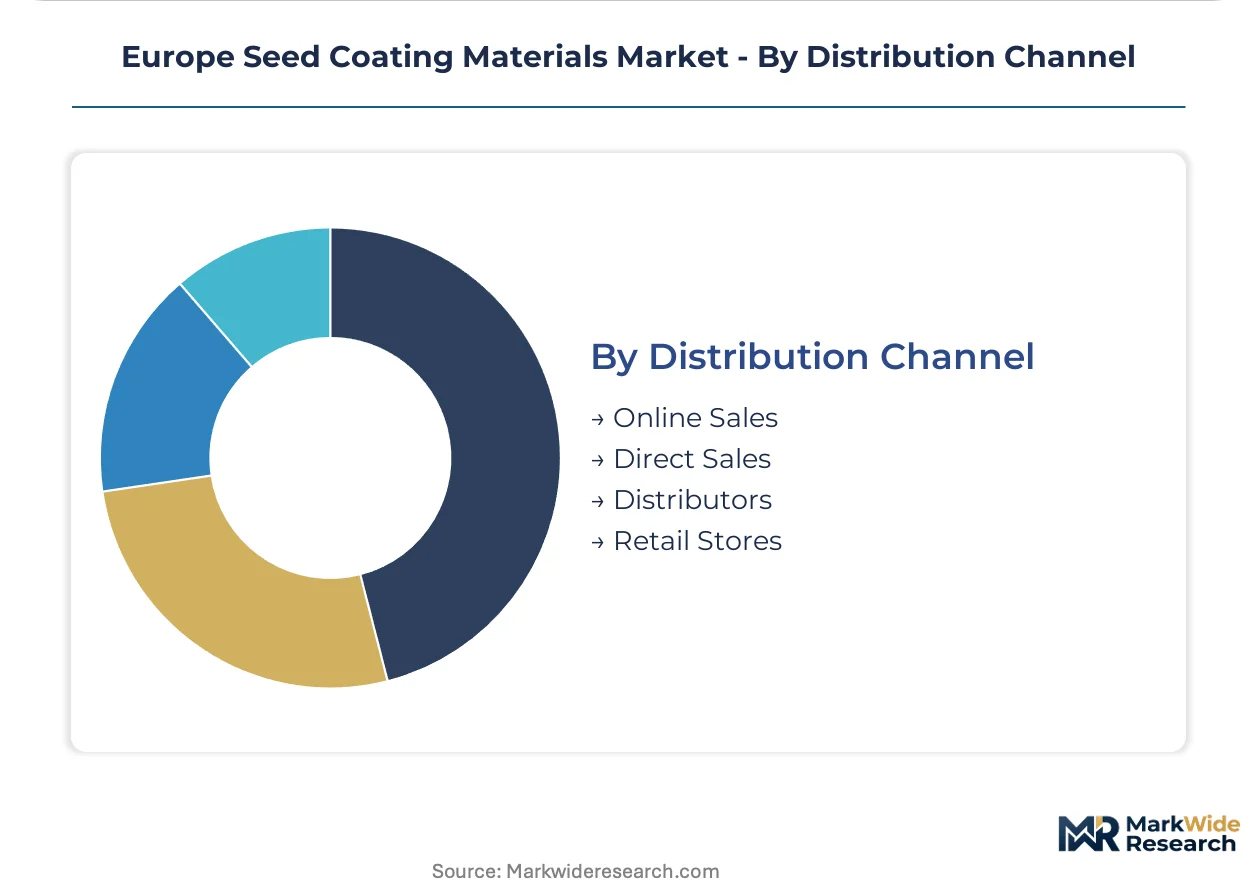
Distribution Channel:
Channel selection reflects order scale, technical consultation requirements, and the physical logistics of perishable coated seed inventory.
- Direct Sales:Seed producers and major agricultural companies transact volume contracts with technical service attachments, bypassing distributor margins for large German and French arable operations.
- Distributors:Regional agrochemical wholesalers maintain coating application equipment and inventory for mid-scale Polish and Romanian farms lacking on-film infrastructure.
- Online Sales:Specialty biological inoculants and micronutrient packages reach precision agriculture adopters through direct-to-farm platforms.
- Retail Stores:Traditional farm supply cooperatives serve Eastern European grain farmers with commodity coating products.
High-volume flow moves through Direct Sales. Technical consultation concentrates in Distributor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western European countries consume the majority of seed coating materials while production capacity clusters in Germany and the Netherlands. Eastern European markets remain underpenetrated but present installation opportunities for coating infrastructure.
Germany
Large-scale arable operations in Lower Saxony and Brandenburg specify polymer-coated seeds for precision oilseed rape and maize sowing. ECHA substance authorization under REACH extends commercialization timelines for new coating formulations. BASF SE anchors polymer science R&D in Ludwigshafen, driving bio-based binder development to meet microplastic restriction proposals.
France
Autumn oilseed rape programs in Île-de-France and Hauts-de-France command premium dual-function coatings integrating rhizobium inoculants. EU Green Deal Farm to Fork biocide restrictions redirect investment toward biological coating platforms. Croda International PLC maintains formulation development near Paris to serve farmer-owned purchasing groups controlling regional procurement.
Poland
Precision agriculture adopters in Greater Poland and Silesia specify zinc and manganese micronutrient coatings tailored to loess soil deficiencies. National implementations of the Sustainable Use of Pesticides Directive shape product registration conditions. Consolidating arable farms upgrade from clay-dusted to basic polymer coatings as precision drill penetration advances.
Netherlands
Dutch seed producers and agricultural cooperatives specify proprietary coating formulations as competitive differentiation in vegetable and ornamental propagation. CSRD disclosure requirements position bio-based coatings as Scope 3 reduction instruments for food processors. Incotec Group and Germains Seed Technology cluster near Wageningen to access microbial viability research infrastructure.
Romania
Consolidating arable farms in the Romanian Plain lack coating infrastructure, creating first-mover installation opportunities for fluidized bed application systems. EFSA residue assessments determine which biological actives gain market access. Bayer CropScience AG targets distributor partnerships in Bucharest and Cluj-Napoca to establish technical service presence ahead of competitor entry.
Europe Seed Coating Materials Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, with market structure tilting toward integrated agricultural input suppliers with polymer science capabilities. Three archetypes dominate: multinational chemical conglomerates leveraging material science portfolios, dedicated seed technology specialists with microbial viability expertise, and regional coating houses serving commodity grain markets. Competitive moves concentrate on biological-polymer convergence R&D and geographic expansion into underpenetrated Eastern European markets.
Among Germany-based diversified suppliers, BASF SE and Bayer CropScience AG occupy positions spanning polymer binders through biological integration, while UK-headquartered Croda International PLC exemplifies the sustainable chemistry specialist archetype navigating tightening EU environmental standards. Syensqo represents the mid-tier European material science player reformulating to address REACH microplastic restrictions.
| Leading Market Players |
|---|
| BASF SE |
| Bayer CropScience AG |
| Clariant International Ltd |
| Croda International PLC |
| Germains Seed Technology |
| Incotec Group |
| Syensqo |
| Lanxess AG |
| Chromatech Incorporated |
| Others |
Supply & Pricing Matrix
Captive polymer production by German and Dutch chemical conglomerates anchors both supply security and pricing power across coating formulation tiers. This backward integration into polyurethane and acrylic binders shields integrated suppliers from naphtha feedstock volatility while compressing margin capture opportunities for independent coating houses dependent on spot market procurement.
Pricing Analysis
Margin tightening in biological coating tiers reflects the technical complexity of maintaining microbial viability through film-curing processes. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade under REACH substance authorization and volume commitment scale. Cost-down pressure on commodity polymer coatings accelerates because Eastern European grain farmers retain clay-dusted alternatives. Seed producers controlling farmer-owned purchasing groups exhibit lowest price sensitivity, while independent Romanian distributors face acute procurement constraints.
Supply Chain Analysis
REACH substance authorization and EFSA residue assessments function as qualification gates that filter supplier participation across formulation categories. Manufacturing concentrates in Germany, the Netherlands, and France. Feedstock supply draws from petrochemical naphtha streams, bio-based alginate cultivation, and chitosan derivative processing. Single-source vulnerability sits with encapsulated rhizobium inoculant strains held by limited microbial culture collections. Distribution runs through seed producer direct contracts and regional agrochemical wholesalers maintaining coating application equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe seed coating market sits in a polymer-to-biological transition phase as encapsulated rhizobium inoculants displace synthetic biocide treatments under EU Green Deal restrictions.
For Market Incumbents: To counter margin compression from petrochemical feedstock volatility, BASF SE and Bayer CropScience AG should deepen backward integration into bio-based alginate cultivation while accelerating certification investment for dual-function polymer-biological formulations under REACH microplastic restriction proposals. For New Entrants and Emerging Players: Launch via fluidized bed application system partnerships in Romania and Bulgaria where consolidating arable farms lack coating infrastructure. White-space concentration sits with micronutrient prescriptions for Polish loess soil deficiencies and biological inoculant distribution through direct-to-farm precision agriculture platforms. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified agricultural input conglomerates seeking microbial viability capabilities. Five-to-ten year viability favors specialists with cross-disciplinary formulation expertise spanning polymer science and bacterial culture maintenance. Watch EFSA residue assessment timelines for biological actives as inflection indicator for platform substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Binders | Captive alginate supply secures REACH-compliant polymer formulations against microplastic restriction proposals. |
| Fluidized Bed System Installation | Single-pass polymer-biological application opens premium coating tiers for oilseed rape producers in France. |
| EFSA Regulatory Pre-Submission | Early residue assessment engagement compresses commercialization timelines for bacterial inoculant formulations. |
| Farmer-Owned Cooperative Partnership | Access to Dutch and Danish purchasing groups controlling sixty percent of coated seed volumes anchors demand. |
| Carbon Accounting Certification | CSRD-compliant bio-based coatings position suppliers as Scope 3 reduction instruments for food processors. |
Research Methodology
Independent corroboration across coating formulator technical directors, seed producer procurement managers, and EFSA regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from REACH substance authorization databases, EU fertilizing product regulation implementation records, and customs trade data for polymer binder imports. Bottom-up volume estimates from application equipment installations triangulate against top-down agricultural input expenditure flows.
Rate-of-change decomposition separates volume expansion from value mix shift across the projection horizon. Segmentation dimensions encompass coating chemistry tier, crop application intensity, end-user procurement scale, and national regulatory implementation cluster. CAGRs derive from iterative convergence between equipment penetration curves and substitution elasticity parameters for biological versus synthetic actives. Forecast inputs incorporate precision drill adoption rates in German arable operations and EFSA residue assessment pipeline status.
REACH restriction proposal adoption delays, EFSA biological active authorization reversals, and naphtha price volatility spikes are the dominant revision risks. Forecasts reflect documented assumptions regarding regulatory implementation timelines and equipment upgrade cycles. A model refresh is warranted upon material change in EU Green Deal Farm to Fork biocide restriction enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
France Seed Treatment Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
China Seed Treatment Market
Seed Technology
Seed Coating Materials Market
Seed Technology
Mexico Seed Treatment Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
Japan Seed Treatment Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
Seed Treatment Market
Seed Technology
North America Seed Coating Materials Market
Seed Technology
Asia-Pacific Seed Coating Materials Market
Seed Technology
North America Cotton Seed Treatment Market
Seed Technology
Canada Seed Treatment Market
Seed Technology
Protein Content Optimizing Cereal Fertility Program Market
Seed Technology
Seed Additives Market