
 Canada Seed Treatment Market | 2026-2036
Canada Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Seed Treatment Market Outlook
Biological efficacy standards is rotating the Canada seed treatment market toward premium formulations with verified colony-forming-unit guarantees. BASF SE leverages its microbial pipeline to anchor biological seed treatment development in Saskatoon research facilities. Syngenta Group sustains broad-spectrum chemical portfolios while navigating PMRA re-evaluation timelines for neonicotinoid compounds. Bayer CropScience AG competes through in-house production of seed-applied biologicals, controlling quality from fermentation through field delivery.
Canada seed treatment encompasses the application of protective or performance-enhancing agents—fungicides, insecticides, nematicides, inoculants, or growth promoters—directly onto seed surfaces prior to planting, typically at rates of milliliters per hundred kilograms of seed, to establish early-season crop protection before canopy closure. The primary purpose is to reduce establishment-phase mortality from soil-borne pathogens and early insect pressure, thereby improving plant population uniformity and final yield recovery. Chemical treatment dominates current volume but biological treatment captures expanding margin pools as Prairie growers face pollinator stewardship obligations under provincial environmental farm plans. Seed companies represent the fastest-growing end-user channel, with agricultural cooperatives in Manitoba and Saskatchewan consolidating procurement to secure volume pricing on treated canola and wheat seed.
Health Canada and PMRA govern active ingredient registration and maximum residue limits under the Pest Control Products Act, while provincial regulators in Alberta, Saskatchewan, and Manitoba enforce seed quality standards through respective agricultural services corporations. The Pest Management Regulatory Agency's accelerated timeline for neonicotinoid specialty reviews is forcing reformulation toward biological alternatives and non-systemic chemistries. Stakeholders must monitor PMRA final decisions on clothianidin and thiamethoxam seed uses, as these rulings will determine whether domestic formulators retain access to core cereal and canola protection chemistries or must complete biological registration packages within compressed windows.
Market Dynamics
PMRA's accelerated neonicotinoid re-evaluation timeline is compressing formulation windows and forcing Prairie growers toward biological alternatives before canopy closure. This regulatory pressure is restructuring supplier relationships and R&D priorities across the Canadian agricultural input sector.
Growth Catalysts
- Pollinator Stewardship Obligations:Provincial environmental farm plans in Saskatchewan and Alberta mandate habitat buffers that favor biological seed treatments over systemic chemistries for canola establishment.
- PMRA Re-evaluation Timelines:The Pest Management Regulatory Agency's specialty review process is accelerating registration packages for non-neonicotinoid chemistries and microbial inoculants.
- Prairie Cooperative Consolidation:Agricultural cooperatives in Manitoba and Saskatchewan are aggregating procurement volumes to secure treated seed supply contracts with verified biological efficacy guarantees.
Market Restraints
- Active Ingredient Supply Concentration:Domestic production of microbial fermentation inputs concentrates in Saskatoon research corridors, creating geographic vulnerability for biological formulation supply.
- CFU Verification Costs:Colony-forming-unit guarantee testing for biological seed treatments requires specialized laboratory infrastructure that elevates per-batch quality assurance expenses.
- Chemical Residue Limits:Health Canada's tightening maximum residue limits under the Pest Control Products Act restrict re-treatment flexibility for cereal and oilseed growers facing variable spring conditions.
Strategic Opportunities
- Manitoba Pulse Expansion:Underpenetrated lentil and pea acreage in southwestern Manitoba offers first-mover positioning for rhizobial inoculant seed treatments with established nitrogen fixation credentials.
- Seed Company Channel Integration:Direct-to-seed-company distribution partnerships bypass cooperative markup structures and capture margin pools from vertically integrated canola breeding programs.
- Non-Systemic Chemistry Reformulation:PMRA's clothianidin and thiamethoxam review timeline creates compressed registration windows for contact fungicide and insecticide alternatives with novel modes of action.
Industry Challenges
- Microbial Formulation Stability:Shelf-life degradation of live biological agents during Prairie winter storage conditions requires cold-chain infrastructure investments that strain regional distributor capital allocation.
- PMRA Registration Timeline Compression:Compressed decision windows for neonicotinoid alternatives force simultaneous toxicology, efficacy, and residue package submissions without sequential regulatory feedback.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Seed Treatment Market |
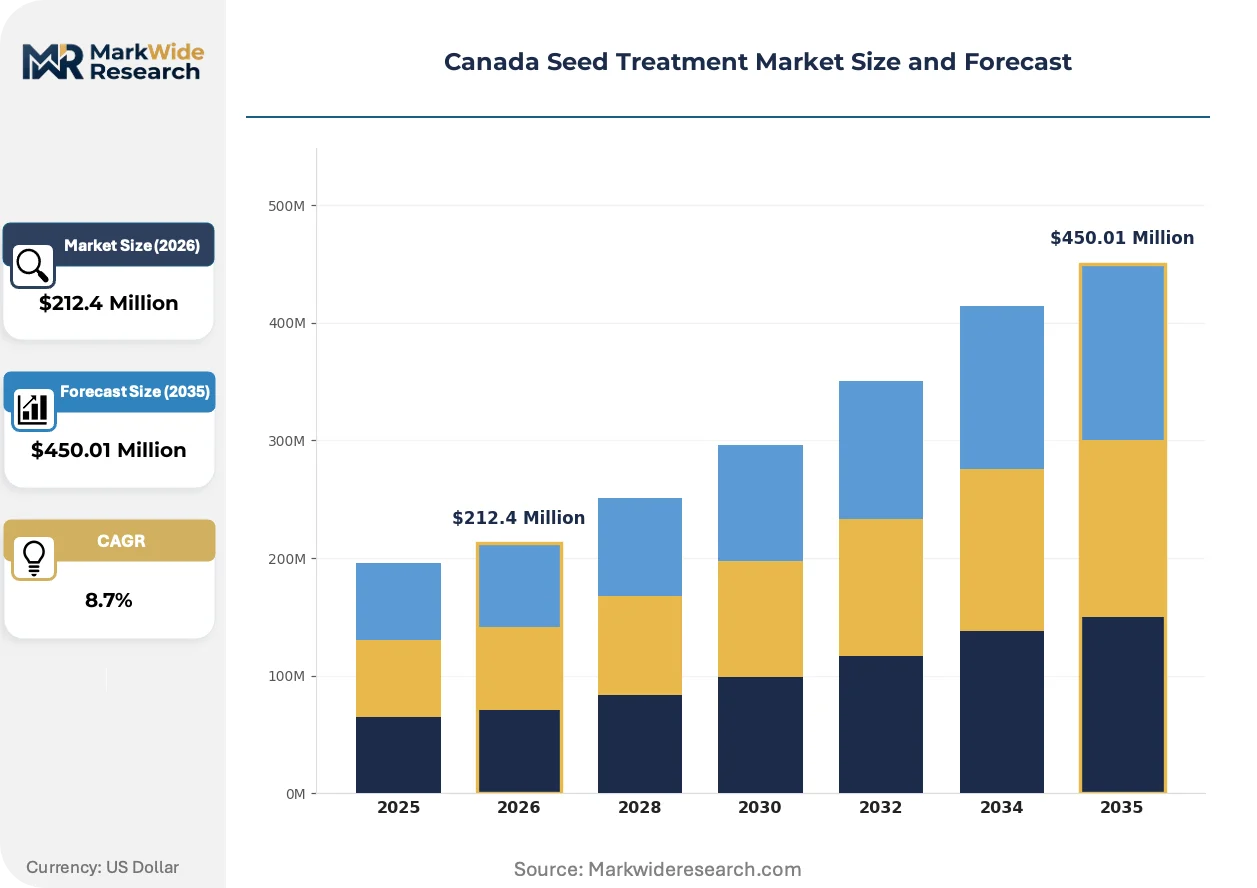
| Market Size in 2026 | $212.4 Million |
| Market Size in 2035 | $450.01 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Treatment, Biological Treatment, Coating, Seed Enhancer Application: Crops, Vegetables, Fruits, Flowers Distribution Channel: Online Retail, Agricultural Stores, Distributors, Wholesalers End User: Farmers, Agricultural Cooperatives, Research Institutions, Seed Companies |
| Companies Covered | BASF SE, Syngenta Group, Bayer CropScience AG, Corteva Agriscience, FMC Corporation, UPL Limited, Nufarm Limited, ADAMA Agricultural Solutions Ltd, Sumitomo Chemical Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Seed Treatment Market Strategic Shifts
Biological efficacy verification standards are restructuring competitive positioning around colony-forming-unit guarantees rather than chemical concentration metrics. This shift is elevating fermentation quality control and field-performance documentation as core differentiators.
Microbial seed treatment technology is bifurcating the Prairie protection market between premium biological formulations with verified CFU counts and residual chemical applications facing regulatory sunset. Large-scale commercial farming operations in Saskatchewan are adopting microbial inoculants at accelerating rates for canola establishment. This adoption pattern is compressing margins on commodity chemical treatments while expanding margin pools for fermentation-controlled biological supply chains.
Health Canada's Pest Control Products Act amendments are accelerating residue limit reviews for systemic insecticides used in cereal production. The industrial consequence is forced reformulation toward contact chemistries and microbial alternatives before the 2025 growing season. Western Canadian formulators are responding by redirecting R&D expenditure toward biological registration packages and non-systemic active ingredient screening.
Seed company procurement consolidation is displacing cooperative distribution channels for treated canola and wheat varieties in the Prairie Provinces. Agricultural input purchasing is concentrating through vertically integrated breeding companies that bundle genetic traits with protective seed coatings. This channel shift is most visible in Alberta, where commercial farm scale enables direct volume contracting with national seed suppliers.
Canada Seed Treatment Market Segmentation
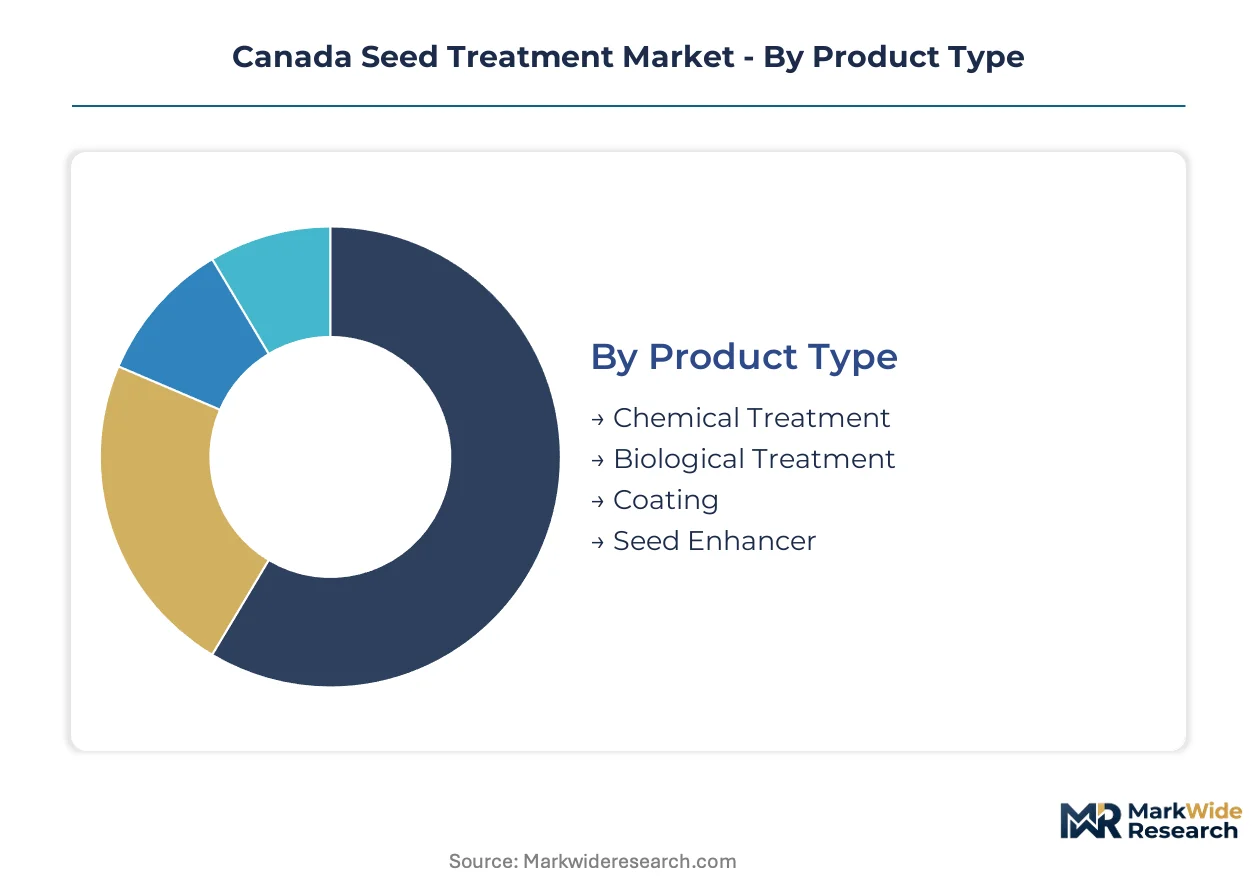
Segmentation in the Canada seed treatment market determines which formulations reach Prairie growers through cooperative bulk procurement versus direct seed company channels. Understanding these pathways clarifies where biological premiums command pricing power and where chemical volumes retain scale economies.
Product Type:
Chemical treatments flow through agricultural cooperatives in Saskatchewan and Manitoba, while biological formulations concentrate in seed company direct contracts with verified CFU guarantees.
- Chemical Treatment:Synthetic fungicides and insecticides—primarily neonicotinoid-based for canola and cereals—deliver broad-spectrum protection through systemic uptake. Demand concentrates in Alberta and Saskatchewan where large-scale wheat operations prioritize cost-per-acre efficiency over residue stewardship.
- Biological Treatment:Microbial inoculants and biofungicides containing Bacillus and Trichoderma species establish rhizosphere colonization for nutrient mobilization and pathogen suppression. Prairie canola growers in Saskatchewan are expanding procurement through seed company channels as PMRA tightens clothianidin and thiamethoxam registration timelines.
- Coating:Polymer-based seed coatings encapsulate active ingredients for controlled release and improved flowability during mechanical planting.
- Seed Enhancer:Nutritional priming agents and plant growth regulators accelerate germination uniformity under variable Prairie spring conditions.
Chemical treatment dominates installed base. Biological treatment is where expansion concentrates.
Application:
Margin structures vary sharply across crop categories, with oilseeds commanding formulation premiums and cereals driving volume throughput.
- Crops:Canola, wheat, and barley represent the core revenue pool, with seed treatments applied at 50-400 milliliters per hundred kilograms depending on pathogen pressure and target pest spectrum.
- Vegetables:High-value potato and onion seed treatments in southwestern Ontario and British Columbia command premium pricing for specialized fungicide complexes.
- Fruits:Vine crops and berry propagation in the Okanagan Valley and Niagara Peninsula utilize niche biological inoculants for soil-borne disease suppression.
- Flowers:Ornamental and turfgrass seed treatments constitute a marginal segment concentrated in greenhouse supply chains.
Crops absorb the majority of formulation volume. Vegetables generate the steepest margin expansion trajectory.
Distribution Channel:
Channel selection directly determines price realization and biological efficacy verification standards for Prairie growers.
- Online Retail:Digital procurement platforms serve small-scale Manitoba and British Columbia growers with packaged biological inoculants and specialty seed coatings.
- Agricultural Stores:Independent retailers in Alberta and Saskatchewan maintain chemical treatment inventories for walk-in farmers requiring immediate spring planting supplies.
- Distributors:Regional agricultural input distributors consolidate biological and chemical formulations for cooperative delivery across Prairie Provinces.
- Wholesalers:Volume aggregators supply treated seed to seed companies and national breeding programs with standardized CFU documentation.
Distributors and agricultural stores retain the bulk of chemical volume. Online retail is gaining share fastest in biological specialty segments.
End User:
Customer scale and procurement sophistication dictate whether seed treatments arrive as commodity formulations or precision biological packages.
- Farmers:Individual Prairie growers purchase through cooperative channels or agricultural stores, with adoption patterns splitting between cost-optimized chemical treatments and stewardship-driven biological alternatives.
- Agricultural Cooperatives:Saskatchewan and Manitoba cooperatives aggregate member demand to secure volume pricing on treated canola and wheat seed, consolidating procurement power across thousands of acres.
- Research Institutions:Universities and federal agriculture research stations in Saskatoon and Lethbridge evaluate novel biological strains and formulation stability under Prairie storage conditions.
- Seed Companies:Vertically integrated breeding operations in Alberta bundle genetic traits with protective coatings, bypassing cooperative markups and capturing margin pools through direct farmer contracting.
Agricultural cooperatives dominate chemical treatment procurement. Seed companies are where biological adoption concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biological seed treatment supply chains concentrate in Saskatoon research corridors and Alberta distribution hubs. Prairie provincial regulations and cooperative procurement patterns reshape where chemical versus biological formulations gain adoption across Canadian agricultural regions.
Prairie Provinces
Large-scale canola and wheat operations in Saskatchewan and Alberta drive volume demand for treated seed. Health Canada and PMRA neonicotinoid re-evaluations accelerate biological adoption timelines for Prairie growers. Saskatoon hosts concentrated microbial fermentation research facilities serving regional biological formulation supply.
Ontario
High-value vegetable seed treatments for potato and onion production command premium pricing in southwestern Ontario. Provincial environmental farm plans mandate pollinator protection buffers that favor biological alternatives. Research institutions in Guelph evaluate novel biological strains under Great Lakes climate conditions.
British Columbia
Okanagan Valley berry propagation and greenhouse ornamental production utilize niche biological inoculants for soil-borne disease suppression. The province's organic certification density exceeds national averages, expanding addressable market for microbial seed treatments. Vancouver distribution channels serve specialty agricultural input demand across the Pacific Northwest.
Manitoba
Agricultural cooperatives in Manitoba consolidate member procurement to secure volume pricing on treated canola and wheat seed. Underpenetrated lentil and pea acreage in southwestern regions offers expansion opportunity for rhizobial inoculant applications. Provincial regulators enforce seed quality standards through Manitoba Agricultural Services Corporation certification protocols.
Quebec
Specialized corn and soybean seed treatment demand concentrates in the St. Lawrence River valley corridor. Provincial agricultural research stations evaluate biological formulation stability under eastern Canadian storage conditions. Montreal-area distributors serve diversified crop protection needs across mixed farming operations.
Canada Seed Treatment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Canada seed treatment market. Consolidated multinational agrochemical conglomerates dominate chemical formulation supply while specialized biological developers capture expanding margin pools. Three strategic archetypes define competitive positioning: integrated breeding-treatment bundlers, fermentation-controlled biological specialists, and broad-spectrum chemical portfolio managers. Dominant competitive moves include seed company channel integration partnerships and accelerated biological registration package submissions under compressed PMRA timelines.
Within the integrated multinational tier, BASF SE, Bayer CropScience AG, and Syngenta Group represent archetypal positioning. BASF SE anchors microbial pipeline development through Saskatoon-based research infrastructure. Bayer CropScience AG exemplifies backward integration into in-house biological production from fermentation through field delivery. Syngenta Group occupies a position navigating PMRA re-evaluation timelines while sustaining broad-spectrum chemical portfolios.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta Group |
| Bayer CropScience AG |
| Corteva Agriscience |
| FMC Corporation |
| UPL Limited |
| Nufarm Limited |
| ADAMA Agricultural Solutions Ltd |
| Sumitomo Chemical Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Biological fermentation inputs displacing neonicotinoid chemistries are simultaneously concentrating Prairie supply geography around Saskatoon research corridors and compressing pricing economics for commodity chemical treatments. This substitution dynamic elevates colony-forming-unit verification costs while eroding margins on legacy systemic formulations.
Pricing Analysis
The Pest Control Products Act dictates the pricing tier structure across the Canada seed treatment market. Three-tier pricing structure across premium, standard, and economy levels separates verified-CFU biological formulations from commodity chemical treatments and uncoated bare seed. Price differentiation stems from certification grade under PMRA registration tiers and volume scale through cooperative procurement aggregation. Pricing pressure stems from tightening maximum residue limits forcing reformulation investments. Agricultural cooperatives in Manitoba exhibit highest price sensitivity, while vertically integrated seed companies in Alberta accept premium positioning for biological guarantees.
Supply Chain Analysis
Saskatoon research corridor concentration anchors microbial fermentation supply for Prairie biological formulations. Domestic production draws from Canadian fermentation infrastructure, US active ingredient imports, and European formulation technology partnerships. Raw material dependencies include microbial culture media, polymer coating substrates, and neonicotinoid technical grade materials. Single-source vulnerability concentrates in Saskatoon-based biological production facilities. Distribution runs through agricultural cooperative networks in Saskatchewan and Manitoba, with seed company direct channels expanding in Alberta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada seed treatment market functions as a defensive-moat story anchored in regulatory entrenchment. PMRA registration timelines create switching costs that protect incumbent formulation portfolios while compressing windows for competitive entry.
For Market Incumbents: Shield market position through backward integration into Saskatoon-based microbial fermentation capacity and accelerated biological registration package submissions ahead of PMRA clothianidin decisions. Channel control through seed company direct partnerships represents the priority defensive lever against cooperative consolidation. Threat substitution from emerging biological specialists demands preemptive CFU verification infrastructure investment. For New Entrants and Emerging Players: Differentiate on Manitoba pulse crop rhizobial inoculant specialization where incumbent coverage remains thin. Southwestern Manitoba lentil and pea acreage offers the most penetrable white-space target for nitrogen fixation credential establishment. Go-to-market execution should prioritize agricultural cooperative channel partnerships over seed company incumbent relationships. For Investors and Strategic Acquirers: The market sits at a regulatory transition phase that favors fermentation-controlled biological specialists with verified supply chain documentation. Long-term viability over the projection horizon rests on PMRA registration portfolio depth rather than chemical volume scale. Acquisition target archetype: Saskatoon-corridor biological developers with established CFU testing protocols. Signal to watch: PMRA final determinations on thiamethoxam seed uses as biological adoption inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Registration Package Submission | Accelerated PMRA timelines for neonicotinoid alternatives compress development windows for microbial formulations. |
| Seed Company Channel Integration | Direct partnerships with Alberta breeding operations bypass cooperative markups and capture margin pools from trait bundling. |
| Backward Integration into Fermentation | In-house microbial production from culture through field delivery controls quality assurance costs under CFU verification standards. |
| Cooperative Procurement Consolidation | Volume aggregation across Saskatchewan and Manitoba member bases secures pricing leverage against national seed suppliers. |
| Non-Systemic Chemistry Reformulation | Novel mode-of-action contact fungicides address PMRA residue limit tightening while retaining chemical cost structures. |
Study Parameters
Operator-level perspectives from seed treatment formulators, agricultural cooperative procurement managers, seed company R&D directors, and PMRA regulatory affairs specialists anchored the qualitative base. Primary interview findings combined with secondary validation from Health Canada registration databases, PMRA re-evaluation dockets, Prairie agricultural services corporation seed quality reports, and cooperative procurement disclosure records. Bottom-up volume estimates from crop-acreage treatment rates triangulated against top-down market value reconstructions.
Sensitivity analysis around PMRA decision timelines and biological adoption curves informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application crop category, distribution channel structure, and end-user procurement sophistication. CAGRs derived from trend extrapolation of treatment rate intensities and pricing trajectory assumptions. Industry-specific forecast inputs incorporated neonicotinoid phase-out scenarios and microbial formulation stability parameters under Prairie storage conditions.
Material uncertainties — PMRA final rulings on clothianidin and thiamethoxam, biological shelf-life degradation rates, and cooperative consolidation patterns — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory trajectory continuity and grower adoption elasticity. Practitioners should keep alternative scenarios live as PMRA decision schedules and pollinator stewardship mandate stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
Seed Storage Systems Market
Seed Technology
Protein Content Optimizing Cereal Fertility Program Market
Seed Technology
Seed Coating Materials Market
Seed Technology
Europe Seed Coating Materials Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
North America Cotton Seed Treatment Market
Seed Technology
India Seed Treatment Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
Seed Coating Ingredients Market
Seed Technology
Mexico Seed Treatment Market
Seed Technology
Asia-Pacific Seed Coating Materials Market
Seed Technology
North America Seed Coating Materials Market
Seed Technology
Seed Additives Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
China Seed Treatment Market