
 North America Cotton Seed Treatment Market | 2026-2036
North America Cotton Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cotton Seed Treatment Market Analytics
Biological seed treatment platforms is reconfiguring how active ingredients are delivered to cotton seedlings, shifting from standalone synthetic chemistries toward integrated biocontrol-synthetic combinations. Syngenta AG leverages its biologicals pipeline to anchor premium positioning in the Texas market. Nufarm Limited sustains cost-competitive manufacturing scale across broadacre row crops. FMC Corporation differentiates through proprietary polymer coating technologies that improve active ingredient adhesion.
Cotton seed treatment encompasses the application of crop protection agents—typically insecticides, fungicides, herbicides, or biological agents—directly onto seed surfaces prior to planting, with coating thicknesses generally ranging from 0.1 to 0.5 millimeters depending on active ingredient loading requirements. The primary purpose is to establish a protective zone around the germinating seed and emerging radicle, reducing early-season pest pressure and pathogen infection during the critical 21-to-45-day establishment window. Insecticides command the largest product type share due to persistent thrips and aphid pressure across southern U.S. cotton belts, while biological agents represent the fastest-expanding category as resistance management protocols and retailer sustainability requirements intensify. Seed coating dominates application method volumes because centralized treaters at gin facilities and seed company processing plants achieve uniformity impossible with on-farm alternatives.
The U.S. EPA and state departments of agriculture in Texas, Mississippi, and Georgia enforce seed treatment labeling and pollinator protection standards that directly influence product registration timelines and buffer zone requirements. The Federal Insecticide, Fungicide, and Rodenticide Act (FIFRA) governs active ingredient approval, while emerging state-level neonicotinoid restrictions in certain jurisdictions are forcing suppliers to diversify chemistries. Stakeholders must monitor regulatory divergence between federal and state frameworks while building biological agent portfolios to preempt compliance-driven demand shifts.
Market Dynamics
The U.S. EPA's pollinator protection mandates are forcing rapid chemistry reformulation across the cotton seed treatment supply chain, compressing registration timelines and accelerating biological agent adoption.
Growth Catalysts
- Thrips pressure in the Mississippi Delta:Persistent early-season insect infestations drive demand for precision-treated seed with extended residual protection.
- Texas High Plains acreage density:Concentrated cotton production justifies capital investment in centralized gin-based seed treatment infrastructure.
- FIFRA registration pathways for biologicals:Streamlined federal approval processes accelerate commercialization of biocontrol-synthetic combination products.
Market Restraints
- Active ingredient cost volatility:Neonicotinoid supply constraints and reformulation costs squeeze margins for established chemistries.
- State-level regulatory fragmentation:Divergent neonicotinoid restrictions across Texas, Mississippi, and Georgia create compliance complexity and inventory segmentation.
- Seed treatment equipment capex:Precision application systems at gin facilities require substantial upfront investment, limiting treater network expansion.
Strategic Opportunities
- Georgia Piedmont expansion:Underpenetrated cotton acreage in southeastern states offers whitespace for biological-first positioning.
- Polymer coating innovation:Advanced adhesion technologies enabling reduced active ingredient loading while maintaining efficacy thresholds.
- Retailer sustainability mandates:Major agricultural retailers imposing biocontrol minimums create guaranteed demand pools for biological suppliers.
Industry Challenges
- Seed treatment applicator certification:State-mandated licensing requirements create bottlenecks in workforce scaling across the southern cotton belt.
- Legacy equipment integration:Older gin facilities face technical friction retrofitting precision coating systems without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cotton Seed Treatment Market |
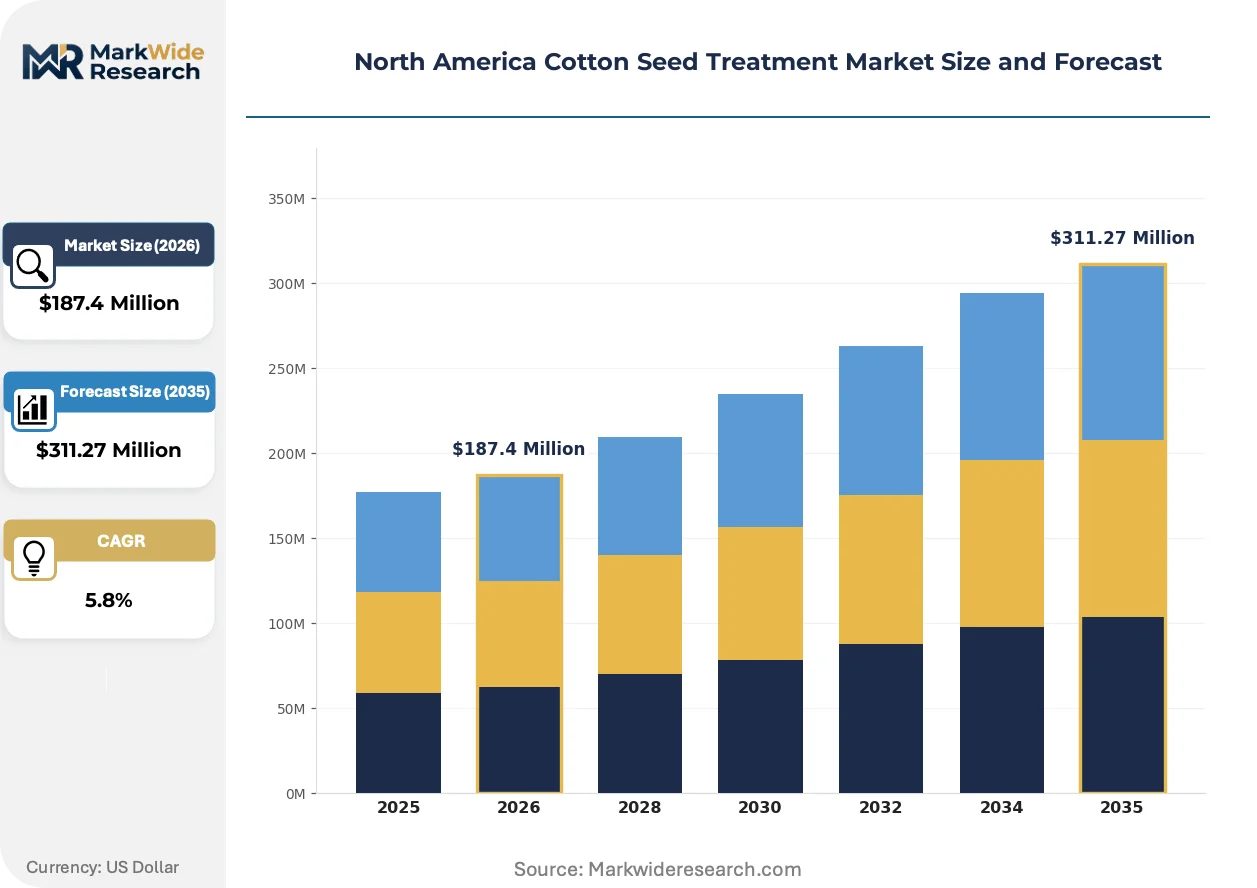
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticides, Fungicides, Herbicides, Biological Agents Application Method: Seed Coating, Soil Treatment, Drip Irrigation, Foliar Spray End User: Farmers, Agricultural Cooperatives, Seed Companies, Retailers Distribution Channel: Online Retail, Agricultural Stores, Direct Sales, Distributors |
| Companies Covered | Syngenta AG, Nufarm Limited, FMC Corporation, Adama Agriculture Solutions, Albaugh LLC, Corteva Agriscience, BASF SE, UPL Limited, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cotton Seed Treatment Market Evolving Landscape
Biological-synthetic integration is restructuring product development priorities, with coating technologies and regulatory compliance protocols emerging as decisive competitive differentiators.
Microencapsulated biological agents with extended viability windows are rendering obsolete conventional standalone synthetic chemistries in premium seed treatment tiers. Commercial cotton growers in the Mississippi Delta are adopting these platforms at accelerated rates. The technology is compressing the efficacy gap between biological and synthetic options while satisfying retailer sustainability requirements.
The U.S. EPA's evolving pollinator protection mandates under FIFRA are forcing active ingredient diversification across neonicotinoid-dependent product lines. Registration timelines for novel chemistries have compressed as biological pathways gain priority review status. Texas-based formulators are responding by building biocontrol agent portfolios ahead of anticipated state-level neonicotinoid restrictions.
Centralized procurement through gin facility treaters is displacing on-farm seed treatment applications across the Texas High Plains. Large-scale commercial operations now specify treatment specifications at origin rather than handling chemicals directly. This concentration is most visible in the Lubbock-Plainview corridor, where three gin cooperatives process the majority of regional seed volume.
North America Cotton Seed Treatment Market Segmentation
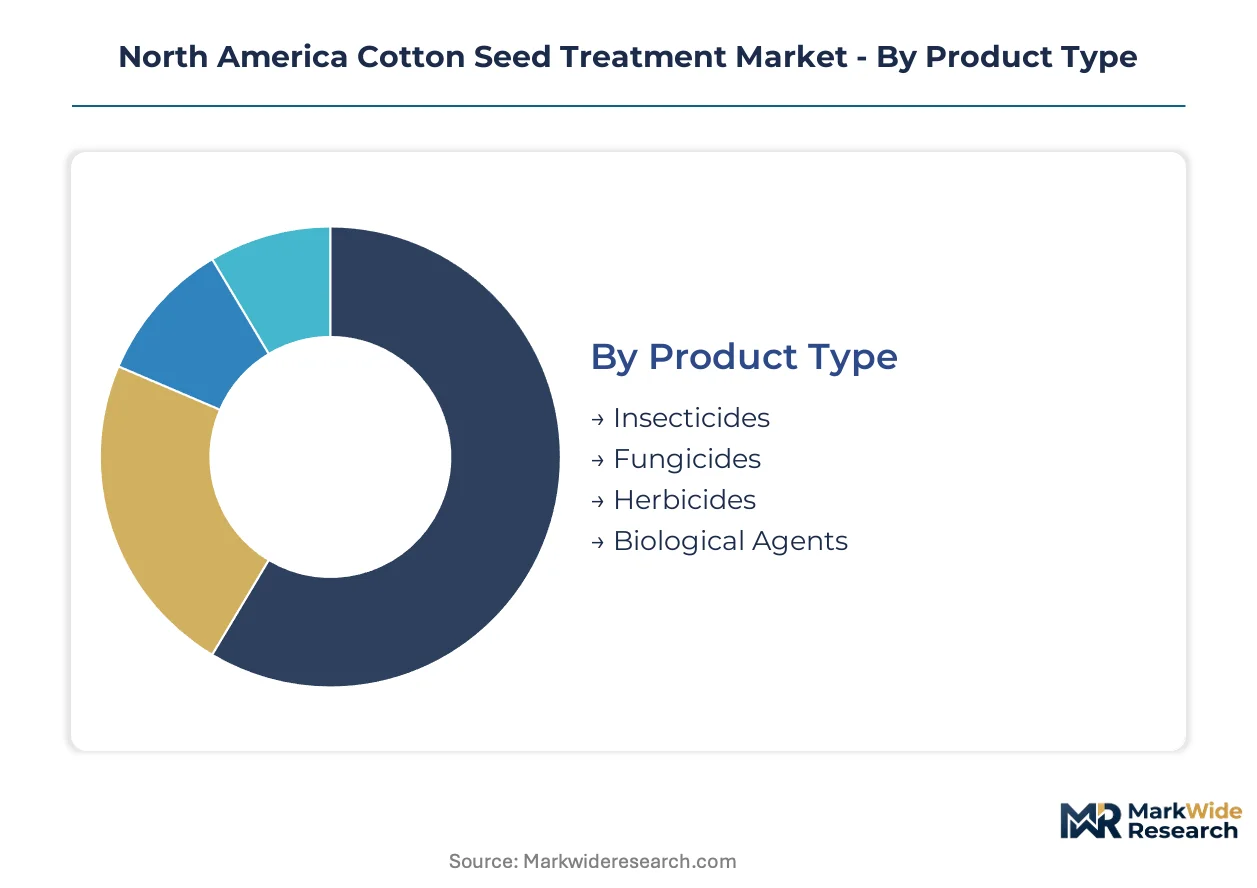
Segmentation in cotton seed treatment determines how suppliers allocate technical service resources, as precision application systems require sustained field support. Product formulation complexity and application method sophistication drive divergent margin structures across customer tiers.
Product Type:
After-sales service intensity varies sharply across chemistry classes, with biological agents demanding intensive grower education and residue monitoring support.
- Insecticides:Synthetic pyrethroids and neonicotinoids form the backbone of thrips and aphid management programs, with coating formulations optimized for 21-to-45-day residual windows. Mississippi Delta commercial growers specify these treatments at origin through gin-based centralized treaters to ensure uniformity. EPA pollinator protection mandates are compressing registration timelines and forcing active ingredient diversification.
- Biological Agents:Microencapsulated biocontrol platforms integrate with synthetic chemistries to satisfy retailer sustainability minimums, requiring cold-chain handling and viability monitoring. Texas High Plains acreage concentration justifies dedicated technical service teams for these premium-tier products. FIFRA streamlined pathways accelerate commercialization.
- Fungicides:Triazole and strobilurin-based seed treatments target Pythium and Rhizoctonia seedling disease complexes.
- Herbicides:Safener-enhanced formulations protect emerging cotton from early-season weed competition.
By volume, insecticides lead. By growth pace, biological agents are climbing the fastest.
Application Method:
Cost tier separation distinguishes capital-intensive centralized systems from labor-dependent on-farm alternatives.
- Seed Coating:Precision polymer-based application at gin facilities achieves 0.1-to-0.5 millimeter coating uniformity impossible with farmer-operated equipment. Texas High Plains cooperatives in the Lubbock-Plainview corridor anchor regional infrastructure investment. Centralized procurement displaces on-farm chemical handling.
- Soil Treatment:In-furrow liquid applications at planting require calibrated equipment and certified applicator licensing.
- Drip Irrigation:Chemigation delivery suits high-value specialty cotton systems with existing micro-irrigation infrastructure.
- Foliar Spray:Post-emergence rescue treatments address gaps in seed-applied protection.
Seed coating dominates volume. Biological-synthetic integration is gaining share fastest in premium coating tiers.
End User:
Customer type dictates pricing architecture, with seed companies capturing formulation premiums and farmers absorbing treatment costs through seed premiums.
- Seed Companies:Integrated breeding-treatment operations specify active ingredient loadings and polymer specifications at origin, controlling quality consistency. Mississippi Delta and Texas High Plains gin partnerships concentrate procurement power. Biological agent portfolios differentiate premium positioning.
- Farmers:Commercial cotton growers in Georgia Piedmont and southeastern expansion zones specify treatment packages through retailer channels.
- Agricultural Cooperatives:Gin-based treater networks aggregate volume for chemistry negotiation leverage.
- Retailers:Sustainability mandate enforcement creates guaranteed demand pools for biocontrol suppliers.
Seed companies lead by procurement volume. Retailer sustainability requirements are expanding fastest as demand drivers.
Distribution Channel:
Supply concentration shapes channel profitability, with direct sales capturing formulation premiums and distributors managing inventory segmentation complexity.
- Direct Sales:Seed company and gin-treater relationships bypass intermediaries for high-volume chemistry procurement. State-level neonicotinoid restriction divergence forces inventory segmentation expertise.
- Distributors:Regional chemical wholesalers manage compliance complexity across Texas, Mississippi, and Georgia regulatory frameworks.
- Agricultural Stores:Local input retailers serve smaller-scale Georgia Piedmont and southeastern cotton operations.
- Online Retail:Digital platforms capture replacement chemistry and equipment parts demand.
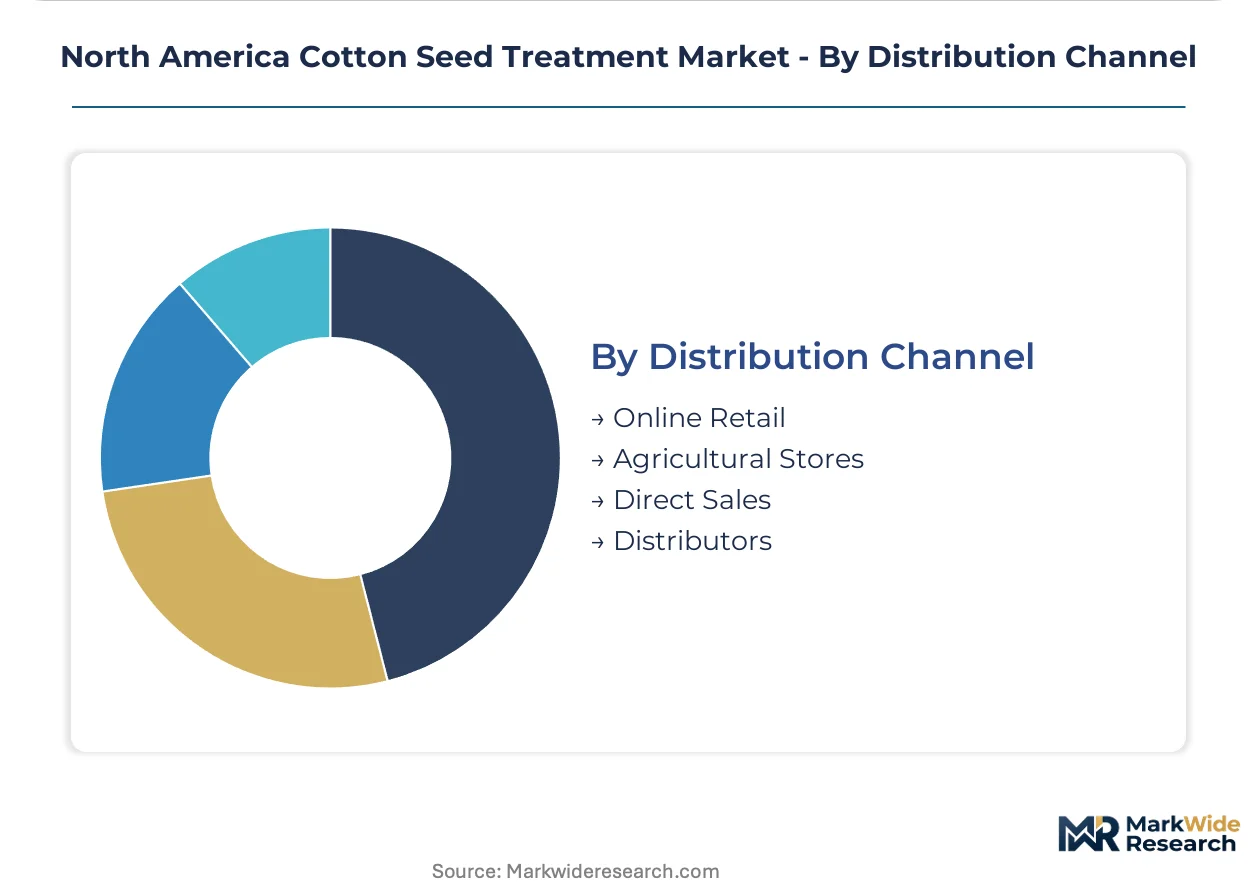
Direct sales dominate volume. Distributor networks are expanding fastest to manage regulatory fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States cotton seed treatment exports flow primarily to Mexican textile processors and Central American garment manufacturers, establishing a north-south trade corridor that shapes regional capacity planning.
United States
Texas High Plains gin cooperatives concentrate centralized seed treatment infrastructure, processing the majority of domestic cotton seed volume. EPA pollinator protection mandates under FIFRA accelerate biological agent registration pathways. The Lubbock-Plainview corridor anchors national supply, with three gin cooperatives handling precision polymer coating operations.
Canada
Canadian prairie cotton trials in southern Ontario and Manitoba drive limited biological seed treatment demand for research plots and specialty fiber programs. Health Canada's PMRA enforces residue standards aligned with EPA frameworks but with extended buffer zone requirements. Winnipeg-based agricultural distributors manage cross-border chemistry procurement for research institutions.
Mexico
Mexican cotton expansion in Sinaloa and Tamaulipas generates import demand for U.S.-formulated seed treatments, particularly neonicotinoid-based thrips management. Mexico's national agricultural regulator, SENASICA, coordinates phytosanitary certification with USDA APHIS for seed treatment residue protocols. The Culiacán Valley cluster concentrates gin infrastructure investment from domestic and U.S. seed companies.
North America Cotton Seed Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a moderately consolidated structure where seed company partnerships determine volume allocation. Three archetypes dominate: integrated agrochemical-seed conglomerates with breeding-treatment integration, standalone formulation specialists with cost-optimized manufacturing scale, and biological platform developers with premium sustainability positioning. M&A activity concentrates on biocontrol pipeline acquisition, while strategic partnerships between gin cooperatives and formulators lock in regional supply security.
Within the integrated conglomerate tier, Syngenta AG and Bayer AG exemplify breeding-treatment integration models that capture formulation premiums through seed company procurement channels. BASF SE occupies a position bridging synthetic and biological portfolios, reflecting the chemistry diversification imperative driven by EPA regulatory pressure. These three anchors represent distinct strategic responses to pollinator protection mandates: biological pipeline depth, polymer coating technology leverage, and scale-driven cost optimization.
| Leading Market Players |
|---|
| Syngenta AG |
| Nufarm Limited |
| FMC Corporation |
| Adama Agriculture Solutions |
| Albaugh LLC |
| Corteva Agriscience |
| BASF SE |
| UPL Limited |
| Bayer AG |
| Others |
Value Network & Pricing Analysis
The Lubbock-Plainview corridor's gin cooperative concentration shapes downstream pricing power through volume aggregation and chemistry procurement leverage. Three processing facilities anchor North American seed treatment capacity, enabling coordinated input purchasing that compresses margins for standalone formulators while securing supply security for integrated seed companies.
Pricing Analysis
Next-generation biological-synthetic combination platforms command substantial premiums over conventional neonicotinoid-based formulations, while economy-tier standalone synthetics face persistent cost compression. Pricing stratifies across premium, standard, and economy tiers based on polymer coating sophistication and active ingredient loading specifications. Price erosion runs through economy-tier synthetics as EPA pollinator protection mandates force reformulation investments. Commercial cotton growers in the Mississippi Delta exhibit lowest price sensitivity due to thrips-driven yield protection economics, while Georgia Piedmont expansion acreage demonstrates highest sensitivity to per-seed treatment premiums.
Supply Chain Analysis
Extended payment terms from Texas-based gin cooperatives to formulators stretch working capital requirements across the supplier base, concentrating financial risk with mid-tier standalone manufacturers. Active ingredient supply draws from China, India, and domestic U.S. synthesis facilities for pyrethroids and biological fermentation substrates. Neonicotinoid regulatory fragmentation across Texas, Mississippi, and Georgia creates inventory segmentation complexity and compliance-driven supply chain risk. Distribution runs through direct seed company procurement channels and regional agricultural chemical distributors managing state-level restriction divergence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America cotton seed treatment market sits in cyclical recovery as EPA regulatory pressure forces chemistry refresh cycles and biological pipeline investments accelerate replacement demand.
For Market Incumbents: Build regulatory compliance moats through biological agent portfolio depth ahead of anticipated state-level neonicotinoid restrictions. Secure exclusive gin-treater partnerships in the Texas High Plains to lock in volume allocation, while investing in cold-chain handling infrastructure for microencapsulated biocontrol platforms that emerging biological specialists cannot replicate at scale. For New Entrants and Emerging Players: Establish a beachhead in Georgia Piedmont underpenetrated acreage through biological-first positioning that satisfies retailer sustainability minimums without competing directly against entrenched Texas infrastructure. Target certified applicator training services as a differentiated entry point, leveraging workforce bottleneck pain points that incumbent technical service teams cannot address across dispersed southeastern expansion zones. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory transition play because EPA pollinator protection mandates and state-level restriction divergence create sustained chemistry refresh demand regardless of cotton commodity price cycles. Acquisition targets should emphasize biological fermentation capacity and polymer coating technology IP rather than standalone synthetic formulation assets. Watch FIFRA registration priority status for biocontrol-synthetic combinations as the signal for inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Pipeline Acquisition | Secures EPA-compliant chemistry alternatives ahead of neonicotinoid restriction expansion across southern states. |
| Gin-Treater Partnership Lock-In | Concentrates volume allocation through exclusive supply agreements with Lubbock-Plainview corridor cooperatives. |
| Polymer Coating R&D Investment | Enables reduced active ingredient loading while maintaining thrips protection thresholds for cost-sensitive growers. |
| Certified Applicator Training Program | Addresses state-mandated licensing bottlenecks that constrain treater network expansion across the cotton belt. |
| Georgia Piedmont Distribution Buildout | Captures whitespace biological-first demand from southeastern cotton expansion acreage seeking sustainability certification. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA registration databases, FIFRA filing records, and state department of agriculture regulatory notices to validate market sizing and chemistry transition timelines. Primary interviews covered seed company breeding directors, gin cooperative operations managers, certified seed treatment applicators, and agricultural retailer sustainability officers. Secondary sources included USDA cotton acreage reports, U.S. Customs treatment chemistry import data, and SEC filings from publicly traded agrochemical firms. Bottom-up volume estimates from gin facility processing capacity triangulated against top-down seed treatment expenditure flows.
Forecast inputs incorporate active ingredient registration status transitions, biological agent commercialization trajectories, and cotton acreage elasticity to commodity price movements across the analysis window. Segmentation modeling spans product type chemistry classes, application method infrastructure tiers, end user procurement channels, and regional regulatory framework clusters. CAGRs derive from regression analysis of historical treatment penetration rates against projected acreage shifts and chemistry substitution elasticities. Industry-specific inputs include EPA pollinator protection mandate implementation timelines and state-level neonicotinoid restriction legislative tracking.
Sensitivities concentrate around EPA registration priority shifts for biological pathways, state legislative divergence on neonicotinoid buffer zones, and cotton commodity price volatility affecting grower treatment premium willingness. Forecasts reflect assumptions on regulatory implementation pace and biological efficacy convergence with synthetic benchmarks. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
India Seed Treatment Market
Seed Technology
Seed Additives Market
Seed Technology
China Seed Treatment Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
Seed Coating Ingredients Market
Seed Technology
France Seed Treatment Market
Seed Technology
Seed Treatment Market
Seed Technology
Seed Storage Systems Market
Seed Technology
Seed Coating Materials Market
Seed Technology
Europe Seed Coating Materials Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
Mexico Seed Treatment Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
North America Seed Coating Materials Market
Seed Technology
Seed Quality Imaging and Germination Prediction Test Systems Market