
 Seed Additives Market | 2026-2036
Seed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Additives Market Analytics
Subscription-based agronomic advisory bundled with seed treatment formulations is pivoting how growers procure additive packages. BASF SE leverages its global formulation network to sustain leadership in fungicide-based coatings. Bayer AG anchors its position through integrated seed-and-trait systems that compete across multiple crop categories. Corteva Agriscience differentiates via biological inoculant portfolios that extend beyond conventional chemistry.
Seed additives comprise chemical and biological formulations applied to seed surfaces to enhance germination, protect against soil-borne pathogens, and improve stress tolerance, typically involving active ingredients at concentrations between 0.1% and 5% by seed weight. These treatments serve commercial agriculture by reducing early-season crop losses and enabling precision placement of crop protection inputs. Pesticide coatings dominate current volume due to established efficacy against fungal and insect threats, while inoculant segments occupy faster-expanding niches as nitrogen-fixing biologicals gain farmer acceptance. Growth regulator applications lead margin pools in high-value vegetable and fruit crop segments where uniform emergence commands premium pricing.
The EPA regulates treated seed as a pesticide-fertilizer hybrid under FIFRA, requiring rigorous residue and environmental fate testing before market entry. The EU Green Deal and REACH frameworks restrict certain neonicotinoid chemistries, redirecting R&D toward biological alternatives and low-dose formulations. Brazil's national agricultural regulator enforces strict import tolerances that shape which additive chemistries gain access to Latin America's largest soybean market. Stakeholders must monitor evolving residue thresholds and biological registration pathways to anticipate which formulation platforms will retain market access across major producing regions.
Market Dynamics
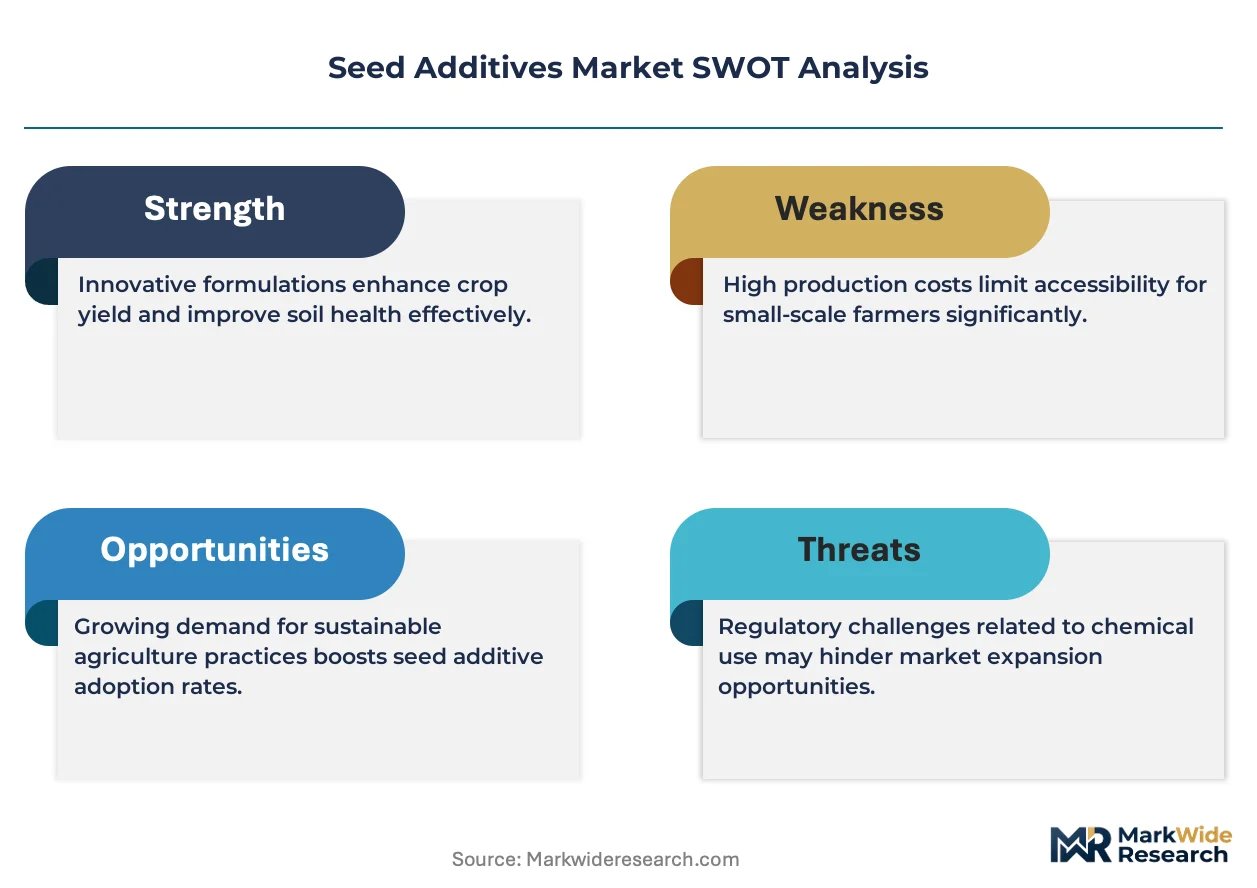
The EU F-Gas Regulation and REACH frameworks are compressing chemical coating tolerances while Brazil's soybean belt and North American corn regions pull biological alternatives into commercial scale. This regulatory-demand tension is restructuring formulation R&D priorities and supplier access rules across major agricultural markets.
Growth Catalysts
- Biological inoculant efficacy:Nitrogen-fixing microbial coatings now match early-season protection from synthetic chemistries in Brazilian soybean trials. Farmer acceptance is accelerating as yield data accumulates across multiple growing seasons.
- EU Green Deal compliance mandates:The European Commission's Farm to Fork strategy imposes binding pesticide reduction targets that redirect procurement toward low-dose and biological seed treatments. Member state enforcement timelines compress supplier transition windows.
- Precision planting equipment penetration:High-speed seeders with individual-row monitoring require uniform seed flow that treated seed coatings enable. Equipment manufacturers in the US Corn Belt now specify treated seed compatibility in new machine specifications.
Market Restraints
- Active ingredient cost volatility:Neonicotinoid chemistry supply concentrates among Chinese intermediate producers, exposing formulators to input price swings and import disruption risks.
- Biological formulation stability:Microbial inoculants face shelf-life limitations of 6-12 months that constrain distribution radius and inventory management flexibility.
- REACH registration complexity:The European Chemicals Agency's substance evaluation processes extend lead times for new active ingredient approvals, freezing some suppliers out of EU market access for 3-5 year windows.
Strategic Opportunities
- Underpenetrated African commercial farming:South African maize operations and emerging commercial sectors in Zambia and Kenya lack established seed treatment supply chains, creating first-mover positioning for biological-focused entrants.
- Carbon credit-linked biological adoption:The EU Carbon Border Adjustment Mechanism creates indirect incentives for nitrogen-fixing inoculants that reduce synthetic fertilizer downstream emissions. Verification protocols are aligning with seed treatment application data.
- Drone-based seed treatment application:Aerial application systems bypass centralized treatment infrastructure, enabling on-farm biological inoculation timing that matches soil temperature and moisture conditions precisely.
Industry Challenges
- Microbiologist formulation talent scarcity:Biological seed additive development requires dual expertise in microbial physiology and seed coating engineering that few technical training programs currently produce.
- Multi-jurisdiction residue testing:Brazil's ANVISA, the US EPA, and EU EFSA maintain non-harmonized maximum residue limits that force redundant field trial programs for global product launches.
- Legacy equipment incompatibility:Existing seed treaters designed for chemical slurries require retrofit investment to handle living biological suspensions without viability loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Additives Market |
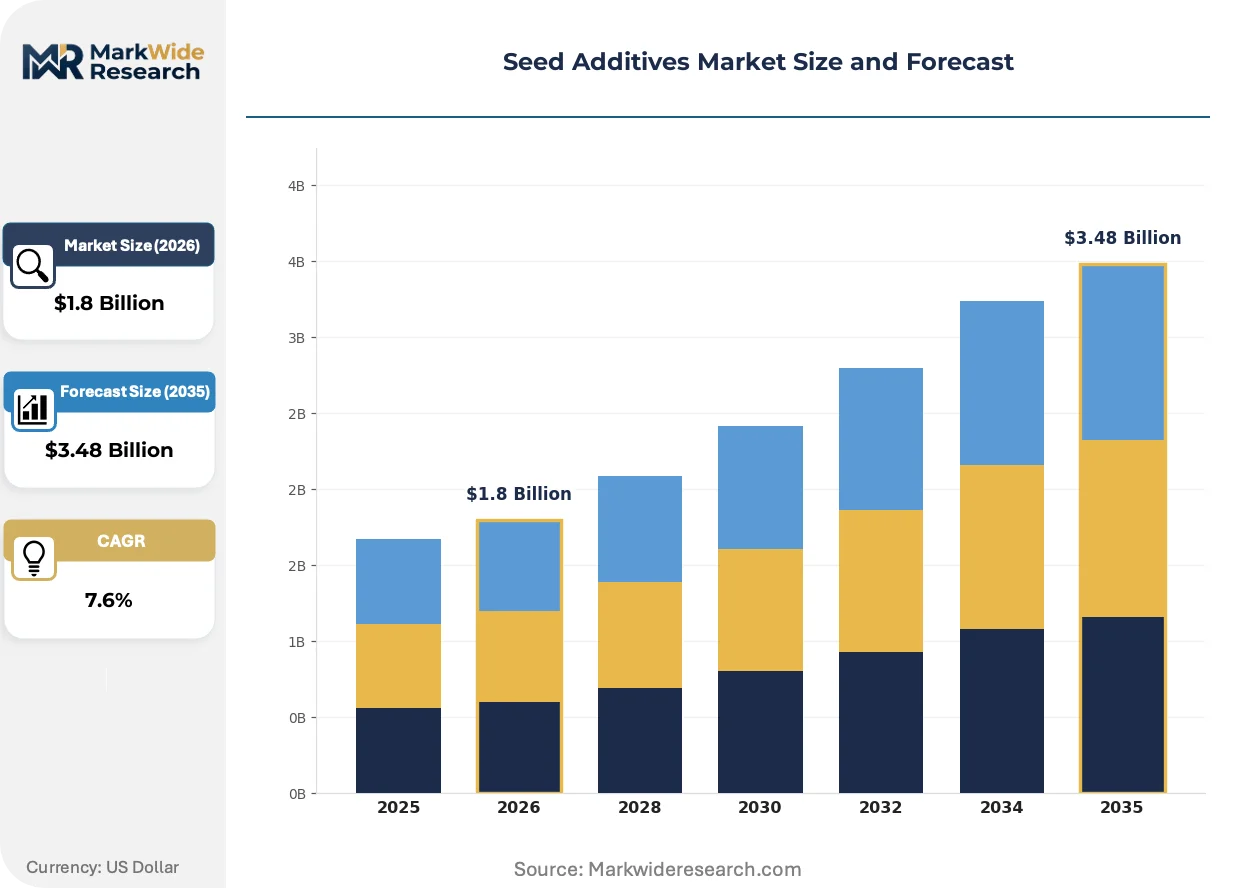
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pesticides, Fungicides, Growth Regulators, Inoculants Application: Agronomic Crops, Turf & Ornamental, Vegetable Crops, Fruit Crops End Use Industry: Agriculture, Horticulture, Greenhouse, Organic Farming Packaging Type: Bags, Drums, Bulk Containers, Sachets |
| Companies Covered | BASF SE, Bayer AG, Corteva Agriscience, Syngenta, Croda International, Clariant, UPL, FMC, Nufarm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Additives Market Evolving Landscape
Formulation science is converging with digital agriculture infrastructure, reshaping how active ingredients are selected, applied, and verified across commercial farming operations. Three distinct vectors are restructuring competitive positioning in seed additive supply.
RNA-interference seed coatings targeting specific fungal pathogens are electrifying the crop protection pipeline. Large-scale row crop operators in the US Midwest are piloting these precision biocides to reduce broad-spectrum chemical loads. The technology is electrifying R&D allocation toward nucleic acid delivery systems that penetrate seed coat barriers without germination inhibition.
The EU F-Gas Regulation's phase-down schedule for fluorinated greenhouse gases is redirecting film-coating polymer choices. Formulators must abandon certain moisture-barrier chemistries by 2030, compressing the development timeline for bio-based coating alternatives. Vegetable seed producers in Spain and Italy face the most acute substitution pressure due to their reliance on extended shelf-life packaging.
Subscription agronomic advisory bundled with seed treatment procurement is displacing transactional chemical purchasing. Brazilian soybean cooperatives now contract season-long technical support alongside biological inoculant packages. This bundling is most advanced in Mato Grosso, where integrated service contracts now cover 15-20% of treated soybean acreage.
Seed Additives Market Segmentation
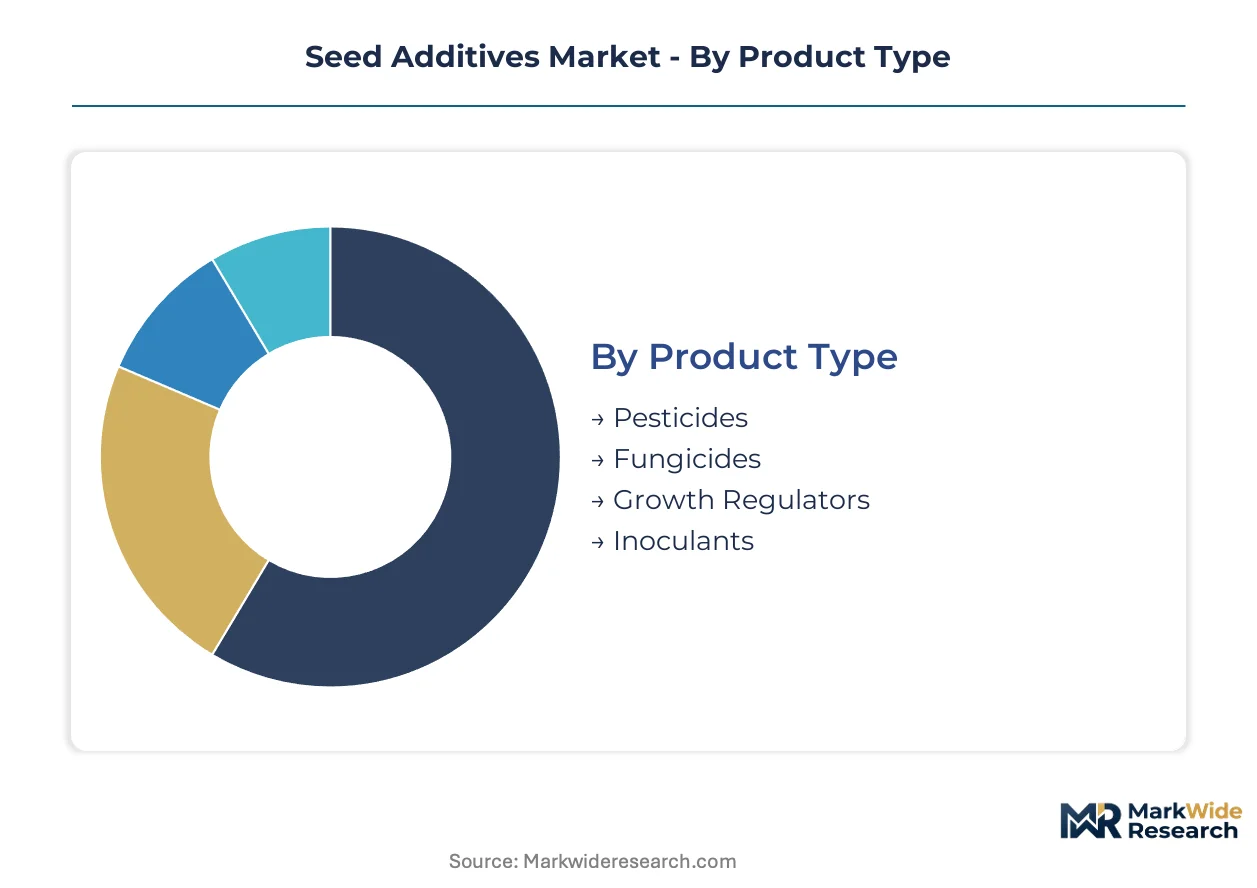
Segmentation in seed additives reveals how formulation chemistry, crop specificity, and distribution infrastructure intersect to determine supplier profitability. Each dimension exposes distinct margin structures and regulatory exposure profiles that shape competitive positioning.
Product Type:
Standalone chemical coatings dominate commercial agriculture, while biological inoculants increasingly embed into integrated crop management systems rather than pure product sales.
- Pesticides:Neonicotinoid and pyrethroid-based coatings protect germinating seed against soil-dwelling insects and early-season foliar pests. Demand concentrates in Iowa and Illinois corn operations where wireworm and seedcorn maggot pressure justifies treatment costs. EPA FIFRA registration requirements create multi-year barriers to new active ingredient entry.
- Fungicides:Triazole and strobilurin chemistries form protective barriers against Pythium, Rhizoctonia, and Fusarium pathogens. Brazilian soybean growers in Mato Grosso and Paraná drive volume as tropical soil conditions elevate disease pressure. EU REACH restrictions on certain azole fungicides are redirecting R&D toward biological alternatives.
- Growth Regulators:Gibberellin and cytokinin formulations synchronize emergence timing in high-value vegetable production.
- Inoculants:Bradyrhizobium and Rhizobium nitrogen-fixing bacteria reduce synthetic fertilizer dependency in legume cropping systems.
Pesticide coatings lead volumes today; inoculants are gaining share fastest.
Application:
Cost tiering separates commodity row crop treatments from premium vegetable and fruit formulations where performance guarantees command price multiples.
- Agronomic Crops:Corn, soybean, wheat, and rice seed treatments constitute the volume base, with formulations optimized for high-speed planting equipment compatibility. North American corn belt operations and Brazilian Cerrado expansion zones anchor demand. Precision agriculture adoption is elevating requirements for uniform coating thickness and flowability.
- Vegetable Crops:Brassica, solanaceous, and cucurbit seed treatments demand exacting germination uniformity that justifies premium pricing. Spanish protected horticulture in Almería and Italian tomato seed producers drive specification intensity. EU F-Gas Regulation compliance pressures are accelerating bio-based coating polymer substitution.
- Turf & Ornamental:Golf course and landscape applications emphasize aesthetic uniformity over yield maximization.
- Fruit Crops:Strawberry, melon, and tree fruit nursery stock requires specialized pathogen protection during extended propagation cycles.
Agronomic crops anchor revenue today; vegetable crop applications expand most quickly.
End Use Industry:
Customer maturity varies sharply between conventional agriculture's established procurement channels and organic farming's emerging certification requirements.
- Agriculture:Commercial field crop operations purchase seed treatments through dealer networks and cooperative procurement systems. US Corn Belt and Brazilian soybean belt distribution infrastructure concentrates supplier access. Carbon credit verification protocols are beginning to influence biological inoculant selection criteria.
- Organic Farming:Certified organic operations restrict allowable inputs to OMRI-listed biologicals and natural origin coatings. California Central Valley vegetable growers and Midwest organic corn producers drive specification development. Supply chain traceability requirements exceed conventional agriculture standards.
- Horticulture:Nursery and floriculture operations prioritize disease-free propagation material.
- Greenhouse:Controlled environment agriculture demands pathogen-free seed with zero tolerance for chemical residue.
Conventional agriculture generates dominant volumes; organic farming climbs the fastest.
Packaging Type:
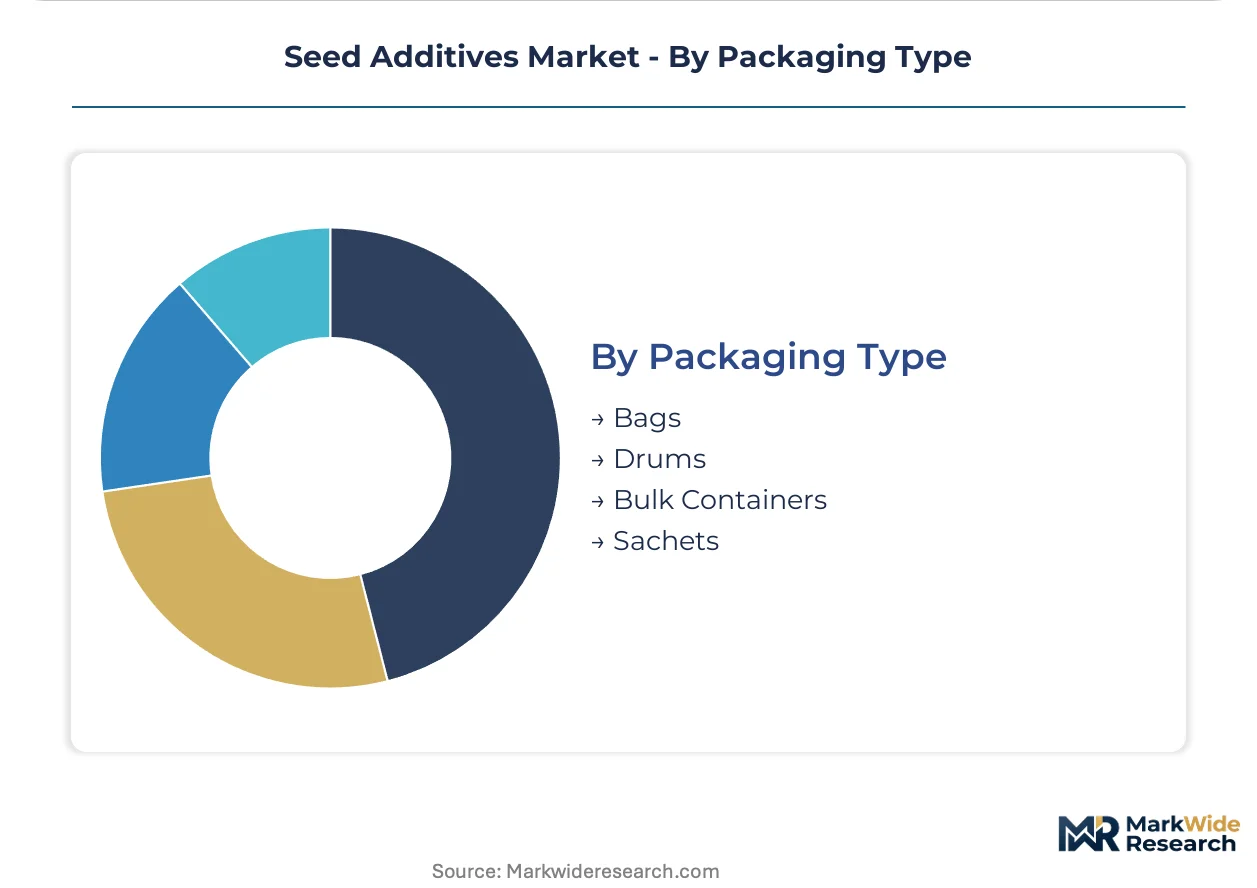
Supply concentration in bulk logistics versus decentralized sachet distribution reflects crop scale and treatment timing flexibility requirements.
- Bulk Containers:Tote and tank systems serve large-scale seed treaters at cooperative and processor facilities. Brazilian Mato Grosso grain elevators and US Midwest seed company central treatment plants anchor demand. Just-in-time biological inoculant delivery requirements are pressuring inventory turnover speeds.
- Bags:Multi-wall paper and woven polypropylene packages dominate retail-scale seed treatment product distribution.
- Drums:Steel and plastic drum formats serve mid-volume formulators and regional seed treatment operations.
- Sachets:Unit-dose packaging enables on-farm biological inoculation timing precision for smallholder and specialty crop applications.
Bulk containers lead volumes today; sachets are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's soybean belt generates treatment volumes that rival North American corn operations, while European regulatory stringency forces faster formulation transitions than in other producing regions.
United States
Iowa and Illinois corn growers drive neonicotinoid coating demand to combat wireworm pressure. EPA FIFRA registration requirements extend lead times for new active ingredients. Precision planting equipment manufacturers in the US Corn Belt now specify treated seed compatibility as standard.
Brazil
Mato Grosso and Paraná soybean operations anchor Latin American biological inoculant adoption. ANVISA enforces strict import tolerances that filter which chemistries enter the market. Brazilian cooperatives in the Cerrado expansion zone now bundle subscription advisory with biological packages.
Germany
EU Green Deal pesticide reduction targets redirect procurement toward low-dose biological alternatives. ECHA REACH substance evaluation processes extend approval timelines for conventional chemistries. Formulation R&D clusters in Ludwigshafen and Leverkusen accelerate bio-based coating polymer development.
China
Domestic neonicotinoid intermediate production concentrates supply leverage for global formulators. The Ministry of Ecology and Environment tightens environmental fate testing for export-bound treatments. Shandong and Jiangsu chemical manufacturing hubs supply active ingredients to Brazilian and North American markets.
India
Punjab and Haryana wheat operations expand treated seed penetration amid rising commercial farming consolidation. The Central Insecticides Board regulates residue thresholds that shape import decisions. Maharashtra soybean growers pilot Bradyrhizobium inoculants as synthetic fertilizer prices fluctuate.
Seed Additives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated agrochemical conglomerates commanding formulation scale while regional treaters retain proximity to farmgate decisions. Market structure tilts toward consolidation at the active ingredient level and fragmentation at the application service tier. Three archetypes dominate: multinational integrated seed-and-trait systems, standalone formulation specialists, and biological-focused entrants. Competitive moves concentrate on portfolio diversification into biologicals and strategic partnerships with precision equipment manufacturers.
Within the integrated systems tier, BASF SE and Bayer AG exemplify scale-driven positioning that spans multiple crop categories and geographic markets. Corteva Agriscience occupies a distinct position through biological inoculant portfolios that extend beyond conventional chemistry. These three entities anchor the competitive map by representing divergent R&D allocation strategies—chemical formulation networks, seed-and-trait integration, and biological specialization—each responding differently to EU regulatory compression and Brazilian biological adoption curves.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| Syngenta |
| Croda International |
| Clariant |
| UPL |
| FMC |
| Nufarm |
| Others |
Value Network & Pricing Analysis
Neonicotinoid intermediate price volatility in Shandong and Jiangsu chemical hubs cascades through formulation tiers, compressing margins for commodity pesticide coatings while biological inoculant premiums hold firm against input cost swings.
Pricing Analysis
Capacity additions in Chinese active ingredient manufacturing are reshaping price floors for synthetic chemistries, yet biological formulations maintain premium positioning due to microbial strain patent scarcity. Three-tier pricing structure across premium biological inoculants, standard fungicide coatings, and economy generic pesticides separates customer segments by certification requirements and after-sales advisory bundling. Cost compression in neonicotinoid-based tiers is intensifying because Brazilian ANVISA residue thresholds now demand redundant field testing. Smallholder cooperatives in India's Maharashtra state exhibit highest price sensitivity, while Mato Grosso commercial operators prioritize yield guarantees over unit cost.
Supply Chain Analysis
REACH registration and EPA FIFRA compliance certification gates access for European and North American markets, filtering supplier participation before volume economics apply. Concentration in Chinese intermediate production, German formulation R&D clusters, and Brazilian distribution cooperatives creates geographic interdependence. Raw material flows draw from Shandong neonicotinoid precursors, Ludwigshafen polymer film coatings, and domestic Brazilian microbial culture banks. Single-source vulnerability concentrates in Chinese intermediate supply for synthetic chemistries. Distribution runs through cooperative procurement systems in the US Corn Belt and Mato Grosso, with sachet retail channels penetrating Indian smallholder markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU Green Deal compliance costs in Germany and France exceed Brazilian regulatory burden by multiples, creating margin capture opportunities for biological-focused suppliers with Latin American manufacturing footprints.
For Market Incumbents: Deploy backward integration into microbial strain libraries to defend against biological-specialist entrants. Consolidate dealer network control in Iowa and Illinois to lock out fungicide coating competitors. Anchor R&D allocation in RNA-interference delivery systems before regulatory compression eliminates conventional chemistries from EU access. For New Entrants and Emerging Players: Direct-to-farm digital advisory platforms bypass incumbent dealer infrastructure in underpenetrated African commercial farming zones. Target South African maize operations and Zambian emerging commercial sectors where seed treatment supply chains remain undeveloped. Lead with drone-based biological inoculation services that match application timing to soil conditions, avoiding centralized treater capital requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with biological formulation specialists possessing dual expertise in microbial physiology and seed coating engineering. Five-to-ten year viability hinges on carbon credit verification protocol alignment with nitrogen-fixing inoculant application data. Monitor EU Carbon Border Adjustment Mechanism implementation timing as inflection indicator for biological adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Inoculant Portfolio Expansion | Corteva's microbial R&D investments capture Brazilian soybean cooperative procurement shifts away from synthetic chemistries. |
| Drone-Based Application Infrastructure | Aerial seed treatment systems bypass centralized treater capital barriers for smallholder market penetration in India. |
| Carbon Credit Verification Alignment | EU Carbon Border Adjustment Mechanism compliance protocols integrate nitrogen-fixing inoculant application data for downstream emission reductions. |
| RNA-Interference Coating Development | Precision biocide delivery systems penetrate seed coat barriers while reducing broad-spectrum chemical loads for EPA regulatory continuity. |
| Cooperative Advisory Bundling | Subscription agronomic services displace transactional chemical purchasing in Mato Grosso, locking in biological package loyalty. |
Research Methodology
Direct dialogue with seed company R&D directors, cooperative procurement managers, biological formulation scientists, and precision equipment manufacturers grounded qualitative findings, validated against customs trade records, EPA FIFRA registration databases, ANVISA import tolerance filings, and EU ECHA substance evaluation disclosures. Bottom-up treatment volume estimates triangulated with top-down agrochemical market sizing.
Segment-level value outputs across product type, application, and end-use dimensions were generated through elasticity-calibrated demand modeling across the projection horizon. CAGRs derived from acreage expansion rates, treatment penetration curves, and biological adoption slope analysis. Key inputs included Brazilian soybean yield trial data, EU pesticide reduction target enforcement timelines, and precision planter equipment installation rates in the US Corn Belt.
The model assumes a particular technology adoption path; alternative pathways for RNA-interference seed coatings would alter the outlook if regulatory approval timelines compress or expand. Forecasts reflect assumptions about EU Green Deal enforcement consistency and Chinese intermediate supply stability. A model refresh is warranted upon material change in carbon credit verification protocol alignment with biological inoculant application data.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
Mexico Seed Treatment Market
Seed Technology
Seed Quality Imaging and Germination Prediction Test Systems Market
Seed Technology
Seed Coating Ingredients Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
France Seed Treatment Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
Europe Seed Coating Materials Market
Seed Technology
Seed Coating Materials Market
Seed Technology
Seed Treatment Market
Seed Technology
Asia-Pacific Seed Coating Materials Market
Seed Technology
Japan Seed Treatment Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
Canada Seed Treatment Market
Seed Technology
Seed Storage Systems Market
Seed Technology
North America Seed Coating Materials Market