
 Japan Seed Treatment Market | 2026-2036
Japan Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Seed Treatment Market Foresight
The capability gap between integrated agrochemical conglomerates and specialized domestic formulators is rotating competitive capital allocation across Japan's seed treatment sector. Syngenta Co Ltd leverages its global biologicals pipeline to anchor premium positions in rice seed coating. Sumitomo Chemical sustains domestic manufacturing scale through captive fermentation capacity for microbial inoculants. Kureha Corporation specializes in controlled-release polymer formulations that differentiate its pelleting systems from commodity alternatives.
Japan seed treatment encompasses chemical and biological agents applied to seeds before sowing to protect against pathogens, pests, and abiotic stress, typically involving active ingredients formulated at 0.5-5% loading rates on polymer or mineral carriers to ensure uniform adhesion during mechanical planting. The primary purpose is to reduce early-season crop losses while minimizing field-spray applications in Japan's fragmented, high-labor-cost farming landscape. Pesticides still occupy the largest value share, though biostimulants represent the fastest-expanding category as METI's Green Food System Strategy tightens maximum residue limits. Coating dominates treatment method volumes for rice and soybean sowing, while priming gains traction in vegetable transplant production where germination uniformity commands price premiums.
METI's Green Food System Strategy and the Ministry of Agriculture, Forestry and Fisheries (MAFF) pesticide registration framework jointly determine which active ingredients gain market access, with microbial strains facing shorter evaluation timelines than novel chemicals since regulatory amendments. JIS standards for seed quality and the Japan Agricultural Cooperatives (JA) group procurement specifications further constrain formulation choices for suppliers seeking national distribution. Stakeholders must monitor MAFF's pending biologicals registration simplification proposals, as these will reshape which domestic and foreign entrants can achieve commercial scale without legacy chemical portfolios.
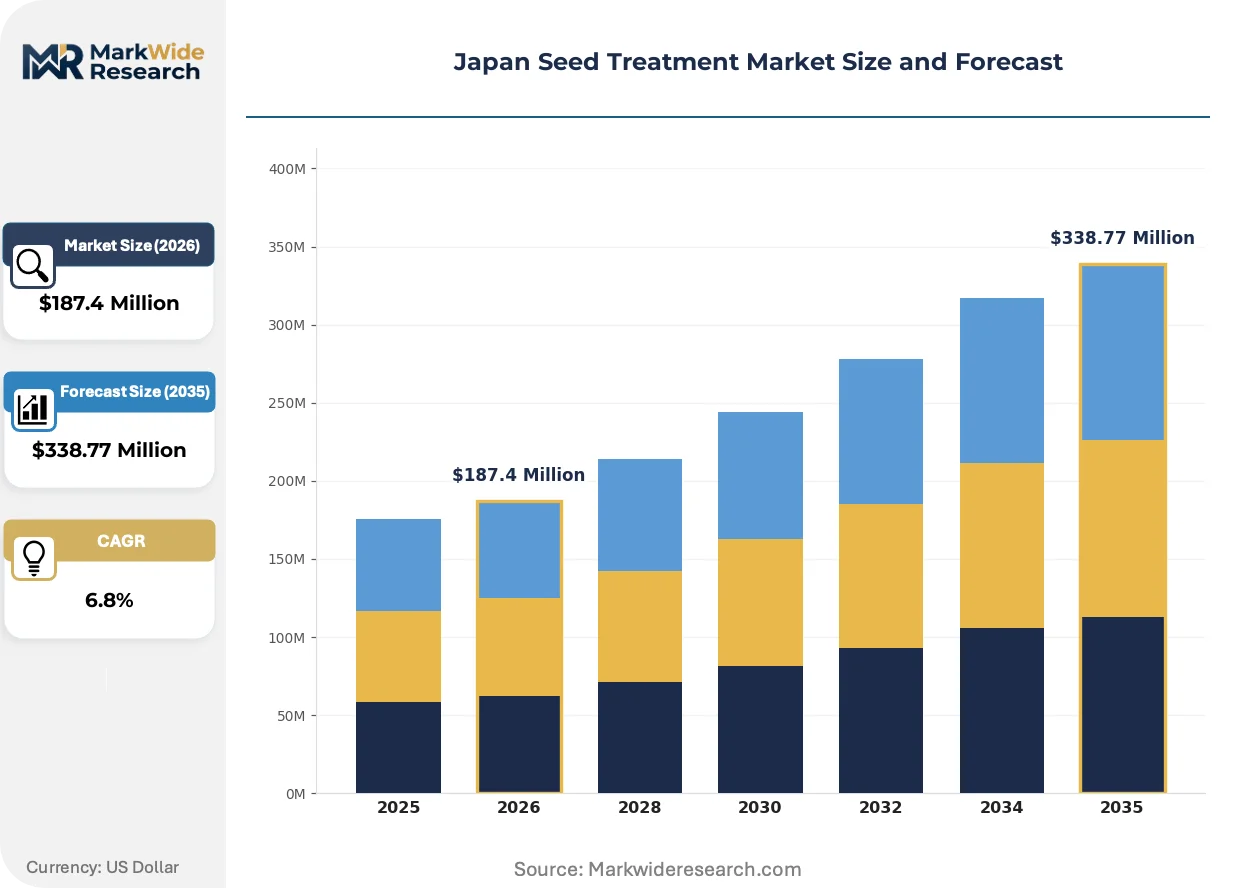
Market Dynamics
METI's Green Food System Strategy is compressing chemical pesticide registration timelines while accelerating biologicals pathways, forcing incumbents to reallocate R&D toward microbial inoculants and controlled-release polymers.
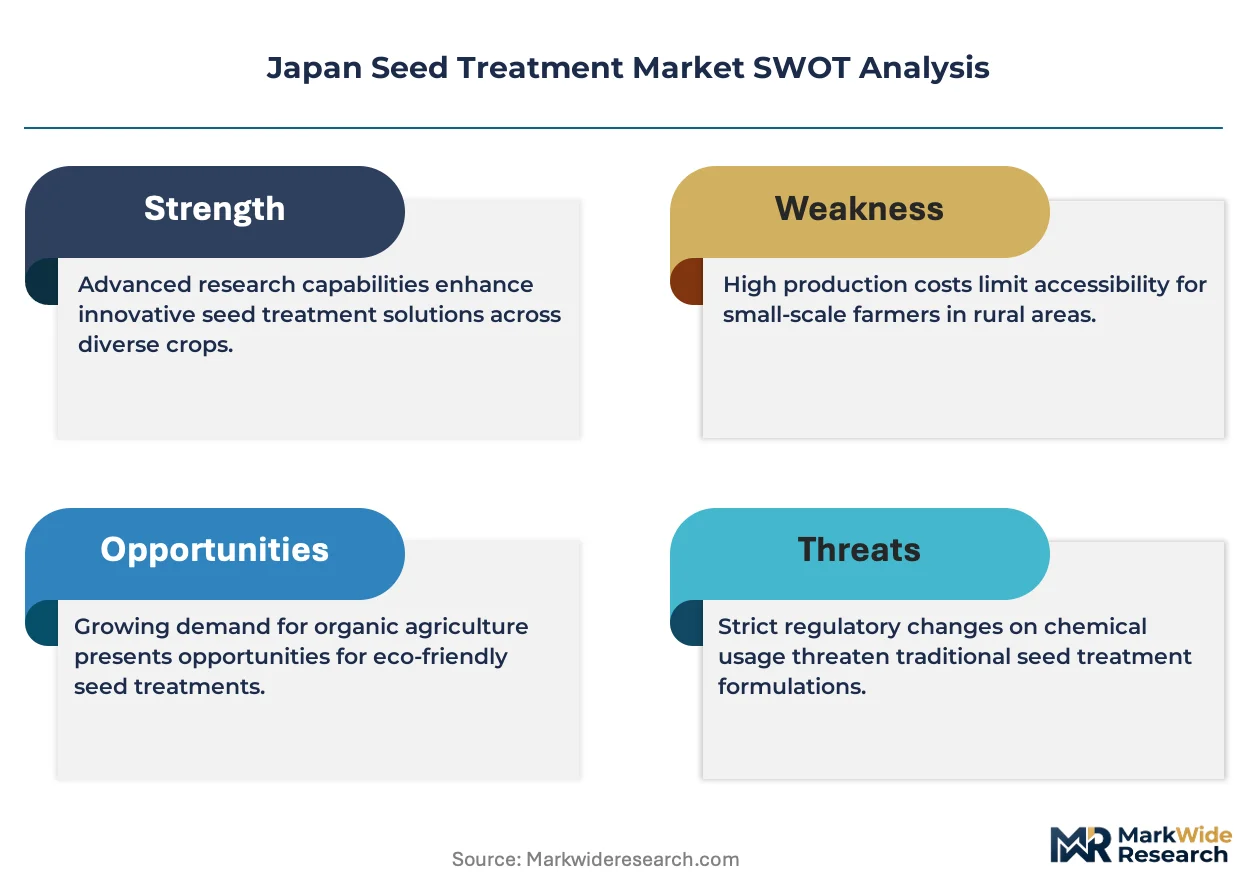
Growth Catalysts
- Biologicals Registration Simplification:MAFF's pending amendments shorten evaluation timelines for microbial strains versus novel chemicals, enabling faster market entry for domestic formulators without legacy portfolios.
- Hokkaido Rice Cooperative Expansion:Farming cooperatives in northern Japan are scaling biological seed treatment adoption to meet JA group procurement specifications for reduced chemical loads.
- Kanto Plain Vegetable Intensification:Soil-borne disease pressure and labor constraints in Japan's dominant vegetable production zone are elevating seed treatment from optional input to essential cost-control mechanism.
Market Restraints
- Petroleum-Derived Polymer Cost Volatility:Pelleting system raw materials fluctuate with naphtha prices, squeezing margin structures for controlled-release formulation specialists.
- Fermentation Capacity Concentration:Domestic microbial inoculant production relies on captive fermentation infrastructure concentrated among integrated chemical conglomerates, creating supply bottlenecks for independent entrants.
- JIS Standard Compliance Friction:Seed quality certification requirements impose fixed formulation constraints that limit product differentiation for suppliers seeking national JA distribution.
Strategic Opportunities
- Tohoku Biological Corridor:Rice farming cooperatives in northeastern prefectures represent underpenetrated demand for microbial seed coatings as water management infrastructure modernizes.
- Priming Method Expansion:Vegetable transplant producers in Shizuoka and Ibaraki are adopting priming over coating to command germination uniformity premiums in high-value export segments.
- Polymer-Mineral Carrier Convergence:Hybrid formulation technologies combining controlled-release polymers with mineral carriers enable dual-action protection against abiotic stress and soil pathogens.
Industry Challenges
- Microbial Strain Banking Expertise Gap:Domestic formulators lack in-house culture collection management capabilities, forcing reliance on third-party academic or overseas strain repositories.
- Mechanical Planting Integration Complexity:Seed treatment adhesion specifications must synchronize with precision drill calibration across heterogeneous farm equipment fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Seed Treatment Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pesticides, Inoculants, Fertilizers, Biostimulants Application: Crops, Vegetables, Fruits, Ornamental Plants Treatment Method: Coating, Soaking, Pelleting, Priming Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Syngenta Co Ltd, BASF SE, Bayer Cropscience AG, Corteva Agriscience, Sumitomo Chemical, Adama Agricultural Solutions, UPL Ltd, Kureha Corporation, FMC Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Seed Treatment Market Shifts & Advancements
Japan's seed treatment sector is pivoting from chemical protection toward biological-functional hybrids, with formulation science and regulatory arbitrage becoming primary competitive levers.
Microbial consortia combining plant-growth-promoting rhizobacteria with mycorrhizal fungi is supplanting single-strain inoculants in premium rice seed coatings. Hokkaido farming cooperatives are adopting these multi-organism formulations at accelerating pace. This convergence is compressing the addressable market for standalone chemical fungicides in water-seeded rice systems.
METI's Green Food System Strategy mandates progressive reduction in chemical pesticide maximum residue limits across food categories. The policy redirects MAFF registration review resources toward biological active ingredients and streamlines microbial strain safety data requirements. Vegetable producers in the Kanto Plain face the tightest compliance windows, driving fastest adoption of biostimulant-loaded priming treatments.
JA group procurement consolidation is compressing supplier tiers as regional cooperatives centralize seed treatment specification-setting. Independent formulators without captive fermentation or polymer synthesis capabilities are losing shelf space to integrated conglomerates offering bundled input packages. This concentration is most visible in soybean seed coating contracts across western Honshu prefectures.
Japan Seed Treatment Market Segmentation
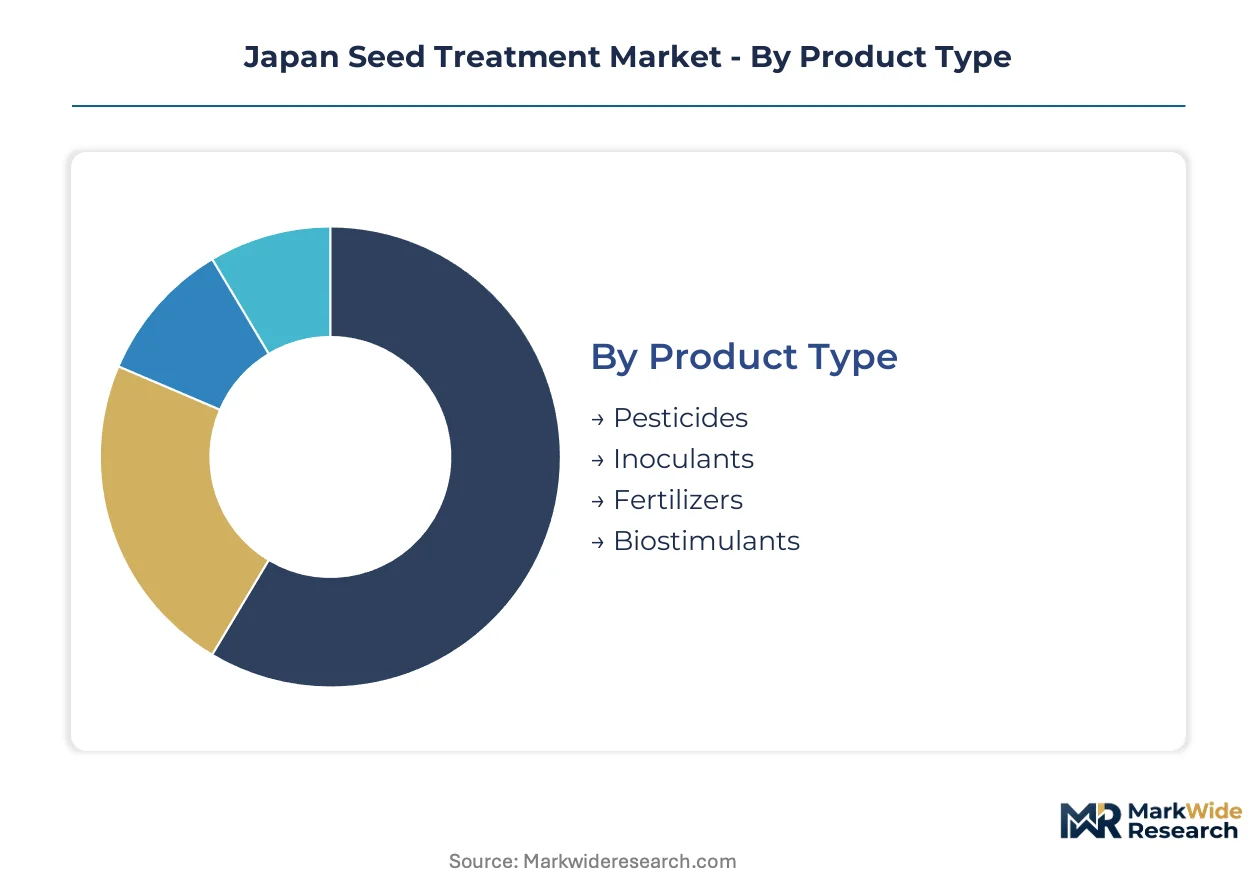
Japan's seed treatment market fragments across four distinct dimensions that determine formulation specifications, regulatory pathways, and procurement access. Each segmentation layer carries unique substitution pressures from adjacent input categories and alternative crop protection methods.
Product Type:
Pesticides face intensifying substitution pressure from biological alternatives as METI's Green Food System Strategy tightens maximum residue limits across food categories.
- Pesticides:Chemical fungicides and insecticides formulated at 0.5-5% loading rates on polymer carriers dominate rice and soybean seed coating volumes. Hokkaido farming cooperatives are reducing procurement quotas for chemical-loaded treatments under JA group sustainability specifications.
- Inoculants:Microbial strains including plant-growth-promoting rhizobacteria and mycorrhizal fungi target nitrogen fixation and phosphorus mobilization. Tohoku rice cooperatives are scaling adoption as water management infrastructure modernizes and biological registration timelines compress.
- Fertilizers:Nutrient-loaded coatings deliver starter phosphorus and micronutrients for early root establishment in vegetable transplant production.
- Biostimulants:Seaweed extracts and protein hydrolysates enhance abiotic stress tolerance; Kanto Plain vegetable growers command germination uniformity premiums.
Pesticides retain volume leadership; biostimulants hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity grain applications from high-value specialty crop segments where treatment premiums justify advanced formulation investments.
- Crops:Rice seed coating dominates absolute tonnage, with water-seeded systems in Hokkaido and Tohoku requiring uniform adhesion for mechanical transplanting. Soybean and wheat treatments concentrate in western Honshu prefectures.
- Vegetables:High-value transplant production in the Kanto Plain elevates priming and pelleting specifications; soil-borne disease pressure and labor constraints make seed treatment essential for cost control.
- Fruits:Citrus and apple nursery stock in Shizuoka and Aomori prefectures drive demand for graft-compatible treatments.
- Ornamental Plants:Chrysanthemum and rose propagation for export markets requires phytosanitary certification compliance.
Crops anchor absolute volume; vegetables generate the highest value per treated hectare.
Treatment Method:
Application technology maturity determines equipment compatibility and adhesion performance across Japan's heterogeneous farm machinery fleets.
- Coating:Polymer-based film coatings at controlled thicknesses protect against fungal pathogens during germination; standard for rice and soybean sowing across JA group procurement networks.
- Soaking:Liquid treatment immersion targets pathogen suppression in vegetable seed lots; limited by drying time constraints in commercial operations.
- Pelleting:Controlled-release polymer formulations from Kureha Corporation and integrated conglomerates enable precision drilling of small-seeded crops; mineral carrier hybrids gain traction for dual-action protection.
- Priming:Hydration-controlled germination advancement commands price premiums in Shizuoka and Ibaraki vegetable export segments where uniformity determines market access.
Coating maintains installation base dominance; priming climbs fastest among specialty producers.
Distribution Channel:
Customer type concentration shapes channel economics, with cooperative procurement consolidation favoring bundled input suppliers over independent formulators.
- Direct Sales:Integrated agrochemical conglomerates supply captive fermentation-derived biologicals directly to Hokkaido and Tohoku farming cooperatives under multi-year procurement agreements.
- Distributors:Regional agricultural supply houses bridge independent formulators to western Honshu soybean growers; JIS standard compliance requirements constrain product differentiation.
- Retail:JA-affiliated farm supply centers handle commodity pesticide coatings for smallholder rice producers; shelf space compression favors bundled input packages.
- Online:Emerging channel for specialty biostimulant priming treatments targeting high-value vegetable export producers seeking direct strain provenance documentation.
Direct sales capture cooperative volume leadership; online channels post the steepest growth trajectory among specialty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Japan's agricultural regions, with Hokkaido's large-scale cooperatives driving hard procurement negotiations while Kanto's specialty vegetable growers absorb premium treatment costs for export-grade uniformity.
Hokkaido
Rice farming cooperatives dominate biological seed treatment procurement, prioritizing reduced chemical loads for JA group sustainability specifications. METI's Green Food System Strategy accelerates microbial inoculant adoption timelines. Sapporo-based formulation specialists serve water-seeded rice systems requiring uniform adhesion for mechanical transplanting.
Tohoku
Northeastern rice cooperatives represent underpenetrated demand as irrigation infrastructure modernizes. MAFF's pending biologicals registration simplification shortens market entry for domestic microbial suppliers. Sendai corridor clusters concentrate pelleting system distribution for soybean and wheat rotations.
Kanto Plain
Intensive vegetable production elevates seed treatment to essential cost-control against soil-borne disease pressure. METI's maximum residue limit tightening drives fastest biostimulant-loaded priming adoption. Ibaraki and Shizuoka transplant producers command germination uniformity premiums in high-value export segments.
Kansai
Western Honshu soybean growers concentrate procurement through regional agricultural supply houses. JIS seed quality standards constrain independent formulator differentiation. Osaka-based distributors bridge integrated conglomerates to mid-scale farming operations seeking bundled input packages.
Kyushu
Citrus and greenhouse vegetable production generates specialized nursery stock treatment demand. JA-affiliated supply centers handle commodity coatings for smallholder producers. Fukuoka metropolitan area clusters emerging online channels for specialty biostimulant documentation.
Japan Seed Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with fermentation capacity and polymer synthesis capabilities determining procurement access to cooperative networks. The structure compresses margin for independent formulators lacking captive biological production or controlled-release formulation expertise. Three archetypes dominate: global agrochemical conglomerates leveraging biologicals pipelines, integrated Japanese chemical producers with domestic manufacturing scale, and specialized polymer formulators differentiating through release-control technology. Competitive moves concentrate on backward integration into microbial strain banking and strategic partnerships with JA group procurement committees.
Within the integrated conglomerate tier, Syngenta Co Ltd and Sumitomo Chemical anchor positions through contrasting approaches to biologicals commercialization. Syngenta leverages global pipeline access for premium rice seed coating positions. Sumitomo Chemical sustains domestic manufacturing scale through captive fermentation infrastructure. Kureha Corporation occupies the specialist vector, with its controlled-release polymer formulations differentiating pelleting systems from commodity alternatives in cooperative procurement networks.
| Leading Market Players |
|---|
| Syngenta Co Ltd |
| BASF SE |
| Bayer Cropscience AG |
| Corteva Agriscience |
| Sumitomo Chemical |
| Adama Agricultural Solutions |
| UPL Ltd |
| Kureha Corporation |
| FMC Corporation |
| Others |
Supply & Pricing Matrix
Sixty-day fermentation batch cycles for microbial inoculants compress pricing power for independent formulators lacking captive bioreactor capacity, while polymer carrier lead times tethered to naphtha futures expose margin structures to petrochemical volatility. This inventory-to-pricing linkage concentrates procurement leverage among integrated conglomerates offering bundled biological-polymer packages to JA group cooperatives.
Pricing Analysis
After-sales technical support contracts for seed treatment application equipment drive lifetime value capture beyond initial formulation sales. Three-tier pricing structure across premium microbial consortia, standard single-strain inoculants, and economy chemical coatings separates value tiers by registration complexity and strain provenance documentation. Pricing pressure stems from MAFF's biologicals registration simplification compressing premium windows for novel microbial entrants. Hokkaido rice cooperatives exhibit highest price sensitivity due to consolidated procurement volumes, while Kanto Plain vegetable export producers absorb premium priming costs for germination uniformity certification.
Supply Chain Analysis
Japan and China anchor microbial strain fermentation and polymer carrier synthesis respectively, with domestic captive bioreactor capacity concentrated among integrated chemical conglomerates in Osaka and Tokyo Bay industrial zones. Active ingredient production draws from petroleum-derived polymer feedstocks and specialized mineral carriers, with fermentation media sourcing from agricultural commodity processors. Single-source vulnerability runs through concentrated domestic fermentation infrastructure, where bioreactor commissioning timelines extend supplier lock-in. Distribution runs through JA-affiliated farm supply centers for commodity coatings and direct technical sales for cooperative biological procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through JA group procurement consolidation, as regional cooperatives centralize seed treatment specification-setting and compress supplier tiers toward bundled input providers.
For Market Incumbents: Fortify captive fermentation capacity and controlled-release polymer synthesis capabilities to defend cooperative procurement access against emerging domestic microbial specialists. METI's Green Food System Strategy is accelerating biologicals registration timelines, eroding chemical formulation margins and demanding R&D reallocation toward strain banking partnerships. Backward integration into microbial culture collection management reduces reliance on third-party academic repositories and secures proprietary consortia formulations for premium rice coating positions. For New Entrants and Emerging Players: MAFF's pending biologicals registration fast-track offers entry velocity for domestic formulators lacking legacy chemical portfolios, particularly targeting Tohoku rice cooperatives where irrigation infrastructure modernization is expanding addressable demand. White-space concentration sits with priming method specialization for Shizuoka and Ibaraki vegetable export producers seeking germination uniformity documentation. Go-to-market execution should prioritize direct technical sales relationships with high-value transplant producers rather than JA retail channel penetration. For Investors and Strategic Acquirers: Long-term, this sits as a biological-functional hybrid play because METI's maximum residue limit tightening structurally displaces chemical protection toward microbial-biostimulant convergence over the projection horizon. Acquisition targets should emphasize specialized polymer formulators with controlled-release expertise and established JA distribution relationships. The signal to watch is MAFF biologicals registration amendment finalization, which would inflect domestic entrant viability and reshape competitive capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Banking | Proprietary microbial consortia development reduces third-party repository dependence for Hokkaido cooperative supply. |
| Controlled-Release Polymer Capacity Expansion | Kureha Corporation's pelleting technology differentiation commands premium positioning in JA procurement networks. |
| Biologicals Registration Fast-Track Utilization | MAFF amendment exploitation accelerates market entry timelines for domestic entrants without legacy chemical portfolios. |
| Priming Method Specialization | Shizuoka vegetable export segment adoption commands germination uniformity premiums above standard coating economics. |
| Direct Cooperative Sales Channel Development | Bypassing JA retail compression captures Hokkaido and Tohoku rice cooperative procurement consolidation volume. |
Research Methodology
The analysis maps biological seed treatments, chemical coatings, polymer pelleting systems, and priming formulations, each validated through fermentation facility managers, JA group procurement committee members, MAFF regulatory affairs specialists, and Kanto Plain vegetable cooperative technical directors. Primary interview findings triangulated against MAFF pesticide registration databases, METI Green Food System Strategy implementation documents, JIS seed quality standards, and JA group procurement specification records. Bottom-up treatment volume estimates and top-down agrochemical input spending benchmarks converged through iterative stakeholder validation.
Consistency checks validated projection outputs against historical biologicals adoption curves in comparable regulatory environments and polymer carrier cost trajectories across petrochemical cycles. Segmentation modeling incorporated product type, application crop, treatment method, and distribution channel dimensions across the analysis window. CAGRs derived from treatment volume growth rates, pricing tier migration patterns, and biologicals penetration assumptions calibrated to MAFF registration timeline scenarios. Industry-specific inputs included fermentation capacity utilization rates and JA cooperative procurement consolidation trajectories.
Decision-makers should treat outputs as directional under sustained METI Green Food System Strategy enforcement and MAFF biologicals registration simplification implementation; material deviation in regulatory timelines or polymer feedstock cost trajectories would warrant model refresh. Forecasts reflect assumptions regarding cooperative procurement centralization velocity and microbial strain adoption curves in water-seeded rice systems. Recalibration cycles align with material shifts in MAFF registration framework amendments and JA group specification-setting consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
Europe Seed Coating Materials Market
Seed Technology
Seed Coating Materials Market
Seed Technology
China Seed Treatment Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
Asia-Pacific Seed Coating Materials Market
Seed Technology
Mexico Seed Treatment Market
Seed Technology
North America Cotton Seed Treatment Market
Seed Technology
India Seed Treatment Market
Seed Technology
Seed Storage Systems Market
Seed Technology
Seed Coating Ingredients Market
Seed Technology
Seed Treatment Market
Seed Technology
Seed Quality Imaging and Germination Prediction Test Systems Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
North America Seed Coating Materials Market
Seed Technology
Asia-Pacific Tomato Seed Market