
 Seed Coating Ingredients Market | 2026-2036
Seed Coating Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Coating Ingredients Market Analytics
Specialty seed producers is recalibrating procurement priorities toward film-coated and encrusted formulations that reduce dust-off and improve planting precision. BASF SE leverages its polymer R&D pipeline to anchor positions in moisture-retention binders. Croda International Plc differentiates through bio-based additive portfolios targeting European sustainability mandates. Syensqo competes in high-performance colorant systems that enable optical sorting automation.
Seed coating ingredients encompass polymers, additives, colorants, and biostimulants applied to seed surfaces through spray, powder, film, or encrusting processes, typically at application rates of 0.5% to 5% of seed weight to protect genetic potential and enhance field establishment. The polymer segment dominates value capture due to binding and controlled-release functions, while biostimulants represent the fastest-expanding category as growers seek reduced-chemical establishment protocols. Film coating technology leads volume adoption in row crops, whereas encrusting commands premium positioning in vegetable and specialty seeds where sizing uniformity directly affects mechanical planting efficiency.
The EPA regulates treated seed as pesticides under FIFRA, requiring rigorous data on active ingredient mobility and non-target organism toxicity before market authorization. REACH and the EU Green Deal compel European formulators to phase out microplastic-containing polymers and disclose full substance inventories across coating supply chains. Stakeholders must monitor evolving regulatory divergence between jurisdictions, as compliance investments in one region may not transfer to another, reshaping competitive advantage toward multi-certification capabilities.
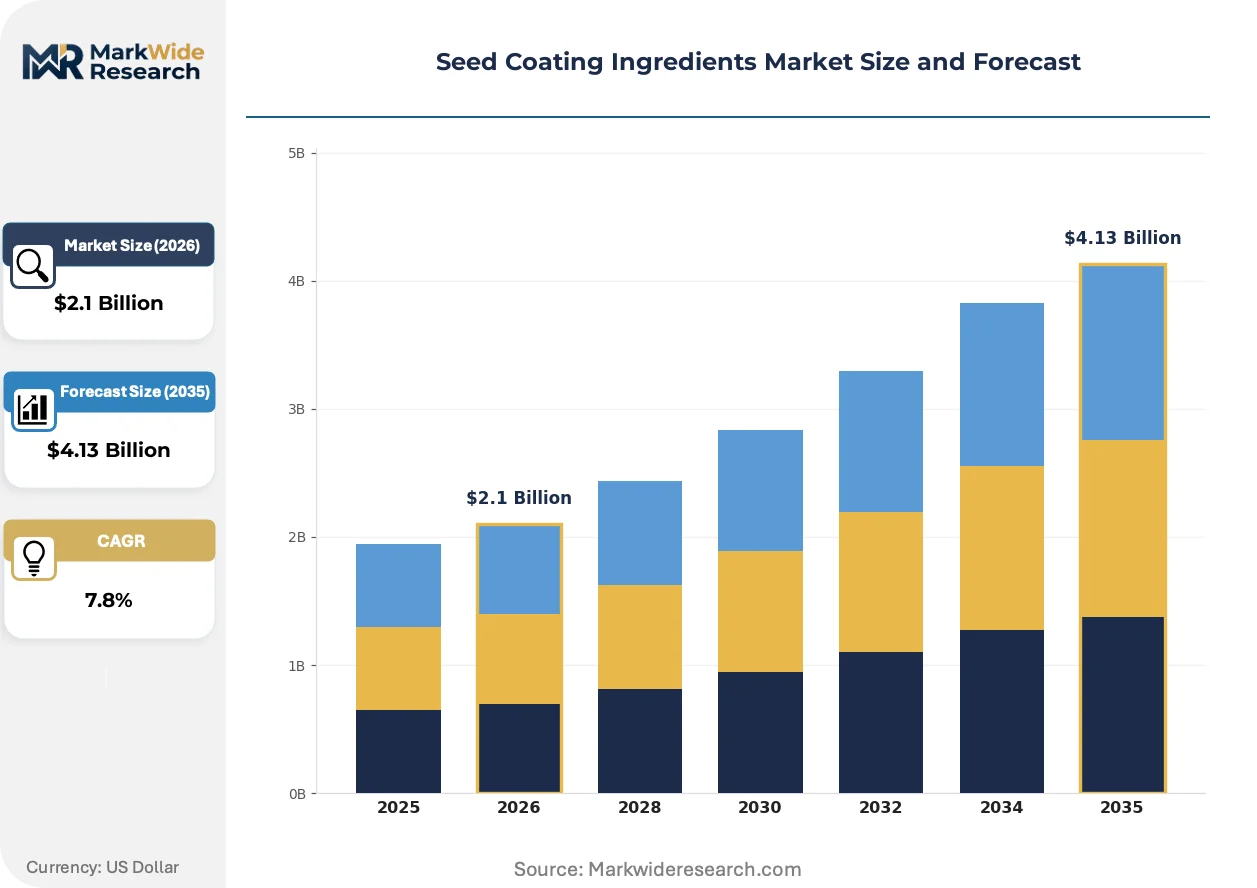
Market Dynamics
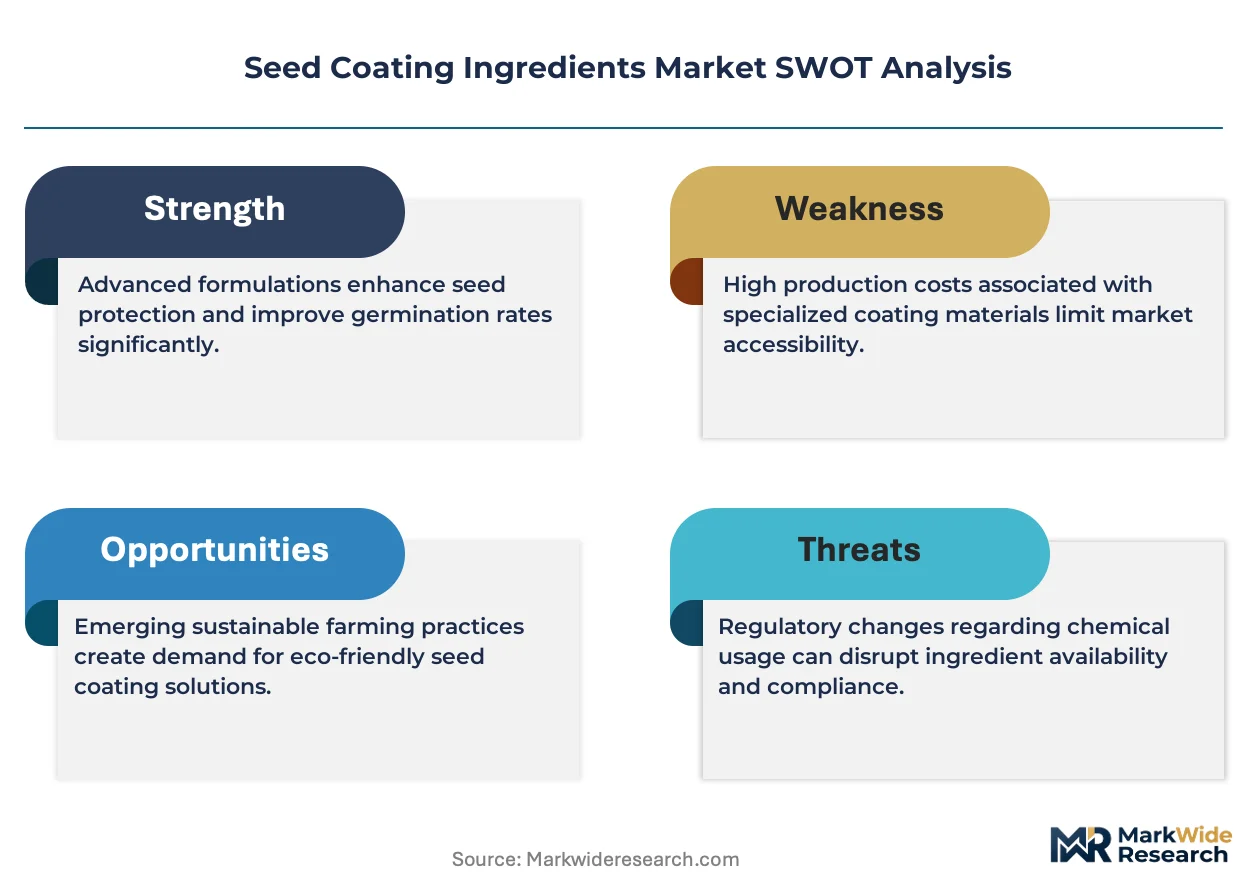
Polymer microplastic disclosure mandates under REACH and the EU Green Deal are forcing formulators to rebuild coating architectures from binder chemistry upward, compressing product development cycles and disqualifying legacy portfolios.
Growth Catalysts
- Brazilian soybean seed treatment expansion:Treatment rates in Brazil are climbing toward developed-market levels, concentrating demand for high-performance film coatings that reduce dust-off during mechanical planting.
- REACH microplastic restrictions:The European regulation is accelerating R&D investment in bio-based polymer alternatives that maintain controlled-release performance without triggering disclosure penalties.
- Optical sorting automation:Vegetable seed producers are adopting colorant-embedded coatings that enable machine vision systems to reject off-type seeds at processing speeds exceeding manual thresholds.
Market Restraints
- Petrochemical binder volatility:Acrylic and polyurethane polymer feedstocks expose coating margins to crude-derived input swings that seed producers rarely index.
- Chinese intermediate concentration:Pigment and polymer additive synthesis clusters in Jiangsu and Zhejiang provinces, creating single-source vulnerability for European and North American formulators.
- Biostimulant efficacy variability:Field performance inconsistency across soil types and climate zones limits grower willingness to pay premium coating prices for microbial inoculants.
Strategic Opportunities
- Indian specialty vegetable seeds:Mechanized transplanting adoption in Maharashtra and Karnataka is creating first-mover demand for encrusted coatings that deliver uniform sizing for precision seeders.
- EU F-Gas Regulation compliance services:Formulators can capture value by offering full substance inventory documentation and substitution roadmaps that seed companies lack in-house capacity to generate.
- Drone-applied coating integration:Convergence of aerial application platforms with film-coating chemistry enables on-farm seed treatment customization that bypasses centralized processor bottlenecks.
Industry Challenges
- Polymer toxicology data generation:EPA FIFRA registration timelines for novel binder chemistries extend 18-36 months, freezing product launches until mobility and non-target organism studies complete.
- Cross-jurisdictional certification fragmentation:Coatings approved under EPA protocols require redundant EU REACH dossier construction, multiplying compliance headcount without transferable documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Coating Ingredients Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymers, Additives, Coloring Agents, Biostimulants Coating Technology: Spray Coating, Powder Coating, Film Coating, Encrusting Application Field: Agricultural Seeds, Horticultural Seeds, Turf Seeds, Specialty Seeds Functionality: Pest Control, Nutrient Release, Moisture Retention, Disease Resistance |
| Companies Covered | BASF SE, Clariant, Croda International Plc, Solvay, Sensient Technologies Corporation, Syensqo, Michelman, Precision Laboratories, Roquette Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Coating Ingredients Market Evolving Landscape
Active coating architectures are shifting from passive protection to biological activation, embedding living organisms and responsive polymers that interact with soil microbiology rather than simply shielding genetic material.
Biodegradable polymer seed coatings derived from polysaccharide and protein matrices are electrifying row-crop establishment protocols. Corn and soybean producers in the US Midwest are piloting these materials at 15,000-acre scales. The technology is electrifying competitive positioning by enabling treated seed sales into European export markets that exclude conventional microplastic-containing alternatives.
REACH Annex XVII microplastic restrictions and the EU Green Deal chemical disclosure framework are compelling formulators to phase out synthetic polymer binders entirely. European seed companies now require full substance inventories from coating suppliers back to monomer origins. Vegetable seed specialists operating glasshouse propagation systems face the steepest compliance burden, as their high-value genetics command coating price premiums that absorb reformulation costs.
Seed coating procurement is consolidating through processor-direct contracting that disintermediates traditional agricultural chemical distributors. Large-scale row-crop seed producers in Brazil and the US are negotiating multi-year coating supply agreements tied to germination performance guarantees. This pattern is most pronounced in soybean and corn seed supply chains where treated seed represents the dominant delivery format and coating quality directly affects brand reputation at planting.
Seed Coating Ingredients Market Segmentation
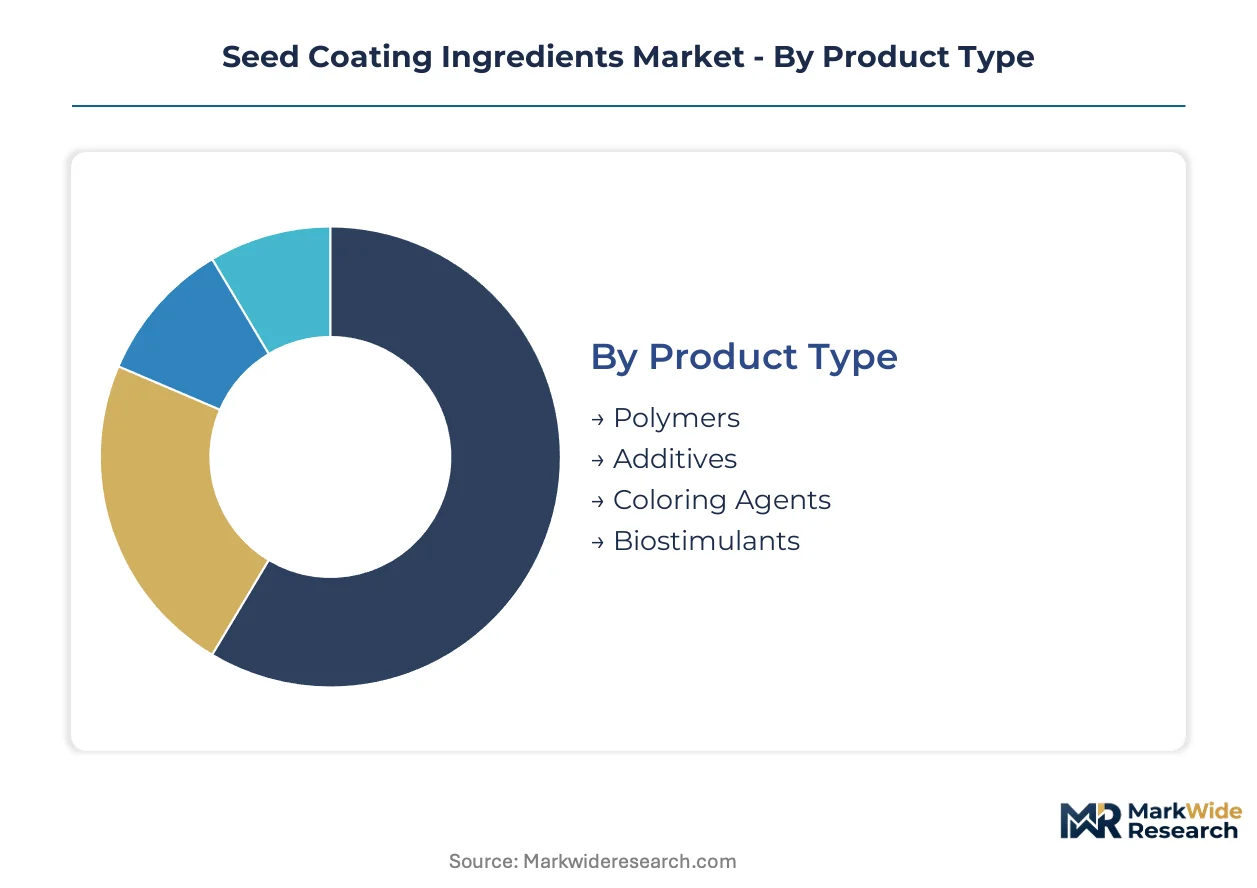
Seed coating procurement pivots on germination performance guarantees rather than ingredient cost alone. Formulators must align polymer selections, application technologies, and functional architectures to specific crop establishment protocols across divergent regulatory jurisdictions.
Product Type:
Buyer decisions hinge on controlled-release performance and regulatory compliance burden rather than unit chemistry cost.
- Polymers:Acrylic, polyurethane, and bio-based binders form the structural matrix controlling active ingredient release kinetics. Corn and soybean producers in Brazil prioritize dust-off reduction polymers that protect brand reputation during mechanical planting operations.
- Biostimulants:Microbial inoculants and plant-growth-promoting rhizobacteria embed living organisms that activate upon soil contact. Field performance variability across soil types constrains pricing power despite strong grower interest in reduced-chemical protocols.
- Additives:Surfactants, anti-foam agents, and flow aids optimize coating adhesion and processing efficiency.
- Coloring Agents:Pigments and dyes enable optical sorting automation and treated-seed identification compliance.
Volume sits with Polymers; growth tilts toward Biostimulants.
Coating Technology:
Application method selection traces directly to seed value density and planting mechanization levels.
- Film Coating:Thin, uniform polymer layers applied through precision spray systems dominate high-volume row-crop processing. Brazilian soybean seed treatment facilities are scaling film-coating capacity as treatment rates converge toward developed-market benchmarks.
- Encrusting:Heavy material deposition builds uniform seed sizing for precision mechanical planters. Vegetable seed specialists in the Netherlands command premium pricing for encrusted products that eliminate planter skips in glasshouse transplanting systems.
- Spray Coating:Conventional liquid application suits lower-value seed categories with less stringent uniformity requirements.
- Powder Coating:Dry particulate adhesion serves niche applications where moisture sensitivity constrains liquid processing.
Revenue concentrates in Film Coating; margin expansion favors Encrusting.
Application Field:
End-use segmentation reflects divergence between commodity scale and specialty value capture.
- Agricultural Seeds:Corn, soybean, wheat, and rice coatings prioritize operational throughput and treatment cost minimization at million-ton scales. US Midwest processors negotiate multi-year supply agreements tying coating quality to germination performance guarantees.
- Specialty Seeds:High-value vegetable, herb, and ornamental genetics absorb premium coating investments that would be uneconomical in commodity crops. European vegetable seed producers under EU Green Deal disclosure mandates are absorbing reformulation costs that commodity channels resist.
- Horticultural Seeds:Greenhouse and nursery establishment protocols demand precision sizing and pathogen protection.
- Turf Seeds:Lawn and sports field applications emphasize aesthetic uniformity and establishment speed.
Throughput dominates Agricultural Seeds; pricing power concentrates in Specialty Seeds.
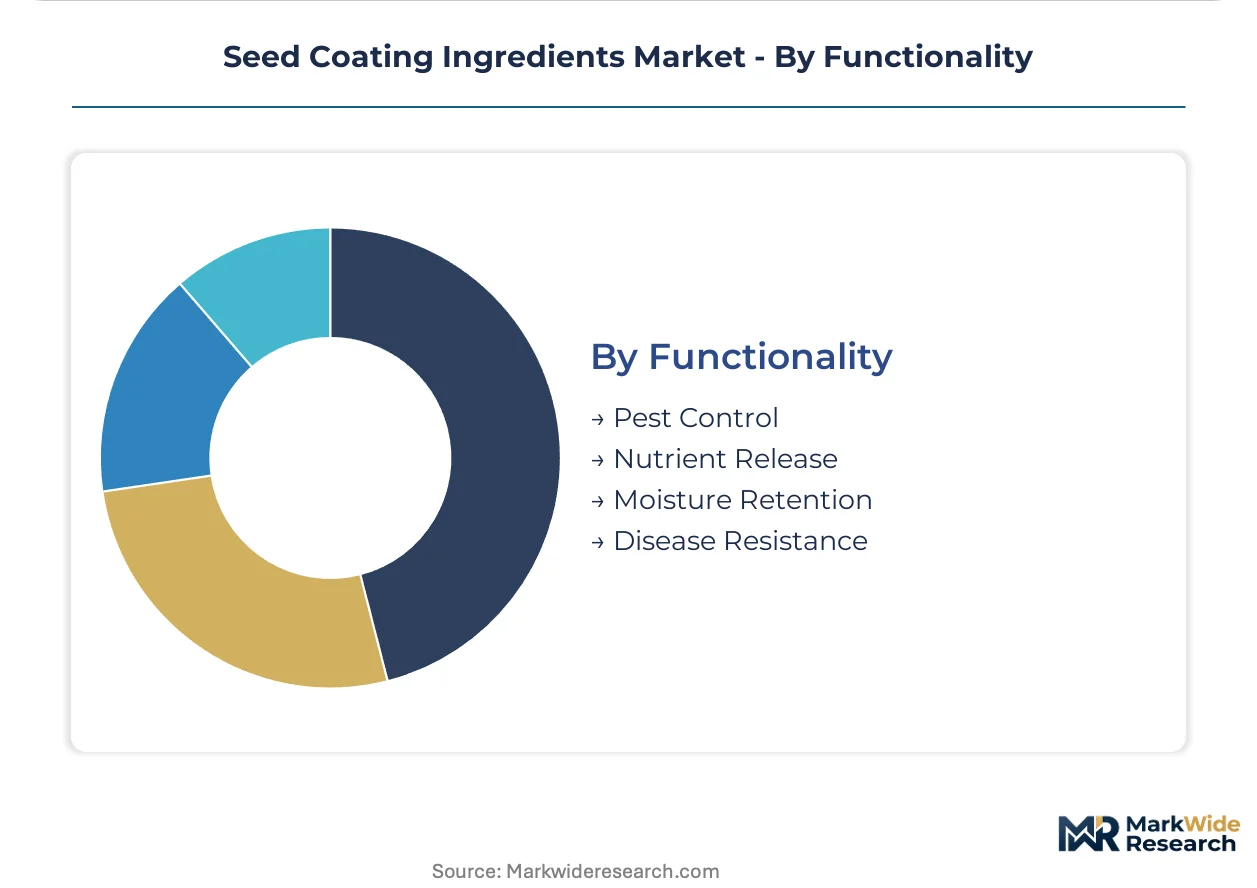
Functionality:
Performance claims must survive jurisdiction-specific efficacy validation before commercial deployment.
- Moisture Retention:Hydrophilic polymer architectures and superabsorbent materials buffer germinating seeds against erratic precipitation. EPA FIFRA registration requirements for novel moisture-control chemistries extend development timelines 18-36 months.
- Pest Control:Insecticide and nematicide delivery through seed coatings reduces foliar spray dependency. EU REACH microplastic restrictions are forcing reformulation of conventional pesticide-binding polymers.
- Nutrient Release:Encapsulated fertilizers provide establishment-phase nutrition without separate application passes.
- Disease Resistance:Fungicide coatings and biological antagonists protect against soilborne pathogens during vulnerable germination windows.
Deployment breadth favors Pest Control; regulatory pressure is accelerating Moisture Retention innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of seed coating ingredients clusters in European and North American chemical manufacturing hubs, while consumption growth concentrates in Brazilian and Indian agricultural expansion zones. This geographic mismatch creates supply chain complexity for formulators serving high-growth markets.
United States
Corn and soybean seed processors in the Midwest negotiate multi-year coating supply agreements tied to germination performance guarantees. EPA FIFRA registration timelines for novel binder chemistries extend 18-36 months, freezing product launches until mobility studies complete. Iowa and Illinois seed treatment facilities represent the densest concentration of film-coating capacity for row-crop establishment.
Brazil
Soybean seed treatment rates are climbing toward developed-market levels, concentrating demand for high-performance film coatings that reduce dust-off during mechanical planting. ANVISA chemical disclosure requirements are tightening parallel to EU standards, forcing importers to rebuild documentation systems. São Paulo and Mato Grosso processing corridors anchor South American coating consumption.
Germany
Specialty vegetable seed producers under EU Green Deal mandates absorb reformulation costs that commodity channels resist. REACH Annex XVII microplastic restrictions accelerate R&D investment in bio-based polymer alternatives. The Rhine-Ruhr chemical cluster hosts concentrated polymer R&D infrastructure serving European coating formulators.
India
Mechanized transplanting adoption in Maharashtra and Karnataka creates first-mover demand for encrusted coatings delivering uniform sizing for precision seeders. BIS standards for treated seed quality are evolving toward international alignment, requiring technical documentation upgrades. Gujarat chemical synthesis hubs supply pigment and polymer additive intermediates to domestic formulators.
China
Pigment and polymer additive synthesis clusters in Jiangsu and Zhejiang provinces create single-source vulnerability for European and North American formulators. MEE environmental enforcement is tightening discharge standards for coating intermediate manufacturing. The Yangtze River Delta concentration of fine chemical production dominates Asia-Pacific supply for colorant systems.
Seed Coating Ingredients Market Competitive Landscape
Top-tier vendors anchor polymer and biostimulant innovation, while mid-tier regional specialists compete on formulation customization and local regulatory navigation. The vendor base stratifies across integrated chemical conglomerates with captive polymer supply, agricultural input distributors backward-integrating into coating services, and pure-play coating technology developers. Strategic archetypes include sustainability-focused bio-based formulators, performance-guarantee contract manufacturers, and regulatory compliance service bundlers. Dominant competitive moves encompass multi-year supply agreements tying coating quality to germination outcomes, and geographic expansion through processor-direct contracting that disintermediates traditional distribution.
Within the integrated chemical conglomerate tier, BASF SE and Croda International Plc exemplify divergent strategic positioning. BASF anchors moisture-retention binder development through its polymer R&D pipeline. Croda occupies a position representing bio-based additive portfolios targeting European sustainability mandates. Syensqo sits within the performance-systems archetype, competing in colorant technologies that enable optical sorting automation. These three entities collectively illustrate how coating ingredient suppliers are recalibrating toward regulatory compliance capabilities and biological activation functionalities rather than commodity chemical supply.
| Leading Market Players |
|---|
| BASF SE |
| Clariant |
| Croda International Plc |
| Solvay |
| Sensient Technologies Corporation |
| Syensqo |
| Michelman |
| Precision Laboratories |
| Roquette Group |
| Others |
Value Network & Pricing Analysis
Acrylic and polyurethane feedstock indices cascade through coating ingredient supply chains into stratified pricing tiers, with Brazilian soybean processors absorbing premium polymer costs that Indian vegetable seed producers resist under BIS quality mandates.
Pricing Analysis
Margin tightening in commodity polymer tiers reflects petrochemical feedstock volatility that seed producers rarely index into supply contracts. Pricing stratifies across premium, standard, and economy tiers based on REACH microplastic compliance certification and volume-scale procurement commitments. Cost-down pressure on bio-based alternatives accelerates because European vegetable seed companies under EU Green Deal mandates absorb reformulation premiums that commodity channels reject. Agricultural seed processors in Brazil and the US Midwest demonstrate lowest price sensitivity due to germination performance guarantees, while Indian specialty vegetable producers exhibit highest sensitivity to coating cost escalation.
Supply Chain Analysis
Dual-sourcing qualification requirements from European formulators now mandate redundant supplier validation for polymer binders and colorant systems. Manufacturing gravity centers on Germany's Rhine-Ruhr chemical cluster, China's Jiangsu and Zhejiang pigment synthesis corridors, and Gujarat's domestic intermediate hubs. Raw material flows draw from acrylic acid derivatives, polyurethane prepolymers, and bio-based polysaccharide feedstocks. Single-source vulnerability concentrates in Chinese intermediate manufacturing, where MEE environmental enforcement tightens discharge standards. Distribution runs through processor-direct contracting that disintermediates traditional agricultural chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The seed coating ingredients market sits in a polymer-transition phase, with bio-based binder technologies displacing legacy microplastic-containing architectures under regulatory pressure.
For Market Incumbents: Lock in multi-year supply agreements with Brazilian soybean processors before ANVISA disclosure requirements fully align with EU REACH standards. BASF SE and Croda International Plc should deepen captive polymer supply control to defend margin position against petrochemical feedstock swings. Priority R&D investment targets moisture-retention binders that satisfy both EPA FIFRA registration timelines and EU microplastic restrictions. For New Entrants and Emerging Players: EU F-Gas Regulation compliance services in Germany open a window for documentation-specialist entrants lacking legacy portfolio exposure to microplastic penalties. Target Indian encrusted coating demand in Maharashtra and Karnataka mechanized transplanting zones. Go-to-market positioning centers on drone-applied coating integration that bypasses centralized processor bottlenecks for on-farm customization. For Investors and Strategic Acquirers: The window for entry favors bio-based polymer specialists with REACH dossier construction capabilities and multi-certification track records. Long-term viability hinges on formulators navigating 18-36 month EPA FIFRA registration timelines without freezing product pipelines. Signal to watch: germination performance guarantee adoption rates in Brazilian processor-direct contracts as proxy for pricing power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Polymer Supply | Croda International Plc anchors European sustainability mandates through captive polysaccharide feedstock control. |
| REACH Compliance Documentation Services | Formulators capture value from seed companies lacking in-house substance inventory generation capacity. |
| Drone-Applied Coating Platform Integration | Aerial application convergence enables on-farm seed treatment customization bypassing processor bottlenecks. |
| Multi-Year Performance Guarantee Contracts | Brazilian soybean processors tie coating quality to germination outcomes, consolidating procurement consolidation. |
| Optical Sorting Colorant System Development | Syensqo competes in machine vision-enabled seed rejection technologies for vegetable seed specialists. |
Research Methodology
Multi-period observation of Brazilian seed treatment rate convergence, EU polymer disclosure mandate implementation, and Indian mechanized transplanting adoption anchored the trend analysis, supplemented by interviews with coating formulator R&D directors, seed company procurement leads, polymer plant managers, and regulatory affairs specialists at EPA and ECHA. Secondary validation drew from customs trade data, SEC 10-K filings of listed chemical conglomerates, ANVISA disclosure requirement drafts, and BIS treated seed quality standard evolution documents. Bottom-up polymer consumption modeling triangulated against top-down seed treatment market sizing.
Input-output matrices mapped polymer binder demand to soybean and corn seed treatment expansion across geographic clusters, with segmentation dimensions spanning product type, coating technology, application field, and functionality performance claims. CAGRs derived from regression analysis of historical treatment rate penetration curves applied to acreage expansion projections. Industry-specific forecast inputs incorporated EPA FIFRA registration timeline distributions and REACH microplastic restriction phase-out schedules.
The model assumes a particular technology adoption path; alternative pathways for biodegradable polymer seed coatings would alter the outlook if field performance variability resolves faster than projected. Forecasts reflect documented assumptions regarding Brazilian treatment rate convergence speed and EU Green Deal enforcement consistency. Deviation in Chinese intermediate manufacturing disruption or petrochemical feedstock volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
Seed Treatment Market
Seed Technology
North America Seed Coating Materials Market
Seed Technology
France Seed Treatment Market
Seed Technology
Europe Seed Coating Materials Market
Seed Technology
Seed Coating Materials Market
Seed Technology
Seed Additives Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
India Seed Treatment Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
Seed Quality Imaging and Germination Prediction Test Systems Market
Seed Technology
Seed Storage Systems Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
Protein Content Optimizing Cereal Fertility Program Market
Seed Technology
Asia-Pacific Seed Coating Materials Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
Canada Seed Treatment Market