
 North America Castor Oil Market | 2026-2036
North America Castor Oil Market Size, Share, and Industry Trends Forecast 2026-2036
North America Castor Oil Market Intelligence
Specialty chemical intermediates is rewriting margin allocation across the North America castor oil value chain. Croda International PLC leverages its lipid chemistry expertise to dominate high-purity refined grades for cosmetic actives. Arkema SA anchors its position through backward integration into sebacic acid derivatives for nylon engineering polymers. Jayant Agro-Organics Ltd. competes on raw material sourcing scale, sustaining supply continuity to North American toll processors.
Castor oil is a triglyceride composed principally of ricinoleic acid, typically comprising 85-95% of total fatty acid content, obtained through mechanical pressing or solvent extraction of Ricinus communis seeds and valued for its hydroxyl functionality, high viscosity index, and dual solubility in alcohols and hydrocarbons. The pressed product type occupies the volume base for industrial lubricant and biofuel applications where color and odor tolerance is higher, while hydrogenated castor oil commands premium positioning in personal care wax systems and pharmaceutical coatings due to oxidative stability. Cosmetics application leads value capture through formulation complexity and brand pull, whereas biofuels represents the fastest-expanding demand pool as renewable diesel and sustainable aviation fuel specifications tighten.
The US EPA Renewable Fuel Standard and FDA monograph requirements for pharmaceutical-grade oleochemicals shape product purity thresholds and market access conditions across the region. Health Canada and PMRA coordinate on agricultural adjuvant registrations, creating cross-border compliance obligations for suppliers serving both markets. Stakeholders must monitor evolving biofuel credit mechanisms and biobased procurement mandates to align capacity investments with policy-driven demand inflections.
Market Dynamics
US EPA biofuel mandates are redirecting Gulf Coast refinery investment toward plant-derived feedstocks, concentrating castor oil demand within the petrochemical corridor while tightening ricinoleic acid purity specifications for renewable diesel and sustainable aviation fuel applications.
Growth Catalysts
- Renewable Fuel Standard mandates:US EPA volume obligations for biomass-based diesel expand the addressable market for castor oil methyl esters in renewable diesel blending.
- Sebacic acid demand from nylon 6,10 polymerization:Engineering plastics manufacturers in the US Southeast are securing long-term ricinoleic acid supply contracts for polyamide intermediates.
- Texas-Louisiana corridor concentration:Hydrogenation capacity investments along the Gulf Coast are creating captive demand for crude castor oil feedstocks.
Market Restraints
- Indian supply concentration:Over 85% of global castor seed crushing capacity resides in Gujarat, exposing North American processors to monsoon-dependent crop volatility and rupee-denominated pricing.
- High oleic sunflower oil substitution:Food-grade lubricant formulators are substituting modified vegetable oils where oxidative stability requirements permit lower viscosity indices.
- FDA pharmaceutical monograph compliance costs:USP-grade certification requires dedicated refining trains, fragmenting capacity economics between industrial and pharmaceutical grades.
Strategic Opportunities
- Mexico nearshoring expansion:Cosmetic manufacturers are relocating formulation operations to Baja California and Querétaro to access USMCA tariff preferences on biobased emollients.
- Carbon intensity scoring under California LCFS:Low-carbon fuel standard credit stacking rewards castor oil biodiesel with favorable pathway carbon intensity values versus soybean alternatives.
- Enzymatic interesterification convergence:Lipase-catalyzed transesterification with medium-chain triglycerides is opening cosmetic ester applications previously dominated by petrochemical emollients.
Industry Challenges
- Specialized oleochemical process engineering scarcity:North American universities have shuttered dedicated fats and oils programs, forcing processors to recruit European-trained talent or develop in-house training pipelines.
- Multi-jurisdictional agricultural adjuvant registration:Health Canada and US EPA coordinated review timelines extend commercialization cycles for biopesticide formulations by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Castor Oil Market |
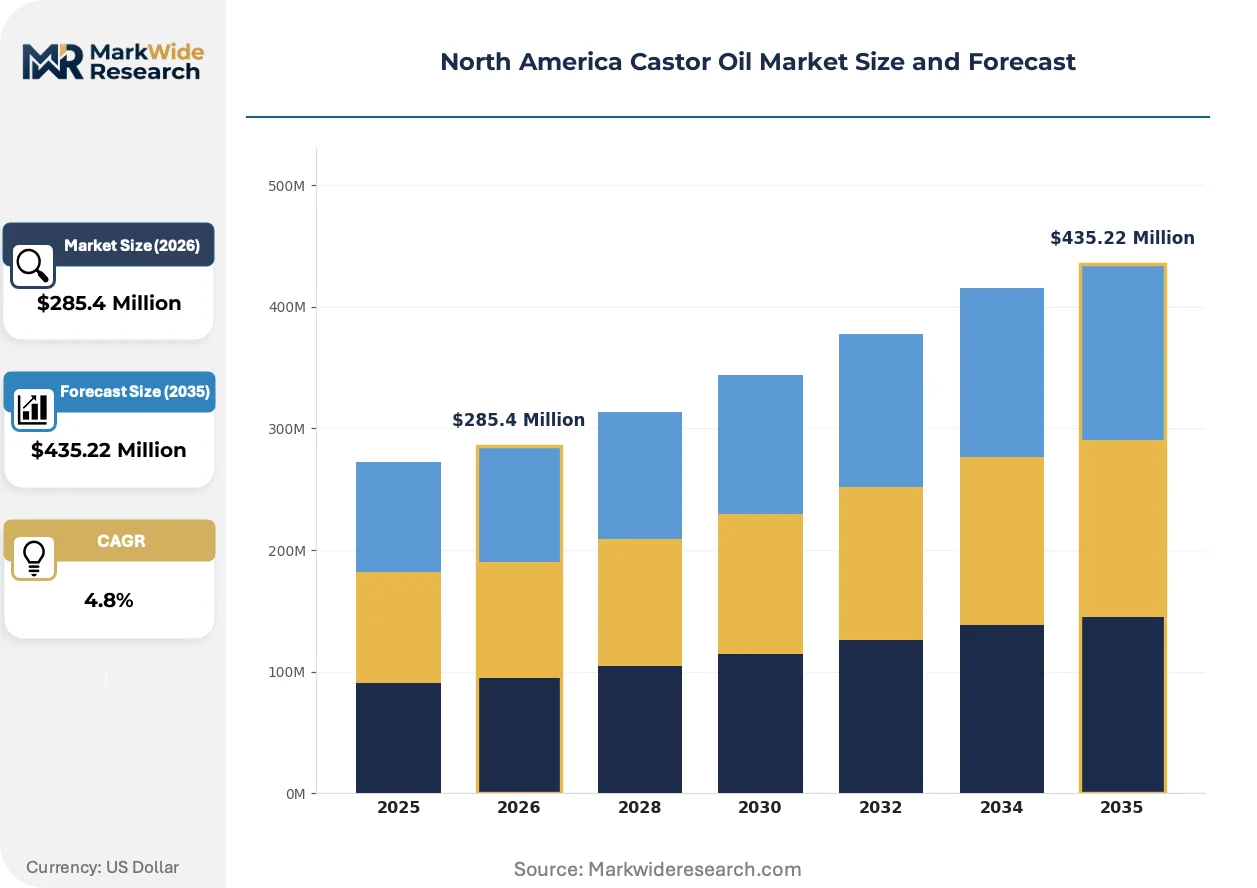
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressed, Refined, Hydrogenated, Dehydrated Application: Cosmetics, Pharmaceuticals, Biofuels, Lubricants End User: Personal Care, Automotive, Industrial, Agriculture Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Croda International PLC, Parchem, Vertellus Holding LLC, Jayant Agro-Organics Ltd., Adani Wilmar Ltd., Arkema SA, Oleon NV, Gokul Agri International Ltd., Emery Oleochemicals GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Castor Oil Market Strategic Shifts & Innovations
Mechanical pressing and solvent extraction technologies are undergoing selective replacement as hydrogenation and enzymatic modification capabilities expand across the value chain. Three developments are compressing traditional margin structures.
Continuous hydrodeoxygenation reactor designs are collapsing the cost differential between plant-derived and petroleum-derived C18 platform chemicals. US Gulf Coast refiners are retrofitting hydrotreating assets to process ricinoleic acid feedstocks at 2,000+ barrel-per-day scale. This capacity expansion is compressing sebacic acid pricing premiums and forcing traditional splitters to defend position through pharmaceutical-grade certification.
California Air Resources Board Low Carbon Fuel Standard amendments are tightening carbon intensity benchmarks for diesel substitutes. Fuel pathway certification now requires detailed agricultural practice documentation from castor seed origins through crushing. Biodiesel blenders are responding by securing mass-balance certified supply chains from Gujarat processors with verified no-till farming practices.
Personal care procurement teams are consolidating supplier panels around vertically integrated oleochemical houses capable of delivering carbon footprint disclosures. Brand owners are disintermediating commodity traders and contracting directly with hydrogenated castor oil manufacturers for wax ester systems. This concentration is most visible in New Jersey and California formulation clusters where ESG reporting requirements have become procurement gatekeepers.
North America Castor Oil Market Segmentation
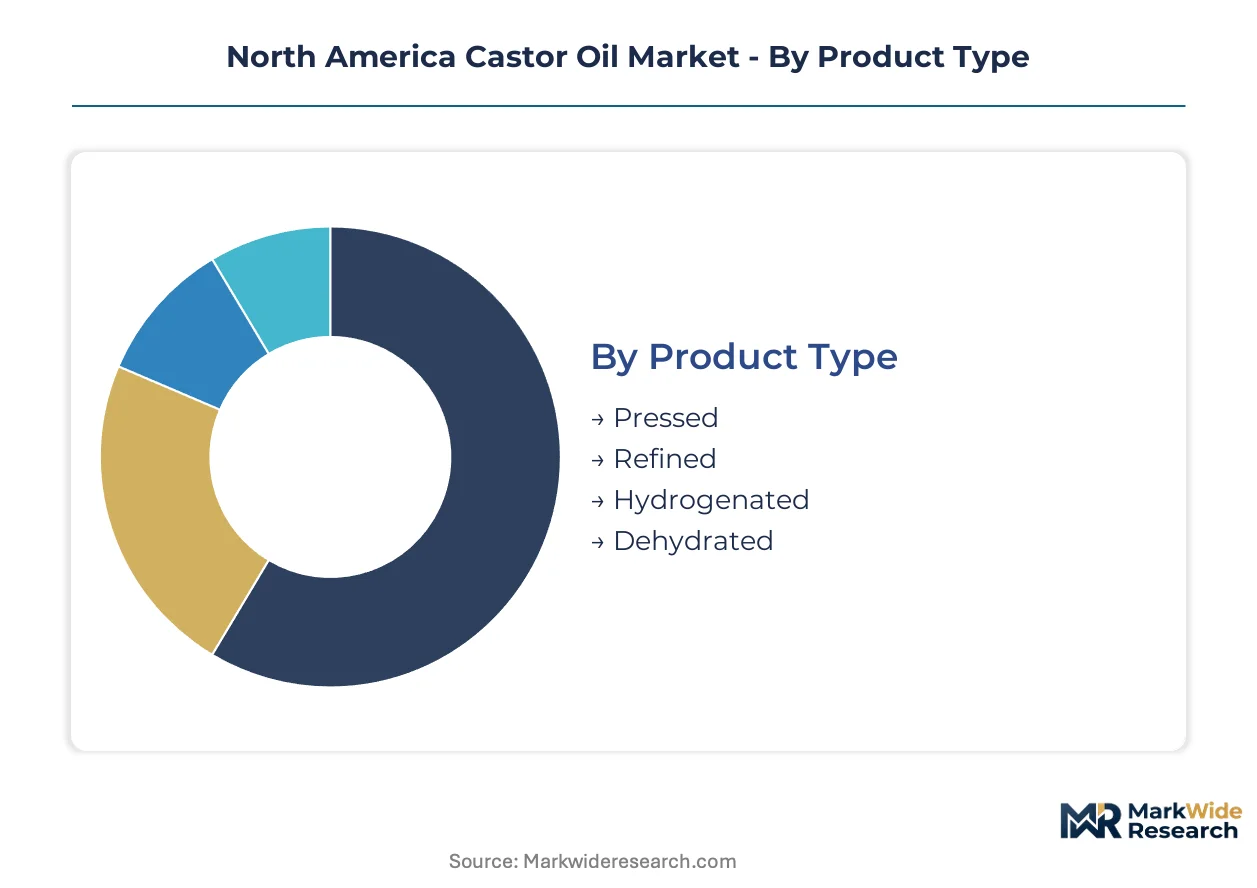
Castor oil segmentation in North America reflects divergent purity requirements across industrial and consumer applications. Technical specifications for ricinoleic acid content, moisture levels, and hydrogenation degree determine pricing tiers and supplier qualification thresholds.
Product Type:
After-sales service intensity varies sharply across product types, with pharmaceutical-grade refined oils demanding batch traceability and technical support that crude industrial grades do not require.
- Pressed:Cold-pressed or expeller-pressed castor oil retains higher phospholipid content and characteristic odor, serving industrial lubricant blenders and biofuel producers along the US Gulf Coast where color tolerance permits lower processing intensity. Demand concentrates in Texas and Louisiana hydrotreating facilities converting raw feedstocks to renewable diesel intermediates.
- Refined:Degummed, neutralized, and bleached grades achieve USP or technical specifications required by pharmaceutical formulators and cosmetic manufacturers. New Jersey and California formulation clusters source these grades for emollient systems where brand owners mandate carbon footprint documentation and supply chain transparency.
- Hydrogenated:Hardened castor oil provides oxidative stability for wax ester applications in personal care coatings and sustained-release pharmaceutical tablets.
- Dehydrated:DCO serves as a drying oil alkyd resin feedstock for industrial coating manufacturers seeking biobased alternatives to petroleum-derived binders.
By volume, Pressed leads. By growth pace, Hydrogenated is gaining share fastest as cosmetic procurement consolidates around vertically integrated oleochemical houses.
Application:
Application segmentation tracks margin capture potential, with formulation complexity and regulatory burden determining value extraction across the value chain.
- Cosmetics:Emollient and surfactant applications in skin care, hair care, and color cosmetics command premium positioning through brand pull and ESG-driven procurement requirements. California LCFS credit stacking and USMCA tariff preferences are accelerating nearshoring to Baja California formulation facilities.
- Pharmaceuticals:FDA monograph-compliant grades for laxative, excipient, and active pharmaceutical ingredient applications require dedicated refining trains and USP certification. Compliance costs fragment capacity economics between industrial and pharmaceutical grades, concentrating supply among processors with validated quality systems.
- Biofuels:Renewable diesel and sustainable aviation fuel pathways represent the steepest expansion trajectory as EPA volume obligations tighten and CARB carbon intensity benchmarks favor castor oil methyl esters over soybean alternatives.
- Lubricants:High-viscosity-index base stocks serve food-grade machinery and marine applications where biodegradability requirements displace mineral oil formulations.
Cosmetics captures the highest unit margins. Biofuels is expanding most quickly as refinery retrofits scale across the Gulf Coast corridor.
End User:
End user segmentation reveals divergent procurement patterns, with automotive and industrial buyers prioritizing volume contracts while personal care demands technical partnership.
- Personal Care:Brand owners and contract manufacturers in New Jersey and California formulation clusters are disintermediating commodity traders to contract directly with hydrogenated castor oil producers for wax ester systems.
- Automotive:Renewable diesel blenders and sustainable aviation fuel producers along the Texas-Louisiana corridor secure long-term ricinoleic acid supply contracts under EPA Renewable Fuel Standard mandates.
- Industrial:Nylon 6,10 polymerization in the US Southeast drives sebacic acid derivative demand from engineering plastics manufacturers.
- Agriculture:Biopesticide formulators face 18-24 month commercialization cycles due to coordinated Health Canada and US EPA agricultural adjuvant registration requirements.
Personal Care leads in value concentration. Automotive is climbing the fastest as biofuel mandates redirect refinery investment.
Distribution Channel:
Channel segmentation tracks disintermediation pressure, with direct procurement eroding traditional distributor roles in premium segments.
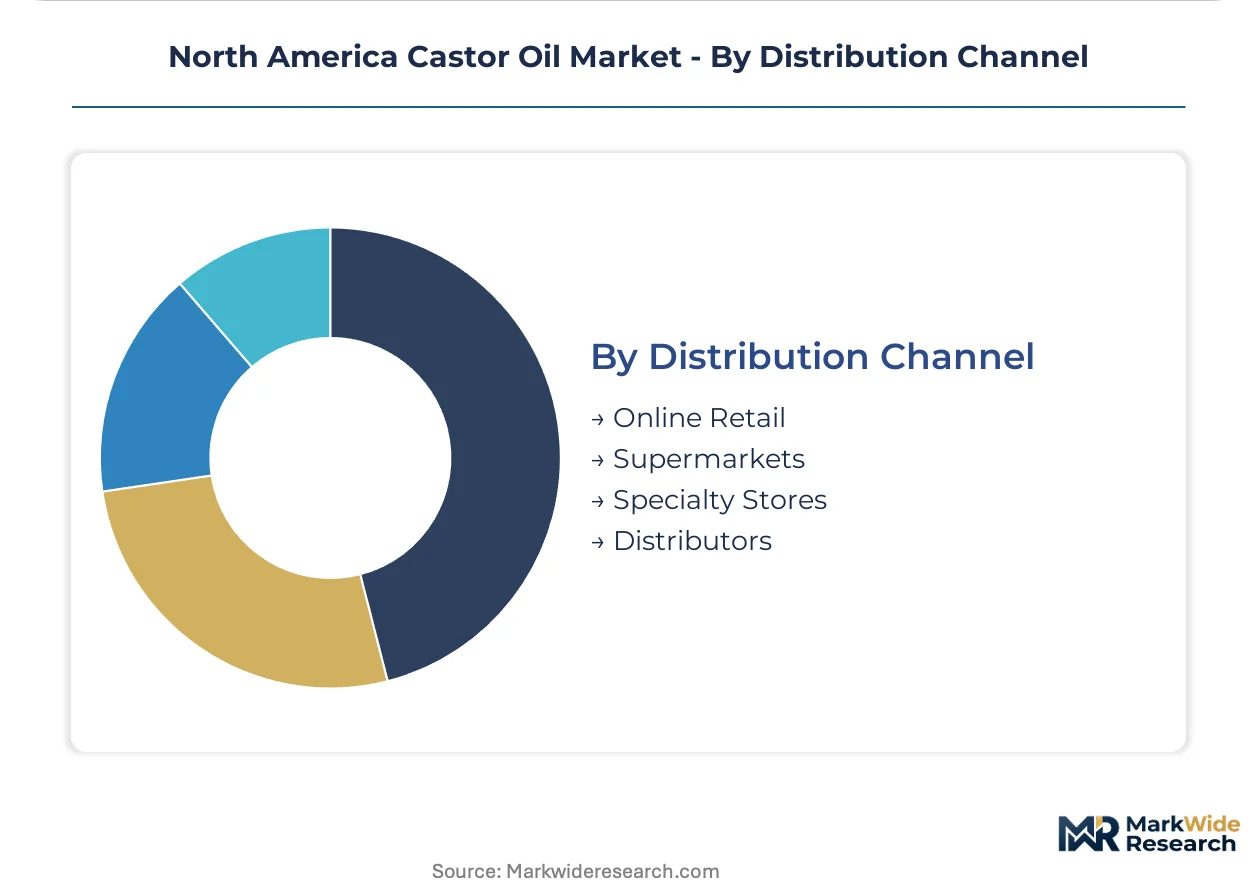
- Online Retail:E-commerce platforms serve small-scale cosmetic formulators and DIY personal care producers with packaged quantities and technical documentation.
- Supermarkets:Mass-market retailers stock pharmaceutical-grade castor oil for consumer laxative and skin care applications.
- Specialty Stores:Professional beauty supply and industrial chemical distributors maintain inventory for salon-grade hair treatments and small-batch lubricant blenders.
- Distributors:Bulk commodity traders face margin compression as Gulf Coast refiners and cosmetic manufacturers establish direct relationships with Gujarat-based processors.
Distributors still handle the largest volume flows. Online Retail is gaining share fastest among emerging formulators and regional blenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers along the Texas-Louisiana corridor exhibit the highest price elasticity, sourcing crude pressed grades for hydrotreating with minimal specification tolerance. Pharmaceutical and cosmetic formulators in New Jersey and California demonstrate the lowest elasticity, absorbing premium differentials for USP-certified and hydrogenated derivatives.
United States
EPA Renewable Fuel Standard mandates and California LCFS credit mechanisms drive biodiesel and sustainable aviation fuel procurement from Gulf Coast refiners. FDA pharmaceutical monograph requirements enforce USP-grade certification thresholds for laxative and excipient applications. Houston and Port Arthur hydrotreating facilities are retrofitting assets to process ricinoleic acid feedstocks at industrial scale.
Canada
Health Canada and PMRA coordinated agricultural adjuvant registrations extend commercialization timelines for biopesticide formulators serving cross-border markets. The national pharmaceutical regulator enforces oleochemical purity standards aligned with US FDA benchmarks. Ontario-based toll processors are expanding hydrogenation capacity to supply personal care manufacturers in the Quebec formulation corridor.
Mexico
USMCA tariff preferences on biobased emollients accelerate nearshoring of cosmetic formulation operations to Baja California and Querétaro. The federal economic secretariat administers biobased procurement incentives under national sustainability frameworks. Guanajuato's industrial parks are attracting hydrogenated castor oil toll processing investments to serve California brand owners.
North America Castor Oil Market Key Industry Players
Specialty chemical houses and integrated oleochemical processors split the market between premium-grade and volume-oriented supply positions. Concentration is moderate, with three to five processors controlling hydrogenated and pharmaceutical-grade segments while commodity traders handle crude pressed volumes. Two strategic archetypes dominate: backward-integrated seed crushers with captive Gujarati supply, and downstream hydrogenation specialists with Gulf Coast refinery partnerships. Competitive moves center on direct procurement relationships with cosmetic brand owners and long-term ricinoleic acid supply contracts with nylon polymerization facilities.
Within the premium-grade tier, Croda International PLC and Arkema SA exemplify contrasting positioning strategies. Croda leverages its UK-based lipid chemistry heritage to occupy high-purity refined grades for cosmetic actives. Arkema anchors its presence through sebacic acid derivative production for engineering polymer applications. Jayant Agro-Organics Ltd. represents the upstream-integrated archetype, sustaining raw material sourcing scale to North American toll processors. These three entities collectively illustrate the margin allocation tension between formulation complexity and feedstock security.
| Leading Market Players |
|---|
| Croda International PLC |
| Parchem |
| Vertellus Holding LLC |
| Jayant Agro-Organics Ltd. |
| Adani Wilmar Ltd. |
| Arkema SA |
| Oleon NV |
| Gokul Agri International Ltd. |
| Emery Oleochemicals GmbH |
| Others |
Cost & Logistics Intelligence
Gujarat's crushing capacity monopoly over 85% of global castor seed processing anchors margin capture downstream, concentrating pricing power among Indian exporters while Gulf Coast refiners and New Jersey cosmetic formulators compete for value extraction through hydrogenation and pharmaceutical-grade certification.
Pricing Analysis
Technical support contracts for pharmaceutical-grade refined oils drive lifetime value through batch traceability and regulatory documentation services. Three-tier pricing structure across USP-certified, technical-grade, and crude pressed levels segments buyers by purity tolerance and application criticality. Cost compression in crude industrial grades is intensifying because Gulf Coast hydrotreating facilities are scaling ricinoleic acid processing capacity. Biofuel blenders along the Texas-Louisiana corridor exhibit the highest price elasticity, sourcing minimal-specification feedstocks, while California cosmetic brand owners absorb premium differentials for carbon-disclosed hydrogenated derivatives.
Supply Chain Analysis
Monsoon-dependent crop volatility in Gujarat exposes North American processors to rupee-denominated pricing swings and harvest uncertainty. The supply chain draws from Indian seed crushers, Gulf Coast hydrogenation specialists, and Mexican toll processors in Querétaro. Single-source vulnerability concentrates in Gujarat's crushing corridor, where drought or pest pressure disrupts global ricinoleic acid availability. Distribution runs through direct procurement relationships between cosmetic brand owners and hydrogenated castor oil manufacturers, bypassing traditional commodity traders in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across the North America castor oil market as EPA biofuel mandates and California LCFS credit mechanisms create specialized supply niches for renewable diesel intermediates and low-carbon hydrogenated grades.
For Market Incumbents: Harden defensive positions by securing long-term ricinoleic acid offtake agreements with Gujarat processors and investing in dedicated USP-grade refining trains to fragment capacity economics away from industrial-grade competitors. High oleic sunflower oil substitution in food-grade lubricants threatens volume positions, making pharmaceutical certification and cosmetic direct-contracting the priority levers for margin defense. For New Entrants and Emerging Players: Build out enzymatic interesterification capabilities in Baja California to capture USMCA tariff-preferred cosmetic ester demand from California brand owners. The nearshoring wave into Querétaro and Guanajuato offers the most penetrable geography, with toll processing partnerships serving as the viable go-to-market angle against established Gulf Coast hydrogenation assets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed oleochemical processors lacking backward integration into Indian seed supply. Long-term viability over the five-to-ten year window hinges on carbon intensity scoring advantages under evolving LCFS frameworks. Watch for EPA volume obligation expansion signals as the inflection indicator for renewable diesel intermediate demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gujarat Seed Supply | Captive ricinoleic acid sourcing insulates processors from monsoon volatility and rupee fluctuation. |
| Hydrogenation Capacity Expansion | Gulf Coast refinery retrofits at Port Arthur and Houston scale renewable diesel intermediate production. |
| Pharmaceutical-Grade Certification Investment | USP-grade refining trains fragment capacity economics and concentrate supply among validated quality systems. |
| Enzymatic Interesterification Scale-Up | Lipase-catalyzed transesterification opens cosmetic ester applications previously dominated by petrochemical emollients. |
| Direct Procurement Relationship Building | Cosmetic brand owners in New Jersey and California formulation clusters are disintermediating commodity traders. |
Research Approach
A standing panel of hydrogenation plant managers, cosmetic procurement leads at brand owners, biofuel blenders, and agricultural adjuvant formulators provided ongoing calibration across primary fieldwork. Secondary validation drew from US EPA Renewable Fuel Standard filings, California Air Resources Board LCFS pathway certifications, Health Canada agricultural adjuvant registration databases, and SEC 10-K disclosures from listed oleochemical processors. Bottom-up segmentation modeling and top-down macroeconomic triangulation converged on volume and value estimates.
Scenario-bracketing framed analytical projections across the modeling period, with sensitivity testing for monsoon variability and rupee exchange rate swings. Segmentation dimensions included product type tier, application vertical, end-use industry procurement pattern, and regional production hub concentration. CAGRs were derived from trend extrapolation of EPA volume obligation trajectories and refinery retrofit announcement pipelines, cross-referenced against cosmetic formulation nearshoring momentum.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Gulf Coast refiners or California brand owners would shift outcomes through supply chain disintermediation. Specific risks include Gujarat crop failure, LCFS carbon intensity benchmark tightening beyond modeled pathways, and FDA pharmaceutical monograph revisions altering USP certification requirements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
South America Plant Growth Regulators Market
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
Asia-Pacific Swine Feed Premix Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
North America Feed Amino Acids Market
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
Turf and Ornamental Inputs Market
Agricultural Chemicals
United States Feed Amino Acids Market