
 Seed Storage Systems Market | 2026-2036
Seed Storage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Storage Systems Market Insights
Market Context
Buyer concentration among commercial seed companies is hardening as multinationals consolidate long-term germplasm preservation contracts. Conviron leverages its controlled-environment engineering heritage to anchor premium vault installations for research institutions. Thermo Fisher Scientific sustains R&D intensity in cryogenic and ultra-low temperature systems that serve gene banks. Seedburo competes through specialized desiccator and testing equipment that supports smaller-scale agricultural operations.
Technical Definition and Segment Structure
Seed storage systems encompass engineered enclosures, environmental control modules, and monitoring infrastructure designed to maintain specific temperature, humidity, and atmospheric conditions that preserve seed viability over decades, typically operating between -20°C and 4°C with relative humidity below 15 percent for long-term conservation. Cold storage dominates value capture due to capital-intensive refrigeration infrastructure and energy consumption profiles, while controlled environment systems represent the fastest-expanding segment as precision agriculture and biotechnology applications multiply. Plastic materials lead unit volume for small-scale and home gardener applications, whereas metal construction anchors large-scale and bulk installations where structural durability and thermal mass prove critical.
Regulatory Environment and Outlook
The EPA regulates energy efficiency standards for commercial refrigeration equipment used in agricultural seed preservation, while the USDA enforces germination testing protocols and genetic identity requirements that directly specify storage condition documentation. ISO standards for seed testing and the OECD Seed Schemes provide international harmonization frameworks that equipment manufacturers must address for cross-border market access. Stakeholders should monitor evolving federal energy-efficiency mandates and precision-agriculture data-integration requirements that will reshape equipment specification criteria.
Market Dynamics
Commercial seed companies are consolidating procurement of climate-controlled vaults, hardening buyer concentration and reshaping equipment specification standards across long-term germplasm preservation contracts.
Growth Catalysts
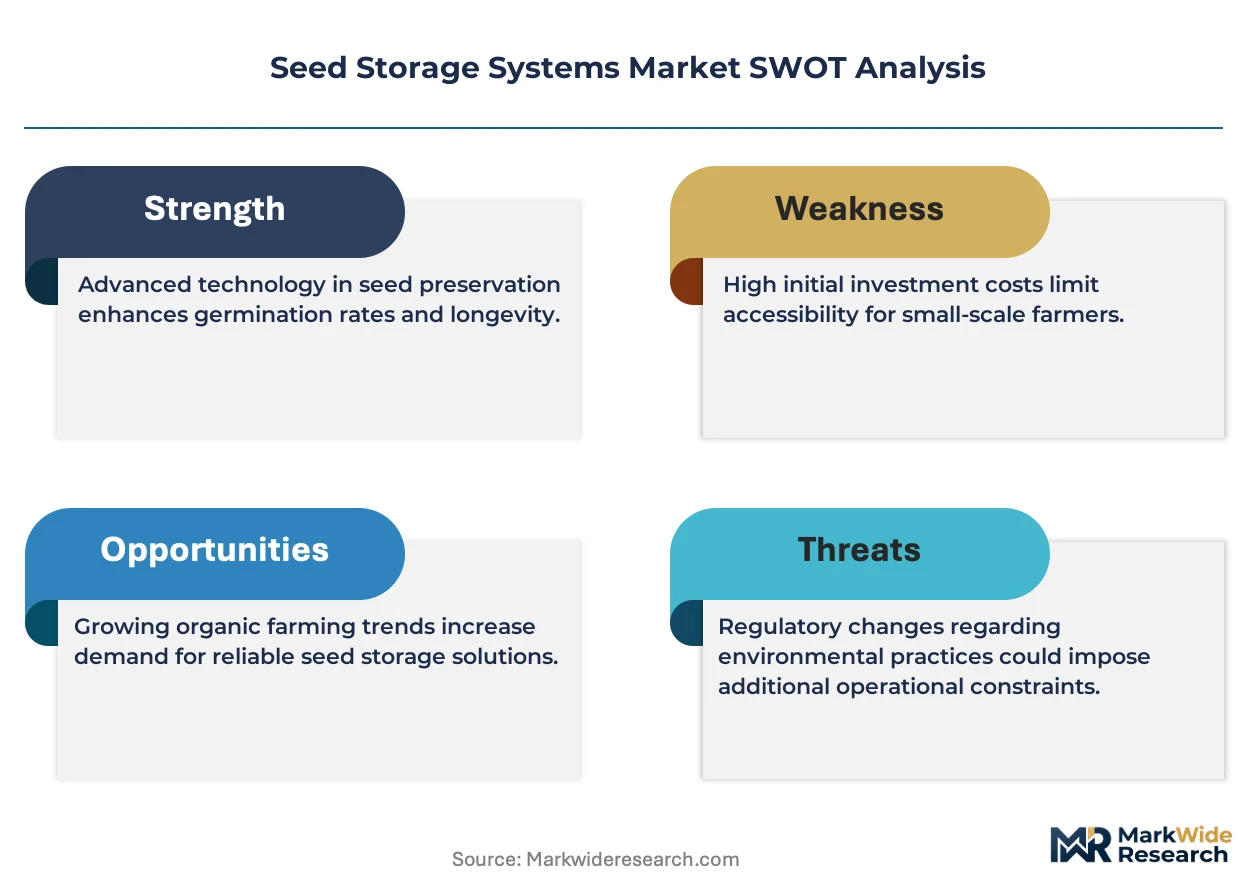
- USDA Germination Standards:Federal enforcement of genetic-purity protocols mandates documented storage conditions, driving replacement cycles for monitoring infrastructure in agricultural biotechnology facilities.
- Cryogenic Preservation:Gene banks and research institutions are adopting ultra-low temperature systems to extend viability horizons for heritage and engineered seed lines.
- Midwest Agricultural Clusters:Concentration of large-scale seed operations in Iowa, Illinois, and Nebraska generates sustained demand for bulk metal-construction vault installations.
Market Restraints
- Refrigeration Energy Costs:Cold storage operations face persistent margin pressure from electricity price volatility and EPA efficiency mandates for commercial equipment.
- Equipment Supplier Concentration:Premium vault engineering capabilities concentrate among a limited set of controlled-environment specialists, constraining procurement flexibility for mid-scale operations.
- Humidity Control Limitations:Desiccant system performance degrades in high-ambient-humidity regions, restricting reliable deployment in coastal agricultural zones without redundant infrastructure.
Strategic Opportunities
- Precision Agriculture Integration:Controlled environment systems are converging with IoT sensor networks and automated inventory management, creating bundled service models for commercial seed producers.
- Home Gardener Segment:Plastic-construction residential units remain underpenetrated relative to institutional markets, presenting white space for scaled manufacturing and direct-to-channel distribution.
- Energy Efficiency Incentives:Federal and state-level agricultural energy programs subsidize equipment upgrades, accelerating replacement demand for legacy refrigeration infrastructure.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Gene bank and biotechnology facilities report acute shortages of technicians qualified to maintain ultra-low temperature systems and troubleshoot cascade refrigeration failures.
- Legacy System Integration:Retrofitting monitoring infrastructure into existing vault networks requires custom engineering to bridge proprietary control protocols with modern data-logging platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Storage Systems Market |
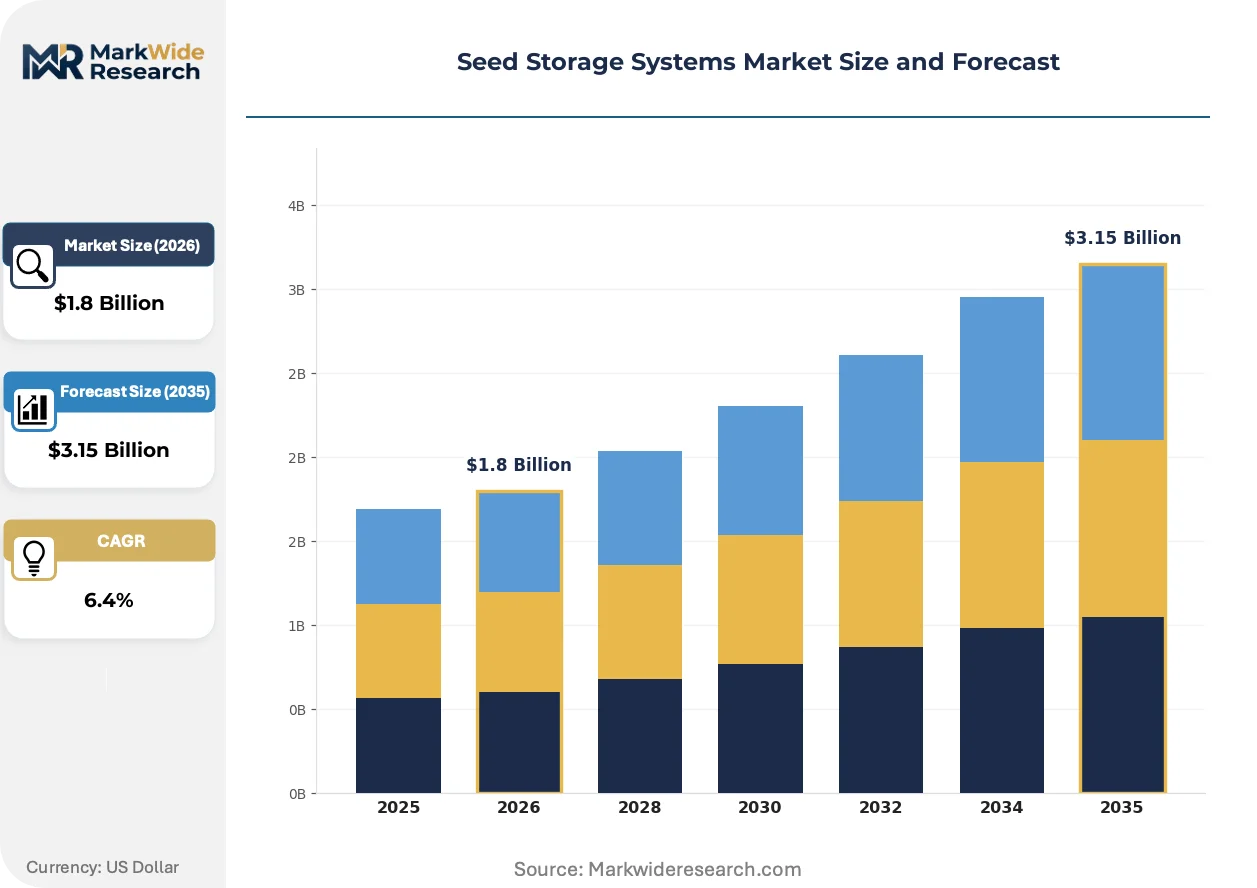
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controlled Environment, Natural Storage, Desiccators, Cold Storage Material: Plastic, Metal, Wood, Glass Capacity: Small Scale, Medium Scale, Large Scale, Bulk End User: Agriculture, Research Institutions, Seed Companies, Home Gardeners |
| Companies Covered | Conviron, Thermo Fisher Scientific, Panasonic Healthcare, Seedburo, Modular Cold Storage Solutions, Lineage Logistics, Americold, Cargill, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Storage Systems Market Trends and Innovations
Environmental monitoring technology is absorbing capital investment as seed preservation operations digitize condition documentation to satisfy tightening regulatory audit requirements and enable predictive maintenance workflows.
Phase-change materials are absorbing thermal load management functions in next-generation seed vault designs, reducing compressor cycling frequency and energy consumption profiles. Research institutions with 24-hour preservation mandates are piloting these thermal mass systems most aggressively. The technology is absorbing share from conventional refrigeration in applications where temperature stability outweighs capital cost sensitivity.
EPA commercial refrigeration efficiency standards are tightening energy performance thresholds for equipment deployed in agricultural seed preservation, forcing manufacturers to redesign compressor architectures and insulation systems. Cold storage segment suppliers face the steepest compliance timelines given their higher energy intensities. Large-scale operators are responding by consolidating procurement into longer-term equipment refresh cycles that synchronize with efficiency mandate phase-ins.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts as sophisticated buyers separate hardware acquisition from condition monitoring and predictive analytics subscriptions. Commercial seed companies with internal engineering capabilities are driving this disaggregation, preferring to own vault infrastructure while outsourcing specialized environmental oversight. This pattern is most pronounced in the Corn Belt states where agricultural biotechnology firms operate extensive preservation networks.
Seed Storage Systems Market Segmentation
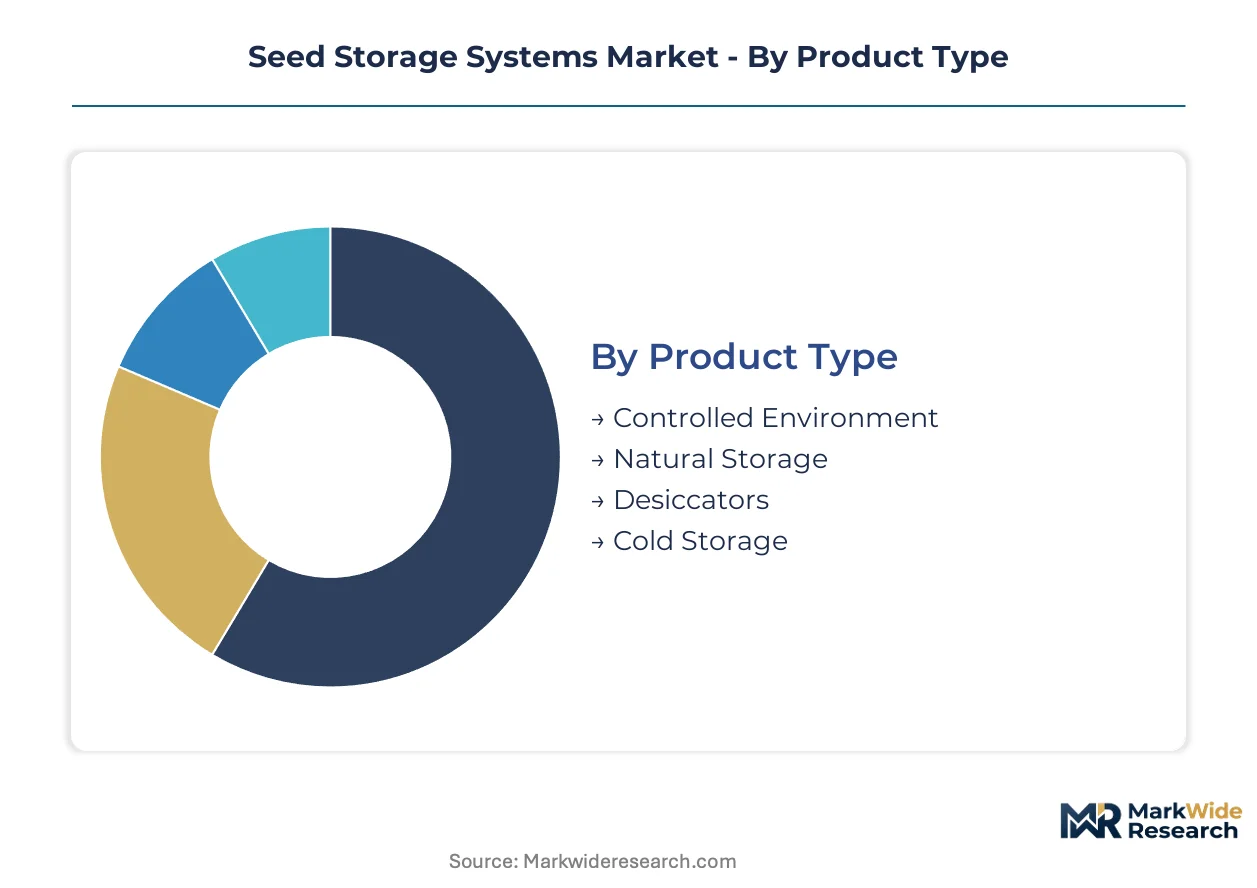
Equipment specification diverges sharply between embedded preservation networks and standalone installations. Procurement patterns in seed storage track integration depth, with multinationals favoring system-wide environmental control while smaller operators acquire discrete units.
Product Type:
Standalone systems dominate home gardener and small-scale agricultural procurement, while embedded controlled-environment modules integrate into facility-wide germplasm preservation networks.
- Cold Storage:Capital-intensive refrigeration infrastructure operating between -20°C and 4°C anchors bulk preservation operations. USDA germination-rate documentation requirements drive replacement demand in Iowa and Illinois biotechnology facilities facing EPA efficiency mandates.
- Controlled Environment:Precision modules with IoT sensor integration and automated atmospheric regulation serve gene banks and research institutions. These systems are expanding most quickly as precision agriculture applications multiply and regulatory audit requirements tighten.
- Desiccators:Passive humidity control units employing silica gel or molecular sieve media protect small seed collections. Performance degrades in high-ambient-humidity coastal zones without redundant infrastructure.
- Natural Storage:Ambient-temperature solutions with basic moisture barriers serve heritage seed networks and developing-region agricultural extension programs. Limited viability horizons restrict commercial adoption.
Cold storage leads volumes today; controlled environment is gaining share fastest.
Material:
Cost tiers separate commodity construction from engineered thermal performance, with specification tightly coupled to capacity scale and preservation duration requirements.
- Metal:Galvanized steel and aluminum enclosures with high thermal mass anchor large-scale and bulk installations. Structural durability supports multi-decade preservation contracts in Nebraska and Kansas seed processing clusters.
- Plastic:Polypropylene and ABS construction dominates unit volume for residential and small-scale applications. Manufacturing scale economies create entry-level pricing for home gardener segments.
- Wood:Cedar and redwood chests with natural pest resistance serve heritage seed savers and organic certification operations. Moisture sensitivity limits institutional adoption.
- Glass:Borosilicate and soda-lime vessels with hermetic seals protect reference collections and germplasm samples. Fragility constrains deployment outside controlled laboratory environments.
Metal construction commands premium pricing; plastic materials drive unit volume expansion.
Capacity:
Customer type and application maturity determine scale specification, with bulk installations concentrating among commercial seed companies consolidating procurement.
- Bulk:Vault-scale installations exceeding 10,000 cubic feet serve multinational germplasm preservation networks. Conviron and controlled-environment specialists dominate engineering procurement for these capital-intensive projects.
- Large Scale:Industrial units between 1,000 and 10,000 cubic feet support regional seed company operations and university agricultural research stations. Metal construction and cascade refrigeration predominate.
- Medium Scale:Cabinet and chamber systems from 100 to 1,000 cubic feet serve county extension services and independent seed processors. Hybrid plastic-metal construction balances cost and thermal performance.
- Small Scale:Benchtop and under-counter units below 100 cubic feet target home gardeners and specialty crop breeders. Direct-to-channel distribution and e-commerce penetration remain underdeveloped relative to institutional markets.
Bulk installations concentrate revenue; small scale offers white-space expansion opportunity.
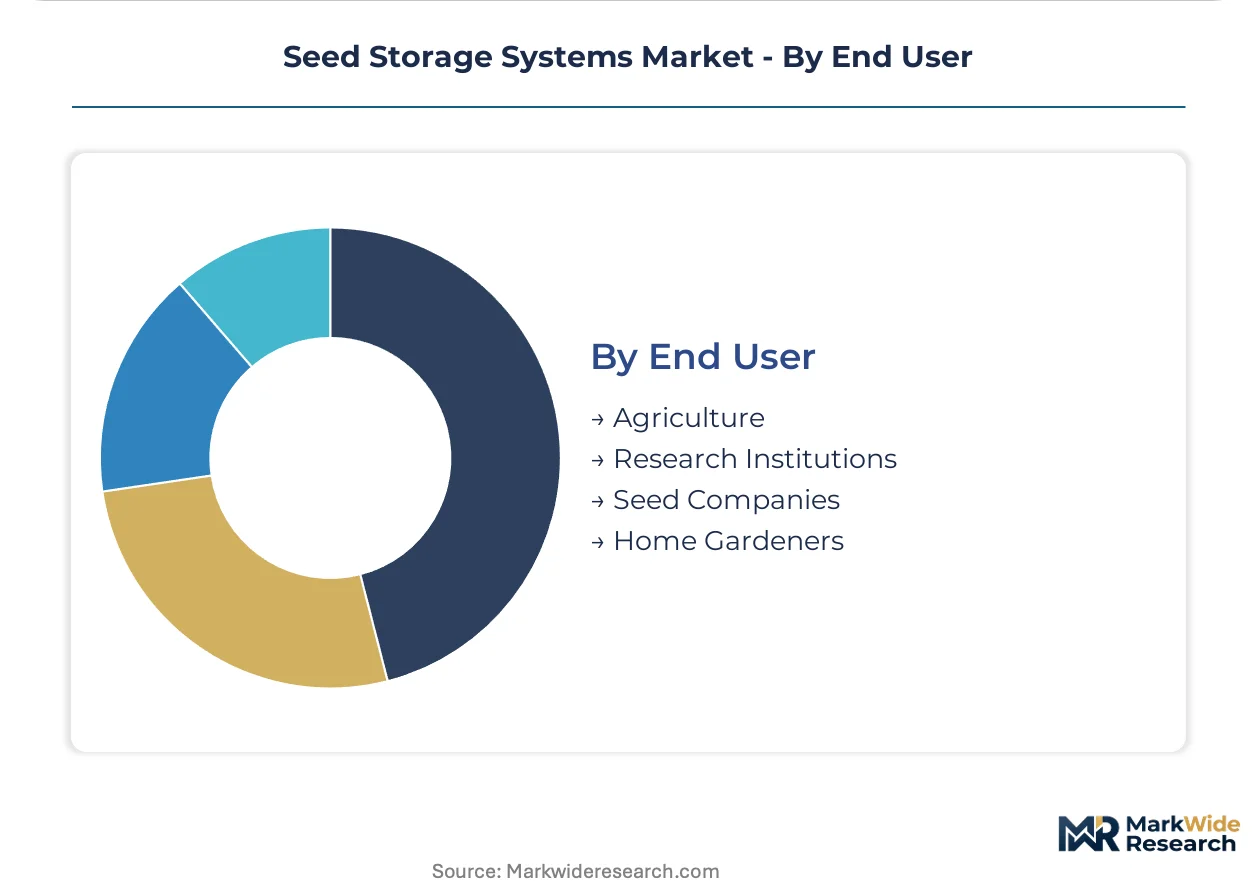
End User:
Application-specific requirements around documentation, monitoring precision, and preservation duration segment procurement behavior across user categories.
- Seed Companies:Commercial biotechnology and hybrid seed producers operate the most extensive preservation networks. These buyers are unbundling equipment acquisition from condition monitoring services, driving contract restructuring across the Corn Belt.
- Research Institutions:Gene banks and agricultural universities prioritize ultra-low temperature cryogenic systems for heritage and engineered line preservation. Acute technician shortages constrain operational scaling.
- Agriculture:Cooperative and independent farming operations utilize medium-scale cold storage for foundation seed and varietal maintenance. Federal energy-efficiency incentive programs accelerate equipment refresh cycles.
- Home Gardeners:Residential preservation remains underpenetrated relative to institutional demand. Plastic-construction desiccators and compact refrigeration units present scaled manufacturing opportunities through direct-to-consumer channels.
Seed companies anchor revenue concentration; home gardeners represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cryogenic technicians and controlled-environment engineers concentrate in agricultural biotechnology clusters across four major economies, anchoring regional demand for precision preservation infrastructure.
United States
Commercial seed companies in Iowa and Illinois operate the most extensive germplasm preservation networks worldwide. The USDA enforces germination-rate documentation standards that mandate continuous environmental monitoring. Nebraska's seed processing corridor drives bulk vault installations serving multinational hybrid producers.
Germany
Research institutions across Bavaria and Baden-Württemberg prioritize ultra-low temperature cryogenic systems for heritage line conservation. The ECHA regulates desiccant material safety classifications affecting equipment specification. Stuttgart's agricultural engineering cluster advances phase-change material integration for thermal stability applications.
China
National gene bank expansion in Beijing and Sichuan generates institutional procurement of cascade refrigeration infrastructure. The MIIT enforces energy efficiency standards for commercial cold storage equipment. Yangtze River Delta seed biotechnology parks concentrate demand for large-scale controlled-environment modules.
Australia
Heritage seed networks and indigenous agricultural programs in New South Wales and Victoria utilize ambient natural storage for community-based preservation. The TGA oversees equipment safety certification for laboratory-grade preservation vessels. Adelaide's dry climate supports passive desiccator deployment without redundant humidity infrastructure.
Seed Storage Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, creating a bifurcated structure where capital-intensive vault engineering concentrates among controlled-environment heritage firms while commodity fabrication fragments across regional metalworkers. Three strategic archetypes dominate: integrated biotechnology conglomerates with captive preservation infrastructure, specialized controlled-environment engineering firms, and scaled refrigeration contractors serving agricultural cold chain adjacencies. Competitive intensity manifests through procurement contract consolidation among seed multinationals and technology licensing partnerships between cryogenic specialists and gene bank operators.
Within the controlled-environment heritage tier, Conviron exemplifies precision vault engineering capabilities anchored in research institution relationships. Thermo Fisher Scientific occupies a diversified life sciences position spanning cryogenic and ultra-low temperature system portfolios. Seedburo represents specialized equipment fabrication focused on desiccator and testing apparatus for mid-scale agricultural operations.
| Leading Market Players |
|---|
| Conviron |
| Thermo Fisher Scientific |
| Panasonic Healthcare |
| Seedburo |
| Modular Cold Storage Solutions |
| Lineage Logistics |
| Americold |
| Cargill |
| ADM |
| Others |
Pricing and Supply Chain Analysis
Steel price indices and aluminum commodity benchmarks cascade through refrigeration equipment fabrication, compressing margins for metal-construction vault suppliers while amplifying pricing power for controlled-environment specialists with captive thermal engineering capabilities.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity cold storage components. Three-tier pricing structure across premium, standard, and economy levels separates Conviron-engineered vault installations from regional refrigeration contractors and plastic desiccator imports. Price differentiation hinges on EPA energy-efficiency certification tiers and after-sales monitoring service bundling. Cost compression in standard-tier metal construction is intensifying because of raw material volatility, while seed companies with internal engineering capabilities exhibit lowest price sensitivity and home gardener segments face acute budget constraints.
Supply Chain Analysis
Welding technician and cryogenic systems specialist availability constrains output in Ohio, Michigan, and Wisconsin manufacturing corridors. Component fabrication draws from galvanized steel mills in Indiana, compressor assemblies from Mexico, and control electronics from South Korean semiconductor foundries. Single-source vulnerability concentrates in cascade refrigeration unit supply from a limited set of ultra-low temperature specialists. Distribution runs through agricultural equipment dealers serving the Corn Belt and direct-to-institutional contracts for gene bank and research facility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as commercial seed companies consolidate procurement toward premium vault specifications with integrated IoT monitoring and documented USDA compliance trails.
For Market Incumbents: Lock in long-term service contracts with gene bank operators facing acute cryogenic technician shortages. Deepen backward integration into phase-change material thermal mass systems to differentiate from commodity refrigeration suppliers. Control channel access across Midwest agricultural equipment dealer networks before efficiency mandate deadlines force replacement cycles.
For New Entrants and Emerging Players: Begin with plastic-construction residential desiccators targeting underpenetrated home gardener segments through direct-to-consumer e-commerce channels. Exploit manufacturing scale economies in compact refrigeration units below 100 cubic feet. Pursue white-label partnerships with heritage seed networks requiring basic moisture barrier solutions.
For Investors and Strategic Acquirers: Asymmetric upside sits with controlled-environment engineering specialists possessing research institution relationships and precision agriculture data integration capabilities. Five-to-ten year viability favors acquisition targets with proprietary thermal management IP and existing EPA efficiency certification. Monitor federal agricultural energy subsidy program allocations as inflection indicator for replacement demand velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Engineering Talent Acquisition | Gene bank expansion in Beijing and Sichuan strains qualified technician supply chains. |
| Phase-Change Material Integration | Stuttgart engineering clusters advance thermal stability applications for 24-hour preservation mandates. |
| IoT Sensor Network Convergence | USDA germination-rate documentation requirements drive predictive maintenance workflow adoption. |
| Energy Efficiency Certification Investment | EPA commercial refrigeration standards force compressor architecture redesigns across Iowa facilities. |
| Direct-to-Consumer Channel Development | Home gardener segment white space enables scaled manufacturing bypassing institutional procurement concentration. |
Research Methodology
Coverage spans the United States, Germany, China, and Australia, with primary inputs from each market cluster. The analysis combines structured interviews with controlled-environment engineering directors, gene bank facility managers, agricultural equipment procurement officers, and EPA compliance specialists with secondary validation against USDA germination testing protocols, ISO seed testing standards, OECD Seed Schemes documentation, and customs trade data for refrigeration equipment imports. Bottom-up equipment shipment tallies and top-down germplasm preservation network capacity estimates provide triangulation anchors.
Granularity extends to product type, material construction, capacity tier, and end-user category with regional regulatory cluster overlays. CAGRs derive from logistic diffusion modeling of replacement cycle timing and precision agriculture technology adoption curves across the projection horizon. Industry-specific forecast inputs include federal energy-efficiency incentive program allocations and gene bank expansion pipeline visibility from national agricultural research institute capital budgets.
Several conditions sit outside the modeled scope, including unannounced tariff modifications on Chinese refrigeration components and breakthroughs in ambient-temperature seed preservation biotechnology. Forecasts reflect assumptions around EPA mandate phase-in schedules and USDA documentation requirement enforcement intensity. Material deviation in steel commodity pricing or cryogenic technician training program throughput warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
Europe Seed Coating Materials Market
Seed Technology
Japan Seed Treatment Market
Seed Technology
Asia-Pacific Seed Coating Materials Market
Seed Technology
Mexico Seed Treatment Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
North America Seed Coating Materials Market
Seed Technology
Canada Seed Treatment Market
Seed Technology
Seed Treatment Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
Seed Coating Materials Market
Seed Technology
North America Cotton Seed Treatment Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
Seed Additives Market
Seed Technology
Protein Content Optimizing Cereal Fertility Program Market
Seed Technology
Seed Quality Imaging and Germination Prediction Test Systems Market